
 Global Industrial Safety Gates Market | 2026-2036
Global Industrial Safety Gates Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Safety Gates Market Outlook
Modular safety gate configurations with integrated access control and sensor packages is expanding buyer choice beyond standalone barriers. ASSA ABLOY AB leverages its electromechanical expertise to bundle gate hardware with digital credentialing systems. Kee Safety Inc. anchors its position through proprietary modular connection technology that accelerates on-site assembly without welding. Rite-Hite Holding Corporation dominates in high-throughput manufacturing environments where gate-cycle speed directly affects line productivity.
Industrial safety gates are physical barrier systems engineered to restrict unauthorized personnel access, prevent falls from elevated platforms, and control material flow at hazardous zone boundaries, typically fabricated from steel or aluminum with load-rated hinges, self-closing mechanisms, and corrosion-resistant finishes. Their primary purpose is to enforce controlled access while maintaining emergency egress compliance in industrial, commercial, and infrastructure settings. Swing gates occupy the largest product type position due to their mechanical simplicity and broad compatibility with existing fencing infrastructure. Composite materials represent the fastest-growing material segment as facilities seek reduced-weight alternatives that resist chemical exposure without galvanizing maintenance. Safety compliance applications command premium pricing because they require third-party certification against regional standards and documented traceability.
OSHA regulations in the United States mandate specific load ratings and self-closing functionality for industrial gates used near unprotected edges, while ISO 14120 establishes international guard design and testing protocols that exporters must satisfy for cross-border equipment sales. The EU Machinery Directive and CE marking requirements further shape product development cycles for manufacturers serving European industrial customers. Stakeholders must monitor evolving harmonization between national building codes and international machine safety standards to anticipate certification burden shifts that could reshape competitive access across major procurement markets.
Market Dynamics
Retrofit mandates from OSHA and ISO 14120 are accelerating replacement cycles for legacy barrier systems across manufacturing and logistics facilities, compressing the traditional 15-20 year equipment refresh timeline into 7-10 year windows.
Growth Catalysts
- Warehouse automation retrofit:Aging distribution centers in Germany and the United States are replacing fixed railings with sensor-equipped gates that integrate with warehouse management systems.
- OSHA edge protection mandates:Updated enforcement protocols for unprotected elevated platforms are forcing facility upgrades in food processing and chemical handling operations.
- Composite material substitution:Chemical manufacturers in Belgium and the Netherlands are specifying fiberglass-reinforced polymer gates to eliminate galvanizing maintenance in corrosive environments.
Market Restraints
- Steel price volatility:Hot-rolled coil fluctuations in China and India transmit directly to gate fabrication costs, squeezing margin on standard steel product lines.
- Certification backlog:Third-party testing laboratory capacity constraints in North America and Europe are extending CE marking and OSHA compliance timelines by 4-6 months.
- Modular substitute threat:Flexible barrier systems from temporary safety equipment vendors are capturing short-duration project demand that previously flowed to permanent gate installations.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for electronics and pharmaceutical production are creating specification-grade safety gate demand in greenfield facilities near Chennai and Hyderabad.
- Access control convergence:Biometric credentialing and RFID tracking systems are merging with gate hardware to create integrated perimeter security solutions for data center and critical infrastructure operators.
- EU Green Deal procurement:Public tender scoring criteria now weight embodied carbon and recyclability, favoring aluminum and composite gate suppliers with verified environmental product declarations.
Industry Challenges
- Installation technician scarcity:Qualified riggers with fall protection certification are concentrated in unionized markets, creating bottlenecks for project execution in the southern United States and eastern Europe.
- Legacy system integration:Mechanical gates in 20-year-old facilities often lack mounting compatibility with modern self-closing hinge mechanisms, requiring costly structural modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Safety Gates Market |
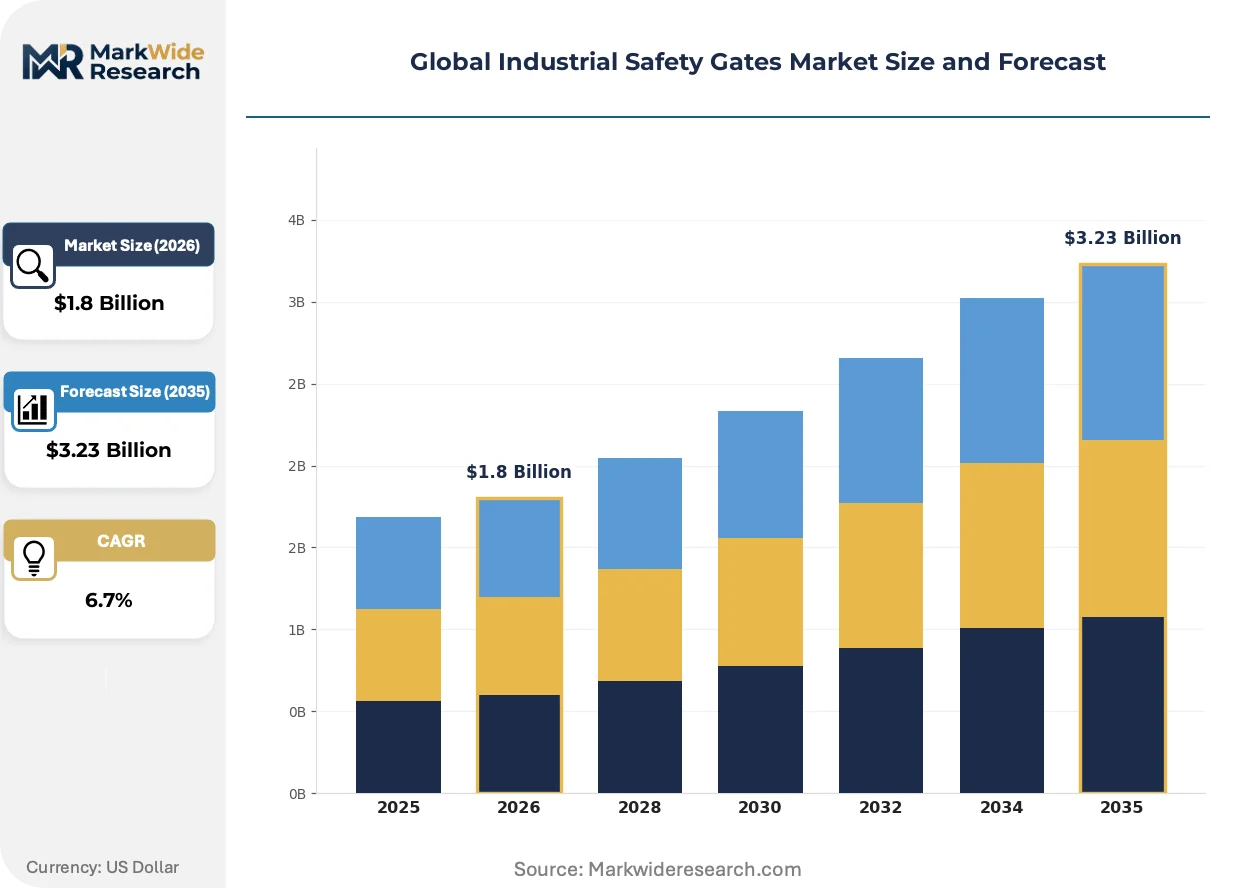
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swing Gates, Sliding Gates, Bi-Folding Gates, Turnstile Gates Material: Steel, Aluminum, Composite, Plastic End User: Manufacturing, Warehousing, Construction, Oil & Gas Application: Emergency Exits, Access Control, Safety Compliance, Crowd Management |
| Companies Covered | Abbey Gates, Ametco Manufacturing Corp., ASSA ABLOY AB, Avon Barrier Corp. Ltd., Benko Products Inc., FAAC Spa, Kee Safety Inc., A-Safe Ltd., Rite-Hite Holding Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Safety Gates Market Strategic Shifts
Sensor-enabled gate systems are displacing purely mechanical barriers as the default specification for high-throughput environments, embedding condition monitoring and predictive maintenance capabilities directly into access control infrastructure.
Photoelectric and pressure-sensitive edge sensors are integrating with industrial safety gates to detect obstructions and trigger emergency stops before contact occurs. Automotive assembly plants in Germany and battery manufacturing facilities in South Korea are specifying these packages on 60% of new gate procurements. The technology is integrating lockout-tagout compliance documentation directly into facility maintenance software, eliminating manual inspection logs.
REACH substance restrictions on hexavalent chromium plating are forcing European gate manufacturers to shift toward powder coating and anodized aluminum finishes. The regulation eliminates traditional galvanizing for food-contact and cleanroom applications, redirecting R&D spending toward corrosion-resistant alloy development. Export-oriented suppliers in Poland and the Czech Republic are accelerating ISO 14120 testing to maintain cross-border equipment eligibility.
Lifecycle service contracts are unbundling from equipment sales as facilities outsource inspection, recertification, and hinge replacement to specialized maintenance providers. Third-party service networks are displacing manufacturer-direct technician deployment in the United States and United Kingdom, particularly for multi-site logistics operators with standardized gate fleets. This shift is most visible among e-commerce fulfillment networks with 50+ facility footprints requiring synchronized compliance documentation.
Global Industrial Safety Gates Market Segmentation
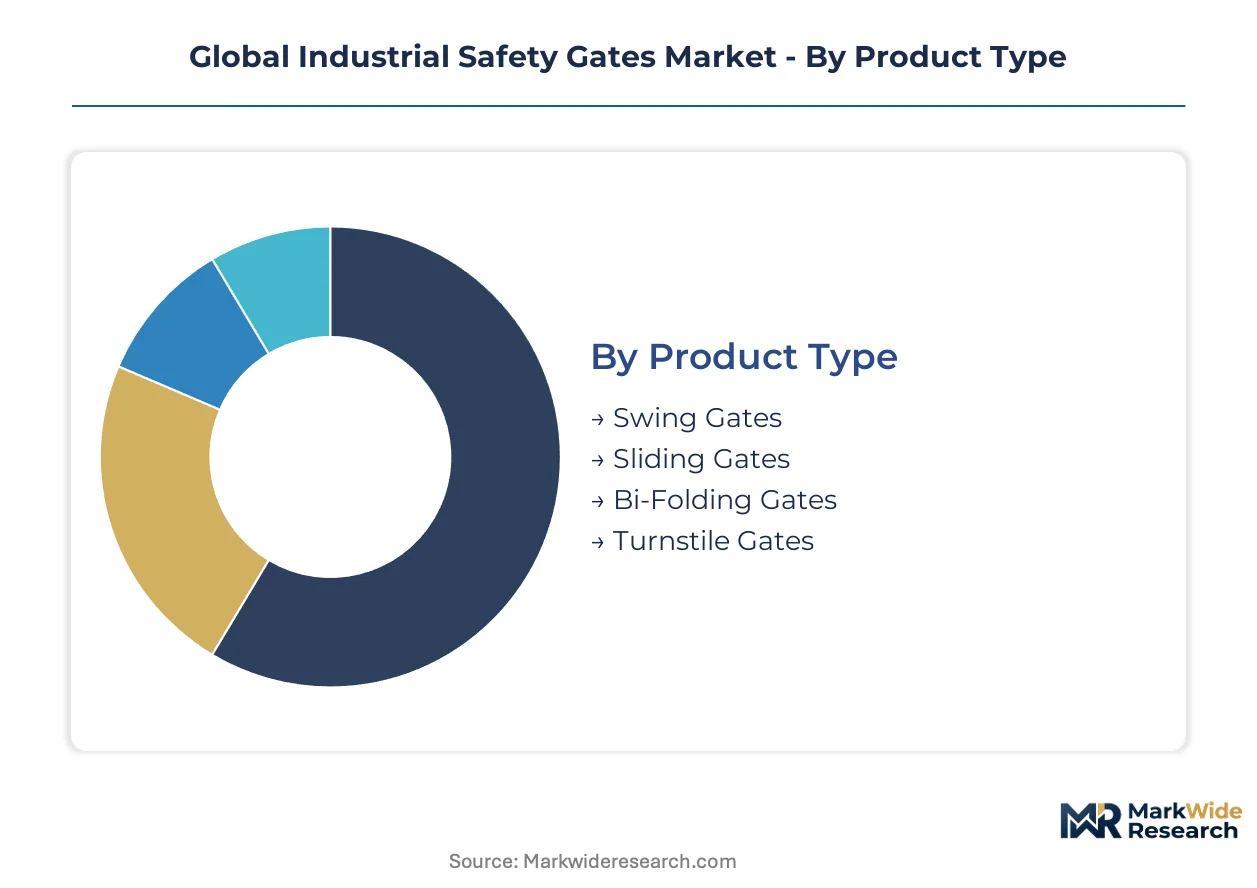
Segmentation in industrial safety gates reveals how certification requirements, material specifications, and end-use environments reshape procurement patterns. Buyers select configurations based on load-rating mandates from OSHA and ISO 14120, corrosion exposure levels, and integration complexity with existing access control infrastructure.
Product Type:
OSHA mandates self-closing functionality and specific load ratings for gates near unprotected edges, while ISO 14120 testing protocols govern swing and sliding configurations for cross-border equipment sales in Europe. CE marking requirements under the EU Machinery Directive add compliance layers for automated gate systems with sensor integration.
- Swing Gates:Hinged barrier systems fabricated from steel or aluminum with load-rated pivot mechanisms and spring-assisted closure. Automotive assembly plants in Germany specify these for pedestrian walkways adjacent to production lines, driven by mechanical simplicity and compatibility with legacy fencing infrastructure. OSHA edge protection mandates accelerate replacement cycles in US food processing facilities.
- Sliding Gates:Horizontal-movement barriers mounted on overhead tracks or ground-level guides, optimized for space-constrained environments. Battery manufacturing facilities in South Korea deploy sensor-equipped sliding configurations to maintain cleanroom integrity while enabling automated material flow integration.
- Bi-Folding Gates:Collapsible barrier systems with dual-panel articulation for reduced swing radius requirements. Compact footprint suits narrow warehouse aisles and mezzanine platforms where standard gate arcs exceed available clearance.
- Turnstile Gates:Rotating access control barriers with unidirectional or bidirectional passage capability. Data centers in the United States integrate these with biometric credentialing systems for perimeter security hardening.
Swing gates sit at the top of the volume ranking, with sliding gates climbing the fastest as automation retrofit demand intensifies.
Material:
Cost tiers stratify sharply between commodity steel and specification-grade composites, with aluminum occupying a mid-market position where weight reduction justifies premium pricing over galvanized alternatives.
- Steel:Hot-rolled and cold-formed carbon steel with zinc galvanizing or powder coating for corrosion resistance. Standard specification for heavy-duty manufacturing environments in the United States and Germany, though price volatility in Chinese coil markets squeezes fabricator margins on volume contracts.
- Composite:Fiberglass-reinforced polymer formulations eliminating metallic corrosion in chemical exposure environments. Chemical manufacturers in Belgium and the Netherlands specify these to satisfy REACH substance restrictions on hexavalent chromium plating while eliminating galvanizing maintenance cycles.
- Aluminum:Extruded alloy systems with anodized or powder-coated finishes offering weight reduction and recyclability advantages. EU Green Deal procurement criteria favor aluminum suppliers with verified environmental product declarations in public infrastructure tenders.
- Plastic:Injection-molded polymer barriers for light-duty applications and temporary installations. Lowest cost tier captures short-duration project demand in construction and event management sectors.
Steel dominates absolute volume, while composite materials gain share fastest as corrosion-resistant specifications proliferate.
End User:
Customer type determines specification intensity, with manufacturing and oil & gas demanding third-party certified systems while warehousing prioritizes cycle speed and WMS integration.
- Manufacturing:Automotive, electronics, and pharmaceutical production facilities requiring guard synchronization with automated production lines. German automotive clusters drive specification-grade procurement with integrated sensor packages and predictive maintenance capabilities.
- Warehousing:Distribution and fulfillment centers retrofitting aging infrastructure with automated access solutions. E-commerce operators with multi-site footprints in the United States standardize on modular configurations with RFID tracking integration.
- Construction:Temporary and permanent barrier needs across commercial and infrastructure projects. Flexible deployment schedules favor rental and lease models over capital purchase in this segment.
- Oil & Gas:Offshore platforms, refineries, and pipeline facilities with explosive atmosphere and marine corrosion requirements. Ex-certified gate systems command substantial premiums for hazardous zone deployment.
Manufacturing anchors volume demand, with warehousing expanding most quickly as logistics automation accelerates.
Application:
Maturity gradients separate established safety compliance specifications from emerging integrated security applications, with emergency egress representing the most regulated deployment category.
- Safety Compliance:Fall protection and edge guarding systems meeting OSHA and ISO 14120 load-rating and self-closing mandates. Third-party certification and documented traceability support premium pricing in regulated industries.
- Access Control:Credential-verified entry systems merging physical barriers with digital authentication. Critical infrastructure operators in the United States and South Korea specify biometric-integrated configurations for data center and utility perimeter hardening.
- Emergency Exits:Egress-compliant gates with panic release mechanisms and minimum opening force requirements. Building code alignment with fire safety regulations drives specification in commercial and industrial construction.
- Crowd Management:High-throughput directional flow control for transportation hubs and event venues. Turnstile and barrier configurations optimize passenger processing rates in rail and aviation terminals.
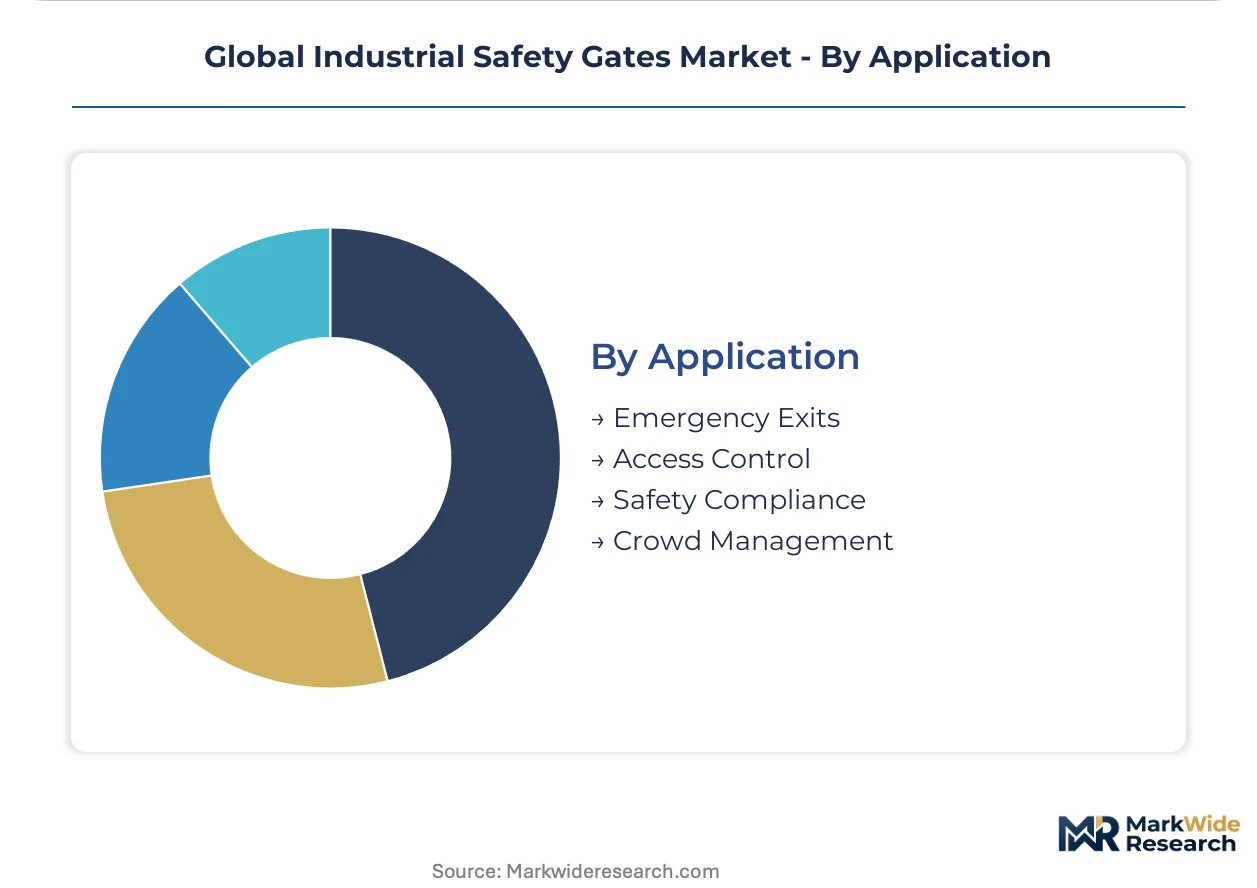
Safety compliance commands the largest revenue share, with access control demonstrating the steepest expansion trajectory as physical-digital security convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial safety gate manufacturing traces its commercial origins to post-war industrialization in Germany and the United States, where automotive and chemical sectors first codified fall protection standards. German engineering firms pioneered modular barrier systems in the 1960s, establishing design conventions that persist in ISO 14120 protocols today.
United States
Warehouse automation retrofits drive specification-grade procurement across aging distribution networks. OSHA enforcement protocols for unprotected elevated platforms mandate load-rated self-closing systems in food processing and chemical handling operations. E-commerce fulfillment clusters in Pennsylvania and Ohio standardize on sensor-integrated configurations with warehouse management system compatibility.
Germany
Automotive and chemical manufacturing clusters anchor European demand for certification-intensive barrier systems. EU Machinery Directive and CE marking requirements shape product development cycles for automated gate systems with integrated sensors. Industrial corridors in Bavaria and Baden-Württemberg specify predictive maintenance-capable configurations for synchronized production line access.
China
Steel fabrication capacity concentrates in coastal provinces serving domestic infrastructure and export markets. GB standards and MIIT industrial safety regulations govern domestic procurement specifications for manufacturing facilities. Yangtze River Delta electronics manufacturing hubs generate demand for cleanroom-compatible access control integration.
India
PLI scheme incentives for electronics and pharmaceutical production create specification-grade demand in greenfield facilities. BIS certification requirements and factory safety regulations mandate third-party tested barrier systems for new industrial construction. Manufacturing corridors near Chennai and Hyderabad specify corrosion-resistant configurations for tropical operating environments.
Netherlands
REACH substance restrictions on hexavalent chromium plating redirect procurement toward powder-coated and composite alternatives. Port and petrochemical infrastructure in Rotterdam drives demand for marine-corrosion-resistant access systems. Chemical manufacturers in Belgium-Netherlands border regions specify fiberglass-reinforced polymer gates to eliminate galvanizing maintenance cycles.
Global Industrial Safety Gates Market Competitive Environment
The competitive structure tilts toward diversified industrial conglomerates with electromechanical integration capabilities. Three tiers separate specification-grade certification specialists from volume fabricators and regional installation service providers. Consolidation pressure concentrates among mid-scale fabricators facing steel price volatility and extended certification timelines. Dominant competitive moves include strategic partnerships for sensor technology licensing and backward integration into aluminum extrusion and composite molding operations.
Among diversified industrial access control conglomerates, ASSA ABLOY AB exemplifies the electromechanical integration archetype through bundled hardware-credentialing systems. Kee Safety Inc. and Rite-Hite Holding Corporation occupy differentiated positions within the specialist tier, representing modular connection technology and high-throughput manufacturing environment expertise respectively. These three anchors illustrate how competitive positioning separates electromechanical convergence plays from mechanical specialization and cycle-speed optimization strategies.
| Leading Market Players |
|---|
| Abbey Gates |
| Ametco Manufacturing Corp. |
| ASSA ABLOY AB |
| Avon Barrier Corp. Ltd. |
| Benko Products Inc. |
| FAAC Spa |
| Kee Safety Inc. |
| A-Safe Ltd. |
| Rite-Hite Holding Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade premium tiers separating OSHA-compliant sensor-integrated systems from commodity steel barriers manifest in divergent supply chain footprints, with specification-grade procurement tethered to European and North American fabrication while volume steel production feeds from Asian coil markets. This bifurcation concentrates pricing power among electromechanical integrators serving regulated industries while squeezing margins for standardized fabricators exposed to raw material volatility.
Pricing Analysis
Three-tier pricing structure across premium specification-grade, mid-market aluminum, and economy steel levels governs procurement negotiations, with ISO 14120 and OSHA certification tiers commanding substantial premiums over uncertified alternatives. Price differentiation hinges on third-party testing documentation and sensor integration complexity, with automated gate systems carrying material premiums over mechanical equivalents. Cost compression in standard steel product lines is intensifying because hot-rolled coil fluctuations in China transmit directly to fabricator margins. Warehousing operators demonstrate highest price sensitivity due to multi-site standardization mandates, while oil and gas facilities show lowest sensitivity given hazardous zone certification requirements.
Supply Chain Analysis
Freight cost differentials between Asian steel coil sources and European fabrication centers are reshaping regional procurement patterns for commodity-grade barriers. Supply concentrates in China for raw steel inputs, Germany for precision-engineered specification systems, and the United States for integrated access control packages. Raw material dependencies center on hot-rolled carbon steel, fiberglass-reinforced polymer resins, and aluminum extrusion billets. Single-source vulnerability in Chinese coil supply creates exposure to tariff and logistics disruption. Distribution runs through manufacturer-direct channels for specification-grade projects and industrial distributors for volume replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European regulatory stringency on REACH substance restrictions and CE marking creates cost and compliance differentials against Asian manufacturing bases.
For Market Incumbents: To counter modular flexible barrier substitutes capturing short-duration project demand, incumbent gate manufacturers should deepen backward integration into aluminum extrusion and composite molding operations while accelerating sensor technology licensing partnerships. Certification investment in ISO 14120 testing capacity represents the critical defensive lever against European competitors exploiting third-party laboratory backlogs. For New Entrants and Emerging Players: Sensor-enabled predictive maintenance platforms offer the most penetrable technology-first wedge for new market entry, with white-space concentration in Indian pharmaceutical and electronics manufacturing corridors where PLI scheme incentives are greenfielding specification-grade demand. Targeting corrosion-resistant composite configurations for chemical manufacturers in Belgium and the Netherlands provides a defensible beachhead against established steel-centric incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale fabricators possessing captive aluminum extrusion capabilities and verified environmental product declarations aligned with EU Green Deal procurement scoring. Long-term viability over the analysis window favors targets with service contract revenue streams displacing manufacturer-direct technician deployment. Watch for inflection signals in Indian BIS certification harmonization with ISO protocols as a trigger for consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive supply of EU Green Deal-compliant material secures public infrastructure tender eligibility. |
| Sensor Technology Licensing Partnership | Photoelectric edge detection integration addresses German automotive assembly plant procurement specifications. |
| Lifecycle Service Contract Unbundling | Third-party maintenance networks capture recurring revenue from e-commerce fulfillment multi-site operators. |
| Composite Material R&D Expansion | Fiberglass-reinforced polymer development eliminates REACH hexavalent chromium compliance exposure. |
| Indian Manufacturing Footprint Establishment | PLI scheme electronics and pharmaceutical corridors near Chennai generate specification-grade greenfield demand. |
Study Parameters
Multiple input streams — primary interviews with plant engineers and maintenance directors, secondary validation through OSHA enforcement databases and EU Machinery Directive filings, and customs trade flow analysis — were reconciled to construct market estimates. Stakeholder consultations included safety compliance officers at automotive manufacturers, procurement leads at warehousing operators, and aftermarket service heads at distribution networks. Secondary sources encompassed SEC 10-K filings, BIS certification registries, and trade association technical bulletins. Bottom-up facility-level demand aggregation was cross-checked against top-down industrial construction spending patterns.
Data-stream reconciliation across product type, material grade, end-use industry, and regional regulatory cluster dimensions anchored the analytical framework. CAGRs were derived from segmented growth rate modeling applied across the projection horizon. Industry-specific forecast inputs included warehouse automation retrofit timelines and REACH substance restriction implementation schedules. Volume and value outputs reflect triangulation between equipment shipment tracking and end-user capital expenditure surveys.
The model holds under stable regulatory enforcement intensity and continued steel price volatility within historical bands; deviation in OSHA mandate acceleration or Chinese environmental policy tightening would shift replacement cycle assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Electronic Security Systems Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Global Automatic Door Control Market
Access Control Systems
Wireless Security System Market
Access Control Systems
Mobile Turnstile Market
Access Control Systems
Anti-Theft System Market
Access Control Systems
Smart Locker Locks Market
Access Control Systems
APAC Home Security System Market
Access Control Systems
Car Security System Market
Access Control Systems
Latin America Card-Based Access Control Market
Access Control Systems
Mechanical Locks Market
Access Control Systems
Airport Passenger Screening System Market
Access Control Systems
Global Industrial Access Control Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Card-Based Electronic Access Control Systems Market