
 Programmable Safety Systems Market | 2026-2036
Programmable Safety Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable Safety Systems Market Analytics
Sil-3 certification tier is collapsing the gap between premium safety architectures and mid-market machine builders. Siemens AG leverages its TÜV-certified portfolio to anchor demand across process industries. Rockwell Automation competes through embedded safety motion control in North American automotive lines. Pilz GmbH & Co. KG specializes in modular safety relay modules for small-to-medium German machinery OEMs.
Programmable safety systems comprise certified logic solvers, input devices, and actuators engineered to execute safety functions with quantified reliability levels such as SIL 1 through SIL 3 per IEC 61508. These systems perform emergency shutdown, guard monitoring, and safe motion control to prevent personnel injury and equipment damage in hazardous operating environments. Safety controllers lead product type demand where process industries require centralized diagnostics, while safety-integrated PLCs represent the fastest-growing technology segment as machine builders consolidate standard and safety control on single hardware platforms. Machine safety applications capture the largest application share, though process safety applications command higher per-unit value due to redundant architecture requirements.
IEC 61508 and ISO 13849 shape functional safety design rules across EU machinery exports, while OSHA lockout-tagout enforcement in the United States drives retrofit demand in legacy manufacturing plants. China's GB standards and SAMR certification timelines increasingly determine market access for imported safety controllers. Stakeholders must monitor divergence between regional certification reciprocity agreements and emerging cybersecurity annexes to functional safety standards.
Market Dynamics
The programmable safety systems market is undergoing structural compression as machine builders consolidate standard and safety control architectures onto unified hardware platforms, collapsing the historical separation between process automation and discrete manufacturing safety tiers.
Growth Catalysts
- IEC 61508 Functional Safety Mandates:European machinery exports face tightening SIL certification thresholds, forcing OEMs to embed certified safety controllers or risk market exclusion.
- Automotive Assembly Line Modernization:North American vehicle manufacturers are retrofitting legacy stamping and welding lines with safety-integrated PLCs to reduce wiring complexity and downtime.
- China's SAMR Certification Timelines:Accelerated mandatory compliance windows for imported industrial controllers are compressing procurement cycles and favoring pre-certified suppliers.
Market Restraints
- Semiconductor Component Volatility:Safety-rated microcontrollers and ASICs face extended lead times from concentrated Taiwanese foundry capacity, delaying controller production.
- Specialized Engineering Talent Scarcity:Functional safety design expertise remains concentrated in Germany's industrial automation corridor, constraining rapid scale-up elsewhere.
- Legacy System Interoperability Friction:Proprietary fieldbus protocols in installed process safety systems resist seamless integration with Ethernet-based safety architectures.
Strategic Opportunities
- Indian Manufacturing Safety Underpenetration:Domestic machinery OEMs serving textiles and food processing remain below global safety controller adoption benchmarks, creating first-mover whitespace.
- Cybersecurity-Functional Safety Convergence:IEC 62443 annexes to safety standards are opening integrated secure safety controller categories for critical infrastructure operators.
- Subscription-Based Safety Validation Services:Cloud-hosted SIL verification tools are emerging as a channel innovation, reducing certification burden for small-to-medium machine builders.
Industry Challenges
- TÜV Certification Timeline Compression:Third-party assessor backlogs are extending SIL 3 validation cycles, delaying product launches and freezing R&D capital.
- Multi-Standard Compliance Burden:Simultaneous ISO 13849, IEC 62061, and regional GB standard adherence is fragmenting engineering resources and documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable Safety Systems Market |
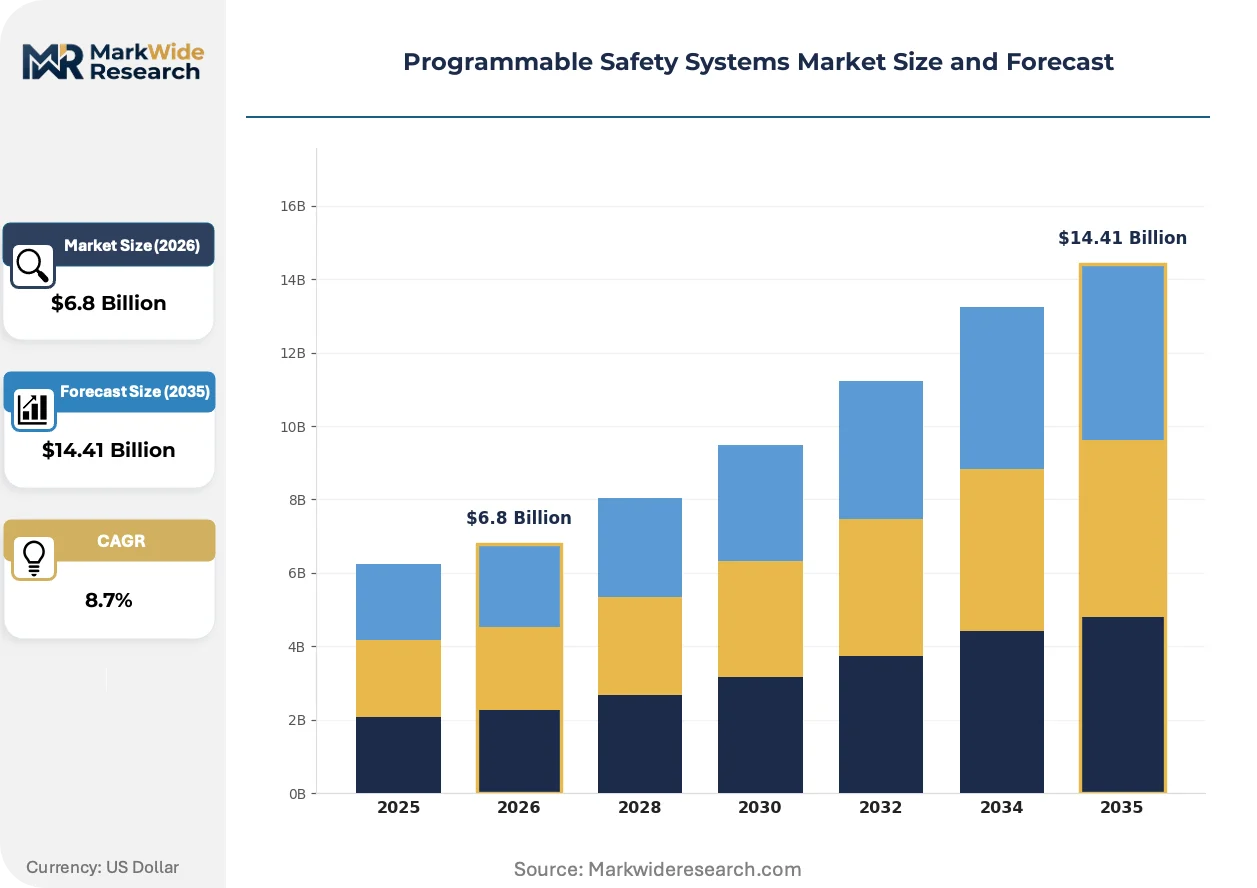
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emergency Stop Systems, Safety Controllers, Safety Relay Modules, Safety Input Devices End User: Manufacturing, Oil & Gas, Healthcare, Automotive Technology: Programmable Logic Controllers, Safety-Integrated PLCs, Fieldbus Technologies, Wireless Safety Systems Application: Machine Safety, Process Safety, Functional Safety, Industrial Automation |
| Companies Covered | Rockwell Automation, Siemens AG, Schneider Electric SE, ABB Group, Honeywell, Mitsubishi Electric, Pilz GmbH & Co. KG, Emerson Electric, OMRON Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable Safety Systems Market Evolving Landscape
Functional safety architectures are actively fragmenting across performance tiers as mid-market machine builders reject over-engineered SIL 3 systems while process industries demand higher diagnostic granularity from single-platform controllers.
Safety-integrated drive technology is bifurcating the motion control segment. Safe torque off and safe limited speed functions now ship standard on servo amplifiers for packaging machinery. Automotive tier-one suppliers are specifying these embedded safety features for new electric vehicle battery assembly lines. The technology is bifurcating supplier tiers, separating motion vendors with certified safety stacks from those dependent on external safety relays.
The EU Machinery Regulation's 2023 recast tightens conformity assessment procedures for safety-related control systems. Manufacturers must now document software lifecycle processes under harmonized EN ISO 13849-1:2023. German machinery OEMs exporting to Southeast Asia are front-loading compliance investment to maintain uninterrupted customs clearance, while smaller Italian automation houses face certification cost barriers.
Buyer specification authority is migrating from plant maintenance departments to corporate EHS functions with centralized safety standard mandates. This shift compresses vendor shortlists to pre-approved global suppliers with multi-site service networks. The pattern is most visible in North American chemical processing, where consolidated owner-operators now specify identical safety controller families across geographically dispersed facilities.
Programmable Safety Systems Market Segmentation
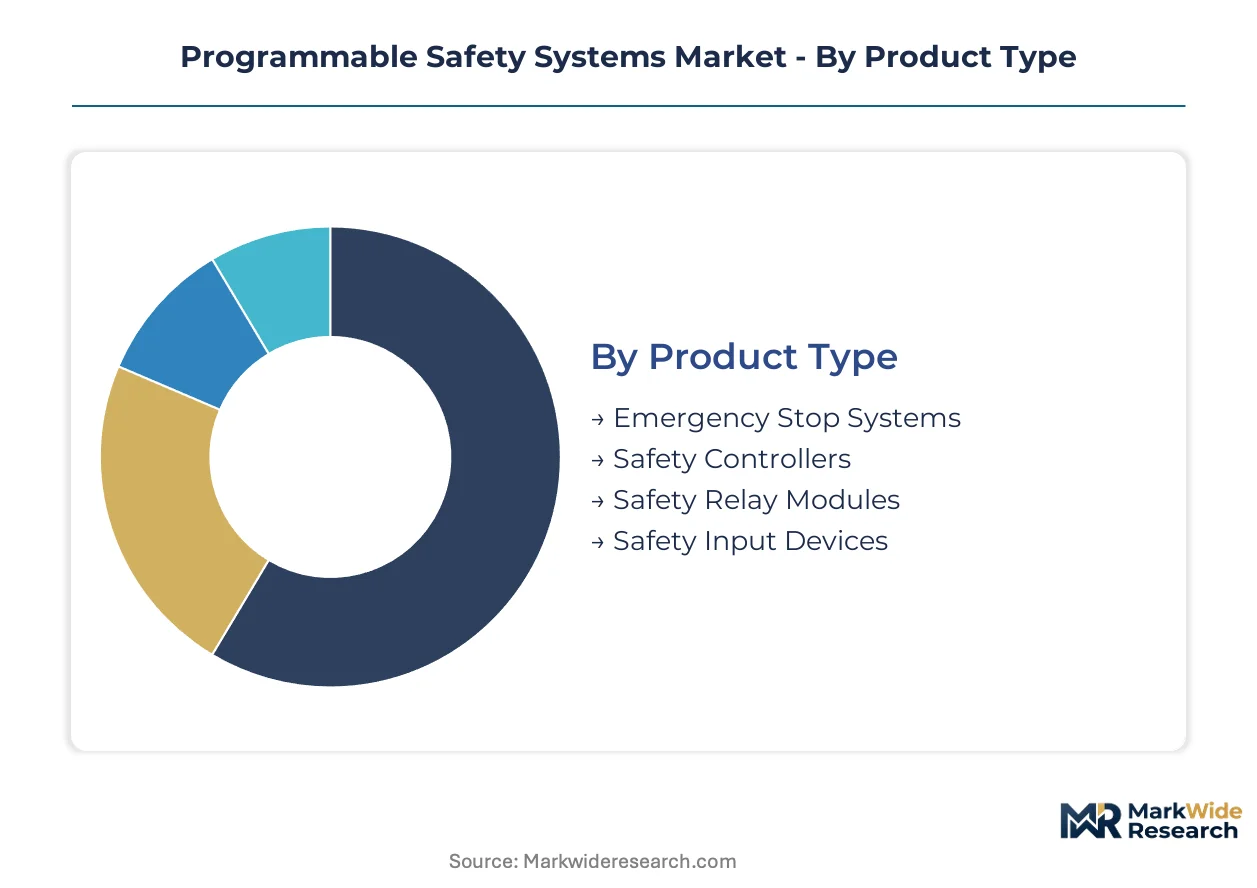
Programmable safety systems fragment across four critical dimensions where substitution pressure varies sharply. Product architecture determines integration depth with standard automation, while end-user verticals impose divergent certification burdens and lifecycle expectations.
Product Type:
Safety relay modules face the steepest substitution pressure as machine builders consolidate toward programmable platforms that eliminate hardwired logic.
- Safety Controllers:Centralized logic solvers with SIL-certified diagnostics manage multiple safety zones through modular I/O architectures. German automotive OEMs specify these for welding line retrofits where single-point configuration replaces distributed relay cabinets. IEC 61508 compliance mandates are compressing procurement toward pre-certified platforms.
- Safety Relay Modules:Standalone electromechanical or solid-state relays execute discrete safety functions without programming capability. Small Italian packaging machinery builders still specify these for cost-sensitive export equipment, though volume is eroding as safety-integrated PLCs penetrate the mid-market.
- Emergency Stop Systems:Hardwired mushroom-button circuits with positive-break contacts remain mandatory for localized hazard isolation.
- Safety Input Devices:Light curtains, laser scanners, and safety mats provide presence-sensing inputs to controller architectures.
Safety controllers anchor the volume base while safety-integrated PLCs gain share at the steepest rate.
End User:
Margin concentration follows application criticality, with process industries commanding premium pricing for redundant architectures that manufacturing verticals rarely require.
- Oil & Gas:Upstream and downstream facilities deploy triple-modular-redundant safety instrumented systems for emergency shutdown. US Gulf Coast refineries specify SIL 3 fire and gas detection loops where regulatory enforcement by OSHA and EPA drives replacement cycles.
- Automotive:Vehicle manufacturers consolidate stamping press safety with motion control on single platforms. Battery assembly lines for electric vehicles specify safe torque-off servo drives to reduce wiring complexity and commissioning time.
- Manufacturing:Discrete production machinery spans food processing to metal fabrication with variable safety depth.
- Healthcare:Medical device manufacturing and hospital infrastructure deploy lower-complexity safety monitoring for radiation equipment and robotic surgery systems.
Manufacturing generates the largest unit volume while automotive exhibits the steepest expansion trajectory.
Technology:
Protocol standardization is accelerating displacement of proprietary fieldbus architectures by Ethernet-based safety networks with integrated diagnostics.
- Safety-Integrated PLCs:Unified hardware platforms execute standard and safety control tasks through certified software partitions. Machine builders in Germany's industrial automation corridor favor these to reduce panel space and eliminate separate safety controller hardware.
- Programmable Logic Controllers:Traditional PLCs with safety function blocks operate in legacy installations where full replacement is capital-constrained.
- Fieldbus Technologies:DeviceNet Safety, PROFIsafe, and CIP Safety protocols persist in installed process systems.
- Wireless Safety Systems:Industrial Wi-Fi and dedicated safety radio enable mobile equipment protection where cabling is impractical.
Programmable logic controllers retain the largest installed base while safety-integrated PLCs are climbing the fastest.
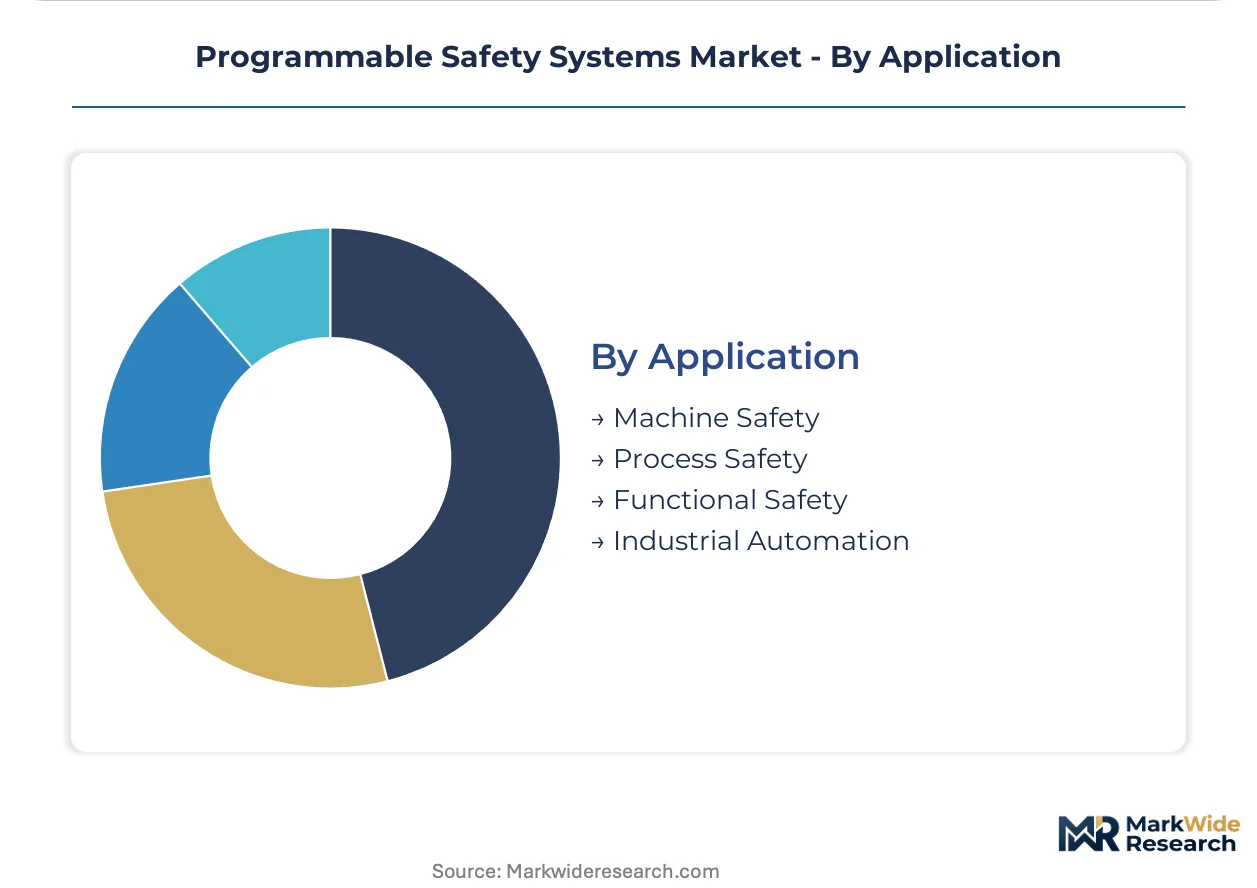
Application:
Customer specification authority migration toward corporate EHS functions is collapsing vendor shortlists to suppliers with multi-site service networks.
- Machine Safety:Guard interlocking, presence sensing, and safe motion control protect operators from mechanical hazards. Packaging machinery OEMs in Italy and Spain specify modular safety controllers to maintain CE marking compliance for EU exports.
- Process Safety:Safety instrumented systems monitor pressure, temperature, and flow to trigger emergency shutdown. US chemical processing plants face intensified OSHA enforcement of lockout-tagout procedures, accelerating retrofit demand.
- Functional Safety:Systematic design approaches per IEC 61508 govern safety lifecycle management across industries.
- Industrial Automation:Broad integration of safety with general automation architectures spans discrete and process manufacturing.
Machine safety commands the largest revenue pool while process safety exhibits the steepest value-per-unit expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German machinery OEMs export safety-certified controllers throughout Southeast Asia and North America, creating compliance-driven procurement corridors that shape regional demand patterns.
Germany
Automotive stamping lines and battery assembly plants in Stuttgart and Munich drive SIL 3 controller procurement. TÜV certification requirements under EU Machinery Regulation 2023 recast force exporters to front-load compliance documentation. The industrial automation corridor spanning Baden-Württemberg and Bavaria concentrates machinery OEM specification authority for export-bound equipment.
United States
Gulf Coast refineries and chemical processing clusters demand redundant safety instrumented systems for emergency shutdown loops. OSHA enforcement of lockout-tagout procedures accelerates retrofit cycles in legacy manufacturing plants. Houston and Baton Rouge petrochemical complexes specify identical safety controller families across dispersed facilities to standardize maintenance protocols.
China
Electric vehicle battery assembly expansion in Shanghai and Shenzhen pulls safety-integrated PLC demand from automotive tier-one suppliers. SAMR certification timelines compress procurement windows for imported industrial controllers. Yangtze River Delta machinery builders face accelerated mandatory compliance deadlines that favor pre-certified European and Japanese suppliers.
Japan
Robotics and semiconductor equipment manufacturers in Nagoya and Osaka embed safe motion control in precision assembly systems. METI industrial safety guidelines tighten conformance assessment for machinery exports to ASEAN markets. Kyushu-based automotive component suppliers specify embedded safety features to reduce wiring complexity in electric powertrain assembly.
India
Textile and food processing machinery OEMs in Gujarat and Maharashtra remain below global safety controller adoption benchmarks. BIS certification alignment with IEC 61508 creates first-mover opportunities for certified suppliers. Tamil Nadu automotive component clusters show nascent demand for safety-integrated PLCs as export quality requirements tighten.
Programmable Safety Systems Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and vertical integration intensity. Siemens AG and Rockwell Automation anchor the premium tier through TÜV-certified portfolios and embedded safety motion control, while Pilz GmbH occupies the modular safety relay segment. The vendor base stratifies into three archetypes: diversified automation conglomerates, safety-focused specialists, and regional system integrators. Competitive moves center on consolidating standard and safety control architectures onto unified hardware platforms, and on cloud-hosted SIL verification services that reduce certification burden for smaller machine builders.
Within the diversified automation tier, Siemens AG and Rockwell Automation exemplify scale-driven platform consolidation, while ABB Group and Schneider Electric SE occupy positions spanning process and discrete manufacturing safety. Honeywell and Emerson Electric sit within the process safety archetype serving oil and gas and chemical verticals. Pilz GmbH & Co. KG represents the specialist model focused on modular safety architectures for German machinery OEMs. Mitsubishi Electric and OMRON Corp. anchor the Asia-Pacific supply vector with regional certification expertise.
| Leading Market Players |
|---|
| Rockwell Automation |
| Siemens AG |
| Schneider Electric SE |
| ABB Group |
| Honeywell |
| Mitsubishi Electric |
| Pilz GmbH & Co. KG |
| Emerson Electric |
| OMRON Corp. |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts between German machinery OEMs and Taiwanese semiconductor foundries lock in safety-rated microcontroller supply while capping unit cost volatility for SIL-certified controllers. These arrangements bind safety controller manufacturers to minimum volume commitments in exchange for allocation priority during foundry capacity constraints.
Pricing Analysis
Current-generation safety-integrated PLCs command 40-60% premiums over prior-generation safety relay modules, while next-generation secure safety controllers with embedded cybersecurity stacks are entering at additional markups. Pricing stratifies across SIL certification tiers, with SIL 3 architectures carrying significant premiums over SIL 2 equivalents due to redundant diagnostic requirements and TÜV validation costs. Cost compression in the safety relay tier is intensifying because machine builders consolidate toward programmable platforms, forcing relay specialists to absorb certification overhead across shrinking volumes. Small-to-medium Italian packaging machinery OEMs exhibit the highest price sensitivity, prioritizing CE marking compliance at minimum cost, while US Gulf Coast petrochemical operators show lowest sensitivity due to regulatory-driven replacement mandates and downtime cost exposure.
Supply Chain Analysis
Strategic stockpiling of safety-rated ASICs and industrial-grade FPGAs dominates inventory strategy among German and Japanese safety controller manufacturers, contrasting with just-in-time preferences for standard automation components. Concentrated supply rests on Taiwan for safety microcontroller fabrication, Germany for precision electromechanical relay production, and Japan for industrial optical components in safety input devices. Critical dependencies include silicon wafers from Taiwanese foundries, rare earth elements for magnetic actuators sourced from Chinese processors, and specialized epoxy resins for high-reliability encapsulation. Single-source vulnerability concentrates in 28nm automotive-grade microcontroller supply from TSMC's dedicated capacity. Distribution runs through authorized industrial automation distributors with certified application engineering support, bypassing commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer specification authority is concentrating in corporate EHS functions with centralized multi-site mandates, compressing vendor shortlists to pre-approved global suppliers and eroding pricing power for regional specialists without service network scale.
For Market Incumbents: Compound platform consolidation advantages by embedding safety motion control deeper into servo drive architectures, eliminating external safety relay dependencies for automotive battery assembly lines. Accelerate TÜV pre-certification of unified hardware platforms to capture procurement cycles compressed by China's SAMR compliance windows. Counter emerging cloud-hosted SIL verification services by bundling validation tools with hardware subscriptions to retain small-to-medium machine builder relationships. For New Entrants and Emerging Players: Differentiate on cybersecurity-functional safety convergence by developing IEC 62443-annexed secure safety controllers for critical infrastructure operators underserved by legacy suppliers. Target India's textile and food processing machinery OEMs in Gujarat and Maharashtra, where safety controller penetration sits below global benchmarks and BIS certification alignment with IEC 61508 creates first-mover whitespace. Deploy subscription-based safety validation services to reduce certification burden for cost-constrained small machine builders. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among safety controller vendors with cloud-hosted diagnostics and subscription validation services, offering superior cash flow predictability over transactional hardware models. Over the projection horizon, vertically integrated specialists with captive semiconductor sourcing and multi-regional certification expertise present acquisition profiles with defensive moats against foundry volatility. Watch for inflection when SAMR reciprocity agreements with EU notified bodies accelerate, signaling procurement normalization for pre-certified European suppliers in China's Yangtze River Delta automotive clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Safety-Integrated PLC Platform Launch | Consolidates standard and safety control to reduce wiring complexity in German automotive lines. |
| Backward Integration into ASIC Design | Captures safety microcontroller specification authority away from Taiwanese foundry dependencies. |
| Cloud-Hosted SIL Verification Service | Reduces TÜV certification burden for small Italian packaging machinery OEMs. |
| Cybersecurity-Functional Safety Certification | Opens IEC 62443-annexed secure controller categories for US critical infrastructure. |
| Regional Certification Reciprocity Partnership | Accelerates SAMR compliance timelines for European suppliers in China's battery assembly expansion. |
Research Methodology
A spread of perspectives from machinery OEM procurement directors, plant safety engineers, TÜV certification assessors, and industrial automation distributors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against IEC 61508 implementation databases, EU Machinery Regulation compliance filings, SAMR certification timelines, and OSHA enforcement records. Bottom-up demand estimates from end-user verticals were triangulated against top-down supply-side capacity assessments from safety controller manufacturers.
Segmentation dimensions modeled include product architecture, certification tier, end-user vertical, and regional regulatory cluster across the analysis window. CAGRs were derived from installed base replacement cycles, automotive electrification capital expenditure trajectories, and process safety retrofit mandates. Industry-specific forecast inputs incorporated TÜV validation backlog durations, foundry capacity allocation patterns for automotive-grade silicon, and corporate EHS centralization trends in North American chemical processing.
Material uncertainties — semiconductor supply disruptions, reciprocity agreement negotiations between EU and Chinese regulators, and cybersecurity annex adoption timelines — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification timeline compression and buyer consolidation patterns. Revision becomes warranted when TÜV assessor capacity constraints extend SIL 3 validation cycles beyond critical procurement windows or when SAMR reciprocity agreements materially alter import compliance pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Smart Locker Locks Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Electronic Security Systems Market
Access Control Systems
Home Control and Security Systems Market
Access Control Systems
Modular Biometric Access Control Terminals Market
Access Control Systems
Europe Cylinder Lock Market
Access Control Systems
Network Access Control Market
Access Control Systems
Access Control Readers Market
Access Control Systems
Japan Access Control Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Global Digital Door Lock Systems Market
Access Control Systems
US Access Control Market
Access Control Systems
United States Smart Lock Market
Access Control Systems
Indoor Electromagnetic Lock Market
Access Control Systems
Cylindrical Door Lock Market
Access Control Systems
North America Proximity Access Control Market