
 Multi-Factor Authentication (MFA) Market | 2026-2036
Multi-Factor Authentication (MFA) Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Factor Authentication (MFA) Market Analysis
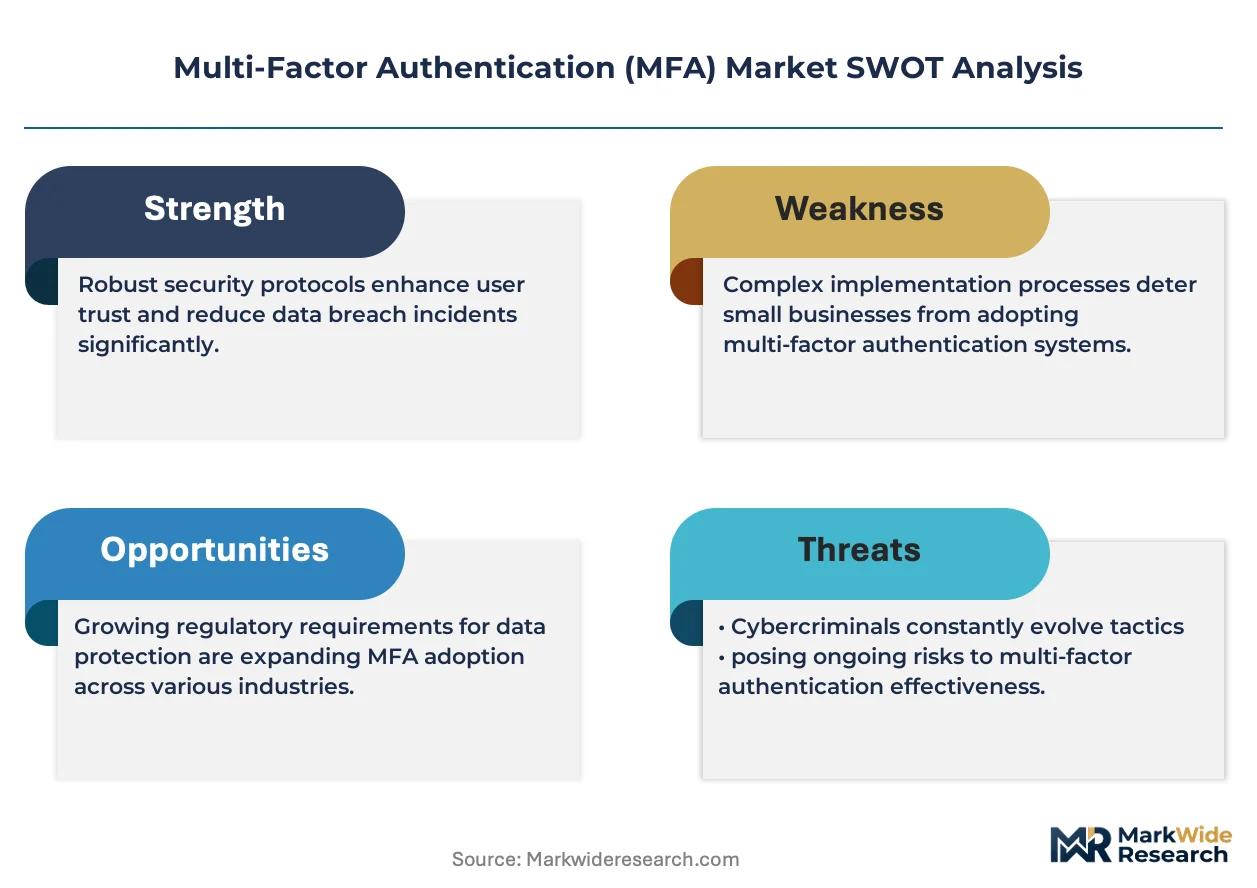
Platform bundling is restructuring buyer choice in enterprise identity stacks. Microsoft Entra ID leverages its Azure ecosystem to anchor bundled MFA within broader cloud security suites. Okta competes through extensive third-party integrations that sustain vendor-neutral positioning. Cisco Duo specializes in zero-trust network access, differentiating its MFA module with device-trust telemetry.
Multi-factor authentication verifies user identity through two or more independent credential categories—typically combining knowledge factors, possession factors, and inherence factors such as biometric templates or FIDO2 hardware keys—to protect against credential theft and unauthorized system access. Cloud-based deployment leads segment growth as organizations retire on-premises identity infrastructure, while biometrics represents the fastest-expanding technology category driven by facial recognition and fingerprint standards. Banking dominates end-user demand due to PSD2 strong-customer-authentication mandates, though healthcare is gaining share as telemedicine platforms require stepped-up provider verification.
NIST 800-63 digital identity guidelines shape product standards across the US federal contracting base, while the EU AI Act imposes conformity requirements on biometric authentication systems deployed in European member states. The SEC's cybersecurity disclosure rules now push publicly traded firms toward auditable MFA implementations. Stakeholders must weigh FIDO Alliance certification against emerging post-quantum cryptographic requirements when selecting long-term authentication architectures.
Market Dynamics
Platform bundling is compressing standalone MFA pricing as hyperscalers integrate authentication into cloud security suites, forcing pure-play vendors to differentiate through specialized zero-trust telemetry or vertical-specific compliance modules.
Growth Catalysts
- PSD2 Strong Customer Authentication:European banking regulators mandate stepped-up verification for electronic payments, driving hardware token and biometric adoption across retail and corporate banking channels.
- Telemedicine expansion:Healthcare providers in France, Germany, and the United States deploy provider-facing MFA to secure remote diagnostic platforms and patient data access.
- FIDO2/WebAuthn standardization:Passwordless authentication protocols gain traction as enterprises retire SMS-based one-time passwords vulnerable to SIM-swapping attacks.
Market Restraints
- Biometric hardware costs:Fingerprint sensors and facial recognition cameras carry 3-5x premiums over software-only solutions, limiting deployment at mid-market scale.
- EU AI Act conformity timelines:Biometric authentication systems face extended certification cycles for high-risk AI categorization, delaying European product launches.
- SMS interception vulnerabilities:Telecom signaling weaknesses expose OTP delivery channels, eroding enterprise confidence in lower-cost authentication tiers.
Strategic Opportunities
- Post-quantum cryptographic migration:NIST-standardized algorithms create replacement demand for FIDO2 hardware keys and public-key infrastructure before cryptanalytically relevant quantum computers emerge.
- Operational technology integration:Manufacturing and energy facilities apply MFA to industrial control system access, extending identity security beyond IT networks.
- India's digital public infrastructure:Aadhaar-linked authentication and RBI guidelines for fintech create localized demand for voice and fingerprint biometric modules.
Industry Challenges
- Legacy identity system integration:Enterprises with Active Directory forests built over decades face complex migration paths to cloud-native authentication architectures.
- Zero-trust architecture skill scarcity:Security architects capable of designing device-trust telemetry and continuous authentication policies command premium compensation, constraining implementation velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Factor Authentication (MFA) Market |
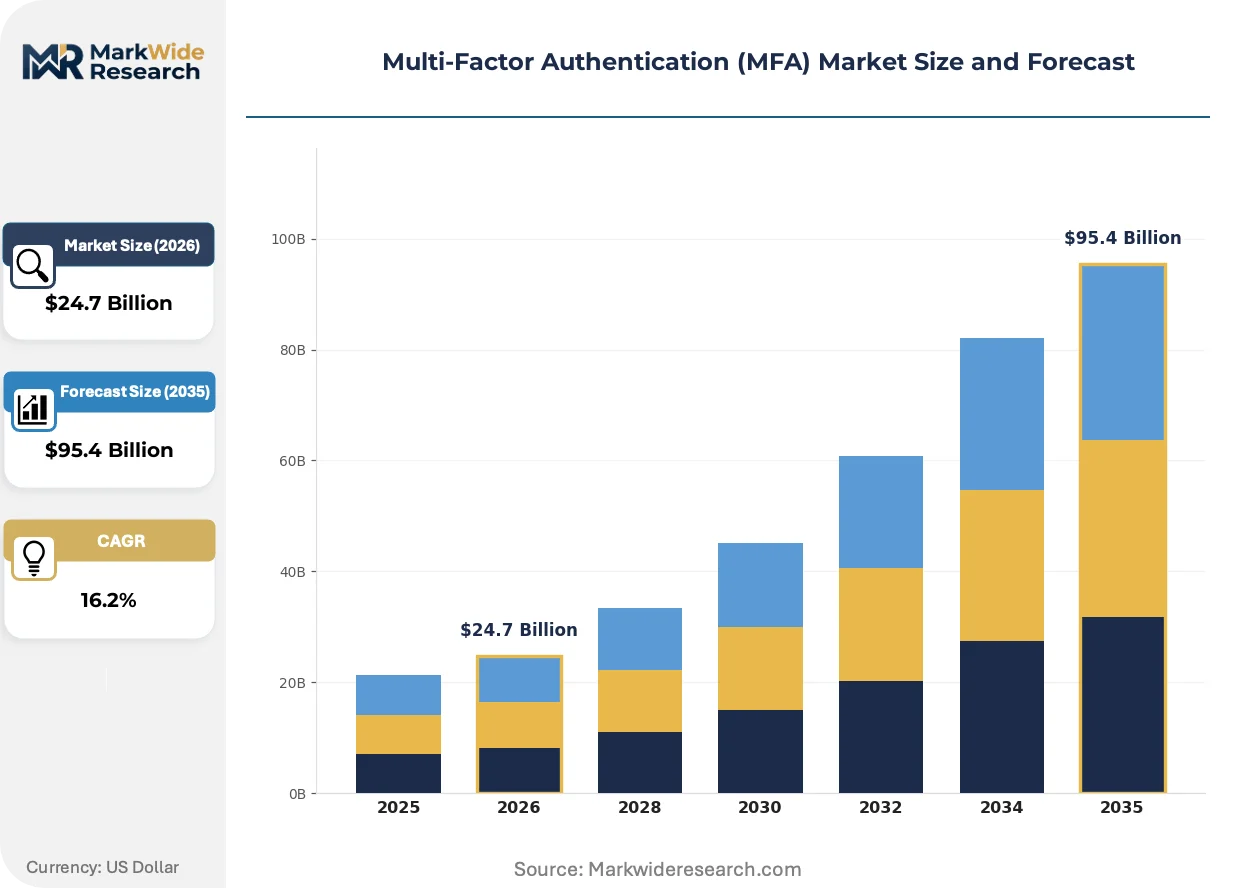
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $95.4 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Technology: SMS, Email, Biometrics, Hardware Token End User: Banking, Healthcare, Government, Retail Service Type: Consulting, Implementation, Support, Maintenance |
| Companies Covered | ManageEngine, FusionAuth, Okta, IBM Verify, Descope, Cisco Duo, LastPass, SecurID, Microsoft Entra ID, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Factor Authentication (MFA) Market Emerging Trajectories
Authentication infrastructure is converging on continuous, risk-based verification models that replace static password gates with contextual trust scoring drawn from device posture and behavioral biometrics.
Passkey technology is unifying consumer and enterprise authentication under a single cryptographic standard. Financial services institutions in Germany and the Netherlands are piloting passkey deployments for retail banking apps, eliminating shared secrets while reducing helpdesk password-reset volume. This unification is compressing the addressable market for standalone password managers and SMS OTP gateways.
The SEC's cybersecurity disclosure rules now require publicly traded firms to document authentication control effectiveness in annual filings. Audit committees are mandating FIDO Alliance-certified implementations with attestation capabilities to satisfy external examiner scrutiny. Technology and healthcare sectors are responding fastest, with manufacturing adoption lagging due to operational technology segmentation.
Enterprise buyers are consolidating vendor relationships around identity-platform ecosystems rather than procuring point-solution MFA. Security teams at Fortune 500 firms now evaluate authentication modules primarily through integration depth with existing SIEM and SOAR investments. This preference shift is visible most acutely in the United States, where CISOs face board-level pressure to reduce vendor sprawl and streamline incident response workflows.
Multi-Factor Authentication (MFA) Market Segmentation
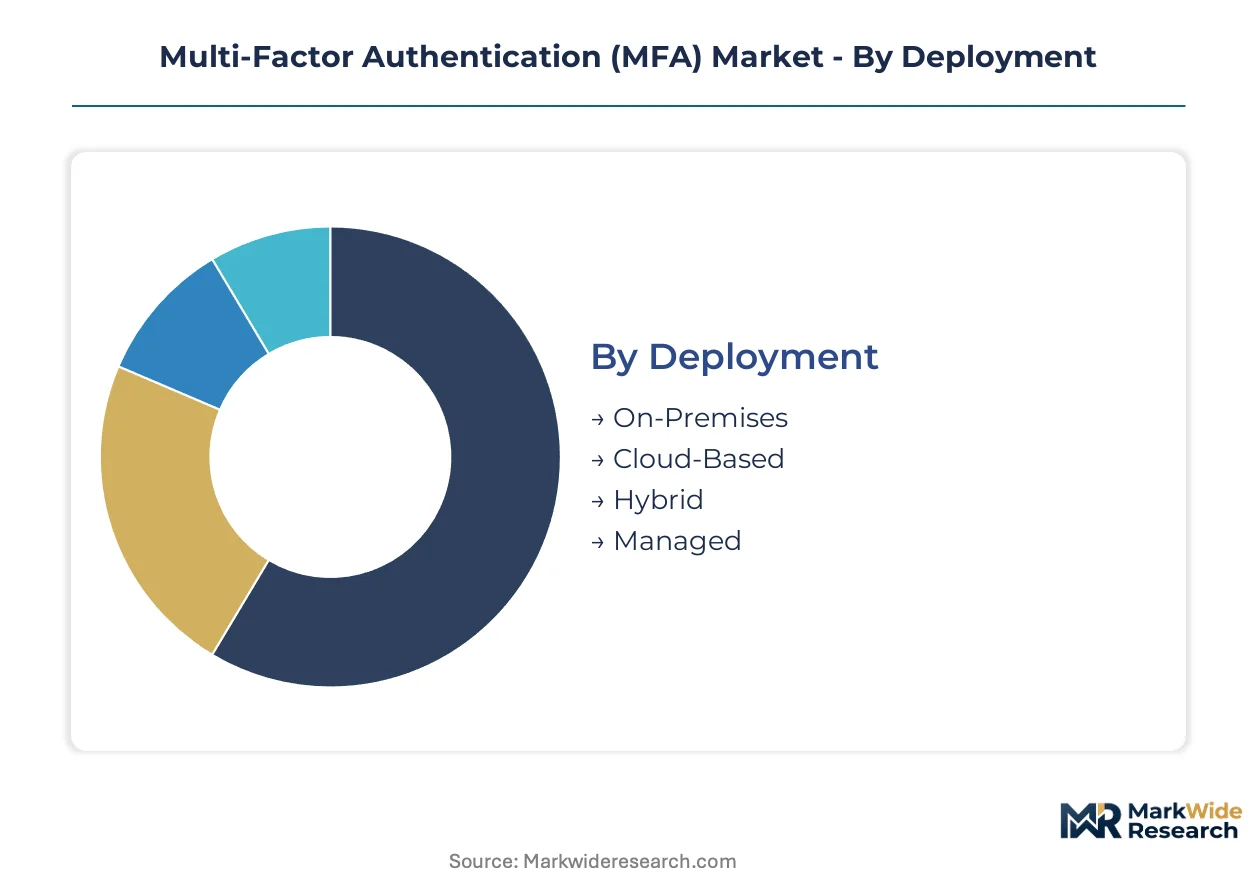
Segmentation in MFA markets reveals how deployment economics, technology maturity, and regulatory pressure fragment buyer requirements across verticals. Understanding these divisions exposes where vendors can defend pricing power versus where commoditization accelerates.
Deployment:
Volume deployments favor cloud delivery for its elimination of capital expenditure, while premium engagements retain on-premises control for air-gapped environments.
- Cloud-Based:Organizations retire identity infrastructure through SaaS consumption models. Demand concentrates in Germany's banking corridor where PSD2 mandates drive rapid cloud migration for retail payment authentication.
- On-Premises:Enterprises maintain physical control over authentication servers and cryptographic key storage. Defense contractors and classified government facilities in the United States require FIPS-validated hardware security modules that resist cloud exfiltration.
- Hybrid:Split architectures preserve sensitive credentials on-site while offloading user directories to cloud identity providers.
- Managed:Outsourced operations transfer authentication infrastructure monitoring to specialized security service providers.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
Technology:
Authentication modalities separate by resistance to interception, with possession factors commanding premium positioning against knowledge-based alternatives.
- Biometrics:Facial recognition and fingerprint templates eliminate shared secrets entirely. France's healthcare digitization hubs deploy provider-facing biometric verification for telemedicine platforms under CNIL oversight.
- Hardware Token:FIDO2 security keys and PKI smartcards provide cryptographic proof of possession. European corporate banking channels adopt hardware tokens to satisfy PSD2 strong-customer-authentication requirements.
- SMS:One-time passwords delivered through cellular networks face SIM-swapping vulnerabilities that erode enterprise confidence.
- Email:OTP distribution through corporate mail systems offers low-friction deployment for workforce authentication at elevated interception risk.
Hardware Token retains the steepest expansion trajectory in regulated finance. Email dominates mid-market cost sensitivity despite known weaknesses.
End User:
Vertical compliance intensity determines authentication sophistication, with financial services and healthcare facing the most stringent identity verification mandates.
- Banking:Retail and corporate payment systems require stepped-up verification under PSD2 and SEC cybersecurity disclosure rules. German and Dutch institutions pilot passkey deployments to eliminate password-reset overhead.
- Healthcare:Telemedicine expansion and HIPAA obligations drive provider authentication investment. United States health systems deploy stepped-up verification for remote diagnostic platform access.
- Government:Federal agencies mandate FIDO Alliance certification with attestation capabilities for external audit compliance.
- Retail:E-commerce platforms balance checkout friction against fraud prevention through risk-based authentication scoring.
Banking absorbs the highest per-seat authentication spend. Retail exhibits the widest deployment variance from SMS to biometric.
Service Type:
Professional services revenue concentrates in complex migration engagements, while recurring support contracts stabilize vendor cash flow.
- Implementation:Active Directory forest migration to cloud-native architectures demands specialized identity engineering for Fortune 500 enterprises.
- Consulting:Zero-trust architecture design and continuous authentication policy development command premium compensation due to skill scarcity.
- Support:Tiered helpdesk operations handle password-reset volume reduction and end-user enrollment assistance.
- Maintenance:Software update delivery and security patch management ensure cryptographic library currency against emerging threats.
Implementation services peak during cloud migration waves. Maintenance contracts extend longest in regulated verticals with audit requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American vendors command premium positioning in cloud-native authentication suites, while European demand concentrates around PSD2 compliance hardware and biometric certification. Asian markets exhibit steepest volume growth as digital public infrastructure programs accelerate.
United States
SEC cybersecurity disclosure rules drive FIDO Alliance-certified implementations at Fortune 500 firms. Federal agencies mandate attestation-capable authentication under NIST 800-63 guidelines. Silicon Valley and Seattle tech corridors anchor cloud identity provider development, with healthcare systems in Boston deploying stepped-up verification for telemedicine platforms.
Germany
PSD2 strong-customer-authentication mandates sustain hardware token demand across retail and corporate banking channels. BaFin oversight tightens audit requirements for payment service providers. Frankfurt's banking corridor concentrates passkey pilot programs, while Munich industrial clusters apply MFA to operational technology access in manufacturing facilities.
France
CNIL oversight shapes biometric authentication deployment timelines under EU AI Act high-risk categorization. Healthcare digitization hubs in Paris and Lyon deploy provider-facing facial recognition for remote diagnostic platforms. Grand Est region pharmaceutical manufacturers integrate MFA into GxP-compliant manufacturing execution systems.
India
RBI guidelines for fintech create localized demand for voice and fingerprint biometric modules linked to Aadhaar infrastructure. Mumbai and Bangalore financial centers pilot passwordless authentication for mobile banking applications. Gujarat pharmaceutical exporters adopt hardware tokens to satisfy EU importer audit requirements.
United Kingdom
FCA operational resilience rules push institutional banks toward auditable MFA architectures with continuous authentication capabilities. London's financial district concentrates zero-trust network access deployments among hedge funds and asset managers. Edinburgh fintech startups leverage cloud-native identity stacks to reduce capital expenditure barriers.
Multi-Factor Authentication (MFA) Market Vendor Landscape
The competitive structure tilts toward platform bundling as hyperscalers absorb authentication into broader cloud security suites. Pure-play vendors defend positioning through specialized zero-trust telemetry or vertical-specific compliance modules. Three archetypes dominate: ecosystem-anchored suites, vendor-neutral integration specialists, and device-trust telemetry providers. M&A activity concentrates on identity orchestration capabilities, while strategic partnerships target post-quantum cryptographic migration.
Within the ecosystem-anchored tier, Microsoft Entra ID and Cisco Duo exemplify platform bundling strategies that compress standalone pricing. Okta occupies a position as the vendor-neutral integration specialist, sustaining third-party connectivity as a differentiation vector against bundled alternatives. These three anchors represent the dominant competitive poles shaping procurement evaluation criteria.
| Leading Market Players |
|---|
| ManageEngine |
| FusionAuth |
| Okta |
| IBM Verify |
| Descope |
| Cisco Duo |
| LastPass |
| SecurID |
| Microsoft Entra ID |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FIDO Alliance-certified hardware tokens and commodity SMS OTP solutions manifests in both pricing power and supplier qualification requirements. Premium vendors command 3-5x unit economics over software-only alternatives while maintaining dual-source manufacturing across Taiwan semiconductor fabs and Shenzhen assembly corridors.
Pricing Analysis
Margin tightening in mid-market cloud deployments reflects hyperscaler bundling strategies that absorb authentication into broader security suites. Subscription SaaS-tiered pricing dominates enterprise procurement, with differentiation resting on FIPS 140-2 certification grade and vertical-specific compliance module depth. Cost compression accelerates in standalone SMS gateway tiers as SIM-swapping vulnerabilities erode buyer confidence. Banking and government verticals exhibit lowest price sensitivity due to audit mandate stringency, while retail e-commerce platforms prioritize friction reduction over security investment.
Supply Chain Analysis
Dual-sourcing requirements from Fortune 500 buyers mandate qualified suppliers across Taiwan, China, and South Korea for FIDO2 security key semiconductor components. Hardware token manufacturing draws from ARM-based secure element chips, biometric sensor modules, and USB-C connector assemblies. Single-source vulnerability concentrates in advanced cryptographic co-processor fabrication. Distribution runs through direct enterprise sales teams for regulated verticals and cloud marketplaces for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform bundling from Microsoft and Cisco is compressing standalone vendor margins, forcing consolidation among pure-play authentication specialists lacking ecosystem anchoring.
For Market Incumbents: Acquire zero-trust telemetry capabilities to differentiate against hyperscaler bundling. Secure device-trust orchestration assets that enable continuous authentication policy enforcement. Deepen FIDO Alliance certification portfolios to satisfy SEC audit committee scrutiny and defend against emerging post-quantum cryptographic entrants. For New Entrants and Emerging Players: The price-point gap between premium hardware tokens and economy SMS tiers offers entry for biometric software solutions targeting healthcare telemedicine expansion. France's CNIL-compliant facial recognition modules and India's Aadhaar-linked voice authentication present white-space opportunities. Partner with regional system integrators to bypass direct competition with entrenched cloud identity providers. For Investors and Strategic Acquirers: Re-rating potential sits with identity orchestration specialists given post-quantum cryptographic migration catalysts. Long-term viability favors vendors with NIST-standardized algorithm roadmaps and FIPS-validated hardware security module integration. Monitor EU AI Act high-risk biometric certification timelines as inflection indicators for European market access trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Migration | NIST-standardized algorithm adoption future-proofs FIDO2 hardware keys against quantum cryptanalysis threats. |
| Zero-Trust Platform Integration | Device-trust telemetry embedding differentiates MFA modules within broader cloud security suite procurement. |
| Vertical Compliance Module Development | PSD2 and HIPAA-specific authentication workflows capture regulated banking and healthcare procurement budgets. |
| Biometric Certification Investment | EU AI Act high-risk system conformity enables European healthcare and government market participation. |
| Operational Technology Extension | Industrial control system MFA deployment extends identity security beyond traditional IT network boundaries. |
Methodological Framework
Document review covered SEC cybersecurity disclosure filings, EU AI Act regulatory texts, and FIDO Alliance certification databases, complemented by interviews with CISOs at Fortune 500 enterprises, identity platform engineers, and healthcare IT security directors. Secondary validation drew from NIST 800-63 guideline publications, PSD2 implementation reports, and cloud hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models and technology categories.
Historical authentication spending patterns cross-referenced against expert panel input on zero-trust adoption velocity shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, authentication modality, end-user vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted growth curves incorporating FIDO2 standardization timelines and biometric hardware cost trajectories. Post-quantum cryptographic readiness and EU AI Act compliance certification cycles served as industry-specific forecast modifiers.
Inputs from primary interviews and regulatory documentation were available through the study window; gaps in real-time enterprise procurement transaction data introduce uncertainty bands around cloud migration velocity assumptions. Forecasts reflect documented adoption assumptions and technology substitution elasticities. A model refresh is warranted upon material change in NIST post-quantum algorithm standardization timelines or EU AI Act enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Global Multifactor Authentication Market
Biometrics & Identity Management
Europe Decentralized Identity Market
Biometrics & Identity Management
Italy Mobile Biometrics Market
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Identity Verification Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
Global Biometric Technology Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
Voice Biometric Solutions Market
Biometrics & Identity Management
Asia Pacific Biometrics in Government Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Biometric Lockers Market
Biometrics & Identity Management
Flash Calling Authentication Market