
 Automated Barriers and Bollards Market | 2026-2036
Automated Barriers and Bollards Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Barriers and Bollards Market Analysis
Recurring revenue from predictive maintenance contracts and software-defined access protocols is shifting how automated barrier vendors capture lifetime value. FAAC Group leverages its installed base across European transport networks to sustain service income. Magnetic Autocontrol GmbH anchors its position through manufacturing scale in precision electromechanical drive systems. BFT Automation differentiates by controlling distribution channels in Southern European residential and commercial segments.
Automated barriers and bollards are electromechanical or hydraulic access control devices, typically fabricated from galvanized steel or reinforced composites, designed to restrict or permit vehicle passage through controlled entry points with impact resistance ratings measured in kJ stopping capacity. Their primary purpose is perimeter security and traffic flow management at critical infrastructure, commercial, and institutional sites. Crash barriers and automatic bollards lead product type demand where anti-ram protection commands premium pricing, while roadblock systems represent the fastest-growing segment as portable deployable units gain traction for temporary event security. Electric actuator technology dominates installed units for its precision and lower maintenance burden, though hydraulic systems retain margin pools in high-duty-cycle military and embassy applications.
The EU Machinery Directive and CE marking requirements shape product compliance costs and market access across European member states, while EN ISO 13849 and IWA 14-1 crash-test standards define the performance benchmarks that differentiate certified from uncertified suppliers. The US Department of State's Overseas Security Policy Board and ASTM F2656 anti-ram specifications govern federal and diplomatic procurement, effectively filtering non-compliant manufacturers from high-value government verticals. Stakeholders must monitor evolving counter-terrorism procurement frameworks and electrification compatibility standards as barrier systems integrate with smart city infrastructure and vehicle-to-everything communication protocols.
Market Dynamics
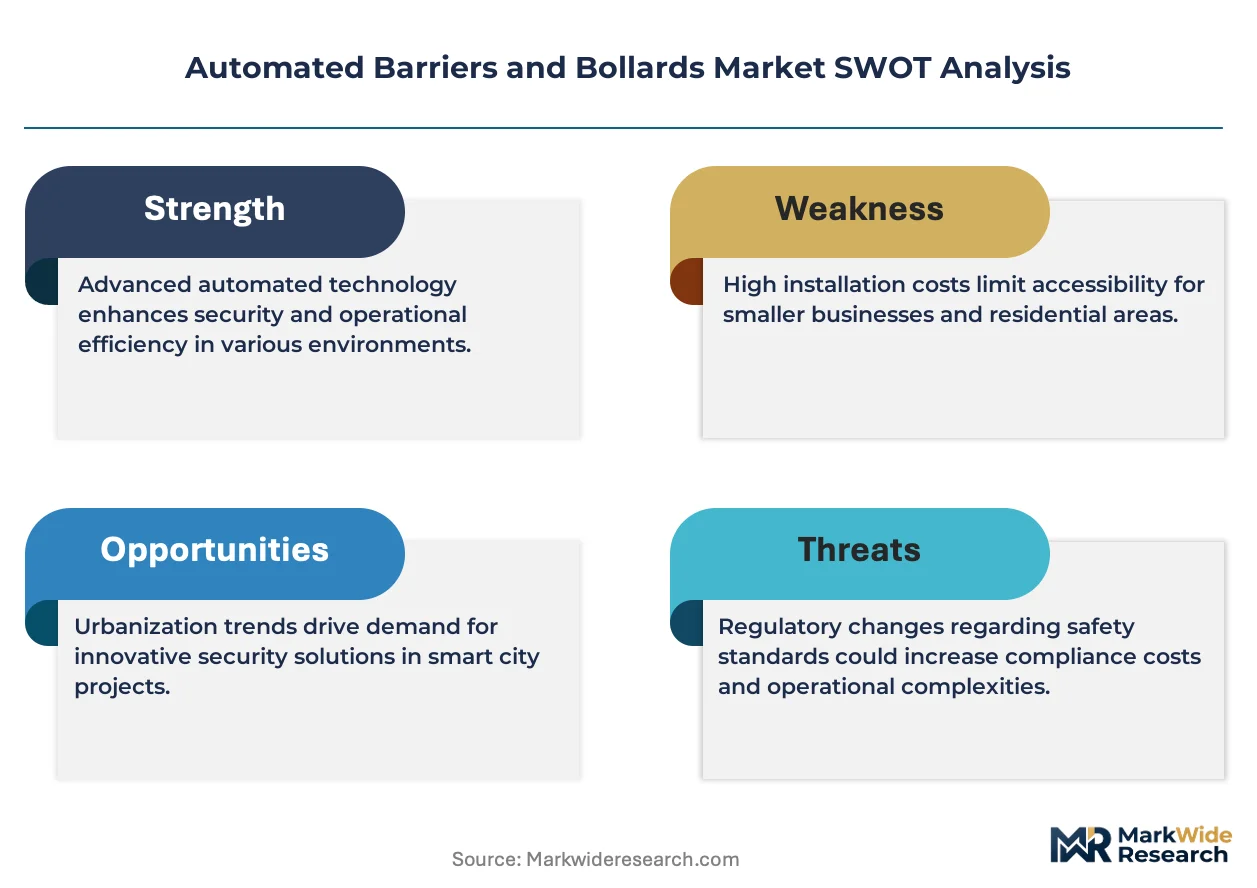
Crash-rated certification requirements under EN ISO 13849 and ASTM F2656 are compressing supplier margins while creating tiered entry barriers that favor electromechanical specialists over generalist fabricators.
Growth Catalysts
- Federal infrastructure mandates:Germany's federal infrastructure protection protocols mandate replacement cycles at transport hubs and government complexes, creating predictable demand pipelines for certified barrier systems.
- EN ISO 13849 compliance:Tightening safety standards for electromechanical access control equipment are filtering uncertified competitors from premium procurement channels across EU member states.
- Crash-rated bollard deployments:Commercial facilities are expanding perimeter hardening at entry points, with anti-ram protection commanding sustained pricing power in retail and corporate campus verticals.
Market Restraints
- Steel input volatility:Galvanized steel price fluctuations directly impact fabrication costs for barrier housings and bollard casings, compressing margins for fixed-price contract holders.
- Hydraulic component concentration:Precision electromechanical drive systems and high-duty-cycle hydraulic actuators concentrate among German and Italian component suppliers, creating geographic supply risk.
- CE marking friction:The EU Machinery Directive's conformity assessment procedures extend product launch timelines by 6-18 months for non-EU manufacturers lacking notified body relationships.
Strategic Opportunities
- Smart city integration:Vehicle-to-everything communication protocols are opening specification slots for barrier systems with API-accessible control interfaces in urban traffic management deployments.
- Portable roadblock units:Temporary event security applications are accelerating demand for rapidly deployable crash-rated systems at stadiums, exhibition centers, and festival infrastructure.
- Predictive maintenance contracts:Software-defined access protocols enable remote diagnostics and condition monitoring, shifting vendor revenue toward recurring service income streams.
Industry Challenges
- Functional safety engineering scarcity:Certified expertise in EN ISO 13849-compliant control system design concentrates among aging specialists in Central Europe, constraining R&D expansion.
- Legacy electromechanical integration:Retrofitting smart control modules into installed barrier bases requires custom mechanical adaptation, complicating upgrade paths at transport authority sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Barriers and Bollards Market |
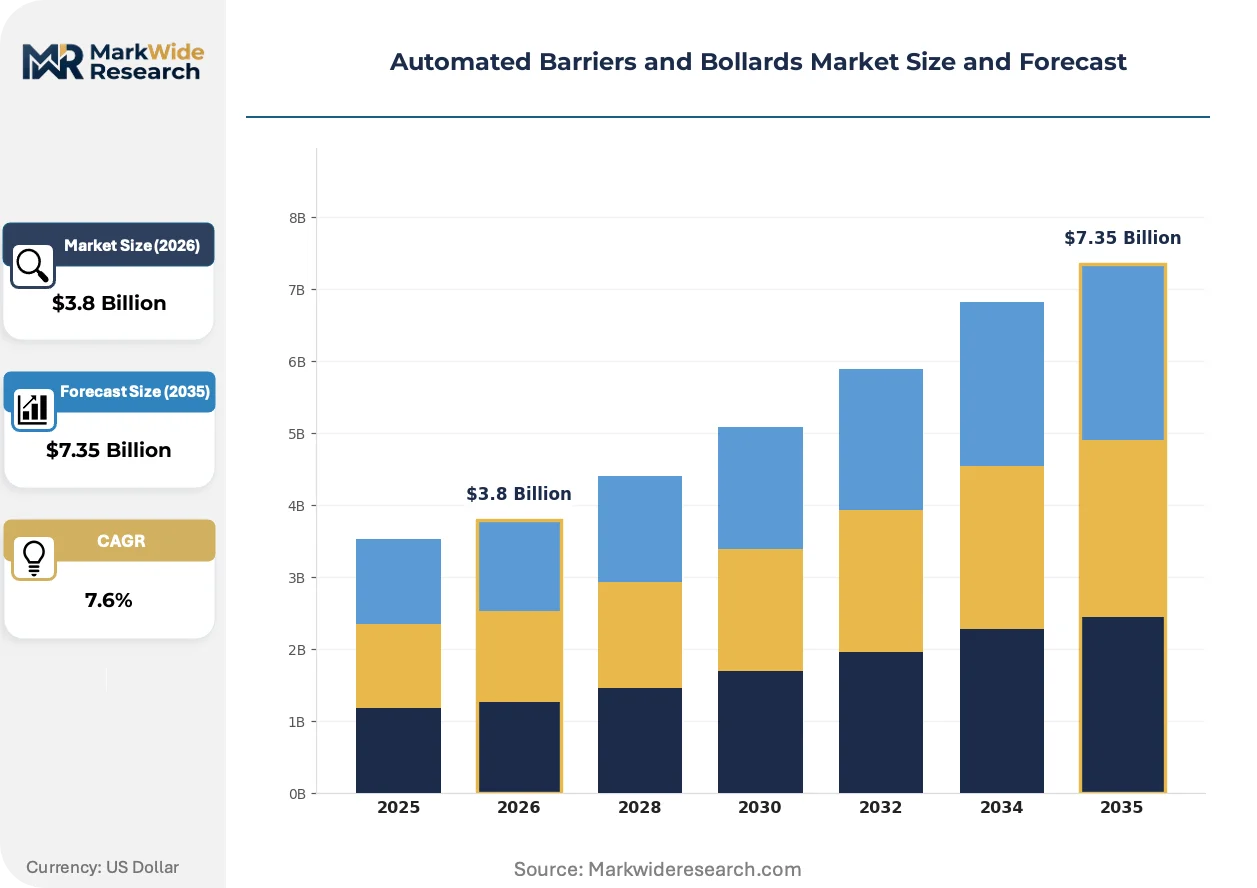
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crash Barriers, Automatic Bollards, Roadblock Systems, Security Barriers Technology: Hydraulic Systems, Pneumatic Systems, Electric Actuators, Manual Controls End User: Public Transport, Commercial Facilities, Government Buildings, Residential Areas Installation: Temporary, Permanent, Mobile, Integrated Systems |
| Companies Covered | BFT Automation, Magnetic Autocontrol GmbH, FAAC Group, Houston System Private Limited, Macs Automated Bollard System Ltd, CAME Group, Avon Barrier, Omnitec Group, Automatic Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Barriers and Bollards Market Emerging Trajectories
Barrier system architecture is fragmenting into interoperable subsystems as procurement shifts from monolithic installations toward componentized, upgradeable platforms.
Modular barrier control electronics are modularizing around standardized I/O interfaces and swappable drive controllers. Airport authorities and metro operators in France and the Netherlands are specifying these platforms for phased infrastructure refresh programs. This architecture is modularizing supplier relationships, allowing end-users to mix electromechanical hardware from one vendor with access control software from another, compressing single-source contract values.
ASTM F2656 anti-ram testing protocols are tightening penetration resistance thresholds for diplomatic and federal procurement categories. The US Department of State's Overseas Security Policy Board has elevated certification requirements for embassy perimeter systems, disqualifying suppliers lacking third-party crash-test documentation. High-security verticals are responding by consolidating procurement around pre-qualified vendor lists with established testing relationships.
Specification decisions are migrating from capital expenditure committees to facility operations teams with lifecycle cost mandates. Commercial property managers in German logistics hubs are unbundling hardware acquisition from 10-year maintenance contracts, forcing vendors to compete on total cost of ownership metrics rather than upfront equipment pricing. This pattern is most visible in Düsseldorf and Frankfurt corridor distribution centers where landlord-tenant service charge structures incentivize operational expenditure optimization.
Automated Barriers and Bollards Market Segmentation
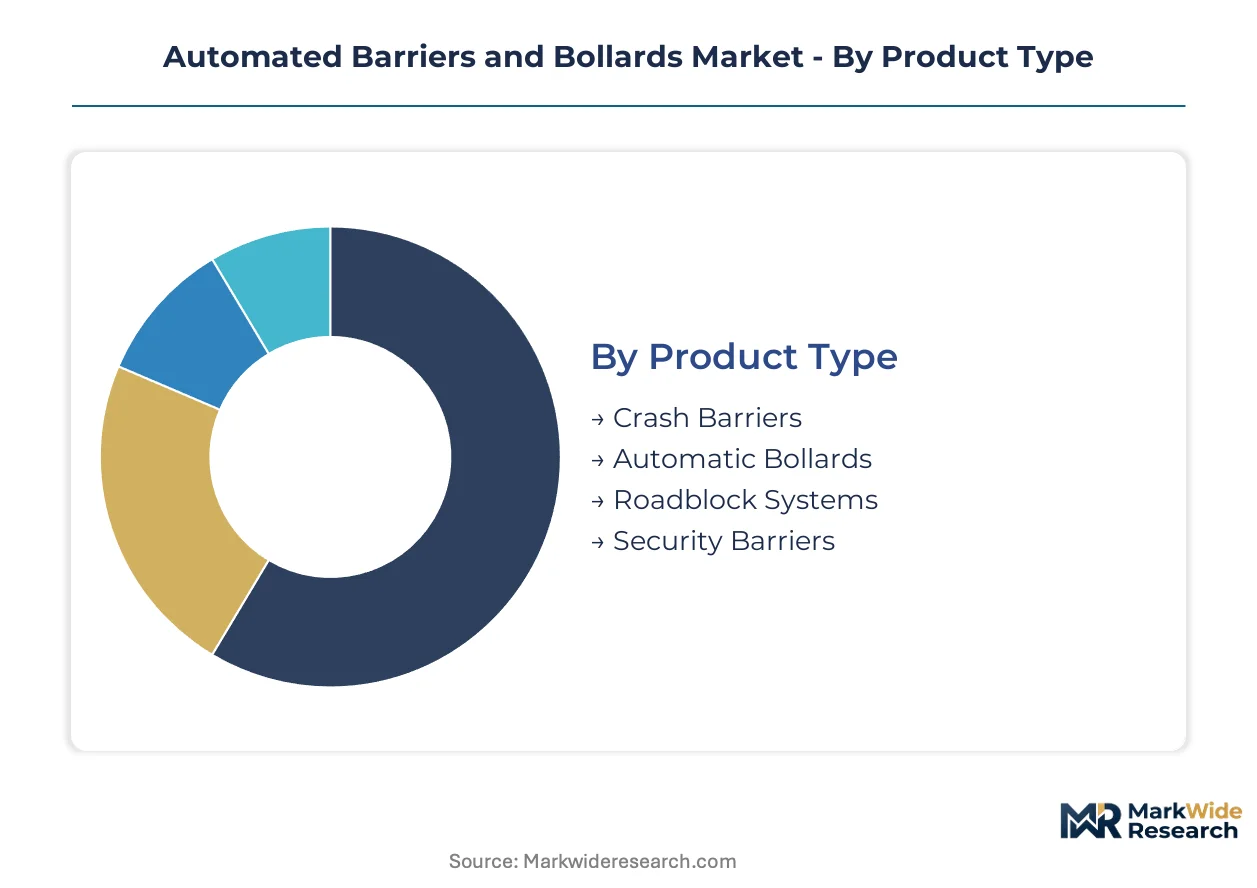
Automated barrier and bollard procurement decisions split across technical specifications, operational requirements, and lifecycle cost structures. Specification committees weigh crash-rating certification against integration complexity and maintenance burden. Each segmentation axis reveals distinct margin pools and competitive dynamics.
Product Type:
Crash-rated performance tiers separate premium-certified systems from commodity perimeter hardware.
- Crash Barriers:Fabricated from galvanized steel or reinforced composites with kJ stopping capacity ratings. Demand concentrates at German transport hubs and government complexes where federal infrastructure protection mandates enforce replacement cycles. EN ISO 13849 compliance filters uncertified competitors from these procurement channels.
- Automatic Bollards:Electromechanical or hydraulic vertical access control devices with anti-ram protection. Commercial facilities in retail and corporate campus verticals are expanding perimeter hardening at entry points, with certified systems commanding sustained pricing power.
- Roadblock Systems:Portable deployable units gaining traction for temporary event security at stadiums and exhibition centers.
- Security Barriers:Fixed or retractable horizontal barriers for traffic flow management at institutional sites.
Mature deployment sits with crash barriers at established transport infrastructure. Newer deployment is concentrated in roadblock systems for rapidly deployable temporary security applications.
Technology:
Actuation mechanisms determine maintenance schedules, precision tolerances, and duty-cycle suitability across application verticals.
- Electric Actuators:Precision electromechanical drive systems dominating installed units for lower maintenance burden and control accuracy. Airport authorities and metro operators in France and the Netherlands specify these for phased infrastructure refresh programs.
- Hydraulic Systems:High-pressure fluid power actuation retaining margin pools in military and embassy applications with extreme duty-cycle requirements. Component supply concentrates among German and Italian precision manufacturers.
- Pneumatic Systems:Compressed air actuation for specific environmental or safety-critical deployments.
- Manual Controls:Non-powered operation for low-frequency or backup access scenarios.
Electric actuator technology holds the dominant installed base. Hydraulic systems maintain entrenched positions where failure modes must default to secure states.
End User:
Procurement authority structures vary sharply across public, commercial, and residential verticals.
- Public Transport:Railway stations, airports, and metro systems with federal procurement frameworks. German federal mandates create predictable replacement demand at transport hubs.
- Commercial Facilities:Retail campuses, logistics distribution centers, and corporate headquarters. Property managers in Düsseldorf and Frankfurt corridor distribution centers unbundle hardware from decade-long maintenance contracts.
- Government Buildings:Embassy perimeters and federal complexes governed by ASTM F2656 and Overseas Security Policy Board requirements.
- Residential Areas:Gated communities and private estate access control with shorter procurement cycles.
Public transport verticals drive volume through mandated refresh programs. Commercial facilities are shifting fastest toward total cost of ownership procurement models.
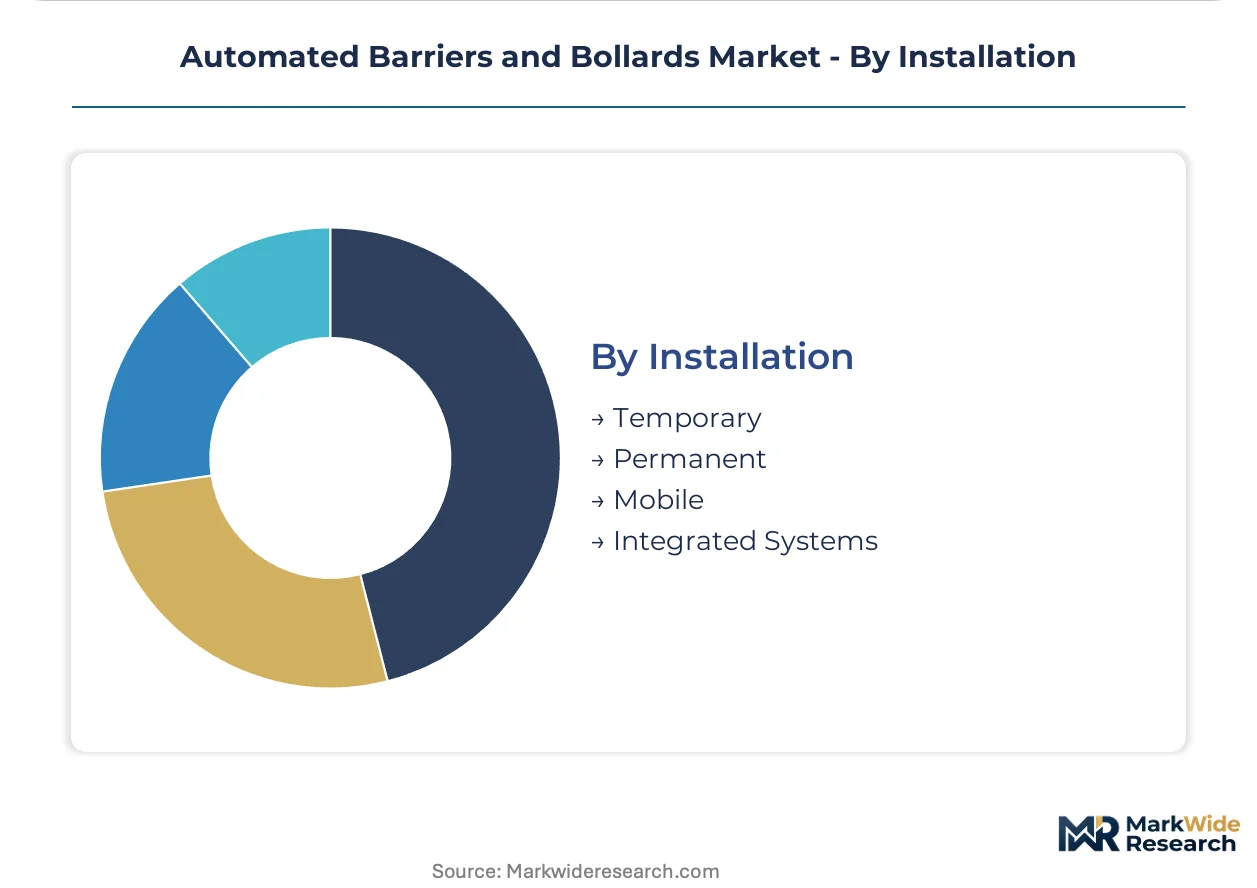
Installation:
Deployment duration and mobility requirements determine foundation engineering and control system architecture.
- Temporary:Rapidly deployable systems for event security and emergency response without permanent foundations.
- Permanent:Cast-in-place bollard and barrier installations with embedded control infrastructure.
- Mobile:Trailer-mounted or transportable units for repositionable perimeter control.
- Integrated Systems:Barrier hardware unified with smart city traffic management and vehicle-to-everything communication protocols.
Permanent installations represent the established revenue base. Integrated systems are expanding most quickly as urban traffic management platforms open API-accessible specification slots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures precision electromechanical drive systems and hydraulic components that supply barrier fabricators worldwide, while the United States, United Kingdom, France, and Italy concentrate installation demand at transport hubs and diplomatic facilities.
Germany
Federal infrastructure protection mandates enforce replacement cycles at transport hubs and government complexes, creating predictable procurement pipelines. The EU Machinery Directive and EN ISO 13849 compliance requirements filter uncertified competitors from premium channels. Manufacturing clusters in Baden-Württemberg and Bavaria produce precision drive systems and hydraulic actuators for domestic and export markets.
United States
ASTM F2656 anti-ram specifications and the Department of State's Overseas Security Policy Board govern embassy perimeter procurement, disqualifying suppliers lacking third-party crash-test documentation. Federal procurement frameworks concentrate specification authority at diplomatic and military installations. Metropolitan Washington D.C. and New York City corridor distribution centers drive commercial facility hardening demand.
United Kingdom
Transport for London and Network Rail mandate certified barrier systems at stations and depots, with specification committees weighing crash-rating against lifecycle cost metrics. The Health and Safety Executive enforces machinery safety compliance at public access points. London and Manchester logistics hubs unbundle hardware acquisition from decade-long maintenance contracts.
France
Airport authorities and metro operators in Paris and Lyon specify modular barrier platforms with standardized I/O interfaces for phased infrastructure refresh programs. ANSM and CNIL oversight shapes data handling in smart city integration deployments. The Île-de-France region concentrates demand for vehicle-to-everything compatible access control at urban traffic management sites.
Italy
Southern European residential and commercial segments drive demand for electromechanical access control with shorter procurement cycles than federal verticals. CE marking conformity assessment procedures extend launch timelines for non-EU manufacturers lacking notified body relationships. Northern industrial clusters in Lombardy and Emilia-Romagna supply precision hydraulic components for high-duty-cycle military applications.
Automated Barriers and Bollards Market Vendor Landscape
Top-tier vendors anchor electromechanical specialization and manufacturing scale, while mid-tier fabricators compete on regional distribution density and installation service networks. The supplier base stratifies across crash-rated certification holders, precision drive system manufacturers, and software-integrated platform providers. Strategic archetypes include electromechanical specialists leveraging installed bases for recurring service income, vertically integrated fabricators controlling component supply, and distribution-channel capturers unbundling hardware from long-term maintenance contracts. Competitive moves concentrate on predictive maintenance contract expansion and API-accessible control module development.
Among European electromechanical specialists, Magnetic Autocontrol GmbH and FAAC Group occupy positions anchored in precision drive system manufacturing and transport network installed bases. BFT Automation represents the distribution-channel archetype with density in Southern European residential and commercial segments. These three exemplify how vendor strategy diverges across technical specialization, service revenue capture, and geographic channel control rather than converging on uniform product-centric competition.
| Leading Market Players |
|---|
| BFT Automation |
| Magnetic Autocontrol GmbH |
| FAAC Group |
| Houston System Private Limited |
| Macs Automated Bollard System Ltd |
| CAME Group |
| Avon Barrier |
| Omnitec Group |
| Automatic Systems |
| Others |
Supply Flow & Price Mechanics
Galvanized steel input costs cascade through three distinct pricing tiers for barrier fabricators, with German precision electromechanical drive manufacturers commanding premium positioning while Asian metal processors feed commodity-grade housing suppliers at compressed margins.
Pricing Analysis
Margin tightening in mid-tier electric actuator systems reflects steel price volatility and CE marking compliance burdens that concentrate among non-specialist fabricators. Three-tier pricing structure across crash-certified, standard-duty, and economy-grade installations separates procurement channels, with EN ISO 13849 certification tier commanding sustained premiums from federal buyers. Cost-down pressure on hydraulic roadblock units accelerates because military procurement consolidation favors pre-qualified vendor lists. Commercial facility managers in logistics verticals demonstrate highest price sensitivity through unbundled hardware-maintenance tenders, while embassy security committees remain least sensitive given ASTM F2656 mandate requirements.
Supply Chain Analysis
Regional distribution centers in Germany, Italy, and the Netherlands anchor hub-and-spoke patterns for precision electromechanical components serving European barrier fabricators. Manufacturing draws from Baden-Württemberg drive system clusters, Lombardy hydraulic actuator specialists, and Chinese galvanized steel processors. Single-source vulnerability concentrates in high-duty-cycle hydraulic valves from Italian precision suppliers. Distribution runs through certified installer networks with notified body relationships, creating friction for non-EU manufacturers lacking established conformity assessment pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into precision drive manufacturing and predictive maintenance software represents the decisive vertical-integration race, with component control and recurring service revenue determining long-term margin capture.
For Market Incumbents: To counter modular platform unbundling by airport authorities and metro operators, anchor positions through captive supply of EN ISO 13849-compliant control electronics and exclusive distribution partnerships with notified bodies for CE marking acceleration. Expand predictive maintenance contract penetration to shift revenue mix toward recurring service income streams that resist hardware commoditization. For New Entrants and Emerging Players: EU Machinery Directive enforcement gaps in Southern European residential segments open a window for standardized electric barrier kits with simplified conformity pathways. Target Italian and Spanish commercial installers through direct channel relationships bypassing established distributor markups. Pursue portable roadblock system specifications for temporary event security where certification requirements remain less stringent than permanent infrastructure mandates. For Investors and Strategic Acquirers: Consolidation of embassy procurement around ASTM F2656 pre-qualified vendor lists is the leading indicator that certification asset value is concentrating among established testing relationships. Position for five-to-ten year viability through acquisition targets possessing dual EN ISO 13849 and IWA 14-1 crash-test documentation with existing notified body partnerships. Monitor German federal infrastructure replacement cycle announcements as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Software-defined access protocols enable remote diagnostics at Transport for London and Frankfurt logistics hubs. |
| Crash-Rating Certification Investment | ASTM F2656 and IWA 14-1 testing relationships unlock US embassy and NATO procurement channels. |
| Modular Control Electronics Standardization | API-accessible I/O interfaces meet Paris and Lyon metro authority phased refresh specifications. |
| Backward Integration into Drive Manufacturing | In-house precision electromechanical production reduces dependency on Baden-Württemberg component suppliers. |
| Smart City Integration Partnership | Vehicle-to-everything protocol compatibility secures Île-de-France urban traffic management deployments. |
Methodological Framework
Document review covered EU Machinery Directive implementation guidance, EN ISO 13849 safety standard technical specifications, and ASTM F2656 crash-test protocols, complemented by interviews with barrier system procurement managers at German transport authorities, facility operations directors at Düsseldorf logistics hubs, and technical directors at notified bodies for CE marking assessment. Secondary validation drew from federal infrastructure protection mandate filings, customs trade data for galvanized steel and electromechanical components, and airport authority tender documentation. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows.
Segmented outputs across product type, actuation technology, end-user vertical, and installation duration informed value projections over the projection horizon. Electric actuator versus hydraulic system splits, crash-rated certification tiers, and maintenance contract attachment rates served as industry-specific forecast inputs. CAGRs derived from replacement cycle analysis at mandated German transport hubs and commercial facility refresh patterns in logistics corridors.
Caveats apply where steel input volatility, regulatory enforcement intensity shifts, or smart city procurement timeline delays could materially shift the outlook. Forecasts rest on documented assumptions regarding federal mandate continuity and certification standard stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
Acousto-Magnetic (AM) Security Systems Market
Access Control Systems
Electronic Access Control Systems Market
Access Control Systems
Pedestrian Entrance Control System Market
Access Control Systems
Global Industrial Safety Gates Market
Access Control Systems
France Access Control Market
Access Control Systems
Access Control As a Service Market
Access Control Systems
Digital Security Control Market
Access Control Systems
China Access Control Market
Access Control Systems
North America Pin-Based Access Control Market
Access Control Systems
North America Proximity Access Control Market
Access Control Systems
North America Safety Systems Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
Access Control Readers Market
Access Control Systems
Global Smart Lock Market
Access Control Systems
North America Home Security System Market
Access Control Systems
Industrial Barrier Systems Market