
 Middle East and Africa Proximity Access Control Market | 2026-2036
Middle East and Africa Proximity Access Control Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Proximity Access Control Market Insights
Biometric-grade authentication is bifurcating the Middle East and Africa proximity access control landscape into premium and standard tiers. Assa Abloy leverages its hardware-software integration depth to anchor high-security government contracts across the Gulf. Honeywell International Inc competes through building automation convergence, while Dahua Technology Co Ltd extends its video surveillance channel dominance into bundled access solutions.
Proximity access control encompasses credential-based physical entry systems that authenticate users through radio frequency identification, near-field communication, or Bluetooth Low Energy transmission ranges typically under 10 centimeters, with readers decoding encrypted tokens to release electromechanical locks. The primary purpose spans workforce tracking, asset protection, and regulatory audit trails across commercial and institutional facilities. Biometric readers command premium positioning due to liveness detection requirements in financial and defense applications, while mobile access segments gain traction as enterprises depreciate legacy card infrastructure. Cloud-based installation models attract mid-market buyers seeking subscription economics, though on-premises architectures persist where national data sovereignty rules restrict cross-border credential storage.
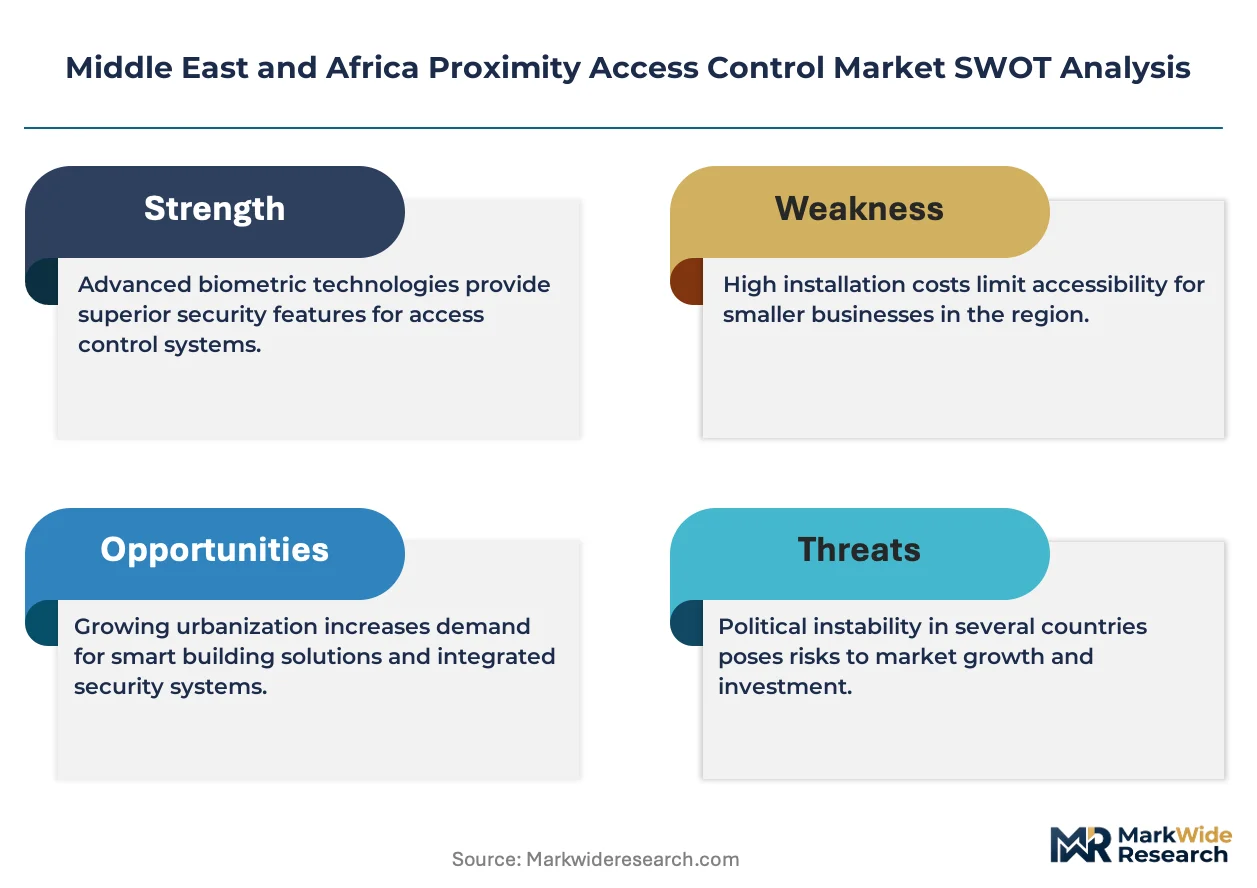
Saudi Arabia's SAMR and the UAE's NESA impose cybersecurity certification on critical infrastructure access systems, compelling vendors to embed tamper-evident hardware modules. South Africa's POPIA and Nigeria's NDPR extend data protection liability to biometric template storage, reshaping product architecture decisions. Stakeholders must weigh sovereign hosting mandates against cloud scalability when configuring regional deployment strategies.
Market Dynamics
Cybersecurity certification mandates from Saudi Arabia's SAMR and the UAE's NESA are forcing hardware architecture redesigns across the Middle East and Africa proximity access control supply base. Vendors must now embed tamper-evident modules and sovereign data hosting capabilities to retain critical infrastructure eligibility.
Growth Catalysts
- Smart city infrastructure mandates:The UAE's Dubai 2040 Urban Master Plan and Saudi Vision 2030 are embedding credential readers into municipal buildings, transit hubs, and healthcare facilities as standard procurement specifications.
- Biometric data protection rules:South Africa's POPIA and Nigeria's NDPR are compelling financial institutions to upgrade template storage architectures, driving replacement cycles for legacy proximity systems.
- Mobile credential adoption:Near-field communication and Bluetooth Low Energy readers are gaining preference among Gulf Cooperation Council commercial landlords seeking to eliminate physical card logistics.
Market Restraints
- Semiconductor supply concentration:Reader controller chip fabrication concentrates in East Asian foundries, exposing Middle East and Africa integrators to extended lead times and allocation volatility.
- High sovereign hosting costs:National data residency rules in Saudi Arabia and the UAE require localized server infrastructure, inflating total cost of ownership versus cloud-native alternatives.
- Copper and rare earth price volatility:Electromechanical lock components and reader antenna materials face input cost instability that compresses hardware margins for regional distributors.
Strategic Opportunities
- Nigeria's banking infrastructure expansion:Tier-2 and Tier-3 financial institutions outside Lagos and Abuja remain underpenetrated by biometric-grade access systems, offering first-mover positioning.
- Convergence of video analytics and access control:Facial recognition liveness detection bundled with proximity readers creates premium pricing power for security integrators serving defense and diplomatic facilities.
- Saudi SAMR cybersecurity certification:Compliance mandates for critical infrastructure create a regulatory tailwind for vendors with pre-certified hardware-software stacks.
Industry Challenges
- Cyber-physical systems engineering scarcity:The regional talent pool lacks sufficient depth in embedded security firmware development and hardware tamper-resistance design.
- Legacy Wiegand protocol integration:Decades-old wiring infrastructure in established Gulf commercial buildings complicates migration to encrypted OSDP and mobile credential architectures.
- Multi-jurisdiction certification timelines:Vendors must sequence approvals across SAMR, NESA, and POPIA frameworks, extending product launch cycles by twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Proximity Access Control Market |
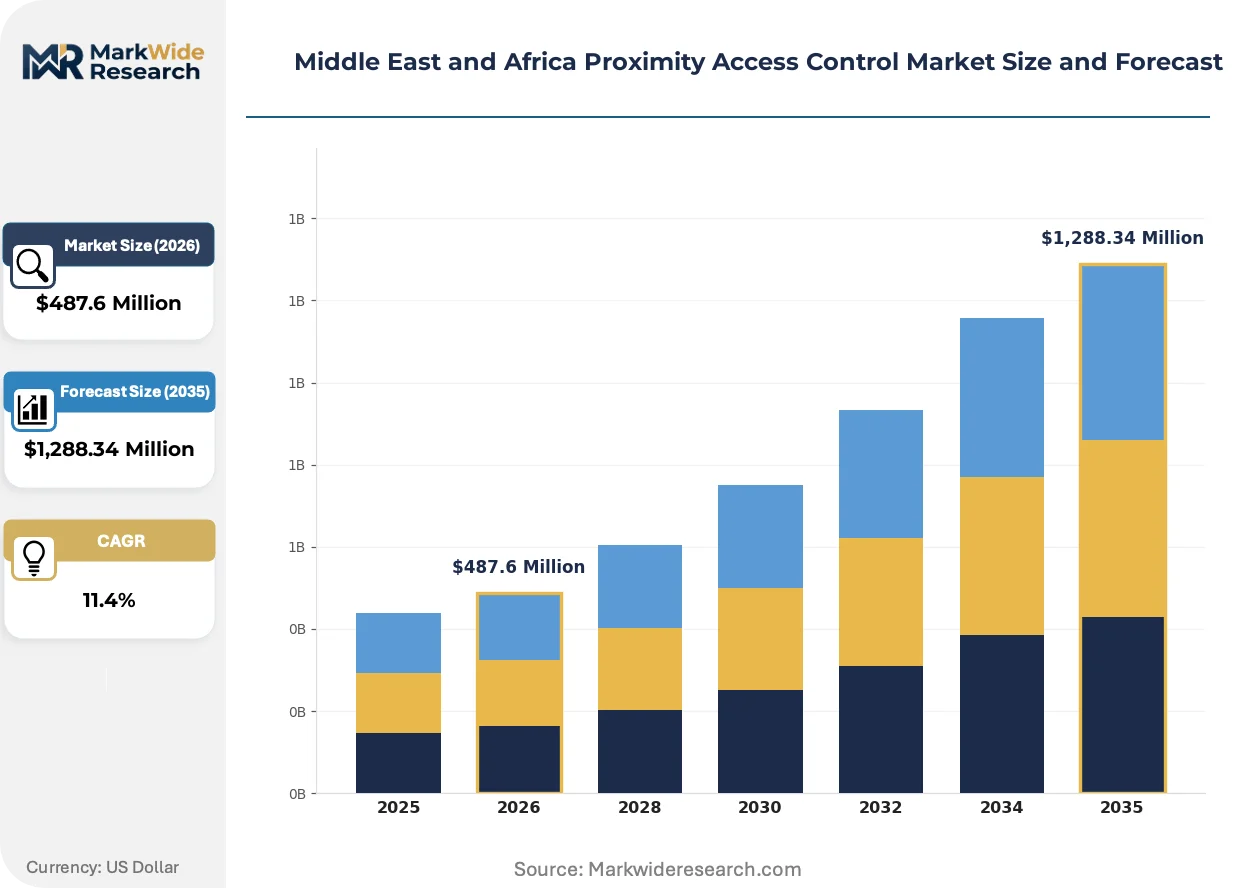
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Card Readers, Biometric Readers, Key Fobs, Mobile Access End User: Commercial Buildings, Government Facilities, Educational Institutions, Manufacturing Plants Technology: RFID, Bluetooth, NFC, Infrared Installation: On-Premises, Cloud-Based, Integrated Systems, Standalone Solutions |
| Companies Covered | Axis Communications AB, Dormakaba Group, Nedap NV, Assa Abloy, Anviz Global Inc, HID Global, Johnson Controls, Honeywell International Inc, Dahua Technology Co Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Proximity Access Control Market Trends and Innovations
Authentication modalities are diversifying beyond card-based credentials as mobile wallets and biometric liveness detection mature. The competitive frontier now centers on seamless multi-factor orchestration rather than reader hardware specifications alone.
Mobile credential platforms leveraging smartphone secure elements are fragmenting the traditional smart card reader market. Large commercial landlords in Dubai and Riyadh are piloting Bluetooth Low Energy and ultra-wideband readers for frictionless entry experiences. This technology is fragmenting procurement decisions away from security departments toward IT and facilities management budgets.
Saudi SAMR and UAE NESA cybersecurity certification requirements are mandating firmware signing, secure boot processes, and hardware security module integration for critical infrastructure deployments. Industrial consequence includes disqualification of uncertified vendors from government and energy sector tenders. Financial institutions in the Gulf Cooperation Council states are responding fastest, embedding compliance into RFP scoring criteria ahead of retail and education verticals.
Subscription-based access control as a service is displacing capital-intensive on-premises installations among mid-market buyers. Channel partners in South Africa and Kenya are bundling hardware, software, and maintenance into monthly per-door pricing. This shift is most visible in Nigeria's rapidly formalizing commercial real estate sector, where property developers prioritize operational expenditure predictability over upfront asset ownership.
Middle East and Africa Proximity Access Control Market Segmentation
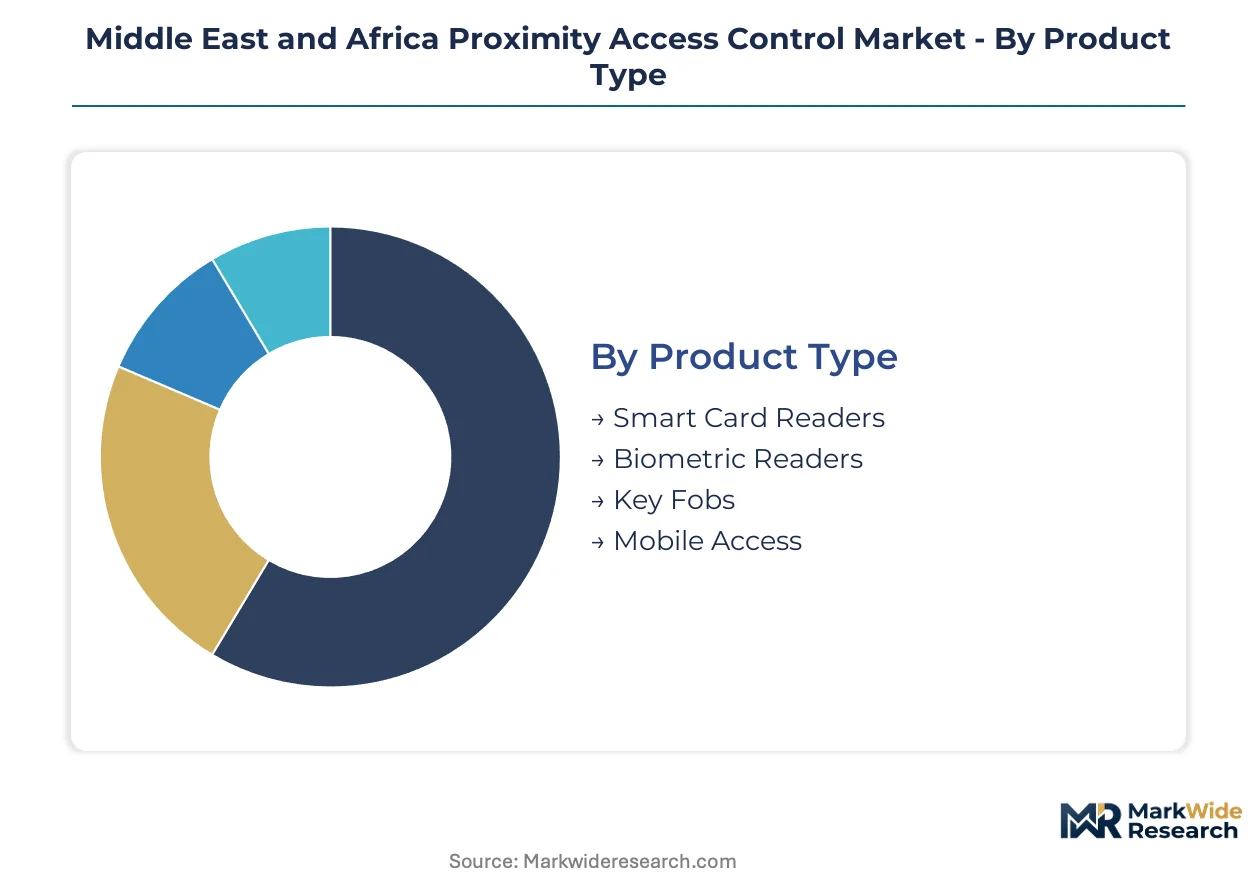
Segmentation in the Middle East and Africa proximity access control market reveals how regulatory mandates and infrastructure maturity reshape procurement patterns across credential technologies and deployment architectures. Buyers in Saudi Arabia and the UAE face divergent compliance pathways that segment vendor eligibility by certification status rather than hardware specifications alone.
Product Type:
Saudi SAMR and UAE NESA cybersecurity certifications bifurcate hardware procurement into certified and uncertified tiers, with biometric and mobile credential systems facing stricter firmware signing requirements than legacy card readers.
- Smart Card Readers:Contactless RFID readers operating at 13.56 MHz dominate commercial building retrofits across Dubai and Riyadh, where legacy Wiegand wiring infrastructure constrains migration to encrypted protocols. Demand concentrates in mid-tier office developments seeking POPIA-compliant audit trails without biometric template storage liability.
- Biometric Readers:Fingerprint and facial recognition terminals with liveness detection embed hardware security modules to satisfy SAMR mandates for critical infrastructure. Saudi government facilities and UAE diplomatic compounds drive premium positioning, with template encryption requirements extending replacement cycles.
- Key Fobs:Passive 125 kHz proximity tokens persist in price-sensitive Nigerian banking branches and Kenyan educational campuses where mobile penetration remains uneven.
- Mobile Access:Bluetooth Low Energy and NFC smartphone credentials gain traction among Gulf Cooperation Council commercial landlords eliminating card logistics; South African financial institutions pilot secure element-based authentication ahead of NDPR enforcement.
Smart card readers handle the majority of throughput across the region's installed base; mobile access is expanding most quickly in the Gulf's premium commercial real estate segment.
End User:
Vertical specialization determines whether procurement prioritizes cybersecurity certification, biometric data protection, or operational expenditure predictability.
- Commercial Buildings:Dubai and Riyadh office towers drive mobile credential adoption as facilities managers merge access budgets with IT infrastructure spending. Subscription pricing models displace capital-intensive installations among property developers seeking operational expenditure visibility.
- Government Facilities:Saudi ministries and UAE federal buildings mandate SAMR and NESA certified hardware-software stacks, disqualifying uncertified vendors from tender participation. Facial recognition with liveness detection dominates high-security zones.
- Educational Institutions:South African universities and Nigerian secondary schools prioritize cost-efficient card-based systems, with POPIA compliance limited to template-free proximity deployments.
- Manufacturing Plants:Industrial facilities in Saudi Arabia's Jubail and UAE's Jebel Ali free zones require ruggedized readers with tamper-evident modules for outdoor and hazardous environment deployment.
Commercial buildings generate the highest absolute demand volume; government facilities command the steepest pricing premium due to certification requirements.
Technology:
Transmission protocol selection reflects trade-offs between read range, power consumption, and smartphone ecosystem integration.
- RFID:13.56 MHz high-frequency and 125 kHz low-frequency radio frequency identification anchor the regional installed base, with high-frequency systems displacing low-frequency in Nigerian banking infrastructure upgrades.
- Bluetooth:Low Energy 4.2 and 5.0 protocols enable smartphone-based frictionless entry across Dubai's smart city developments, with ultra-wideband pilots emerging in Riyadh premium commercial properties.
- NFC:Near-field communication leverages smartphone secure elements for cryptographic credential storage, satisfying UAE financial regulator preferences for hardware-backed authentication.
- Infrared:Line-of-sight transmission persists in legacy Saudi government installations and budget-constrained Kenyan educational facilities where electromagnetic interference concerns are minimal.
RFID maintains dominant share across the Middle East and Africa proximity access control market; Bluetooth is gaining share fastest in Gulf Cooperation Council commercial deployments.
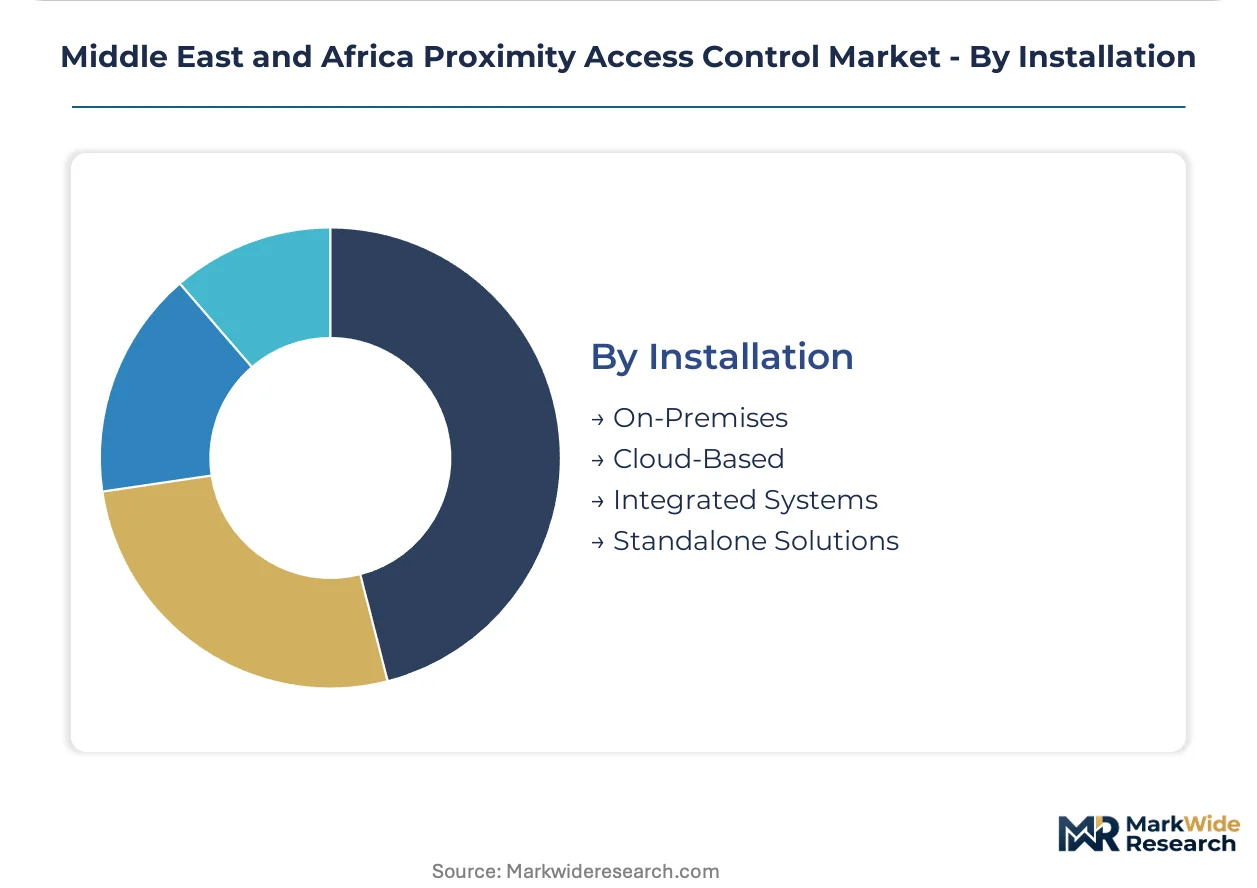
Installation:
Architecture decisions hinge on national data sovereignty rules that restrict cross-border credential storage and template transmission.
- On-Premises:Local server deployments satisfy Saudi and UAE data residency mandates for biometric template storage, inflating total cost of ownership versus cloud alternatives but preserving critical infrastructure eligibility.
- Cloud-Based:Access control as a service attracts South African and Nigerian mid-market buyers through monthly per-door pricing, though sovereign hosting requirements limit addressable market in the Gulf.
- Integrated Systems:Convergence with video surveillance and building automation platforms dominates UAE smart city tenders, with Honeywell and Dahua bundling access readers into unified security architectures.
- Standalone Solutions:Single-door controllers with embedded memory serve Nigerian Tier-3 bank branches and remote South African mining facilities where network connectivity remains unreliable.
On-premises installations retain majority share in the Gulf states due to regulatory constraints; cloud-based deployment is climbing the fastest in sub-Saharan African markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence on reader controller chips from East Asian foundries shapes procurement timelines across Middle East and Africa markets, while localized assembly capacity expands in the UAE and South Africa to mitigate lead time volatility.
United Arab Emirates
Dubai's smart city developments and Abu Dhabi's government district renewals drive NFC and Bluetooth Low Energy reader deployment. NESA cybersecurity certification mandates restrict tender participation to vendors with sovereign data hosting capabilities. Jebel Ali free zone industrial facilities require ruggedized readers with tamper-evident modules for hazardous environment deployment.
Saudi Arabia
Saudi Vision 2030 municipal building programs and NEOM urban development embed credential readers as standard procurement specifications. SAMR cybersecurity mandates compel firmware signing and hardware security module integration for critical infrastructure eligibility. Riyadh's premium commercial properties pilot ultra-wideband readers for frictionless entry experiences.
South Africa
POPIA data protection rules reshape biometric template storage architectures across Johannesburg financial institutions and Cape Town educational campuses. Mid-market buyers shift toward subscription-based access control as a service models. Mining facilities in remote provinces deploy standalone single-door controllers where network connectivity remains unreliable.
Nigeria
Tier-2 and Tier-3 banking infrastructure outside Lagos and Abuja remains underpenetrated by biometric-grade access systems. The NDPR extends data protection liability to biometric storage, driving replacement cycles for legacy proximity systems. Commercial real estate developers in Lagos prioritize operational expenditure predictability through monthly per-door pricing.
Middle East and Africa Proximity Access Control Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and hardware-software integration capabilities. The vendor base segments into three tiers: multinational conglomerates with building automation portfolios, security-focused specialists with regional certification expertise, and emerging technology providers leveraging video surveillance channels. Strategic moves center on SAMR and NESA pre-certification investments to secure government tender eligibility, alongside subscription model transitions to capture mid-market buyers.
Within the certification-driven tier, Assa Abloy and Honeywell International Inc anchor high-security positioning through hardware-software stack depth, while Dahua Technology Co Ltd exemplifies video surveillance channel extension into bundled access solutions. These three represent divergent archetypes: the Nordic industrial conglomerate, the American building automation integrator, and the Chinese technology platform.
| Leading Market Players |
|---|
| Axis Communications AB |
| Dormakaba Group |
| Nedap NV |
| Assa Abloy |
| Anviz Global Inc |
| HID Global |
| Johnson Controls |
| Honeywell International Inc |
| Dahua Technology Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Mobile credential platforms replacing physical smart cards are redrawing procurement geography toward smartphone secure element suppliers and compressing hardware margins for traditional reader manufacturers across Gulf Cooperation Council states.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Middle East and Africa proximity access control market. SAMR and NESA certification tiers separate biometric-grade systems with hardware security modules from uncertified card readers, while volume scale and after-sales service bundling differentiate mid-market positioning. Cost compression in standard-tier readers is intensifying because semiconductor allocation volatility forces distributors to absorb input price swings. Tier-2 Nigerian banks and Kenyan educational campuses exhibit highest price sensitivity, whereas UAE government facilities demonstrate lowest sensitivity due to cybersecurity compliance mandates.
Supply Chain Analysis
Taiwan and South Korea anchor controller chip fabrication for proximity readers, while China dominates electromechanical lock component manufacturing and antenna material processing. Regional assembly draws from copper wiring, rare earth magnets, and encrypted firmware modules. Single-source vulnerability in East Asian foundry capacity exposes Middle East and Africa integrators to allocation volatility and extended replenishment cycles. Distribution runs through authorized security system integrators in Dubai and Riyadh, with direct OEM relationships penetrating large government tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proximity access control incumbents face substitution pressure from smartphone-native authentication platforms that bypass dedicated reader hardware entirely, requiring defensive repositioning around compliance-certified physical infrastructure.
For Market Incumbents: Consolidate certification depth around SAMR and NESA pre-approval status to disqualify uncertified competitors from Saudi and UAE government tenders. Deepen backward integration into tamper-evident hardware module production to defend margins against semiconductor cost volatility. Channel control through exclusive integrator partnerships in Lagos and Nairobi protects against emerging mobile-first entrants. For New Entrants and Emerging Players: Cloud-managed access control as a service represents an under-served layer where incumbents lack subscription pricing infrastructure. Target South African mid-market commercial real estate developers seeking operational expenditure predictability over capital-intensive on-premises installations. A direct-to-facilities-manager go-to-market angle bypasses established security integrator gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed security technology platforms lacking Gulf cybersecurity certification. Five-to-ten year viability hinges on regulatory compliance moats rather than hardware differentiation alone. Watch for SAMR certification backlog clearance as an inflection signal for vendor market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| SAMR Certification Investment | Pre-approved hardware-software stacks unlock Saudi critical infrastructure tenders. |
| Mobile Credential Platform Launch | Bluetooth Low Energy readers capture Gulf commercial landlord IT budget migration. |
| Backward Integration into HSM Production | In-house hardware security module manufacturing defends margins against semiconductor volatility. |
| Subscription Model Transition | Per-door monthly pricing penetrates Nigerian and South African mid-market buyers. |
| Video Surveillance Convergence | Facial recognition bundling with proximity readers commands premium at UAE diplomatic facilities. |
Research Methodology
A standing panel of security systems integrators, facilities management directors, government procurement officers, and biometric technology specialists provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with channel partners in Dubai, Riyadh, Lagos, and Johannesburg alongside secondary validation through SAMR certification databases, NESA compliance registries, and POPIA enforcement guidance documents. Customs import records for reader controller chips and electromechanical lock components supplied trade flow triangulation. Bottom-up door-level installation estimates and top-down security equipment spending aggregates were cross-referenced for consistency.
Output validation against external benchmarks confirmed analytical coherence across the projection horizon. Segmentation modeling incorporated credential technology type, deployment architecture, end-use vertical, and national regulatory framework dimensions. CAGRs were derived from fitted growth curves applied to installation base expansion and replacement cycle timing, with biometric template storage liability costs and sovereign hosting infrastructure investments as industry-specific forecast inputs.
Forecasts assume regulatory continuity in Saudi SAMR, UAE NESA, and South African POPIA enforcement regimes; material policy shifts would require re-modeling. Specific risks include cybersecurity certification timeline extensions, rare earth export restrictions, and mobile credential platform security breaches that could accelerate or decelerate hardware replacement cycles. Recalibration cycles align with material shifts in Gulf smart city procurement schedules and sub-Saharan banking infrastructure investment waves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Access Control Systems
RFID Locks Market
Access Control Systems
Latin America Pin-Based Access Control Market
Access Control Systems
Europe Proximity Access Control Market
Access Control Systems
GPS Smart Locks Market
Access Control Systems
Smart Entry System Market
Access Control Systems
US Restricted Access Barrier System Market
Access Control Systems
North America Proximity Access Control Market
Access Control Systems
France Access Control Market
Access Control Systems
Port Security Systems Market
Access Control Systems
Facial Recognition Access Control Solution Market
Access Control Systems
Asia-Pacific Access Control Hardware Market
Access Control Systems
Pedestrian Access Control System Market
Access Control Systems
Germany Access Control Market
Access Control Systems
Europe Pin-Based Access Control Market
Access Control Systems
Locks Market
Access Control Systems
Latin America Card-Based Access Control Market