
 Europe Hazardous Waste Handling Automation Market | 2026-2036
Europe Hazardous Waste Handling Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hazardous Waste Handling Automation Market Foresight
Aftermarket service revenue is tilting toward predictive maintenance contracts for automated crane and robotic sorting installations. Konecranes PLC leverages its Nordic installed base to capture recurring service streams across Scandinavian chemical ports. Terex MHPS GmbH anchors German heavy-industry demand with specialized gantry systems for drum handling. Hosokawa Micron Powder Systems differentiates through integrated size-reduction and containment automation for pharmaceutical waste streams.
Europe hazardous waste handling automation encompasses electromechanical systems, sensor networks, and software-controlled robotics engineered to manipulate, transport, and process toxic, flammable, or reactive materials without direct human contact, typically operating within temperature-controlled enclosures rated for corrosive environments and pressure differentials sufficient to prevent fugitive emissions. Robotic Systems and AI Integration command the dominant share of new capital deployment as waste management companies pursue autonomous sorting lines capable of identifying chemical compatibility hazards in real time. Sensor Technology occupies a mature but essential position, with fiber-optic and infrared detection modules forming the baseline safety layer for container handling operations across industrial facilities.
The EU Green Deal and REACH regulation mandate cradle-to-grave tracking of hazardous substances, forcing waste management companies to upgrade manual handling infrastructure or face permit restrictions. ECHA's classification and labeling requirements directly shape sensor calibration standards and robotic gripping specifications for cross-border waste shipments. Stakeholders must weigh the capital intensity of full-line automation against modular retrofit paths as the EU AI Act begins imposing conformity assessment obligations on autonomous decision systems in industrial environments.
Market Dynamics
EU Green Deal enforcement is forcing waste management operators to replace manual drum handling with sensor-integrated robotic systems, compressing capital deployment timelines across chemical manufacturing clusters.
Growth Catalysts
- REACH substance tracking mandates:Cradle-to-grave traceability requirements compel waste handlers to deploy automated container identification systems with embedded RFID and optical character recognition.
- Chemical manufacturing expansion:German and French petrochemical complexes are retrofitting legacy disposal lines with AI-driven sorting robotics to preempt regulatory penalties.
- EU AI Act conformity pathways:Early compliance with autonomous system certification standards creates first-mover advantage for waste operators securing cross-border shipment permits.
Market Restraints
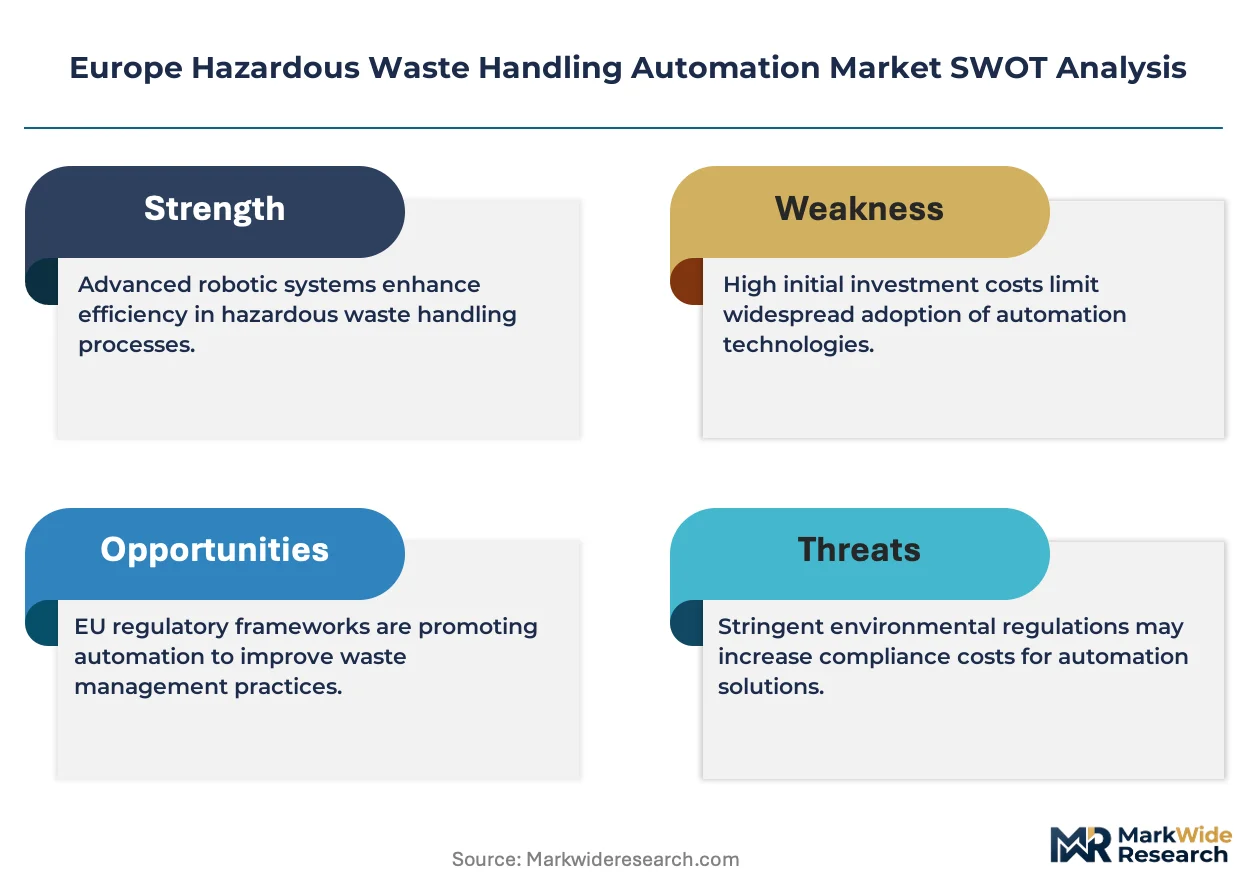
- Specialized actuator supply concentration:Corrosion-resistant servo motors for explosive atmospheres depend on a limited supplier base concentrated in Nordic industrial zones.
- Capital intensity of full-line replacement:Integrated robotic gantry systems for drum handling require multi-year depreciation cycles that strain mid-tier waste operator balance sheets.
- Technical limitation in mixed-waste identification:Current near-infrared spectroscopy modules struggle to distinguish composite chemical containers with layered polymer structures.
Strategic Opportunities
- Polish industrial corridor penetration:Emerging chemical manufacturing clusters near Wrocław and Łódź lack automated hazardous waste infrastructure, creating greenfield deployment potential.
- Pharmaceutical cytotoxic waste stream specialization:Isolator-integrated robotic handling for antineoplastic drug disposal addresses unmet demand from oncology manufacturing facilities.
- CSRD sustainability reporting convergence:Mandatory emissions disclosure is accelerating procurement of sensor networks that generate auditable waste-handling data for ESG compliance.
Industry Challenges
- ATEX certification bottlenecks:Notified body backlogs for explosive atmosphere equipment approvals extend deployment timelines by 8-14 months.
- Interoperability with legacy SCADA architectures:1990s-era waste facility control systems require costly middleware development to interface with modern robotic controllers.
- Specialized technician scarcity:Maintenance of fiber-optic safety interlocks and collaborative robot arms demands hybrid electromechanical-optical skills rarely found in traditional waste operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hazardous Waste Handling Automation Market |
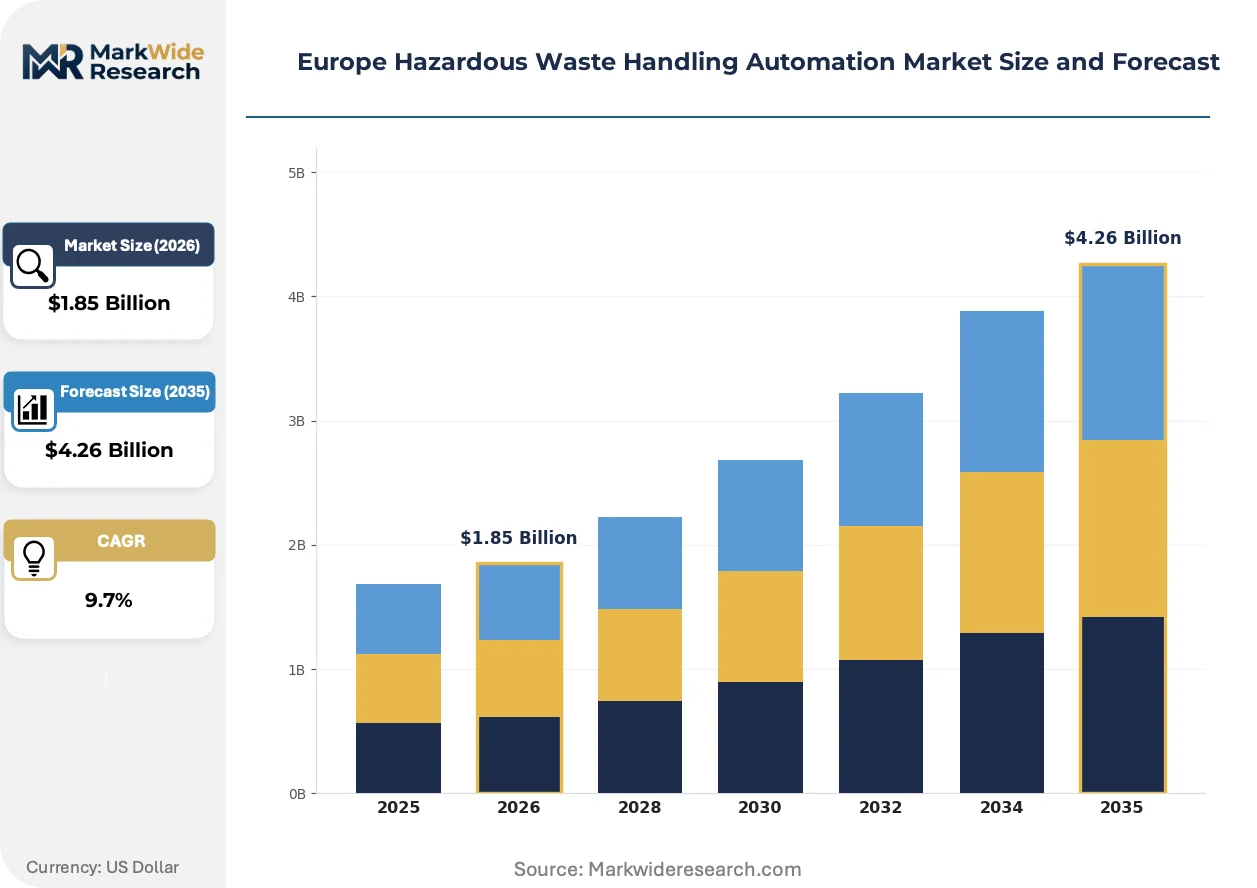
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Robotic Systems, AI Integration, Sensor Technology, Automated Vehicles Application: Waste Sorting, Waste Collection, Disposal Management, Container Handling End User: Industrial Facilities, Waste Management Companies, Research Laboratories, Government Agencies Service Type: Consulting Services, Maintenance Services, Installation Services, Training Services |
| Companies Covered | Konecranes PLC, Terex MHPS GmbH, Pallmann, Floatograph Technologies, PENZ Crane, PaR Systems Inc, Hiab, Hosokawa Micron Powder Systems, DX Engineering, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hazardous Waste Handling Automation Market Shifts & Advancements
Robotic waste handling architectures are pivoting from fixed gantry systems toward modular mobile manipulators, while regulatory data requirements reshape sensor integration priorities across European industrial zones.
Collaborative robot arms with force-torque sensing are migrating from pharmaceutical cleanroom applications into hazardous waste drum decanting operations. Belgian and Dutch chemical waste processors are piloting these platforms for semi-autonomous compatibility testing of unknown substances. The shift is compressing deployment timelines for facilities that previously relied on fully custom-engineered handling lines.
EU AI Act risk classification for autonomous decision systems in industrial environments is redefining software validation requirements for waste sorting algorithms. Machine vision systems must now demonstrate explainability for chemical identification outputs to secure CE marking under the new conformity assessment framework. German waste operators are front-loading compliance investment to avoid operational shutdowns during transitional enforcement periods.
Service contracting for automated handling systems is unbundling from equipment procurement, with waste management companies purchasing predictive maintenance subscriptions separately from capital hardware. This shift is visible most acutely in Scandinavian port facilities, where chemical waste throughput volatility makes outcome-based uptime guarantees preferable to fixed maintenance schedules. Equipment vendors are responding with sensor-embedded remote diagnostics platforms priced on availability metrics rather than hourly labor rates.
Europe Hazardous Waste Handling Automation Market Segmentation
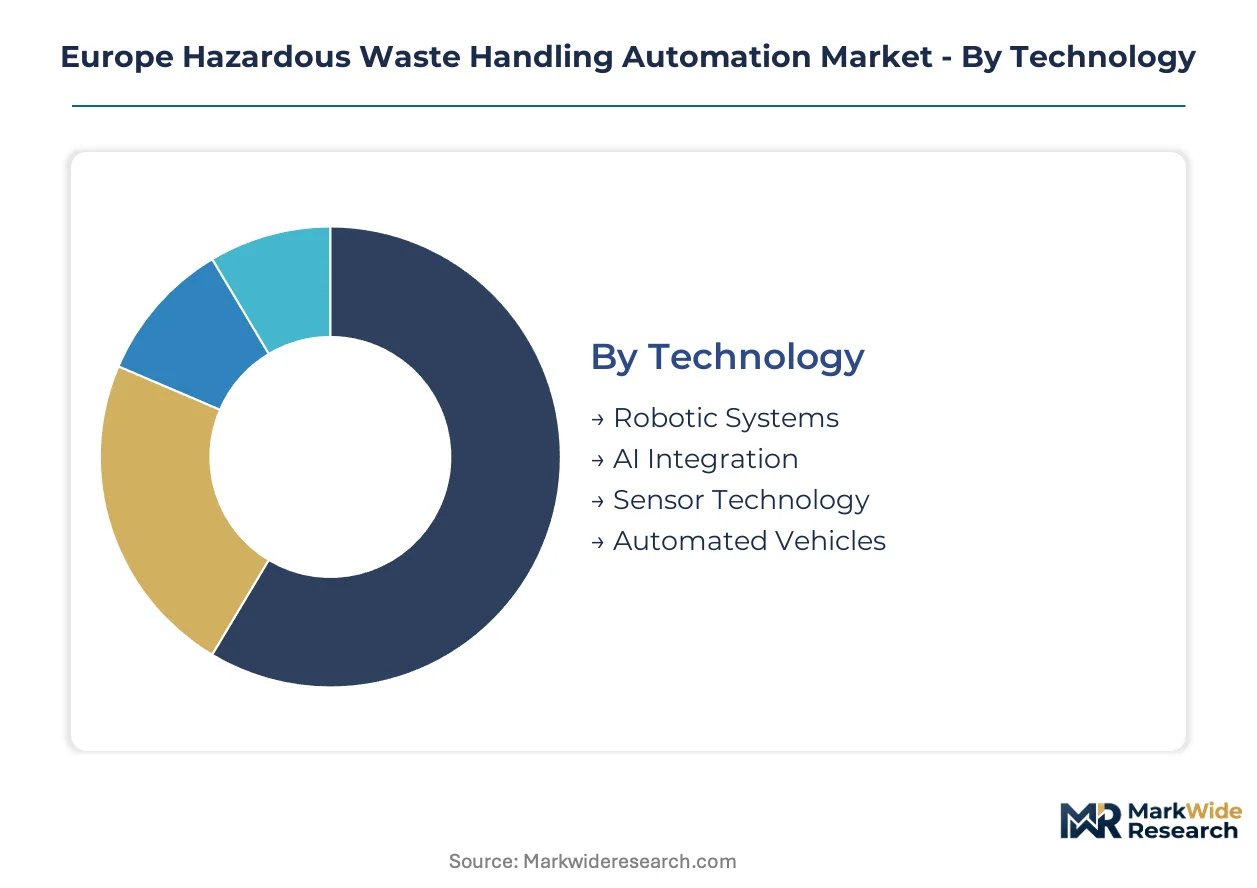
Segmentation in Europe's hazardous waste handling automation market reveals distinct technology-application pairings that determine service intensity and capital deployment cycles. Each dimension carries specific regulatory compliance implications under EU directives.
Technology:
After-sales service intensity varies sharply across technology tiers, with predictive maintenance contracts concentrated in electromechanical segments requiring ATEX-certified technician networks.
- Robotic Systems:Multi-axis manipulators with force-torque sensing and corrosion-resistant actuators handle drum decanting and container manipulation in explosive atmospheres. German chemical corridors in Ludwigshafen and Leverkusen deploy these for REACH-mandated substance segregation, with service contracts averaging 18% of initial capital cost annually.
- AI Integration:Machine vision platforms with explainable output algorithms for chemical identification under EU AI Act conformity requirements. French waste operators near Lyon front-load compliance investment to secure cross-border shipment permits ahead of transitional enforcement deadlines.
- Sensor Technology:Fiber-optic and infrared detection modules forming baseline safety interlocks for container handling.
- Automated Vehicles:AGVs and autonomous mobile robots for intra-facility waste transport with zone-exclusion safety systems.
By volume, Sensor Technology leads through ubiquitous deployment across legacy facility retrofits. By growth pace, AI Integration is expanding most quickly as conformity assessment obligations reshape procurement specifications.
Application:
Cost tier stratification separates fully automated lines from modular retrofits, with capital intensity determining addressable customer base width.
- Waste Sorting:AI-driven segregation lines with real-time chemical compatibility analysis and autonomous bin routing. Belgian and Dutch processors pilot collaborative robot platforms for unknown substance testing, compressing deployment timelines versus custom-engineered alternatives.
- Container Handling:Robotic gantry systems and mobile manipulators for drum lifting, stacking, and transfer operations in corrosive environments. Scandinavian chemical ports drive demand for sensor-embedded remote diagnostics priced on availability metrics rather than fixed labor schedules.
- Waste Collection:Automated pickup systems with RFID tracking for cradle-to-grave traceability compliance.
- Disposal Management:Integrated size-reduction and containment automation for final processing stages.
By installed base, Container Handling dominates through heavy-industry retrofit cycles. By contract value expansion, Waste Sorting is climbing the fastest as real-time identification capabilities become mandatory under tightening ECHA classification requirements.
End User:
Customer type dictates procurement authority and depreciation horizon, with industrial facilities commanding longest capital cycles and government agencies shortest.
- Waste Management Companies:Mid-tier to large operators retrofitting legacy disposal infrastructure with modular automation to preempt regulatory penalties. Polish clusters near Wrocław and Łódź present greenfield deployment potential where automated hazardous waste infrastructure remains underdeveloped.
- Industrial Facilities:Chemical and pharmaceutical manufacturers with captive waste handling requirements and internal maintenance capabilities. Oncology manufacturing facilities in Switzerland and Germany generate unmet demand for isolator-integrated robotic handling of cytotoxic antineoplastic streams.
- Research Laboratories:Academic and private R&D facilities with lower throughput but higher variety in waste profiles.
- Government Agencies:National environmental authorities and municipal operators with procurement constrained by public budgeting cycles.
By contract volume, Industrial Facilities lead through continuous process integration requirements. By growth pace, Waste Management Companies are gaining share fastest as competitive pressure and permit restrictions force automation adoption.
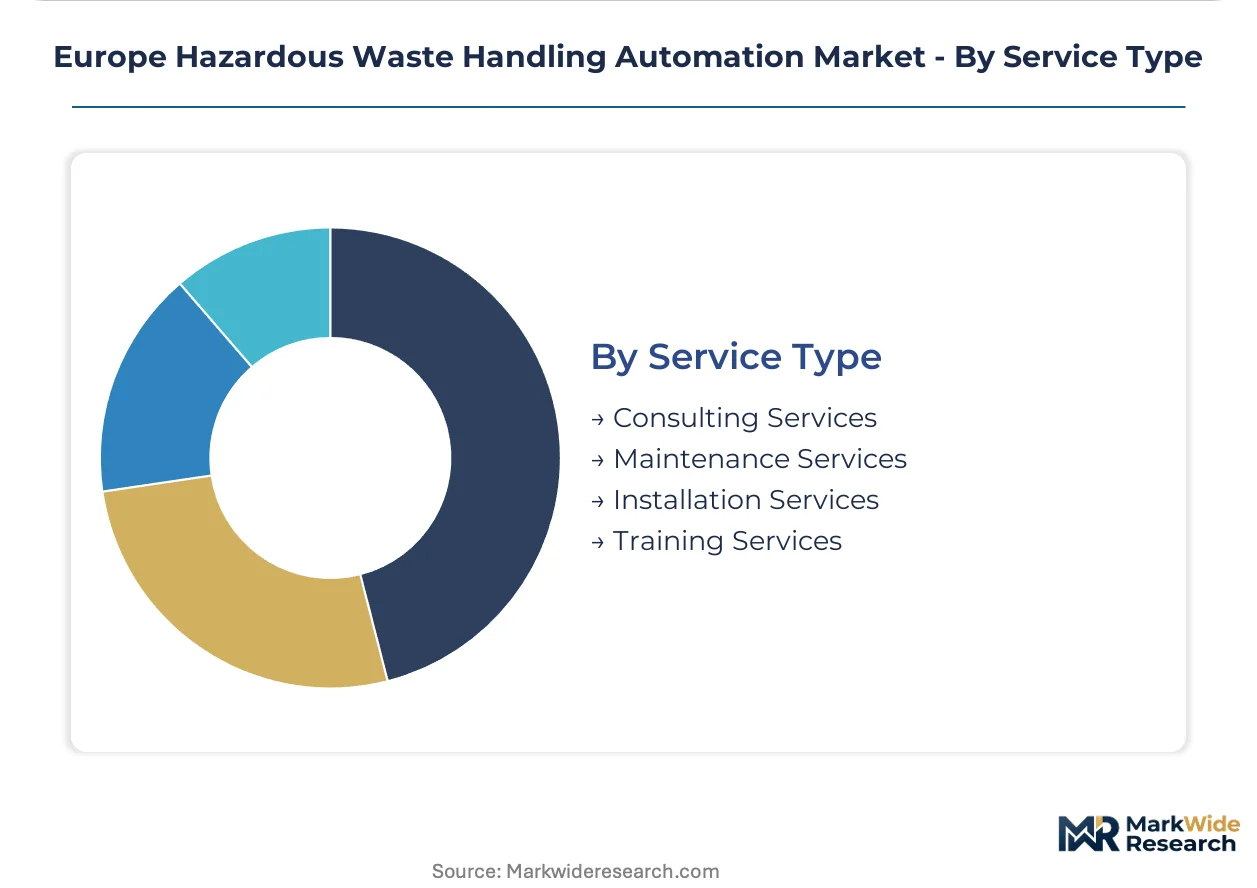
Service Type:
Margin structure favors recurring revenue streams over one-time installation, with outcome-based contracting reshaping vendor-customer relationships.
- Maintenance Services:Predictive maintenance subscriptions with sensor-embedded remote diagnostics and uptime guarantees. Nordic chemical ports demonstrate preference for availability-based pricing over fixed schedules due to throughput volatility.
- Consulting Services:Regulatory compliance pathway design and EU AI Act conformity assessment preparation. German operators engage early to avoid operational shutdowns during transitional enforcement periods.
- Installation Services:System integration and commissioning with ATEX certification support.
- Training Services:Technician certification programs for hybrid electromechanical-optical skills scarce in traditional waste operations.
By revenue stability, Maintenance Services leads through multi-year contract renewal rates. By expansion trajectory, Consulting Services shows steepest growth as CSRD sustainability reporting and AI Act obligations create compliance advisory demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Europe's hazardous waste handling automation market. German chemical manufacturers absorb premium pricing for ATEX-certified robotic systems without volume contraction. Polish and Romanian waste operators remain highly price-sensitive, favoring modular retrofits over full-line replacements.
Germany
Ludwigshafen and Leverkusen chemical corridors drive capital deployment for REACH-compliant substance segregation. The EU Green Deal accelerates retrofit timelines for legacy disposal infrastructure. Bavarian waste processors invest in predictive maintenance contracts for gantry systems handling corrosive drum inventories.
France
Lyon-based chemical waste operators front-load EU AI Act compliance investment for cross-border shipment permits. ECHA classification requirements reshape sensor calibration standards for container handling. The Grand Est region shows emerging demand for collaborative robot platforms in pharmaceutical waste streams.
Netherlands
Rotterdam chemical ports prioritize sensor-embedded remote diagnostics priced on availability metrics. REACH substance tracking mandates force automated container identification upgrades. Belgian-Dutch border facilities pilot semi-autonomous compatibility testing for unknown chemical substances.
Poland
Wrocław and Łódź industrial corridors present greenfield deployment potential with underdeveloped automated hazardous waste infrastructure. Mid-tier waste operators favor phased automation adoption to manage capital intensity. CSRD sustainability reporting convergence drives sensor network procurement for ESG compliance documentation.
Switzerland
Basel oncology manufacturing facilities generate unmet demand for isolator-integrated robotic handling of cytotoxic antineoplastic streams. Swissmedic pharmaceutical waste regulations exceed EU baseline requirements. Zurich chemical processors invest in specialized containment automation for high-potency active pharmaceutical ingredient disposal.
Europe Hazardous Waste Handling Automation Market Competitive Landscape
Heavy-industrial equipment specialists and precision automation engineers split the market into distinct capability tiers. Nordic crane manufacturers leverage installed base density for recurring service revenue capture. German engineering groups anchor chemical corridor demand with corrosion-resistant material handling systems. Competitive positioning crystallizes around predictive maintenance contract penetration and ATEX certification speed rather than hardware pricing alone.
Within the Nordic heavy-industrial tier, Konecranes PLC anchors recurring revenue streams through predictive maintenance contracts across Scandinavian chemical ports. German engineering specialists Terex MHPS GmbH exemplify the corrosion-resistant gantry system archetype for drum handling in petrochemical clusters. Precision automation engineers Hosokawa Micron Powder Systems occupy a position in integrated containment solutions for pharmaceutical waste streams. These three archetypes represent the dominant competitive vectors shaping procurement authority across European waste management operators.
| Leading Market Players |
|---|
| Konecranes PLC |
| Terex MHPS GmbH |
| Pallmann |
| Floatograph Technologies |
| PENZ Crane |
| PaR Systems Inc |
| Hiab |
| Hosokawa Micron Powder Systems |
| DX Engineering |
| Others |
Supply & Pricing Matrix
Single-source dependency on Nordic corrosion-resistant servo motor suppliers determines both three-tier pricing stratification and supply chain resilience planning across European hazardous waste automation procurement. REACH substance tracking mandates force waste operators to absorb premium pricing for ATEX-certified systems while maintaining dual-sourcing strategies for critical electromechanical components.
Pricing Analysis
Predictive maintenance subscription tiers drive lifetime value capture, with Scandinavian chemical ports demonstrating preference for availability-based contracts over fixed labor schedules. Pricing stratifies across premium certified systems, standard modular retrofits, and economy-grade sensor networks based on ATEX certification level and integration complexity. Cost compression in mid-tier gantry systems intensifies as Polish and Romanian operators delay full-line replacement decisions. Waste management companies show highest price sensitivity, while German chemical manufacturers absorb premium positioning without volume contraction.
Supply Chain Analysis
Contract manufacturing for robotic controllers concentrates in Germany, Switzerland, and the Czech Republic, with specialized ATEX-certified actuator production anchored in Nordic industrial zones. The supply chain draws from rare-earth magnet suppliers in China, precision gear manufacturers in Japan, and fiber-optic sensor specialists in the Netherlands. Single-source vulnerability for explosion-proof servo motors creates procurement risk for drum handling system integrators. Distribution runs through authorized regional service partners with certified technician networks rather than direct OEM sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where EU AI Act conformity pathways and REACH certification requirements create switching costs that lock in incumbent positions. Network effects concentrate in predictive maintenance data pools that improve algorithmic sorting accuracy with installed base expansion.
For Market Incumbents: Pre-empt modular mobile manipulator displacement of fixed gantry architectures by acquiring collaborative robot platform specialists with pharmaceutical cleanroom credentials. Anchor German chemical corridor relationships through backward integration into corrosion-resistant actuator supply chains. Accelerate ATEX certification body partnerships to compress deployment timelines against emerging Nordic competitors.
For New Entrants and Emerging Players: Pursue greenfield deployment opportunities in Polish industrial corridors near Wrocław and Łódź where automated hazardous waste infrastructure remains underdeveloped. Target pharmaceutical cytotoxic waste stream specialization in Swiss oncology manufacturing clusters with isolator-integrated robotic handling systems. Lead with outcome-based uptime guarantees rather than capital equipment sales to penetrate mid-tier waste operator budgets.
For Investors and Strategic Acquirers: EU AI Act transitional enforcement deadlines reshape the acquisition landscape toward predictive maintenance platform providers with explainable algorithm capabilities. Five-to-ten year viability favors vendors with dense Nordic installed bases generating recurring service revenue streams. Monitor ATEX notified body approval backlogs as inflection indicator for deployment timeline risk and working capital pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Front-loaded compliance spending secures cross-border shipment permits ahead of transitional enforcement deadlines. |
| Predictive Maintenance Platform Expansion | Sensor-embedded remote diagnostics capture recurring revenue from Scandinavian chemical port volatility. |
| Polish Industrial Corridor Penetration | Greenfield automation deployment addresses underdeveloped hazardous waste infrastructure near Wrocław. |
| Pharmaceutical Cytotoxic Specialization | Isolator-integrated robotic handling targets unmet demand from Basel oncology manufacturing facilities. |
| ATEX Certification Acceleration | Notified body partnership strategies compress 8-14 month approval bottlenecks for explosive atmosphere equipment. |
Research Methodology
The analysis maps robotic systems, AI integration platforms, sensor networks, and automated vehicle technologies, each validated through maintenance directors at waste management companies, plant engineers at chemical manufacturing facilities, aftermarket service heads at Nordic crane manufacturers, and procurement leads at pharmaceutical waste processors. Primary interview findings triangulate against ECHA substance classification databases, EU AI Act conformity assessment guidance, customs data for electromechanical component trade flows, and SEC filings from heavy-industrial equipment specialists. Bottom-up installed base enumeration cross-references with top-down capital expenditure estimates across German, French, and Polish chemical corridors.
Forecast assumptions hold EU Green Deal enforcement timelines and REACH tracking mandate compliance deadlines fixed while varying chemical manufacturing capacity expansion rates and ATEX certification approval speeds. The analytical framework models technology type, application intensity, end-user procurement authority, and service contract structure across the projection horizon. CAGRs derive from regression analysis of historical capital deployment patterns against regulatory milestone timing. Forecast inputs incorporate ECHA classification update frequencies and predictive maintenance contract renewal rates from Scandinavian port facilities.
Sensitivities concentrate around ATEX notified body backlog duration, rare-earth magnet supply disruptions, and EU AI Act transitional enforcement interpretation variance. Forecasts reflect documented assumptions regarding chemical manufacturing capacity expansion and regulatory compliance cost absorption. Quarterly review of ATEX approval queue lengths, Nordic servo motor order backlogs, and ECHA substance classification update schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Safety
Noise Monitoring System Market
Environmental Safety
Environmental Health and Safety Market
Environmental Safety
Asia-Pacific Rockfall Radar Market
Environmental Safety
Germany Environment Health & Safety Market
Environmental Safety
Air Audit Equipment Market
Environmental Safety
UV Air Sanitizer Market
Environmental Safety
Europe Pest Control Services Market
Environmental Safety
US Home Decontamination Services Market
Environmental Safety
Europe Process Safety Services Market
Environmental Safety
North America Rockfall Radar Market
Environmental Safety
Latin America Hazardous Waste Handling Automation Market
Environmental Safety
Environment Health & Safety Market
Environmental Safety
Home Decontamination Services Market
Environmental Safety
Global Air Sampling Pumps Market
Environmental Safety
China Home Decontamination Services Market
Environmental Safety
Industrial Noise Control Market