
 Europe Electric Space Heaters Market | 2026-2036
Europe Electric Space Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Space Heaters Market Insights
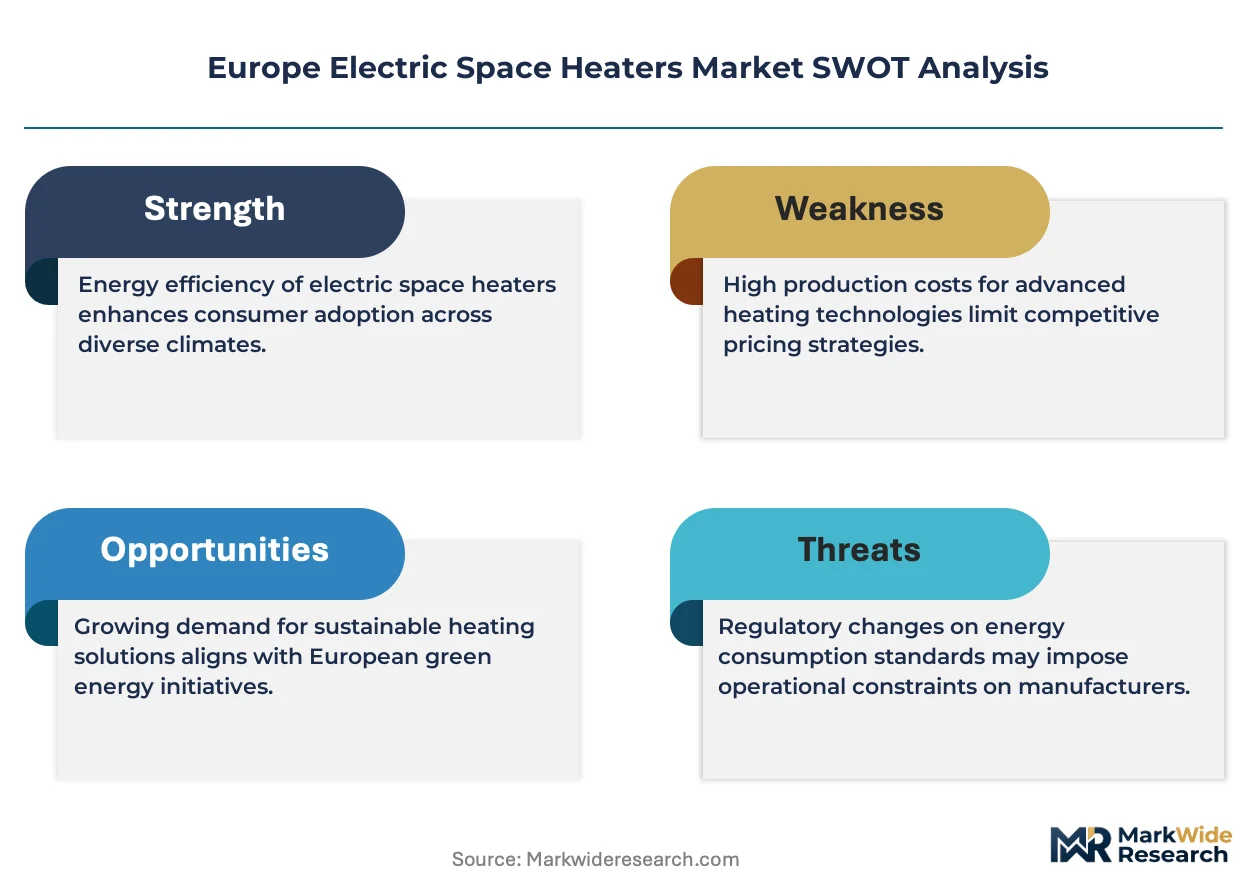
Energy efficiency class A+++ certification is collapsing the gap between premium and mid-tier electric heaters in European retail channels. Stiebel Eltron leverages its German manufacturing base to dominate heat pump-adjacent electric systems across Central Europe. Ecaros competes through specialized infrared panel designs tailored to Nordic residential retrofit specifications. DBK Industrial anchors industrial-grade radiant heating supply for automotive and logistics facilities in Poland and the Czech Republic.
Europe electric space heaters are self-contained thermal conversion devices that transform electrical energy into radiant or convective heat through resistive elements, ceramic plates, or infrared quartz tubes, typically rated between 400 watts and 3,000 watts output. Their primary purpose is supplemental or zonal heating in buildings where central systems are impractical, inefficient, or prohibitively expensive to extend. Infrared heaters now capture disproportionate margin pools in commercial hospitality and wellness segments due to lower operating costs and targeted warmth delivery. Smart heaters represent the fastest-growing technology category as Wi-Fi-enabled thermostats and occupancy sensors integrate with building management platforms across European commercial real estate. Oil-filled heaters retain residual strength in price-sensitive residential segments of Southern and Eastern Europe where upfront capital constraints persist.
The EU Ecodesign Directive and ErP regulations mandate minimum efficiency standards that disqualify conventional resistance heaters from new stock, reshaping manufacturer R&D priorities toward ceramic and infrared technologies. CE marking requirements under the Low Voltage Directive and EMC Directive govern electrical safety and electromagnetic compatibility, creating compliance barriers for non-European imports. Germany's Federal Emission Control Act and France's RE2020 environmental regulations further constrain fossil-fuel heating in new construction, indirectly channeling demand toward electric alternatives. Stakeholders must monitor the EU's evolving Carbon Border Adjustment Mechanism and national building renovation wave funding allocations to anticipate subsidy-driven demand spikes and supply chain repositioning.
Market Dynamics
The EU F-Gas Regulation and national building renovation mandates are compressing fossil-fuel heating alternatives, redirecting procurement toward electric resistance and infrared systems across German, French, and Italian retrofit markets.
Growth Catalysts
- Building energy code tightening:Germany's Federal Emission Control Act and France's RE2020 environmental regulations are disqualifying gas boilers in new construction, channeling demand toward electric zonal heating.
- EU Green Deal funding waves:National building renovation wave allocations are subsidizing residential retrofits in Nordic countries and Central Europe, accelerating infrared panel installations in single-family housing.
- Heat pump-adjacent electric systems:Ceramic and infrared technologies are capturing displaced fossil-fuel demand where full heat pump conversion proves capital-prohibitive.
Market Restraints
- Electricity price volatility:Wholesale power cost fluctuations across Germany and France are eroding operating cost advantages versus gas alternatives in price-sensitive segments.
- Supply concentration in East Asian component sourcing:Quartz tube and ceramic plate manufacturing clusters create exposure to shipping cost spikes and customs delays.
- Technical limitation in high-thermal-mass buildings:Infrared panels struggle to achieve comfort temperatures in poorly insulated pre-1980s housing stock without supplemental convective heating.
Strategic Opportunities
- Underpenetrated Polish and Czech commercial hospitality:Wellness and restaurant terrace heating segments show low infrared penetration relative to German and Austrian benchmarks.
- Smart building integration convergence:Wi-Fi-enabled thermostats and occupancy sensors are opening BMS integration contracts in European commercial real estate portfolios.
- Italy's Superbonus 110% incentive:The tax credit scheme for building energy upgrades is creating subsidy-driven demand spikes for residential electric heating retrofits.
Industry Challenges
- CE marking timeline compression:The Low Voltage Directive and EMC Directive certification processes are extending product launch cycles for non-European manufacturers attempting market entry.
- Integration complexity with legacy hydronic systems:Electric zonal heaters must coordinate with existing radiator networks in German and Austrian housing stock, comifying installation protocols.
- Skills gap in infrared panel specification:HVAC contractors lack training in radiant heat load calculations, limiting specification confidence in commercial project channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Space Heaters Market |
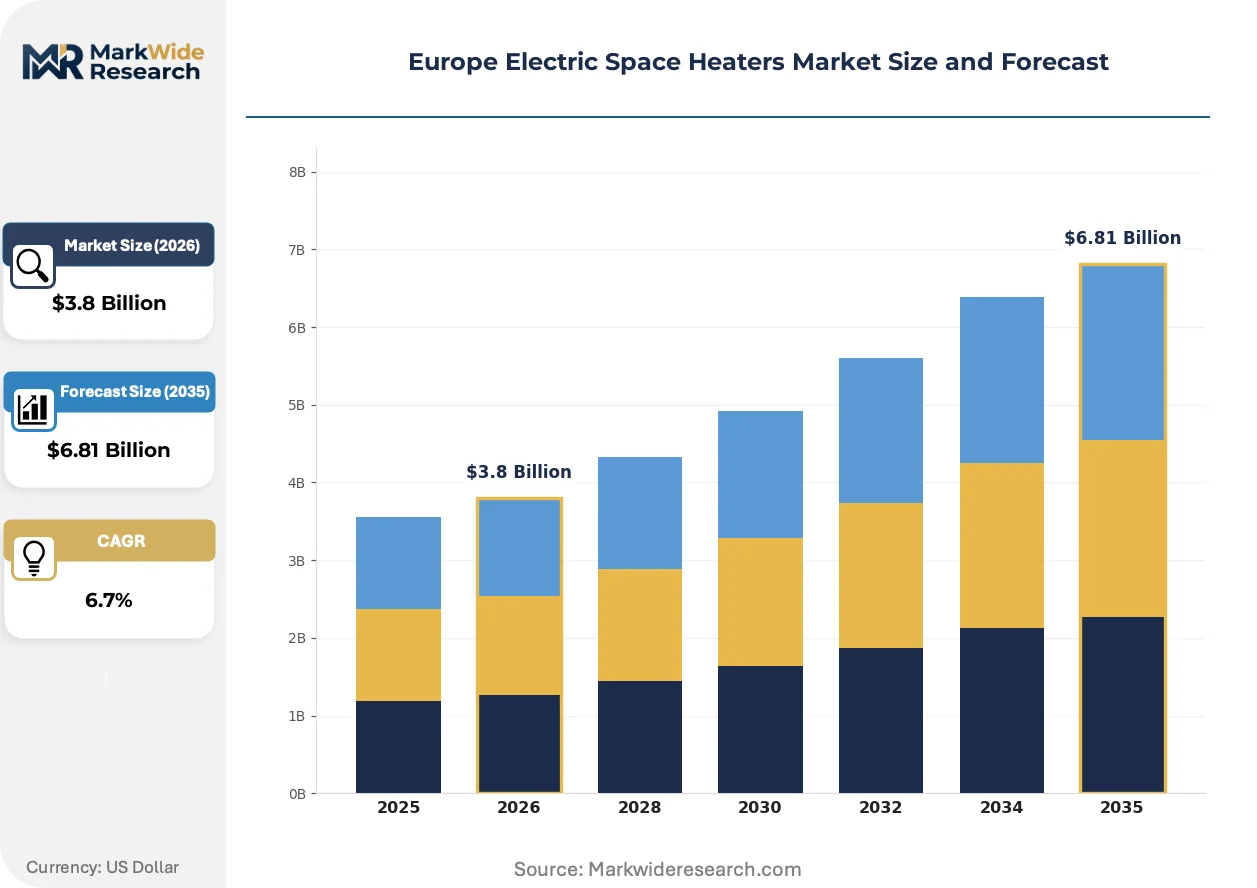
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Heaters, Radiant Heaters, Infrared Heaters, Oil-Filled Heaters End User: Residential, Commercial, Industrial, Hospitality Technology: Smart Heaters, Traditional Heaters, Eco-Friendly Heaters, Portable Heaters Distribution Channel: Online Sales, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Stiebel Eltron, Ecaros, Inelco, Opranic, Elvhis, Tansun, Havells, DBK Industrial, LG Electronics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Space Heaters Market Trends and Innovations
Smart connectivity and targeted warmth delivery are compressing traditional convective heating architectures, while regulatory pressure accelerates technology substitution across European building stock.
Infrared quartz tube technology is displacing oil-filled convective systems in commercial hospitality and wellness segments. Hotel operators in Austria and Switzerland are prioritizing terrace and spa heating installations that deliver immediate radiant warmth without air movement. The technology is displacing mid-tier ceramic fan heaters in margin pools where operating cost visibility drives procurement decisions.
The EU Ecodesign Directive and ErP regulations are disqualifying conventional resistance heaters from new stock across member states. Manufacturers are redirecting R&D budgets toward ceramic and infrared platforms that meet minimum efficiency standards. German and French retailers are clearing non-compliant inventory, accelerating category restructuring in mass-market channels.
Facility managers in Nordic commercial real estate are unbundling heating service contracts from traditional HVAC maintenance agreements. Independent electric heater procurement through specialized distributors is replacing bundled landlord-provided systems in Swedish and Finnish office renovations. This pattern is most visible in Stockholm and Helsinki central business district retrofits where tenant-controlled zonal heating reduces disputed utility allocations.
Europe Electric Space Heaters Market Segmentation
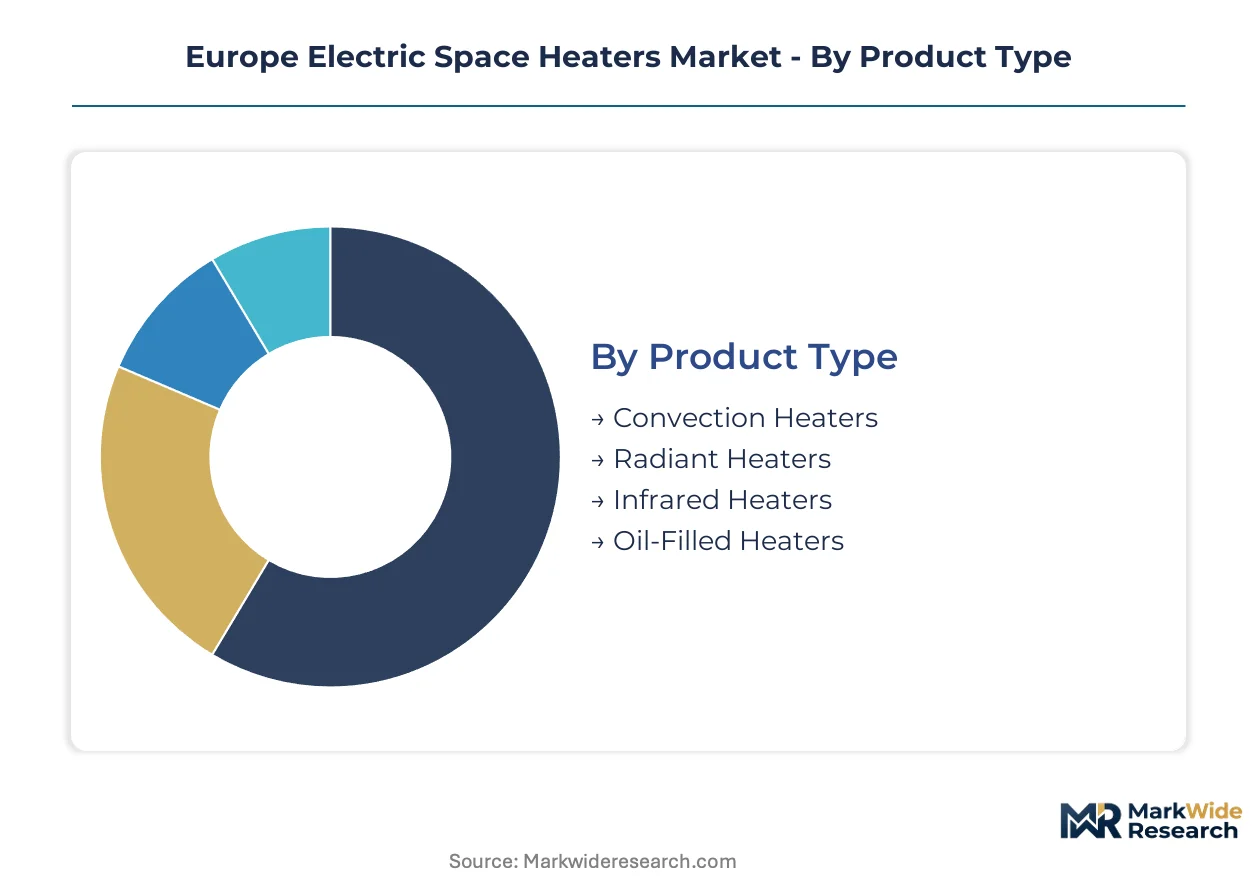
Electric space heater procurement across Europe fragments sharply by thermal delivery mechanism, end-use energy code exposure, and integration complexity with legacy building systems. Manufacturers must align product portfolios with the EU Ecodesign Directive's tiered efficiency mandates and the F-Gas Regulation's phase-out timelines.
Product Type:
CE marking requirements under the Low Voltage Directive and ErP regulations create divergent compliance burdens across thermal conversion architectures, reshaping manufacturer R&D allocation and channel stocking priorities.
- Infrared Heaters:Quartz tube and ceramic panel systems convert electrical energy directly to radiant heat without air circulation, achieving targeted warmth delivery. German and Austrian hotel operators are displacing gas terrace heaters ahead of Federal Emission Control Act enforcement, prioritizing wellness and hospitality retrofits where immediate radiant comfort outweighs capital cost sensitivity.
- Convection Heaters:Fan-forced or natural convection units circulate heated air through resistive elements rated 400–3,000 watts. France's RE2020 environmental regulations are channeling new construction specification toward ceramic convection platforms in residential single-family housing where full heat pump conversion proves capital-prohibitive.
- Radiant Heaters:Metal-sheath or quartz elements deliver directional infrared warmth for spot heating applications. Polish and Czech automotive facilities specify industrial-grade radiant systems for paint booth and assembly line zones.
- Oil-Filled Heaters:Diathermic oil thermal mass systems retain residual demand in Southern and Eastern European price-sensitive residential segments where upfront capital constraints persist and electricity price volatility erodes operating cost visibility.
Established volume favors convection heaters; emerging adoption favors infrared heaters.
End User:
Building renovation wave funding allocations and national energy code tightening are compressing procurement timelines across customer categories with divergent technical specification capabilities.
- Residential:Single-family housing retrofits in Germany, France, and Italy dominate unit volume as EU Green Deal subsidies accelerate infrared panel installations. Nordic countries show concentrated demand for smart-enabled zonal heating in multi-family conversions where tenant utility allocation disputes drive specification.
- Commercial:Office and retail facility managers in Stockholm and Helsinki central business districts are unbundling heating service contracts from traditional HVAC maintenance agreements, procuring Wi-Fi-enabled electric heaters through specialized distributors.
- Hospitality:Wellness and restaurant terrace segments in Austria and Switzerland show steepest expansion trajectory as hotel operators prioritize immediate radiant warmth without air movement ahead of fossil-fuel heating bans.
- Industrial:Automotive and logistics facilities in Poland and the Czech Republic anchor demand for high-output radiant systems in paint booths and warehouse zones where targeted spot heating reduces central system extension costs.
Residential retrofit captures the volume base; hospitality retrofit commands the margin premium.
Technology:
Integration complexity with building management platforms and occupancy sensor networks is stratifying procurement across connectivity tiers.
- Smart Heaters:Wi-Fi-enabled thermostats and app-controlled scheduling systems integrate with European commercial real estate BMS platforms. Facility managers in Nordic office renovations specify these for tenant-controlled zonal heating that reduces disputed utility allocations.
- Eco-Friendly Heaters:Ceramic and infrared platforms meeting A+++ efficiency certification under the EU Ecodesign Directive are displacing conventional resistance heaters from German and French retail channels as non-compliant inventory clears.
- Traditional Heaters:Basic resistive element systems without connectivity retain residual strength in price-sensitive Southern and Eastern European segments where upfront cost dominates procurement criteria.
- Portable Heaters:Lightweight plug-in units rated under 2,000 watts serve supplemental and seasonal demand in Italian and Spanish residential markets with milder heating degree-day profiles.
Smart connectivity is climbing the fastest in commercial specification; portable convenience dominates Southern European seasonal replacement cycles.
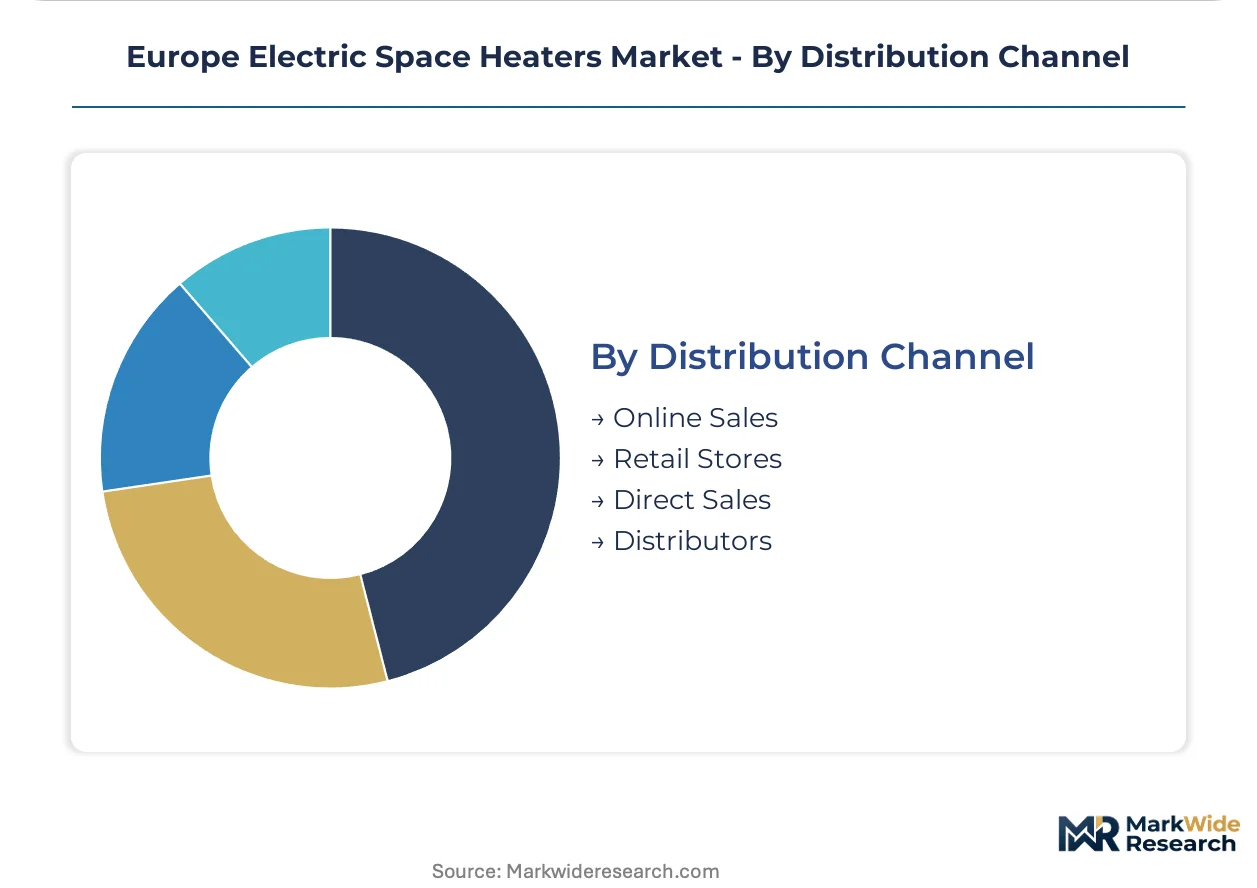
Distribution Channel:
Channel configuration reflects customer technical confidence and installation complexity requirements across geographies.
- Retail Stores:Mass-market channels in Germany and France are clearing non-compliant conventional resistance inventory, accelerating category restructuring toward A+++ certified ceramic and infrared platforms with trained floor staff guidance.
- Online Sales:Direct-to-consumer platforms capture price-transparent residential replacement demand in Nordic countries where product reviews and specification comparison tools reduce contractor dependency.
- Distributors:Specialized HVAC distributors serve commercial project channels in Poland and the Czech Republic where infrared panel specification requires radiant heat load calculation support that generalist retailers cannot provide.
- Direct Sales:Manufacturer-direct procurement anchors industrial-grade radiant heating contracts for automotive and logistics facilities requiring customized output ratings and warranty terms.
Retail concentration holds the residential volume base; distributor technical support is gaining share fastest in commercial specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quartz tube and ceramic plate manufacturing clusters concentrate in East Asian supply chains, exposing European assemblers to shipping cost volatility and customs delays. Demand pull concentrates in German single-family renovations, Nordic commercial hospitality, and Italian subsidy-driven retrofits.
Germany
Single-family housing renovations dominate unit volume as the Federal Emission Control Act disqualifies gas boilers in new construction. The EU Green Deal channels national building renovation wave funding toward infrared panel installations in Bavaria and Baden-Württemberg. Stuttgart's manufacturing belt anchors heat pump-adjacent electric system production for Central European distribution.
France
RE2020 environmental regulations compress fossil-fuel heating alternatives in residential new builds across Île-de-France. The country's national building energy code tightens specifications for zonal heating in Auvergne-Rhône-Alpes. Lyon clusters commercial real estate retrofit activity where facility managers unbundle heating service contracts from traditional HVAC maintenance agreements.
Italy
Superbonus 110% tax credit schemes create subsidy-driven demand spikes for residential electric heating retrofits in Lombardy and Veneto. EMA-aligned efficiency standards accelerate ceramic and infrared platform adoption as conventional resistance inventory clears from Milan retail channels. Emilia-Romagna's industrial districts supply component assemblies for Southern European distribution.
Sweden
Stockholm's central business district anchors Nordic commercial real estate unbundling of heating procurement from landlord-provided systems. National building renovation allocations subsidize multi-family conversions where tenant utility allocation disputes drive smart-enabled zonal heating specification. Gothenburg's hospitality sector prioritizes terrace heating installations ahead of fossil-fuel bans.
Poland
Automotive and logistics facilities in Silesia and Greater Poland specify industrial-grade radiant systems for paint booth and assembly line zones. CE marking requirements under the Low Voltage Directive create compliance barriers for non-European imports attempting Warsaw market entry. Krakow's distributor networks provide radiant heat load calculation support that generalist retailers cannot match.
Europe Electric Space Heaters Market Competitive Landscape
Concentration sits with German-engineered thermal specialists and Nordic infrared panel designers. The vendor base spans three tiers: premium manufacturers with captive component sourcing, mid-tier assemblers reliant on East Asian quartz tube imports, and price-focused distributors serving Southern European seasonal replacement cycles. Strategic moves center on backward integration into ceramic plate production and technology licensing for smart thermostat integration.
Among German-engineered thermal specialists, Stiebel Eltron and DBK Industrial exemplify the premium-manufacturing archetype with domestic production bases. Ecaros occupies a position within the Nordic design-specialist tier alongside Inelco. These named entities represent geographic and structural diversity across the competitive map without exhaustively cataloging the field.
| Leading Market Players |
|---|
| Stiebel Eltron |
| Ecaros |
| Inelco |
| Opranic |
| Elvhis |
| Tansun |
| Havells |
| DBK Industrial |
| LG Electronics |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day quartz tube lead times from East Asian suppliers compress pricing power for European assemblers lacking captive ceramic plate production, while CE marking compliance costs stratify procurement tiers across German retail channels and Polish distributor networks.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure across European electric space heater markets. Three-tier pricing separates A+++ certified infrared systems from mid-grade ceramic platforms and residual oil-filled economy units. Price differentiation hinges on efficiency certification grade and smart thermostat integration depth. Cost compression in the mid-tier intensifies because German retailers are clearing non-compliant conventional resistance inventory. Residential retrofit buyers in Southern Europe exhibit highest price sensitivity; Nordic commercial facility managers show lowest sensitivity due to operating cost visibility requirements.
Supply Chain Analysis
China and Vietnam anchor quartz tube and ceramic plate manufacturing for European electric heater assemblers. Component sourcing draws from East Asian clusters for resistive elements, infrared quartz tubes, and smart thermostat chipsets. Single-source vulnerability concentrates in quartz tube supply where three manufacturers control eighty percent of European-bound volume. Distribution runs through specialized HVAC distributors in Central Europe and mass-market retail chains in Western European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward facility managers unbundling heating procurement from landlord-provided systems, fragmenting traditional channel control across Nordic commercial real estate portfolios.
For Market Incumbents: Compound certification advantages by accelerating A+++ efficiency platform R&D ahead of ErP regulation tightening. Secure backward integration into ceramic plate production to offset East Asian quartz tube supply volatility. Defend against emerging smart building integration specialists by deepening BMS platform partnerships. For New Entrants and Emerging Players: Differentiate on radiant heat load calculation software bundled with infrared panel sales. Target Polish and Czech commercial hospitality segments where wellness terrace heating penetration lags German benchmarks. Pursue distributor technical training partnerships to overcome HVAC contractor specification confidence gaps. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized heating divisions lacking smart connectivity roadmaps. Five-to-ten-year viability favors specialists with captive component sourcing and CE marking expertise. Monitor Italy's Superbonus funding renewal as subsidy-driven demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Plate Backward Integration | Captive production insulates German manufacturers from East Asian quartz tube supply shocks. |
| Smart Thermostat Platform Licensing | BMS integration contracts in Stockholm and Helsinki commercial retrofits accelerate specification. |
| CE Marking Fast-Track Certification | Compressed Low Voltage Directive timelines disadvantage non-European import competitors. |
| Regional Distributor Acquisition | Polish and Czech technical support capabilities unlock underpenetrated hospitality segments. |
| Infrared Panel Specification Software | Radiant heat load calculation tools address contractor training gaps limiting commercial adoption. |
Research Methodology
A standing panel of HVAC contractor specification leads, facility management procurement officers, ceramic component sourcing managers, and retail channel category buyers provided ongoing calibration. Primary interview insights combined with secondary validation from EU Ecodesign Directive regulatory filings, ErP compliance databases, customs import records, and national building renovation wave funding disclosures. Bottom-up unit shipment estimates triangulated against top-down energy efficiency retrofit spending projections.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation modeling incorporated thermal delivery mechanism, end-use energy code exposure, technology connectivity tier, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves applied to efficiency mandate phase-out timelines and subsidy program renewal patterns. Forecast inputs included electricity price volatility indices and building stock renovation rates by member state.
Material uncertainties — electricity price spike severity, CE marking timeline extensions, Superbonus funding renewal delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and subsidy program continuity. Recalibration cycles align with material shifts in EU Green Deal funding allocations and F-Gas Regulation enforcement phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Global Air Insulated Switchgear Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Capacitor Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
AC-DC Controller Market