
 Offshore Cables Market | 2026-2036
Offshore Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Cables Market Outlook
Offshore wind farms is rebalancing the end-use mix away from oil and gas platform electrification as developers commission larger arrays in deeper waters. Prysmian Group leverages its vertical manufacturing footprint to control insulation compound supply and reduce lead times for high-voltage submarine projects. Nexans anchors European demand through dedicated subsea cable facilities in Norway and France. NKT competes with a focused DC technology portfolio that addresses long-distance offshore grid connections.
Offshore cables are specialized submarine power and communications lines engineered with cross-linked polyethylene insulation, steel wire armoring, and lead or aluminum sheathing to withstand hydrostatic pressure, salt corrosion, and mechanical abrasion at depths exceeding 500 meters. Their primary purpose is to transmit electricity and data between offshore energy assets, islands, and mainland grids. AC cables still occupy the majority of inter-array connections within wind farms due to cost efficiency at shorter distances, while DC cables represent the fastest-growing product category as voltage source converter technology matures for long-haul export links. Fiber optic cables command premium positioning within composite bundled designs that integrate power and monitoring functions for offshore wind farm operators.
The European Union's F-Gas Regulation and CE marking requirements under the MDR framework shape insulation material selection and product certification pathways for cable manufacturers serving North Sea projects. The International Electrotechnical Commission publishes submarine cable standards that govern testing protocols for water ingress, thermal cycling, and bending radius performance. China's MIIT and GB standards influence supplier qualification for domestic offshore wind tenders. Stakeholders must monitor how regulatory divergence between the EU Green Deal's cable recycling mandates and China's dual carbon goals affects cross-border component sourcing and plant location decisions.
Market Dynamics
Offshore wind developers are commissioning arrays exceeding one gigawatt in capacity, forcing cable suppliers to scale manufacturing for longer export links and higher voltage ratings. This capacity expansion is compressing lead times and concentrating procurement power among a handful of European project developers.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of sulfur hexafluoride insulation is accelerating adoption of gas-insulated cable systems with synthetic ester fluids in North Sea projects.
- Voltage source converter technology:Maturing HVDC transmission is enabling interconnector projects spanning multiple jurisdictions and island nations.
- Floating offshore wind:Dynamic cable designs for tethered platforms are opening deeper water sites off Scotland and Portugal.
Market Restraints
- Copper and aluminum price volatility:Raw material swings constitute over half of cable production costs, squeezing fixed-price contract margins.
- Specialized vessel scarcity:Cable-laying ship availability concentrates among Norwegian and Dutch operators, creating installation bottlenecks.
- XLPE insulation thickness limits:Current extrusion technology caps voltage ratings for ultra-deep installations beyond 800 meters.
Strategic Opportunities
- United States offshore wind:Lease auctions off Massachusetts and California are creating first-mover advantages for cable system integrators.
- Composite bundled designs:Fiber optic integration with power cores enables real-time temperature monitoring and predictive maintenance for wind farm operators.
- EU Green Deal recycling mandates:Circular economy requirements for cable sheathing recovery are favoring suppliers with closed-loop polymer processing.
Industry Challenges
- Submarine cable jointing technicians:The specialized workforce for high-voltage splices at sea numbers fewer than five hundred certified specialists across Europe.
- IEC 62895 certification timelines:Type testing for DC submarine cables requires eighteen to twenty-four months, delaying project financial close.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Cables Market |
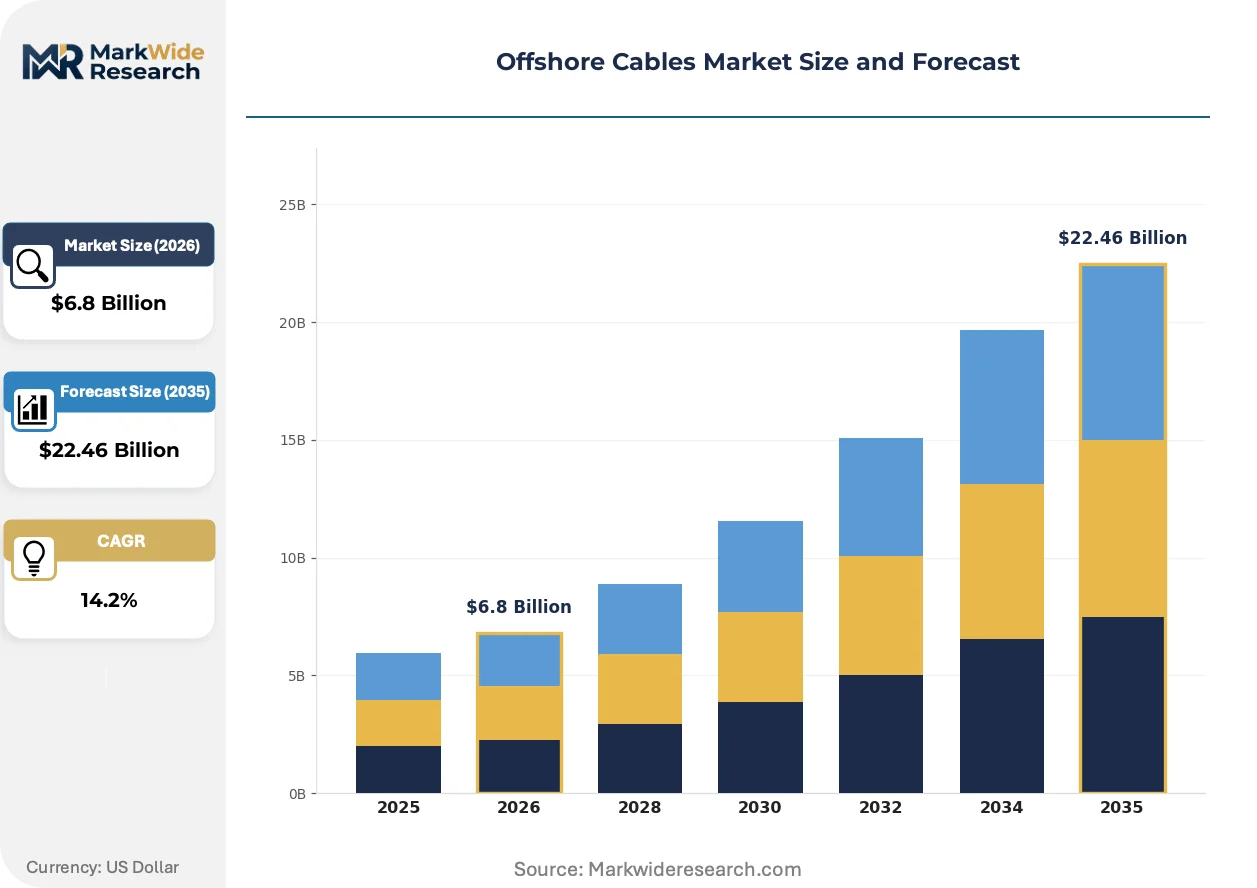
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Cables, DC Cables, Fiber Optic Cables, Composite Cables Installation Type: Buried, Surface-laid, Bundled, Integrated End User: Utilities, Offshore Wind Farms, Oil & Gas, Marine Contractors Material: Copper, Aluminium, Polyethylene, Steel Wire |
| Companies Covered | Prysmian Group, Nexans, NKT, Sumitomo Electric Industries, LS Cable & System, JDR Cable Systems, Hellenic Cables, Furukawa Electric, ZTT Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Cables Market Strategic Shifts
Material science advances and installation automation are compressing project schedules while extending operational lifespans. The competitive frontier has shifted from pure manufacturing scale to integrated system design and offshore logistics coordination.
Cross-linked polyethylene insulation rated for 525 kilovolts is consolidating as the dominant dielectric for long-distance export cables. Offshore wind developers in Germany and Denmark are specifying this material for projects exceeding two hundred kilometers from shore. The technology is consolidating supplier portfolios around fewer compound formulations with proven deep-water performance records.
The EU F-Gas Regulation's 2027 phase-down targets for fluorinated gases are forcing reformulation of gas-insulated transmission lines. Cable manufacturers serving North Sea markets are retrofitting testing facilities for synthetic ester and nitrogen-based insulation systems. Subsea cable facilities in Norway face the steepest compliance costs due to existing SF6 infrastructure.
Long-term service agreements are displacing transactional component sales for inter-array cable systems. Wind farm operators in the United Kingdom are contracting fifteen-year availability guarantees covering installation, monitoring, and replacement. This shift concentrates risk with cable suppliers while reducing developer capital exposure.
Offshore Cables Market Segmentation
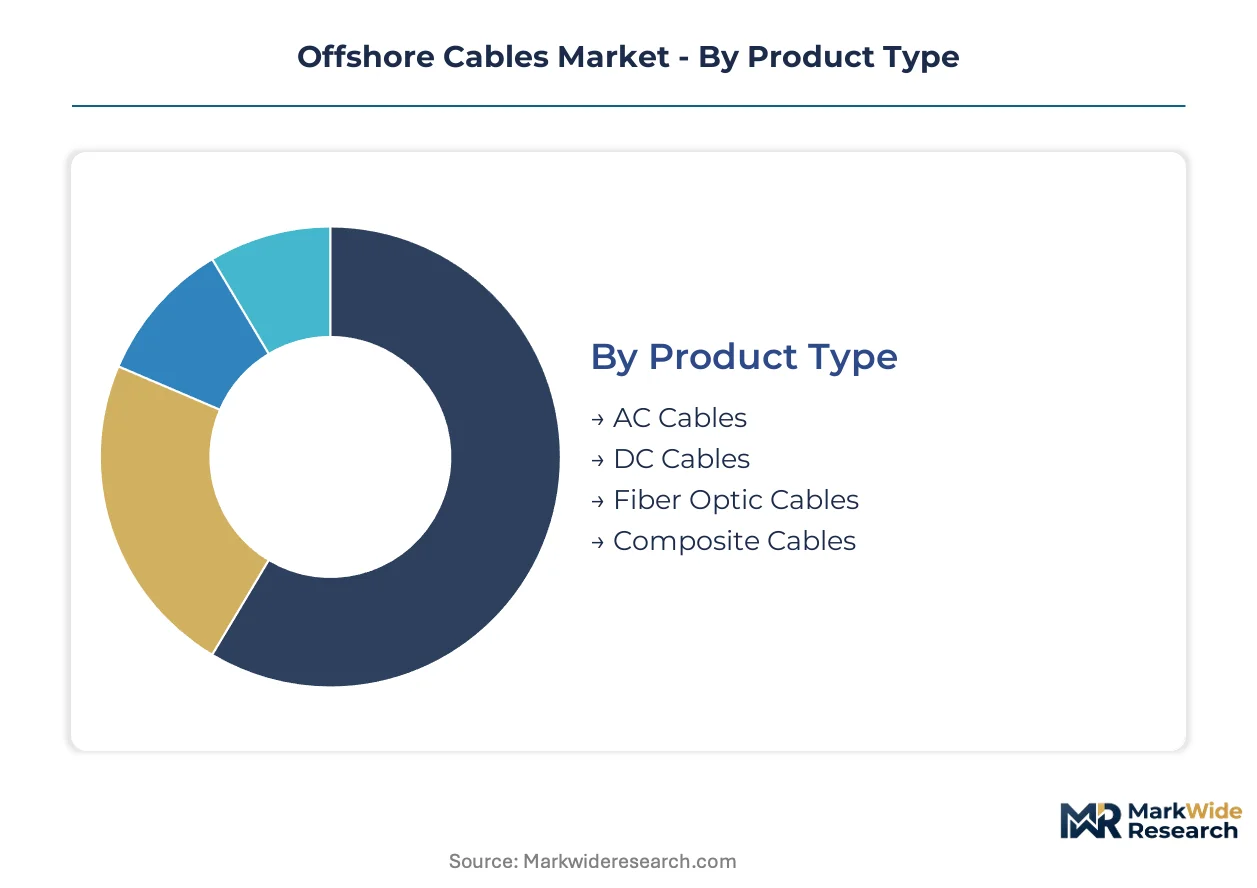
Offshore cable procurement decisions hinge on voltage distance economics, installation logistics, and regulatory material compliance. Developers weigh capital expenditure against operational reliability across product generations and deployment methods. Each segmentation dimension reveals distinct margin structures and supplier specialization patterns.
Product Type:
Voltage source converter economics and array-to-shore distances determine whether developers specify alternating or direct current transmission systems.
- AC Cables:Cross-linked polyethylene insulation rated to 245 kilovolts dominates inter-array connections within wind farms under 80 kilometers from shore. German and Danish developers favor this technology for its mature jointing protocols and lower converter station costs.
- DC Cables:Mass-impregnated or extruded insulation systems enable bulk power transmission beyond 100 kilometers with lower line losses. Voltage source converter maturation is accelerating HVDC adoption for gigawatt-scale export links from Scottish and Norwegian offshore zones.
- Fiber Optic Cables:Silica-core sensing lines integrated within power bundles provide distributed temperature monitoring and structural health data for predictive maintenance algorithms.
- Composite Cables:Hybrid designs combining power cores with fiber elements reduce installation vessel trips and simplify subsea infrastructure footprint for floating wind platforms.
AC Cables lead on scale; DC Cables lead on momentum.
Installation Type:
Seabed geology, fishing activity intensity, and water depth dictate mechanical protection requirements and trenching method selection.
- Buried:Plough or jet-trenching to 1-3 meters below mudline protects against anchor strikes and trawling gear in the North Sea and Irish Sea corridors. Rock dumping supplements burial where sediment is thin.
- Surface-laid:Concrete mattress or articulated pipe protection suits hard seabed conditions or steep slopes where trenching is impractical. This method concentrates in Norwegian fjord crossings and Mediterranean depths.
- Bundled:Multiple circuits share a single trench or protective structure to minimize seabed disturbance and permitting complexity for clustered wind farm export routes.
- Integrated:Pre-installed cable systems within monopile or jacket foundations eliminate separate burial operations and reduce offshore construction weather windows.
Buried installation dominates procurement volumes; Integrated methods are climbing the fastest as foundation designs standardize.
End User:
Contracting structures and technical specifications diverge sharply between regulated utilities and merchant offshore developers.
- Utilities:Grid operators in Germany and the United Kingdom procure export cables under regulated asset base frameworks with standardized technical specifications and 40-year depreciation horizons.
- Offshore Wind Farms:Independent power producers negotiate turnkey engineering-procurement-construction contracts that transfer installation risk to cable system integrators, with availability guarantees extending 15-25 years.
- Oil & Gas:Platform electrification projects in the Norwegian North Sea and UK Continental Shelf specify dynamic cables rated for wave-induced fatigue and hydrocarbon exposure.
- Marine Contractors:Installation fleet operators purchase cable storage and handling equipment, plus spares inventory, to maintain vessel utilization across project portfolios.
Offshore Wind Farms lead on scale; Oil & Gas leads on specification complexity.
Material:
Conductivity requirements, weight constraints, and corrosion resistance determine metal and polymer selection across voltage classes.
- Copper:Oxygen-free high-conductivity grades dominate medium-voltage inter-array circuits where ampacity density justifies premium pricing over aluminum alternatives.
- Aluminium:Lighter conductor mass reduces topside structural loads for floating wind applications and long-span suspension bridges in Norwegian fjord crossings.
- Polyethylene:Cross-linked compounds rated for 90°C continuous operation form the dielectric backbone of extruded HVDC and HVAC submarine systems.
- Steel Wire:Galvanized or stainless armoring layers withstand hydrostatic pressure exceeding 50 bar and provide tensile strength for deep-water lowering operations.
Copper leads on revenue per kilometer; Aluminium leads on volume growth in floating wind segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea basin concentrates offshore cable manufacturing and installation capacity across specialized facilities in Norway, Germany, and Denmark. Developers in this corridor commission the highest voltage-rated systems for gigawatt-scale wind arrays. Regulatory frameworks and vessel availability shape procurement patterns in each national market.
United Kingdom
Dogger Bank and Hornsea wind zones drive demand for 525 kilovolt export cables exceeding 200 kilometers in length. The UK regulator Ofgem oversees offshore transmission owner frameworks that standardize 40-year asset lifespans. Manufacturing clusters in Scotland and Northeast England specialize in dynamic cable systems for floating wind prototypes.
Germany
Baltic Sea and North Sea lease rounds specify HVDC connections for projects 100 kilometers from shore. The Federal Network Agency implements offshore grid development plans that mandate redundant cable corridors. Cable fabrication facilities in Lower Saxony and Schleswig-Holstein scale extrusion capacity for 66 kilovolt inter-array circuits.
Norway
Fjord-crossing interconnectors and oil platform electrification projects require aluminum-conductor cables for long-span suspensions. The Norwegian Water Resources and Energy Directorate licenses subsea power links under integrated resource planning frameworks. Stavanger and Bergen host specialized jointing technician training centers serving North Sea contractors.
Denmark
Kriegers Flak and Thor offshore zones anchor procurement for bundled AC export systems. The Danish Energy Agency coordinates cross-border cable corridors with German and Swedish regulators. Esbjerg port facilities function as the primary cable load-out hub for North Sea installation fleets.
China
Provincial offshore wind tenders in Guangdong and Fujian specify 220 kilovolt submarine cables for typhoon-resistant installations. MIIT and GB standards govern supplier qualification for state-owned utility procurement. Yangtze River Delta manufacturing bases produce armoring wire and insulation compounds for domestic project pipelines.
Offshore Cables Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers retrofit facilities for 525 kilovolt extrusion lines and synthetic ester testing. The vendor base concentrates among European specialists with captive cable-laying vessel access and Asian conglomerates with integrated metal supply chains. Two strategic archetypes define competitive positioning: vertically integrated compound-to-cable producers controlling insulation material supply, and system integrators bundling installation services with long-term availability guarantees. M&A activity targets specialized jointing technicians and dynamic cable engineering capabilities, while strategic partnerships secure vessel slots amid fleet scarcity.
Among European cable specialists, Prysmian Group, Nexans, and NKT occupy positions spanning manufacturing scale and technology specialization. Prysmian Group exemplifies the integrated compound producer archetype through captive supply of cross-linked polyethylene insulation. Nexans represents the system integrator model with dedicated subsea facilities anchoring regional procurement relationships. NKT sits within the high-voltage DC technology tier, addressing long-distance offshore grid connections through focused converter-compatible cable portfolios.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| NKT |
| Sumitomo Electric Industries |
| LS Cable & System |
| JDR Cable Systems |
| Hellenic Cables |
| Furukawa Electric |
| ZTT Group |
| Others |
Value Chain & Pricing Dynamics
Captive supply of cross-linked polyethylene insulation anchors pricing power for vertically integrated European cable manufacturers serving North Sea offshore wind projects. This backward integration into compound production shields margin positions from raw material volatility while locking in supply priority for 525 kilovolt export cable contracts.
Pricing Analysis
Input-cost pass-through from copper and aluminum markets dominates contract structures, with metal price escalation clauses standard in fixed-price agreements for inter-array systems. Price differentiation rests on voltage rating tier and IEC 62895 certification status, with DC-rated cables commanding substantial premiums over AC alternatives. Pricing pressure stems from developer consolidation concentrating procurement leverage among five major European offshore wind sponsors. Merchant independent power producers exhibit highest price sensitivity, while regulated utilities under UK and German offshore transmission owner frameworks accept longer-term cost structures.
Supply Chain Analysis
Dual-sourcing requirements from project financiers mandate qualified supplier redundancy for critical path components, forcing developers to pre-qualify cable manufacturers in Norway, Germany, and Denmark alongside Asian alternatives. Raw material flows draw from Chilean copper cathode, Chinese aluminum smelting, and Saudi petrochemical feedstock for polyethylene compounds. Single-source vulnerability concentrates in specialized cable-laying vessel availability, with Norwegian and Dutch operators controlling fleet deployment. Distribution runs through Esbjerg port consolidation hubs before offshore installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The offshore cables market functions as a regulatory compounder where EU F-Gas Regulation phase-down mandates and EU Green Deal recycling requirements continuously reshape material specifications and compliance costs.
For Market Incumbents: Hedge against synthetic ester insulation technology transition by retrofitting testing facilities ahead of 2027 compliance deadlines. Secure captive cable-laying vessel slots through long-term charter agreements to defend against installation bottleneck risks. Prioritize technician certification programs to address the sub-500 specialist workforce constraint for high-voltage submarine jointing. For New Entrants and Emerging Players: The premium-to-economy price-point gap in dynamic cable systems for floating offshore wind platforms offers accessible entry terrain. Target Portuguese and Scottish deep-water zones where tethered platform designs lack established supply relationships. Pursue joint development agreements with floating wind foundation specialists to embed cable specifications early in project design cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized jointing technician capabilities and dynamic cable engineering expertise concentrate in fragmented regional service providers. Frame five-to-ten year viability assessments around HVDC converter technology maturation trajectories and floating wind commercialization timelines. Monitor synthetic ester insulation qualification milestones as inflection indicators for technology transition winners.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Ester Insulation Qualification | EU F-Gas Regulation compliance secures market access for North Sea project participation. |
| Cable-Laying Vessel Charter Agreement | Norwegian and Dutch fleet access eliminates installation schedule risk for export cable contracts. |
| Jointing Technician Training Center | Stavanger and Bergen facilities address sub-500 specialist bottleneck constraining project execution. |
| Composite Bundled Design Development | Fiber optic integration enables predictive maintenance contracts with 15-year availability guarantees. |
| Closed-Loop Polymer Processing Investment | EU Green Deal recycling mandates favor suppliers with circular economy cable sheathing recovery. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with offshore wind project developers, cable system procurement leads, subsea installation contractors, and regulatory affairs specialists at transmission system operators with secondary validation from IEC standards documentation, EU regulatory filings, and vessel fleet deployment databases. Bottom-up project pipeline aggregation and top-down manufacturing capacity assessment provided triangulation across the analysis window.
Segment-weighting approaches distributed value and volume projections across AC cable, DC cable, fiber optic, and composite product categories, with installation type and end-user dimensions layered into the analytical framework. CAGRs derived from project commissioning schedules and manufacturing capacity expansion timelines incorporated voltage source converter technology adoption curves and floating wind platform deployment trajectories as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for gas-insulated transmission line retrofitting would alter the outlook for synthetic ester insulation demand. Deviation in EU F-Gas Regulation enforcement timelines or cable-laying vessel availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
HVDC Converter Station Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
North America Alternating Current (AC) Drive Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
Portable Space Heater Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Storage Water Heater Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market