
 Alternator Regulator Market | 2026-2036
Alternator Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Alternator Regulator Market Analytics
A shortage of power electronics engineers with embedded firmware expertise is redrawing competitive boundaries across the alternator regulator supply chain. Bosch leverages its in-house semiconductor capabilities to sustain design leadership in microcontroller-based architectures. Denso anchors its position through captive integration with Toyota's hybrid vehicle platforms. AS-PL competes aggressively in the European aftermarket channel with cost-optimized electronic regulator replacements.
An alternator regulator governs voltage output from an automotive alternator to maintain battery charge stability, typically operating within a 13.5–14.5 V setpoint range through feedback control circuits that adjust field current to the rotor winding. Electronic regulators have displaced mechanical designs across passenger vehicle applications, while digital regulators with CAN bus communication represent the fastest-growing technology tier as automakers pursue software-defined charging strategies. The commercial vehicle end-user segment occupies the deepest margin pools due to durability specifications and fleet telematics integration requirements. Marine applications remain a specialized niche where corrosion-resistant packaging commands premium positioning.
The EPA enforces fuel economy standards that directly shape alternator efficiency targets, while NHTSA electrical system safety regulations mandate overvoltage protection thresholds. China's MIIT implements GB standards for vehicle electrical subsystems that constrain import market access for non-compliant designs. Stakeholders must monitor how ISO 26262 functional safety requirements propagate from high-voltage electrification into 12 V subsystem component specifications.
Market Dynamics
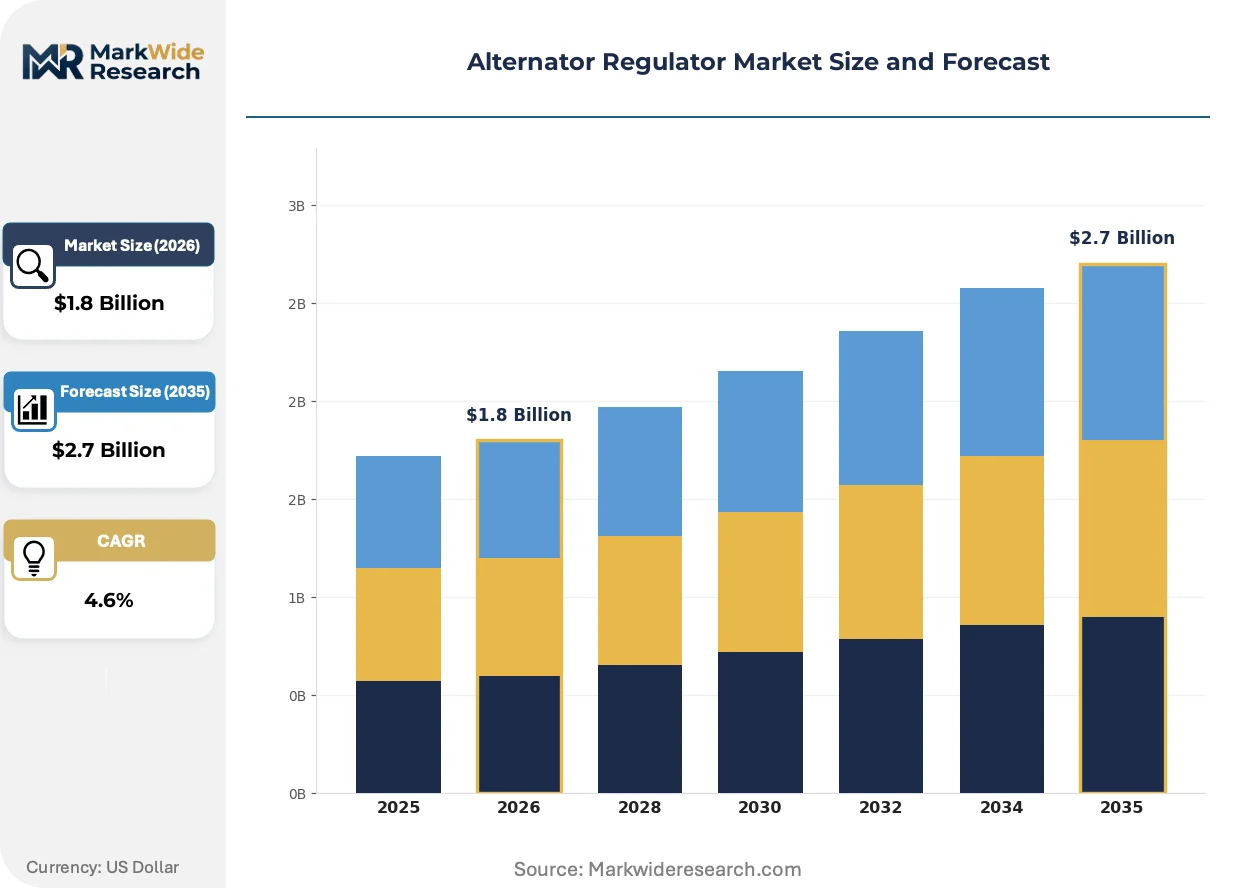
The alternator regulator market is reconfiguring around semiconductor supply constraints and the migration from analog to microcontroller-based voltage control architectures. Tier-1 suppliers with captive chip fabrication or long-term foundry partnerships are capturing procurement volume from smaller competitors.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases is compelling automakers to replace mechanical regulators with electronic designs that reduce alternator drag and improve fuel efficiency.
- Commercial vehicle fleet telematics:Heavy-duty truck operators are mandating CAN bus-enabled digital regulators to enable real-time battery health monitoring and predictive maintenance scheduling.
- China's dual carbon goals:MIIT efficiency mandates for internal combustion vehicles are accelerating domestic adoption of smart charging algorithms that optimize alternator load cycles.
Market Restraints
- Silicon carbide MOSFET cost volatility:Power semiconductor substrate prices fluctuate with electric vehicle demand, compressing margins for regulator manufacturers without backward integration into wafer supply.
- Concentrated foundry capacity:Advanced node production for automotive-grade microcontrollers clusters in Taiwan and South Korea, creating geographic supply risk for European and North American tier suppliers.
- 12V/48V system coexistence:Hybrid electrical architectures require dual-voltage compatible regulators, adding design complexity and certification burden without proportional price premiums.
Strategic Opportunities
- India's PLI scheme for auto components:Localized production incentives are opening domestic manufacturing footholds for electronic regulator assembly serving Maruti Suzuki and Tata Motors supply chains.
- Marine electrification:Yacht and commercial vessel builders are specifying sealed, salt-spray-resistant digital regulators for integrated starter-generator systems in hybrid propulsion packages.
- ISO 26262 ASIL-D certification:Functional safety compliance for voltage regulation is becoming a procurement differentiator as automakers extend safety-critical standards from high-voltage to 12V subsystems.
Industry Challenges
- Embedded firmware engineering scarcity:Power electronics specialists with automotive safety-critical coding expertise command premium compensation, constraining R&D scaling for mid-tier suppliers.
- Legacy system integration friction:Retrofitting digital regulators into 10-15 year vehicle platforms requires backward-compatible pin configurations and analog fallback modes that dilute performance advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternator Regulator Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Regulators, Electronic Regulators, Digital Regulators, Hybrid Regulators End User: Automotive OEMs, Aftermarket Providers, Heavy Machinery, Marine Technology: Linear Technology, PWM Technology, Switch Mode Technology, Microcontroller Based Application: Passenger Vehicles, Commercial Vehicles, Industrial Equipment, Recreational Vehicles |
| Companies Covered | Remy, AS-PL, Bosch, Marathon Electric, Hitachi, Denso, DB Electrical, Tuff Stuff, ACDelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternator Regulator Market Evolving Landscape
Active developments across three domains are compressing product lifecycles and redrawing competitive boundaries in voltage regulation technology. Semiconductor integration, emissions-linked certification, and procurement centralization are converging to reshape supplier economics.
Multi-phase synchronous rectification is miniaturizing alternator regulator footprints while improving thermal efficiency. Passenger vehicle OEMs are adopting these designs for engine-downsized platforms where under-hood space constraints intensify. The technology is miniaturizing discrete component counts by 40-60%, enabling single-package integration with the alternator brush holder assembly.
EPA vehicle efficiency mandates are tightening alternator load cycle specifications to reduce parasitic engine losses. Tier-1 suppliers must now validate fuel economy contribution data for each regulator variant seeking OEM qualification. The commercial vehicle segment bears the heaviest compliance burden, with fleet operators demanding documented efficiency deltas for warranty-backed fuel economy claims.
Fleet procurement centralization is consolidating alternator regulator purchasing through telematics-integrated service contracts. Independent repair shops are losing share to authorized dealer networks that bundle voltage regulation diagnostics with predictive battery replacement programs. This pattern is most pronounced in Germany and the United States, where commercial fleet management companies negotiate multi-year supply agreements with direct OEM channel partners.
Alternator Regulator Market Segmentation
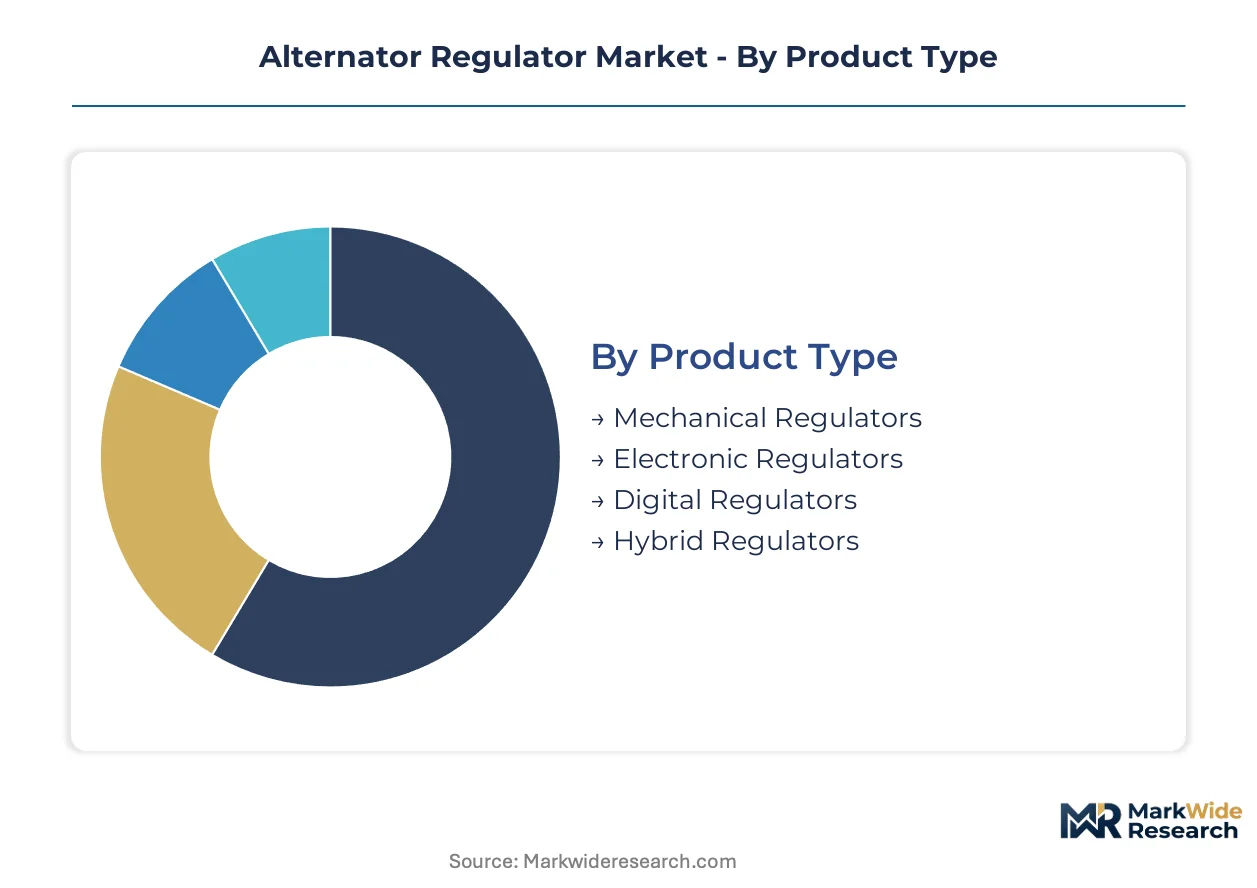
Segmentation in the alternator regulator market reveals how procurement channels and technical specifications diverge across customer types. Product architecture choices cascade through certification requirements, foundry partnerships, and margin structures.
Product Type:
Channel-mix patterns vary sharply across regulator architectures, with OEM direct procurement favoring digital and hybrid designs while aftermarket distributors stock electronic replacements for legacy fleet maintenance.
- Mechanical Regulators:Electromechanical voltage control using vibrating contact points and spring-tension adjustments. Demand persists in vintage vehicle restoration and developing-market commercial fleets where simplicity outweighs efficiency mandates. Brazil's ANVISA-aligned vehicle safety standards still permit these designs for certain heavy-duty applications.
- Electronic Regulators:Solid-state designs with zener diode reference circuits and power transistor switching. These dominate aftermarket distribution through NAPA, O'Reilly, and similar retail networks serving North American passenger vehicle maintenance. EPA fuel economy verification requirements now exclude these from new OEM platforms.
- Digital Regulators:Microcontroller-based architectures with programmable voltage setpoints and CAN bus diagnostics. OEM direct procurement concentrates here for EU F-Gas Regulation compliance.
- Hybrid Regulators:Dual-mode designs combining analog fallback with digital primary control for 12V/48V system compatibility. Emerging procurement channel through tier-1 alternator manufacturers.
Electronic regulators dominate installed base. Digital regulators are where expansion concentrates.
End User:
Cost tier stratification separates specification-intensive OEM contracts from price-sensitive aftermarket volume.
- Automotive OEMs:Direct procurement with multi-year supply agreements, ISO 26262 ASIL-D certification requirements, and embedded firmware validation protocols. Toyota, Volkswagen, and Stellantis negotiate consolidated alternator-regulator-battery system contracts.
- Aftermarket Providers:Distributor-mediated sales through WAI Global, BBB Industries, and regional jobber networks. Price competition intensifies with AS-PL and similar specialists offering electronic regulator replacements at 40-60% below OEM list pricing.
- Heavy Machinery:Caterpillar and Komatsu specify sealed regulators with extended temperature ranges for construction and mining equipment. Procurement runs through equipment dealer service departments with telematics-integrated predictive maintenance contracts.
- Marine:Yacht builders and commercial vessel operators demand salt-spray-resistant packaging per IEC 60945 maritime standards. Specialized distribution through West Marine and commercial marine suppliers commands premium positioning.
Aftermarket providers move highest unit volumes. Automotive OEMs capture steepest expansion trajectory.
Technology:
Application requirements dictate technology selection, with thermal management and electromagnetic compatibility driving architecture choices.
- Linear Technology:Continuous conduction mode with dissipative regulation. Simple implementation suits low-current auxiliary applications in recreational vehicles where cost minimization dominates.
- PWM Technology:Pulse-width modulation switching at fixed frequency reduces power dissipation versus linear designs. Commercial vehicle alternators adopt these for improved thermal efficiency under sustained high-load operation.
- Switch Mode Technology:Variable frequency switching with synchronous rectification enables highest efficiency conversion. Passenger vehicle engine-downsized platforms specify these for under-hood space constraints.
- Microcontroller Based:Software-defined voltage profiles with adaptive load response and diagnostic logging. Fastest-growing technology tier as MIIT efficiency mandates in China and EPA standards in the United States converge on smart charging algorithms.
PWM technology holds broadest application footprint. Microcontroller-based designs are gaining share fastest.
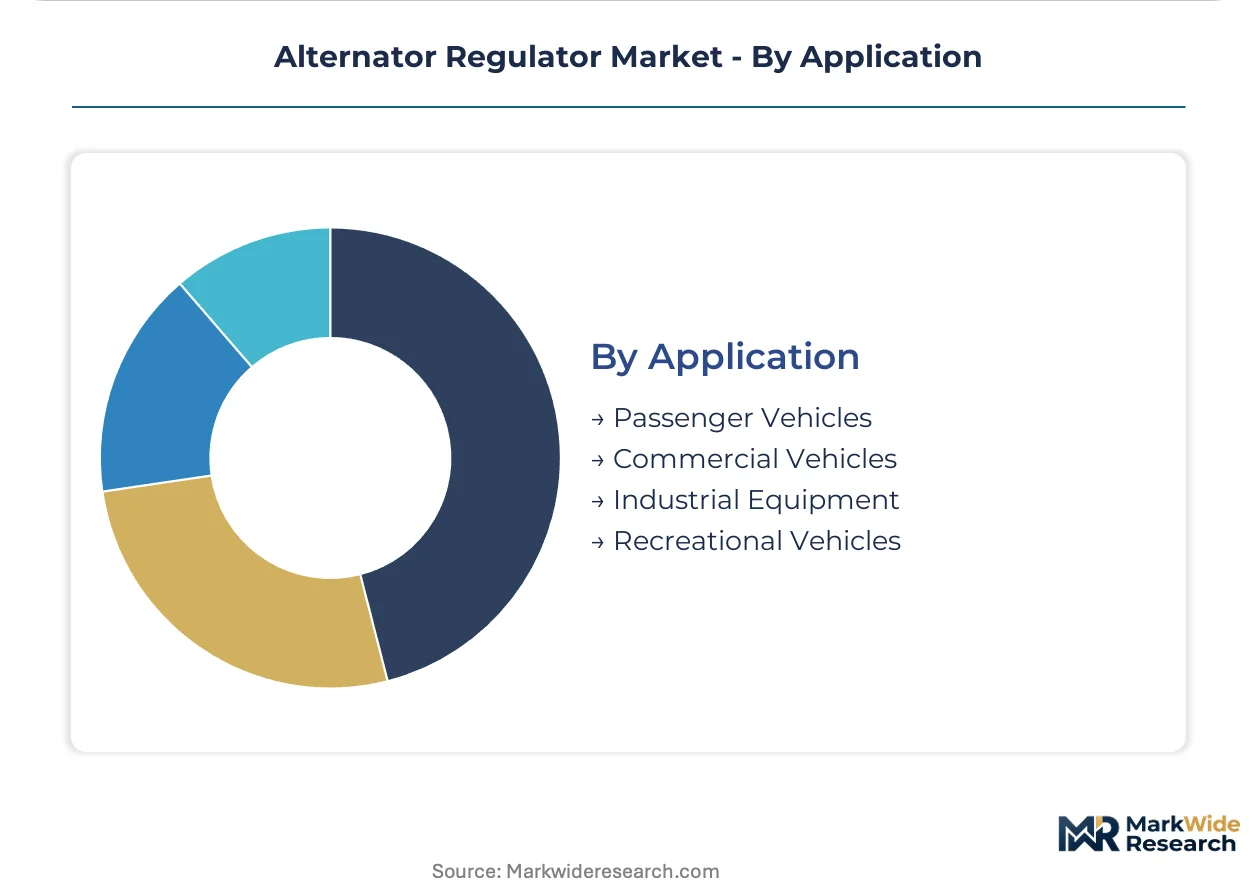
Application:
Volume concentration and margin structure diverge across mobility segments, with duty cycle intensity shaping durability specifications.
- Passenger Vehicles:Start-stop system compatibility and regenerative braking integration drive microcontroller-based regulator adoption. Germany's KBA type approval process validates fuel economy contribution data for each design variant.
- Commercial Vehicles:Fleet telematics mandate CAN-enabled digital regulators for real-time battery health monitoring. PACCAR and Daimler Truck negotiate multi-year supply agreements with documented efficiency deltas.
- Industrial Equipment:Extended temperature operation and vibration resistance specifications exceed automotive grades. Procurement concentrates through original equipment manufacturers with captive alternator production.
- Recreational Vehicles:Dual-battery system compatibility and solar charging integration create specialized voltage regulation requirements. Aftermarket retrofit demand flows through RV service centers and direct-to-consumer channels.
Passenger vehicles anchor production volume. Commercial vehicles concentrate margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes alternator regulators through precision-engineered OEM supply chains, while China absorbs volume through domestic vehicle manufacturing scale and the United States channels demand through fleet telematics integration. Brazil and India represent divergent consumption patterns—Brazil through aftermarket persistence of mechanical designs, India through accelerating electronic regulator localization.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify microcontroller-based digital regulators for EU F-Gas Regulation compliance. KBA type approval validates fuel economy contribution data for each design variant before platform integration. The Baden-Württemberg cluster around Bosch anchors European semiconductor-in-house production of automotive-grade voltage control modules.
China
Domestic automakers in Shanghai and Guangzhou procure smart charging algorithms under MIIT efficiency mandates for internal combustion vehicles. GB standards for vehicle electrical subsystems constrain import market access, favoring local suppliers with certified designs. The Yangtze River Delta manufacturing belt concentrates alternator production for BYD, Geely, and SAIC Motor supply chains.
United States
Commercial fleet operators in Michigan and Texas mandate CAN bus-enabled regulators for real-time battery health monitoring. EPA fuel economy standards enforce alternator load cycle specifications that reduce parasitic engine losses. Detroit's tier-1 supplier corridor feeds integrated alternator-regulator-battery system contracts with Stellantis and Ford.
Brazil
Heavy-duty commercial fleets in São Paulo state continue mechanical regulator procurement where simplicity outweighs efficiency mandates. ANVISA-aligned vehicle safety standards permit electromechanical designs for certain truck applications. The ABC Paulista industrial zone maintains aftermarket distribution channels serving vintage vehicle restoration demand.
India
Maruti Suzuki and Tata Motors suppliers in Haryana and Maharashtra accelerate electronic regulator assembly under the PLI scheme for auto components. CEA electrical safety regulations shape import substitution patterns for voltage control subsystems. The Chennai-Bangalore corridor hosts emerging foundry partnerships for automotive-grade microcontroller sourcing.
Alternator Regulator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in alternator regulator supply. Tier-1 suppliers with captive semiconductor fabrication or long-term foundry partnerships capture procurement volume from smaller competitors lacking backward integration. Three archetypes dominate: diversified automotive electronics conglomerates with in-house chip design, alternator manufacturers with captive regulator production, and aftermarket specialists with cost-optimized electronic replacements. Consolidation pressures favor M&A activity among mid-tier suppliers, while technology licensing agreements proliferate for ISO 26262 functional safety certification.
Among the named players, Bosch and Denso exemplify the integrated conglomerate archetype with semiconductor capabilities and OEM captive relationships. AS-PL represents the aftermarket specialist tier competing through cost-optimized electronic replacements. Remy and Hitachi occupy positions within the alternator manufacturer segment with historical voltage control integration. These company structures illustrate how supply chain positioning—ranging from in-house wafer supply to distributor-mediated sales—determines competitive boundaries across regulatory compliance tiers.
| Leading Market Players |
|---|
| Remy |
| AS-PL |
| Bosch |
| Marathon Electric |
| Hitachi |
| Denso |
| DB Electrical |
| Tuff Stuff |
| ACDelco |
| Others |
Value Network & Pricing Analysis
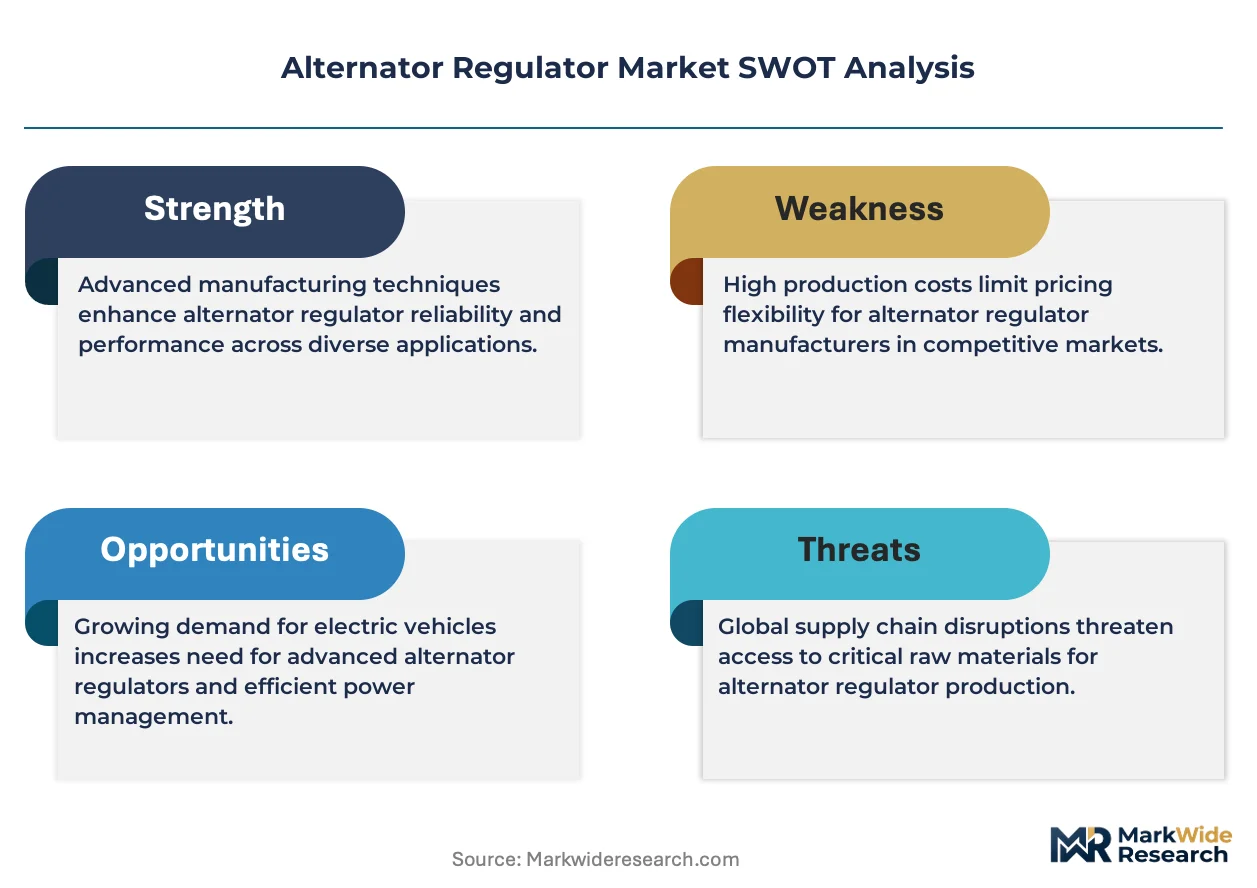
Foundry scale economies in Taiwan and South Korea concentrate automotive-grade microcontroller supply, compressing margin structures for European and North American tier suppliers lacking captive wafer access while establishing price floors for digital regulator variants.
Pricing Analysis
Long-term offtake agreements dominate OEM procurement, with multi-year supply contracts locking volume commitments for microcontroller-based designs. Price differentiation stems from ISO 26262 ASIL-D certification tier and embedded firmware customization depth. Cost compression in the aftermarket channel is intensifying because AS-PL and similar specialists undercut OEM list pricing by 40-60%. Fleet operators exhibit lowest price sensitivity due to telematics-integrated service contracts, while independent repair shops face acute margin pressure.
Supply Chain Analysis
Strait of Malacca transit risk underwrites just-in-time delivery schedules for silicon carbide substrates and automotive-grade MOSFETs. Manufacturing concentrates in Germany, China, and the United States, with foundry partnerships in Taiwan and South Korea feeding wafer supply. Raw material dependencies center on silicon wafers, copper windings, and epoxy molding compounds. Single-source vulnerability in advanced node production creates geographic supply risk. Distribution runs through tier-1 alternator manufacturers and authorized dealer networks serving fleet telematics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microcontroller-based voltage control architectures are in early-cycle expansion as EPA efficiency mandates and EU F-Gas Regulation compliance deadlines accelerate displacement of mechanical designs.
For Market Incumbents: Fortify backward integration into semiconductor supply through long-term foundry partnerships or captive wafer allocation. Prioritize ISO 26262 ASIL-D certification investment to defend against emerging entrants lacking functional safety validation capabilities. Expand embedded firmware engineering headcount to address capability scarcity constraining R&D scaling. For New Entrants and Emerging Players: Lead with cost-optimized electronic regulator replacements targeting Brazil's aftermarket persistence of mechanical designs and India's PLI scheme localization incentives. Marine electrification applications offer penetrable white space with corrosion-resistant packaging specifications. Pursue distributor-mediated sales through West Marine and commercial marine suppliers to bypass OEM direct procurement barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors alternator manufacturers with captive regulator production and semiconductor partnerships. Long-term viability hinges on software-defined charging algorithm capabilities extending from 12V into 48V hybrid architectures. Watch for MIIT efficiency mandate expansion as inflection signal for smart charging algorithm adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership Lock-in | Secures automotive-grade microcontroller allocation from TSMC and Samsung fabs. |
| ISO 26262 ASIL-D Certification | Unlocks OEM direct procurement contracts with Toyota and Volkswagen platforms. |
| Firmware Engineering Acquisition | Addresses embedded software talent scarcity constraining digital regulator development. |
| Marine-Specific Product Line | Captures premium positioning through IEC 60945 salt-spray-resistant packaging. |
| India PLI Manufacturing Footprint | Establishes localized assembly serving Maruti Suzuki and Tata Motors supply chains. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and tier-1 supplier procurement data anchors the qualitative findings. Primary interviews with alternator manufacturer procurement directors, semiconductor foundry account managers, automotive OEM electrical system engineers, and aftermarket distributor category buyers were synthesized with secondary validation. Sources include EPA fuel economy certification databases, KBA type approval records, MIIT GB standard filings, IHS Markit vehicle production data, and SEC 10-K disclosures from listed automotive electronics suppliers. Bottom-up unit volume estimates and top-down market size triangulation were reconciled across modeling approaches.
Sensitivity analysis tested forecast outputs against variable adoption rates for microcontroller-based architectures and divergent foundry capacity expansion scenarios. Segmentation dimensions modeled span product architecture, end-user procurement channel, technology tier, and application duty cycle intensity across the projection horizon. CAGRs were derived from regression analysis of historical vehicle production correlations and forward-looking regulatory compliance deadlines. Industry-specific inputs include alternator content per vehicle by propulsion architecture and fleet telematics penetration rates in commercial vehicle segments.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor supply normalization and stable EPA enforcement posture would require recalibration. Forecasts reflect assumptions regarding EU F-Gas Regulation phase-down timelines and China dual carbon goal implementation velocity. Practitioners should keep alternative scenarios live as silicon carbide MOSFET cost volatility and foundry geographic concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
Canada Electric Space Heater Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
North America Alternating Current (AC) Drive Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Capacitor Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Busbar Protection Market