
 Nuclear Cables Sales Market | 2026-2036
Nuclear Cables Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Cables Sales Market Insights
European cable manufacturers is expanding production capacity for nuclear-qualified safety cables to serve reactor upgrade cycles across France and the United Kingdom. Nexans leverages its vertically integrated compound formulation capabilities to secure long-term supply agreements with EDF and Orano. Prysmian Group sustains competitive positioning through specialized manufacturing of low-smoke zero-halogen jackets for containment-area installations. Sumitomo Electric Industries anchors its presence in the Japanese nuclear restart program with domestically certified radiation-resistant product lines.
Nuclear cables are electrically insulated conductors engineered to maintain signal integrity and power transmission under extreme thermal, radiation, and mechanical stress conditions, typically employing cross-linked polyethylene or ethylene-propylene rubber insulation rated for 60-year operational lifespans. These cables serve critical functions in reactor control, safety system actuation, and containment isolation where failure modes must meet single-failure-proof design criteria. Copper cables occupy the largest revenue share due to established qualification databases and broad regulatory acceptance across operating fleets. Radiation-resistant technology commands premium positioning as utilities prioritize cable replacement in aging pressurized water reactors and boiling water reactors. Safety systems application represents the fastest-growing demand pool driven by regulatory mandates for diversified redundancy in digital instrumentation and control architectures.
The International Electrotechnical Commission's IEC 60780 and IEEE 383 standards govern qualification testing protocols that determine market access for cable suppliers serving Western reactor designs. The US Nuclear Regulatory Commission enforces 10 CFR 50 Appendix B quality assurance requirements that shape procurement specifications and vendor qualification timelines for American utilities. China's National Nuclear Safety Administration implements GB standards that parallel IEC frameworks while adding localization requirements for domestically deployed reactor technologies. Stakeholders must monitor evolving regulatory divergence between Western and Chinese qualification regimes as export-oriented vendors face dual-certification cost pressures.
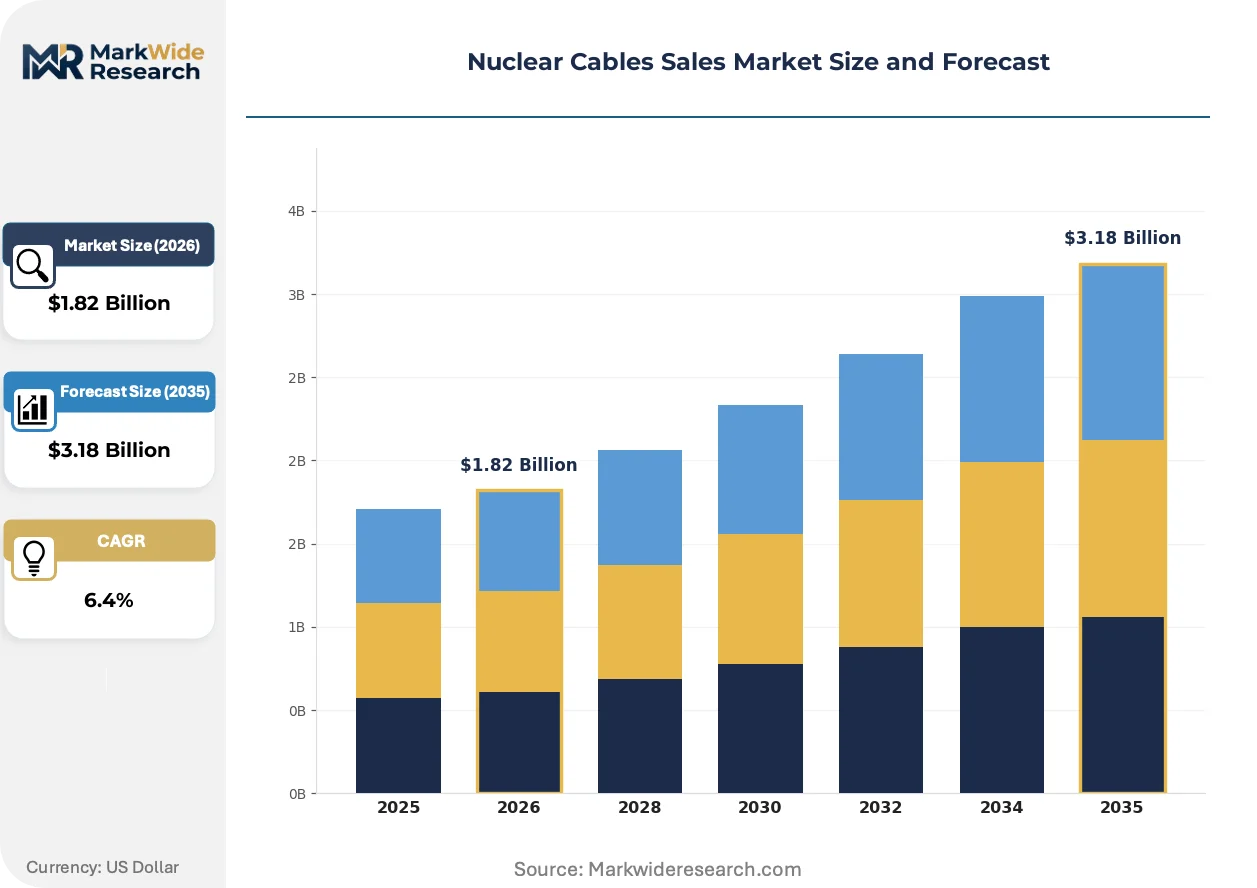
Market Dynamics
Reactor fleet modernization programs across established nuclear economies are accelerating cable replacement cycles, while new build programs in Asia-Pacific are compressing supplier qualification timelines and reshaping procurement concentration.
Growth Catalysts
- GB Standards Localization:China's National Nuclear Safety Administration mandates domestic certification for reactor projects, creating captive demand for locally qualified cable suppliers serving Hualong One deployments.
- Control System Digitalization:Utilities are replacing analog instrumentation with distributed digital architectures, requiring new cable specifications for electromagnetic compatibility and signal integrity in reactor protection systems.
- France:EDF's Grand Carénage reactor life extension program is driving systematic cable replacement in 56 operating units, with safety system upgrades prioritized under ASN oversight.
Market Restraints
- Copper Price Volatility:Raw material cost swings in copper cathode markets compress cable manufacturer margins and complicate long-term fixed-price contracting with utility procurement teams.
- Qualification Database Concentration:Established suppliers in France and Japan hold proprietary 60-year aging test data that new entrants cannot replicate, creating insurmountable barriers to safety system market entry.
- IEC 60780 Revision Lag:Pending updates to international qualification standards create procurement uncertainty, with utilities deferring specification finalization until test protocol harmonization is resolved.
Strategic Opportunities
- Small Modular Reactor Cabling:NuScale and Rolls-Royce SMR designs require compact, flexible cable configurations for factory fabrication and modular transport, opening specifications unconstrained by legacy fleet databases.
- United Kingdom:Sizewell C and prospective additional EPR projects represent greenfield procurement without incumbent supplier lock-in, favoring vendors with fresh qualification investment capacity.
- Polymer Nanocomposite Insulation:Integration of radiation-resistant nanoparticles with cross-linked polyethylene is enabling 80-year design life claims that differentiate replacement cable offerings in aging PWR markets.
Industry Challenges
- Radiation Test Engineer Scarcity:Specialized expertise in cobalt-60 accelerated aging protocols and dose-rate effect modeling is concentrated among retiring specialists at national laboratories in France and the United States.
- Dual-Certification Burden:Suppliers serving both Western and Chinese reactor exports must maintain parallel qualification systems under IEEE 383 and GB standards, doubling documentation and audit compliance costs.
- Legacy System Integration:Digital I&C retrofits in 1970s-era BWRs require cable solutions bridging incompatible connector standards and grounding architectures without triggering full system recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Cables Sales Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Cables, Fiber Optic Cables, Superconducting Cables, Specialty Cables End User: Nuclear Power Plants, Research Facilities, Medical Imaging, Government Agencies Application: Control Systems, Instrumentation, Safety Systems, Communication Systems Technology: High Temperature, Radiation Resistant, Voltage Regulation, Signal Integrity |
| Companies Covered | Nexans, Prysmian Group, General Cable, Sumitomo Electric Industries, RSCC Wire & Cable, Habia Cable, Kabelwerk Eupen, Anhui Cable, NKT AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Cables Sales Market Trends and Innovations
Advanced manufacturing methods and qualification protocol evolution are compressing cable development cycles while extending operational life claims. Material science breakthroughs and procurement model experimentation are redrawing competitive boundaries between established and emerging suppliers.
Silicone-based composite insulation systems are decentralizing the historical dominance of ethylene-propylene rubber in containment-area applications. Japanese utilities operating restarted BWR units are specifying these materials for their superior steam resistance and reduced thermal aging degradation. The shift is compressing qualification timelines for alternative polymer formulations and enabling new compound suppliers to penetrate safety-class markets previously controlled by incumbent cable manufacturers with decades of EP rubber test data.
REACH regulation amendments targeting persistent organic pollutants are restricting legacy flame-retardant additives in cable jacket compounds across European reactor projects. Compound formulators must reformulate halogen-free systems using phosphorus-nitrogen synergists that maintain low-smoke performance under LOCA conditions. French cable suppliers serving EDF's upgrade program are absorbing reformulation costs while awaiting formal exemption clarity from ECHA, with specification uncertainty delaying procurement awards for containment building projects.
Long-term service agreements are displacing transactional cable procurement for reactor life extension programs. US utilities under NRC license renewal pathways are contracting integrated cable replacement and condition monitoring packages spanning 20-year operational periods. Duke Energy and Dominion Energy have structured performance-based contracts with suppliers assuming responsibility for thermal-radiation aging surveillance, transferring technical risk from utility engineering departments to vendor quality assurance organizations.
Nuclear Cables Sales Market Segmentation
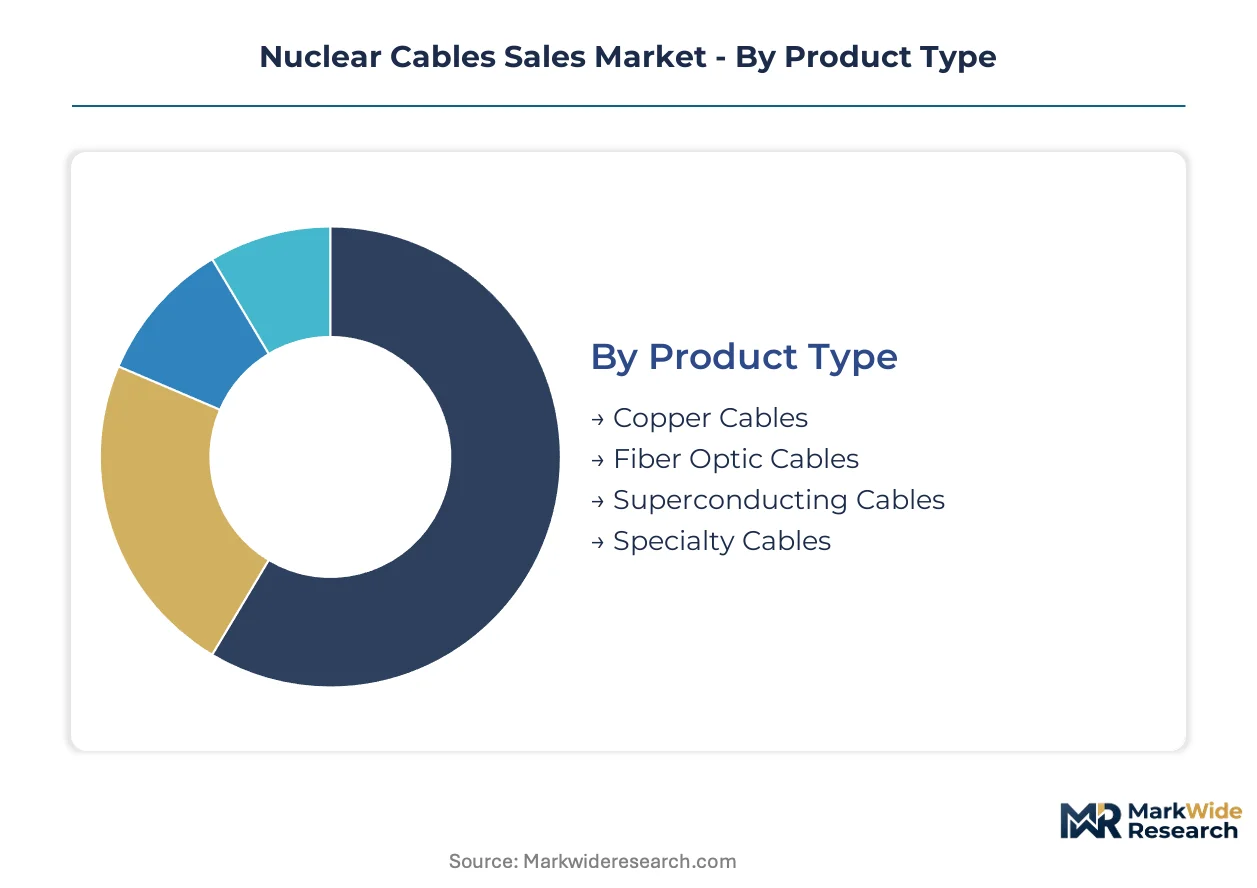
Nuclear cable procurement specifications diverge sharply across reactor systems, with qualification protocols and radiation exposure profiles dictating material selection and manufacturing standards. Segment boundaries in this market reflect regulatory certification requirements rather than interchangeable commodity logic.
Product Type:
Standardization dominates copper and fiber optic categories, while specialty cables demand bespoke compound formulation and accelerated aging test programs.
- Copper Cables:Cross-linked polyethylene or ethylene-propylene rubber insulation systems deliver power transmission and signal integrity across reactor control and safety circuits. EDF's Grand Carénage program in France and China's Hualong One deployments consume the largest procurement volumes, with 60-year operational life requirements locking in established qualification databases.
- Fiber Optic Cables:Silica-core designs with radiation-hardened coatings transmit data across digital instrumentation and control architectures without electromagnetic interference susceptibility. Japanese BWR restart programs and US license renewal pathways are accelerating replacement of legacy copper instrumentation with fiber-based distributed sensing networks.
- Superconducting Cables:Niobium-titanium or rare-earth barium copper oxide conductors operating at cryogenic temperatures enable compact high-current feeds for experimental fusion reactors.
- Specialty Cables:Custom-configured coaxial, triaxial, or multi-conductor assemblies address unique routing constraints in containment penetrations and hot cells.
Most installed capacity flows through Copper Cables. Expansion is steepest in Fiber Optic Cables.
End User:
Procurement scale and qualification rigor separate utility reactor operators from research and institutional buyers.
- Nuclear Power Plants:Operating utilities under NRC, ASN, or NNSA jurisdiction enforce 10 CFR 50 Appendix B, RCC-E, or GB 50572 quality assurance systems. EDF, Duke Energy, and China National Nuclear Power dominate cable procurement through 20-year life extension and new build programs.
- Research Facilities:CERN, Oak Ridge National Laboratory, and ITER Organization purchase specialized cables for particle accelerator beam lines and experimental reactor test stands with dose-rate specifications exceeding commercial power plant requirements.
- Medical Imaging:Cyclotron and synchrotron radiation therapy centers require compact, shielded cable assemblies for isotope production and proton beam delivery systems.
- Government Agencies:Naval reactor programs and weapons complex facilities procure to military specifications with enhanced security clearance and traceability protocols.
Procurement volume concentrates in Nuclear Power Plants. Research Facilities are gaining share fastest.
Application:
Functional criticality determines cable classification, with safety-related systems subject to single-failure-proof design criteria and non-safety systems under standard industrial specifications.
- Control Systems:Reactor protection system cables must maintain signal integrity through design basis accident conditions including loss-of-coolant accidents and seismic events. Digital I&C retrofits in 1970s-era US and Japanese BWRs are compressing procurement timelines for electromagnetic-compatible cable configurations.
- Safety Systems:Emergency core cooling, containment isolation, and auxiliary feedwater actuation circuits employ safety-class cables qualified to IEEE 383 or IEC 60780 with 60-year thermal-radiation aging databases. ASN and NRC mandates for diversified redundancy are expanding cable counts per reactor.
- Instrumentation:Neutron flux monitoring, process variable sensing, and radiation monitoring cables operate in high-radiation zones with mineral-insulated or organic insulation systems.
- Communication Systems:Plant-wide networking and emergency response coordination cables fall under commercial telecommunications standards with supplemental fire resistance requirements.
Safety Systems command the highest unit pricing. Control Systems are expanding most quickly.
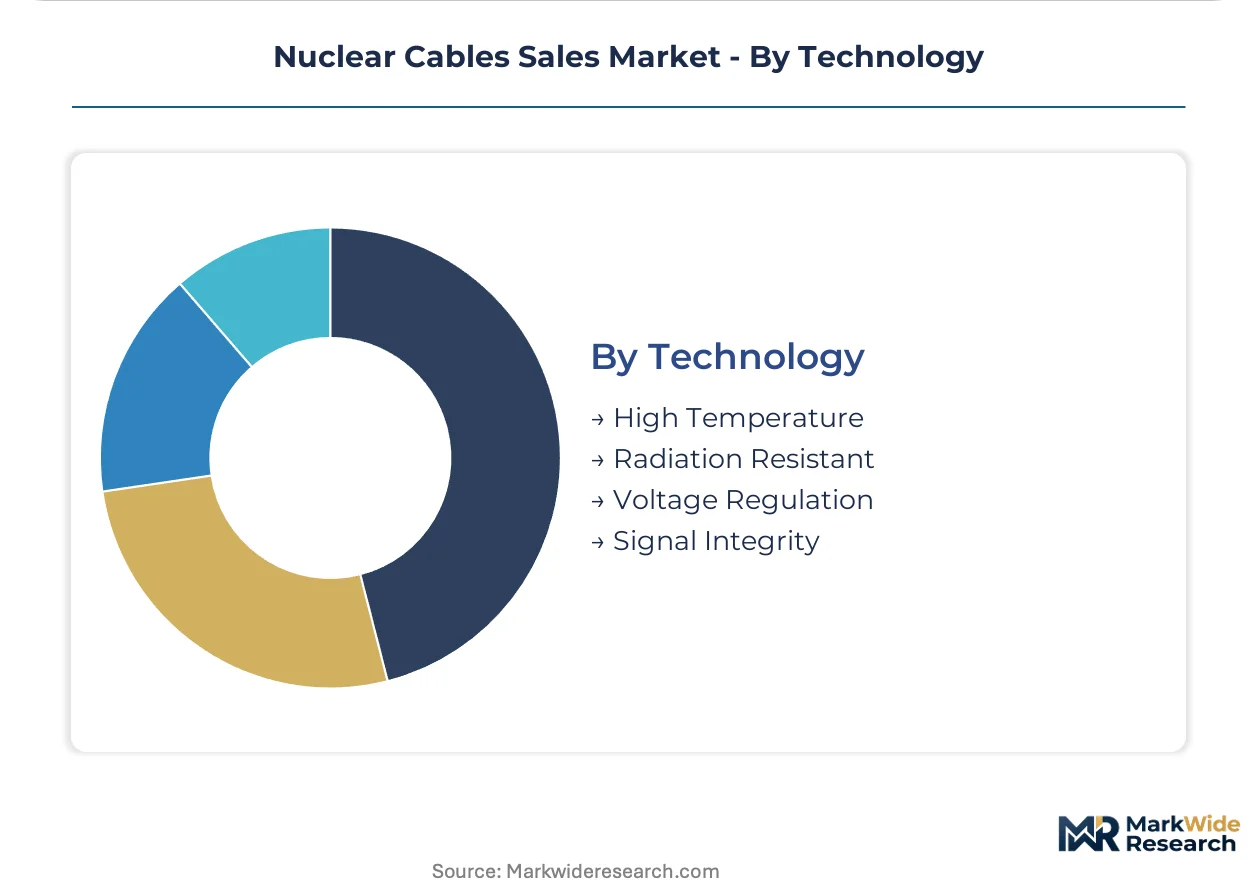
Technology:
Performance claims differentiate supplier offerings, with radiation resistance and signal integrity commanding qualification investment premiums.
- Radiation Resistant:Cross-linked polyethylene and ethylene-propylene rubber compounds stabilized with antioxidant packages maintain mechanical properties through 100-200 Mrad accumulated doses. Incumbent French and Japanese suppliers hold proprietary 60-year aging data that new entrants cannot replicate.
- High Temperature:Silicone-based composite insulation systems rated for 180°C continuous operation are displacing legacy materials in Japanese BWR containment areas due to superior steam resistance.
- Signal Integrity:Shielded twisted-pair and triaxial geometries with controlled impedance specifications address electromagnetic compatibility requirements in digital I&C architectures.
- Voltage Regulation:Medium-voltage distribution cables with stress-grading layers manage electric field distribution across insulation systems in auxiliary power networks.
Radiation Resistant technology anchors supplier market position. Signal Integrity specifications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling cable production toward jurisdictions with streamlined qualification protocols, as dual-certification burdens under IEEE 383 and GB standards reshape supplier location decisions.
United States
Duke Energy and Dominion Energy anchor cable procurement through 20-year license renewal pathways under NRC oversight. The NRC enforces 10 CFR 50 Appendix B quality assurance requirements that compress vendor qualification timelines. Charlotte, North Carolina and Richmond, Virginia clusters concentrate utility engineering headquarters where integrated cable replacement contracts are being structured.
France
EDF's Grand Carénage reactor life extension program drives systematic cable replacement across 56 operating units. ASN oversight mandates diversified redundancy in safety system architectures, expanding cable counts per reactor. Lyon and Le Havre industrial corridors host compound formulation facilities serving containment-area installations with low-smoke zero-halogen specifications.
China
Hualong One deployments under CNNC and CGN procurement programs create captive demand for GB 50572 certified cable suppliers. The National Nuclear Safety Administration mandates domestic certification parallel to IEC frameworks. Shanghai and Sichuan manufacturing bases concentrate localization-compliant production for reactor export projects.
Japan
Restarted BWR units under METI jurisdiction specify silicone-based composite insulation for superior steam resistance in containment areas. JIS standards govern qualification alongside IEC 60780 alignment. Osaka and Nagoya industrial zones anchor domestic radiation-resistant product line manufacturing for post-Fukushima safety upgrades.
United Kingdom
Sizewell C and prospective additional EPR projects represent greenfield procurement without incumbent supplier lock-in. The Office for Nuclear Regulation enforces RCC-E derived standards for safety-class cabling. Somerset and Suffolk development corridors concentrate new build engineering activity favoring vendors with fresh qualification investment capacity.
Nuclear Cables Sales Market Competitive Landscape
French and Japanese producers anchor the established tier with proprietary 60-year aging databases; Chinese specialists hold emerging positions under GB localization mandates. Market structure tilts toward oligopoly in safety-class segments while remaining accessible in non-safety applications. Three archetypes dominate: vertically integrated compound formulators, radiation-test data incumbents, and modular reactor-focused challengers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers position for SMR qualification cycles.
Among European cable manufacturers, Nexans leverages compound formulation capabilities to secure utility relationships, while Prysmian Group occupies a position in specialized containment-area product categories. Sumitomo Electric Industries exemplifies the Asia-Pacific incumbent archetype with domestically certified radiation-resistant lines. These three names represent the geographic split between European qualification-database holders and Japanese restart-program suppliers.
| Leading Market Players |
|---|
| Nexans |
| Prysmian Group |
| General Cable |
| Sumitomo Electric Industries |
| RSCC Wire & Cable |
| Habia Cable |
| Kabelwerk Eupen |
| Anhui Cable |
| NKT AS |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between safety-class and industrial-grade cables creates parallel pricing architectures that track distinct supply chain configurations. Safety-class procurement flows through vertically integrated compound formulators with captive radiation-test facilities, while non-safety cables compete on copper spot pricing through distributor networks.
Pricing Analysis
Distributor margin layers compress most acutely in non-safety cable categories where spot copper pricing and standard industrial specifications dominate transactional procurement. Safety-class cables command project-based long-term contracting with utilities, where 60-year qualification databases and IEEE 383 certification tiers create price differentiation against uncertified alternatives. Cost compression in copper conductor tiers is intensifying because cathode volatility complicates fixed-price agreements with EDF and China National Nuclear Power procurement teams. Research facilities and SMR developers show least price sensitivity, prioritating radiation-test documentation over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with cobalt-60 irradiation facilities concentrated in France and the United States, where accelerated aging protocols require specialized national laboratory infrastructure. Compound formulation draws from Belgium, France, and Japan for radiation-resistant polymer systems, while copper conductor supply rests on Chilean and Chinese smelter output. Tariff exposure runs through cross-border qualification audits under dual IEEE 383 and GB standards regimes. Distribution runs through direct utility contracting for safety-class cables, with industrial-grade products flowing via electrical supply distributors serving maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Nuclear Cables Sales Market compounds steadily through reactor fleet modernization mandates that institutionalize replacement cycles across 60-year asset lifespans.
For Market Incumbents: Lock in long-term service agreements with US utilities under NRC license renewal pathways, transferring thermal-radiation aging surveillance risk to vendor quality organizations. Deepen backward integration into antioxidant compound formulation to defend margin position against copper volatility and REACH-regulated flame-retardant reformulation costs. For New Entrants and Emerging Players: Begin with SMR cabling specifications for NuScale and Rolls-Royce factory-fabrication designs, where legacy qualification database requirements do not constrain market entry. Target UK Sizewell C procurement with fresh GB and RCC-E certification investment, positioning containment-area low-smoke zero-halogen supply as the anchor go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where radiation-test engineer scarcity concentrates proprietary aging data with retiring specialists at French and US national laboratories. Position for 5-to-10 year viability through acquisition of compound formulators with captive cobalt-60 facility access, watching SMR deployment velocity as the inflection signal for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Service Agreement | Duke Energy and Dominion Energy transfer aging surveillance risk to vendors under 20-year performance contracts. |
| Backward Integration into Compound Formulation | Nexans secures EDF supply relationships through captive antioxidant and base polymer production. |
| Dual Certification Investment | Suppliers serving Western and Chinese reactor exports absorb parallel IEEE 383 and GB standards compliance costs. |
| SMR Qualification Cycle Positioning | Rolls-Royce and NuScale designs enable new entrants to bypass legacy 60-year aging database barriers. |
| Polymer Nanocomposite R&D | 80-year design life claims differentiate replacement cable offerings in EDF Grand Carénage aging PWR markets. |
Research Methodology
Direct dialogue with utility procurement managers, cable manufacturer quality assurance directors, nuclear regulatory compliance officers, and compound formulation R&D leads grounded the qualitative assessment. Secondary validation drew from NRC 10 CFR 50 filings, ASN reactor oversight reports, IEC 60780 and IEEE 383 standards documentation, and EDF Grand Carénage procurement disclosures. Bottom-up utility spending analysis and top-down reactor fleet cable density assumptions were triangulated against manufacturer capacity disclosures.
Segment-level value and volume estimates across the projection horizon reflect disaggregation by product type, end user, application, and technology tier. Modeled dimensions included copper versus fiber optic versus specialty cable categories, nuclear power plant versus research facility end-use splits, and radiation-resistant versus high-temperature versus signal integrity technology claims. CAGRs were derived from reactor new build and life extension program timelines, with nuclear capacity addition assumptions and cable replacement cycle frequency as primary forecast inputs.
Several conditions sit outside the modeled scope, including abrupt regulatory divergence between IEEE and GB standards, cobalt-60 facility closures disrupting qualification timelines, and SMR deployment acceleration compressing conventional cable demand. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Air Insulated Switchgear Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Gas Circuit Breaker Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
Train Contactor Market
Electrical Power Equipment
Instrument Transformers Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market