
 Home Inverter Battery Market | 2026-2036
Home Inverter Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Home Inverter Battery Market Insights
Lithium iron phosphate chemistry is rewriting the cost-performance equation for home energy storage. LG Energy Solution leverages its cylindrical cell expertise to anchor premium residential segments in South Korea and North America. Tesla sustains brand pull through integrated Powerwall ecosystems that bundle inverter and battery management. BYD competes on vertical cell-to-system manufacturing that compresses bill-of-material costs for price-sensitive markets.
A home inverter battery stores direct-current electricity for conversion to alternating current during grid outages or peak-rate periods, typically employing electrochemical cells rated between 100Ah and 250Ah with cycle lives exceeding 3,000 deep discharges. Lithium-ion configurations now dominate new installations where energy density and warranty terms outweigh upfront cost premiums. Lead acid retains residual share in rural and budget-tier deployments where capital constraints override lifetime cost calculations. Smart technology integration with hybrid inverters represents the fastest-expanding segment as homeowners seek solar self-consumption optimization and time-of-use arbitrage.
India's BIS certification mandates and CEA grid-interconnection standards shape product eligibility for rooftop solar subsidies, while the EU's F-Gas Regulation and CE marking directives constrain refrigerant-based thermal management in European-bound systems. India's PLI scheme for advanced chemistry cells is forcing import-dependent assemblers to localize cell sourcing or surrender subsidy access. Stakeholders must monitor how evolving battery passport requirements under the EU's CSRD reshape traceability obligations and supplier qualification protocols.
Market Dynamics
Lithium iron phosphate chemistry is compressing total cost of ownership curves while India's PLI scheme for advanced chemistry cells forces assemblers to localize cell sourcing or surrender subsidy access, restructuring competitive positioning across price tiers.
Growth Catalysts
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives are pulling cell production away from import dependency, creating captive supply advantages for certified assemblers in Maharashtra and Gujarat.
- Grid instability in suburban India:Frequent outages across Tamil Nadu's manufacturing corridors are accelerating residential solar-plus-storage procurement as homeowners seek backup autonomy.
- Lithium iron phosphate chemistry:Superior cycle life and thermal stability are displacing lead-acid in new installations where warranty terms outweigh upfront premiums.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings compress assembler margins and complicate long-term pricing contracts with residential distributors.
- Cell supply concentration in East Asia:Dependency on cylindrical and prismatic cell imports from South Korea and China exposes assemblers to logistics bottlenecks and tariff uncertainty.
- Lead-acid residual share:Capital-constrained rural deployments continue selecting flooded batteries despite lifetime cost disadvantages, slowing premium chemistry penetration.
Strategic Opportunities
- Rural electrification gaps in Uttar Pradesh and Bihar:Underpenetrated districts with erratic grid supply present first-mover advantages for pay-as-you-go battery leasing models.
- EU battery passport requirements under CSRD:Traceability mandates are creating qualification barriers that favor vertically integrated assemblers with documented supply chains.
- Hybrid inverter convergence:Integration of MPPT charge controllers with bidirectional power electronics is enabling solar self-consumption optimization and time-of-use arbitrage for residential prosumers.
Industry Challenges
- BIS certification timelines:Bureau of Indian Standards testing backlogs delay product launches by 4-6 months, compressing effective selling seasons before subsidy windows close.
- Integration complexity with legacy lead-acid infrastructure:Retrofit installations require custom charge profile programming and physical form-factor adaptation, inflating deployment costs.
- Field technician skill gaps:Shortage of certified installers for lithium-ion thermal management and battery management system diagnostics limits service network expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Inverter Battery Market |
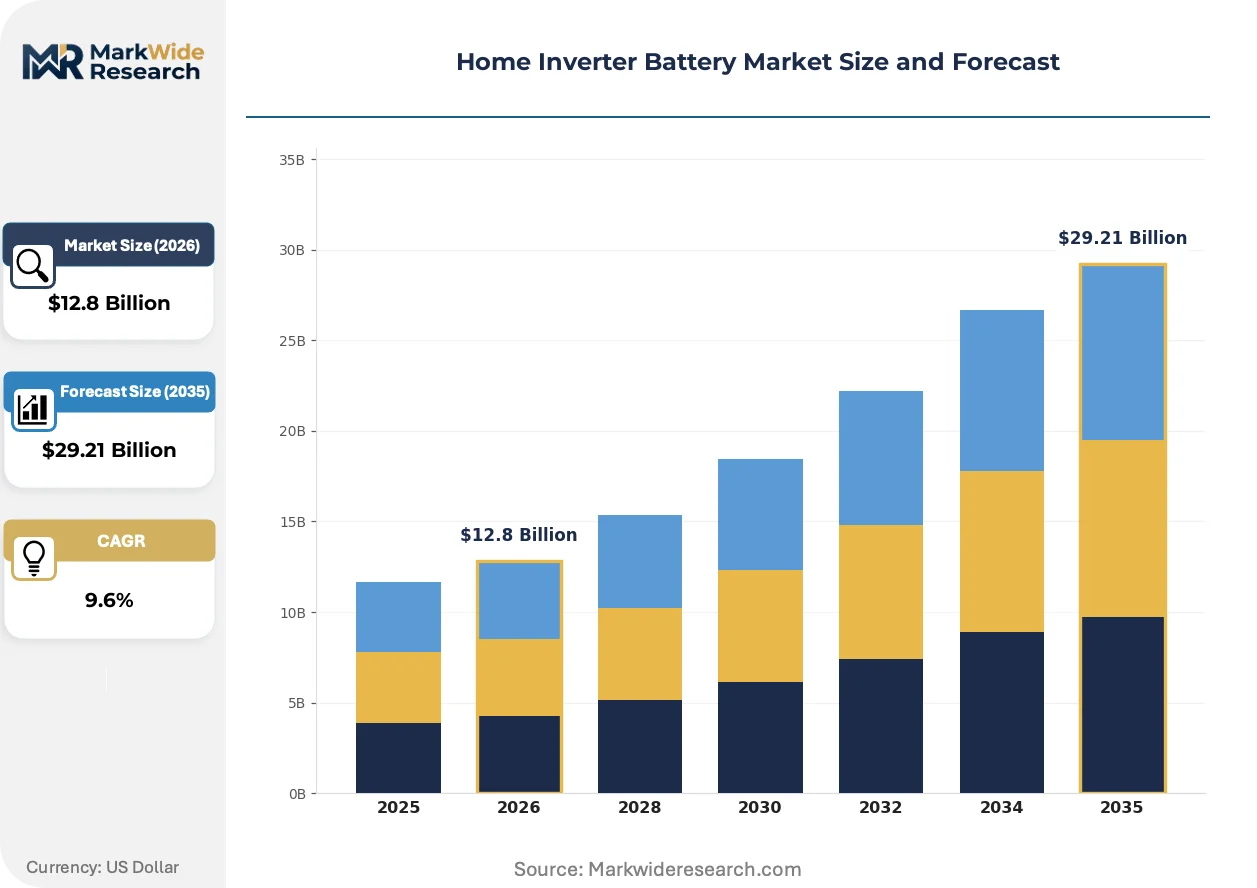
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.21 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-ion, Nickel Cadmium, Gel End User: Residential, Small Business, Large Enterprises, Institutions Capacity: 100Ah, 150Ah, 200Ah, 250Ah Technology: Off-Grid, Hybrid, Smart, Traditional |
| Companies Covered | LG Energy Solution, Deye, Tesla, Siemens, Gronsol, BYD, Growatt, Panasonic, Sungrow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Inverter Battery Market Trends and Innovations
Smart technology integration with hybrid inverters is accelerating as homeowners prioritize solar self-consumption optimization over simple backup functionality, rewiring procurement criteria across distribution channels.
Lithium iron phosphate cells are migrating from premium residential segments in South Korea toward mid-tier deployments in suburban India where total cost of ownership calculations now favor chemistry switchover. Maharashtra's solar rooftop adopters are specifying 48V rack configurations with 10-year warranties, compressing lead-acid's residual addressable market to capital-constrained rural pockets. The technology is migrating from niche premium positioning toward mass-market standard equipment as local assemblers achieve BIS certification for domestically packaged systems.
The EU's F-Gas Regulation is constraining refrigerant-based thermal management in European-bound battery systems, forcing manufacturers toward passive cooling architectures or dielectric fluid alternatives. India's CEA grid-interconnection standards are mandating anti-islanding protection and frequency ride-through capabilities that add 8-12% to inverter-bom costs. Product development teams are responding with modular architectures that segregate power electronics from battery enclosures, enabling localized certification without full system redesign.
Homeowner purchasing patterns are pivoting from dealer-led specification toward direct online research and e-commerce procurement, disintermediating traditional electrical supply houses. Tier-1 cities including Mumbai, Bengaluru, and Delhi are seeing 35-40% of inquiries originate from digital channels before physical showroom visits. This channel rotation is compressing distributor margins and rewarding assemblers with direct-to-consumer logistics capabilities and localized installation partnerships.
Home Inverter Battery Market Segmentation
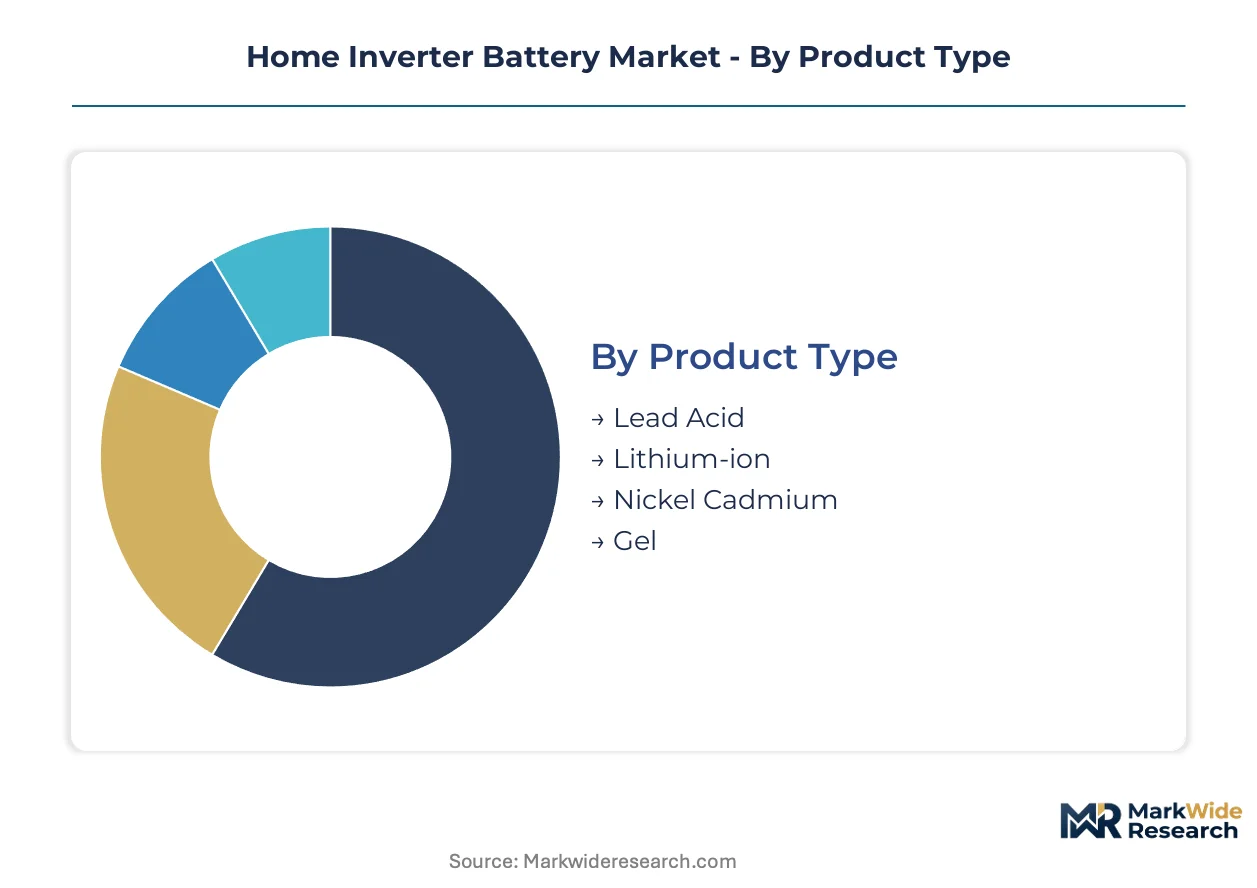
Segmentation in the home inverter battery market reveals divergent service intensity requirements across chemistry types and installation scales. Product architecture, end-use scale, and technology integration levels each dictate distinct warranty terms, replacement cycles, and field support networks that reshape profitability profiles.
Product Type:
After-sales-service intensity varies sharply across chemistries, with lithium-ion systems demanding specialized thermal management diagnostics and lead-acid requiring routine electrolyte maintenance that drives recurring technician visits.
- Lead Acid:Flooded and sealed variants employ sulfuric acid electrolyte with antimony or calcium alloy grids, delivering 300-500 cycle life at 50% depth of discharge. Demand concentrates in rural Uttar Pradesh and Bihar where capital constraints override lifetime cost calculations and local technicians command lower service fees.
- Lithium-ion:Lithium iron phosphate cells achieve 3,000-6,000 cycles with passive or active thermal management, typically packaged in 48V rack configurations with integrated battery management systems. Procurement accelerates across Maharashtra and Gujarat where grid instability and solar rooftop subsidies justify upfront premiums.
- Nickel Cadmium:Sintered plate construction tolerates extreme temperature swings and deep discharge abuse, retaining residual demand in institutional backup applications with harsh ambient conditions.
- Gel:Thixotropic electrolyte immobilization eliminates spillage risk and reduces ventilation requirements, finding niche adoption in enclosed residential installations with space constraints.
Lead acid holds the largest share; momentum sits with lithium-ion.
End User:
Installation scale determines procurement channel structure, with residential buyers favoring dealer networks and institutional purchasers mandating tender-based vendor qualification that extends sales cycles.
- Residential:Single-family and apartment installations typically specify 100Ah-200Ah systems for 2-8 hour backup coverage, with procurement shifting toward e-commerce platforms in Mumbai, Bengaluru, and Delhi.
- Small Business:Retail shops and clinics require 4-12 hour autonomy for refrigeration and point-of-sale continuity, driving demand for modular 48V rack systems with expansion capability.
- Large Enterprises:Manufacturing facilities and data centers deploy megawatt-hour scale battery rooms with centralized monitoring, though this segment lies at the edge of traditional home inverter definitions.
- Institutions:Schools, hospitals, and government offices prioritize diesel-generator hybridization with automatic mains failure switching, subject to CEA grid-interconnection standards for subsidy eligibility.
Residential dominates volume; institutional contracts yield the highest service attach rates.
Capacity:
Capacity selection correlates with solar array sizing under net metering regulations, with 150Ah and 200Ah configurations emerging as the standard pairing for 3-5 kilowatt rooftop installations.
- 100Ah:Compact 12V monobloc designs serve apartment balconies and small shops with sub-2 kilowatt load profiles, dominating entry-level price tiers.
- 150Ah:The workhorse specification for suburban Indian households with 2-3 kilowatt solar arrays, balancing physical footprint against overnight autonomy requirements.
- 200Ah:Tall tubular and lithium rack configurations address premium residential and small commercial loads, climbing fastest as solar self-consumption optimization gains priority over simple backup.
- 250Ah:Industrial-grade tubular plate and prismatic lithium systems serve large villas and small factories with extended discharge requirements.
150Ah anchors current procurement; 200Ah gains share fastest as solar-plus-storage bundling standardizes.
Technology:
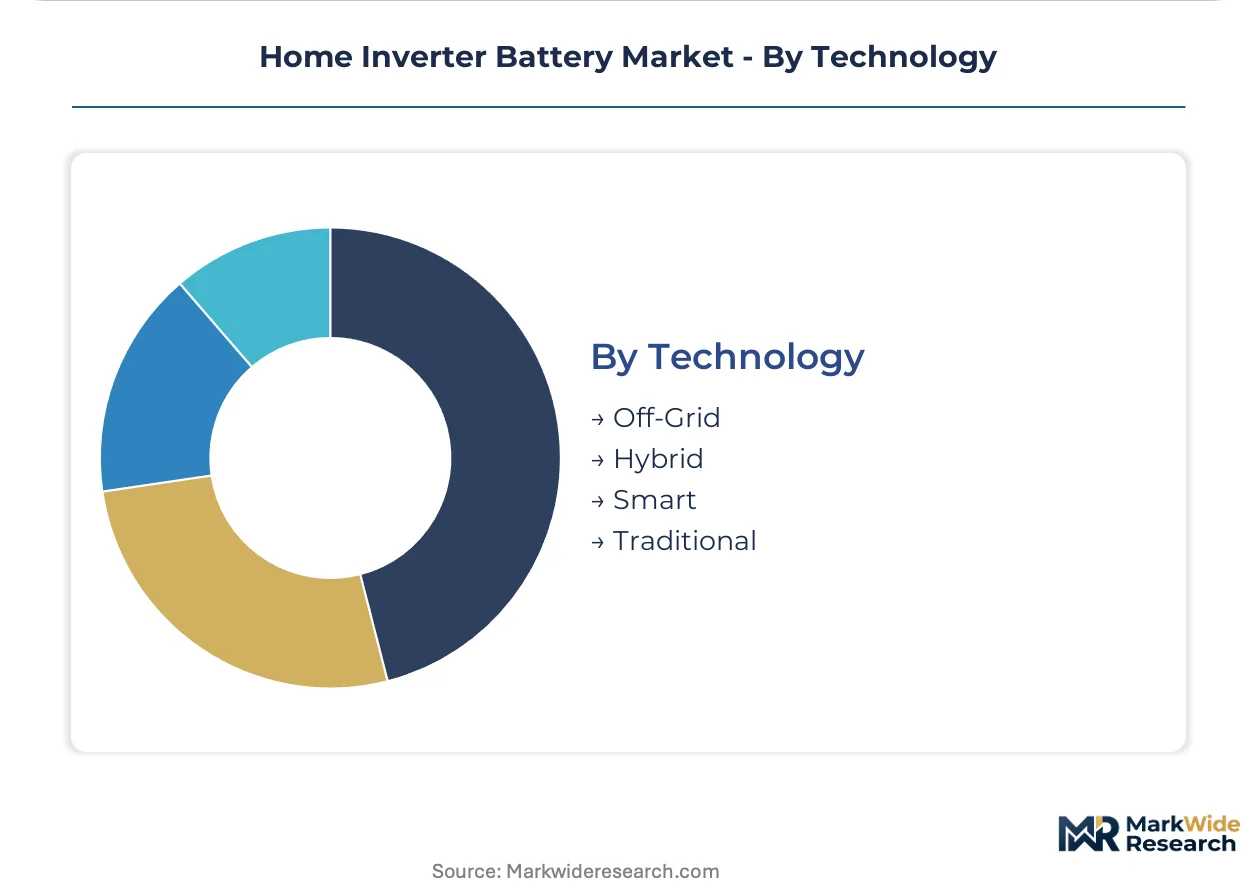
Technology tier determines inverter-battery integration depth, with hybrid and smart systems commanding 25-40% price premiums that compress payback periods through time-of-use arbitrage.
- Off-Grid:Standalone systems with DC coupling and manual transfer switches retain demand in unelectrified hamlets and remote agricultural pumping applications.
- Hybrid:Bidirectional power electronics with MPPT charge controllers enable simultaneous grid export, solar charging, and backup discharge, representing the steepest expansion trajectory as net metering policies stabilize.
- Smart:Cloud-connected battery management with predictive analytics and remote firmware updates commands premium positioning in tech-forward urban markets.
- Traditional:Simple sine-wave inverters with external charge controllers persist in replacement markets and price-sensitive rural deployments.
Traditional systems retain residual volume; hybrid architectures capture the fastest growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are tilting toward domestic cell production across major consuming economies, with localized assembly operations displacing fully imported systems as policy incentives harden.
India
Maharashtra's solar rooftop adopters are driving procurement of 48V lithium-ion rack systems with 10-year warranties as grid instability accelerates backup power investment. The PLI scheme for advanced chemistry cells is forcing assemblers to localize cell sourcing or surrender subsidy access under BIS certification mandates. Gujarat's manufacturing corridors are emerging as captive supply hubs where certified packagers achieve cost parity with imports.
China
Domestic demand for residential energy storage is concentrating in coastal provinces where net metering policies stabilize solar-plus-storage economics. MIIT's dual carbon goals are accelerating backward integration into lithium iron phosphate cell production for price-sensitive export markets. Shenzhen and Dongguan industrial clusters are shipping prismatic cells to Indian and Southeast Asian assemblers under long-term supply agreements.
Germany
Residential prosumers in Bavaria and Baden-Württemberg are specifying hybrid inverter-battery systems to optimize time-of-use arbitrage under volatile electricity tariffs. The EU's F-Gas Regulation and CE marking directives are constraining refrigerant-based thermal management in European-bound systems. Eindhoven-adjacent distribution networks are channeling Chinese and Korean cells into German installer networks with documented supply chains for battery passport compliance.
United States
California's NEM 3.0 transition is compressing solar export compensation rates and redirecting homeowner investment toward self-consumption optimization with battery storage. FERC interconnection standards and state-level fire safety codes are adding compliance costs to residential deployments. Texas's ERCOT grid instability events are driving suburban Dallas and Houston households toward backup autonomy solutions with 4-8 hour discharge capability.
South Korea
Premium residential segments in Seoul Capital Area are specifying cylindrical cell configurations from domestic suppliers for integrated inverter-battery ecosystems. METI-equivalent efficiency standards and KTL safety certifications are creating qualification barriers for non-domestic assemblers. Busan-Ulsan industrial zones are exporting cylindrical cells to North American and European packagers under technology licensing arrangements.
Home Inverter Battery Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: vertically integrated cell-to-system manufacturers, specialized battery packagers with regional certification expertise, and inverter specialists extending into energy storage through partnership models. Strategic archetypes include chemistry-forward cell suppliers, software-integrated system architects, and cost-optimized local assemblers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms seek to secure cell supply and distribution channel access.
Within the integrated-system tier, Tesla and LG Energy Solution exemplify contrasting approaches to residential market capture. BYD occupies a position as a vertically integrated cell-to-system manufacturer with cost-optimized packaging capabilities. Deye and Growatt represent inverter-centric specialists extending into battery integration through module sourcing partnerships. Panasonic anchors a position as a cylindrical cell supplier with legacy brand recognition in consumer electronics channels.
| Leading Market Players |
|---|
| LG Energy Solution |
| Deye |
| Tesla |
| Siemens |
| Gronsol |
| BYD |
| Growatt |
| Panasonic |
| Sungrow |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate price volatility compresses assembler margins and determines both pricing tier spreads and supply chain shape across import-dependent markets and localized production zones.
Pricing Analysis
The lithium iron phosphate versus lead-acid pricing gap stratifies procurement across residential segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under BIS mandates and after-sales service bundling. Pricing pressure stems from raw material cost swings in lithium carbonate contracts. Rural Uttar Pradesh and Bihar households exhibit highest price sensitivity, while Maharashtra solar rooftop adopters prioritize warranty terms over upfront premiums.
Supply Chain Analysis
Contract manufacturing concentration sits with Shenzhen and Dongguan industrial clusters shipping prismatic cells under long-term supply agreements. Cell production draws from China, South Korea, and Japan, with lithium iron phosphate cathode and electrolyte formulations as critical inputs. Single-source vulnerability from cylindrical cell dependency on Busan-Ulsan zones exposes assemblers to logistics bottlenecks. Distribution runs through dealer networks in tier-2 cities and direct-to-consumer platforms in Mumbai, Bengaluru, and Delhi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's PLI scheme for advanced chemistry cells constitutes a regulatory inflection that will concentrate supply advantage among certified domestic assemblers and compress import-dependent competitors.
For Market Incumbents: Entrench position through backward integration into cell sourcing under PLI certification and expansion of BIS-accredited testing infrastructure to compress product launch timelines. Lithium iron phosphate chemistry migration from premium segments threatens lead-acid residual share. Channel control through localized installation partnerships in Maharashtra and Gujarat secures subsidy-eligible procurement flows. For New Entrants and Emerging Players: Build out pay-as-you-go battery leasing models targeting rural electrification gaps in Uttar Pradesh and Bihar where capital constraints exclude upfront purchase. Underpenetrated districts with erratic grid supply present first-mover advantages. Direct-to-consumer digital acquisition with localized technician certification programs enables bypass of established distributor networks. For Investors and Strategic Acquirers: Regional packagers with BIS certification and captive cell supply agreements under PLI schemes offer acquisition profiles with defensible subsidy access. Long-term viability hinges on chemistry transition completion and grid-interconnection standard compliance. Quarterly review of CEA guideline amendments and lithium carbonate futures curves is advised to detect inflection.| Strategic Initiative | Industry Significance |
|---|---|
| PLI Certification Acquisition | Unlocks subsidy access under India's advanced chemistry cell scheme for Maharashtra and Gujarat assemblers. |
| Hybrid Inverter Integration | Captures solar self-consumption optimization demand through MPPT charge controller bundling. |
| Direct-to-Consumer Platform Launch | Disintermediates traditional electrical supply houses in Mumbai, Bengaluru, and Delhi digital channels. |
| Backward Integration into Cell Sourcing | Reduces exposure to lithium carbonate price volatility and Korean cylindrical cell import dependency. |
| BIS Testing Infrastructure Expansion | Compresses 4-6 month certification backlogs that delay product launches before subsidy windows close. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with battery packagers, inverter specialists, CEA regulatory officers, and residential solar installers; and secondary validation through BIS certification databases, CEA grid-interconnection filings, customs import records, and PLI scheme beneficiary disclosures. Bottom-up unit economics triangulated against top-down market sizing across chemistry types and capacity configurations.
Forecast inputs considered lithium iron phosphate cost curves, solar rooftop subsidy allocation trajectories, and net metering policy stability across state jurisdictions. Segmentation dimensions modeled include chemistry type, capacity tier, technology integration level, and state-level regulatory cluster. CAGRs derived from installed base replacement cycles and new construction penetration rates throughout the forecast period.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated cell-to-system manufacturers would shift outcomes beyond projected bounds. Lithium carbonate price spikes, BIS certification timeline extensions, or PLI scheme eligibility revisions could compress assembler margins and redirect procurement flows. Quarterly review of raw material futures, certification backlog durations, and state subsidy disbursement rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Alkaline Battery Market
Batteries
Primary Lithium Battery Market
Batteries
Nimh Battery Market
Batteries
Nas Battery Market
Batteries
North America Battery Market
Batteries
North America Industrial Battery Market
Batteries
VRLA Batteries Market
Batteries
Nuclear Battery Sales Market
Batteries
Australia Battery Market
Batteries
FORTELION Battery Module Market
Batteries
Vanadium Redox Batteries Market
Batteries
Iron Salt Battery Market
Batteries
Micro Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
America SLI Battery Market
Batteries
Asia-Pacific Consumer Battery Market