
 Utility Poles Market | 2026-2036
Utility Poles Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Poles Market Intelligence
Composite-grade pole specifications is rotating toward the center of procurement decisions as grid operators seek longer asset life and reduced maintenance liability. Valmont Industries Inc. leverages its integrated galvanizing and coating capabilities to dominate steel pole contracts across North American utilities. Stella-Jones Inc. anchors the treated wood segment through controlled forestland holdings and pressure-treatment facilities. Koppers Inc. specializes in preservative chemistry and pole treatment services that sustain its position in replacement cycles.
Utility poles are engineered support structures manufactured from wood, steel, concrete, or composite materials, typically ranging from 30 to 120 feet in height and designed to carry electrical conductors, telecommunications cables, or lighting fixtures. Steel poles undergo hot-dip galvanization to achieve 50-plus-year corrosion resistance, while composite variants incorporate fiberglass reinforcement and UV-stabilized resins for reduced weight and electrical insulation. Application segmentation reveals power distribution as the mature volume base, while telecommunication poles represent the fastest-growing category as 5G small-cell densification drives shorter-height, higher-volume orders. Material-type dynamics show concrete poles retaining share in coastal and hurricane-prone zones for their wind-load performance, though composite poles are capturing margin pools in corrosion-critical environments where lifecycle cost outweighs first cost.
US utilities navigate EPA preservative regulations and OSHA fall-protection standards that dictate treatment chemistry and climbing hardware specifications. India's Central Electricity Authority enforces structural loading codes that favor steel and concrete in cyclone corridors, while the Bureau of Indian Standards certifies wood species and treatment penetration depths. China's Ministry of Ecology and Environment enforces dual carbon targets that restrict creosote use and encourage recycled steel content. Stakeholders must monitor how evolving storm-resilience mandates and right-of-way vegetation rules reshape pole replacement scheduling and material selection across their served territories.
Market Dynamics
Grid operators face a structural pivot as asset lifecycle economics displace upfront capital cost as the primary procurement filter, forcing material selection decisions toward composites and engineered steel that minimize total ownership liability across fifty-year service windows.
Growth Catalysts
- Rural electrification mandates:India's Central Electricity Authority drives pole orders through village connectivity programs that prioritize steel and concrete for cyclone-zone structural integrity.
- Preservative chemistry restrictions:The US EPA's updated creosote and pentachlorophenol regulations accelerate wood-to-composite transitions in environmentally sensitive watersheds.
- 5G small-cell densification:Telecommunications carriers require shorter-height, higher-volume pole configurations that favor fiberglass-reinforced composite manufacturing economics.
Market Restraints
- Steel input volatility:Hot-rolled coil price swings compress margin visibility for galvanized pole fabricators locked into multi-year utility contracts.
- Treatment facility concentration:North American wood pole pressure-treatment capacity clusters in the US Southeast, creating geographic supply risk during storm recovery surges.
- Concrete weight logistics:Transport costs for spun-concrete poles exceed material costs beyond 500-mile radii, limiting competitive reach.
Strategic Opportunities
- Offshore wind interconnection:Coastal transmission corridors in Germany and Denmark demand corrosion-resistant composite structures for subsea cable landings.
- Wildfire-hardening mandates:California's CPUC fire-safety regulations create replacement cycles for non-combustible steel and concrete in high-risk zones.
- Recycled steel content incentives:China's dual carbon goals reward pole fabricators sourcing scrap-based electric arc furnace material.
Industry Challenges
- Climbing technician certification gaps:OSHA fall-protection standards require specialized training for composite pole hardware attachment that utility workforces lack.
- Legacy wood inventory integration:Mixed-material fleets complicate inspection protocols and maintenance scheduling for diversified pole populations.
- Composite end-of-life processing:Fiberglass resin reclamation infrastructure remains undeveloped, creating future waste liability for early composite adopters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Poles Market |
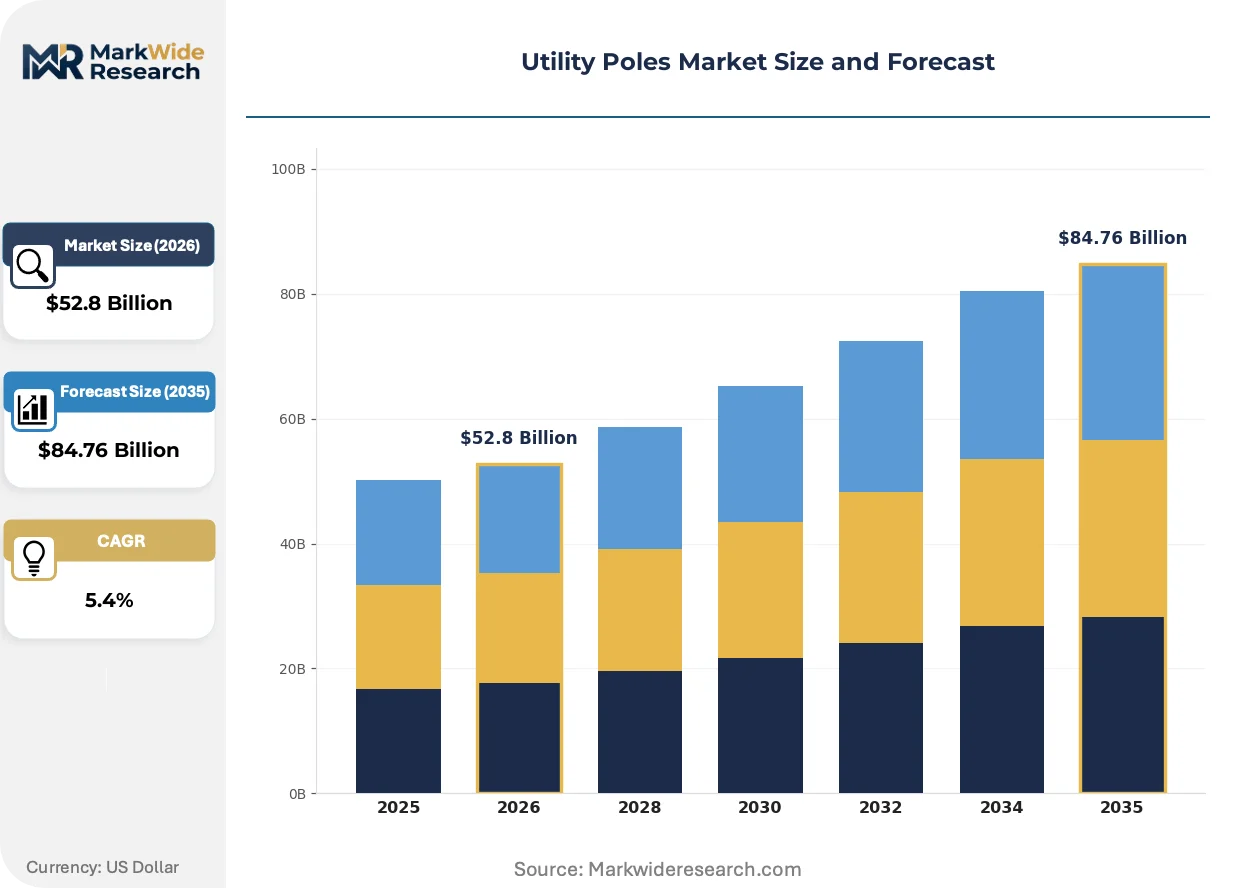
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $84.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Steel, Concrete, Composite Application: Telecommunication, Power Distribution, Street Lighting, Traffic Management Height: Short, Medium, Tall, Extra Tall Installation Type: New Installation, Replacement, Upgrading, Maintenance |
| Companies Covered | RS Technologies Inc., El Sewedy Electric Company, Valmont Industries Inc., Nippon Concrete Industries Co. Ltd., Hill & Smith Holdings Plc, Stella-Jones Inc., Koppers Inc., KEC International, Skipper Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Poles Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry constraints are converging to restructure supplier capabilities and buyer evaluation criteria across transmission and distribution infrastructure.
Pultruded fiberglass composite formulations with UV-stabilized vinyl ester resins is fragmenting traditional material hierarchies in coastal and chemically aggressive environments. Municipal utilities in Florida and the Gulf Coast specify these poles for salt-spray exposure where galvanized steel requires accelerated recoating cycles. The technology is fragmenting procurement patterns by enabling direct-bury installations without concrete foundations, compressing project timelines and labor costs.
REACH restrictions on polycyclic aromatic hydrocarbons in Europe and EPA re-registration reviews in the United States are phasing out legacy wood preservatives. Industrial consequence falls heaviest on railroad and electric utility maintenance programs dependent on creosote-treated crossarms and poles. Nordic utilities respond fastest, specifying thermally modified wood and acetylated alternatives that bypass chemical treatment entirely.
Integrated design-build contracts now bundle pole supply with foundation engineering and installation services, displacing traditional material-only procurement. This model concentrates with investor-owned utilities managing complex urban underground-to-overhead transitions. The shift is most visible in Texas and Arizona, where transmission developers package steel monopole structures with geotechnical work to accelerate interconnection queue positions.
Utility Poles Market Segmentation
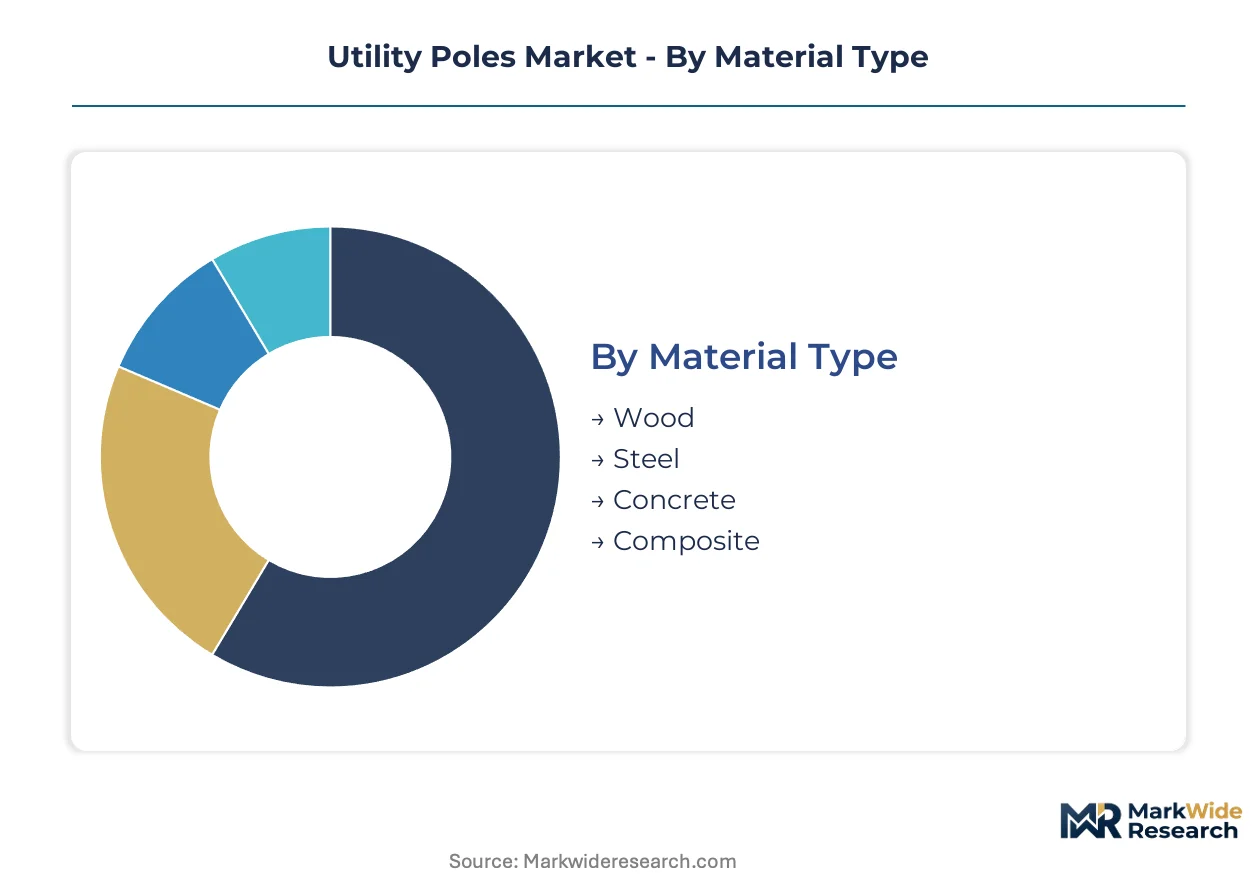
Material selection and application requirements drive fundamentally different procurement patterns across utility pole categories. Each segmentation dimension carries distinct geographic concentration, regulatory exposure, and lifecycle economics that reshape supplier positioning.
Material Type:
Wood poles concentrate in domestic North American replacement cycles, while steel and composite variants increasingly serve export-led infrastructure programs in cyclone corridors and coastal zones.
- Wood:Pressure-treated southern yellow pine and western red cedar dominate legacy distribution networks. US utilities in the Southeast and Midwest source domestically through controlled forestland holdings, though EPA preservative re-registration reviews are narrowing treatment chemistry options and accelerating substitution in watershed-sensitive areas.
- Steel:Hot-dip galvanized tubular and lattice structures anchor transmission corridor expansions. Indian and Chinese grid operators specify these for structural loading compliance in high-wind zones, with fabrication capacity concentrating in integrated mills that control galvanizing chemistry and coating thickness specifications.
- Concrete:Spun-cylindrical and prestressed designs retain share in hurricane-prone coastal utilities from Florida to the Gulf Coast, where mass and wind-load performance outweigh transport cost penalties.
- Composite:Pultruded fiberglass with vinyl ester resins penetrates corrosion-critical environments including salt-spray exposure and chemically aggressive industrial zones.
Wood commands the established base across North American distribution networks. The steepest expansion runs through composite formulations as lifecycle cost analysis displaces first-cost procurement.
Application:
Power distribution absorbs mature volume through regulated replacement cycles, while telecommunications applications scale on carrier-led capital deployment timelines independent of utility rate-base proceedings.
- Telecommunication:5G small-cell densification drives shorter-height, higher-volume pole configurations. US carriers and tower companies source composite and steel alternatives for rapid urban deployment, with attachment agreements and make-ready engineering creating multi-month lead time variability.
- Power Distribution:Investor-owned and municipal utilities manage wood-to-steel transitions through storm-hardening mandates and fire-safety regulations. California's CPUC non-combustibility requirements and Texas reliability standards reshape material selection in high-risk corridors.
- Street Lighting:Municipal procurement concentrates on decorative steel and aluminum structures for urban core beautification programs, with LED retrofit bundling altering foundation and height specifications.
- Traffic Management:Department of transportation specifications favor steel monotube and strain pole designs for signal and camera mounting, with crashworthiness ratings dictating wall thickness and base plate engineering.
Power distribution anchors replacement volume through regulated asset management. Telecommunication poles are climbing the fastest as carrier capital deployment outpaces utility rate-case timelines.
Height:
Medium and tall configurations dominate transmission and distribution procurement with established engineering standards, while short poles scale on telecommunications density economics with compressed customization cycles.
- Short (under 40 feet):5G small-cell and distributed antenna systems specify these heights for urban camouflage and rapid permitting. Carrier procurement favors composite direct-bury designs that eliminate concrete foundations and compress installation timelines.
- Medium (40-65 feet):Standard distribution voltages through 34.5 kV rely on these heights across wood, steel, and composite variants, with class and strength ratings dictating material selection for equivalent loading.
- Tall (65-90 feet):Transmission voltages and heavy angle structures require engineered steel or concrete to manage conductor tension and wind loading, with geotechnical conditions driving foundation type.
- Extra Tall (over 90 feet):River crossings, highway interchanges, and substation entry structures demand custom-engineered steel monopoles or lattice towers with specialized climbing and maintenance access provisions.
Medium-height structures absorb the largest replacement volume across distribution utilities. Short configurations gain share fastest as telecommunications densification outstacks traditional grid expansion.
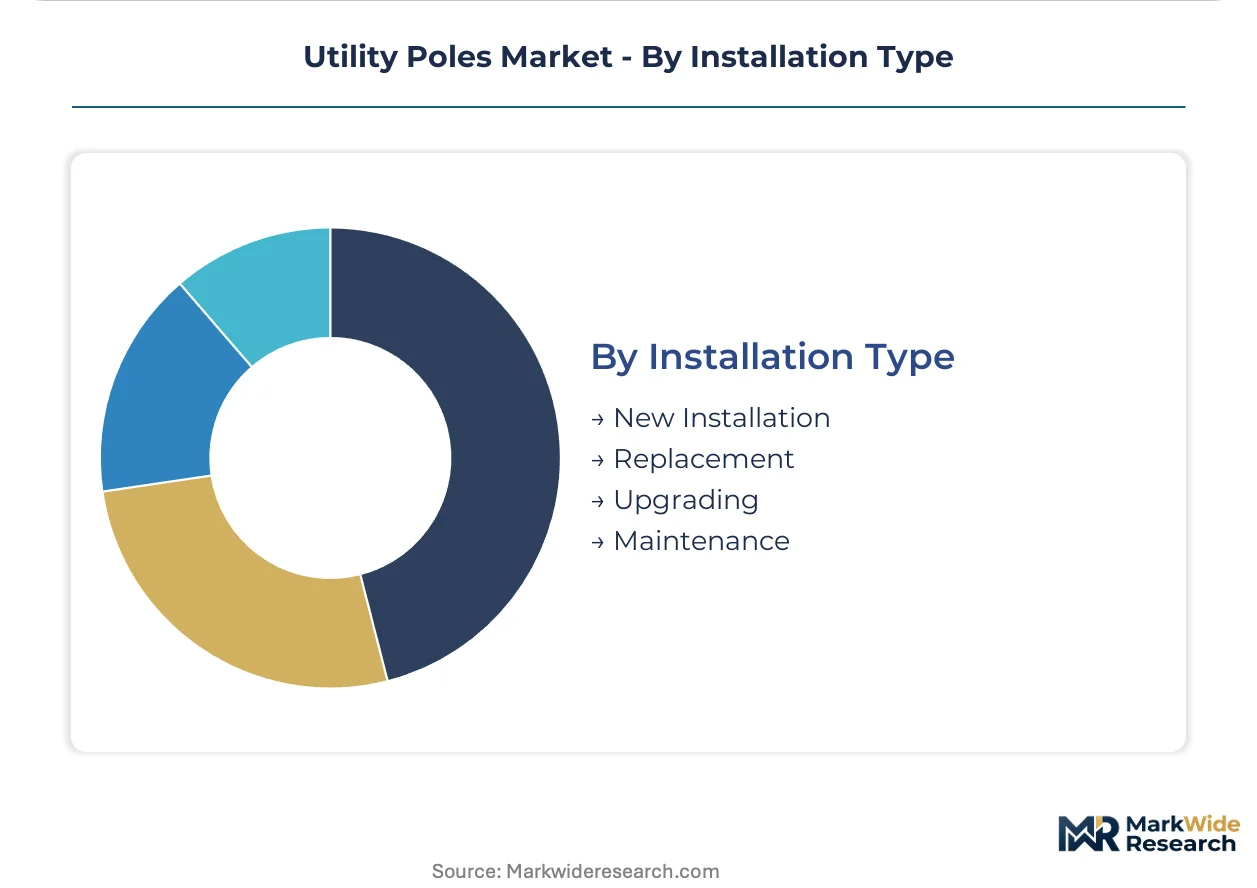
Installation Type:
New installation concentrates in emerging market electrification and greenfield transmission, while replacement and upgrading cycles dominate mature grid infrastructure with regulatory-driven scheduling.
- New Installation:India's rural electrification programs and offshore wind interconnection corridors in Northern Europe drive demand for steel and composite structures with fifty-year design life specifications.
- Replacement:Storm recovery and fire-hardening mandates in California, Texas, and Florida accelerate wood-to-steel and wood-to-concrete transitions with FEMA and state emergency funding altering procurement urgency.
- Upgrading:Reconductoring and voltage conversion projects require stronger pole classes or material substitution to manage heavier conductor bundles and increased loading margins.
- Maintenance:Inspection-triggered replacements and preservative re-treatment decisions sustain wood pole service life in budget-constrained municipal utilities.
Replacement cycles command the largest share of North American utility spending. New installation is expanding most quickly in emerging market electrification and renewable interconnection programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China's rural electrification programs exhibit the highest price elasticity, while US utilities prioritize lifecycle cost over first cost in fire-hardening corridors. European procurement sits between these extremes, balancing REACH compliance premiums against carbon accounting requirements.
United States
Investor-owned utilities in California, Texas, and Florida drive replacement cycles through storm-hardening mandates and wildfire-safety regulations. The EPA's updated creosote restrictions accelerate wood-to-composite transitions in watershed-sensitive areas. Gulf Coast municipal utilities specify pultruded fiberglass for salt-spray exposure, bypassing galvanized steel's accelerated recoating burden.
China
State Grid Corporation and China Southern Power Grid order steel monopoles for ultra-high voltage transmission corridors spanning western provinces to coastal load centers. The Ministry of Ecology and Environment enforces dual carbon targets that restrict creosote use and reward electric arc furnace steel content. Jiangsu and Zhejiang fabrication clusters dominate composite pole exports to Southeast Asian markets.
India
The Central Electricity Authority's rural electrification programs prioritize steel and concrete for cyclone-zone structural integrity across Odisha, Andhra Pradesh, and Tamil Nadu. Bureau of Indian Standards certification mandates specific wood species and treatment penetration depths that limit import sourcing. Gujarat and Maharashtra transmission utilities specify galvanized steel for heavy-angle structures in industrial corridor expansions.
Germany
TenneT and 50Hertz order corrosion-resistant composite structures for offshore wind interconnection corridors in the North Sea and Baltic Sea. REACH restrictions on polycyclic aromatic hydrocarbons phase out creosote-treated wood in railroad and utility maintenance programs. Northern utilities specify thermally modified wood alternatives that bypass chemical treatment entirely.
Brazil
Eletrobras distribution subsidiaries manage wood-to-concrete transitions in Amazon basin humidity zones where preservative leaching accelerates decay. ANVISA regulates preservative chemistry for cross-border pole imports from neighboring Mercosur suppliers. São Paulo and Rio de Janeiro metropolitan utilities specify steel monotube designs for urban underground-to-overhead transitions.
Utility Poles Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated galvanizing and coating specialists capture premium steel pole contracts through chemistry control, while forestland-holding wood treaters defend replacement volume through captive raw material supply. Three archetypes dominate: integrated metal fabricators with in-house galvanizing, controlled-forestland wood treaters, and pultrusion specialists with resin formulation expertise. Competitive moves concentrate on backward integration into raw material supply and design-build contract bundling that displaces material-only procurement.
Among North American integrated fabricators, Valmont Industries Inc. and Stella-Jones Inc. exemplify divergent archetypes—one representing steel galvanization leadership, the other anchored in controlled forestland holdings for pressure-treated wood supply. Koppers Inc. occupies a specialized position in preservative chemistry and treatment services that sustains replacement cycle participation. These three companies illustrate how supplier capabilities align with distinct procurement evaluation criteria across material categories.
| Leading Market Players |
|---|
| RS Technologies Inc. |
| El Sewedy Electric Company |
| Valmont Industries Inc. |
| Nippon Concrete Industries Co. Ltd. |
| Hill & Smith Holdings Plc |
| Stella-Jones Inc. |
| Koppers Inc. |
| KEC International |
| Skipper Limited |
| Others |
Cost & Logistics Intelligence
EPA creosote re-registration reviews and BIS certification mandates gate supplier qualification while simultaneously stratifying price tiers across wood, steel, and composite pole categories. These regulatory filters compress margin pools for non-compliant treaters while rewarding integrated fabricators with chemistry control capabilities.
Pricing Analysis
Extended coating and galvanizing service contracts drive lifetime value for steel pole fabricators, with recurring maintenance revenue offsetting compressed first-sale margins. Three-tier pricing structure across premium, standard, and economy levels reflects galvanizing thickness specifications and wind-load engineering tiers. Cost compression in standard-grade wood poles is intensifying because of preservative chemistry restrictions and Southeast treatment facility concentration. Rural electrification programs in India exhibit highest price elasticity, while US fire-hardening corridors show lowest sensitivity as lifecycle cost displaces first-cost procurement.
Supply Chain Analysis
Strait of Malacca transit underwrites resin and fiberglass feedstock flows to Southeast Asian pultrusion clusters, creating logistics vulnerability for composite pole supply. Manufacturing gravity centers on China, India, and the United States for steel fabrication, with pressure-treatment capacity clustering in the US Southeast. Raw material procurement draws from hot-rolled coil, southern yellow pine timber holdings, and vinyl ester resin formulations. Tariff exposure on Chinese steel inputs threatens margin stability for North American galvanizers. Distribution runs through direct utility contracts and design-build EPC consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The utility poles market is recovering from cyclical lows as grid hardening mandates and rural electrification programs trigger replacement waves. Capital deployment timing aligns with FEMA funding cycles and state regulatory deadlines.
For Market Incumbents: Fortify captive timber positions through controlled forestland acquisitions in the US Southeast, insulating against EPA preservative restrictions that threaten third-party treater viability. Deepen backward integration into galvanizing chemistry control to defend steel pole margins against hot-rolled coil volatility. Prioritize design-build contract bundling to displace material-only procurement in Texas and Arizona transmission corridors. For New Entrants and Emerging Players: Differentiate on pultruded composite formulations for salt-spray environments where recoating burdens disqualify galvanized steel. Target 5G small-cell densification in Florida and Gulf Coast municipalities as the most penetrable white-space segment. Pursue direct-bury installation capabilities that eliminate concrete foundation costs and compress permitting timelines. For Investors and Strategic Acquirers: China's dual carbon goals reshape the acquisition landscape by rewarding electric arc furnace steel content and penalizing creosote-dependent wood treaters. Five-to-ten-year viability favors integrated fabricators with resin formulation expertise or captive galvanizing capacity. Monitor BIS certification backlog as an inflection indicator for Indian market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanizing Chemistry | Valmont Industries leverages in-house coating control to capture premium steel pole contracts from California utilities. |
| Composite Pultrusion Capacity Expansion | RS Technologies scales fiberglass manufacturing to serve Florida salt-spray specifications bypassing steel recoating cycles. |
| Controlled Forestland Acquisition | Stella-Jones anchors pressure-treated wood supply through captive timber holdings in the US Southeast. |
| Design-Build Contract Bundling | Skipper Limited packages pole supply with foundation engineering to accelerate Indian rural electrification timelines. |
| Preservative Chemistry Diversification | Koppers Inc. expands thermally modified wood capabilities to circumvent REACH restrictions on creosote alternatives. |
Research Approach
A standing panel of utility procurement directors, transmission project developers, EPC contractors, and pole treatment facility operators provided ongoing calibration against secondary validation sources. Primary interviews with grid operators in California, Texas, and Florida combined with customs records, EPA enforcement databases, and Bureau of Indian Standards certification filings. Bottom-up pole shipment data triangulated against top-down infrastructure spending forecasts from Central Electricity Authority and State Grid Corporation disclosures.
Consistency checks validated volume and value outputs against external benchmarks including FERC interconnection queue data and carrier capex disclosures for 5G densification programs. The analytical framework modeled material type, application, height class, and installation type across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles and regulatory deadline clustering. Forecast inputs incorporated storm recovery funding authorizations and dual carbon target enforcement intensity in China.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure spending authorization or preservative chemistry approval pathways would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement timing and raw material cost trajectories. Practitioners should keep alternative scenarios live as FEMA funding cycles and REACH restriction phase-ins evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Power Over Ethernet Lighting Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Capacitor Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
HVDC Converter Station Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
Taiwan Electric Power Equipment Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Global Magnetic Circuit Breaker Market