
 Gulf of Mexico Oil and Gas Upstream Market | 2026-2036
Gulf of Mexico Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf of Mexico Oil and Gas Upstream Market Foresight
Independent operators is bifurcating the Gulf of Mexico upstream landscape as multinational corporations retreat from marginal fields and specialty players seize orphaned assets. Shell plc leverages its Appomattox platform infrastructure to dominate the ultra-deepwater corridor, while Chevron Corporation anchors its position through massive capital commitments in the Lower Tertiary trend. Murphy Oil Corporation specializes in tieback developments that exploit existing host facilities, reducing standalone infrastructure costs.
Gulf of Mexico Oil and Gas Upstream encompasses the exploration, drilling, and production of crude oil and natural gas from offshore leases in federal and state waters, typically operating at water depths from 150 meters to over 3,000 meters using subsea wellheads connected to surface platforms or floating production systems. The primary purpose is to extract hydrocarbons for refining into transportation fuels, petrochemical feedstocks, and power generation inputs. Floating Production Systems command the largest capital allocation among technology segments due to their necessity in ultra-deepwater developments where fixed platforms prove uneconomical. Seismic Imaging represents the fastest-evolving capability, with wide-azimuth and full-waveform inversion techniques compressing exploration timelines and improving reservoir characterization accuracy.
The Bureau of Ocean Energy Management governs lease access and decommissioning bonds, while the Bureau of Safety and Environmental Enforcement enforces well control and spill response standards; together these agencies shape project feasibility through permitting timelines and liability thresholds. EPA offshore discharge regulations and Coast Guard safety protocols add compliance layers that favor operators with established environmental management systems. Stakeholders must monitor how evolving carbon intensity benchmarks for imported crude affect Gulf barrel competitiveness against lower-carbon international supply alternatives.
Market Dynamics
The Bureau of Ocean Energy Management's lease sale reforms and expanded use of seismic imaging technologies are compressing exploration timelines and altering field development economics across the ultra-deepwater corridor off Louisiana.
Growth Catalysts
- Wide-azimuth seismic imaging:Full-waveform inversion techniques now compress reservoir characterization timelines from months to weeks, enabling faster drilling decisions in complex salt dome formations.
- Bureau of Ocean Energy Management lease reforms:Streamlined acreage access procedures reduce permitting delays for operators targeting Lower Tertiary and Miocene reservoirs.
- Petrochemical feedstock demand:Gulf Coast crackers and export terminals sustain offtake contracts for associated gas and NGLs from deepwater production streams.
Market Restraints
- Steel and subsea equipment cost volatility:Floating production system hulls and subsea trees face input cost swings tied to global metallurgy supply chains and specialized fabrication yard capacity.
- Deepwater rig supply concentration:Ultra-deepwater capable drillships concentrate among a handful of contractors, creating rate volatility and scheduling bottlenecks for independent operators.
- Decommissioning bond requirements: Bureau of Ocean Energy Management financial assurance rules escalate liability thresholds, tying up capital that could otherwise fund development drilling.
Strategic Opportunities
- Tieback developments to existing host infrastructure:Subsea tiebacks to platforms like Appomattox and Thunder Horse reduce standalone capital requirements for marginal field exploitation.
- Carbon capture integration with offshore facilities:EPA offshore discharge regulations and evolving carbon intensity benchmarks create incentives for reservoir reinjection of CO2 from production streams.
- Lower Tertiary trend extension:Unpenetrated Paleogene reservoirs in Walker Ridge and Keathley Canyon blocks offer untapped resource bases for operators with ultra-deepwater technical capabilities.
Industry Challenges
- Subsea systems engineering talent scarcity:Deepwater completions and flow assurance expertise concentrates among retiring specialists, constraining project execution capacity.
- Integration complexity with legacy platform infrastructure:Brownfield tiebacks require compatibility with aging topsides systems designed decades prior to modern subsea processing standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf of Mexico Oil and Gas Upstream Market |
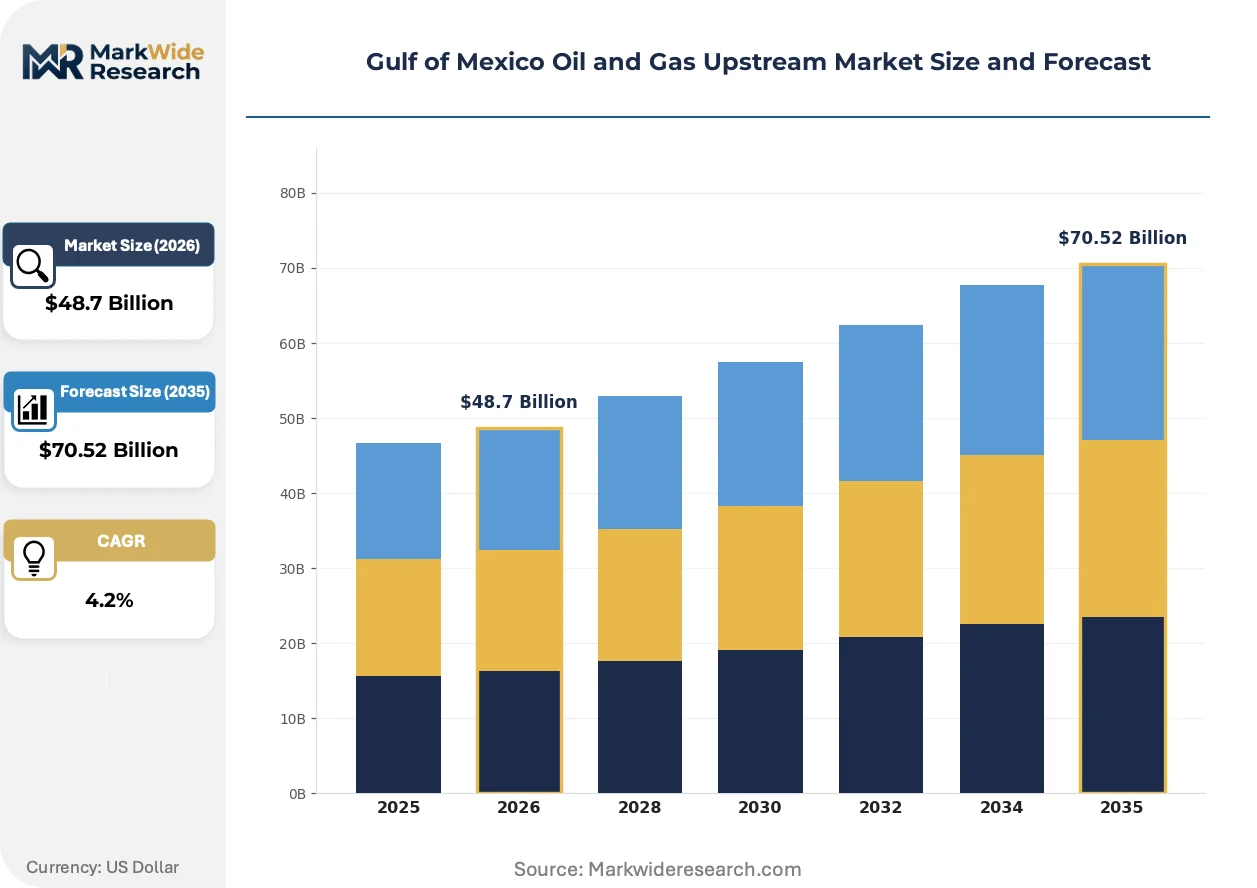
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Subsea Engineering, Production Optimization, Well Completion Technology: Floating Production Systems, Semi-Submersible Rigs, Enhanced Oil Recovery, Seismic Imaging End User: Independent Operators, National Oil Companies, Oilfield Services, Multinational Corporations Component: Offshore Platforms, Pipelines, Umbilicals, Well Heads |
| Companies Covered | Shell plc, Equinor ASA, ExxonMobil Corporation, ConocoPhillips, Eni SpA, Chevron Corporation, TotalEnergies SE, Murphy Oil Corporation, BP plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf of Mexico Oil and Gas Upstream Market Shifts & Advancements
Digital reservoir characterization and autonomous subsea systems are compressing the exploration-to-production cycle while reshaping how operators deploy capital across water depth tiers.
Full-waveform inversion seismic processing is bifurcating the exploration segment into two velocity tiers. Majors with proprietary supercomputing clusters now characterize salt geometries in weeks rather than quarters, while independents without such infrastructure remain dependent on legacy time-domain imaging. This capability gap is concentrating high-confidence prospect generation among capital-intensive players and forcing smaller operators into farm-out arrangements for complex subsalt plays.
Bureau of Safety and Environmental Enforcement well control standards have tightened blowout preventer testing protocols and documentation requirements. Operators must now demonstrate real-time monitoring capabilities and redundant shear ram functionality before receiving drilling permits. Ultra-deepwater developments face the steepest compliance burden, with subsea BOP stacks requiring more frequent surface intervals and third-party verification.
Buyers of Gulf barrels now weight carbon intensity metrics alongside API gravity and sulfur content in term contract negotiations. European refiners and Asian petrochemical complexes increasingly screen crude shipments against evolving Scope 3 disclosure frameworks, compressing price realizations for higher-carbon production streams. This preference shift is most visible in long-term offtake discussions for new Lower Tertiary developments, where reservoir CO2 content and facility electrification plans factor into contract terms.
Gulf of Mexico Oil and Gas Upstream Market Segmentation
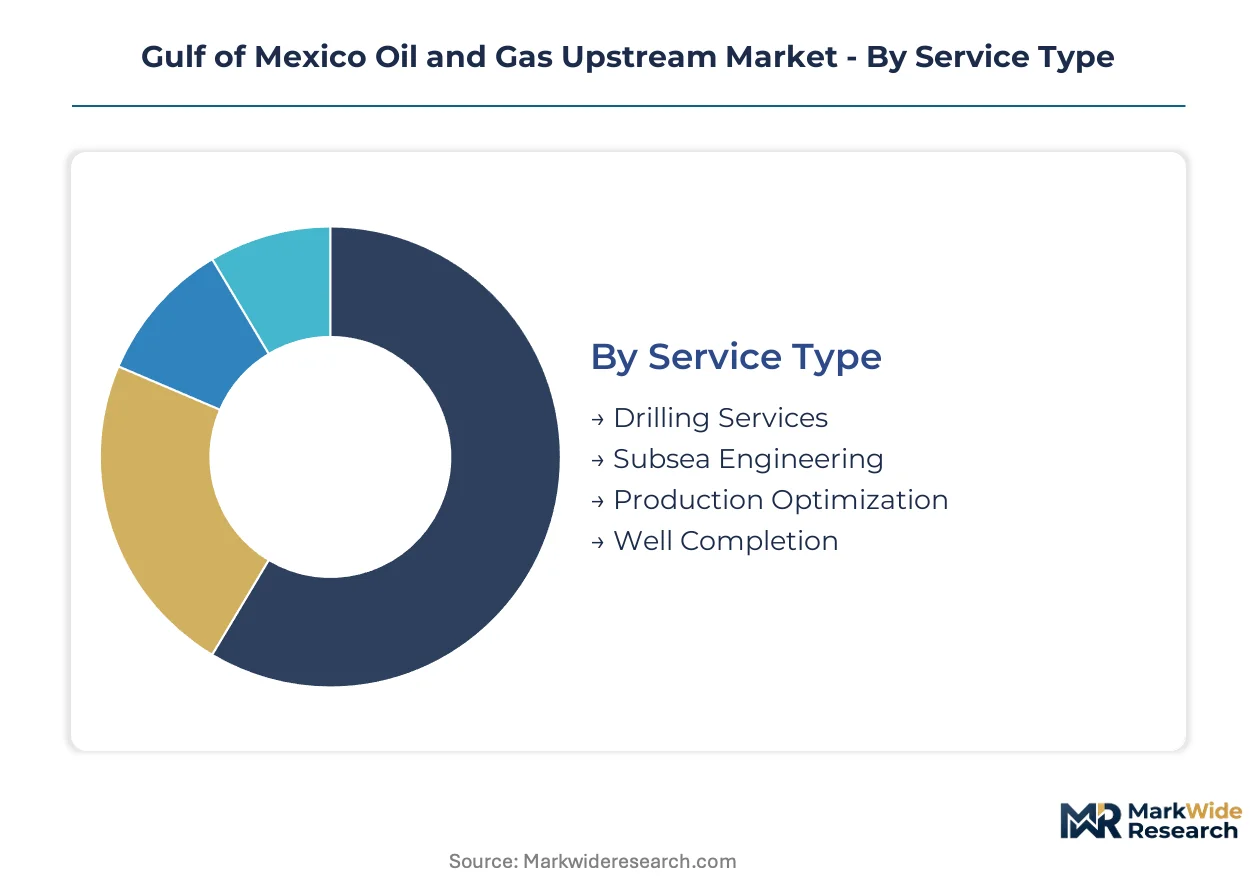
Segmentation in the Gulf of Mexico upstream market reveals how capital allocation and technical specialization concentrate across service tiers, technology platforms, and operator categories. Water depth requirements and infrastructure reuse potential drive divergent procurement patterns across each segment boundary.
Service Type:
Substitution pressure concentrates in commoditized drilling services, where standardized rig specifications compress margins and favor fleet-scale contractors over boutique providers.
- Drilling Services:Contracted drillship and jackup operations span exploratory wildcatting through development drilling, with dayrate volatility tied to ultra-deepwater rig availability. Demand clusters off Louisiana in Lower Tertiary blocks where well depths exceed 30,000 feet measured depth.
- Subsea Engineering:Flow assurance, subsea architecture design, and installation engineering for tieback developments to host platforms. Operators in Walker Ridge and Keathley Canyon drive procurement for complex salt dome completions requiring specialized metallurgy and thermal management.
- Production Optimization:Artificial lift, well intervention, and reservoir management services that extend field plateau rates.
- Well Completion:Sand control, perforating, and intelligent completion installations for high-pressure high-temperature reservoirs.
Drilling Services retains volume leadership; Subsea Engineering holds the steepest expansion curve.
Technology:
Cost tier stratification separates proven shallow-water solutions from capital-intensive ultra-deepwater systems requiring multi-billion dollar platform commitments.
- Floating Production Systems:FPSOs, spars, and tension-leg platforms enabling production in water depths exceeding 1,500 meters where fixed structures prove uneconomical. Shell's Appomattox and Chevron's Anchor developments anchor demand concentration in the Lower Tertiary corridor.
- Seismic Imaging:Wide-azimuth and full-waveform inversion processing that compresses exploration timelines from months to weeks. Full-waveform inversion capabilities bifurcate operators into those with proprietary supercomputing clusters versus dependent independents.
- Semi-Submersible Rigs:Mobile drilling platforms for mid-water depths and harsh environment tolerance.
- Enhanced Oil Recovery:Waterflooding, gas injection, and chemical EOR for mature field redevelopment.
Floating Production Systems commands capital deployment scale; Seismic Imaging delivers the most rapid capability evolution.
End User:
Customer type fragmentation splits procurement between capital-constrained independents seeking tieback economics and majors underwriting greenfield platform investments.
- Multinational Corporations:Integrated majors with balance sheet capacity for standalone ultra-deepwater developments and proprietary seismic processing infrastructure. Chevron and Shell anchor Lower Tertiary production through company-operated host facilities.
- Independent Operators:Specialty players exploiting orphaned assets and marginal fields through subsea tiebacks to existing infrastructure. Murphy Oil and similar firms concentrate acquisitions in Miocene and older producing horizons.
- National Oil Companies:State-backed entities with strategic reserve mandates and long-dated investment horizons.
- Oilfield Services:Schlumberger, Halliburton, and Baker Hughes providing integrated project delivery and technical services.
Multinational Corporations retain volume leadership; Independent Operators are climbing the fastest.
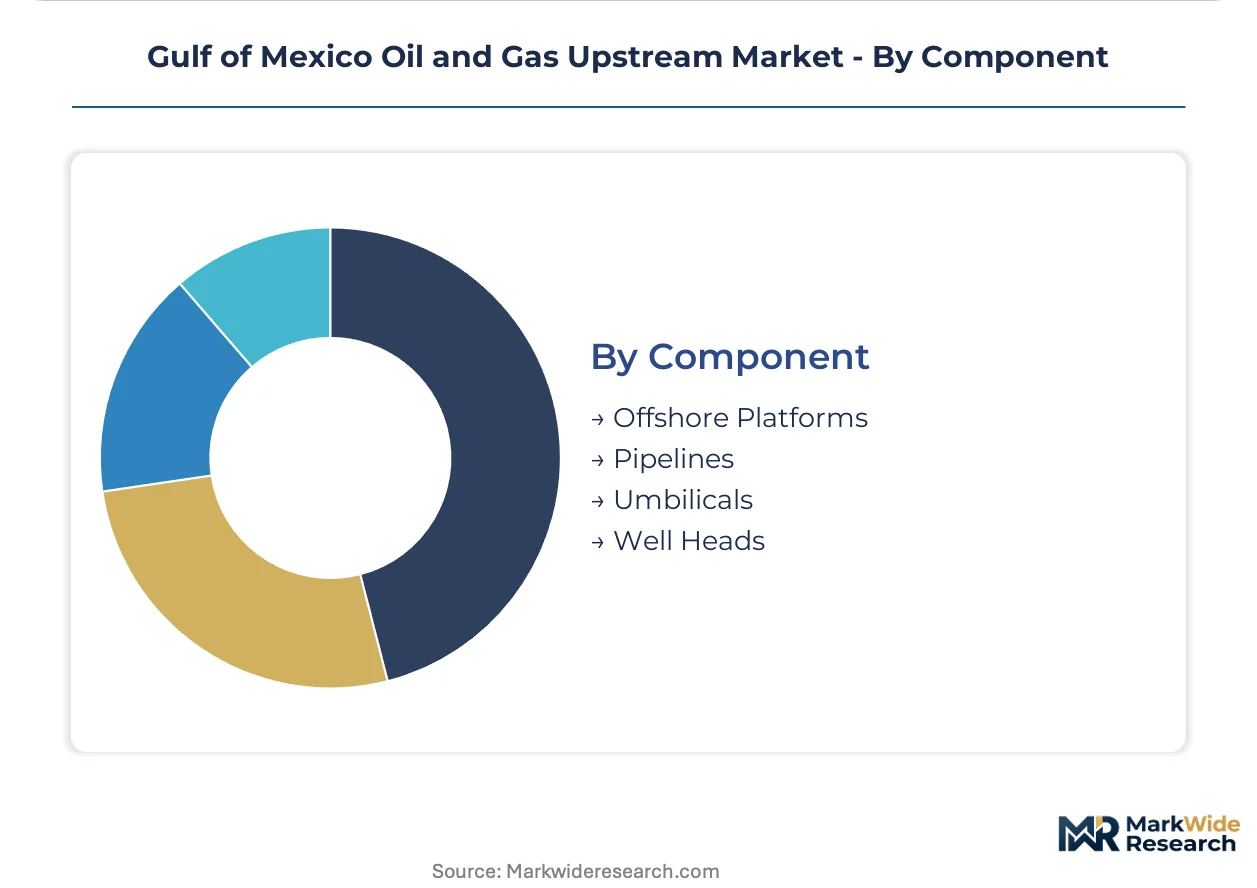
Component:
Supply concentration in subsea fabrication yards and specialized steel forging creates procurement bottlenecks for critical path equipment.
- Well Heads:High-pressure high-temperature subsea wellhead systems rated for 15,000+ psi and 350°F bottom-hole conditions. Lower Tertiary developments in Alaminos and Walker Ridge blocks drive specification escalation toward 20,000 psi ratings.
- Umbilicals:Hydraulic, electric, and fiber-optic control lines connecting subsea trees to surface facilities. Steel tube and thermoplastic hose configurations serve dynamic riser and static flowline applications across water depth tiers.
- Offshore Platforms:Fixed jackets, compliant towers, and floating production hosts.
- Pipelines:Export trunklines and infield flowlines for oil, gas, and multiphase transport.
Well Heads anchor replacement demand cycles; Umbilicals are gaining share fastest in tieback-intensive development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers of Gulf barrels concentrate along the Louisiana-Texas corridor, where petrochemical complexes and export terminals anchor offtake demand. European refiners and Asian petrochemical operators now screen shipments against carbon intensity benchmarks, reshaping procurement patterns for deepwater production streams.
United States
Federal lease auctions in the Western and Central Gulf planning areas drive operator participation, with the Bureau of Ocean Energy Management streamlining acreage access timelines. EPA offshore discharge regulations and Coast Guard safety protocols layer compliance requirements onto project economics. The Port of Houston and Lake Charles industrial corridor host the densest concentration of fractionation capacity and LNG export terminals serving associated gas from ultra-deepwater developments.
Brazil
Pre-salt carbonate reservoirs in the Santos Basin attract capital allocation from operators with ultra-deepwater technical capabilities, competing for shared rig and vessel resources with Gulf of Mexico projects. The National Petroleum Agency (ANP) governs production-sharing contracts and local content requirements that shape field development economics. The Macaé logistics cluster and Rio de Janeiro technical services hub concentrate subsea engineering talent and fabrication capacity for floating production systems.
Norway
North Sea decommissioning obligations and mature field redevelopment priorities divert investment from greenfield frontier exploration, though Norwegian operators retain technical capabilities applicable to Gulf deepwater plays. The Norwegian Petroleum Directorate enforces recovery factor mandates and CO2 storage site licensing that influence offshore investment returns. The Stavanger subsea technology cluster and Oslo financial center anchor North Sea engineering expertise and project finance capacity.
Mexico
Energy sector liberalization has opened shallow-water and deepwater blocks to international operators, creating parallel demand for drilling and subsea services across the Perdido Fold Belt and Salina Basin. The National Hydrocarbons Commission (CNH) manages licensing rounds and joint venture approvals that determine market access for foreign participants. The Ciudad del Carmen service base and Tampico fabrication yards concentrate supply chain capacity for southern Gulf developments.
United Kingdom
North Sea basin maturity and offshore wind transition commitments constrain capital deployment to oil and gas, though UK-based service companies retain subsea engineering capabilities relevant to Gulf projects. The North Sea Transition Authority oversees licensing and decommissioning security arrangements that influence operator portfolio decisions. The Aberdeen energy technology cluster maintains specialized expertise in subsea processing and extended-reach drilling applicable to Lower Tertiary developments.
Gulf of Mexico Oil and Gas Upstream Market Competitive Landscape
Player mix skews toward integrated majors with balance sheet capacity for multi-billion dollar platform investments, while independent operators capture marginal field economics through tieback strategies. Market structure concentrates around two tiers: capital-intensive developers of standalone ultra-deepwater facilities, and specialty players exploiting existing host infrastructure. Strategic archetypes include infrastructure-led majors, tieback-focused independents, and national oil companies with reserve mandates. Competitive moves center on lease acquisition positioning and portfolio high-grading through divestment of non-core assets.
Among the integrated major archetype, Shell plc, Chevron Corporation, and BP plc occupy positions defined by proprietary host facility ownership and Lower Tertiary production scale. Shell plc exemplifies the infrastructure-led model through its Appomattox platform dominance in the ultra-deepwater corridor. Chevron Corporation anchors its position through massive capital commitments in the Lower Tertiary trend. Murphy Oil Corporation represents the independent specialist archetype, concentrating on tieback developments that reduce standalone infrastructure exposure.
| Leading Market Players |
|---|
| Shell plc |
| Equinor ASA |
| ExxonMobil Corporation |
| ConocoPhillips |
| Eni SpA |
| Chevron Corporation |
| TotalEnergies SE |
| Murphy Oil Corporation |
| BP plc |
| Others |
Supply & Pricing Matrix
Full-waveform inversion seismic processing replacing legacy time-domain imaging is redistributing exploration budgets toward supercomputing infrastructure while compressing contract timelines for independent operators without proprietary clusters, simultaneously concentrating pricing power among capital-intensive majors and fragmenting procurement geography across specialized service tiers.
Pricing Analysis
Next-generation floating production systems command premium dayrates against aging semi-submersible rigs and standard jackup configurations. Three-tier pricing structure across premium, standard, and economy levels separates ultra-deepwater drillships from mid-water assets and shallow-water units, with price differentiation anchored in water depth capability and BOP stack redundancy. Cost compression in standard-tier drilling services is intensifying because fleet-scale contractors are absorbing margin erosion to maintain utilization. Independent operators exhibit highest price sensitivity, while integrated majors with proprietary host infrastructure demonstrate inelastic demand for premium-tier assets.
Supply Chain Analysis
Singapore and South Korea anchor floating production system hull fabrication, while Houston and Aberdeen concentrate subsea engineering and project management functions. The supply chain draws from Japanese steel forging for high-pressure wellhead systems, Norwegian umbilical manufacturing for dynamic riser applications, and Mexican fabrication yards for shallow-water jacket structures. Single-source vulnerability concentrates in ultra-deepwater drillship contracting, where a handful of owners control deployable capacity. Distribution runs through integrated majors with captive procurement teams, independents relying on oilfield service intermediaries, and national oil companies with state-backed logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deepwater completions engineering expertise retiring faster than replacement cohorts enter the workforce is constraining project execution capacity across the Gulf, creating asymmetric returns for operators and service companies that secure specialized talent pipelines.
For Market Incumbents: Shield proprietary seismic processing infrastructure through targeted hiring of full-waveform inversion specialists and exclusive licensing agreements with supercomputing facilities. Deepen backward integration into subsea equipment maintenance capabilities to capture lifecycle revenue streams as third-party service availability tightens. Lock in long-term drillship fixtures before independent operators bid up spot market rates. For New Entrants and Emerging Players: Tieback engineering services for marginal field redevelopment represent the most penetrable white-space opportunity, as majors divest non-core assets and independents lack in-house subsea architecture capabilities. Target Walker Ridge and Keathley Canyon blocks where orphaned discoveries await host facility connections. Establish partnerships with platform operators to secure preferential processing capacity allocation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors infrastructure-led majors with balance sheet capacity for multi-billion dollar platform commitments over capital-constrained independents. Long-term viability rests on reservoir reinjection capabilities and carbon intensity management as European offtake contracts harden environmental benchmarks. Monitor Bureau of Ocean Energy Management lease sale participation rates as an inflection indicator for independent operator confidence.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Tieback Development | Murphy Oil-style tiebacks reduce standalone capital requirements by exploiting Shell's Appomattox host infrastructure. |
| Carbon Capture Integration | EPA offshore discharge regulations incentivize CO2 reinjection from Lower Tertiary production streams. |
| Proprietary Seismic Infrastructure | Supercomputing clusters for full-waveform inversion compress exploration timelines from quarters to weeks. |
| Drillship Fleet Expansion | Ultra-deepwater rig supply concentration creates rate volatility that rewards early fixture commitments. |
| Decommissioning Bond Optimization | Bureau of Ocean Energy Management financial assurance rules escalate liability thresholds for marginal operators. |
Research Methodology
A standing panel of deepwater project engineers, subsea procurement leads at integrated majors, independent operator portfolio managers, Bureau of Safety and Environmental Enforcement compliance officers, and Gulf Coast petrochemical offtake specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from Bureau of Ocean Energy Management lease sale records, EPA offshore discharge permit databases, Coast Guard safety incident reports, and SEC 10-K filings from publicly traded operators. Bottom-up project economics modeling triangulated against top-down market sizing from service company revenue disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning service type, technology platform, water depth tier, operator category, and end-use offtake pattern. CAGRs were derived from production decline curve analysis and greenfield development timelines. Forecast inputs incorporated rig dayrate trajectories, steel cost indices, and carbon intensity benchmark evolution.
Forecasts assume regulatory continuity in Bureau of Ocean Energy Management lease access procedures and EPA offshore discharge frameworks; material policy shifts would require re-modeling. Specific risks include Bureau of Safety and Environmental Enforcement well control standard tightening, European carbon border adjustment implementation, and drillship contractor consolidation. Recalibration cycles align with material shifts in lease sale participation, offtake contract carbon clauses, and subsea engineering labor availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Mud Mixers Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Norway Oil and Gas Upstream Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
Latin America Coiled Tubing Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
Crude Oil Desalter Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
LNG Loading Skid Market