
 North America Positive Displacement Pumps Market | 2026-2036
North America Positive Displacement Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
North America Positive Displacement Pumps Market Foresight
EPA methane emissions standards for oil and gas infrastructure is recalibrating the cost-of-entry calculus for pump manufacturers serving upstream extraction. Flowserve Corporation leverages its aftermarket service network to sustain long-term contracts across Permian Basin operators. Dover Corporation anchors its position through backward integration into precision machining for high-pressure diaphragm assemblies.
Positive displacement pumps trap fixed fluid volumes within cavities formed by rotating elements or reciprocating members, then force discharge against system pressure through mechanical displacement; units typically achieve volumetric efficiencies above 85 percent at viscosities exceeding 1,000 cP, making them essential for shear-sensitive polymer transfer and multiphase crude handling. Gear pumps dominate the product type landscape in mature hydrocarbon logistics corridors where margin pools have compressed to service-contract economics. Diaphragm pumps command premium positioning in chemical processing and food safety applications requiring zero-leakage seals.
OSHA process safety management rules and FDA sanitary equipment standards shape procurement specifications across US chemical and food manufacturing facilities. EPA regional enforcement offices in Dallas and Denver intensify inspection schedules for fugitive emissions from rotating equipment. Stakeholders must monitor how state-level carbon intensity scoring in California and Alberta reframes total-cost-of-ownership calculations for pump fleet replacements.
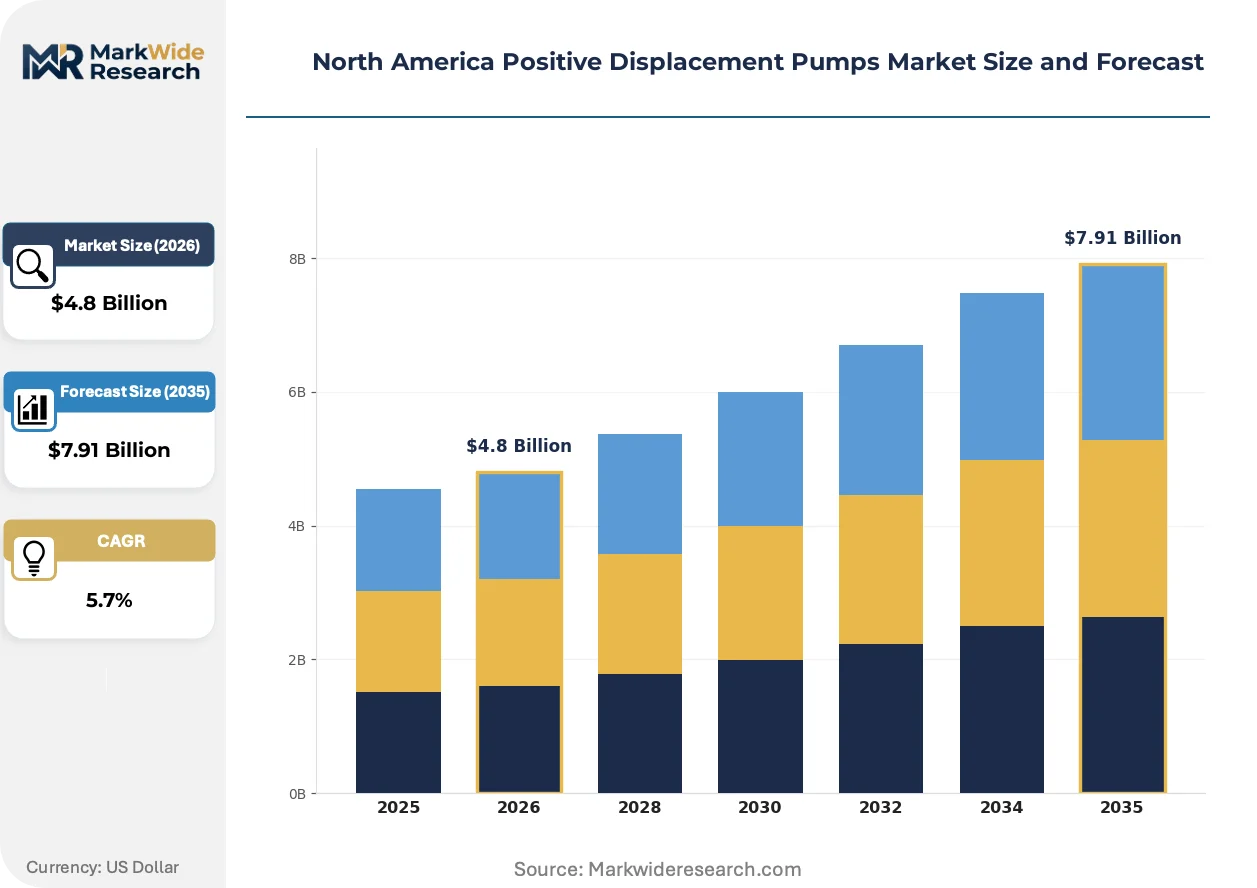
Market Dynamics
EPA methane emissions standards for oil and gas infrastructure are recalibrating the cost-of-entry calculus for pump manufacturers serving upstream extraction across Texas and Louisiana. Chemical processors are accelerating sealed-system pump deployments ahead of enforcement deadlines.
Growth Catalysts
- EPA Methane Rules:Tightening emissions standards for oil and gas infrastructure are forcing Permian Basin operators to replace legacy pump fleets with sealed positive displacement systems.
- Canadian Oil Sands Expansion:Diaphragm pump demand concentrates in Alberta extraction operations requiring zero-leakage seals for bitumen handling and tailings management.
- Food Safety Modernization:FDA sanitary equipment standards are driving gear pump upgrades across US dairy and beverage processing facilities.
Market Restraints
- Specialized Alloy Costs:High-nickel stainless steel price volatility compresses margins for diaphragm pump manufacturers serving corrosive chemical applications.
- Precision Machining Concentration:Domestic supply of tight-tolerance gear housings concentrates among a handful of Midwest machine shops, creating bottleneck risk.
- Substitution by Centrifugal Systems:Advances in low-shear centrifugal designs threaten positive displacement pump share in mid-viscosity polymer transfer applications.
Strategic Opportunities
- Alberta Carbon Capture:Provincial carbon intensity scoring creates demand for high-pressure CO2 injection pumps in enhanced oil recovery and sequestration projects.
- Modular Skid Integration:Pump-integrated process skids are capturing share from standalone unit sales in mid-scale chemical processing.
- California Low-Carbon Fuel Standards:State-level carbon intensity mandates are accelerating renewable diesel plant construction, requiring specialized positive displacement pumps for feedstock handling.
Industry Challenges
- Sealing Technology Talent Gap:Experienced elastomer compounders for zero-emission diaphragm designs remain scarce across US manufacturing bases.
- Legacy System Integration:Retrofitting smart monitoring into 1980s-era pump installations across Gulf Coast refineries demands custom engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Positive Displacement Pumps Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Pumps, Diaphragm Pumps, Lobe Pumps, Screw Pumps End User: Oil & Gas, Water & Wastewater, Chemical Processing, Food & Beverage Installation Type: Above Ground, Below Ground, Portable, Stationary Distribution Channel: Direct Sales, Online Retail, Distributors, Others |
| Companies Covered | SPX FLOW Inc., Flowserve Corporation, Dover Corporation, Xylem Inc., Grundfos Holding A/S, Ampco Pumps Company Inc., ITT Inc., Pentair PLC, Ingersoll Rand, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Positive Displacement Pumps Market Shifts & Advancements
Digital condition monitoring and modular system architectures are displacing conventional standalone pump sales across North American process industries. Equipment buyers now prioritize integrated packages over component procurement.
Magnetic drive sealing technology is modularizing across chemical processing applications. Refinery operators in Texas and Louisiana are specifying magnetically coupled gear pumps for hazardous fluid transfer. This architecture is modularizing maintenance schedules and compressing downtime costs for high-availability units.
OSHA process safety management rules are tightening audit frequencies for rotating equipment in hydrocarbon service. Inspectors in Dallas and Denver regional offices are expanding fugitive emissions testing protocols. Chemical manufacturers are responding by pre-emptively replacing mechanical seal pumps with diaphragm alternatives ahead of citation risk.
Aftermarket service unbundling is fragmenting traditional long-term maintenance contracts. Permian Basin operators are separating parts procurement from labor services, pressuring OEM service margins. This pattern is most visible in Texas and New Mexico shale plays where operator procurement teams have consolidated vendor management functions.
North America Positive Displacement Pumps Market Segmentation
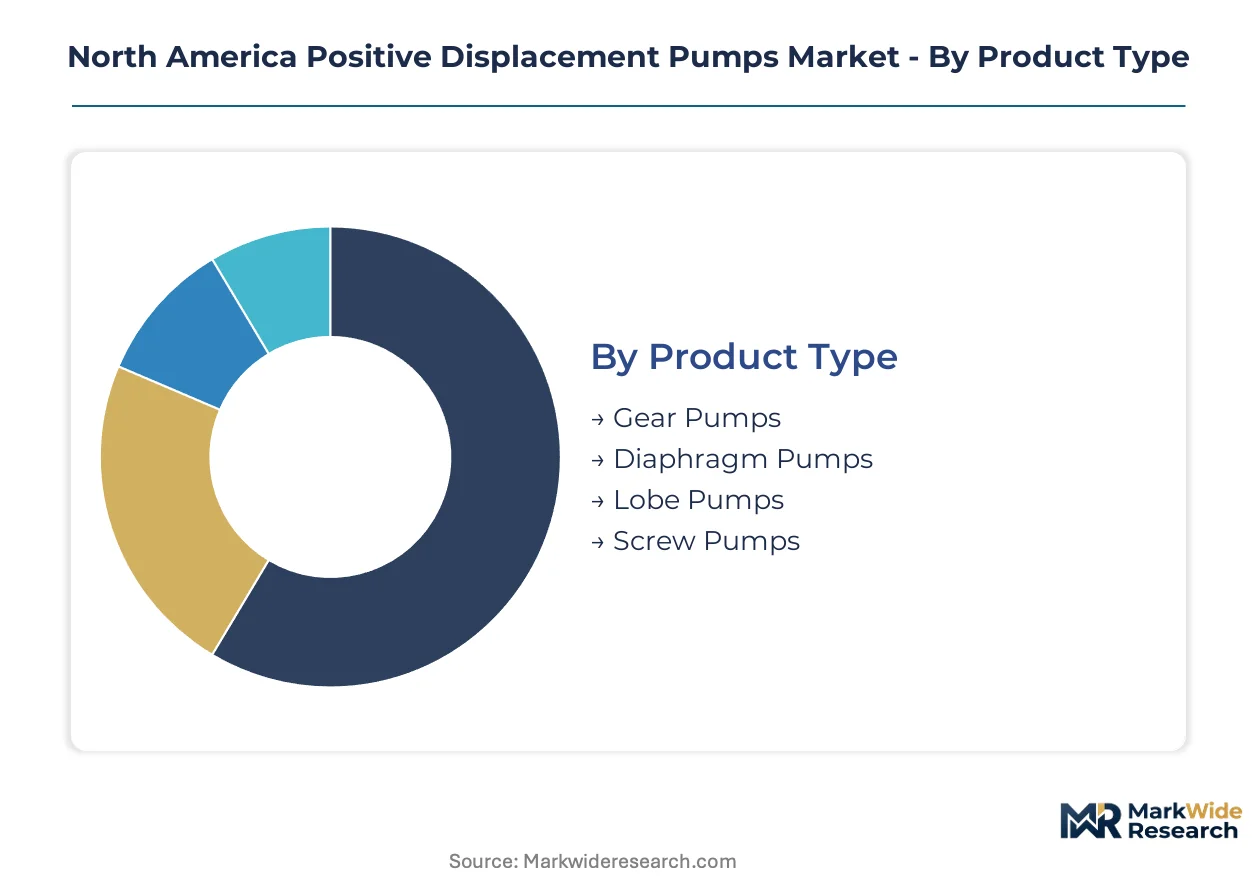
Positive displacement pump buyers in North America segment procurement by fluid characteristics, duty cycle intensity, and integration depth with process control systems. Understanding these divides clarifies why gear pumps dominate mature hydrocarbon corridors while diaphragm systems capture premium chemical applications.
Product Type:
Gear pumps anchor standalone installations across high-volume crude logistics, while diaphragm and lobe designs embed more deeply into sealed chemical processing skids.
- Gear Pumps:Intermeshing cogs trap and displace viscous fluids with minimal shear. Permian Basin operators specify these for multiphase crude gathering where mechanical simplicity outweighs precision. EPA methane enforcement is accelerating sealed-system retrofits that displace legacy external-gear units.
- Diaphragm Pumps:Elastomer or PTFE membranes isolate process fluid from mechanical drive components. Alberta oil sands extraction concentrates demand for zero-leakage bitumen and tailings handling where containment failure carries catastrophic environmental liability.
- Lobe Pumps:Synchronized rotary lobes handle shear-sensitive food slurries without product degradation. FDA sanitary equipment standards drive specification across US dairy processing facilities upgrading for pathogen control.
- Screw Pumps:Meshing helical rotors deliver pulsation-free flow for polymer and heavy fuel oil transfer. Refinery operators in Texas and Louisiana deploy these for viscous residuum handling where pressure stability matters.
Gear pumps lead volumes today; diaphragm pumps are gaining share fastest.
End User:
Cost tier stratification separates capital-intensive upstream extraction from margin-pressured municipal infrastructure.
- Oil & Gas:Upstream operators across Texas, Louisiana, and Alberta prioritize mean-time-between-failure metrics over first cost. Sealed-system positive displacement pumps command premium positioning in fugitive emissions compliance.
- Chemical Processing:Corrosive fluid handling demands alloy-specific pump configurations. Process safety management audits under OSHA jurisdiction drive pre-emptive replacement of mechanical seal pumps with diaphragm alternatives.
- Water & Wastewater:Municipal procurement emphasizes lifecycle cost over performance optimization. Gear and screw pumps handle primary sludge transfer where abrasive wear dominates specification.
- Food & Beverage:3-A sanitary standards and FDA food safety mandates shape stainless steel pump selection. Clean-in-place compatibility differentiates lobe and diaphragm configurations in dairy and beverage processing.
Oil & gas commands the highest average selling prices; food & beverage shows the steepest specification upgrade trajectory.
Installation Type:
Application environment dictates structural reinforcement, sealing architecture, and maintenance accessibility requirements.
- Above Ground:Standard pump-motor assemblies on concrete pads dominate process plant installations. Texas and Louisiana refineries favor this configuration for hazardous service where leak detection systems enable rapid response.
- Below Ground:Submersible positive displacement configurations handle sump drainage and tank bottom sludge. Canadian oil sands tailings ponds require corrosion-resistant below-grade pumping systems.
- Portable:Skid-mounted or trailer-towed units serve frac water transfer and emergency response. Permian Basin operators lease portable gear pump packages for temporary production facility commissioning.
- Stationary:Permanent installations anchor long-term process streams with dedicated utility connections. Chemical processors specify stationary diaphragm pumps for continuous corrosive duty.
Stationary installations dominate installed base; portable configurations are climbing fastest in shale play development.
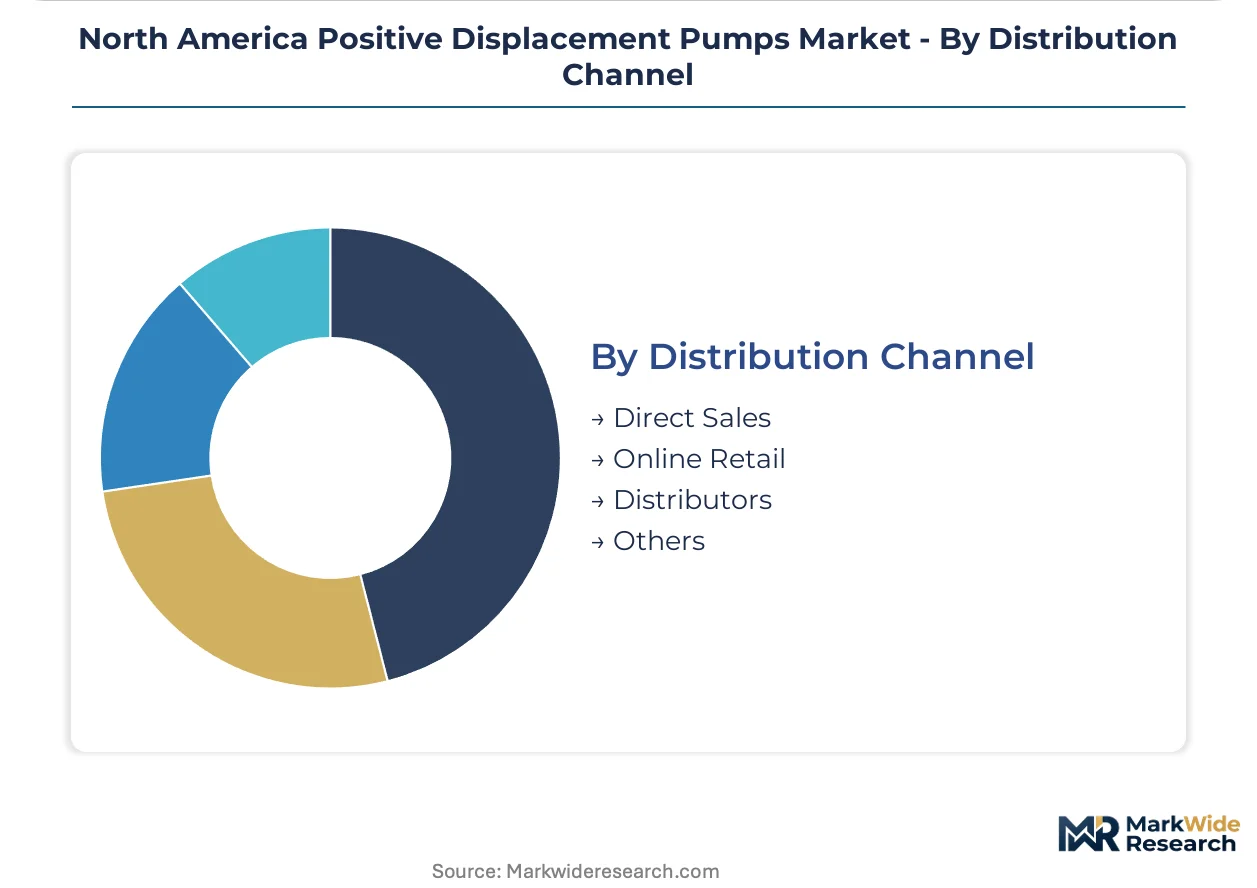
Distribution Channel:
Customer scale and technical complexity determine whether procurement flows through direct OEM relationships or intermediated channels.
- Direct Sales:Large operators in oil & gas and chemical processing negotiate frame agreements with manufacturers. Engineering-intensive diaphragm pump specifications require application support that distributors rarely provide.
- Distributors:Independent industrial distributors stock standard gear pump configurations for maintenance replacement. Midwest machine shop networks concentrate inventory for rapid gear housing and rotor availability.
- Online Retail:E-commerce platforms capture small-volume MRO purchases for non-critical applications. Standardized below-5-horsepower units move through digital channels with minimal pre-sale engineering.
- Others:Rental fleets and integrated system packagers represent fragmented alternative channels. Modular skid builders bundle pumps with process equipment under single-source procurement.
Direct sales capture the largest transaction values; distributor channels handle the highest order frequencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American positive displacement pumps industry traces its commercial roots to early 20th-century petroleum extraction in Texas and Oklahoma, where gear pump designs first scaled for crude handling. Equipment manufacturing subsequently clustered around Great Lakes machining centers and Gulf Coast petrochemical corridors.
United States
Texas and Louisiana refineries drive sealed-system pump demand as EPA methane enforcement intensifies across Permian Basin operations. OSHA process safety management audits now mandate pre-emptive replacement of mechanical seal pumps with diaphragm alternatives in hazardous service. Houston anchors the largest concentration of pump rebuild facilities serving Gulf Coast petrochemical complexes.
Canada
Alberta oil sands extraction concentrates demand for zero-leakage diaphragm pumps in bitumen handling and tailings pond management. Provincial carbon intensity scoring under Alberta's TIER system creates procurement pressure for high-pressure CO2 injection pumps in enhanced oil recovery. Edmonton and Calgary host specialized service networks for heavy-duty slurry pump maintenance.
Mexico
Pemex refinery modernization and private upstream licensing rounds are importing US-specification positive displacement pumps for sour crude processing. Mexican federal environmental regulations under SEMARNAT are tightening fugitive emissions monitoring for rotating equipment in Veracruz and Tamaulipas production zones. Monterey industrial corridor is emerging as a distribution hub for gear pump assemblies serving northern manufacturing.
North America Positive Displacement Pumps Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive precision machining capabilities. Tier-one positions concentrate among pump specialists with integrated aftermarket service networks, while mid-scale fabricators compete on regional delivery speed. Two archetypes dominate: full-line manufacturers with global service footprints, and niche specialists with alloy-specific engineering depth. Capacity expansion and backward integration into precision machining represent the primary competitive vectors.
Among US-based industrial conglomerates, Flowserve Corporation and Dover Corporation exemplify the full-line archetype with integrated manufacturing and service capabilities. SPX FLOW Inc. occupies a position within the specialized fluid handling tier, representing the precision-engineering segment focused on sanitary and industrial process applications.
| Leading Market Players |
|---|
| SPX FLOW Inc. |
| Flowserve Corporation |
| Dover Corporation |
| Xylem Inc. |
| Grundfos Holding A/S |
| Ampco Pumps Company Inc. |
| ITT Inc. |
| Pentair PLC |
| Ingersoll Rand |
| Others |
Supply & Pricing Matrix
Backward integration into precision machining for high-pressure diaphragm assemblies anchors both supply security and premium pricing power for full-line manufacturers serving EPA-regulated chemical corridors. This captive production capability insulates tier-one suppliers from Midwest gear housing bottlenecks while supporting sealed-system premiums across Texas and Louisiana petrochemical installations.
Pricing Analysis
The bundled-vs-unbundled service split now defines transaction economics across North American pump procurement. Aftermarket service unbundling fragments traditional long-term maintenance contracts as Permian Basin operators separate parts procurement from labor services. Price differentiation rests on certification grade for zero-emission diaphragm designs and geographic delivery cost for precision-machined components. Cost compression in standard gear pump tiers is intensifying because distributor inventory concentration enables rapid price matching. Municipal water utilities exhibit highest price sensitivity; upstream oil and gas operators prioritize mean-time-between-failure metrics over first cost.
Supply Chain Analysis
Domestic-content mandates under Buy American provisions for federally funded water infrastructure projects are reshaping sourcing toward US-based foundries and machine shops. Manufacturing concentration centers on Great Lakes machining centers and Gulf Coast petrochemical corridors, with Canadian specialty alloy suppliers feeding Alberta oil sands demand. Raw material dependencies include high-nickel stainless steel for corrosive chemical service, elastomer compounds for zero-leakage diaphragms, and precision-ground gear blanks. Single-source vulnerability in tight-tolerance gear housing supply creates bottleneck exposure. Distribution runs through direct OEM relationships for engineered diaphragm specifications and independent distributors for standard maintenance replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
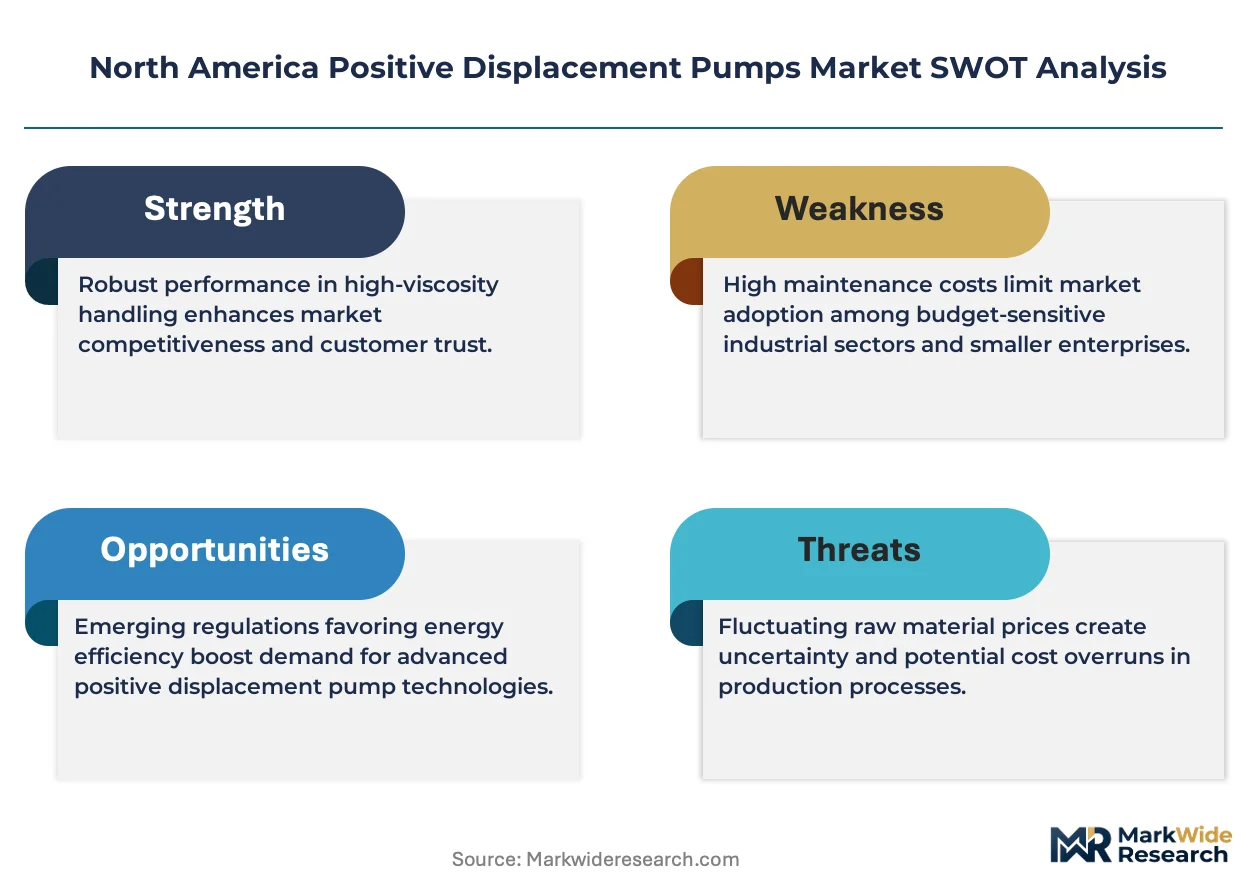
This market functions as a geographic-arbitrage play where Alberta carbon intensity scoring and California low-carbon fuel standards create premium demand corridors that subsidize margin recovery in price-pressured Texas shale plays.
For Market Incumbents: Deepen backward integration into elastomer compounding capabilities to address the sealing technology talent gap constraining zero-emission diaphragm production. Add precision machining capacity in Ohio or Michigan to reduce dependency on concentrated Midwest gear housing suppliers. Defend against centrifugal system substitution by embedding smart condition monitoring into legacy pump fleets under long-term service contracts.
For New Entrants and Emerging Players: Capture modular skid integration opportunities in mid-scale chemical processing where standalone unit sales are eroding. Target portable pump configurations in Permian Basin shale development, the fastest-climbing installation category. Enter through rental fleet partnerships or integrated system packager relationships rather than direct OEM competition.
For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with captive machining capabilities because aftermarket fragmentation enables consolidation of fragmented rebuild facilities. The 5-10 year viability window favors targets with EPA-compliant sealed-system expertise over legacy mechanical seal-dependent operations. Monitor Alberta TIER carbon intensity enforcement as the inflection indicator for high-pressure CO2 injection pump demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Captive gear housing production insulates Flowserve and Dover from Midwest supplier bottlenecks. |
| Modular Skid Integration | Pump-integrated process skids displace standalone sales in Texas and Louisiana chemical corridors. |
| Smart Condition Monitoring Deployment | Digital retrofit packages extend service contract attach rates across 1980s-era Gulf Coast installations. |
| Elastomer Compounding Capability Buildout | In-house diaphragm material development addresses the zero-emission sealing talent shortage. |
| Portable Configuration Fleet Expansion | Skid-mounted and trailer-towed units capture frac water transfer demand in Permian Basin development. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market informing cross-border demand patterns. The analytical approach combines structured interviews with plant engineers at Texas and Louisiana refineries, procurement leads at Alberta oil sands operators, aftermarket service heads at Gulf Coast rebuild facilities, and distribution channel partners across the Midwest industrial belt. Secondary validation draws from EPA enforcement records, FDA sanitary equipment standards filings, SEC 10-K disclosures from diversified industrial conglomerates, and customs data on high-nickel alloy imports. Bottom-up unit demand modeling and top-down industry value triangulation ensure consistency across projections.
Granularity-level modeling extends to product type, end user industry, installation configuration, and distribution channel across the projection horizon. The analytical framework segments gear, diaphragm, lobe, and screw pump technologies with separate demand curves for oil and gas, chemical processing, water and wastewater, and food and beverage applications. CAGRs were derived from regression analysis of historical replacement cycles and regulatory enforcement timelines. Industry-specific forecast inputs include EPA methane rule implementation schedules and Alberta TIER carbon intensity scoring trajectories.
Regulatory enforcement delays, commodity alloy price spikes, and centrifugal pump technology advances are the dominant revision risks that could alter trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Circulators Market
Pumps and Control Devices
Domestic Booster Pump Market
Pumps and Control Devices
Latin America Centrifugal Pumps Market
Pumps and Control Devices
Steam Jet Ejector Market
Pumps and Control Devices
India Solar Water Pump Systems Market
Pumps and Control Devices
Electric Submersible Pump Market
Pumps and Control Devices
Air-Operated Double Diaphragm (AODD) Pumps Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Water Intake Screens Market
Pumps and Control Devices
Rental Industrial Pump Market
Pumps and Control Devices
Seawater Cooling Pumps Market
Pumps and Control Devices
Vertical Immersion Pumps Market
Pumps and Control Devices
Residential Pumps Market
Pumps and Control Devices
Subsea Pumps Market