
 Absolute Pressure Sensor Market | 2026-2036
Absolute Pressure Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Absolute Pressure Sensor Market Analysis
Buyer concentration in automotive electrification is recalibrating procurement volumes for absolute pressure sensors across tier-one suppliers. STMicroelectronics leverages MEMS fabrication scale to anchor European supply contracts for EV battery monitoring. Infineon Technologies specializes in piezoelectric variants that dominate aerospace qualification programs. Honeywell International extends its industrial sensor portfolio through channel control in North American process automation.
An absolute pressure sensor measures pressure relative to a perfect vacuum, typically employing silicon piezoresistive elements or ceramic capacitive membranes fabricated through MEMS lithography to deliver accuracy within 0.1% full scale for critical process control. Silicon-based products capture the largest volume share due to semiconductor manufacturing economies, while piezoelectric variants command premium positioning in high-temperature aerospace environments. The automotive end-use segment generates the fastest expansion trajectory as electric vehicle thermal management systems multiply sensor count per platform.
The EPA regulates emissions monitoring accuracy in US industrial applications, while REACH and RoHS constrain material composition across European supply chains, collectively elevating compliance costs for non-certified entrants. China's GB standards and MIIT directives mandate domestic certification for sensors deployed in national infrastructure projects, fragmenting market access protocols. Stakeholders must monitor evolving battery safety regulations and semiconductor export controls to anticipate demand inflections in sensor-intensive applications.
Market Dynamics
Automotive electrification is compressing sensor qualification cycles while fragmenting supply chains across battery thermal management, cabin pressure, and fuel cell monitoring applications. Tier-one suppliers now demand multi-protocol compatibility from single sensor platforms to reduce BOM complexity.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-global-warming-potential refrigerants in HVAC systems accelerate demand for hermetic pressure sensors capable of handling CO₂ and hydrocarbon working fluids.
- Semiconductor fabrication clusters:China's expanding wafer foundry capacity in Shanghai and Hefei is localizing MEMS supply chains for domestic EV battery management systems.
- Piezoresistive MEMS lithography:Sub-micron etching processes enable multi-sensor arrays on single dies, reducing per-channel costs for industrial automation deployments.
Market Restraints
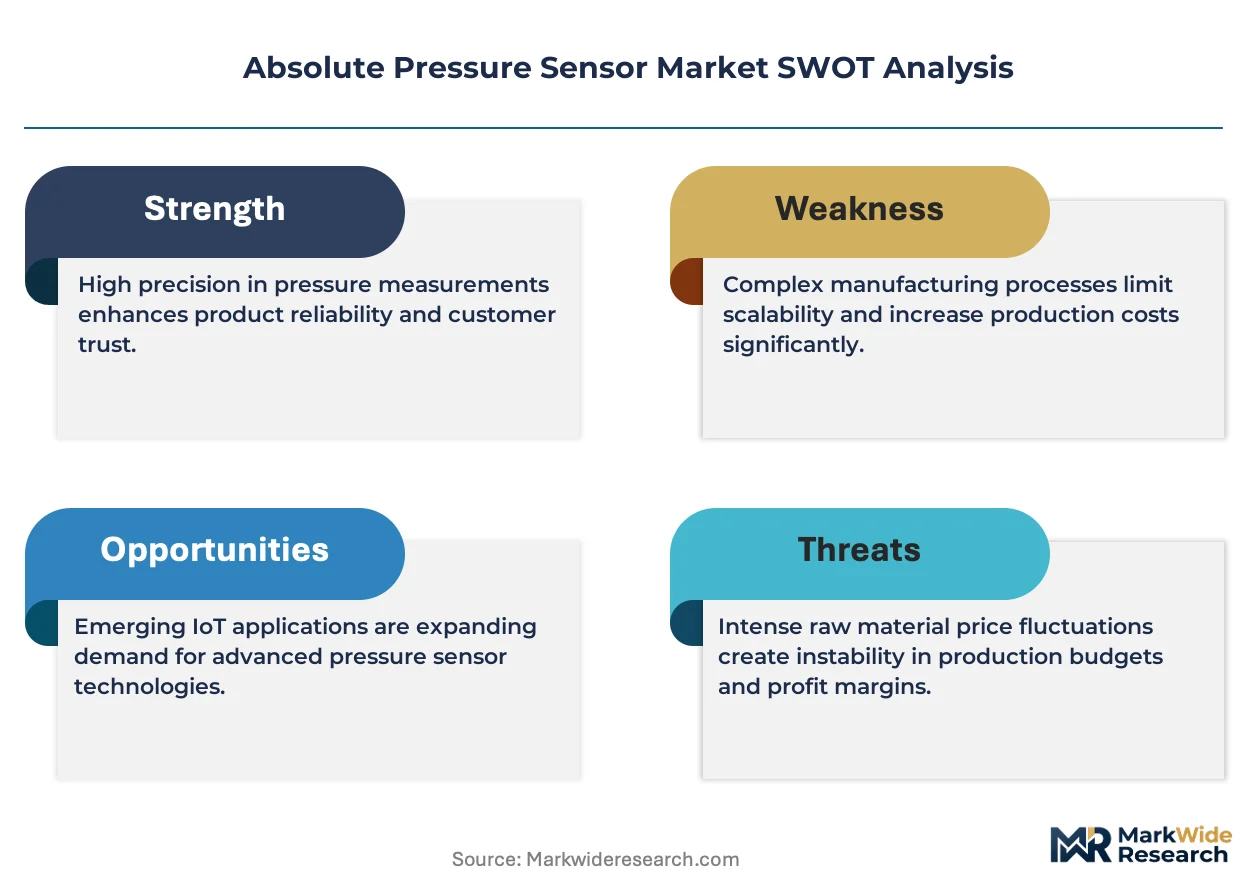
- Silicon wafer supply concentration:Taiwan and South Korean substrate producers control critical 200mm SOI wafer supply, creating input cost volatility for European sensor fabricators.
- REACH substance restrictions:Cadmium and lead limitations in piezoelectric ceramics force reformulation of high-temperature sensor elements, extending R&D timelines.
- Optical pressure transducers:Fiber-optic alternatives eliminate electromagnetic interference concerns in MRI suites and high-voltage EV environments, threatening silicon market position.
Strategic Opportunities
- India's PLI scheme for automotive components:Localized sensor assembly incentives attract tier-two suppliers to Pune and Chennai industrial corridors for cost-competitive export manufacturing.
- Wireless HART and IO-Link convergence:Industrial IoT protocols enable predictive maintenance revenue models through continuous pressure monitoring in chemical processing.
- Japan's METI carbon neutrality roadmap:Hydrogen infrastructure mandates create demand for ultra-high-pressure sensors in refueling station compressors and storage vessels.
Industry Challenges
- MEMS process engineer scarcity:Deep reactive ion etching and wafer-level packaging expertise concentrates in Delft, Eindhoven, and Tsukuba academic clusters, constraining foundry expansion.
- ATEX/IECEx certification timelines:Hazardous area approvals for oil and gas applications extend 14-18 months, delaying revenue recognition for new product variants.
- Legacy 4-20mA integration:Brownfield industrial sites require signal conditioning hardware that increases per-node cost and complexity for digital-native sensor platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Absolute Pressure Sensor Market |
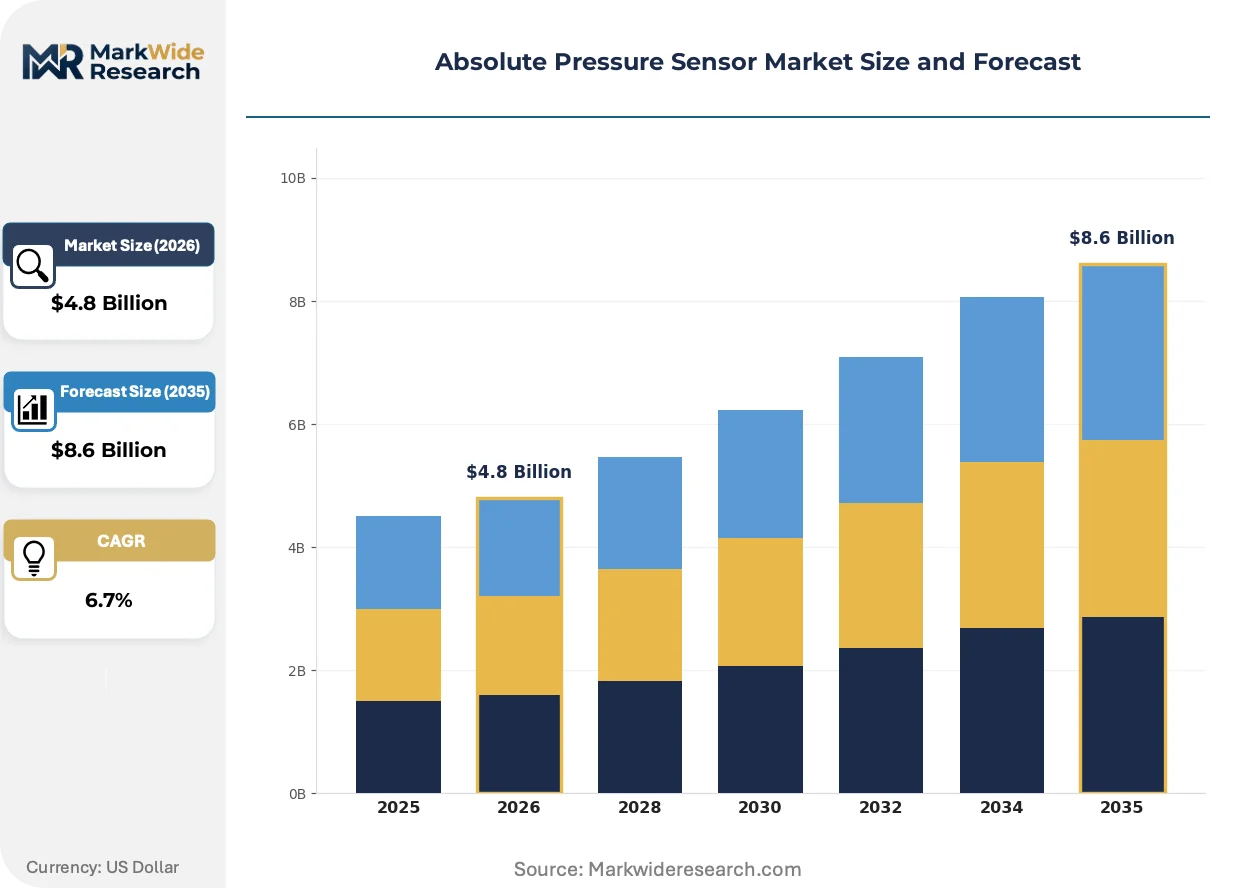
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon, Ceramic, Piezoelectric, Optical End User: Aerospace, Automotive, Industrial, Healthcare Connectivity: Wired, Wireless, Bluetooth, Analog Application: Environmental Monitoring, HVAC, Automotive Testing, Process Control |
| Companies Covered | STMicroelectronics, Infineon Technologies, Honeywell International, Texas Instruments, ABB Ltd., Robert Bosch GmbH, Amphenol Advanced Sensors, Setra Systems, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Absolute Pressure Sensor Market Emerging Trajectories
Silicon carbide MEMS substrates are enabling pressure measurement at temperatures exceeding traditional silicon limits, opening aerospace and geothermal applications previously served by bulkier metal diaphragm designs.
Gallium nitride epitaxy on silicon carbide is rewriting thermal envelope assumptions for absolute pressure sensors. Aerospace propulsion system designers at Safran and Rolls-Royce procurement divisions now specify GaN-compatible sensor packages for turbine blade tip clearance monitoring. This material transition is compressing the addressable market for platinum thin-film sensors in supersonic engine applications.
EPA's updated methane emissions monitoring rules for oil and gas infrastructure mandate continuous pressure surveillance at compressor stations and storage facilities. Midstream operators in the Permian Basin and Appalachian shale regions are retrofitting pneumatic controllers with electronic pressure transmitters to eliminate venting. This regulatory compression is accelerating replacement cycles for mechanical gauge systems that previously operated decades without upgrade.
Consolidated procurement through integrated automation vendors is displacing direct sensor OEM relationships in process industries. End-users in German chemical parks now specify sensor performance parameters to system integrators rather than engaging component manufacturers directly. This channel intermediation concentrates pricing power with Siemens, Emerson, and Yokogawa distributor networks while fragmenting brand visibility for specialized pressure sensor producers.
Absolute Pressure Sensor Market Segmentation
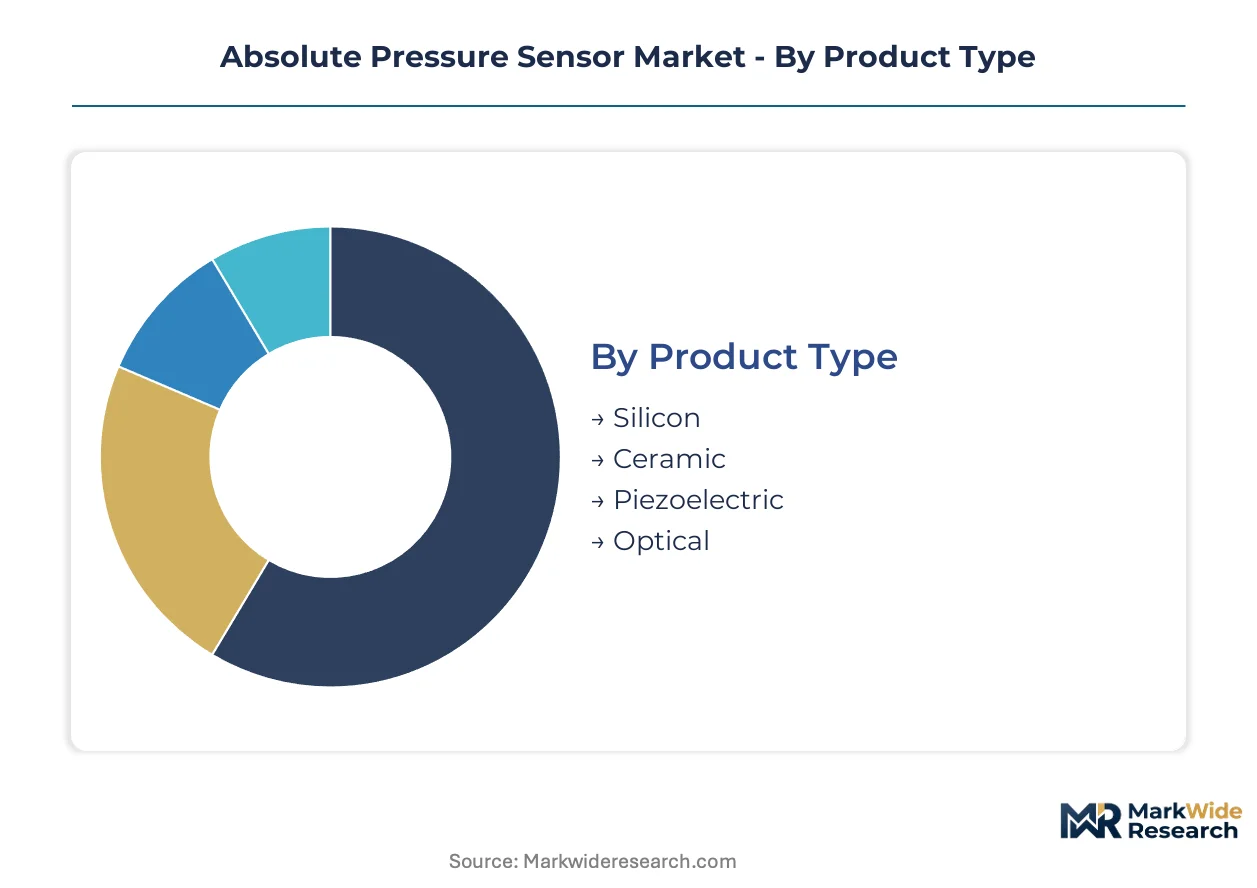
Absolute pressure sensor procurement varies sharply by segment, with certification requirements from EPA, ECHA, and FAA dictating supplier qualification timelines. Material selection and connectivity protocols further fragment sourcing strategies across end-use verticals.
Product Type:
ATEX/IECEx and FAA TSO-C88b certifications concentrate most heavily on ceramic and piezoelectric variants for hazardous aerospace environments, while silicon MEMS face REACH substance scrutiny for consumer-facing automotive deployments.
- Silicon:Piezoresistive MEMS elements fabricated on 200mm SOI wafers deliver accuracy within 0.1% full scale. Automotive battery management systems in Germany's industrial corridor and China's expanding semiconductor clusters drive procurement volume for this cost-optimized technology tier.
- Ceramic:Capacitive alumina diaphragms withstand corrosive process media and extreme thermal cycling. Demand clusters in German chemical parks and US Permian Basin compressor stations where EPA methane rules mandate hermetic pressure surveillance.
- Piezoelectric:Lead zirconate titanate crystals operate above silicon temperature limits for turbine engine monitoring. REACH cadmium restrictions are forcing reformulation of high-temperature elements.
- Optical:Fiber-Bragg-grating transducers eliminate EMI in MRI suites and 800V EV architectures. Adoption accelerates in Japan's hydrogen refueling infrastructure per METI carbon neutrality mandates.
Silicon sits at the top of the volume ranking, with optical climbing the fastest.
End User:
Margin structures diverge by customer procurement power, with aerospace qualification programs commanding premium pricing and automotive electrification squeezing per-unit costs through consolidated tier-one supplier negotiations.
- Aerospace:Rolls-Royce and Safran procurement divisions specify GaN-compatible sensor packages for turbine blade tip clearance monitoring. FAA certification cycles extend 18-24 months, creating substantial barriers for new entrants.
- Automotive:EV thermal management systems multiply sensor count per platform across battery packs, cabin pressure, and fuel cell monitoring. Tier-one suppliers demand multi-protocol compatibility to reduce BOM complexity.
- Industrial:Process automation in German chemical parks and North American midstream operations drives demand for hermetic transmitters. Integrated automation vendors are displacing direct OEM relationships.
- Healthcare:MRI-compatible optical sensors and ventilator pressure modules face FDA 510(k) clearance requirements. HIPAA constraints on data transmission shape wireless connectivity specifications.
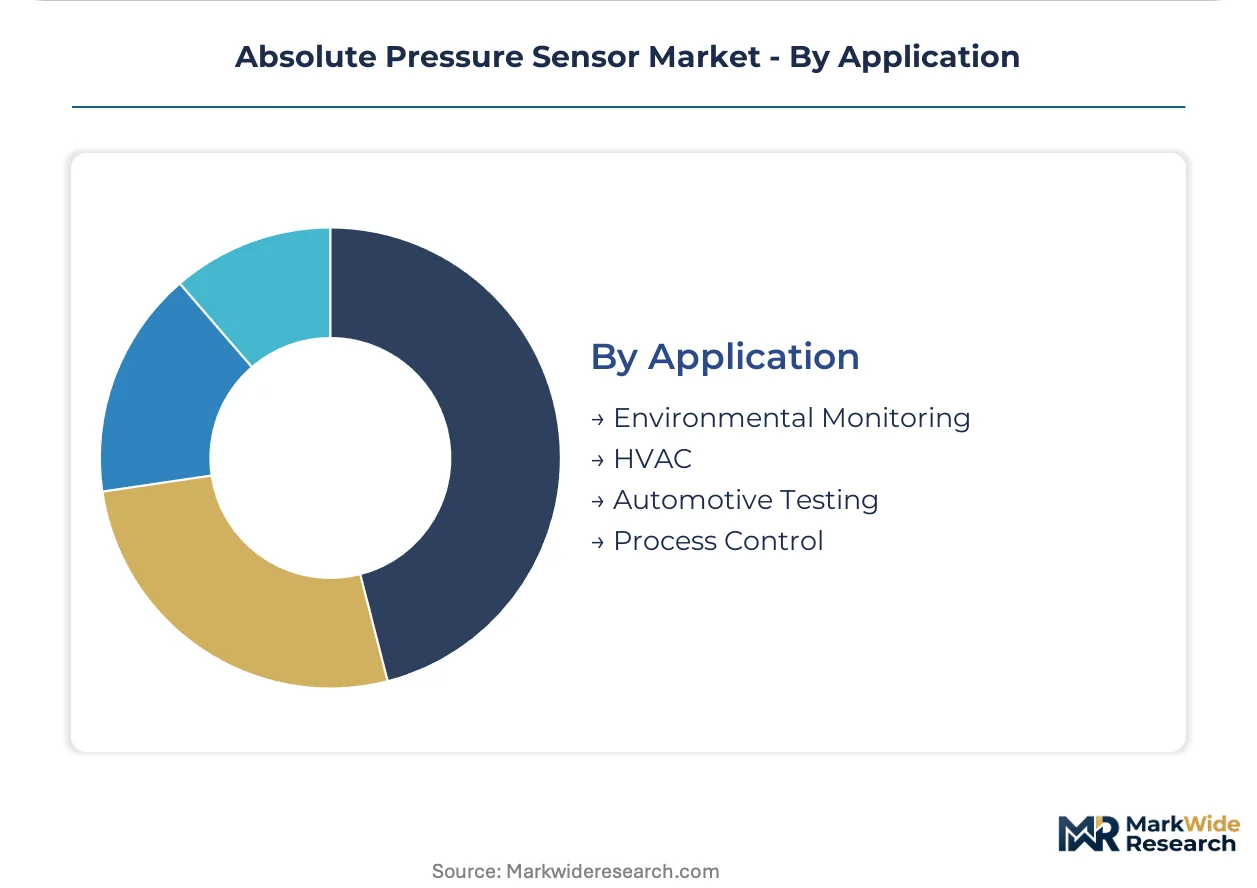
Automotive generates the steepest expansion trajectory, with aerospace retaining the highest margin tier.
Connectivity:
Legacy infrastructure penetration versus greenfield digital deployment creates a bifurcated procurement landscape, with brownfield industrial sites demanding signal conditioning hardware that increases per-node cost.
- Wired:4-20mA current loops dominate oil and gas infrastructure where ATEX certification requirements complicate wireless deployment. Permian Basin operators retrofit pneumatic controllers with electronic transmitters.
- Wireless:Wireless HART and IO-Link protocols enable predictive maintenance revenue models in chemical processing. Battery life constraints limit deployment in remote monitoring applications.
- Bluetooth:Low-energy modules serve portable diagnostic equipment and consumer automotive aftermarket tools. FCC Part 15 certification adds regulatory overhead for US market entry.
- Analog:Voltage-output variants persist in legacy industrial control systems where digital-native platforms face integration friction. Signal conditioning hardware increases per-node cost and complexity.
Wired retains dominant volume share, with wireless gaining share fastest in greenfield industrial deployments.
Application:
Regulatory compression across environmental and safety mandates is accelerating replacement cycles, with mechanical gauge systems facing forced obsolescence under updated emissions and refrigerant rules.
- Environmental Monitoring:Continuous pressure surveillance at compressor stations and storage facilities satisfies EPA methane emissions rules. Midstream operators eliminate pneumatic venting through electronic retrofit programs.
- HVAC:EU F-Gas Regulation mandates for low-GWP refrigerants accelerate demand for hermetic sensors handling CO₂ and hydrocarbon working fluids. CE marking requirements elevate compliance costs for non-certified entrants.
- Automotive Testing:Battery thermal runaway validation and fuel cell membrane characterization require multi-channel pressure acquisition. China's GB standards mandate domestic certification for national infrastructure projects.
- Process Control:Semiconductor fabrication clusters in Shanghai and Hefei localize MEMS supply chains for domestic EV battery management. Sub-micron etching processes enable multi-sensor arrays on single dies.
HVAC commands the largest installed base, with environmental monitoring expanding most quickly under regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation corridor commands premium-tier procurement volumes, while China's semiconductor fabrication clusters localize supply chains at scale. Regulatory divergence across EPA methane rules, EU F-Gas mandates, and China's GB standards fragments certification requirements.
United States
EPA methane emissions monitoring rules compel Permian Basin midstream operators to retrofit pneumatic controllers with electronic pressure transmitters. FERC pipeline safety directives accelerate replacement cycles for legacy mechanical gauge systems. Appalachian shale regions and Gulf Coast petrochemical corridors concentrate demand for hermetic transmitters in compressor station applications.
Germany
REACH substance restrictions and CE marking mandates elevate compliance costs for piezoelectric ceramic formulations in high-temperature sensors. EU F-Gas Regulation drives hermetic sensor demand for CO₂ and hydrocarbon refrigerant handling. The Ruhr industrial belt and Baden-Württemberg automotive corridor anchor procurement volumes for EV battery management systems.
China
MIIT directives and GB standards mandate domestic certification for sensors deployed in national infrastructure projects. Dual carbon goals accelerate hydrogen refueling station buildouts requiring ultra-high-pressure measurement. Shanghai and Hefei wafer foundry clusters localize MEMS supply chains for domestic EV platforms.
Japan
METI carbon neutrality roadmaps create demand for ultra-high-pressure sensors in hydrogen infrastructure compressors and storage vessels. JIS standards govern industrial automation sensor interoperability. The Chubu region around Nagoya and Kanto manufacturing belt concentrate procurement for aerospace turbine monitoring applications.
India
PLI scheme incentives for automotive components attract tier-two sensor suppliers to Pune and Chennai industrial corridors. BIS certification requirements fragment market access for non-domestic entrants. The Delhi-Mumbai Industrial Corridor and Tamil Nadu automotive cluster drive cost-competitive export manufacturing expansion.
Absolute Pressure Sensor Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers. The market structure exhibits moderate consolidation at the premium end and fragmentation in volume segments. Three archetypes dominate: semiconductor fabricators leveraging MEMS lithography scale, industrial automation conglomerates controlling distribution channels, and specialized ceramic sensor producers serving hazardous environment certifications. M&A activity concentrates on wireless connectivity capabilities and ATEX/IECEx certification portfolios.
Among European semiconductor specialists, STMicroelectronics and Infineon Technologies occupy positions defined by MEMS fabrication scale and piezoelectric variant expertise respectively. Honeywell International exemplifies the diversified industrial conglomerate archetype with channel control in North American process automation. These three entities represent distinct competitive vectors: silicon-based volume manufacturing, high-temperature aerospace qualification, and integrated automation system distribution.
| Leading Market Players |
|---|
| STMicroelectronics |
| Infineon Technologies |
| Honeywell International |
| Texas Instruments |
| ABB Ltd. |
| Robert Bosch GmbH |
| Amphenol Advanced Sensors |
| Setra Systems |
| NXP Semiconductors |
| Others |
Supply Flow & Price Mechanics
Silicon carbide MEMS substrate adoption is compressing thermal envelope costs while concentrating premium-tier production in German and Japanese fabrication clusters. This material transition simultaneously elevates performance benchmarks for aerospace procurement and fragments supply chains across legacy silicon and emerging wide-bandgap semiconductor tiers.
Pricing Analysis
Capacity additions in China's Shanghai and Hefei wafer foundry clusters are reshaping price floors for piezoresistive MEMS elements. Three-tier pricing structure across ATEX-certified premium, industrial-standard, and economy automotive tiers reflects certification burden and volume scale differentiation. Cost compression in EV battery management sensors intensifies because tier-one suppliers consolidate procurement through multi-protocol platform requirements. Automotive electrification buyers exhibit highest price sensitivity, while aerospace qualification programs retain lowest sensitivity due to FAA TSO-C88b certification barriers.
Supply Chain Analysis
Returns and refurbishment flows for failed industrial transmitters concentrate in German Ruhr belt service centers, creating reverse-logistics nodes that anchor European aftermarket value capture. Taiwan and South Korea control critical 200mm SOI wafer supply, while China and Germany dominate MEMS packaging and calibration. Raw material dependencies rest on high-purity silicon substrates, ceramic alumina diaphragms, and lead zirconate titanate crystals. Single-source vulnerability in Taiwanese substrate production threatens input cost stability. Distribution runs through integrated automation vendors including Siemens, Emerson, and Yokogawa networks that displace direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS lithography scale economies and GaN-compatible package premiums are expanding margin capture for qualified suppliers. Automotive electrification volume and aerospace thermal performance tiers create divergent profitability arcs across technology investment profiles.
For Market Incumbents: Hedge silicon wafer cost volatility through long-term offtake agreements with Taiwanese substrate producers. Deepen backward integration into ceramic capacitive membrane production to offset REACH cadmium reformulation delays. Channel control in North American process automation remains defensible against emerging wireless-native competitors.
For New Entrants and Emerging Players: Capture India's PLI scheme incentives for automotive component assembly in Pune and Chennai corridors. Wireless HART and IO-Link protocol expertise opens predictive maintenance revenue models in greenfield chemical processing deployments. Target optical fiber-Bragg-grating transducers for MRI suite and 800V EV architectures where EMI immunity commands premium positioning.
For Investors and Strategic Acquirers: Valuations sit cheapest among tier-two ceramic sensor specialists with ATEX/IECEx certification portfolios but limited wireless connectivity capabilities. Five-to-ten year viability hinges on hydrogen infrastructure buildout acceleration under Japan METI and China dual carbon mandates. Monitor EPA methane rule enforcement intensity and semiconductor export control expansion as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Scale-Up | Sub-micron etching investments in Shanghai and Hefei localize supply chains for domestic EV battery management. |
| GaN-Compatible Package Development | Safran and Rolls-Royce procurement divisions now specify wide-bandgap sensors for turbine blade tip clearance monitoring. |
| Wireless Connectivity Acquisition | IO-Link and Wireless HART capabilities enable predictive maintenance revenue models in German chemical park deployments. |
| ATEX/IECEx Certification Portfolio Build | Hazardous area approvals for Permian Basin compressor stations accelerate replacement cycle capture under EPA methane rules. |
| Hydrogen Infrastructure Partnership | METI carbon neutrality mandates in Japan create ultra-high-pressure sensor demand for refueling station compressors. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MEMS process engineers, tier-one automotive procurement directors, aerospace qualification program managers, and industrial automation system integrators with secondary validation against SEC filings, EPA regulatory dockets, EU F-Gas implementation reports, and China MIIT directive documents. Bottom-up sensor shipment estimates and top-down end-use market sizing were triangulated to constrain projection variance.
Historical reference periods anchored the forecast window through the analysis window, with segmentation modeling across product type, end-use vertical, connectivity protocol, and application. CAGRs were derived from fitted growth curves incorporating automotive electrification sensor count multiplication, REACH substance restriction compliance cost trajectories, and semiconductor fabrication cluster localization patterns.
Underlying measurement precision varies by segment; silicon MEMS automotive volumes carry tighter precision than optical fiber-transducer healthcare adoption. Forecasts reflect documented assumptions about regulatory enforcement intensity and substrate supply continuity. Practitioners should monitor EPA methane rule expansion, EU F-Gas refrigerant phase-down schedules, and China GB standards domestic certification mandates for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market