
 Earth and Space Mining Sensors Market | 2026-2036
Earth and Space Mining Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Earth and Space Mining Sensors Market Foresight
The gap between radiation-hardened space-grade sensors and terrestrial mining units is shifting procurement criteria across the industry. Honeywell International leverages decades of aerospace heritage to dominate high-reliability orbital applications. Rockwell Automation competes through integrated control platforms that merge sensor data with autonomous haulage systems. STMicroelectronics anchors the supply chain for MEMS-based proximity and inertial modules used in both domains.
Earth and space mining sensors comprise transducer assemblies engineered to withstand extreme thermal cycling, vacuum exposure, and particulate abrasion while detecting proximity, moisture, chemical composition, temperature, and structural integrity. These devices typically operate across temperature ranges from minus 180 to plus 120 degrees Celsius and rely on hermetic sealing with titanium or Inconel housings for lunar and asteroid environments. Their primary purpose is to enable autonomous resource identification, extraction monitoring, and crew safety in off-world operations and deep-earth deposits. Chemical sensors and proximity sensors capture the dominant share of current revenue as legacy mining operations prioritize hazard detection and collision avoidance. IoT technology and wireless technology represent the fastest-expanding technology segments as operators demand real-time telemetry from distributed drill heads and orbital prospecting platforms. Government agencies and research institutions concentrate margin pools through long-duration contracts for demonstration missions and technology validation.
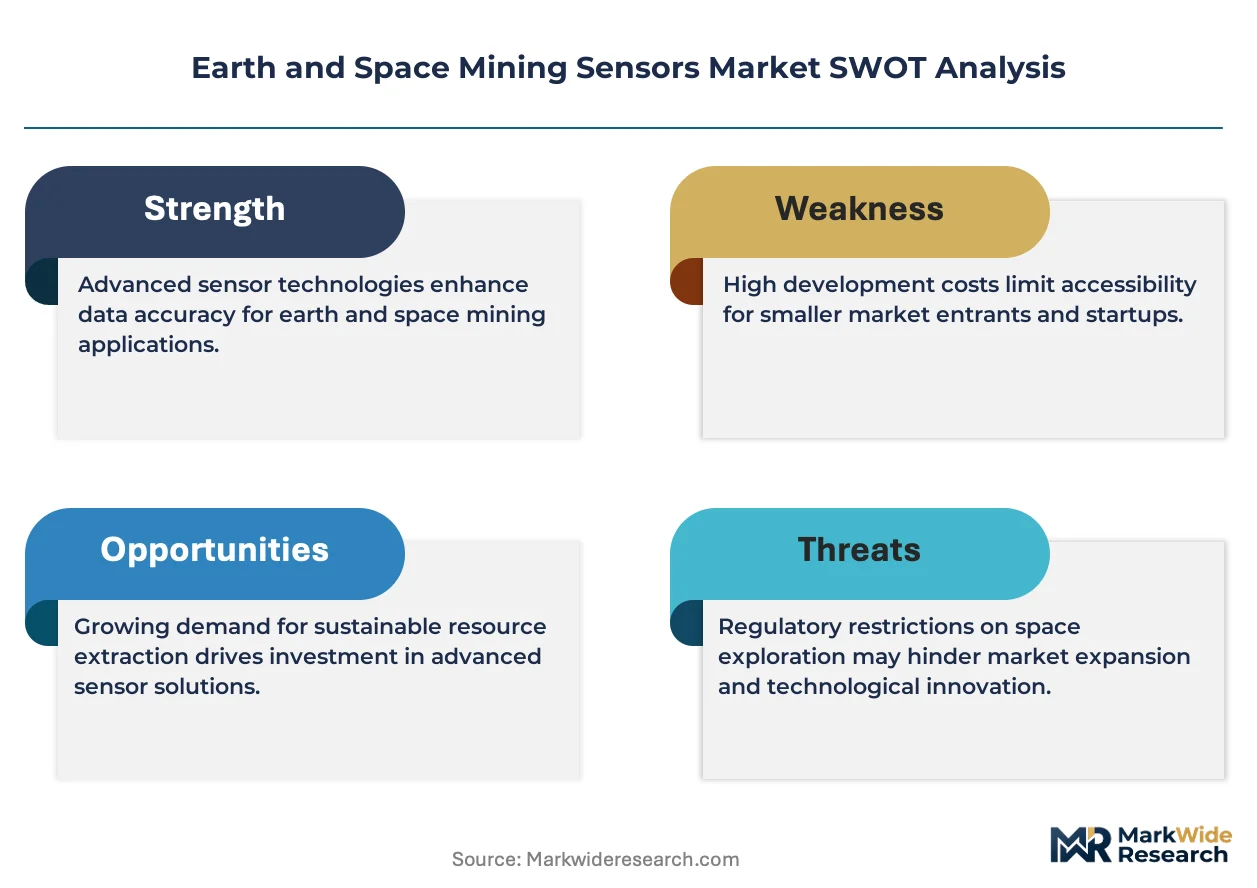
The US FAA and NASA set qualification benchmarks for space-rated sensor hardware, while the EPA and OSHA govern terrestrial deployment standards for chemical exposure and worker safety. The EU Space Surveillance and Tracking framework and REACH chemical registration requirements shape European procurement specifications for orbital and ground-based systems. Stakeholders must monitor how dual-use export controls and emerging national space resource legislation redefine market access for cross-border sensor shipments.
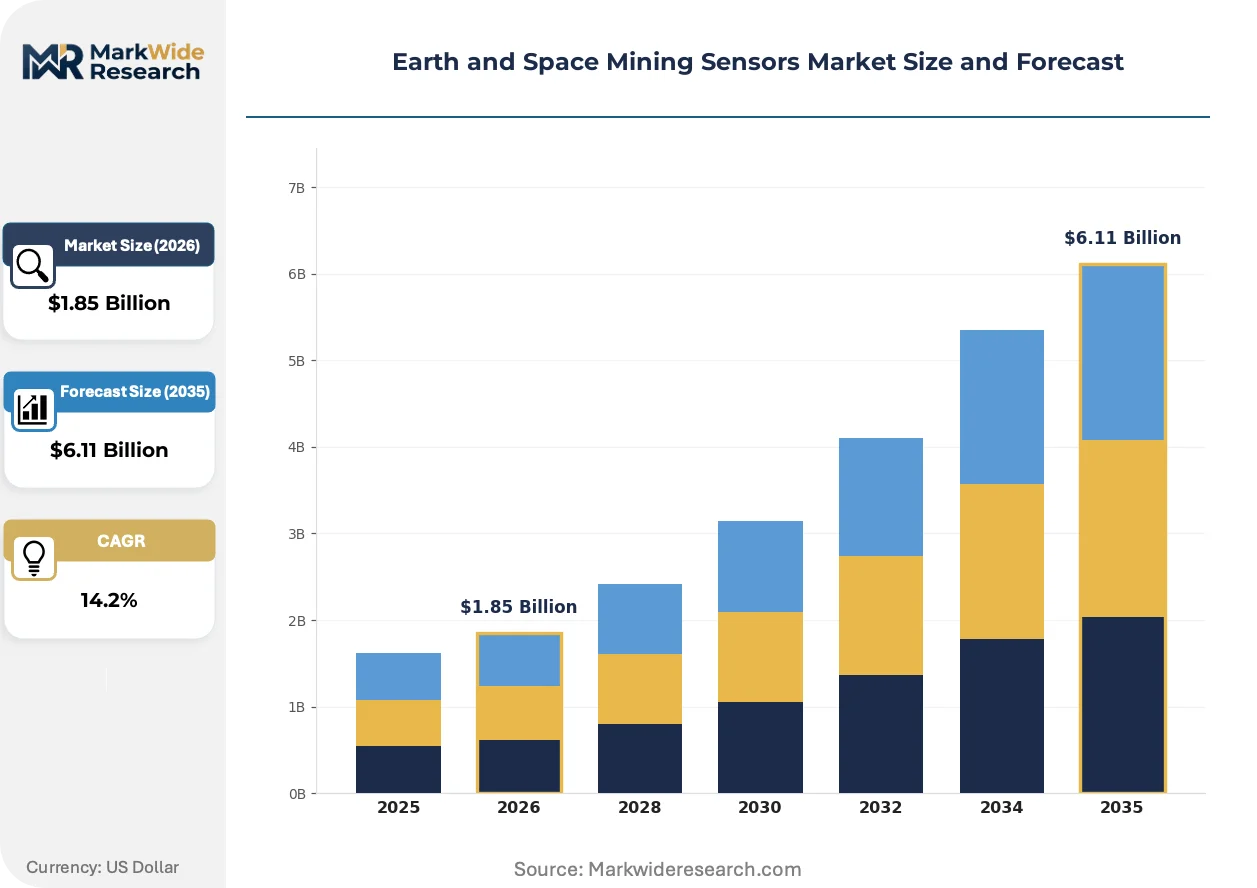
Market Dynamics
Autonomous extraction operations are compressing the procurement cycle for radiation-hardened sensor suites as mining corporations and space agencies converge on unified hardware specifications. This structural force is dissolving the traditional wall between terrestrial and orbital sensor supply chains.
Growth Catalysts
- Lunar resource exploration programs:NASA's Artemis initiative and affiliated national missions are accelerating qualification timelines for vacuum-rated proximity sensors and chemical composition analyzers destined for polar ice prospecting.
- REACH chemical registration:European manufacturers must deploy real-time chemical sensors for hazardous substance monitoring, creating mandated refresh cycles for legacy detection equipment in deep-earth extraction sites.
- MEMS miniaturization:Semiconductor fabrication advances are shrinking inertial measurement units to gram-scale packages suitable for swarm robotics in asteroid proximity operations.
Market Restraints
- Titanium and Inconel supply concentration:Hermetic housing fabrication depends on aerospace-grade alloy suppliers concentrated in United States and Japanese specialty metals markets, exposing sensor OEMs to price volatility and allocation constraints.
- Radiation-hardening yield limitations:Space-qualified electronics require triple-redundant architectures and specialized foundry processes that consume 40-60% more die area than commercial equivalents, compressing margins on volume contracts.
- Dual-use export control friction:US International Traffic in Arms Regulations and EU dual-use lists impose licensing delays on shipments of high-precision inertial sensors capable of guidance applications, fragmenting supplier-customer relationships across jurisdictions.
Strategic Opportunities
- Underpenetrated asteroid prospecting segment:Japanese and Luxembourgish regulatory frameworks for space resource utilization are creating first-mover procurement channels for spectroscopic sensors targeting carbonaceous chondrite composition mapping.
- IoT-wireless convergence:Integration of LoRaWAN telemetry with battery-free vibration-harvesting power systems is enabling permanently installed sensor networks in deep mine shafts previously inaccessible to wired infrastructure.
- US Inflation Reduction Act critical minerals provisions:Domestic content incentives for rare earth and lithium extraction are redirecting capital toward sensor-rich autonomous operations in Nevada and Wyoming deposits.
Industry Challenges
- Radiation effects engineering talent scarcity:The specialized workforce capable of designing single-event upset mitigation for FPGA-based sensor controllers is concentrated at a handful of national laboratories and aerospace primes, constraining product development velocity.
- Multi-domain certification stacking:Sensors destined for lunar surface deployment must sequentially satisfy NASA technical standards, FAA launch vehicle integration requirements, and OSHA terrestrial safety benchmarks, extending qualification timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earth and Space Mining Sensors Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proximity Sensors, Moisture Sensors, Chemical Sensors, Temperature Sensors Technology: Laser Technology, RFID Technology, Wireless Technology, IoT Technology End User: Aerospace Companies, Mining Corporations, Government Agencies, Research Institutions Application: Resource Exploration, Environmental Monitoring, Safety Management, Operational Efficiency |
| Companies Covered | Honeywell International, Rockwell Automation, STMicroelectronics, Texas Instruments, Amphenol Corporation, Siemens, DENSO Corporation, Robert Bosch GmbH, Singapore Technologies Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earth and Space Mining Sensors Market Shifts & Advancements
Sensor fusion architectures are collapsing the distinction between environmental monitoring, navigation, and resource identification into unified hardware platforms. This convergence is redrawing competitive boundaries between specialized component suppliers and integrated system providers.
Quantum-enhanced gravimetric sensing is rewriting the economics of subsurface and subsatellite prospecting. These cryogenic atom interferometer systems detect density variations at microgal resolution, enabling direct ore body mapping without invasive drilling. Australian iron ore operators and Canadian potash miners are piloting terrestrial variants, while NASA-funded consortia adapt the technology for lunar mass concentration detection. The structural consequence is compressing exploration timelines from multi-year geophysical campaigns to single-season sensor deployments.
EU Space Surveillance and Tracking framework mandates are tightening debris avoidance requirements for orbital mining platforms. Operators must now carry redundant proximity sensors with independent processing chains, effectively doubling sensor count per spacecraft. European launch providers and satellite servicing ventures are responding by pre-qualifying multi-sensor suites from single vendors to streamline integration testing. This regulatory pressure is consolidating procurement decisions around established aerospace heritage suppliers.
Buyer concentration among national space agencies and tier-one mining conglomerates is forcing sensor vendors to unbundle hardware from embedded software and calibration services. Large operators now demand API-accessible raw data streams to feed proprietary autonomy stacks, displacing turnkey packaged solutions. This pattern is most visible in United States lunar program procurements and Australian autonomous haulage fleet expansions, where systems integrators specify sensor-agnostic interfaces.
Earth and Space Mining Sensors Market Segmentation
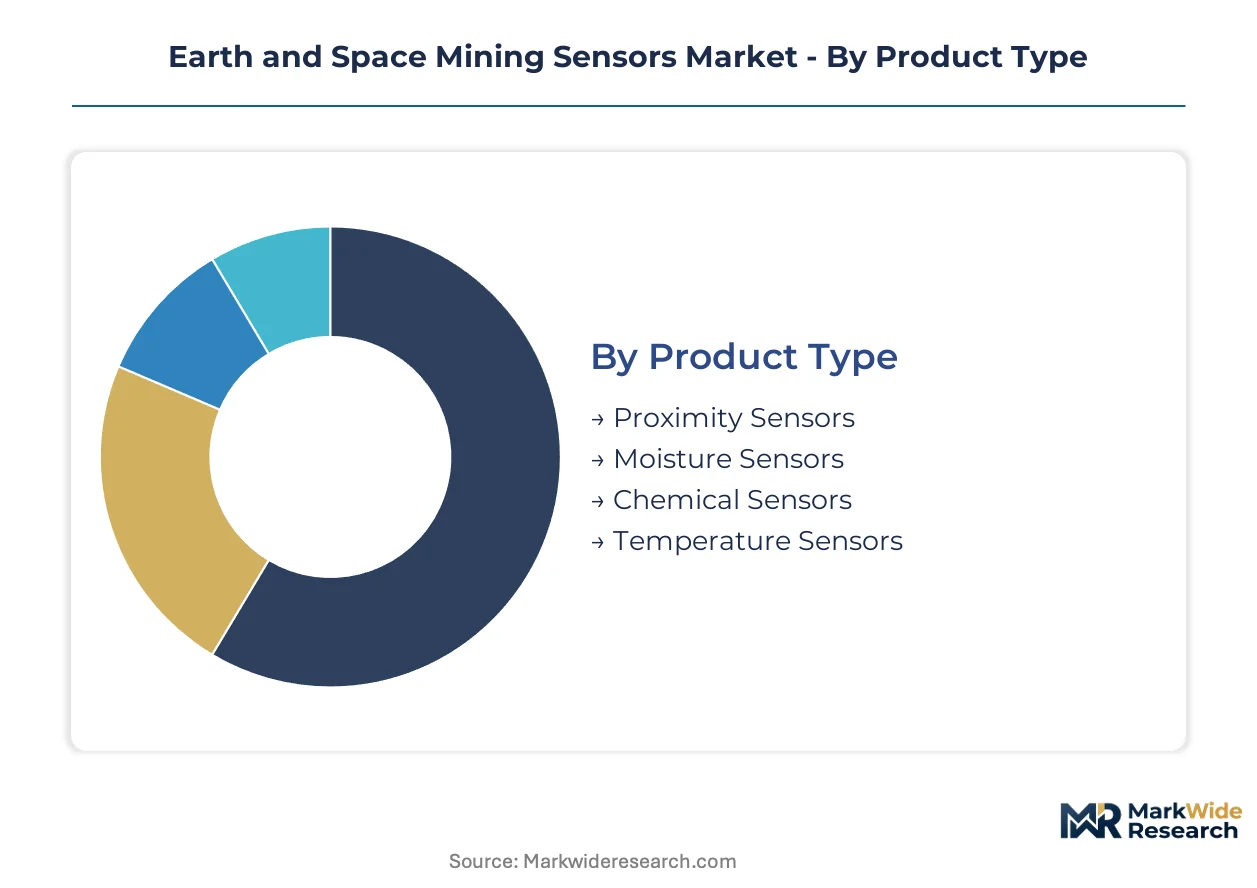
Segmentation in the Earth and Space Mining Sensors Market reveals how capital deployment, regulatory mandates, and operational environments reshape procurement priorities. Understanding these dimensions exposes where sensor OEMs must concentrate engineering resources and certification investments.
Product Type:
Capital intensity varies sharply across product categories, with radiation-hardened chemical analyzers requiring multi-million-dollar qualification programs while standard proximity modules deploy faster.
- Chemical Sensors:These devices detect hazardous gas concentrations, mineral composition, and volatile organic compounds through electrochemical or spectroscopic methods. Mining corporations in Wyoming and Nevada deploy real-time chemical monitoring for lithium brine extraction, driven by EPA worker safety mandates and the US Inflation Reduction Act's domestic content incentives.
- Proximity Sensors:Ultrasonic, LiDAR, and capacitive variants enable collision avoidance in autonomous haulage fleets and orbital debris tracking. NASA's Artemis program accelerates procurement of vacuum-rated proximity units for lunar surface navigation, where hermetic sealing and radiation tolerance dominate specification sheets.
- Moisture Sensors:Capacitive and resistive probes measure substrate water content for optimal extraction timing in deep-earth operations.
- Temperature Sensors:Thermocouple and RTD assemblies monitor thermal cycling extremes from minus 180 to plus 120 degrees Celsius in off-world environments.
Chemical sensors absorb the bulk of installed capacity; proximity sensors are expanding most quickly.
Technology:
Application environment dictates technology selection, with orbital operations demanding hardened architectures and terrestrial mines prioritizing network scalability.
- IoT Technology:Edge computing platforms with distributed sensor nodes enable real-time telemetry from autonomous drill heads and processing equipment. Australian iron ore operators and Canadian potash miners deploy IoT sensor networks for predictive maintenance, compressing downtime intervals through machine-learning-driven anomaly detection.
- Wireless Technology:LoRaWAN and mesh networking protocols eliminate cabling infrastructure in deep shafts and mobile equipment. Battery-free vibration-harvesting power systems now enable permanently installed networks in previously inaccessible geology, with Nevada lithium deposits piloting these architectures.
- Laser Technology:LiDAR and spectroscopic systems provide high-precision distance measurement and material identification for resource mapping.
- RFID Technology:Passive and active tagging systems track equipment location and maintenance history across distributed mining operations.
IoT technology commands the largest deployment base; wireless technology is climbing the fastest as power-harvesting innovations mature.
End User:
Customer type shapes contract structures, with government agencies demanding multi-year validation programs and mining corporations prioritizing rapid integration.
- Government Agencies:NASA, the US FAA, and affiliated national space programs drive qualification standards for radiation-hardened hardware. These entities concentrate procurement in multi-sensor demonstration missions with 18-24 month certification timelines, creating margin pools through long-duration technology validation contracts.
- Mining Corporations:Tier-one extractive operators in Australia, Canada, and the United States specify sensor-agnostic interfaces to feed proprietary autonomy stacks. Autonomous haulage fleet expansions in Western Australia and Nevada redirect capital toward integrated sensor-control platforms.
- Aerospace Companies:Launch providers and satellite servicing ventures pre-qualify multi-sensor suites to streamline spacecraft integration testing.
- Research Institutions:Universities and national laboratories pilot quantum-enhanced gravimetric systems and MEMS miniaturization for future operational deployment.
Mining corporations represent the largest volume purchaser; government agencies are gaining share fastest through Artemis-affiliated lunar programs.
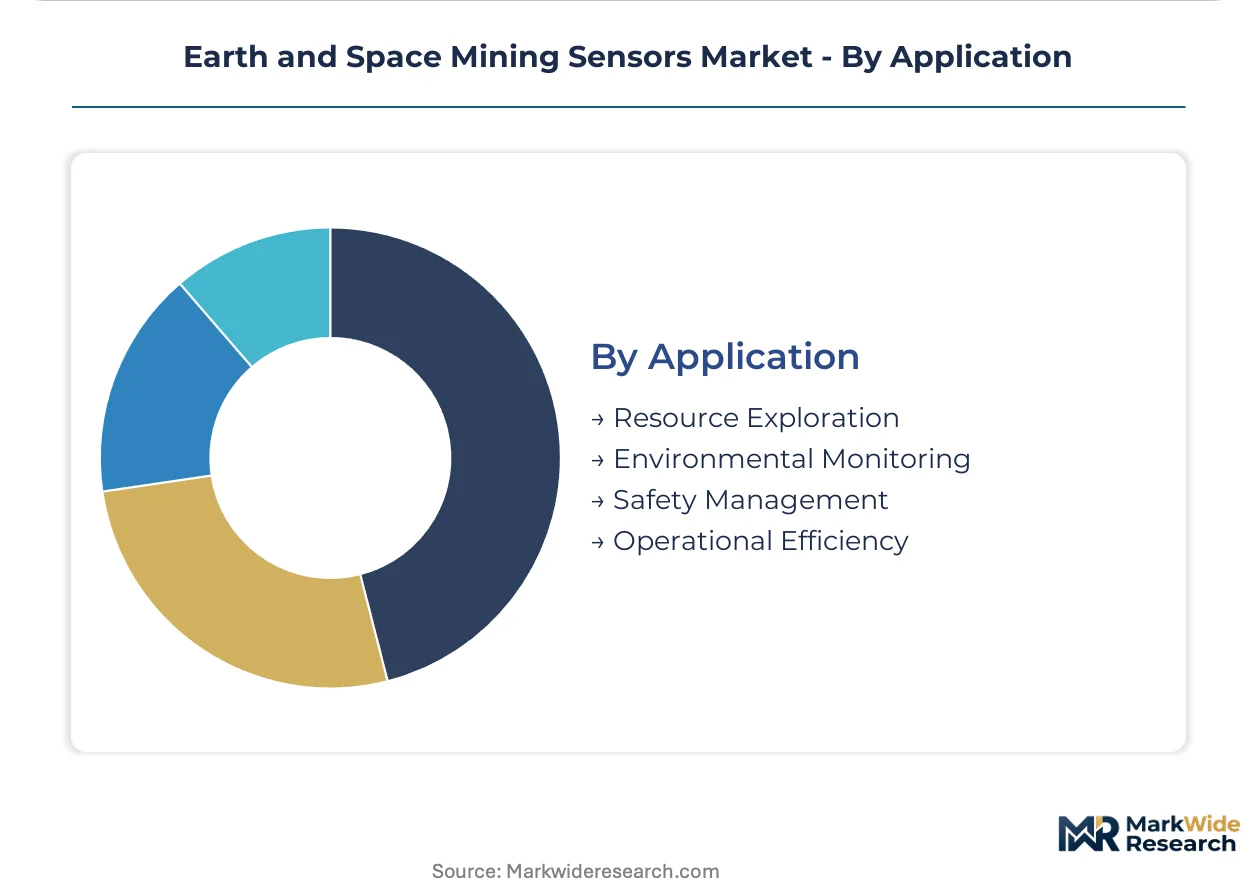
Application:
Use-case maturity determines pricing power, with established safety applications facing commoditization while exploration functions retain premium positioning.
- Resource Exploration:Gravimetric, spectroscopic, and geophysical sensors identify ore bodies and off-world ice deposits without invasive drilling. Quantum-enhanced atom interferometer systems piloted by Australian operators and NASA-funded consortia detect density variations at microgal resolution, collapsing exploration timelines from multi-year campaigns to single-season deployments.
- Safety Management:Hazard detection and collision avoidance systems represent the most penetrated application, with chemical exposure monitoring mandated by OSHA and REACH requirements. European manufacturers face compelled refresh cycles for legacy detection equipment.
- Environmental Monitoring:Sensors track particulate emissions, water quality, and ecosystem disruption for regulatory compliance and community relations.
- Operational Efficiency:Condition monitoring and predictive maintenance systems optimize equipment utilization and energy consumption.
Safety management retains the deepest installed base; resource exploration shows the steepest expansion trajectory as quantum sensing commercializes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston's Johnson Space Center corridor concentrates NASA procurement for lunar-qualified sensor hardware, while Perth's autonomous mining technology cluster drives terrestrial demand for integrated detection systems.
United States
NASA's Artemis program and Nevada lithium extraction operations drive dual-use sensor procurement. The FAA and EPA impose overlapping certification requirements for space-rated hardware and chemical exposure monitoring. Houston's space technology corridor hosts qualification facilities for vacuum-rated proximity sensors destined for polar ice prospecting.
Australia
Western Australia's autonomous haulage fleets and Pilbara iron ore operations deploy predictive maintenance sensor networks. The country's national mining regulator mandates real-time hazard detection systems for deep-earth extraction. Perth anchors development of IoT-enabled drill head monitoring systems for remote operations.
China
Domestic rare earth processing and lunar exploration programs accelerate MEMS sensor fabrication. MIIT standards govern industrial IoT deployment in mining operations. The Yangtze River Delta concentrates foundry capacity for radiation-tolerant proximity modules.
Germany
REACH chemical registration mandates force refresh cycles for legacy detection equipment in potash and lignite operations. The country's national mining regulator enforces worker safety sensor requirements. North Rhine-Westphalia hosts integration facilities merging sensor data with autonomous control platforms.
Japan
Asteroid prospecting missions and domestic specialty metals supply chains shape sensor demand. METI programs fund miniaturized inertial measurement units for swarm robotics. Nagoya's aerospace manufacturing corridor produces hermetic housings from titanium alloys for orbital applications.
Earth and Space Mining Sensors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sensor value chain. Foundry-dependent semiconductor houses invest in radiation-hardened process nodes, while fabless specialists license IP for MEMS architectures. The market structures around three archetypes: aerospace heritage primes with multi-decade qualification track records, industrial automation conglomerates with integrated control platforms, and component specialists dominating specific transducer categories. Competitive moves concentrate on strategic partnerships for multi-domain certification stacking and portfolio diversification into adjacent environmental monitoring segments.
Among aerospace heritage primes, Honeywell International and Rockwell Automation occupy positions spanning space-rated hardware and terrestrial industrial systems. STMicroelectronics anchors the component specialist tier through MEMS fabrication capabilities serving both domains. These three exemplify how qualification depth and manufacturing scale create defensive positions against newer entrants lacking multi-decade certification relationships with NASA and the FAA.
| Leading Market Players |
|---|
| Honeywell International |
| Rockwell Automation |
| STMicroelectronics |
| Texas Instruments |
| Amphenol Corporation |
| Siemens |
| DENSO Corporation |
| Robert Bosch GmbH |
| Singapore Technologies Engineering |
| Others |
Supply & Pricing Matrix
NASA's Artemis procurement specifications for radiation-hardened proximity sensors are compressing supplier margins as qualification timelines stretch to 24 months, forcing foundries to absorb upfront certification costs that recoup only on multi-year production runs. This demand-side pressure concentrates pricing power among aerospace heritage primes with existing NASA technical standard relationships, while tier-two vendors face exclusion from lunar program supply chains.
Pricing Analysis
Value-based pricing anchored to mission-critical uptime guarantees dominates Artemis-affiliated contracts, where sensor failure carries payload-loss exposure measured in hundreds of millions. Three-tier pricing structure across heritage-qualified, commercial-space-grade, and terrestrial-industrial levels separates NASA prime contractors from commercial launch providers and mining operators. Cost compression in commercial space-grade tiers is intensifying as launch cadence expansion attracts MEMS sensor specialists from automotive markets. Mining corporations show highest price sensitivity, prioritizing per-unit acquisition cost over qualification depth; government agencies accept 3-4x premiums for triple-redundant architectures.
Supply Chain Analysis
Freight costs for titanium and Inconel hermetic housings from Japanese and United States specialty metals markets add 15-20% landed cost premiums for European sensor assemblers, compressing margins on volume terrestrial contracts. Fabrication draws from United States, Japan, and German aerospace-grade alloy suppliers, with MEMS die sourcing concentrated in Taiwan and South Korea. Single-source vulnerability in radiation-hardened foundry capacity at United States national laboratories constrains space-qualified output expansion. Distribution runs through direct OEM relationships for space hardware, while terrestrial mining sensors move through industrial automation distributors with regional service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around multi-domain certification capabilities, with 18-24 month qualification stacking timelines forcing capital-constrained specialists toward acquisition by aerospace primes or exit.
For Market Incumbents: To counter MEMS miniaturization threats from automotive semiconductor houses, Honeywell International and Rockwell Automation should deepen backward integration into titanium hermetic housing fabrication and captive radiation-hardened foundry capacity. Certification investment in sequential NASA-FAA-OSHA stacking protocols creates defensive moats against fabless entrants lacking multi-decade agency relationships. For New Entrants and Emerging Players: Begin with asteroid prospecting sensor suites for Japanese and Luxembourgish regulatory frameworks, where first-mover procurement channels remain underdeveloped and qualification requirements lag lunar programs. Target battery-free vibration-harvesting wireless networks for Nevada lithium deposits, selling through industrial IoT system integrators rather than direct mining procurement. For Investors and Strategic Acquirers: The window for entry favors fabless MEMS designers with radiation-tolerant IP libraries and existing automotive volume relationships, positioned for rapid space qualification via acquisition of heritage prime certification teams. Watch NASA Artemis contractor downselect announcements as inflection signal for which qualification pathways will dominate procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Domain Certification Stacking | Sequential NASA-FAA-OSHA qualification compresses competitive field to heritage primes with existing agency relationships. |
| Backward Integration into Hermetic Housing | In-house titanium and Inconel fabrication insulates margins from Japanese specialty metals allocation constraints. |
| API-Accessible Raw Data Unbundling | Sensor-agnostic interfaces align with Australian and United States mining corporation demands for proprietary autonomy stack feeding. |
| Battery-Free Vibration-Harvesting Deployment | LoRaWAN-enabled networks penetrate Nevada lithium deposits previously inaccessible to wired infrastructure. |
| Quantum-Enhanced Gravimetric Sensing Partnership | NASA-funded consortia and Australian iron ore operators pilot cryogenic atom interferometer systems for single-season ore body mapping. |
Research Methodology
Document review covered NASA technical standards, FAA launch vehicle integration requirements, EPA and OSHA terrestrial safety benchmarks, and ECHA REACH chemical registration frameworks, complemented by interviews with sensor procurement leads at tier-one mining corporations, radiation effects engineering directors at aerospace primes, MEMS fabrication specialists at semiconductor foundries, and national laboratory qualification program managers. Secondary validation drew from SEC filings of industrial automation conglomerates, customs data for titanium and Inconel alloy trade flows, and project announcement databases for Artemis-affiliated lunar missions. Bottom-up unit shipment estimates across chemical, proximity, moisture, and temperature sensor categories were triangulated against top-down capital expenditure projections from government space agencies and mining corporation autonomy investment disclosures.
Segment-level outputs across product type, technology, end user, and application dimensions were generated through driver-linked elasticity modeling, with CAGRs derived from scenario-weighted regression against lunar program funding trajectories and autonomous haulage fleet deployment schedules. Quantum sensing commercialization timelines, MEMS miniaturization yield curves, and dual-use export control licensing velocity served as industry-specific forecast inputs throughout the projection horizon.
Underlying measurement precision varies by segment; government agency procurement data carries tighter precision than speculative asteroid prospecting equipment demand. Forecasts reflect assumptions regarding Artemis program schedule adherence, radiation-hardened foundry capacity expansion, and REACH enforcement intensity that could revise trajectories if policy shifts or technical delays emerge. Stakeholders should weight assumptions against their own operating context and qualification backlog visibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Battery Free Wireless Sensor Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Latin America Proximity Sensors Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market