
 Smart Control Socket Market | 2026-2036
Smart Control Socket Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Control Socket Market Insights
Market Context
China is reshaping competitive dynamics through scaled electronics manufacturing clusters in Shenzhen and Dongguan. TP-Link Technologies Co., Ltd. leverages vertical integration across chipset sourcing and firmware development to sustain cost leadership in Wi-Fi-enabled units. Xiaomi Inc. anchors volume distribution through its Mi Home ecosystem, while Belkin International, Inc. differentiates via Matter protocol certification and premium channel positioning in North American retail.
Technical Definition and Segment Structure
A smart control socket is an intelligent electrical outlet enabling remote switching, energy monitoring, and automated scheduling through embedded wireless communication modules operating on 110-240V AC circuits. Smart plugs dominate unit volume due to plug-and-play deployment, while Zigbee-enabled wall-mounted installations command higher margins through embedded architectural integration and mesh network reliability. Wi-Fi technology leads residential penetration for direct router connectivity, whereas Z-Wave specializes in commercial building automation where IT departments prioritize segregated network topology.
Regulatory Environment
EU F-Gas Regulation and CE marking requirements shape product compliance for thermal management components, while FCC Part 15 governs radio frequency emissions in the United States and China's MIIT certifies wireless transmission protocols. Stakeholders must monitor evolving cybersecurity mandates from ETSI EN 303 645 and NIST IoT guidelines as these frameworks increasingly dictate market access rather than voluntary differentiation.
Market Dynamics
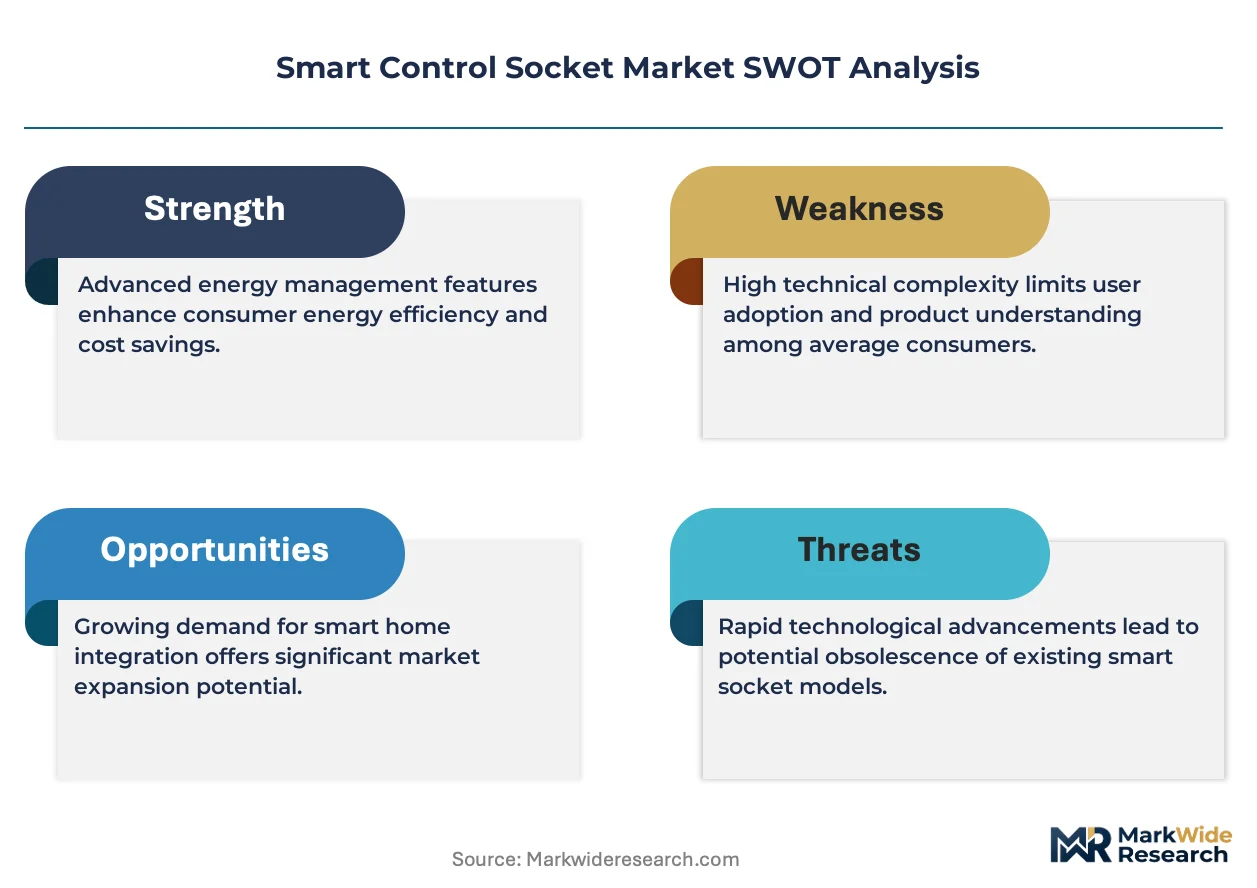
The smart control socket sector is bifurcating between commodity Wi-Fi plug producers and premium embedded-system vendors as Matter protocol certification becomes a de facto gating mechanism for retail shelf access in developed markets.
Growth Catalysts
- EU Energy Efficiency Directives:Germany's building code amendments mandate intelligent load management in urban retrofit projects, accelerating replacement cycles for legacy electrical infrastructure.
- Mesh Network Reliability:Zigbee-enabled wall-mounted installations are gaining traction in commercial building automation where IT departments prioritize segregated network topology over direct router dependency.
- Shenzhen-Dongguan Electronics Clusters:Scaled manufacturing concentration in China's Pearl River Delta compresses component costs for Wi-Fi modules and embedded firmware development.
Market Restraints
- Silicon Supply Concentration:Semiconductor fabrication for wireless communication chipsets remains concentrated among Taiwanese and South Korean foundries, exposing vendors to geopolitical supply disruptions.
- Radio Frequency Certification Friction:FCC Part 15 compliance in the United States and MIIT certification in China impose divergent testing protocols that extend product launch timelines by 4-8 months.
- Interoperability Substitution:Whole-home energy management systems with native outlet intelligence threaten standalone smart plug demand in new residential construction.
Strategic Opportunities
- Underpenetrated Secondary Cities:India's tier-2 and tier-3 urban centers exhibit minimal smart home penetration despite rising residential electricity consumption and grid instability.
- Commercial Building Retrofit Incentives:The US Inflation Reduction Act allocates tax credits for intelligent electrical infrastructure upgrades in multifamily housing and hospitality sectors.
- Matter-Zigbee Convergence:Dual-protocol chipsets enabling simultaneous Matter over Thread and legacy Zigbee compatibility are opening migration paths for installed-base upgrades without full hardware replacement.
Industry Challenges
- Cybersecurity Competency Scarcity:ETSI EN 303 645 and NIST IoT guideline compliance requires embedded firmware security expertise that remains concentrated among a narrow supplier base.
- Legacy Electrical Integration Complexity:Wall-mounted smart socket deployment in European buildings predating 1990 often requires incompatible junction box modifications that inflate installation labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Control Socket Market |
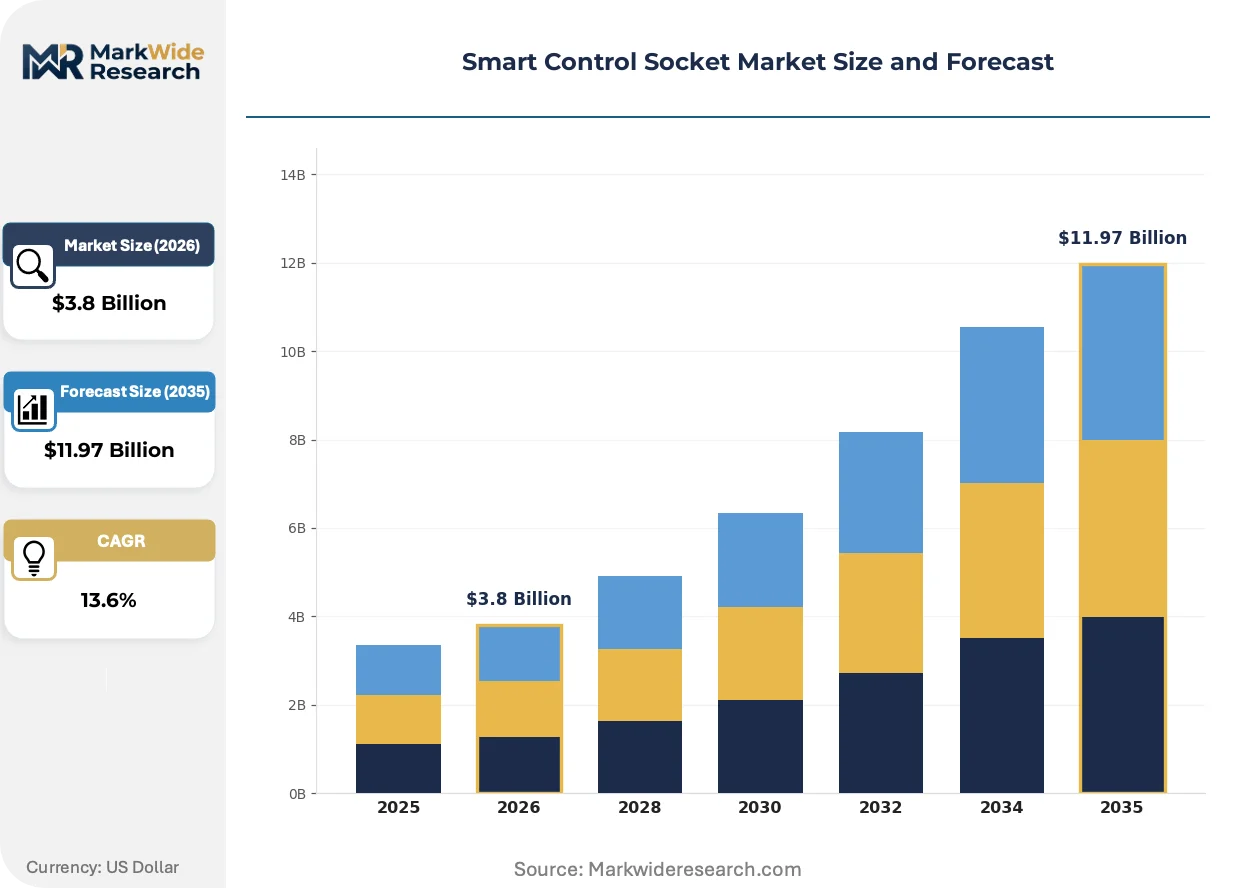
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Plug, Smart Power Strip, Smart Adapter, Smart Extension Cord Technology: Wi-Fi, Bluetooth, Zigbee, Z-Wave End User: Residential, Commercial, Industrial, Hospitality Installation: Plug-and-Play, Wall-Mounted, Embedded, Retrofit |
| Companies Covered | TP-Link Technologies Co., Ltd., Panasonic Corporation, Belkin International, Inc., D-Link Corporation, Xiaomi Inc., Leviton Manufacturing Co., Inc., EDIMAX Technology Co. Ltd., BroadLink Technology Co., Ltd., Etekcity Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Control Socket Market Trends and Innovations
Protocol standardization and edge computing migration are compressing the traditional hardware-software boundary in residential electrical infrastructure, creating new value capture opportunities beyond unit sales.
Edge AI inference engines are migrating from cloud-dependent architectures to on-device processing within smart sockets themselves. Residential buyers in Germany and the Netherlands are prioritizing local data processing to satisfy GDPR-aligned privacy preferences. This capability shift is migrating from premium architectural-grade installations toward mid-market retrofit products, compressing the feature differentiation window between tier-1 and tier-2 vendors.
ETSI EN 303 645 cybersecurity mandates are hardening from voluntary guidance to market-access preconditions across EU member states. Manufacturers must now document secure development lifecycle practices and vulnerability disclosure procedures before CE marking approval. Wall-mounted product categories face the steepest compliance burden due to permanent installation liability exposure and longer expected service lifespans.
Buyer evaluation criteria are elevating total-cost-of-ownership calculations over upfront hardware pricing in commercial procurement. Facility managers in US hospitality and healthcare verticals are unbundling installation, commissioning, and multi-year support into separate contract vehicles. This pattern is most pronounced in California and New York where labor union requirements and local electrical code variations complicate standardized product deployment.
Smart Control Socket Market Segmentation
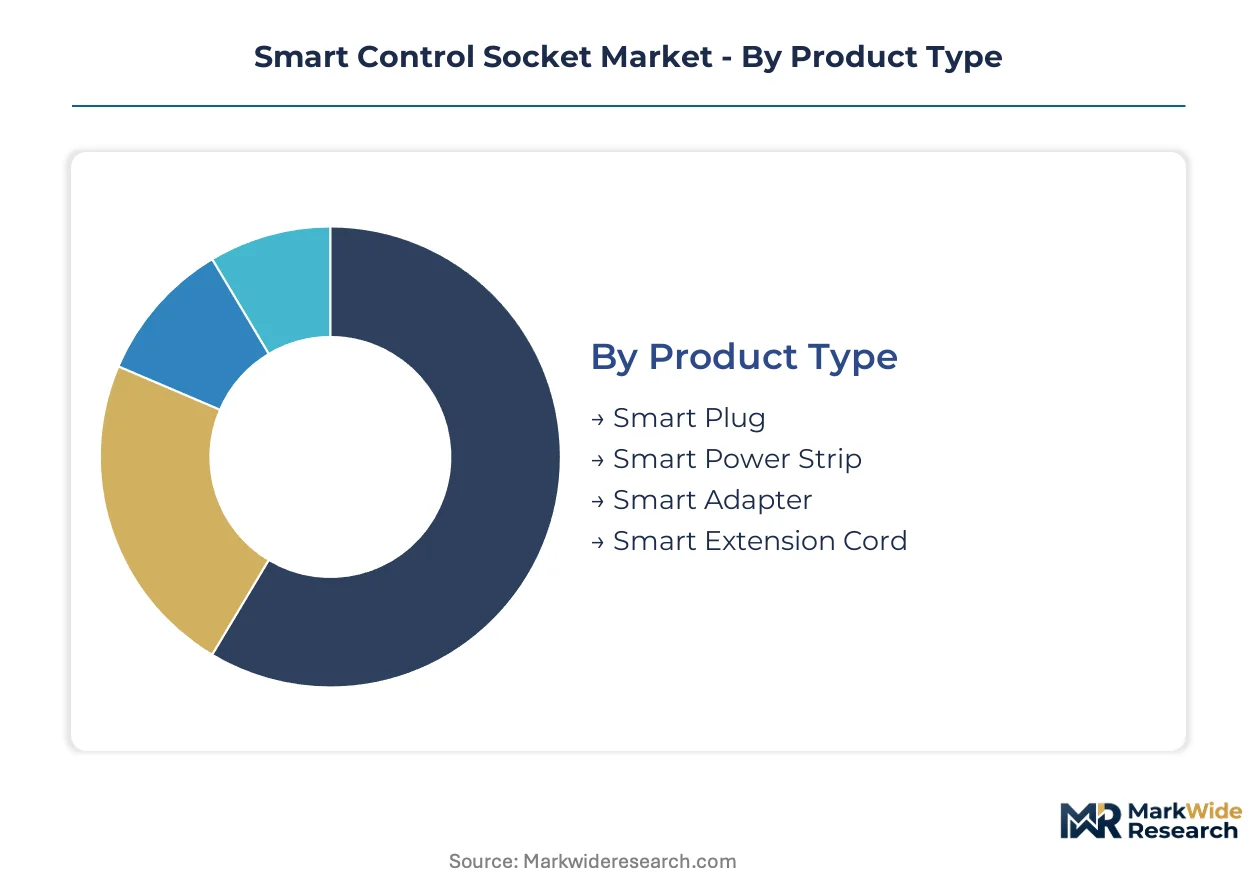
Smart control socket segmentation reveals how hardware form factors, wireless protocols, and deployment contexts create divergent margin profiles and competitive moats. Vendors must align R&D allocation with the specific technical requirements and purchasing behaviors governing each dimension.
Product Type:
Cost tier differentiation separates mass-market retrofit solutions from premium architectural-grade installations with embedded intelligence and extended service lifecycles.
- Smart Plug:Compact single-outlet units with integrated relay switching and basic energy monitoring. Demand concentrates in German urban rental markets where tenants require non-permanent retrofit solutions without landlord electrical modifications.
- Smart Power Strip:Multi-outlet bars with individual socket control and surge protection. Commercial co-working spaces in Shenzhen and Dongguan procurement offices favor these for flexible workstation reconfiguration without embedded wiring costs.
- Smart Adapter:Compact converters adding intelligence to existing dumb outlets. European hospitality procurement in Spain and Italy deploys these for seasonal capacity expansion in historic buildings with restricted electrical access.
- Smart Extension Cord:Corded multi-socket solutions with length flexibility. Residential garage and outdoor applications in US suburban markets drive replacement cycles for weather-exposed legacy units.
Smart plug commands the established base. The steepest expansion runs through smart power strip.
Technology:
Wireless protocol selection dictates network topology, power consumption, and interoperability certification requirements that shape vendor development roadmaps.
- Wi-Fi:Direct router connectivity without hub dependency using 2.4GHz bands. Residential buyers in India and Brazil prioritize immediate smartphone pairing over ecosystem complexity, though FCC Part 15 and MIIT certification friction extends launch timelines.
- Zigbee:Mesh networking with sub-1GHz penetration through building materials. German commercial building automation specifies these for segregated network topology where IT departments isolate IoT traffic from corporate data infrastructure.
- Bluetooth:Short-range pairing for proximity-based control without internet dependency. Japanese apartment dwellers leverage these for localized automation in dense urban RF environments with congested Wi-Fi spectrum.
- Z-Wave:Sub-GHz proprietary mesh with guaranteed interoperability certification. US multifamily housing developers specify these for standardized procurement across property portfolios requiring uniform property management platform integration.
Zigbee commands the established base. The steepest expansion runs through Wi-Fi.
End User:
Customer type determines procurement authority, total-cost-of-ownership calculation methods, and cybersecurity liability exposure.
- Residential:Individual consumers purchasing through retail or direct-to-consumer channels. German households responding to EU energy efficiency directives drive replacement of legacy metering infrastructure with intelligent load management.
- Commercial:Facility managers in office buildings and retail environments. US Inflation Reduction Act tax credits accelerate intelligent electrical infrastructure procurement in California and New York unionized construction markets.
- Industrial:Manufacturing facilities requiring ruggedized units with extended temperature tolerance. Shenzhen electronics clusters deploy these for equipment-level energy monitoring without production line shutdown for hardwired installation.
- Hospitality:Hotels and serviced apartments prioritizing guest experience standardization. Spanish and Italian boutique properties favor plug-and-play adapters to preserve historic interior fabric while adding modern amenity profiles.
Residential commands the established base. The steepest expansion runs through commercial.
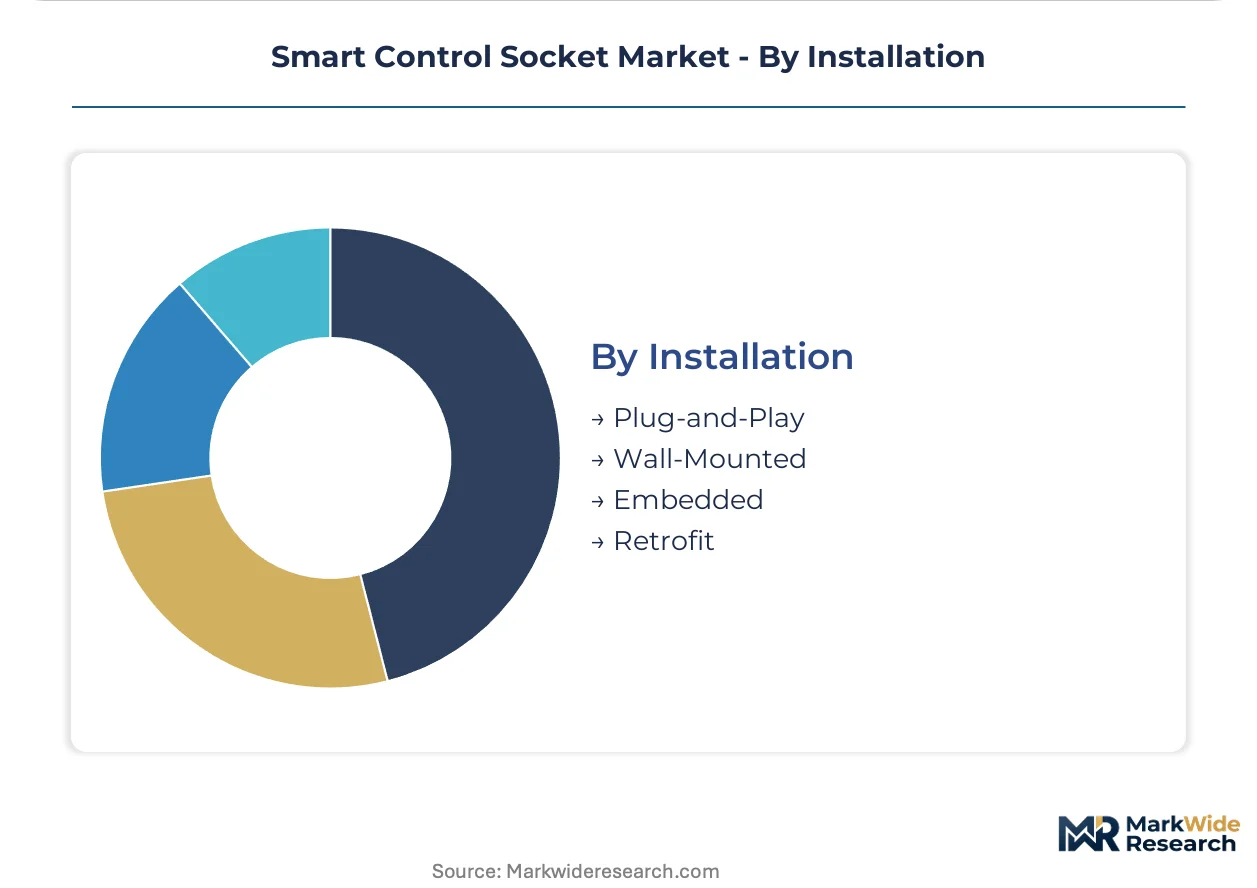
Installation:
Deployment method determines labor cost allocation, regulatory compliance burden, and product lifecycle liability exposure.
- Plug-and-Play:Portable units requiring no electrical trade labor. Indian tier-2 and tier-3 urban centers exhibit concentrated demand despite minimal smart home penetration, driven by grid instability and residential electricity consumption growth.
- Wall-Mounted:Permanent junction box replacement with embedded architectural integration. European buildings predating 1990 require incompatible junction box modifications that inflate German and Dutch installation labor costs.
- Embedded:Factory-integrated outlets in new construction electrical assemblies. US hospitality and healthcare verticals unbundle installation, commissioning, and multi-year support into separate contract vehicles in California and New York.
- Retrofit:Surface-mounted solutions avoiding junction box replacement. Dongguan manufacturing clusters produce these for Southeast Asian markets with aging electrical infrastructure and limited licensed electrician availability.
Plug-and-play commands the established base. The steepest expansion runs through wall-mounted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between retrofit-heavy European markets and first-time adoption in emerging Asian economies. Germany prioritizes embedded wall-mounted installations for energy compliance, while India concentrates demand in portable plug-and-play units addressing grid instability.
United States
Commercial building retrofits dominate procurement through Inflation Reduction Act tax credits for intelligent electrical infrastructure. FCC Part 15 certification requirements govern radio frequency emissions for all Wi-Fi-enabled units entering the market. California and New York facility managers unbundle installation and multi-year support contracts due to union labor requirements and local electrical code variations.
Germany
Urban rental markets drive plug-and-play smart plug demand where tenants require non-permanent solutions without landlord modifications. EU energy efficiency directives mandate intelligent load management systems in building code amendments for retrofit projects. The KBA and federal building authorities enforce CE marking and ETSI EN 303 645 cybersecurity compliance before market access.
China
Shenzhen and Dongguan electronics manufacturing clusters compress component costs for Wi-Fi modules and embedded firmware development. MIIT certification of wireless transmission protocols creates divergent testing timelines from Western markets. Domestic procurement offices favor smart power strips for flexible workstation reconfiguration in commercial co-working spaces.
India
Tier-2 and tier-3 urban centers exhibit concentrated demand for portable plug-and-play units despite minimal smart home penetration. Grid instability and rising residential electricity consumption drive replacement of legacy electrical infrastructure. The CEA and central electricity regulatory frameworks are drafting connected metering standards that will accelerate formal market development.
Japan
Dense urban RF environments in Tokyo and Osaka push apartment dwellers toward Bluetooth-based proximity control without internet dependency. METI efficiency standards shape product specifications for residential energy management systems. Local electronics fabricators specialize in compact form factors suited to space-constrained residential installations.
Smart Control Socket Market Competitive Landscape
Capability concentration sits with premium-tier vendors mastering Matter protocol certification and cybersecurity compliance; scale advantage sits with mass-market producers leveraging Shenzhen-Dongguan manufacturing clusters. The market structures around three tiers: global electronics conglomerates with ecosystem leverage, specialized networking equipment vendors with protocol expertise, and white-label manufacturers serving price-sensitive retail channels. Dominant competitive moves include backward integration into chipset sourcing and strategic partnerships for Matter certification acceleration.
Within the ecosystem-anchored tier, Xiaomi Inc. and TP-Link Technologies Co., Ltd. occupy positions defined by captive distribution channels and vertical control over firmware development. Belkin International, Inc. exemplifies the premium-certification archetype, representing vendors where Matter protocol validation and North American retail positioning command margin premiums over commodity alternatives.
| Leading Market Players |
|---|
| TP-Link Technologies Co., Ltd. |
| Panasonic Corporation |
| Belkin International, Inc. |
| D-Link Corporation |
| Xiaomi Inc. |
| Leviton Manufacturing Co., Inc. |
| EDIMAX Technology Co. Ltd. |
| BroadLink Technology Co., Ltd. |
| Etekcity Corporation |
| Others |
Pricing and Supply Chain Analysis
The Shenzhen-Dongguan freight corridor compresses logistics costs for Wi-Fi module shipments, amplifying pricing power for manufacturers with captive chipset sourcing while forcing commodity plug producers toward thinner margins in Indian and Brazilian retail channels.
Pricing Analysis
Retail shelf prices for Matter-certified wall-mounted units in Germany and the Netherlands command substantial premiums over unbranded Wi-Fi plugs in Indian tier-2 cities. Pricing stratifies across premium architectural-grade, standard retrofit, and economy white-label tiers, with Matter protocol certification and ETSI EN 303 645 compliance as the primary differentiation drivers. Cost compression in the economy tier is intensifying because Shenzhen manufacturing clusters flood export markets with undifferentiated hardware. Commercial facility managers in US hospitality verticals exhibit the lowest price sensitivity due to unbundled service contracts, while Indian residential buyers prioritize upfront hardware cost minimization.
Supply Chain Analysis
Extended payment terms from Dongguan contract manufacturers now stretch to 90-120 days for established white-label exporters, tightening working capital for new entrants without balance sheet depth. Semiconductor fabrication for wireless chipsets draws from Taiwan, South Korea, and mainland China, while plastic housings and relay components source from Shenzhen injection-molding clusters. Single-source vulnerability concentrates in Taiwanese foundry capacity for Zigbee and Thread radio modules. Distribution runs through Amazon and Alibaba e-commerce platforms for residential volumes, with Belkin and TP-Link commanding direct retail partnerships in North American big-box channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as protocol standardization splinters demand across Matter-certified premium installations, legacy Zigbee retrofits, and unconnected economy plugs serving price-sensitive emerging markets.
For Market Incumbents: Harden firmware security capabilities against ETSI EN 303 645 enforcement escalation in EU member states. Deepen backward integration into chipset sourcing to insulate margin structures from Taiwanese foundry concentration. Matter certification investment represents the critical lever for retail shelf access in developed markets.
For New Entrants and Emerging Players: India's tier-2 and tier-3 urban centers present concentrated white-space demand for grid-stabilizing plug-and-play units without ecosystem complexity. Commercial building retrofit incentives under the US Inflation Reduction Act create procurement entry points for intelligent load management vendors. Target facility management platforms with API-first integration rather than competing on hardware specifications.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with dormant smart home divisions lacking Matter protocol roadmap investment. Long-term viability hinges on cybersecurity compliance infrastructure rather than unit volume scale. Watch for MIIT certification acceleration in China as inflection signal for domestic market formalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Retail shelf access in North American and EU channels now requires Matter validation as de facto gating mechanism. |
| Backward Integration into Chipset Sourcing | TP-Link and Xiaomi sustain cost leadership through captive Wi-Fi module production in Shenzhen-Dongguan clusters. |
| Cybersecurity Compliance Infrastructure | ETSI EN 303 645 documentation requirements separate tier-1 vendors from commodity exporters facing CE marking rejection. |
| Geographic Expansion to Indian Secondary Cities | Grid instability in tier-2 and tier-3 urban centers drives replacement demand without requiring ecosystem education investment. |
| Strategic Partnership for Commercial Retrofit | US Inflation Reduction Act tax credits channel procurement through facility management platforms requiring vendor pre-qualification. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MIIT certification databases, FCC Part 15 equipment authorization records, and EU CE marking registries. Interviews with smart home platform engineers, electrical contractor procurement leads, and retail category buyers at Amazon and Alibaba informed demand-side validation. SEC 10-K filings from TP-Link and Xiaomi, customs trade data from Shenzhen port authorities, and ETSI cybersecurity guideline documentation provided supply-side triangulation. Bottom-up unit shipment estimates from manufacturing clusters were cross-referenced against top-down energy efficiency directive implementation timelines.
Forecast inputs include wireless protocol adoption curves, regulatory compliance phase-in schedules, and building code amendment implementation across the analysis window. Segmentation modeling covers product form factor, connectivity technology, end-user vertical, and installation method dimensions. CAGRs were derived from installed base replacement cycles and new construction penetration assumptions. Zigbee-to-Matter migration paths and edge AI inference engine cost curves served as technology-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese white-label exporters or accelerated EU cybersecurity enforcement would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
US Vibration Sensors Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
Hazardous Area Sensors Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Europe Gas Sensors Market