
 Smart Pressure Gauge Market | 2026-2036
Smart Pressure Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pressure Gauge Market Analytics
Wireless sensor integration with edge computing architectures is reshaping how smart pressure gauges collect, process, and transmit operational data across distributed industrial networks. Emerson Electric Co. leverages its Plantweb digital ecosystem to anchor long-term service relationships with downstream energy operators. Honeywell International Inc. competes through embedded cybersecurity protocols that differentiate its gauge portfolios in critical infrastructure deployments. WIKA Instruments specializes in ceramic sensor technology that sustains measurement accuracy under extreme temperature cycling.
A smart pressure gauge is a digitally instrumented pressure measurement device incorporating microelectromechanical sensors, signal conditioning electronics, and wireless or wired communication modules to deliver real-time pressure data with remote diagnostics and calibration management capabilities. These instruments serve primary industrial functions including process safety monitoring, predictive maintenance triggering, and regulatory compliance documentation in hazardous environment operations. Digital gauge variants command premium positioning due to onboard data logging and alarm threshold programming that reduce manual inspection labor. IoT-enabled technology segments are expanding fastest as cloud-native architectures allow centralized dashboarding across multi-site manufacturing footprints. Oil and gas end users represent the deepest margin pool given explosion-proof certification requirements and extended replacement cycles that lock in aftermarket service revenues.
OSHA process safety management standards in the United States and ATEX directives across European Union member states mandate certified pressure instrumentation in hazardous area classifications, directly shaping product design specifications and third-party testing expenditures for gauge manufacturers. The EPA's methane emissions reduction framework intensifies leak detection protocol stringency, compelling upstream operators to deploy higher-frequency pressure monitoring with automated anomaly flagging. Stakeholders must weigh sensor interoperability standards against proprietary platform ecosystems when selecting instrumentation partners for multi-decade asset deployment cycles.
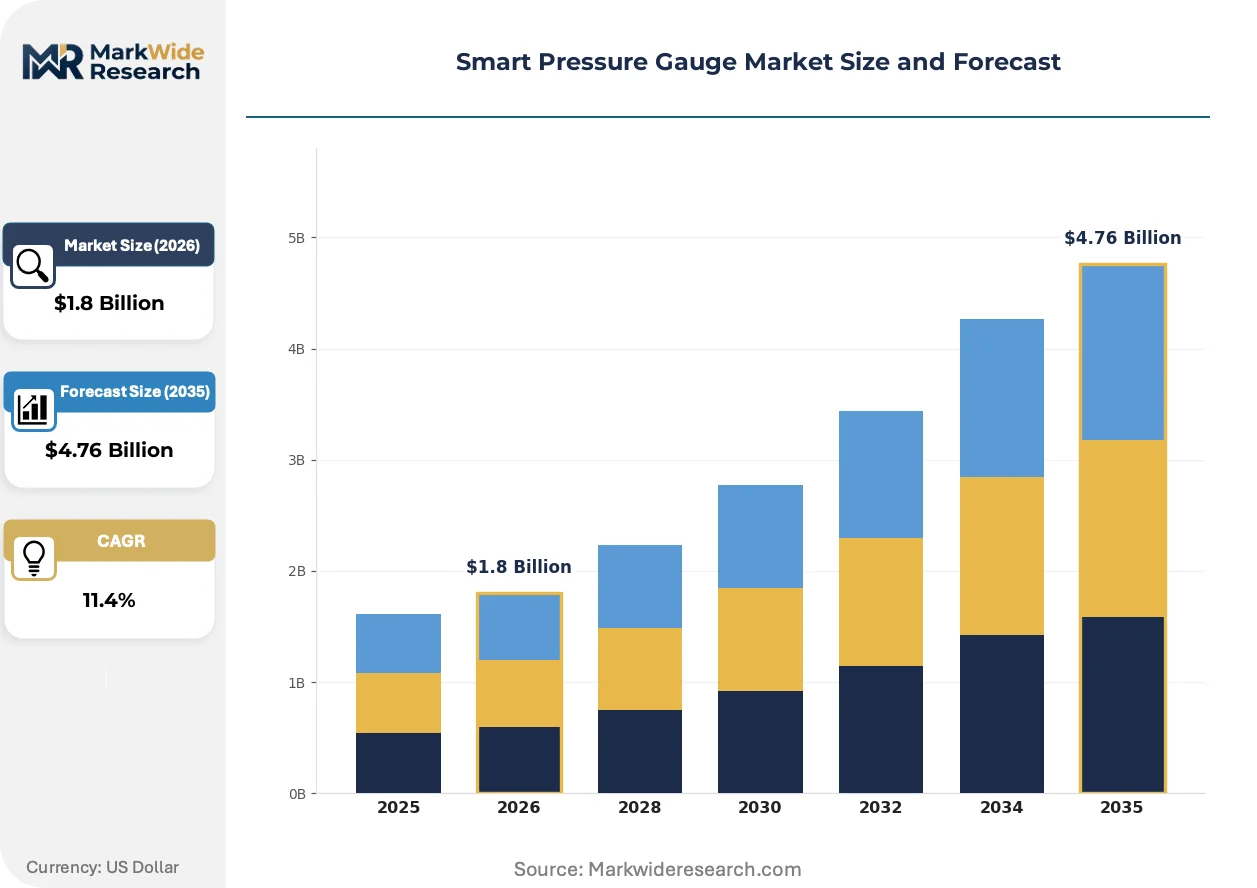
Market Dynamics
Pipeline operators across North America and Europe are retiring mechanical gauge fleets in favor of connected instruments that feed predictive maintenance algorithms, compressing replacement cycles from decades to single-digit years.
Growth Catalysts
- Methane emissions frameworks:The EPA's methane reduction protocols compel upstream oil and gas operators to install continuous pressure monitoring with automated leak flagging, expanding instrument density per well site.
- Ceramic sensor durability:Alumina-based sensing elements withstand thermal cycling in chemical processing, extending calibration intervals and reducing field service visits in German chemical clusters.
- India:PLI scheme incentives for process automation equipment accelerate smart instrument adoption in refinery expansions along the Gujarat and Maharashtra coastlines.
Market Restraints
- Silicon wafer supply concentration:MEMS die fabrication concentrates in Taiwanese and South Korean foundries, exposing gauge manufacturers to geopolitical disruption risk and extended lead times.
- ATEX certification costs:Third-party hazardous area testing for European deployments adds eighteen to twenty-four months to product launch timelines and six-figure expenditure per SKU variant.
- Mechanical gauge residual value:Decades-old Bourdon tube instruments in non-critical applications continue operating without maintenance, delaying upgrade decisions in cost-constrained municipal water systems.
Strategic Opportunities
- Hydrogen infrastructure buildout:High-pressure electrolyzer and pipeline applications require specialized pressure instrumentation rated for embrittlement-resistant materials, opening premium product tiers.
- Edge-to-cloud architecture convergence:Gauge vendors bundling local analytics with SaaS dashboard subscriptions capture recurring revenue streams from multi-site manufacturing operators.
- Brazil:ANVISA pharmaceutical manufacturing standards are tightening process validation requirements, creating demand for calibrated digital pressure records in sterile API production.
Industry Challenges
- Embedded cybersecurity expertise:Industrial IoT protocol hardening against ransomware requires firmware engineering talent scarce in traditional instrumentation houses.
- Legacy 4-20mA integration:Brownfield sites running decades-old DCS architectures demand protocol gateway development, fragmenting engineering resources across conversion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pressure Gauge Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Gauges, Digital Gauges, Smart Gauges, Wireless Gauges End User: Manufacturing, Automotive, Aerospace, Oil & Gas Technology: IoT Enabled, Bluetooth, Wi-Fi, Cloud-Based Application: Fluid Monitoring, Pressure Testing, Data Logging, HVAC Systems |
| Companies Covered | Emerson Electric Co., Honeywell International Inc., WIKA Instruments, AMETEK Inc., Ashcroft Inc., Yokogawa Electric Corporation, ABB Ltd, Endress+Hauser Group, Omega Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pressure Gauge Market Evolving Landscape
Wireless sensor networks combined with on-device inference are collapsing the latency between pressure anomaly detection and maintenance dispatch, rewiring service economics for instrument vendors.
MEMS-based capacitive pressure sensing is rendering obsolete traditional strain gauge architectures in sub-1000 psi industrial applications. Food and beverage processors in Denmark and the Netherlands are adopting these compact sensors for clean-in-place sterilization monitoring. The shift eliminates fluid-filled impulse lines that harbor bacterial contamination, compressing sanitary system validation timelines.
The EU F-Gas Regulation mandates refrigerant leak detection with quantified reporting thresholds for commercial and industrial cooling systems. Equipment OEMs in Germany and France now specify pressure transmitters with integrated temperature compensation for superheat calculations. Cold chain logistics operators respond by retrofitting transport refrigeration units with connected gauges that auto-generate compliance documentation.
Asset-as-a-service contracting is displacing capital purchase models among mid-size chemical processors. Instrument vendors in the US Gulf Coast region now offer per-month pressure monitoring subscriptions bundling hardware, calibration, and cloud analytics. This procurement shift transfers obsolescence risk to suppliers while locking in decade-long customer relationships through embedded software dependencies.
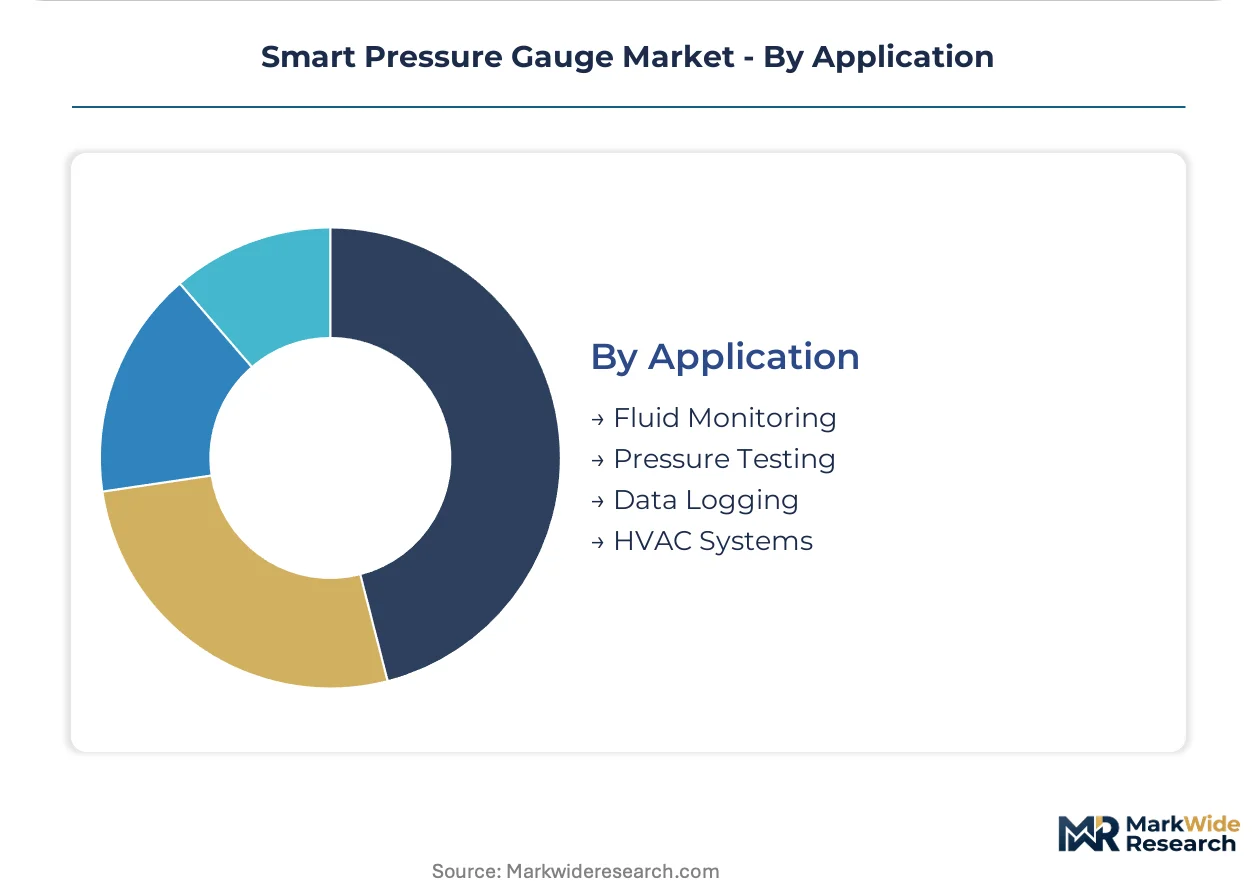
Smart Pressure Gauge Market Segmentation
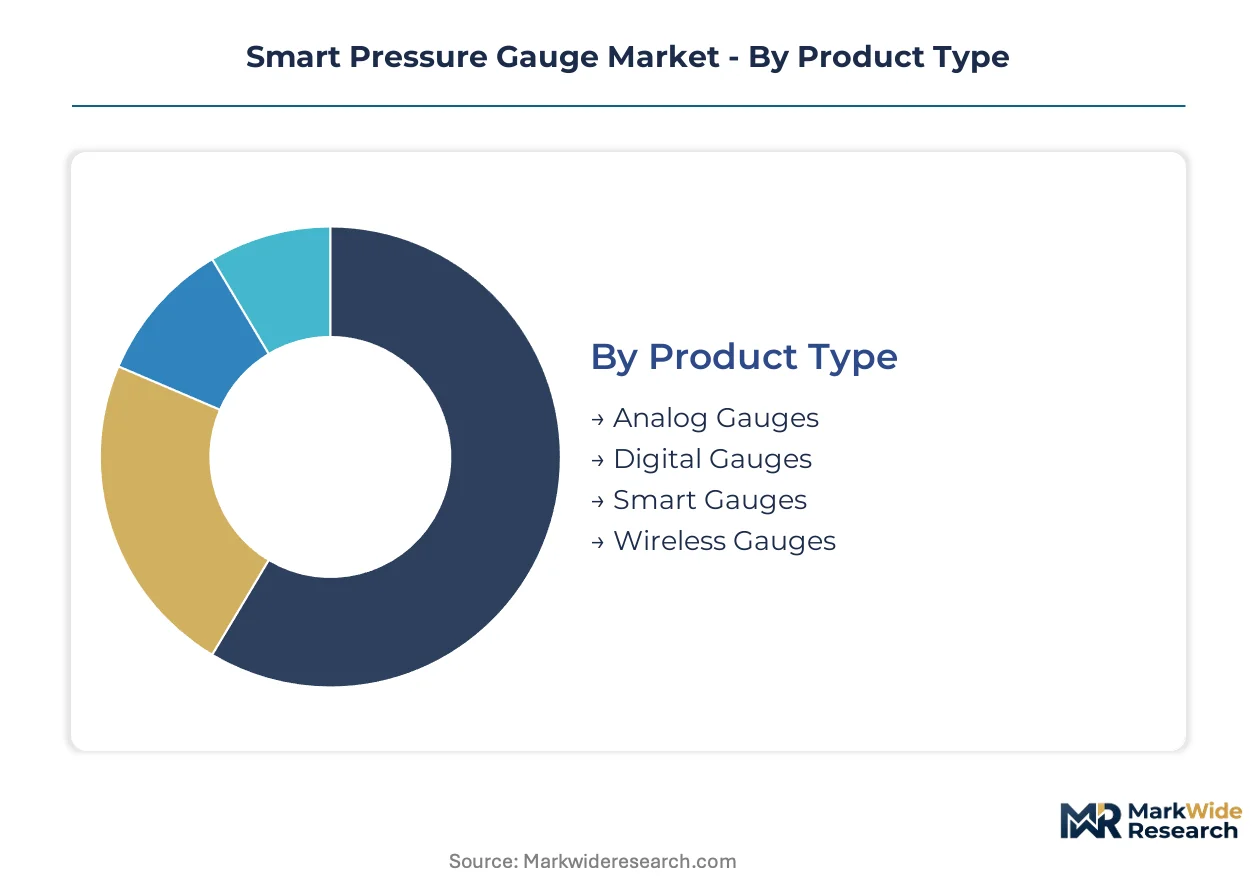
Smart pressure gauge segmentation reveals divergent service economics across product tiers. Digital variants demand firmware update subscriptions, while analog replacements rely on spare parts logistics.
Product Type:
After-sales intensity varies sharply—connected instruments lock in decade-long calibration contracts, mechanical gauges generate only episodic replacement revenue.
- Analog Gauges:Bourdon tube mechanisms dominate municipal water infrastructure where capital budgets resist digitization. German chemical clusters retain these for non-critical utility loops, deferring upgrade cycles amid energy cost pressures.
- Digital Gauges:Microprocessor-based units with onboard data logging command premium positioning in pharmaceutical batch processing. FDA 21 CFR Part 11 compliance requirements in US sterile manufacturing drive validated calibration documentation demand.
- Smart Gauges:Edge-computing instruments with predictive diagnostics anchor Emerson Plantweb deployments across Texas refinery expansions.
- Wireless Gauges:Battery-powered ISA100.11a devices eliminate conduit installation in rotating equipment monitoring.
Digital gauges hold the largest share; momentum sits with wireless gauges.
End User:
Application environments dictate sensor specification divergence—explosion-proof certifications concentrate margin in hazardous deployments.
- Oil & Gas:Upstream wellhead monitoring requires HART-protocol instruments with SIL 2 safety ratings. EPA methane reduction frameworks compel continuous pressure anomaly detection across Permian Basin pad sites.
- Manufacturing:Discrete automation lines favor compact MEMS sensors for pneumatic system efficiency tracking. Japanese automotive stamping plants deploy these for compressed air leak detection.
- Aerospace:Flight-qualified transducers with DO-160G environmental testing sustain narrowbody production rates.
- Automotive:EV battery cell formation processes demand high-purity pressure measurement in dry room environments.
Oil & Gas commands the steepest pricing; manufacturing offers the broadest volume base.
Technology:
Connectivity architecture determines data sovereignty risks and recurring revenue capture for instrumentation vendors.
- IoT Enabled:MQTT-protocol gauges with TLS encryption feed centralized SCADA architectures. Cloud-native dashboards in German chemical parks enable cross-site benchmarking.
- Cloud-Based:SaaS telemetry platforms bundle hardware, connectivity, and analytics for mid-size processors lacking IT infrastructure.
- Bluetooth:Short-range commissioning tools reduce field technician exposure in confined space entries.
- Wi-Fi:802.11ah HaLow variants extend range for outdoor tank farm monitoring without mesh infrastructure.
IoT-enabled configurations dominate installed base; cloud-based deployments are climbing the fastest.
Application:
Measurement purpose shapes accuracy requirements and calibration frequency obligations.
- Fluid Monitoring:Corrosion-resistant diaphragm seals protect sensing elements in sour gas processing. Saudi Aramco offshore platforms specify these for wellstream composition tracking.
- HVAC Systems:Refrigerant pressure-temperature correlation enables superheat calculations for EU F-Gas compliance. French commercial cooling OEMs integrate these for automated leak documentation.
- Pressure Testing:High-accuracy deadweight tester replacements serve calibration laboratory traceability chains.
- Data Logging:Battery-backed recorders capture transient events in hydraulic fracturing pressure validation.
Fluid monitoring anchors current revenue; HVAC applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream oil and gas operators in the Permian Basin, German chemical processors in Ludwigshafen, and Indian refinery expansions along the Gujarat coast represent the three dominant buyer archetypes compressing replacement cycles from mechanical to connected pressure instrumentation.
United States
EPA methane reduction protocols mandate continuous pressure monitoring with automated leak flagging across upstream well sites. OSHA process safety management standards enforce certified instrumentation in hazardous area classifications. Texas Gulf Coast refinery expansions anchor Emerson Plantweb deployments for predictive maintenance analytics.
Germany
EU F-Gas Regulation drives refrigerant leak detection demand with quantified reporting thresholds for industrial cooling systems. ATEX directives shape explosion-proof product specifications and third-party testing expenditures. Chemical clusters in Ludwigshafen and Leverkusen upgrade process automation faster than other European markets.
China
Dual carbon goals accelerate hydrogen infrastructure buildout requiring embrittlement-resistant pressure instrumentation. MIIT standards govern industrial IoT device interoperability in smart manufacturing zones. Yangtze River Delta petrochemical complexes deploy MEMS-based sensors for clean-in-place sterilization monitoring.
India
PLI scheme incentives for process automation equipment accelerate smart instrument adoption in refinery capacity expansions. CEA regulations mandate digital instrumentation in critical utility infrastructure. Gujarat and Maharashtra coastal refineries specify HART-protocol gauges with SIL 2 safety ratings for upstream monitoring.
Saudi Arabia
SFDA pharmaceutical manufacturing standards tighten process validation requirements for sterile API production. National industrial localization programs incentivize domestic assembly of precision instrumentation. Offshore platforms in the Eastern Province specify corrosion-resistant diaphragm seals for sour gas processing applications.
Smart Pressure Gauge Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates bundling digital ecosystems, sensor technology specialists commanding premium positioning through materials science, and regional fabricators serving cost-sensitive municipal infrastructure. Dominant competitive moves include portfolio diversification into edge-to-cloud service bundles and geographic expansion through hazardous area certification stacking.
Among diversified industrial conglomerates, Emerson Electric Co. and Honeywell International Inc. occupy positions anchoring long-term service relationships through embedded platform dependencies. WIKA Instruments exemplifies the sensor technology specialist archetype, with its German GmbH structure signaling deep materials science capabilities in ceramic sensing elements. These three represent distinct competitive vectors: ecosystem lock-in, cybersecurity differentiation, and extreme-environment measurement accuracy.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Honeywell International Inc. |
| WIKA Instruments |
| AMETEK Inc. |
| Ashcroft Inc. |
| Yokogawa Electric Corporation |
| ABB Ltd |
| Endress+Hauser Group |
| Omega Engineering |
| Others |
Value Network & Pricing Analysis
Taiwanese MEMS foundry concentration determines both three-tier pricing spreads across premium, standard, and economy levels and supply chain vulnerability to geopolitical disruption. Gauge manufacturers face eighteen-to-twenty-four-month ATEX certification timelines that compress margin buffers while locking in long-term contract structures with European chemical processors.
Pricing Analysis
Long-term supply agreements with semiconductor foundries typically index MEMS die costs to wafer pricing, forcing gauge OEMs to pass through component volatility or absorb margin erosion. Pricing stratifies across premium, standard, and economy tiers based on SIL safety certification grade and after-sales calibration bundling. Cost compression in economy-tier municipal water applications is intensifying because Bourdon tube residual value delays upgrade decisions. Municipal utilities exhibit highest price sensitivity; oil and gas operators accepting explosion-proof premiums show lowest.
Supply Chain Analysis
Contract manufacturing for MEMS pressure sensing elements concentrates in Taiwanese and South Korean foundries, with ceramic substrate processing anchored in German and Japanese facilities. Raw material dependencies include alumina ceramic substrates, titanium diaphragm alloys, and fluoropolymer seal compounds. Single-source vulnerability in 200mm MEMS wafer capacity exposes gauge manufacturers to allocation risk during semiconductor demand cycles. Distribution runs through authorized instrumentation distributors serving regional industrial clusters, with direct OEM relationships dominating large refinery and chemical complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart pressure gauge markets reward vendors capturing calibration-as-a-service contracts that expand recurring revenue faster than hardware shipments. Firmware update subscriptions and predictive analytics dashboards now anchor decade-long customer relationships previously secured by gauge replacement cycles alone.
For Market Incumbents: Pre-empt cloud-native entrant disruption by bundling edge-to-cloud telemetry with mandatory firmware update subscriptions. Lock in refinery and chemical processor relationships through SIL 2 certification stacking that extends replacement cycle capture. Defend against MEMS commoditization by deepening ceramic sensor materials science differentiation in hydrogen embrittlement-resistant applications.
For New Entrants and Emerging Players: Pursue municipal water infrastructure retrofit opportunities where decades-old Bourdon tube instruments face regulatory pressure for digital compliance documentation. Target India's PLI-subsidized refinery expansions along Gujarat and Maharashtra coastlines where HART-protocol gauge demand outpaces established vendor capacity. Lead with per-month subscription pricing that transfers obsolescence risk from capital-constrained utilities.
For Investors and Strategic Acquirers: EPA methane reduction framework implementation reshapes the acquisition landscape by mandating continuous monitoring density across upstream well sites. Five-to-ten-year viability centers on gauge vendors with embedded cybersecurity firmware engineering capabilities scarce in traditional instrumentation houses. Acquisition target archetype: regional fabricators with ATEX certification infrastructure and undermonetized aftermarket service bases. Signal to watch: hydrogen infrastructure electrolyzer deployment rates indicating premium-tier instrumentation demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Platform Integration | Bundles local analytics with SaaS dashboards for multi-site manufacturing operators. |
| Ceramic Sensor Materials Science Investment | Extends calibration intervals in German chemical cluster thermal cycling applications. |
| Hydrogen Infrastructure Certification Stacking | Captures premium positioning in high-pressure electrolyzer and pipeline deployments. |
| Cybersecurity Firmware Engineering Acquisition | Addresses ransomware hardening talent scarcity in industrial IoT protocol development. |
| India PLI Scheme Geographic Expansion | Accelerates smart instrument adoption in Gujarat and Maharashtra refinery capacity additions. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with instrumentation procurement managers at oil and gas operators, chemical plant engineers, and aftermarket service directors; and secondary validation through customs trade records, ATEX certification registries, and SEC filings from diversified industrial conglomerates. Bottom-up gauge shipment estimates triangulated against top-down process automation capital expenditure patterns across the analysis window.
Forecast inputs span product type segmentation across analog, digital, smart, and wireless gauges; end-use industries from oil and gas through pharmaceutical manufacturing; and technology architectures distinguishing IoT-enabled from cloud-native deployments. CAGRs derive from instrument replacement cycle compression rates and regulatory mandate implementation timelines. Hydrogen infrastructure buildout curves and EPA methane monitoring protocol enforcement intensity serve as industry-specific demand drivers.
Sensitivities concentrate around MEMS wafer supply allocation shocks, ATEX certification timeline extensions, and municipal utility budget cycle delays. Forecasts embed assumptions regarding PLI scheme continuation and F-Gas Regulation enforcement consistency. Quarterly review of semiconductor foundry utilization rates and hydrogen electrolyzer deployment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Refrigeration Gauge Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
North America MEMS and Sensors Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Global Capacitive Sensor Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Global Actuator Sensor Interface Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Cryogenic Temperature Controller Market