
 Temperature Monitoring System Market | 2026-2036
Temperature Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Monitoring System Market Analysis
ISO 13485 certification for medical device quality management is rotating competitive advantage toward suppliers with validated quality systems. Emerson Electric Co. leverages its automation portfolio to anchor industrial process monitoring across North American manufacturing corridors. Honeywell International Inc. competes through building management integration, while Vaisala sustains leadership in precision environmental measurement for regulated life science facilities.
A temperature monitoring system comprises calibrated sensors, signal conditioning circuitry, and data acquisition interfaces that measure thermal states within specified accuracy ranges, typically transmitting readings via analog outputs or digital protocols for process control and compliance documentation. Wireless sensors now lead product type adoption as battery-efficient radio designs reduce installation costs in distributed facilities; IoT-based solutions within the technology dimension are capturing the fastest expansion as edge computing enables real-time anomaly detection without cloud dependency. Healthcare and pharmaceutical end users concentrate margin pools where validation documentation and audit trails command premium pricing.
The FDA enforces 21 CFR Part 11 electronic record requirements for temperature data in drug distribution, while the EU MDR tightens post-market surveillance for implantable devices with environmental sensitivity. OSHA workplace safety standards and EPA environmental compliance frameworks further shape sensor deployment in industrial settings. Stakeholders must monitor evolving cybersecurity mandates for connected monitoring devices as regulatory scope expands beyond measurement accuracy to data integrity protection.
Market Dynamics
IoT-enabled sensor architectures are decomposing legacy wired infrastructure across pharmaceutical and food processing facilities, forcing incumbent suppliers to revalidate wireless calibration protocols or lose qualification status.
Growth Catalysts
- 21 CFR Part 11:FDA electronic record mandates for temperature data in drug distribution compel biologics manufacturers to upgrade continuous monitoring infrastructure.
- Battery-efficient radio designs:Reduced installation costs in distributed facilities accelerate wireless sensor deployment across cold chain logistics networks.
- Germany:KBA automotive and BfArM medical manufacturing enforcement creates concentrated demand for validated environmental monitoring systems.
Market Restraints
- Lithium supply volatility:Battery chemistry cost fluctuations constrain wireless sensor margin structures for distributed IoT deployments.
- Precision sensor foundry concentration:MEMS fabrication capacity clustering in East Asian contract manufacturers creates single-source vulnerability.
- EU MDR transition friction:Extended post-market surveillance documentation timelines delay implantable device monitoring system approvals.
Strategic Opportunities
- Edge computing convergence:Real-time anomaly detection without cloud dependency opens new service models for remote pharmaceutical storage.
- India:CDSCO cold chain expansion for vaccine distribution presents underpenetrated demand for validated temperature logging systems.
- CSRD reporting mandates:EU corporate sustainability disclosure requirements create pull for energy-efficient environmental monitoring in industrial facilities.
Industry Challenges
- ISO 17025 calibration technician scarcity:Qualified metrology personnel shortages extend deployment timelines for validated pharmaceutical installations.
- Legacy SCADA integration complexity:Protocol translation between modern IoT sensors and existing process control systems demands custom engineering.
- IEC 62443 cybersecurity certification:Connected device security standard compliance adds development cycles before connected monitor commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Monitoring System Market |
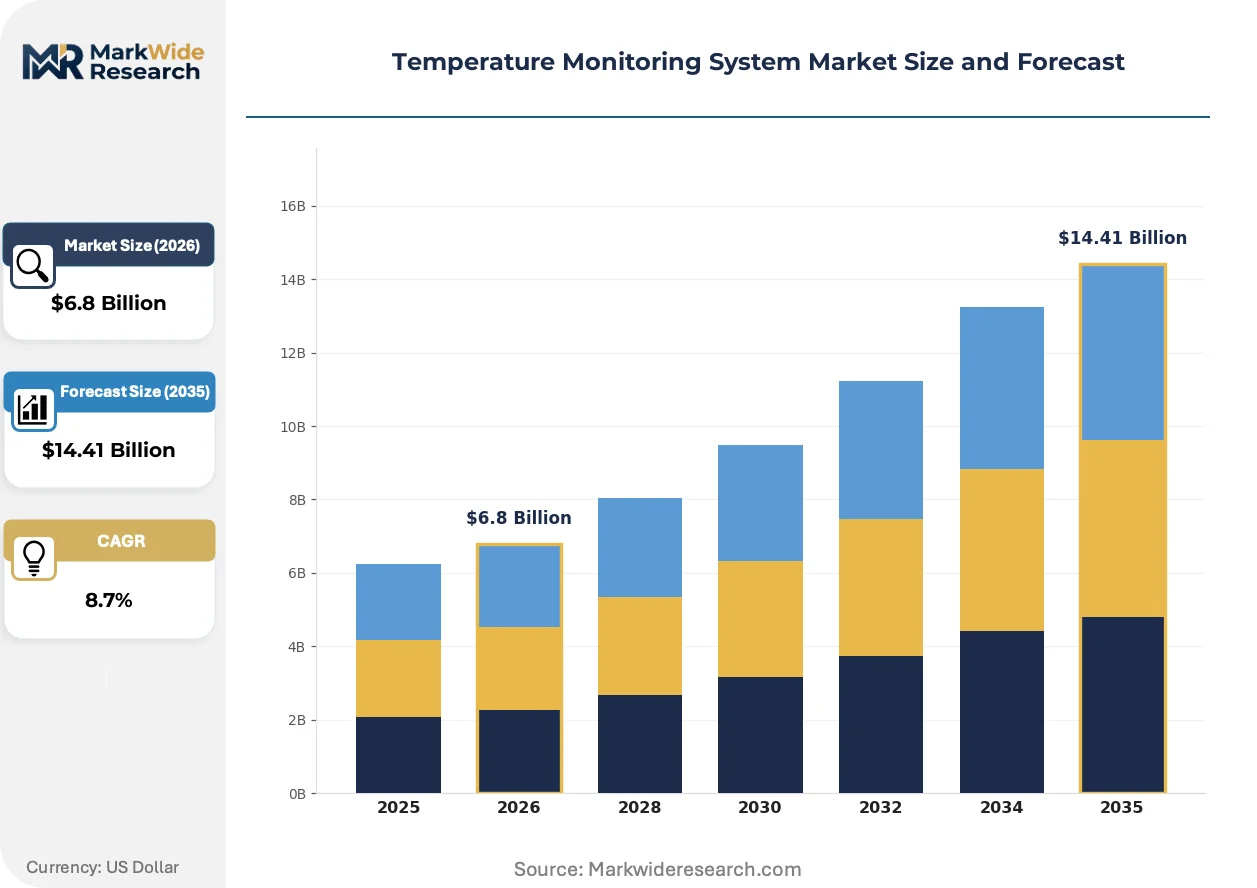
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Sensors, Infrared Thermometers, Thermocouples, Data Loggers Application: Food Safety, HVAC, Industrial Processes, Healthcare Technology: IoT-based Solutions, Cloud Monitoring, Bluetooth Technology, Thermography End User: Hospitality, Manufacturing, Pharmaceutical, Warehousing |
| Companies Covered | 3M, Honeywell International Inc., Emerson Electric Co., Vaisala, Cardinal Health, Monnit Corporation, SensoScientific Inc., E-control Systems Inc., CenTrak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Monitoring System Market Emerging Trajectories
Wireless telemetry architectures are actively displacing copper-wired sensor networks across regulated manufacturing environments, compressing installation timelines while introducing new validation protocols for electromagnetic interference immunity.
LoRaWAN-based temperature loggers is decomposing proprietary radio frequency ecosystems that previously locked pharmaceutical cold chain operators into single-vendor sensor ecosystems. Regional vaccine distributors are adopting these open-protocol devices fastest, enabling multi-supplier procurement strategies that compress hardware margins while expanding software and calibration service attach rates.
EU MDR post-market surveillance requirements for implantable devices with environmental sensitivity tighten temperature excursion documentation throughout distribution. Medical device manufacturers now embed continuous monitoring into secondary packaging, shifting cost structures from capital equipment toward per-shipment sensor consumption. German orthopedic implant suppliers face the steepest compliance ramps.
Subscription-based validation services displace outright hardware ownership in mid-tier pharmaceutical manufacturing. Contract manufacturing organizations in Ireland and Singapore pilot sensor-as-a-service models where calibration maintenance and audit documentation transfer to sensor suppliers, reducing internal quality assurance headcount while ensuring continuous compliance coverage.
Temperature Monitoring System Market Segmentation
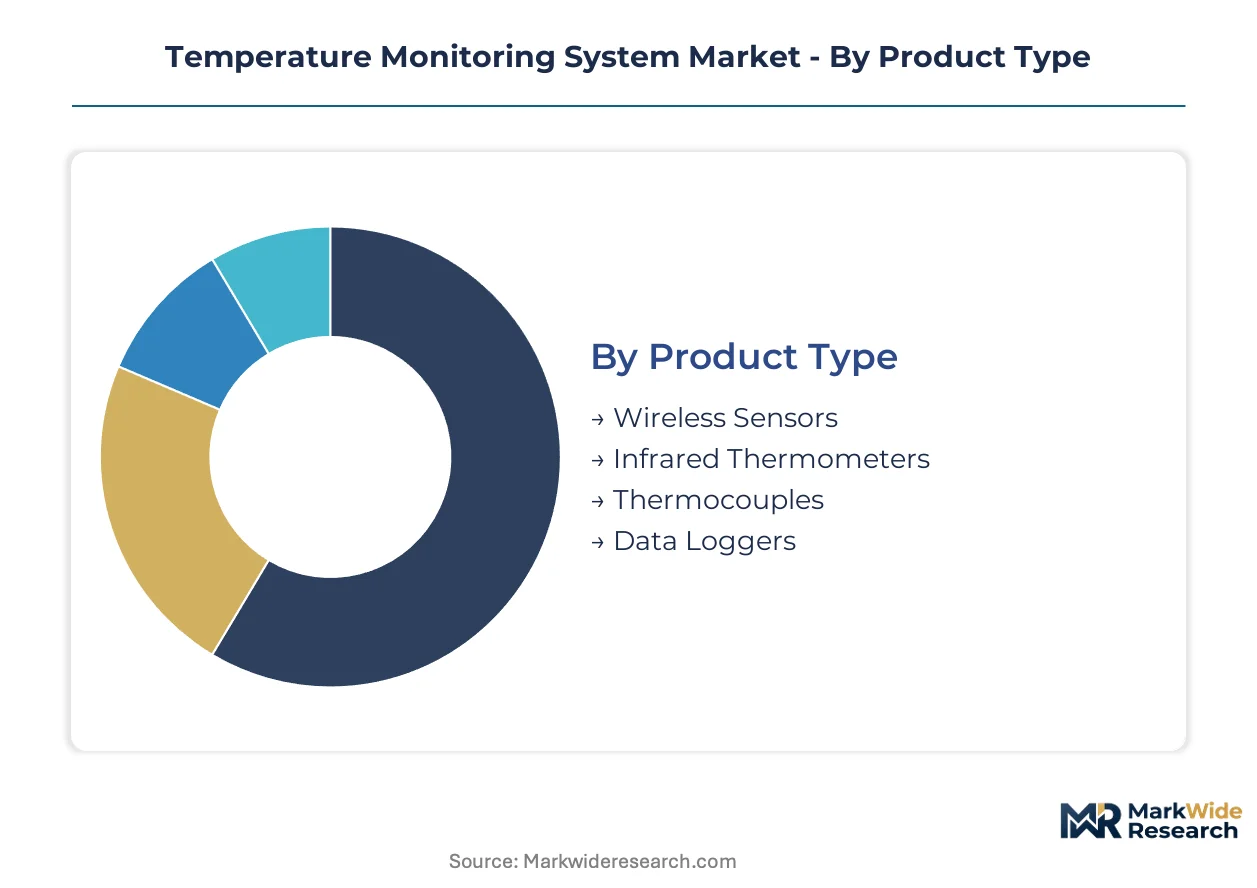
Temperature monitoring system segmentation reveals distinct technology substitution pressures across product architectures, with wireless and IoT-enabled platforms displacing legacy wired infrastructure in regulated environments. Application-driven purchasing patterns concentrate margin pools where validation documentation commands premium pricing, while end-user verticals impose divergent compliance frameworks shaping procurement specifications.
Product Type:
Wireless sensors face the most intense substitution pressure from emerging energy-harvesting architectures, while thermocouple incumbents defend entrenched positions in high-temperature industrial processes.
- Wireless Sensors:Battery-efficient radio designs integrate calibrated thermistors with LoRaWAN or Bluetooth Low Energy transmission protocols. Pharmaceutical cold chain operators in Germany and the United States are consolidating procurement around these devices as KBA automotive and FDA biologics guidance tighten continuous monitoring mandates.
- Infrared Thermometers:Non-contact thermal radiation detectors measure surface temperatures through lens-focused infrared energy collection. Food safety inspectors across commercial kitchen networks favor these instruments for rapid spot-checking without product contamination risk.
- Thermocouples:Junction-based voltage generation sensors withstand extreme thermal ranges in metallurgical and petrochemical process control.
- Data Loggers:Self-contained recording devices with internal memory and USB or wireless data retrieval capabilities serve audit-intensive pharmaceutical distribution.
Wireless sensors retain volume leadership; data loggers hold the steepest expansion curve as per-shipment disposable models gain traction in medical device distribution.
Application:
Cost tier stratification separates capital-intensive industrial process installations from high-volume, low-margin food safety deployments.
- Healthcare:Continuous temperature tracking systems for blood storage, vaccine refrigeration, and operating room environmental control require ISO 17025 calibration certificates and 21 CFR Part 11 electronic record compliance. German hospital networks and United States health systems are standardizing on validated wireless infrastructure.
- Industrial Processes:Harsh-environment thermocouple arrays and RTD assemblies monitor reactor vessels, turbine exhaust, and heat treatment furnaces. Petrochemical complexes along the United States Gulf Coast and German Ruhr industrial corridor anchor replacement demand.
- Food Safety:HACCP-compliant temperature verification tools span from handheld probe thermometers to automated cold chain logging systems.
- HVAC:Building automation integration drives demand for networked zone sensors with BACnet or Modbus protocol compatibility.
Healthcare commands the highest margin tier; food safety generates the largest unit volumes through distributed restaurant and retail deployment.
Technology:
Customer type divergence separates enterprise-scale cloud-dependent deployments from edge-autonomous installations serving remote pharmaceutical storage.
- IoT-based Solutions:Sensor-to-cloud architectures with edge computing capabilities enable real-time anomaly detection without continuous internet connectivity. Indian vaccine distributors under CDSCO cold chain expansion mandates are piloting these systems for rural last-mile storage.
- Cloud Monitoring:Centralized data aggregation platforms with web dashboards and automated alerting serve multi-site pharmaceutical manufacturers.
- Bluetooth Technology:Short-range wireless protocols support smartphone-connected spot measurements and localized data logger retrieval.
- Thermography:Thermal imaging cameras generate two-dimensional temperature maps for electrical panel inspection and building envelope analysis.
IoT-based solutions are expanding most quickly; Bluetooth technology retains dominance in portable diagnostic applications.
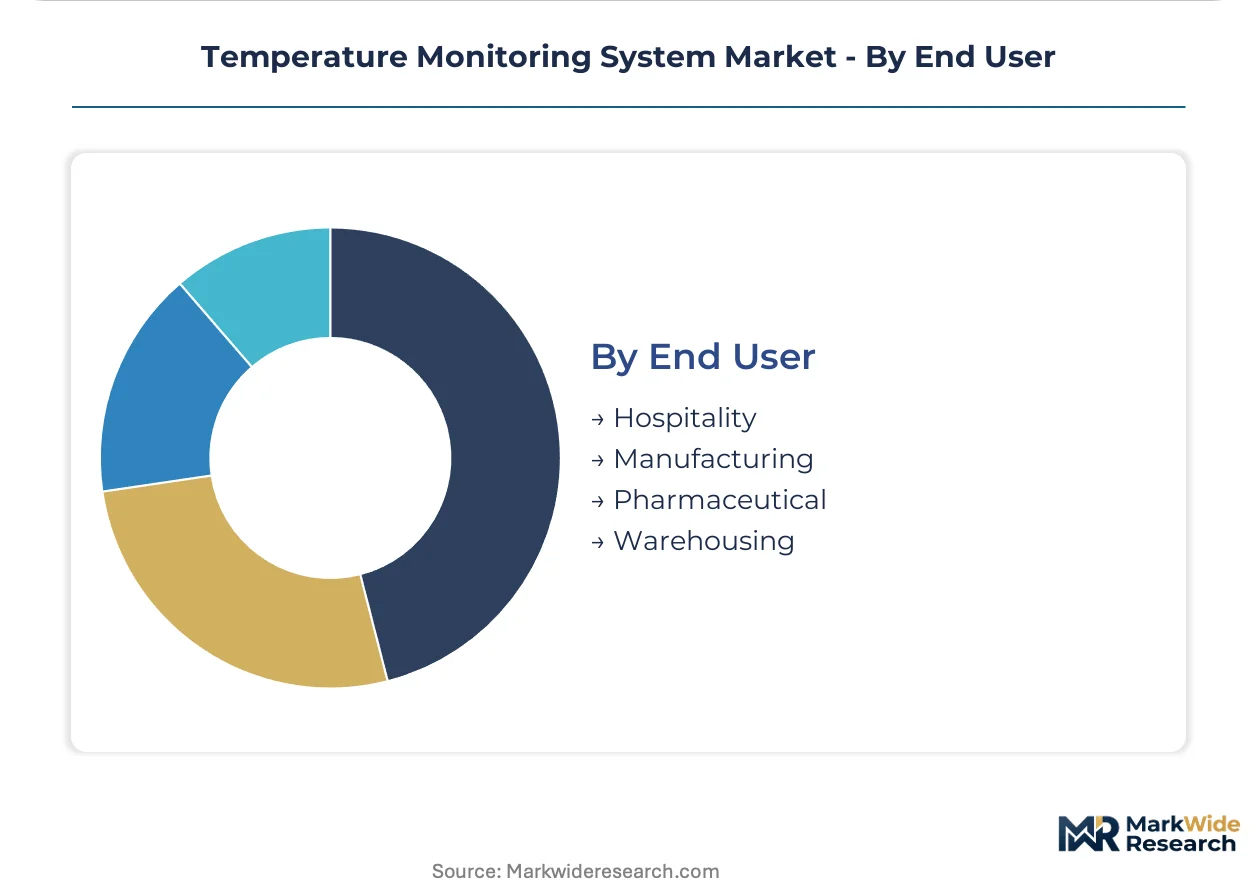
End User:
Supply concentration in precision sensor foundries disproportionately constrains pharmaceutical and manufacturing verticals with stringent calibration requirements.
- Pharmaceutical:Biologics manufacturers and contract manufacturing organizations demand validated environmental monitoring with audit trails and IQ/OQ/PQ documentation. Irish and Singaporean CMOs are piloting sensor-as-a-service models to transfer calibration maintenance burdens.
- Manufacturing:Automotive, electronics, and medical device production facilities deploy distributed sensor networks for cleanroom and process control. German orthopedic implant suppliers face the steepest EU MDR post-market surveillance compliance ramps.
- Warehousing:Third-party logistics providers managing temperature-sensitive inventory require scalable monitoring across distributed facilities.
- Hospitality:Hotel and restaurant chains implement HACCP-compliant refrigeration monitoring to prevent foodborne illness liability.
Pharmaceutical retains the highest pricing power; warehousing represents the fastest-climbing adoption curve as cold chain logistics networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on continuous temperature tracking for biologics and EU MDR post-market surveillance mandates are accelerating infrastructure upgrades across pharmaceutical manufacturing corridors. National regulators in Germany, the United States, India, Japan, and China are tightening qualification requirements for cold chain compliance.
Germany
KBA automotive enforcement and BfArM medical manufacturing standards drive validated environmental monitoring procurement. The country's national pharmaceutical regulator mandates ISO 17025 calibration documentation for implantable device distribution. Bavarian orthopedic implant suppliers face steep compliance ramps as EU MDR post-market surveillance timelines compress.
United States
FDA 21 CFR Part 11 electronic record requirements compel biologics manufacturers to upgrade continuous monitoring infrastructure. OSHA workplace safety standards and EPA environmental compliance frameworks shape sensor deployment in Gulf Coast petrochemical complexes. Greater Boston hospital networks standardize on validated wireless infrastructure for blood storage and vaccine refrigeration.
India
CDSCO cold chain expansion for vaccine distribution creates underpenetrated demand for validated temperature logging systems. The country's national pharmaceutical regulator pilots IoT-based edge computing deployments for rural last-mile storage. Maharashtra and Gujarat pharmaceutical clusters anchor sensor-as-a-service adoption among contract manufacturing organizations.
Japan
METI industrial standards and PMDA pharmaceutical regulations enforce precision measurement protocols for biologics distribution. The country's national pharmaceutical regulator requires continuous temperature documentation for temperature-sensitive medical devices. Kansai region medical device manufacturers embed monitoring into secondary packaging to satisfy post-market surveillance requirements.
China
NMPA biologics distribution guidelines and dual carbon goals accelerate energy-efficient monitoring adoption. The country's national pharmaceutical regulator tightens environmental qualification for vaccine cold chain infrastructure. Yangtze River Delta pharmaceutical manufacturers deploy wireless telemetry to replace legacy wired sensor networks.
Temperature Monitoring System Market Vendor Landscape
Listed leaders compete with private specialists across validation documentation and calibration service capabilities. The market exhibits tiered concentration where automation conglomerates anchor industrial process monitoring while precision measurement specialists defend life science margins. Three archetypes dominate: diversified automation suppliers with building management integration, environmental instrumentation pure-plays with metrology heritage, and wireless sensor specialists with IoT-native architectures. Strategic moves center on sensor-as-a-service business model pilots and edge computing capability acquisitions.
Within the diversified automation tier, Honeywell International Inc. and Emerson Electric Co. represent integrated building and process control positioning. Vaisala occupies a position among precision environmental measurement specialists serving regulated life science facilities. These three companies exemplify competitive archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Vaisala |
| Cardinal Health |
| Monnit Corporation |
| SensoScientific Inc. |
| E-control Systems Inc. |
| CenTrak |
| Others |
Supply Flow & Price Mechanics
Twenty-six-week calibration certificate lead times for ISO 17025-qualified sensors concentrate pricing power with German and Swiss metrology houses, compressing margins for distributors while amplifying premiums for suppliers with captive validation laboratories.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across FDA-validated, CE-marked, and uncertified economy levels stratifies procurement budgets. Pricing pressure stems from LoRaWAN commoditization in pharmaceutical cold chain deployments. Contract manufacturing organizations exhibit highest price sensitivity; biologics manufacturers with 21 CFR Part 11 mandates show least elasticity.
Supply Chain Analysis
Strait of Malacca transit vulnerability exposes MEMS foundry output from Taiwan and South Korea to logistics disruption. Precision thermistor fabrication draws from Japanese ceramics, German semiconductor packaging, and Chinese battery cell assembly. Single-source vulnerability concentrates in East Asian contract manufacturers. Distribution runs through authorized metrology distributors with calibration service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless telemetry substitution threatens wired sensor incumbents defending entrenched pharmaceutical installations. Incumbents must navigate energy-harvesting architectures decomposing legacy infrastructure.
For Market Incumbents: Compound calibration service attach rates to offset hardware margin compression from open-protocol LoRaWAN commoditization. Deepen backward integration into MEMS fabrication through joint development agreements with Taiwanese foundries. Defend qualification status against emerging sensor-as-a-service entrants. For New Entrants and Emerging Players: Subscription-based validation gaps in mid-tier pharmaceutical manufacturing offer white-space penetration. Target Irish and Singaporean contract manufacturing organizations piloting outsourced compliance models. Lead with sensor-as-a-service pricing to displace capital expenditure barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automation conglomerates with under-monetized environmental monitoring divisions. Long-term viability rests on edge computing capability integration and cybersecurity certification depth. Watch IEC 62443 compliance timelines as inflection indicator for connected device commercialization readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-as-a-Service Launch | Transfers calibration maintenance burdens to suppliers, reducing CMO quality assurance headcount. |
| Edge Computing Acquisition | Enables real-time anomaly detection without cloud dependency for remote pharmaceutical storage. |
| LoRaWAN Protocol Certification | Opens multi-supplier procurement strategies for regional vaccine distributors. |
| ISO 17025 Laboratory Buildout | Captures premium pricing from German BfArM and KBA enforcement tightening. |
| IEC 62443 Cybersecurity Investment | Accelerates connected monitor commercialization before regulatory mandates harden. |
Methodological Framework
The analysis maps wireless sensor architectures, IoT-enabled platforms, and legacy wired infrastructure, each validated through quality assurance directors at pharmaceutical manufacturers, calibration laboratory managers, and cold chain logistics operators. Primary interview insights triangulate against FDA 21 CFR Part 11 guidance documents, EU MDR post-market surveillance filings, CDSCO cold chain expansion announcements, and SEC 10-K disclosures from listed automation suppliers. Bottom-up sensor shipment modeling and top-down pharmaceutical capital expenditure aggregation cross-validate volume estimates.
Consistency checks against external benchmarks stress-test projections across the analysis window. Segmentation dimensions include product architecture, application vertical, technology protocol, and end-user compliance tier. CAGRs derive from installed base replacement cycles and regulatory mandate acceleration curves. Forecast inputs incorporate lithium battery cost trajectories and MEMS foundry capacity expansion announcements.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO enforcement regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as EU MDR transition timelines and cybersecurity certification requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Anemometer Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
India Industrial Sensors and Transmitters Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Asia-Pacific MEMS and Sensors Market