
 Digital Pool Thermometers Market | 2026-2036
Digital Pool Thermometers Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Pool Thermometers Market Insights
Asset-light leasing models for pool maintenance equipment are rewriting competitive dynamics in digital thermometer supply. Inkbird leverages its wireless sensor ecosystem to sustain recurring revenue from connected homeowners. ThermoPro anchors its position through specialized handheld precision instruments that dominate the service technician segment.
Digital pool thermometers are electronic temperature sensing devices that measure water temperature through thermistor or infrared sensing elements, typically displaying readings on LCD or LED screens with accuracy ranges of ±0.5°F; they serve commercial and residential aquatic facilities by enabling precise thermal management for bather safety and chemical efficacy. Floating thermometers lead unit volumes due to low replacement costs and universal compatibility, while Bluetooth-enabled devices represent the fastest-expanding margin pool as homeowners demand smartphone integration for remote monitoring. Solar-powered variants remain niche but occupy the premium tier where off-grid installation and sustainability positioning justify higher price points.
The EPA regulates pool pump and heating efficiency standards that indirectly mandate accurate temperature monitoring for compliance documentation, while the FCC governs wireless transmission protocols in connected thermometer models sold across the United States. ISO 9001 quality management standards shape manufacturing benchmarks for sensor calibration and waterproofing integrity. Stakeholders must monitor how evolving smart-home interoperability standards will determine which connectivity protocols become dominant across residential and commercial installation bases.
Market Dynamics
Smart-home interoperability mandates are compressing the connectivity protocol landscape, forcing sensor manufacturers to consolidate around Matter and Bluetooth Low Energy standards or risk exclusion from residential installation specifications.
Growth Catalysts
- EPA Energy Efficiency Guidelines:The agency's documentation requirements for pool heating efficiency create mandatory demand for calibrated temperature sensors in residential and commercial installations.
- Bluetooth Low Energy Integration:Smartphone-native monitoring is virtualizing the traditional thermometer interface, pulling replacement cycles forward among connected homeowners.
- United States Residential Pool Density:Elevated backyard pool ownership rates in Florida, California, and Texas concentrate addressable demand for premium digital sensing equipment.
Market Restraints
- Lithium-Ion Cell Volatility:Battery chemistry cost swings and supply concentration in East Asian processing facilities squeeze margin stability for wireless-enabled device manufacturers.
- Waterproofing Certification Burden:IP68 validation timelines and retesting costs for design iterations extend product development cycles by 4-8 months.
- Mechanical Floating Thermometer Substitution:Analog alternatives at sub-$10 price points retain volume dominance in cost-sensitive commercial maintenance contracts.
Strategic Opportunities
- Sub-Saharan Africa Hospitality Sector:Safari lodge and resort construction in Kenya and South Africa is generating first-time demand for solar-powered off-grid pool monitoring systems.
- European Union F-Gas Regulation:Refrigerant phase-down mandates are accelerating heat pump pool heater adoption, which requires precise temperature feedback loops for efficiency optimization.
- Voice-Assistant Convergence:Integration between temperature sensors and Amazon Alexa or Google Home ecosystems is creating new subscription revenue streams through proactive maintenance alerts.
Industry Challenges
- Firmware Engineering Talent Scarcity:Embedded systems developers with low-power wireless and waterproofing expertise command premium compensation, constraining mid-tier manufacturer expansion.
- Legacy Controller Integration Friction:Proprietary communication protocols in existing pool automation systems from established equipment brands block seamless third-party sensor connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Pool Thermometers Market |
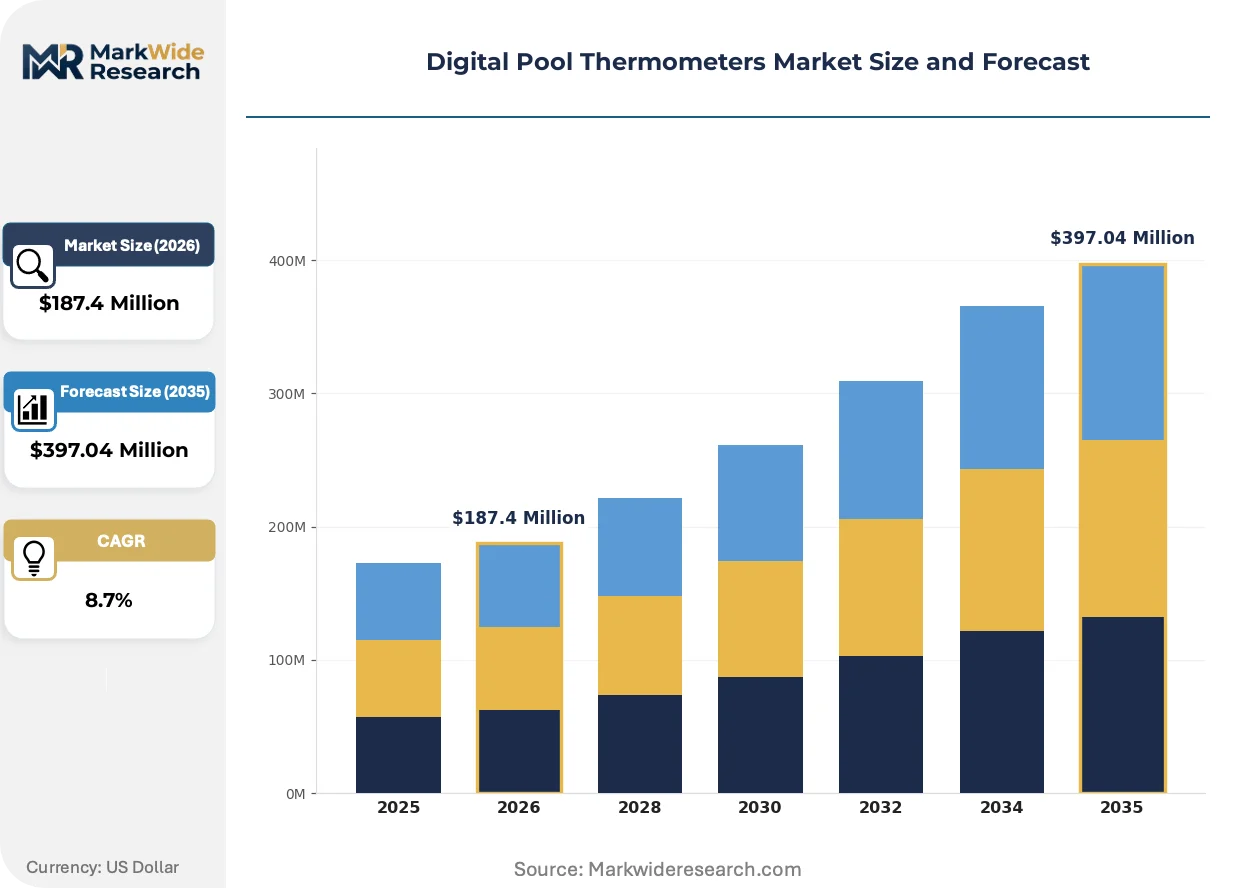
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floating Thermometers, Infrared Thermometers, Handheld Thermometers, Digital Displays Application: Residential Pools, Commercial Pools, Spa Facilities, Hot Tubs Technology: Wireless, Bluetooth, Solar-Powered, Standard Digital End User: Homeowners, Pool Service Providers, Hotels, Recreation Centers |
| Companies Covered | Inkbird, La Crosse Technology, Ambient Weather, AcuRite, ThermoPro, GAME, Ecowitt, Poolmaster, Oregon Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Pool Thermometers Market Trends and Innovations
Sensor miniaturization and edge computing capabilities are redefining what constitutes a pool thermometer, transforming standalone devices into distributed nodes within broader aquatic management systems.
Infrared thermopile arrays are virtualizing the traditional probe-based measurement paradigm. These non-contact sensors eliminate waterproofing failure modes and enable multi-point surface temperature mapping. Luxury residential installers in Scottsdale, Arizona and Naples, Florida are specifying infrared units for infinity-edge pools where submerged sensors disrupt aesthetic continuity. The technology is virtualizing maintenance workflows by enabling drone-mounted thermal scanning for large commercial facilities.
REACH substance restrictions on mercury and cadmium are forcing sensor manufacturers to redesign thermistor formulations. The European Chemicals Agency's candidate list expansions have eliminated several legacy temperature-sensitive resistor compositions from supply chains. German and French distributors now require full material disclosure documentation, shifting procurement qualification criteria toward compliance transparency rather than unit cost alone.
Subscription-based equipment-as-a-service models are displacing outright purchase in the commercial segment. Multi-property hospitality operators in Spain and Portugal are bundling sensor hardware into monthly pool management contracts with guaranteed uptime SLAs. This procurement evolution compresses vendor selection criteria toward predictive analytics capability and nationwide service network coverage rather than device specifications alone.
Digital Pool Thermometers Market Segmentation
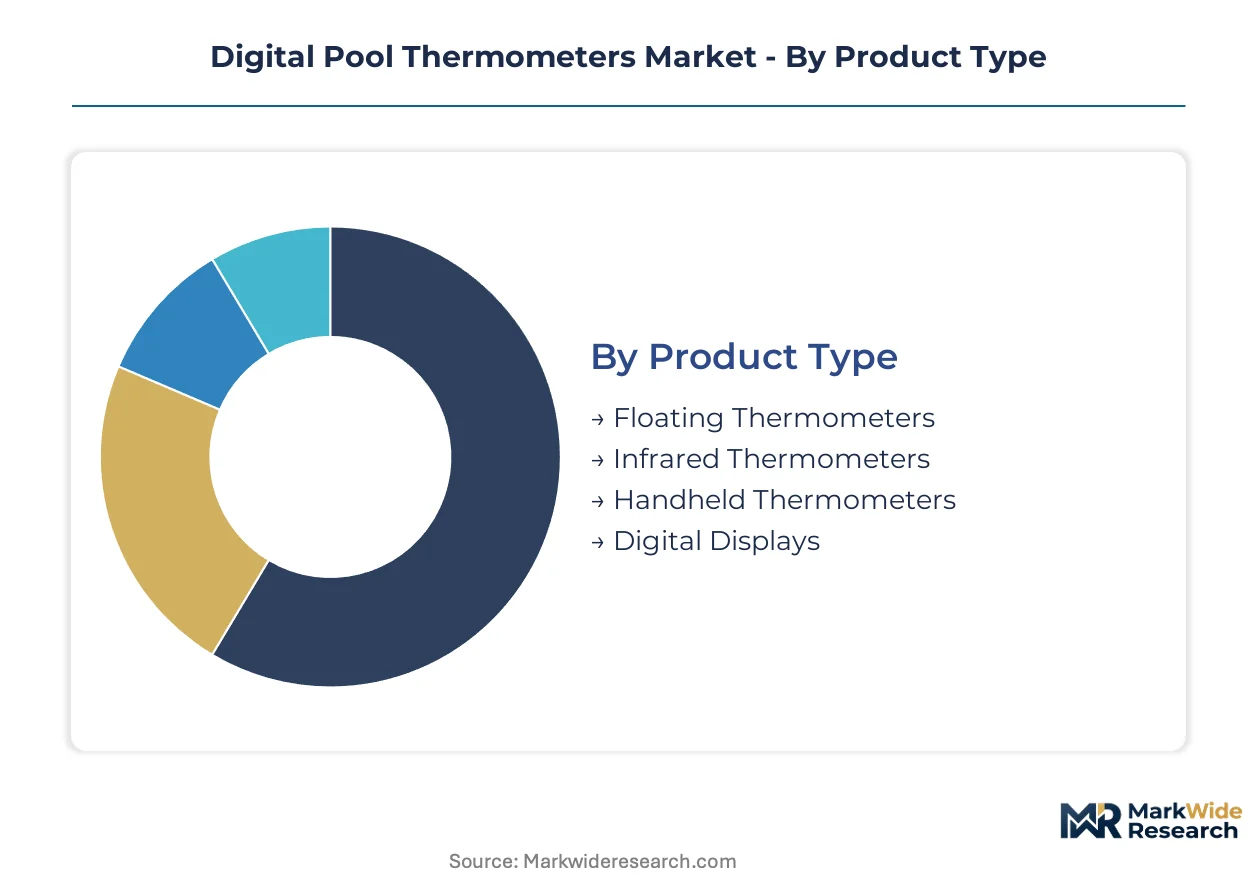
Digital pool thermometers fragment across four distinct dimensions that shape procurement patterns and margin structures. Product type determines waterproofing requirements and replacement cycles. Application context dictates accuracy tolerances and connectivity expectations. Technology selection governs power architecture and smart-home integration pathways. End-user identity separates price-sensitive residential purchases from contract-driven commercial specifications.
Product Type:
Mature floating designs coexist with emerging infrared and handheld precision instruments across diverging price tiers.
- Floating Thermometers:Submerged thermistor probes transmit readings to surface-mounted LCD displays through sealed cable assemblies. Florida and California residential pools drive replacement demand where universal compatibility and sub-$15 price points override connectivity preferences.
- Infrared Thermometers:Non-contact thermopile arrays capture surface temperature signatures without waterproofing vulnerabilities. Luxury infinity-edge installations in Scottsdale and Naples specify these units where submerged sensors disrupt visual continuity.
- Handheld Thermometers:Service technicians favor probe-based precision instruments with ±0.3°F calibration certificates for chemical dosing documentation.
- Digital Displays:Wall-mounted receiver units aggregate multiple sensor feeds for centralized monitoring in commercial pump houses.
Floating thermometers handle the majority of throughput; infrared variants are the fastest mover on share.
Application:
Volume concentrates in residential backyards while margin accumulates in regulated commercial environments with compliance documentation burdens.
- Residential Pools:Backyard installations in Texas, Florida, and California generate the largest addressable base. Smartphone integration and voice-assistant compatibility now dominate purchase criteria among connected homeowners.
- Commercial Pools:Municipal facilities and fitness centers require calibrated sensors with audit trails for health department inspections. EPA energy efficiency documentation mandates accelerate digital adoption in this segment.
- Spa Facilities:Wellness centers prioritize discrete sensor placement and temperature logging for therapeutic protocol validation.
- Hot Tubs:Elevated operating temperatures demand thermistors with expanded calibration ranges beyond standard pool specifications.
Residential pools absorb the highest absolute unit volumes; commercial installations deliver the steepest expansion trajectory as regulatory compliance tightens.
Technology:
Power architecture and connectivity protocol choices increasingly determine vendor selection and replacement timing.
- Wireless:RF-based transmission to dedicated receiver hubs dominates legacy commercial installations where smartphone integration remains secondary.
- Bluetooth:Low-energy protocols enable direct smartphone pairing without intermediary hardware. This segment climbs fastest as Matter interoperability standards consolidate residential smart-home specifications.
- Solar-Powered:Photovoltaic cells eliminate battery replacement cycles in off-grid safari lodges across Kenya and South Africa where sustainability positioning commands premium pricing.
- Standard Digital:Battery-operated LCD units without connectivity features retain dominance in cost-sensitive maintenance contracts.
Standard digital devices maintain the widest installed base; Bluetooth-enabled models gain share fastest as smartphone-native monitoring virtualizes traditional interfaces.
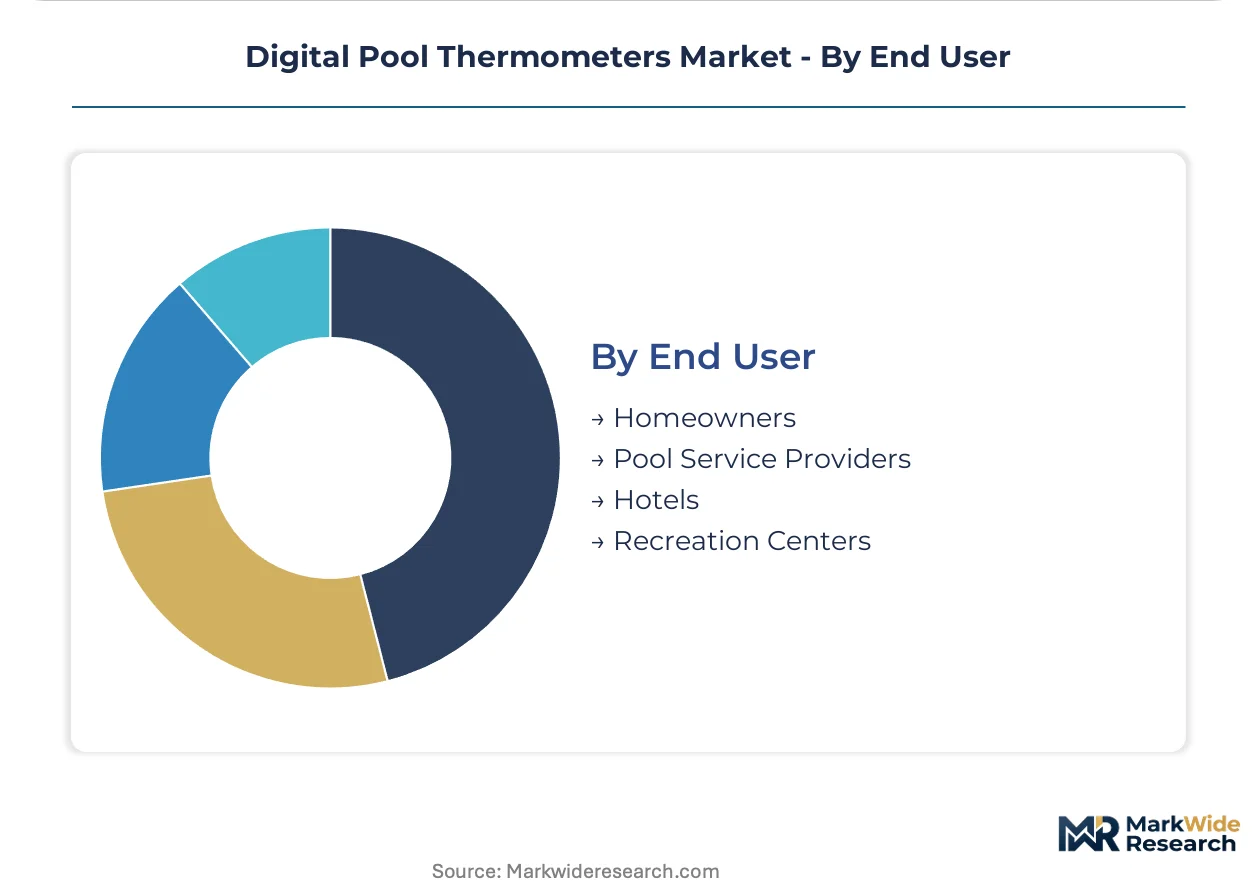
End User:
Procurement authority separates individual purchase decisions from contract-negotiated enterprise specifications.
- Homeowners:Connected consumers in United States metropolitan suburbs prioritize Amazon Alexa and Google Home integration for proactive maintenance alerts.
- Pool Service Providers:Route-based technicians require calibrated handheld instruments with rapid-response probes for chemical balancing workflows.
- Hotels:Multi-property operators in Spain and Portugal are shifting toward equipment-as-a-service bundles with guaranteed uptime SLAs.
- Recreation Centers:Municipal facilities face public procurement rules that favor established suppliers with nationwide service networks.
Homeowners represent the largest addressable population; hotels are expanding most quickly as subscription-based procurement displaces outright purchase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in the United States while German distributors enforce compliance-driven procurement criteria that compress margins for non-certified suppliers.
United States
Florida, California, and Texas backyard pool density sustains the largest addressable base for connected thermometers. EPA energy efficiency documentation mandates for pool heating systems create regulatory pull-through for calibrated sensors. Scottsdale and Naples luxury installers specify infrared non-contact units for infinity-edge pools where submerged sensors disrupt aesthetic continuity.
Germany
REACH substance restrictions on mercury and cadmium force thermistor formulation redesigns across sensor supply chains. ECHA candidate list expansions eliminate legacy temperature-sensitive resistor compositions from procurement options. Bavarian and North Rhine-Westphalian distributors now require full material disclosure documentation, shifting qualification criteria toward compliance transparency.
Spain
Multi-property hospitality operators in Madrid and Barcelona are displacing outright purchase with subscription-based equipment-as-a-service bundles. EU F-Gas Regulation refrigerant phase-down mandates accelerate heat pump pool heater adoption requiring precise temperature feedback loops. Costa del Sol resort construction generates demand for solar-powered off-grid monitoring systems.
Kenya
Safari lodge construction in the Masai Mara and Amboseli corridors generates first-time demand for solar-powered pool monitoring where grid connectivity remains unreliable. The country's national environmental regulator enforces sustainability positioning for hospitality developments near protected reserves. Nairobi-based procurement offices specify photovoltaic-eliminated battery replacement cycles for remote installations.
China
MIIT smart-home interoperability standards consolidate around domestic connectivity protocols that diverge from Matter specifications. Yangtze River Delta manufacturing clusters produce thermistor elements and LCD display modules for export markets. Shenzhen-based electronics assemblers compete on waterproofing IP68 validation speed for Bluetooth-enabled device OEMs.
Digital Pool Thermometers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in sensor and display manufacturing. The vendor base spans wireless ecosystem providers, precision instrument specialists, and private-label pool equipment suppliers. Three archetypes dominate: connected-home platform builders, calibrated handheld instrument makers, and legacy pool maintenance brands. Competitive moves concentrate on smart-home certification partnerships and predictive analytics capability development.
Within the connected-home platform tier, Inkbird and Ecowitt exemplify wireless sensor ecosystem builders that sustain recurring revenue through integrated hardware-software offerings. ThermoPro occupies a position among handheld precision specialists serving route-based service technicians. La Crosse Technology and Ambient Weather sit within the weather monitoring crossover segment where pool temperature sensing extends existing consumer electronics footprints.
| Leading Market Players |
|---|
| Inkbird |
| La Crosse Technology |
| Ambient Weather |
| AcuRite |
| ThermoPro |
| GAME |
| Ecowitt |
| Poolmaster |
| Oregon Scientific |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta freight corridor cost dynamics compress margin buffers for LCD module and thermistor suppliers concentrated in Jiangsu and Zhejiang provinces, amplifying price differentiation between Bluetooth-enabled premium units and standard digital devices while forcing procurement offices in Florida and Texas to absorb logistics volatility through inventory carry costs.
Pricing Analysis
Pool service providers anchor pricing structure around three-tier certification-grade differentiation across ISO 9001-calibrated premium instruments, standard digital units, and economy floating thermometers. Price differentiation hinges on waterproofing IP68 validation depth and FCC wireless certification tier. Cost compression in the economy tier intensifies because analog mechanical substitutes at sub-$10 price points retain contract dominance. Residential homeowners show lowest price sensitivity where smart-home integration commands premium positioning.
Supply Chain Analysis
Extended payment terms from Shenzhen-based electronics assemblers to Yangtze River Delta component suppliers stabilize working capital for Bluetooth-enabled device OEMs. Thermistor elements and lithium-ion cells draw from China, South Korea, and Japan manufacturing clusters. Single-source vulnerability concentrates in East Asian battery chemistry processing facilities. Distribution runs through pool equipment distributors in Florida and California, hospitality procurement offices in Spain and Portugal, and safari lodge developers in Kenya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
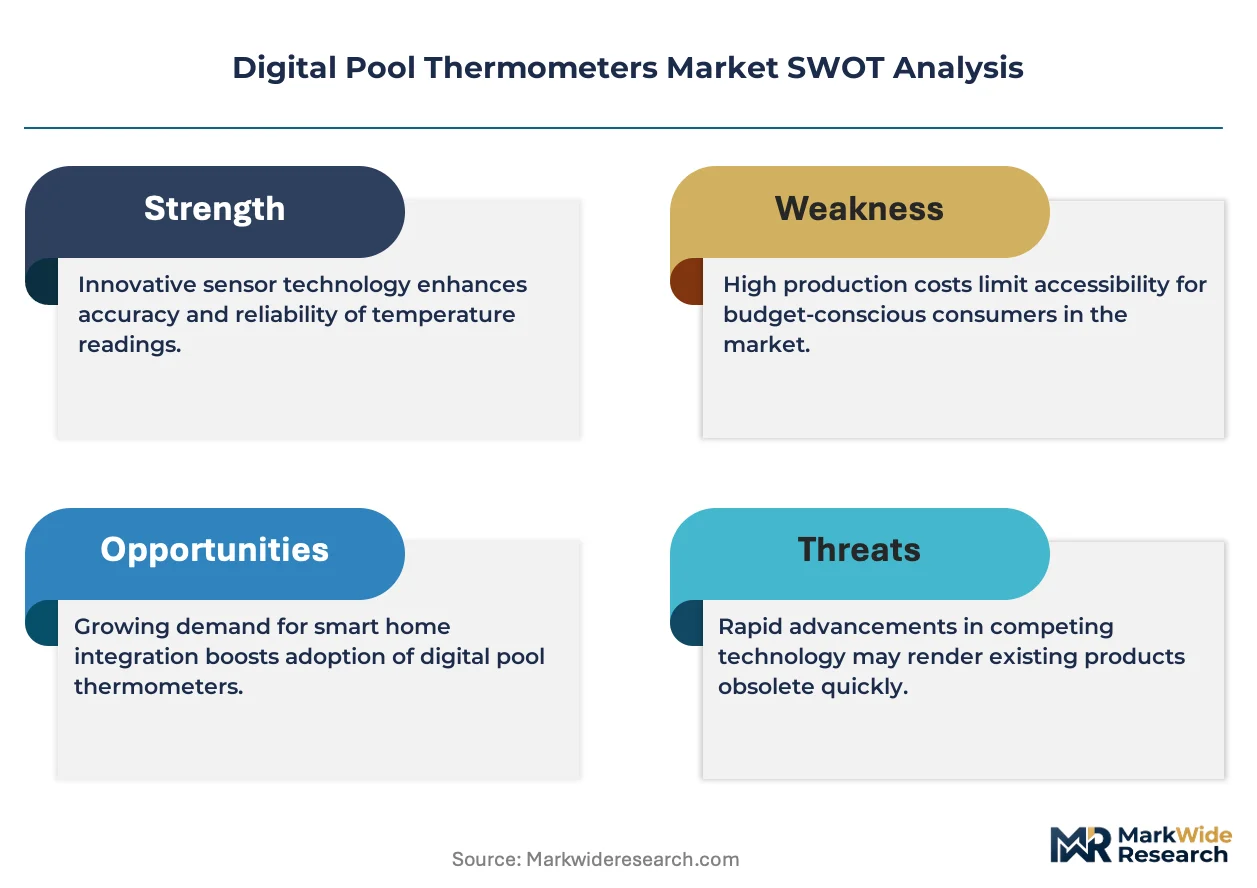
Analog mechanical thermometers represent a persistent substitution threat that digital incumbents must neutralize through connectivity differentiation and compliance documentation bundling.
For Market Incumbents: Pre-empt analog substitution by embedding EPA energy efficiency documentation automation into sensor firmware and consolidating Matter certification partnerships before interoperability standards harden. Vertical integration into thermistor calibration capabilities in Bavaria or Shenzhen defends margin position against component cost volatility. For New Entrants and Emerging Players: Build out solar-powered off-grid monitoring systems for safari lodge construction corridors in Kenya and South Africa where sustainability procurement mandates create first-mover whitespace. Voice-assistant integration partnerships with Amazon Alexa and Google Home ecosystems offer the most penetrable go-to-market angle for residential connected homeowners. For Investors and Strategic Acquirers: Handheld precision instrument specialists with ±0.3°F calibration certificates and established route-based technician relationships present durable acquisition targets as service-provider consolidation accelerates. Long-term viability frames around predictive analytics capability and nationwide service network coverage rather than hardware specifications alone. Watch Matter interoperability certification timelines as inflection indicators for which connectivity protocols achieve residential specification dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Matter Certification Partnership | Smart-home interoperability consolidation in United States residential pools determines protocol survival. |
| Predictive Analytics Development | Equipment-as-a-service bundles in Spanish and Portuguese hospitality require uptime SLA capability. |
| Solar-Powered Product Line | Kenyan safari lodge sustainability mandates generate premium pricing for off-grid installations. |
| IP68 Validation Investment | REACH substance restrictions in Germany force thermistor redesigns with extended certification timelines. |
| Voice-Assistant Integration | Amazon Alexa and Google Home ecosystems create subscription revenue through proactive maintenance alerts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA energy efficiency filings, FCC equipment authorization databases, and ECHA REACH candidate list expansions. Pool equipment distributors, route-based service technicians, hospitality procurement managers, and smart-home integration specialists provided structured input. SEC 10-K disclosures from connected sensor ecosystem builders, customs records for thermistor element trade flows, and ISO 9001 certification registries supplied validation anchors. Bottom-up unit shipment estimates triangulate against top-down addressable pool base calculations.
Forecast inputs incorporate Bluetooth Low Energy adoption curves, Matter interoperability penetration rates, and EPA documentation mandate compliance timelines across the projection horizon. Product type, application context, technology architecture, and end-user procurement authority shape segmentation modeling. CAGRs derive from replacement cycle compression analysis and smart-home integration elasticity estimates. Heat pump pool heater adoption under EU F-Gas Regulation and safari lodge construction permits in Kenya inform scenario-weighted outcomes.
Stress conditions across lithium-ion cell cost volatility, IP68 validation timeline extensions, and analog mechanical substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and smart-home standard consolidation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Russia Non-Contact Infrared Thermometer Market
Sensors and Controls
Smart Flow Meter Market
Sensors and Controls
Fiber Optic Pressure Sensors Market
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
Anemometer Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
GNSS Devices Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
Digital Thermohygrometers Market