
 Electric Pipette Controllers Market | 2026-2036
Electric Pipette Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Pipette Controllers Market Insights
Biotechnology companies are rotating toward electric pipette controllers with programmable functions and ergonomic designs, displacing manual serological pipetting in high-throughput screening environments. Eppendorf leverages its Hamburg-based manufacturing scale to dominate European supply of multi-channel programmable systems. Sartorius anchors premium positioning through R&D intensity in microprocessor-controlled liquid handling platforms. Gilson International differentiates through specialized distribution channels serving academic research institutions across North America.
Electric pipette controllers are motorized handheld or benchtop instruments that aspirate and dispense liquid volumes through piston-driven mechanisms, typically achieving accuracy within ±0.6% for volumes between 1 mL and 100 mL, and serve primarily to reduce repetitive strain injuries while improving reproducibility in serial dilution and cell culture workflows. Multi-channel product types lead unit shipments due to demand from pharmaceutical compound screening, though microprocessor-controlled technology commands the strongest margin pools through calibration memory and programmable step sequences. Battery operated systems compete aggressively on portability for clinical laboratories with limited bench space, while fixed volume variants occupy declining share in mature academic settings.
FDA 21 CFR Part 11 shapes electronic record-keeping requirements for pharmaceutical and clinical laboratory deployments, compelling vendors to embed audit-trail capabilities in programmable units. ISO 8655 standards for piston-operated volumetric apparatus define accuracy and precision benchmarks that manufacturers must meet for European CE marking and US commercial access. EPA Good Laboratory Practice guidelines extend traceability demands to environmental testing laboratories using these instruments. Stakeholders must monitor evolving battery chemistry regulations under EU Battery Directive amendments and decide between integrated versus swappable power architectures before next-generation platform commitments.
Market Dynamics
Programmable microprocessor architecture is compressing replacement cycles across pharmaceutical quality control laboratories, as FDA 21 CFR Part 11 compliance mandates audit-trail capabilities in electronic record-keeping systems.
Growth Catalysts
- Regulatory digitization mandates:FDA 21 CFR Part 11 requirements for electronic records and signatures in pharmaceutical laboratories are accelerating equipment refresh cycles toward programmable units with embedded compliance features.
- Biotechnology workflow automation:High-throughput screening operations in drug discovery are rotating procurement toward multi-channel electric systems that reduce repetitive strain injuries while improving serial dilution reproducibility.
- Precision manufacturing clusters:Concentrated R&D activity around Hamburg and Goettingen in Germany is sustaining innovation pipelines for microprocessor-controlled liquid handling platforms serving European life sciences.
Market Restraints
- Lithium-ion battery chemistry constraints:EU Battery Directive amendments are imposing stricter recycling and substance restrictions on portable electric pipette controllers, complicating power architecture decisions for manufacturers.
- Manual pipette substitution persistence:Fixed-volume manual serological pipettes retain cost advantages in mature academic settings with constrained capital budgets, limiting electric system penetration in education segments.
- Calibration infrastructure concentration:ISO 8655 compliance testing capabilities cluster in Western European and North American metrology labs, creating service access barriers for remote clinical laboratories in emerging markets.
Strategic Opportunities
- Cell and gene therapy manufacturing:Aseptic processing requirements in commercial-scale cell therapy production are opening demand for programmable electric systems with GMP-compliant audit trails and sterilizable components.
- Contract research organization channel expansion:Direct distribution partnerships with CROs serving pharmaceutical outsourcing are bypassing traditional academic distributor networks to capture compound screening volume.
- India PLI scheme alignment:Production-linked incentive schemes for medical devices are attracting component localization investments that could reshape cost structures for battery-operated systems in price-sensitive Asian markets.
Industry Challenges
- Metrology technician scarcity:ISO 8655 calibration expertise concentrates in aging specialist workforces, constraining service capacity expansion as installed bases of programmable units grow.
- Legacy LIMS integration complexity:Pharmaceutical laboratories running decade-old laboratory information management systems face middleware development costs to connect programmable pipette audit trails with centralized data repositories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Pipette Controllers Market |
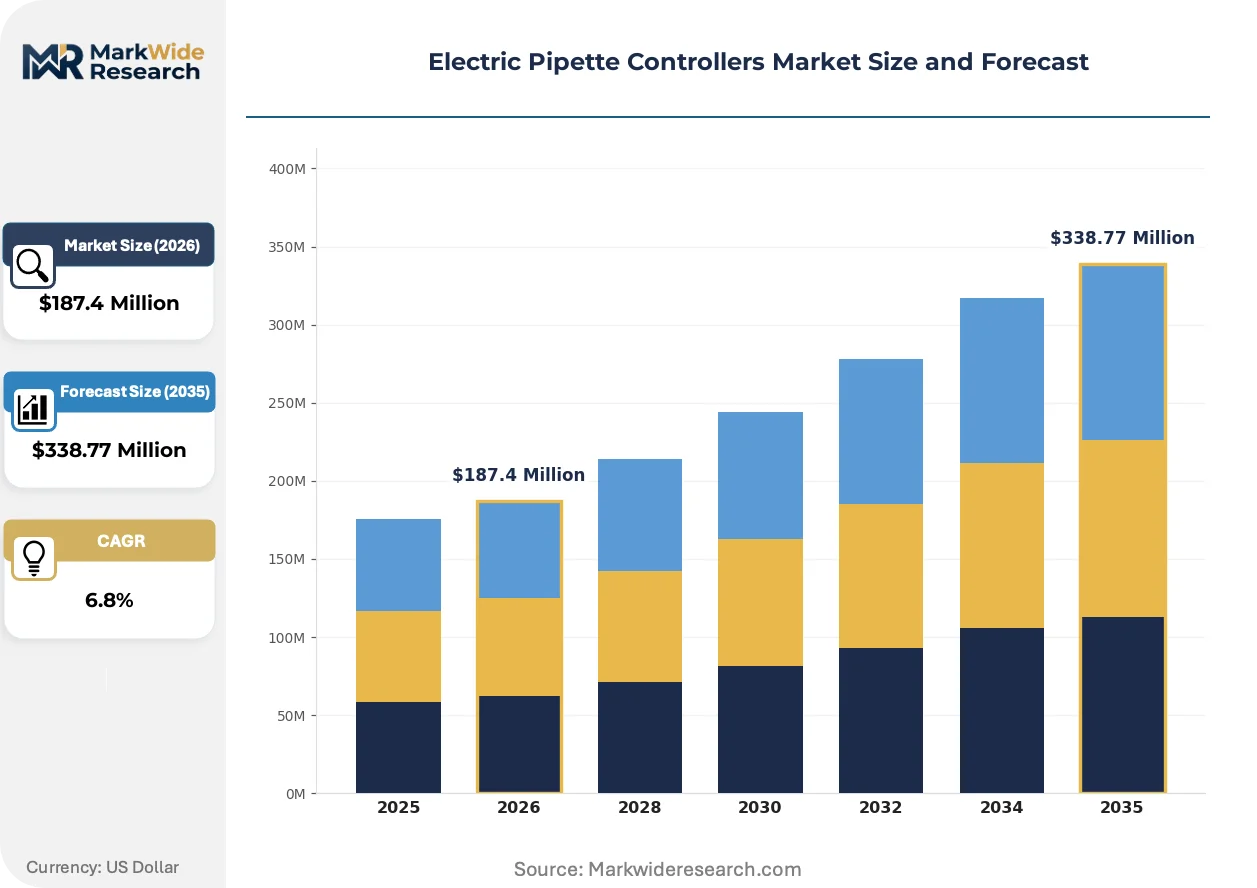
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Channel, Multi-Channel, Adjustable Volume, Fixed Volume End User: Research Institutions, Pharmaceuticals, Clinical Laboratories, Biotechnology Companies Application: Sample Preparation, Liquid Handling, Drug Testing, Academic Research Technology: Microprocessor-Controlled, Battery Operated, Ergonomic Design, Programmable Functions |
| Companies Covered | Sartorius, Avantor, Gilson International, Mettler Toledo, BRANDTECH Scientific, Drummond Scientific Company, Merck, Bio-Rad Laboratories, Eppendorf, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Pipette Controllers Market Trends and Innovations
Microprocessor-controlled liquid handling is decomposing traditional boundaries between handheld portability and benchtop precision, as battery chemistry advances and miniaturized motor designs enable new form factors.
Brushless DC motor technology with integrated encoder feedback is decomposing the accuracy-versus-portability trade-off that previously segmented the market. Pharmaceutical quality control laboratories are adopting these systems for GMP environments where ±0.6% precision must coexist with flexible workflow layouts. The structural consequence is collapsing demand for separate fixed-station and mobile product categories.
EMA's evolving GMP Annex 11 guidance on computerized systems is extending qualification requirements to programmable laboratory equipment. Manufacturers must now embed electronic signature capabilities and tamper-evident data storage directly into controller firmware. European pharmaceutical contract manufacturers are responding by consolidating vendor lists to suppliers with pre-validated compliance packages.
Academic research consortia are unbundling after-sales service contracts from equipment purchases, opting instead for third-party metrology providers or in-house calibration programs. This procurement pattern disrupts traditional distributor margins that relied on captive service revenue. North American research universities are driving this shift most aggressively, pressuring manufacturers to open technical documentation and reduce proprietary lock-in.
Electric Pipette Controllers Market Segmentation
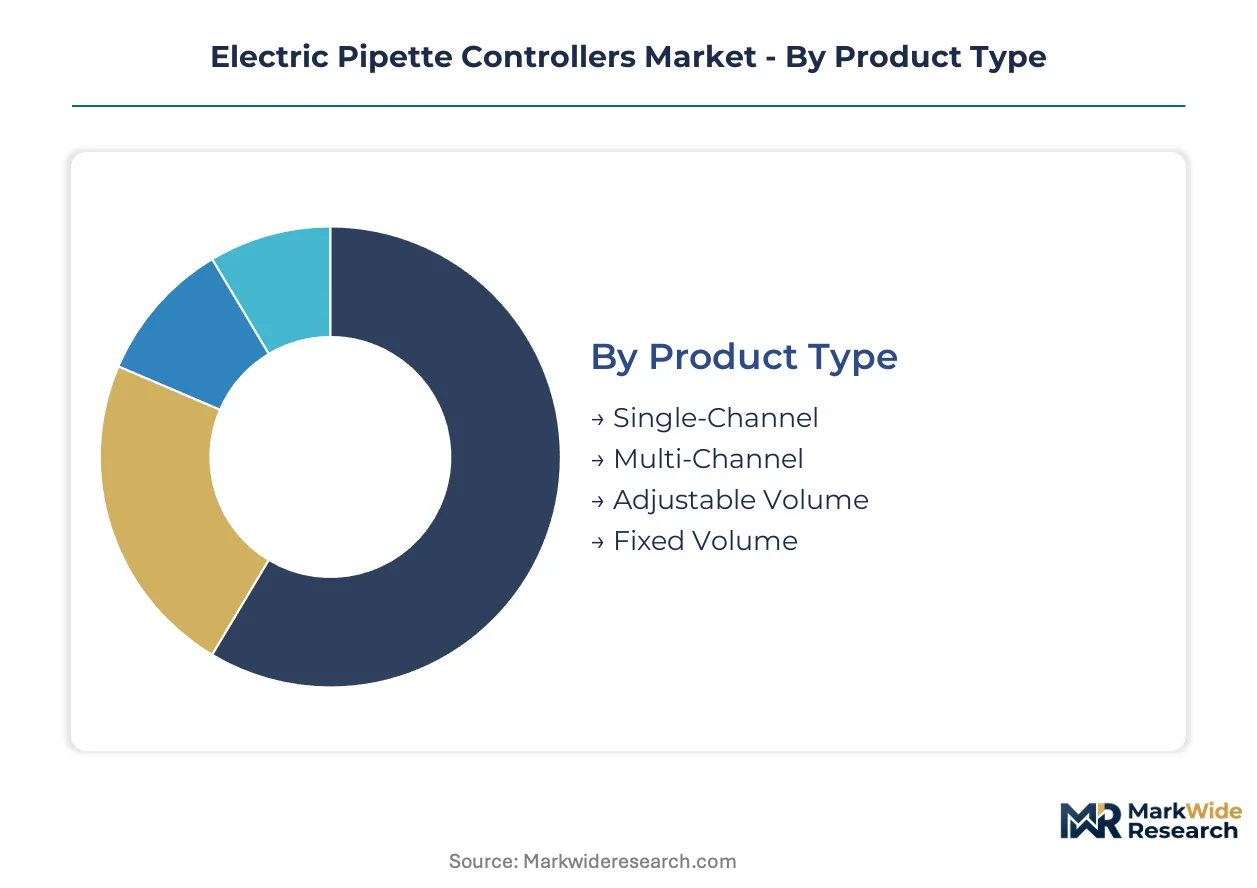
Electric pipette controller procurement patterns diverge sharply across laboratory settings, with pharmaceutical quality control prioritizing compliance-enabled programmable systems while academic buyers optimize for capital efficiency. Segmentation reveals where margin pools concentrate and which technology architectures are compressing legacy categories.
Product Type:
Microprocessor-controlled multi-channel systems command the strongest margin pools through embedded calibration memory and programmable step sequences that pharmaceutical laboratories require for FDA 21 CFR Part 11 compliance.
- Multi-Channel:Motorized systems aspirate and dispense across 8-12 channels simultaneously, achieving throughput rates essential for high-throughput screening workflows in drug discovery operations. Demand concentrates in Germany around Hamburg and Goettingen precision manufacturing clusters where Eppendorf and Sartorius anchor innovation pipelines for pharmaceutical compound screening.
- Single-Channel:Individual piston-driven mechanisms serve cell culture workflows and serial dilution protocols where volume flexibility outweighs throughput requirements. Biotechnology companies in North American research corridors are rotating procurement toward ergonomic variants that reduce repetitive strain injuries during extended pipetting sessions.
- Adjustable Volume:Variable-range mechanisms span 1-100 mL with ±0.6% accuracy specifications, serving contract research organizations with diverse protocol requirements.
- Fixed Volume:Locked-calibration designs occupy declining share in mature academic settings with constrained capital budgets.
Multi-channel systems hold installed capacity in pharmaceutical quality control. Adjustable volume configurations are rotating up the share rankings in CRO channel expansion.
End User:
Volume concentration sits with research institutions, though biotechnology companies are driving the steepest expansion trajectory through programmable system procurement for automated workflows.
- Biotechnology Companies:Commercial-scale cell and gene therapy manufacturers require GMP-compliant audit trails and sterilizable components for aseptic processing environments. FDA 21 CFR Part 11 mandates are accelerating replacement cycles toward microprocessor-controlled units with embedded electronic signature capabilities.
- Pharmaceuticals:Quality control laboratories operate under EMA GMP Annex 11 guidance extending qualification requirements to computerized laboratory equipment. European contract manufacturers are consolidating vendor lists to suppliers with pre-validated compliance packages.
- Research Institutions:Academic consortia unbundle after-sales service contracts, opting for third-party metrology providers and pressuring manufacturers to open technical documentation.
- Clinical Laboratories:Battery-operated systems compete aggressively on portability where limited bench space constrains equipment deployment.
Research institutions hold installed capacity across North American and European geographies. Biotechnology companies are climbing the fastest in procurement volume rankings.
Application:
Margin capture concentrates in liquid handling workflows where reproducibility requirements justify premium positioning for programmable architectures.
- Liquid Handling:Serial dilution and cell culture protocols demand piston-driven precision with encoder feedback mechanisms. Brushless DC motor technology with integrated feedback is collapsing traditional boundaries between handheld portability and benchtop accuracy.
- Sample Preparation:Pre-analytical processing in clinical laboratories requires traceability documentation under EPA Good Laboratory Practice guidelines for environmental testing workflows.
- Drug Testing:Pharmaceutical quality control operations deploy multi-channel systems for compound screening with tamper-evident data storage embedded in controller firmware.
- Academic Research:Fixed-volume manual substitution persists in education segments where capital budgets constrain electric system penetration.
Liquid handling holds installed capacity across pharmaceutical and biotechnology deployments. Sample preparation is gaining share fastest in clinical laboratory channel expansion.
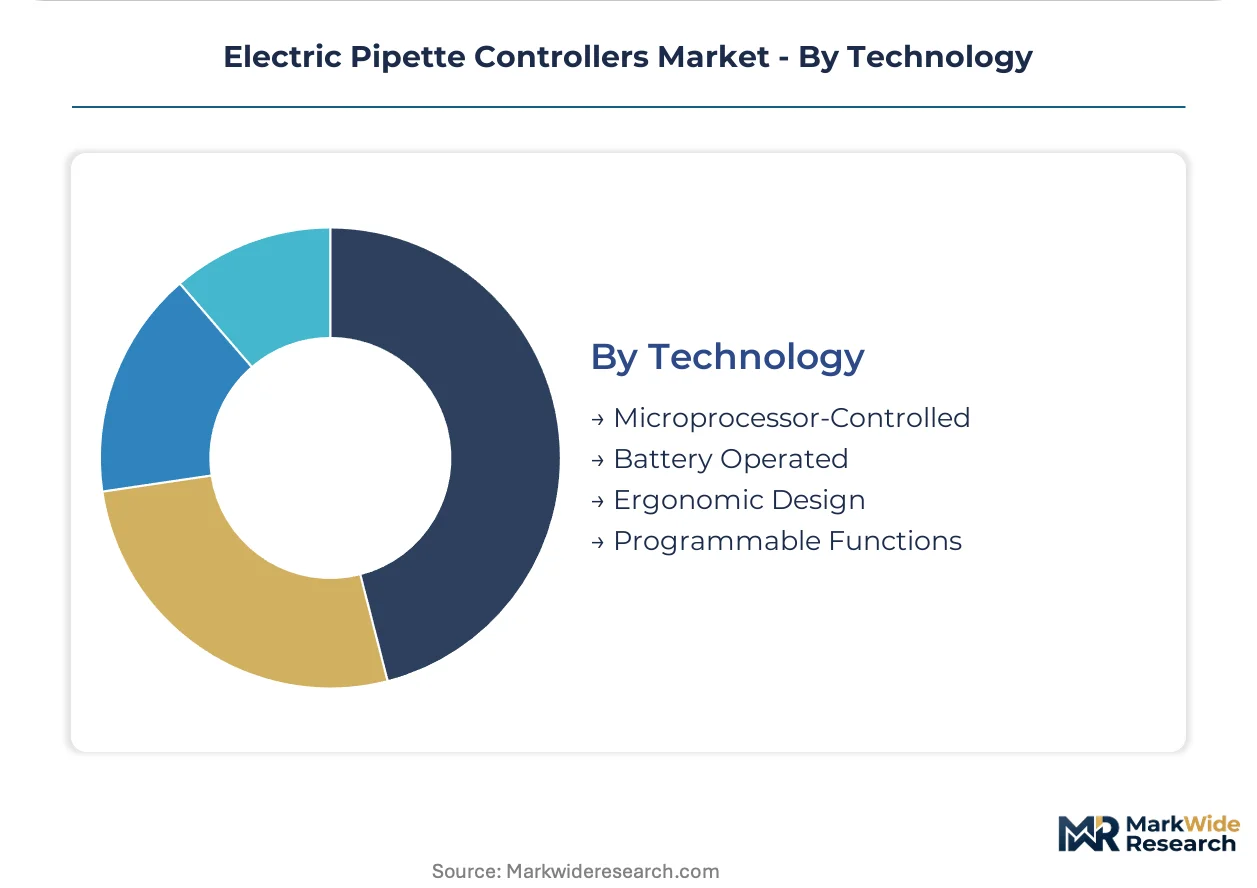
Technology:
Programmable microprocessor architecture captures premium pricing through compliance-enabled features that manual and basic battery systems cannot replicate.
- Microprocessor-Controlled:Embedded calibration memory and programmable step sequences enable audit-trail capabilities required for FDA 21 CFR Part 11 electronic record-keeping. EMA GMP Annex 11 guidance extends qualification requirements to these computerized systems.
- Programmable Functions:Electronic signature capabilities and tamper-evident data storage address pharmaceutical laboratory mandates for centralized data repository integration.
- Battery Operated:Lithium-ion power architectures face EU Battery Directive amendment constraints on recycling and substance restrictions, complicating manufacturer design decisions between integrated versus swappable configurations.
- Ergonomic Design:Reduced repetitive strain injury risk drives procurement rotation in high-throughput screening environments where technician retention carries operational cost implications.
Microprocessor-controlled systems hold installed capacity in regulated pharmaceutical environments. Programmable functions are rotating up the share rankings through compliance-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters export programmable liquid handling systems to pharmaceutical quality control laboratories across the United States and Japan, anchoring high-value trade flows in regulated life sciences equipment.
United States
FDA 21 CFR Part 11 compliance mandates drive procurement of audit-trail-enabled programmable units in pharmaceutical quality control laboratories. The EPA extends Good Laboratory Practice traceability requirements to environmental testing workflows using these instruments. Greater Boston anchors commercial-scale cell and gene therapy manufacturing demand for GMP-compliant sterilizable systems.
Germany
EMA GMP Annex 11 guidance on computerized systems extends qualification requirements to programmable laboratory equipment in pharmaceutical contract manufacturing. The EU Battery Directive imposes stricter recycling obligations on lithium-ion powered portable units. Hamburg and Goettingen precision manufacturing clusters sustain innovation pipelines for microprocessor-controlled multi-channel platforms.
Japan
PMDA quality management system requirements align with international GMP standards for electronic record-keeping in pharmaceutical laboratories. METI industrial policy supports domestic production of precision laboratory instrumentation. The Kanto region around Tokyo concentrates biotechnology company procurement for high-throughput screening automation.
India
CDSCO medical device regulations and the PLI scheme for domestic manufacturing attract component localization investments in battery-operated systems. Price-sensitive clinical laboratories in metropolitan areas drive demand for portable units with limited bench space constraints. Maharashtra and Karnataka biotechnology corridors expand procurement of programmable systems for contract research operations.
China
NMPA medical device registration requirements govern commercial access for imported programmable liquid handling platforms. SAMR standardization initiatives align domestic product specifications with ISO 8655 volumetric accuracy benchmarks. The Yangtze River Delta pharmaceutical manufacturing belt accelerates replacement cycles toward compliance-enabled electronic record-keeping systems.
Electric Pipette Controllers Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities, creating a tiered structure where scale advantages in programmable architecture coexist with niche positioning in ergonomic portability. Market concentration reflects R&D intensity in microprocessor-controlled platforms and captive distribution relationships with pharmaceutical quality control laboratories. Three archetypes dominate: diversified life sciences conglomerates with validated compliance packages, precision instrumentation specialists with concentrated liquid handling portfolios, and regional fabricators competing on cost-adjusted specifications for price-sensitive academic channels. Competitive moves center on pre-validated firmware packages for GMP environments and direct distribution partnerships bypassing traditional academic reseller networks.
Among diversified life sciences conglomerates, Sartorius and Merck exemplify archetypes with integrated compliance capabilities spanning programmable laboratory equipment. Eppendorf occupies a position within the precision instrumentation specialist tier, representing German manufacturing scale in multi-channel programmable systems. These three companies anchor the competitive landscape through differentiated positioning across regulatory validation depth and geographic manufacturing concentration.
| Leading Market Players |
|---|
| Sartorius |
| Avantor |
| Gilson International |
| Mettler Toledo |
| BRANDTECH Scientific |
| Drummond Scientific Company |
| Merck |
| Bio-Rad Laboratories |
| Eppendorf |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with Hamburg and Goettingen precision manufacturing clusters lock in component supply visibility for microprocessor-controlled platforms while insulating pharmaceutical buyers from lithium-ion battery chemistry volatility under evolving EU Battery Directive amendments.
Pricing Analysis
Current-generation microprocessor-controlled systems command substantial premiums over prior-generation battery-operated units and declining fixed-volume manual alternatives. Three-tier pricing structure across premium programmable, standard multi-channel, and economy portable levels reflects FDA 21 CFR Part 11 certification grade and embedded audit-trail capabilities. Pricing pressure stems from academic consortia unbundling after-sales service contracts and pressuring manufacturers to open technical documentation. Biotechnology companies exhibit lowest price sensitivity due to GMP compliance mandates, while education segments in emerging markets remain most cost-constrained.
Supply Chain Analysis
Inventory cycles for brushless DC motor assemblies and encoder feedback modules extend lead times for programmable platform fulfillment beyond standard battery-operated configurations. Component manufacturing concentrates in Germany, China, and Japan, with precision piston mechanisms and microprocessor boards drawing from specialized automotive and industrial automation supplier networks. Single-source vulnerability sits with EU-sourced lithium-ion cells facing recycling obligation uncertainty under Battery Directive amendments. Distribution runs through life sciences distributors serving academic channels and direct partnerships with pharmaceutical quality control laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric pipette controller penetration sits at early-cycle expansion, with FDA 21 CFR Part 11 digitization mandates in pharmaceutical quality control laboratories accelerating replacement cycles toward compliance-enabled programmable architectures.
For Market Incumbents: Shield installed base relationships in pharmaceutical quality control by embedding pre-validated GMP compliance packages that reduce customer qualification burden under EMA Annex 11 guidance. Deepen backward integration into brushless DC motor production to control encoder feedback module supply against automotive sector demand competition. Fortify Hamburg and Goettingen manufacturing scale to defend margin position against emerging Asian fabricators targeting price-sensitive academic channels.
For New Entrants and Emerging Players: Anchor in India PLI scheme incentives for medical device component localization to reshape cost structures for battery-operated systems serving clinical laboratories with limited bench space. Target contract research organization direct distribution partnerships bypassing traditional academic reseller networks to capture compound screening volume with programmable multi-channel platforms. Exploit metrology technician scarcity in emerging markets by offering third-party calibration service capabilities as differentiated attach.
For Investors and Strategic Acquirers: Capital is best deployed toward precision instrumentation specialists with concentrated liquid handling portfolios and established FDA 21 CFR Part 11 validation packages rather than diversified conglomerates with competing capital priorities. Long-term viability over the next decade hinges on firmware architecture differentiation and GMP compliance depth rather than manufacturing scale alone. Monitor CDSCO medical device registration acceleration in India as inflection indicator for Asian market structural shift.
| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Validated Compliance Package Development | Reduces pharmaceutical customer qualification burden under EMA GMP Annex 11 guidance. |
| Direct CRO Distribution Partnership | Bypasses academic reseller networks to capture compound screening volume in drug discovery. |
| India PLI Scheme Alignment | Attracts component localization investments reshaping cost structures for battery-operated systems. |
| Third-Party Calibration Service Launch | Exploits metrology technician scarcity constraining service capacity expansion in emerging markets. |
| Brushless DC Motor Backward Integration | Secures encoder feedback module supply against competing automotive sector demand. |
Research Methodology
Initial hypotheses were tested against primary input from laboratory operations managers, pharmaceutical quality control directors, biomedical equipment procurement leads, and third-party metrology service providers and refined through secondary validation against FDA 21 CFR Part 11 guidance documents, EMA GMP Annex 11 computerized system qualification frameworks, ISO 8655 piston-operated volumetric apparatus standards, and EU Battery Directive amendment regulatory filings. Bottom-up segmentation modeling triangulated against top-down industry aggregation.
Variance decomposition across technology generation, end-user compliance tier, and geographic regulatory cluster shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro pharmaceutical R&D expenditure trends and biotechnology workflow automation penetration curves. Forecast inputs incorporated brushless DC motor adoption trajectories and lithium-ion battery chemistry substitution timelines.
Decision-makers should treat outputs as directional under stable regulatory digitization momentum and intact precision manufacturing cluster capacity; material deviation in FDA enforcement intensity or EU Battery Directive implementation timing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Global Proximity and Displacement Sensors Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Non-Glass Capacitive Sensors Market
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
MEMS for Mobile Devices Market