
 South Korea Sensors Market | 2026-2036
South Korea Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Sensors Market Insights
The South Korea sensors market is shifting toward a clear split between automotive-grade precision components and mass-market consumer electronics variants. Samsung Electronics dominates memory-integrated sensor modules through captive semiconductor capacity. LG Innotek anchors optical sensing supply chains for smartphone camera arrays. TDK Corporation leverages magnetic sensor expertise to serve robotics and factory automation buyers in Gyeonggi Province.
Sensors are transducer devices that convert physical stimuli—temperature, pressure, light, or magnetic fields—into measurable electrical signals, typically operating across voltage ranges from millivolts to standard logic levels for microcontroller interfacing. Their primary purpose spans process control, environmental safety, and human-machine interface applications in industrial and consumer systems. Pressure sensors and proximity sensors lead product-type revenue pools due to automotive electrification mandates and smart factory deployments. Optical sensors and capacitive sensors represent the fastest-expanding technology categories, driven by biometric authentication and touchless interface trends across healthcare and consumer electronics end-use segments.
MFDS medical device regulations enforce electromagnetic compatibility and biocompatibility standards for wearable health sensors, while K-Safety certification mandates flame-resistant housing materials for industrial proximity sensors deployed in petrochemical facilities. The Korea Agency for Technology and Standards operates mandatory conformity assessment schemes that foreign suppliers must clear before public procurement eligibility. Stakeholders must monitor evolving CE-Korea mutual recognition negotiations and domestic content requirements under the National Strategic Technology designation process.
Market Dynamics
Automotive electrification mandates and smart factory deployments are compressing procurement cycles for precision sensing components across South Korea's industrial corridors.
Growth Catalysts
- K-Safety Certification Expansion:Mandatory flame-resistant housing standards for industrial proximity sensors deployed in petrochemical facilities are forcing upgrades across existing installed bases.
- Semiconductor Fab Expansion:Process control sensor procurement from Pyeongtaek and Yongin fabrication complexes is accelerating as memory and logic capacity additions come online.
- Biometric Authentication Mandates:Healthcare and financial services sectors are driving optical sensor integration for fingerprint and facial recognition access systems.
Market Restraints
- Raw Material Concentration:Rare earth element supply for magnetic sensor cores remains concentrated through a narrow band of overseas processors, exposing Korean manufacturers to input volatility.
- Technical Limitation:MEMS pressure sensors face drift calibration challenges in high-temperature automotive exhaust monitoring applications above 600°C operational thresholds.
- Regulatory Friction:MFDS electromagnetic compatibility testing timelines for wearable health sensors extend commercialization cycles by eight to fourteen months versus consumer electronics categories.
Strategic Opportunities
- Underpenetrated Medical Robotics:Daegu and Daejeon hospital clusters present untapped demand for haptic feedback sensors in surgical automation systems.
- Regulatory Tailwind:National Strategic Technology designation pathways offer domestic content preference eligibility for sensors qualifying under advanced manufacturing criteria.
- Technology Convergence:Edge AI inference chips married with environmental sensors are opening predictive maintenance contracts in Gwangju automotive supplier parks.
Industry Challenges
- Specialized Talent Scarcity:Mixed-signal circuit design expertise for sensor fusion architectures remains concentrated among a limited pool of experienced engineers in Seongnam and Suwon.
- Certification Bottlenecks:Korea Agency for Technology and Standards conformity assessment queue times for foreign suppliers delay public procurement eligibility by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Sensors Market |
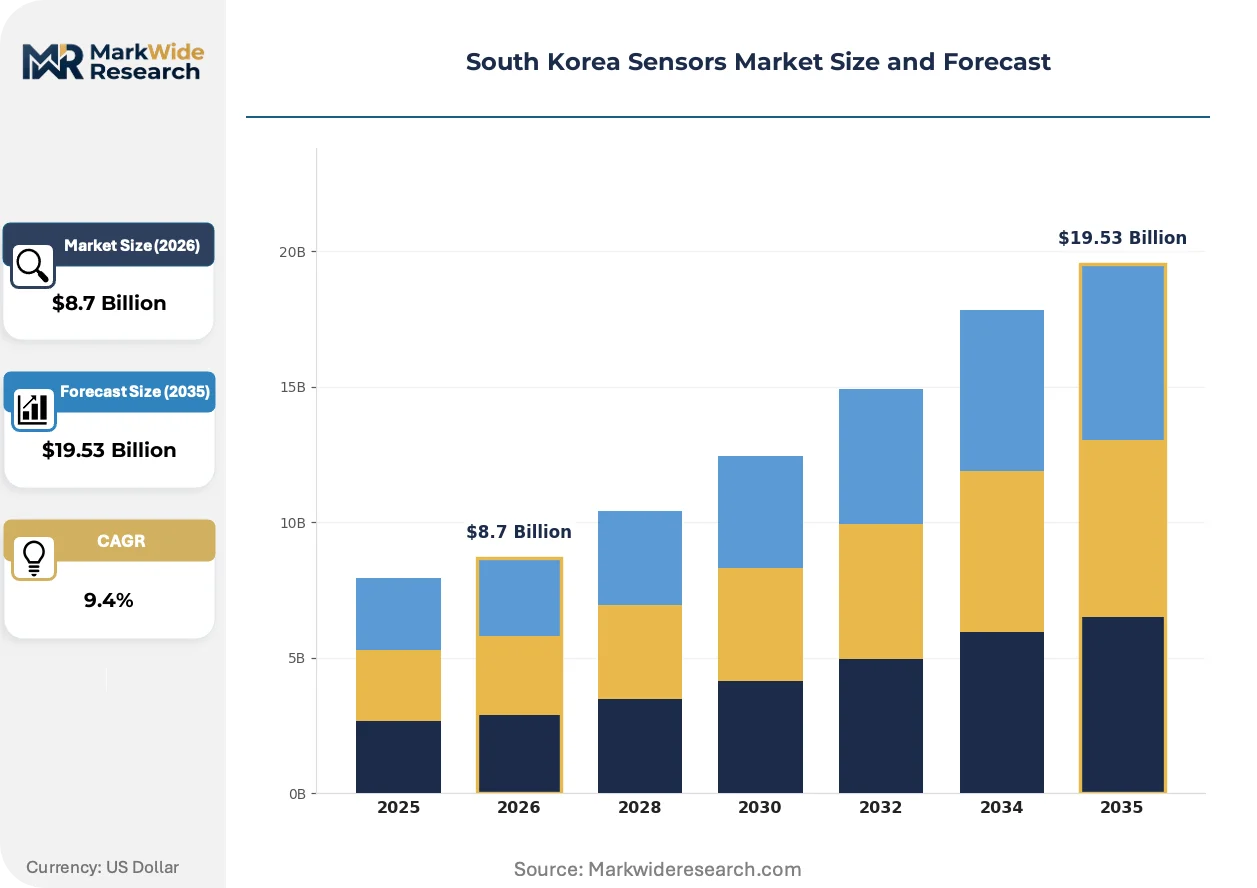
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Humidity Sensors Technology: Optical Sensors, Ultrasonic Sensors, Capacitive Sensors, Magnetic Sensors End User: Automotive, Healthcare, Manufacturing, Transportation Application: Industrial Automation, Smart Homes, Environmental Monitoring, Wearable Devices |
| Companies Covered | TDK Corporation, LG Innotek, ams OSRAM AG, Honeywell International, Infineon Technologies AG, STMicroelectronics, Samsung Electronics, Sensirion AG, Bosch Sensortec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Sensors Market Trends and Innovations
Sensor architectures are converging around multi-modal fusion platforms that compress discrete component counts while elevating measurement fidelity for precision industrial applications.
Time-of-flight optical arrays are unifying depth sensing, ambient light detection, and proximity measurement into single-module formats. Automotive tier-one suppliers around Ulsan are specifying these consolidated units for cabin occupancy monitoring and gesture control interfaces. This unification is collapsing the traditional three-supplier model for discrete optical functions into single-source procurement relationships.
MFDS medical device regulations are tightening biocompatibility and electromagnetic compatibility thresholds for wearable health sensors. Manufacturers must now submit extended cytotoxicity testing protocols before market authorization. Wearable pulse oximetry and continuous glucose monitoring segments are responding by establishing dedicated regulatory affairs teams and pre-submission consultation pathways.
Automotive buyers are consolidating sensor procurement through long-term supply agreements that bundle volume commitments with joint development obligations. Direct OEM-supplier engineering collaboration is displacing the traditional tiered distributor model for pressure and position sensing categories. This pattern is most visible in Gwangju and Ulsan supplier parks where Hyundai Motor Group affiliates dominate component sourcing decisions.
South Korea Sensors Market Segmentation
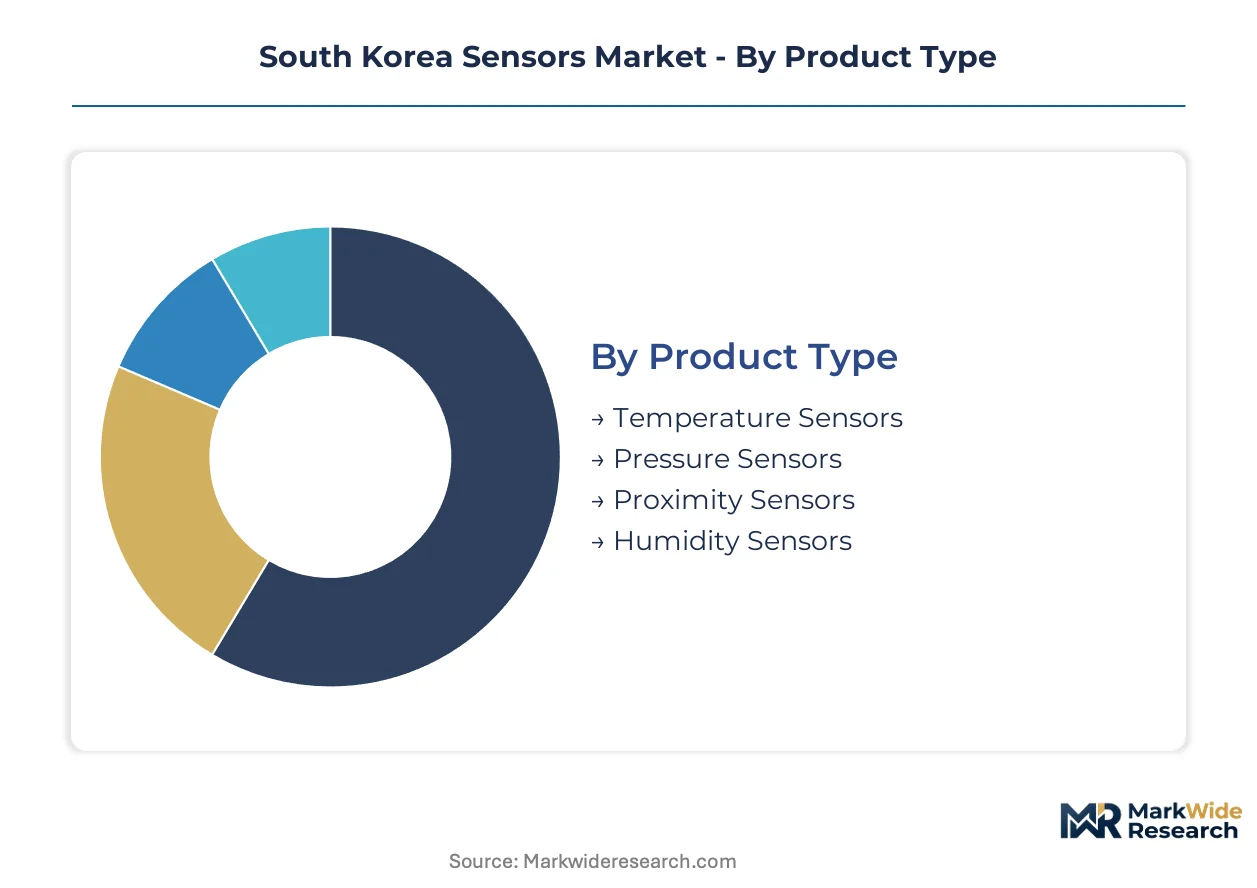
South Korea's sensor market segments reveal a bifurcation between precision industrial components and high-volume consumer variants. Each dimension carries distinct certification burdens and procurement patterns that shape supplier positioning.
Product Type:
Standardization dominates temperature and humidity variants, while pressure and proximity sensors demand extensive customization for automotive and petrochemical end-uses.
- Temperature Sensors:Thermocouple and RTD configurations serve semiconductor fab process control in Pyeongtaek. K-Safety flame-resistant housing mandates are forcing upgrades across petrochemical installations in Ulsan.
- Pressure Sensors:MEMS piezoresistive elements convert mechanical strain into electrical signals for exhaust monitoring and brake systems. Hyundai Motor Group affiliates in Gwangju specify automotive-grade variants with drift calibration protocols for 600°C operational thresholds.
- Proximity Sensors:Inductive and capacitive proximity detection units deploy in smart factory conveyor systems. Yongin logistics hubs specify IP67-rated housings for dust-heavy environments.
- Humidity Sensors:Thin-film capacitive elements measure moisture in cleanroom environments. Samsung Electronics memory fabs specify these for wafer storage climate control.
Most installed capacity flows through Pressure Sensors. Expansion is steepest in Proximity Sensors.
Technology:
Optical and capacitive technologies command premium pricing for biometric applications, while ultrasonic and magnetic variants serve cost-sensitive industrial automation.
- Optical Sensors:Time-of-flight arrays unify depth sensing, ambient light detection, and proximity measurement. Automotive tier-one suppliers around Ulsan consolidate these functions into single-module formats for cabin occupancy monitoring.
- Capacitive Sensors:Electrode-based touch detection enables fingerprint authentication and gesture interfaces. Financial services sectors in Seoul drive optical-capacitive fusion for secure access systems.
- Ultrasonic Sensors:Piezoelectric transducers emit high-frequency pulses for distance measurement. Parking assistance systems in domestic vehicle platforms specify these for obstacle detection.
- Magnetic Sensors:Hall-effect and magnetoresistive elements detect field variations for position tracking. Rare earth element supply concentration through overseas processors exposes Korean manufacturers to input volatility.
Magnetic Sensors anchor the largest installed base. Optical Sensors are gaining share fastest.
End User:
Automotive and manufacturing buyers consolidate procurement through long-term agreements, while healthcare and transportation segments fragment across specialized distributors.
- Automotive:Tier-one suppliers specify pressure, position, and optical sensors for electrification mandates. Direct OEM-supplier engineering collaboration displaces traditional distributor models in Gwangju and Ulsan supplier parks.
- Manufacturing:Smart factory deployments in Gyeonggi Province compress procurement cycles for precision sensing components. Robotics and automation lines specify multi-modal fusion platforms.
- Healthcare:MFDS medical device regulations enforce electromagnetic compatibility and biocompatibility standards for wearable health sensors. Extended cytotoxicity testing protocols extend commercialization cycles.
- Transportation:Railway and logistics infrastructure in Busan deploy environmental monitoring arrays. K-Safety certification mandates flame-resistant housing for tunnel and platform deployments.
Manufacturing absorbs the greatest sensor volume. Healthcare shows the steepest expansion trajectory.
Application:
Industrial automation and smart home applications standardize around modular platforms, while environmental monitoring and wearable devices require specialized form factors.
- Industrial Automation:Multi-sensor fusion platforms compress discrete component counts while elevating measurement fidelity. Process control systems in Pyeongtaek semiconductor fabs specify these for etch and deposition monitoring.
- Wearable Devices:Pulse oximetry and continuous glucose monitoring segments establish dedicated regulatory affairs teams for MFDS pre-submission pathways. Biometric authentication drives optical sensor integration.
- Smart Homes:Voice-activated and touchless interfaces specify proximity and capacitive sensors for appliance control. Seoul metropolitan area smart building deployments concentrate demand.
- Environmental Monitoring:Air quality and water purity sensors deploy in municipal infrastructure. Daegu hospital clusters present untapped demand for surgical automation environmental controls.
Industrial Automation commands the dominant installed base. Wearable Devices are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized engineers in mixed-signal circuit design concentrate in Seongnam and Suwon, anchoring South Korea's sensor innovation capacity. These talent clusters support fabrication complexes across the Seoul Capital Area and southern industrial corridors. The national market splits into five functional economic zones with distinct procurement patterns.
Seoul Capital Area
Financial services and smart building deployments drive optical-capacitive sensor fusion for secure access systems. MFDS electromagnetic compatibility standards enforce extended testing timelines for wearable health devices. Seoul metropolitan smart home installations concentrate demand for proximity and capacitive touch sensors in voice-activated appliance control.
Busan-Ulsan
Automotive tier-one suppliers specify pressure, position, and time-of-flight optical sensors for electrification mandates. K-Safety certification mandates flame-resistant housing for industrial proximity sensors in petrochemical facilities. Ulsan supplier parks see direct OEM-supplier engineering collaboration displacing traditional distributor models.
Daegu-Gyeongbuk
Hospital clusters present untapped demand for haptic feedback sensors in surgical automation systems. MFDS medical device regulations enforce biocompatibility standards for wearable health monitoring. Daegu medical robotics research centers are establishing pre-submission consultation pathways for regulatory clearance.
Daejeon-Sejong
Government research institutes anchor national standards development for sensor calibration protocols. The Korea Agency for Technology and Standards operates mandatory conformity assessment schemes from Sejong administrative facilities. Daejeon technology corridors host edge AI inference chip development married with environmental sensing arrays.
Gwangju-Honam
Automotive supplier parks concentrate procurement for pressure sensors with drift calibration protocols. Hyundai Motor Group affiliates dominate component sourcing decisions through long-term supply agreements. Gwangju manufacturing lines specify MEMS piezoresistive elements for exhaust monitoring above 600°C operational thresholds.
South Korea Sensors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across South Korea's sensor value chain. Samsung Electronics and LG Innotek leverage captive semiconductor capacity against specialized foreign component suppliers. The market structure organizes around three archetypes: integrated electronics conglomerates, precision component specialists, and industrial automation multinationals. Capacity expansion and strategic partnerships dominate competitive moves as procurement consolidates through direct OEM relationships.
Within the precision component tier, TDK Corporation and ams OSRAM AG exemplify magnetic and optical sensing specialists. LG Innotek anchors domestic optical supply chains. These three occupy positions between integrated conglomerates and broad industrial automation players, representing the specialist archetype that serves smartphone, automotive, and medical device buyers through differentiated technology portfolios.
| Leading Market Players |
|---|
| TDK Corporation |
| LG Innotek |
| ams OSRAM AG |
| Honeywell International |
| Infineon Technologies AG |
| STMicroelectronics |
| Samsung Electronics |
| Sensirion AG |
| Bosch Sensortec |
| Others |
Pricing and Supply Chain Analysis
Captive semiconductor fabrication at Samsung Electronics and LG Innotek anchors South Korea's sensor supply position while compressing pricing power for foreign component suppliers. This integration pattern concentrates procurement leverage among domestic electronics conglomerates and forces specialized magnetic and optical sensor vendors into joint development arrangements to maintain margin.
Pricing Analysis
Bundle-unbundle splits separate component-only transactions from engineering-service packages. Automotive tier-one suppliers in Gwangju and Ulsan favor long-term offtake contracts bundling volume commitments with calibration support. Price differentiation hinges on K-Safety certification grade and automotive-grade drift performance. Cost compression in standard proximity sensor tiers intensifies as Chinese manufacturers expand through distributor channels. Healthcare buyers show lowest price sensitivity due to MFDS compliance burdens.
Supply Chain Analysis
Reverse-logistics flows for industrial proximity sensors remain underdeveloped despite K-Safety upgrade cycles forcing equipment refreshes. Rare earth element supply for magnetic sensor cores concentrates through Chinese and Japanese processors, exposing Korean manufacturers to input volatility. MEMS wafer fabrication feeds from Taiwan and domestic Pyeongtaek complexes. Distribution runs through direct OEM-supplier engineering relationships rather than traditional tiered distributor networks, particularly in automotive supplier parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's sensor market reads as a late-cycle quality story. Automotive electrification mandates and MFDS medical device tightening are shifting procurement toward premium-specification components with extended calibration protocols.
For Market Incumbents: Anchor defensive positioning through backward integration into MEMS wafer supply and captive rare earth element processing partnerships. Samsung Electronics and LG Innotek should deepen control over optical sensor die fabrication to forestall specialized foreign entrants. K-Safety certification investment represents the critical lever for maintaining public procurement eligibility against emerging Chinese competitors. For New Entrants and Emerging Players: Regional hospital clusters in Daegu present the most penetrable white-space for haptic feedback sensors in surgical automation systems. Medical robotics research centers lack established supplier relationships and tolerate longer qualification cycles. A joint development pathway with Daejeon government research institutes offers regulatory pre-submission advantages and National Strategic Technology designation eligibility. For Investors and Strategic Acquirers: Roll-up economics work for precision magnetic sensor specialists because rare earth supply concentration creates acquisition scarcity value for firms with established Japanese or Chinese processor relationships. Target asset-light designers with MFDS regulatory affairs capabilities and existing automotive tier-one supplier qualifications. Monitor CE-Korea mutual recognition negotiation progress as an inflection signal for foreign supplier market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Wafer Supply | Captive fabrication capacity at Pyeongtaek complexes reduces dependency on Taiwan foundry allocation. |
| MFDS Pre-Submission Consultation Pathway | Extended cytotoxicity testing protocols compress commercialization timelines for wearable health entrants. |
| Joint Development Agreement with Automotive Tier-Ones | Direct OEM-supplier engineering collaboration in Gwangju supplier parks displaces distributor intermediation. |
| Rare Earth Processor Partnership | Magnetic sensor manufacturers secure input stability against Chinese export restriction exposure. |
| Edge AI Inference Chip Integration | Environmental sensor fusion with predictive maintenance algorithms opens Gwangju automotive contracts. |
Research Methodology
Bottom-up automotive and healthcare procurement modeling reconciled against top-down semiconductor fab capacity tracking forms the analytical core. Primary interviews with Tier 1 supplier procurement managers, MFDS regulatory affairs leads, biomedical engineers at Daegu hospital clusters, and smart factory automation directors in Gyeonggi Province combined with secondary validation. Secondary sources include Korea Agency for Technology and Standards conformity assessment databases, MFDS medical device registration filings, Hyundai Motor Group affiliate procurement disclosures, and semiconductor equipment import records.
Input-output matrices map sensor content per vehicle across propulsion architectures and process control intensity per wafer fabrication line across memory and logic capacity additions. Segmentation dimensions span product type, technology, end user, and application with regional production cluster overlays. CAGRs derive from installed base replacement cycles, electrification mandate compliance deadlines, and smart factory deployment trajectories. Forecast inputs incorporate K-Safety certification expansion timelines and MFDS electromagnetic compatibility testing queue projections.
Revisions become necessary when CE-Korea mutual recognition negotiations stall, rare earth export restrictions materialize, or MEMS drift calibration protocols extend beyond current automotive specifications. Forecasts reflect assumptions about procurement consolidation continuity and regulatory pathway stability. Practitioners should monitor National Strategic Technology designation announcements and foreign supplier conformity assessment queue lengths for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Advanced Sensor Market
Sensors and Controls
Smart Parking Sensor Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
Spectral Sensor Market
Sensors and Controls
Lidar Ceilometer Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
Global Light Sensors Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Global Accelerometers Market