
 Fingertip Pulse Oximeter Electronic Testers Market | 2026-2036
Fingertip Pulse Oximeter Electronic Testers Market Size, Share, and Industry Trends Forecast 2026-2036
Fingertip Pulse Oximeter Electronic Testers Market Insights
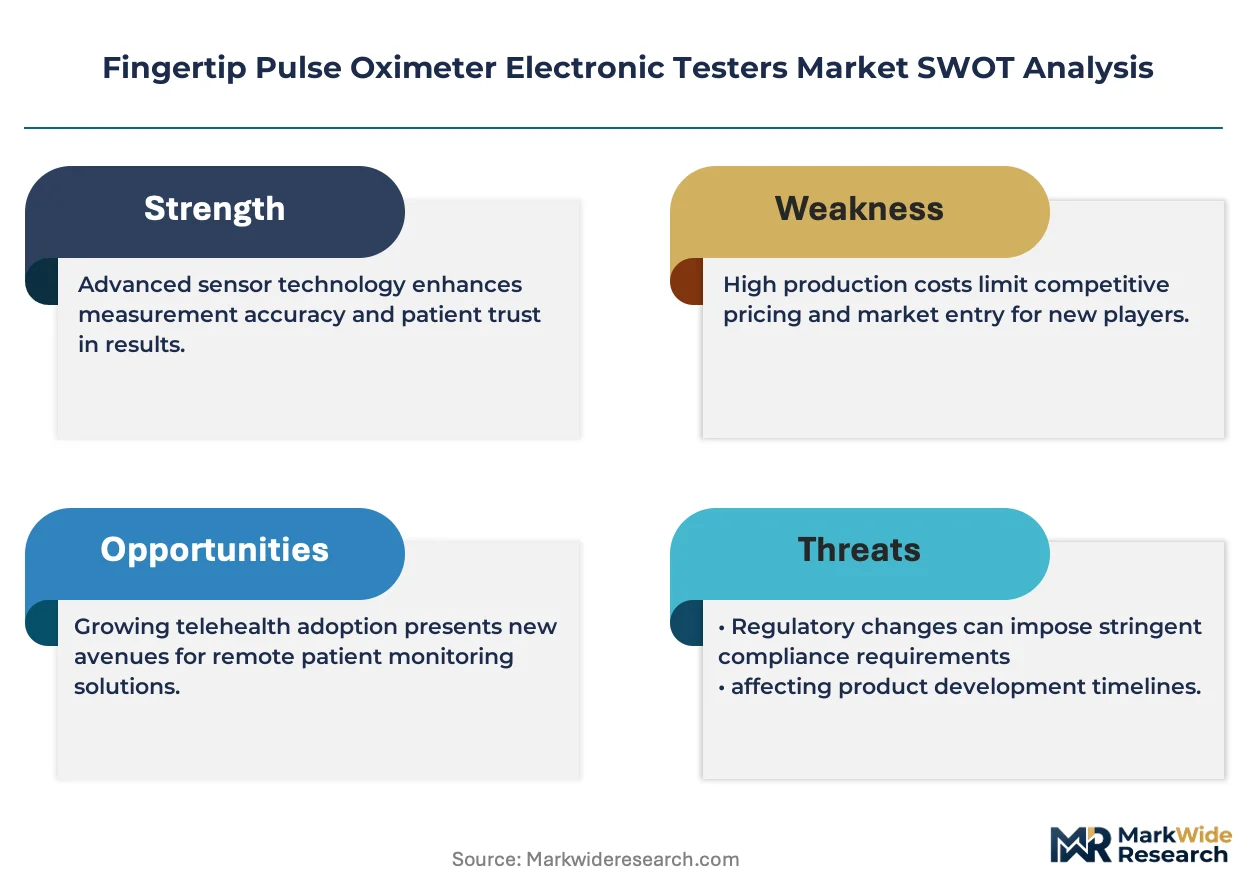
ISO 80601-2-61 is hardening the cost-of-entry calculus for new fingertip pulse oximeter entrants, requiring clinical-grade SpO2 accuracy validation that smaller manufacturers struggle to fund. Masimo Corporation leverages its signal extraction technology to sustain premium positioning in hospital-grade segments. Nonin Medical anchors its competitive stance through FDA-cleared pureSAT pulse oximetry engines. TaiDoc Technology competes aggressively on manufacturing scale across Asian consumer channels.
Fingertip pulse oximeter electronic testers are non-invasive photometric devices that measure arterial oxygen saturation (SpO2) and pulse rate through dual-wavelength light absorption at red (660 nm) and infrared (940 nm) spectra, with primary commercial purpose spanning clinical diagnostics, home respiratory monitoring, and fitness physiology tracking. Handheld and continuous monitoring product types dominate unit volume, while photoplethysmography technology leads installed base due to its maturity and cost efficiency. Disposable variants command margin pools in infectious disease protocols, whereas pulse wave analysis applications in sleep apnea monitoring represent the fastest-growing clinical adoption vector.
FDA 510(k) premarket notification, ISO 80601-2-61 medical electrical equipment standards, and EU MDR conformity assessment collectively shape product standards, demand verification rigor, and market access timelines across North America and Europe. The EU AI Act introduces emerging scrutiny for algorithm-enabled diagnostic features in next-generation devices. Stakeholders must monitor evolving reimbursement parity between prescription and over-the-counter pulse oximeter categories to calibrate channel strategy and pricing architecture.
Market Dynamics
ISO 80601-2-61 accuracy thresholds are hardening the cost-of-entry calculus for new fingertip pulse oximeter entrants, forcing clinical-grade SpO2 validation investments that smaller manufacturers struggle to fund while advantaging established players with existing laboratory infrastructure.
Growth Catalysts
- Remote patient monitoring reimbursement codes:CMS expansion of CPT 99457 and 99458 in the United States reimburses physicians for remote physiologic monitoring, directly incentivizing home pulse oximeter prescriptions for post-acute care patients.
- Japan's super-aged society:METI guidelines promoting home healthcare infrastructure create institutional demand for consumer-grade pulse oximeters among the 29% of Japanese citizens aged 65 and above.
- Photoplethysmography miniaturization:Advances in LED emitter efficiency and silicon photodiode sensitivity enable finger-worn form factors that match hospital-grade accuracy at consumer price points.
Market Restraints
- FDA 510(k) premarket notification costs:Clinical validation studies for SpO2 accuracy across skin pigment diversity add substantial fixed costs that deter mid-tier manufacturers from pursuing US market entry.
- Optical component supply concentration:High-precision 660 nm red and 940 nm infrared emitters concentrate among specialized Japanese and German photonics suppliers, creating input vulnerability.
- Smartwatch SpO2 substitution:Apple Watch and Garmin wrist-based oximetry satisfies fitness-tracking demand, compressing addressable market for dedicated fingertip devices in wellness segments.
Strategic Opportunities
- India's Ayushman Bharat digital health mission:The national health stack's remote monitoring protocols create first-mover advantage for pulse oximeter vendors securing CDSCO manufacturing licenses and state-level hospital procurement contracts.
- Sleep apnea diagnostic convergence:Pulse wave analysis algorithms enabling nocturnal oxygen desaturation detection open reimbursement pathways previously reserved for polysomnography laboratories.
- EU MDR conformity assessment acceleration:Notified body capacity expansion in Germany and the Netherlands shortens time-to-market for CE-marked devices, rewarding early regulatory investment.
Industry Challenges
- Clinical validation workforce scarcity:ISO 80601-2-61 testing protocols require specialized biomedical engineers with photometric instrumentation expertise, creating recruitment bottlenecks in emerging manufacturing hubs.
- Legacy hospital IT integration:Home pulse oximeters must interface with Epic and Cerner electronic health record systems through HL7 FHIR standards, demanding software engineering capabilities absent from hardware-centric vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fingertip Pulse Oximeter Electronic Testers Market |
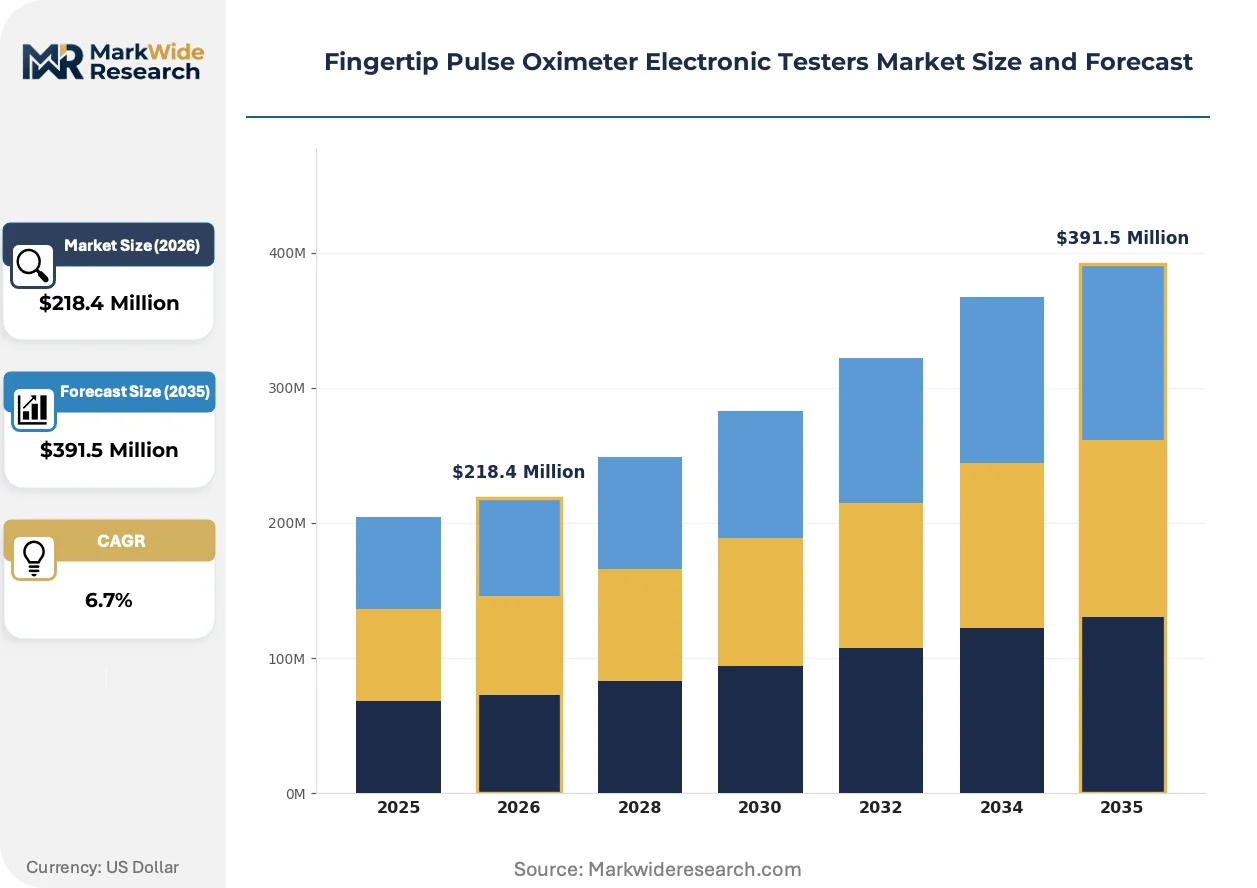
| Market Size in 2026 | $218.4 Million |
| Market Size in 2035 | $391.5 Million |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Continuous Monitoring, Disposable, Tabletop Technology: Infrared, Photoplethysmography, Reflectance, Pulse Wave Analysis End User: Home Healthcare, Hospitals, Medical Clinics, Emergency Services Application: Critical Care, Sleep Apnea Monitoring, Respiratory Assessment, Fitness Tracking |
| Companies Covered | HealthTree, Lanaform, LOOKEE, CA-MI, Promed Group, Zacurate, TaiDoc Technology, Masimo Corporation, Nonin Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fingertip Pulse Oximeter Electronic Testers Market Trends and Innovations
Algorithm-enabled diagnostic features are penetrating fingertip pulse oximeters, with photoplethysmography signal processing advancing beyond basic SpO2 measurement toward arrhythmia detection and respiratory rate estimation. This software layer is redefining competitive differentiation in a market historically segmented by hardware accuracy alone.
Multi-wavelength photoplethysmography is converging with machine learning inference engines to enable non-invasive hemoglobin concentration and carbon monoxide saturation estimation. Sleep medicine clinics in Germany and Japan are piloting these enhanced devices for overnight hypoxemia screening, compressing diagnostic timelines previously requiring laboratory arterial blood gas analysis. The technology is converging with cloud-based telemetry platforms that transmit continuous data streams to pulmonologists, enabling reimbursement under remote therapeutic monitoring codes.
The EU AI Act's risk classification framework is placing algorithm-enabled pulse oximeters into Category IIa medical devices, mandating conformity assessment for machine learning training data transparency and post-market performance monitoring. This regulatory friction most affects vendors embedding arrhythmia detection algorithms, forcing disclosure of training dataset demographic composition and skin pigment diversity. German notified bodies are establishing specialized review pathways for AI-integrated pulse oximetry, creating temporary bottlenecks that favor larger manufacturers with dedicated regulatory affairs teams.
Direct-to-consumer channel expansion is displacing traditional durable medical equipment distribution for non-prescription pulse oximeters. Amazon and pharmacy retail chains in the United States now capture majority volume for sub-fifty-dollar consumer devices, compressing margins for distributors dependent on physician office dispensing relationships. This channel rotation is most pronounced among post-COVID-19 respiratory monitoring purchases, where patients self-initiate device acquisition rather than awaiting clinical prescription.
Fingertip Pulse Oximeter Electronic Testers Market Segmentation
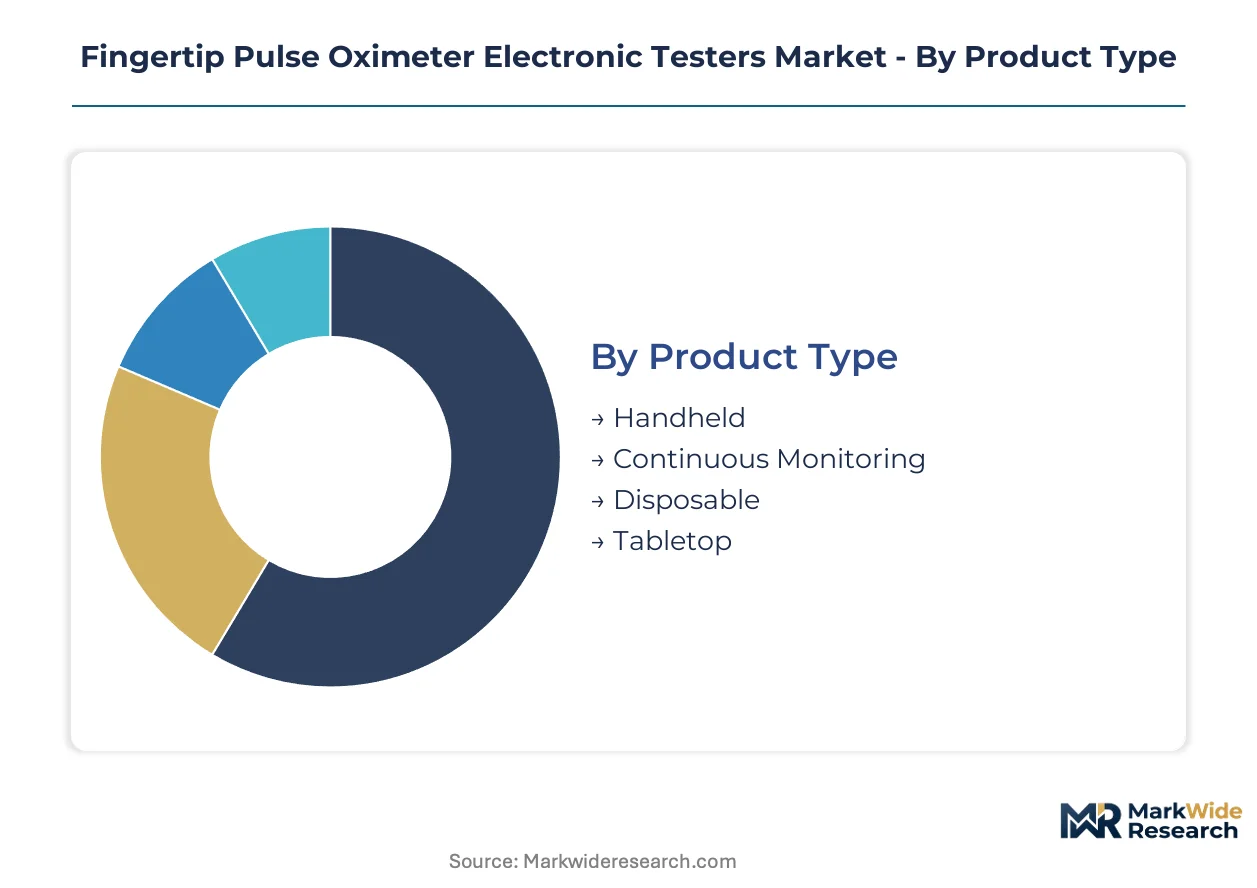
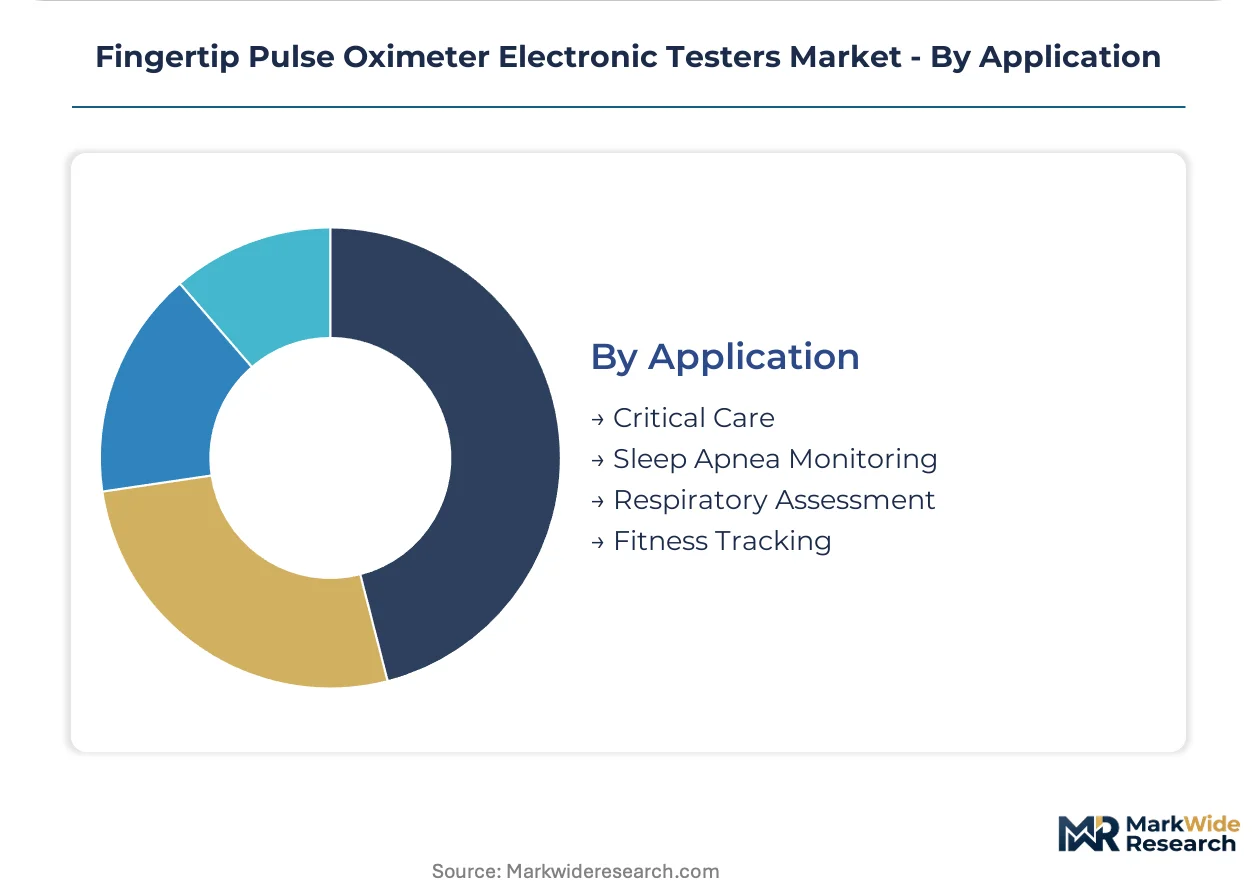
Fingertip pulse oximeter electronic testers fragment across four critical dimensions that shape procurement patterns and margin architecture. Product type and technology configurations determine reimbursement eligibility, while end-user and application segments dictate channel strategy and regulatory burden.
Product Type:
Volume concentrates in portable formats, while premium pricing anchors institutional stationary systems.
- Handheld:Battery-operated devices with clip-style finger probes dominate unit shipments across retail pharmacy and direct-to-consumer channels. Demand clusters in United States home healthcare settings where CMS remote monitoring reimbursement codes incentivize patient-owned devices.
- Continuous Monitoring:Wearable finger-worn sensors with telemetry transmission enable overnight oxygen saturation tracking in sleep medicine applications. German pulmonology clinics and Japanese home healthcare agencies are deploying these for nocturnal hypoxemia screening outside polysomnography laboratories.
- Disposable:Single-use finger probes with integrated electronics serve infectious disease protocols and isolation wards. These command elevated margins in hospital settings where cross-contamination protocols mandate device turnover.
- Tabletop:Stationary multi-parameter monitors with pulse oximetry modules anchor intensive care and operating room installations. These systems integrate with Epic and Cerner electronic health record networks through HL7 FHIR standards.
Mature deployment sits with Tabletop systems in tertiary hospitals. Newer deployment is concentrated in Handheld and Continuous Monitoring formats for decentralized care models.
Technology:
Cost tier stratification separates legacy photometric methods from algorithm-enhanced diagnostic engines.
- Infrared:Dual-wavelength absorption at 940 nm combined with red 660 nm spectra remains the foundational SpO2 measurement approach. Japanese and German photonics suppliers concentrate precision emitter manufacturing for this standard configuration.
- Photoplethysmography:Volumetric blood flow detection through LED-photodiode pairs enables finger-worn miniaturization at consumer price points. This technology leads installed base due to manufacturing maturity and component cost efficiency.
- Reflectance:Forehead and wrist-mounted sensors using backscattered light measurement bypass finger perfusion limitations in hypothermic or vasoconstricted patients. These formats are climbing the fastest in emergency services and pre-hospital applications.
- Pulse Wave Analysis:Advanced signal processing extracts respiratory rate, arrhythmia signatures, and perfusion index from plethysmographic waveforms. EU AI Act Category IIa classification now mandates conformity assessment for algorithm-enabled devices employing this technique.
Mature deployment sits with Photoplethysmography across consumer and clinical channels. Newer deployment is concentrated in Pulse Wave Analysis for multi-parameter diagnostic convergence.
End User:
Customer type determines pricing architecture and regulatory pathway complexity.
- Home Healthcare:Patient-operated devices for post-acute respiratory monitoring and chronic disease management. United States reimbursement expansion through CPT 99457 and 99458 codes is accelerating prescription volume.
- Hospitals:Acute care facilities requiring FDA 510(k) cleared or CE-marked devices with clinical-grade accuracy validation. These procurement decisions prioritize ISO 80601-2-61 compliance and electronic health record integration.
- Medical Clinics:Outpatient settings including pulmonology and sleep medicine practices. German and Japanese clinic networks are piloting cloud-connected devices for remote therapeutic monitoring reimbursement.
- Emergency Services:Pre-hospital and ambulance deployments requiring ruggedized construction and rapid assessment capability. Reflectance technology adoption is expanding in this segment to address poor peripheral perfusion scenarios.
Mature deployment sits with Hospitals as the historical anchor of clinical pulse oximetry. Newer deployment is concentrated in Home Healthcare where reimbursement parity with institutional settings is expanding.
Application:
Margin pools and regulatory scrutiny intensify with diagnostic consequence.
- Critical Care:High-acuity monitoring in intensive care units and operating rooms demands continuous multi-parameter surveillance. These applications require tabletop systems with alarm integration and centralized nursing station display.
- Sleep Apnea Monitoring:Nocturnal oxygen desaturation detection for obstructive sleep apnea screening and therapy compliance. Pulse wave analysis algorithms are compressing diagnostic timelines previously requiring overnight polysomnography.
- Respiratory Assessment:Acute and chronic respiratory condition monitoring including COPD, asthma, and post-COVID-19 hypoxemia. Home healthcare adoption is accelerating among aging populations in Japan and the United States.
- Fitness Tracking:Wellness-oriented SpO2 measurement for altitude acclimatization and athletic performance optimization. Smartwatch substitution from Apple and Garmin is compressing addressable market for dedicated fingertip devices in this segment.
Mature deployment sits with Critical Care as the original clinical application. Newer deployment is concentrated in Sleep Apnea Monitoring where reimbursement pathways are converging with traditional polysomnography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Dongguan concentrate precision photonics manufacturing for pulse oximeter components, drawing component suppliers into tax-advantaged clusters that feed assembly operations across Asia-Pacific and North American markets.
United States
CMS reimbursement expansion through CPT 99457 and 99458 codes drives prescription volume for home pulse oximeters among post-acute care patients. FDA 510(k) premarket notification requirements enforce clinical-grade SpO2 accuracy validation across skin pigment diversity. Minneapolis-St. Paul anchors hospital-grade device procurement networks serving the Upper Midwest healthcare systems.
Germany
Notified body capacity expansion for EU MDR conformity assessment accelerates CE-marked device time-to-market for manufacturers targeting European hospital procurement. The EU AI Act Category IIa classification mandates algorithm transparency for machine learning-enabled diagnostic features. Munich and Stuttgart industrial clusters concentrate precision photonics suppliers serving medical device OEMs.
Japan
METI guidelines promoting home healthcare infrastructure create institutional demand among the super-aged population exceeding 29% citizens aged 65 and above. PMDA regulatory pathways align with ISO 80601-2-61 standards for clinical-grade accuracy thresholds. Osaka-Kobe manufacturing corridors host specialized 660 nm and 940 nm emitter production for precision photonics inputs.
India
Ayushman Bharat digital health mission remote monitoring protocols create first-mover advantage for vendors securing CDSCO manufacturing licenses and state-level hospital procurement contracts. BIS certification requirements govern medical electrical equipment safety standards for domestic market access. Gujarat and Karnataka industrial corridors concentrate contract manufacturing capacity for export-oriented pulse oximeter assembly.
China
NMPA medical device registration requirements enforce clinical validation for Class II diagnostic equipment entering domestic distribution channels. GB standards for medical electrical equipment align with IEC 60601 series for electromagnetic compatibility and safety. Yangtze River Delta special economic zones concentrate LED emitter and silicon photodiode component manufacturing feeding global supply chains.
Fingertip Pulse Oximeter Electronic Testers Market Competitive Landscape
United States producers anchor the premium clinical-grade tier; Taiwanese and Chinese specialists hold manufacturing scale positions in consumer channels. Market structure concentrates among established players with existing ISO 80601-2-61 laboratory infrastructure and regulatory affairs capabilities. Three archetypes dominate: signal extraction technology licensors, pureSAT engine specialists, and high-volume contract manufacturers. Competitive moves center on M&A for regulatory capacity acquisition and strategic partnerships for cloud-based telemetry platform integration.
Among technology-anchored specialists, Masimo Corporation and Nonin Medical occupy positions exemplifying premium-tier clinical positioning, while TaiDoc Technology represents the scale-driven manufacturing archetype serving Asian consumer distribution channels. These three entities illustrate the geographic and capability bifurcation shaping competitive dynamics: US-based firms leverage FDA clearance portfolios for hospital procurement access, while Asia-Pacific manufacturers exploit component supply proximity and labor cost structures for price-sensitive retail segments. The competitive terrain rewards early regulatory investment in EU MDR and FDA 510(k) pathways while penalizing hardware-centric vendors lacking software engineering capabilities for electronic health record integration.
| Leading Market Players |
|---|
| HealthTree |
| Lanaform |
| LOOKEE |
| CA-MI |
| Promed Group |
| Zacurate |
| TaiDoc Technology |
| Masimo Corporation |
| Nonin Medical |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up precision photonics specialists anchor component supply tiers in Japan and Germany, translating captive emitter manufacturing into pricing discipline that resists spot-market volatility while compressing margin pools for assembly-only competitors in Asian consumer channels.
Pricing Analysis
Short lead-time premiums separate hospital procurement contracts from direct-to-consumer spot purchases, with FDA 510(k) cleared devices commanding three-tier pricing structure across premium, standard, and economy levels based on ISO 80601-2-61 certification grade and HL7 FHIR integration capability. Price differentiation hinges on clinical validation depth and electronic health record connectivity, not hardware alone. Cost compression in sub-fifty-dollar retail tiers intensifies because smartwatch SpO2 substitution erodes dedicated device addressable market. Home healthcare patients exhibit highest price sensitivity; intensive care procurement committees prioritize accuracy validation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized Japanese and German photonics suppliers for high-precision 660 nm red and 940 nm infrared emitters, creating input concentration that feeds from precision LED foundries in Osaka-Kobe and Stuttgart industrial corridors. Silicon photodiode sensitivity calibration and optical filter deposition represent additional critical dependencies. Tariff exposure on medical electronics components threatens margin stability for US-bound assembly operations. Distribution runs through Amazon and pharmacy retail chains for consumer devices, while hospital procurement leverages GPO contracts and direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over ISO 80601-2-61 validation laboratories and precision photonics emitter supply determines pricing power and regulatory access speed.
For Market Incumbents: Anchor defensive positioning through backward integration into 660 nm and 940 nm emitter manufacturing or exclusive long-term offtake agreements with Osaka-Kobe and Stuttgart precision photonics suppliers. Accelerate HL7 FHIR integration engineering to defend against hardware-centric vendors lacking electronic health record connectivity capabilities. Threat from algorithm-enabled diagnostic features demands machine learning training data transparency investment ahead of EU AI Act Category IIa enforcement. For New Entrants and Emerging Players: Direct-to-consumer Amazon storefronts offer lowest barrier-to-entry for CDSCO-licensed manufacturers targeting India's Ayushman Bharat remote monitoring procurement, bypassing FDA 510(k) capital requirements that deter US market entry. White-space concentrates in sleep apnea diagnostic convergence where pulse wave analysis algorithms enable reimbursement pathways outside polysomnography laboratories. Go-to-market angle: cloud-based telemetry platform partnerships with German and Japanese pulmonology clinic networks piloting overnight hypoxemia screening. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with existing ISO 80601-2-61 laboratory infrastructure but strained working capital from EU MDR conformity assessment delays, particularly in German and Dutch notified body jurisdictions. Long-term viability rests on software engineering capabilities for algorithm-enabled diagnostic features, not hardware scale alone. Signal to watch: notified body capacity expansion rates for EU AI Act Category IIa medical device review as inflection indicator for regulatory timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks CMS CPT 99457 reimbursement codes for home healthcare prescriptions in United States. |
| EU MDR Conformity Assessment | Accelerates CE-marked device access to German hospital procurement networks and notified body pathways. |
| Precision Photonics Backward Integration | Captures 660 nm and 940 nm emitter supply from Osaka-Kobe and Stuttgart supplier concentration. |
| HL7 FHIR Integration Engineering | Enables Epic and Cerner electronic health record connectivity for hospital system partnerships. |
| Cloud Telemetry Platform Partnership | Supports remote therapeutic monitoring reimbursement under expanding CMS codes for post-acute care. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, ISO 80601-2-61 technical standards, and CMS reimbursement code expansions, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and precision photonics procurement leads. Secondary validation drew from PMDA regulatory filings, EU MDR notified body capacity reports, and METI home healthcare infrastructure guidelines. Bottom-up unit shipment modeling triangulated against top-down expenditure analysis across product type, technology, end user, and application segmentation.
Cross-referencing historical reimbursement code adoption curves against clinician panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product format, photometric technology, customer type, and diagnostic application intensity. CAGRs derived from iterative convergence between supply-side capacity buildouts and demand-side reimbursement expansion trajectories. Forecast inputs incorporated LED emitter efficiency improvement curves and silicon photodiode cost reduction trends.
The model holds under stable FDA 510(k) review timelines and sustained CMS remote monitoring reimbursement; deviation in EU AI Act Category IIa enforcement stringency or notified body capacity constraints would shift algorithm-enabled device adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Brightness Meter Market
Test and Measurement
Data Center Testing Market
Test and Measurement
United States Signal Generator Market
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
Density Meter Market
Test and Measurement
Digital Moisture Meters Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Non-Destructive Testing (NDT) Software Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Pump Testers Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Impedance Tester Market