
 Abdominal Aortic Aneurysm (AAA) Repair Devices Market | 2026-2036
Abdominal Aortic Aneurysm (AAA) Repair Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Abdominal Aortic Aneurysm (AAA) Repair Devices Market Analysis
Aftermarket service revenue from stent graft surveillance and re-intervention procedures is reshaping profitability models across the AAA repair landscape. Medtronic leverages its integrated endovascular portfolio to capture recurring follow-on procedures. Cook Medical anchors its position through deep specialization in custom-fit aortic graft engineering. W. L. Gore & Associates differentiates via proprietary expanded polytetrafluoroethylene material science that commands premium positioning in complex anatomies.
Abdominal Aortic Aneurysm repair devices encompass endoprosthetic stent grafts, surgical grafts, and delivery systems designed to exclude aneurysmal dilation from arterial pressure, typically constructed from nitinol or cobalt-chromium frameworks with woven polyester or ePTFE fabric coverage and deployed at infrarenal or juxtarenal landing zones. Endovascular Aneurysm Repair systems now dominate commercial volume as fenestrated and branched graft designs expand treatable patient anatomies previously relegated to open surgery. Stent Grafts carrying drug-eluting or bioactive surface modifications represent the fastest-growing product subset as manufacturers target reduced endoleak rates and improved long-term durability.
FDA premarket approval pathways and EMA Medical Device Regulation conformity assessments govern commercial access, with both agencies intensifying scrutiny of long-term graft surveillance data to validate sustained efficacy claims. The EU MDR transition has forced European manufacturers to rebuild clinical evidence packages, compressing margins for smaller competitors while advantaging firms with established post-market registries. Stakeholders must monitor evolving FDA guidance on fenestrated device indications and corresponding CMS national coverage determinations that will dictate addressable patient populations.
Market Dynamics
Fenestrated and branched endograft designs are expanding treatable anatomies while CMS reimbursement policies accelerate the shift from open surgery to minimally invasive procedures across United States hospital systems.
Growth Catalysts
- United States aging demographic:Established Medicare screening protocols for men aged 65-75 sustain procedure volumes and create predictable demand pipelines for repair devices.
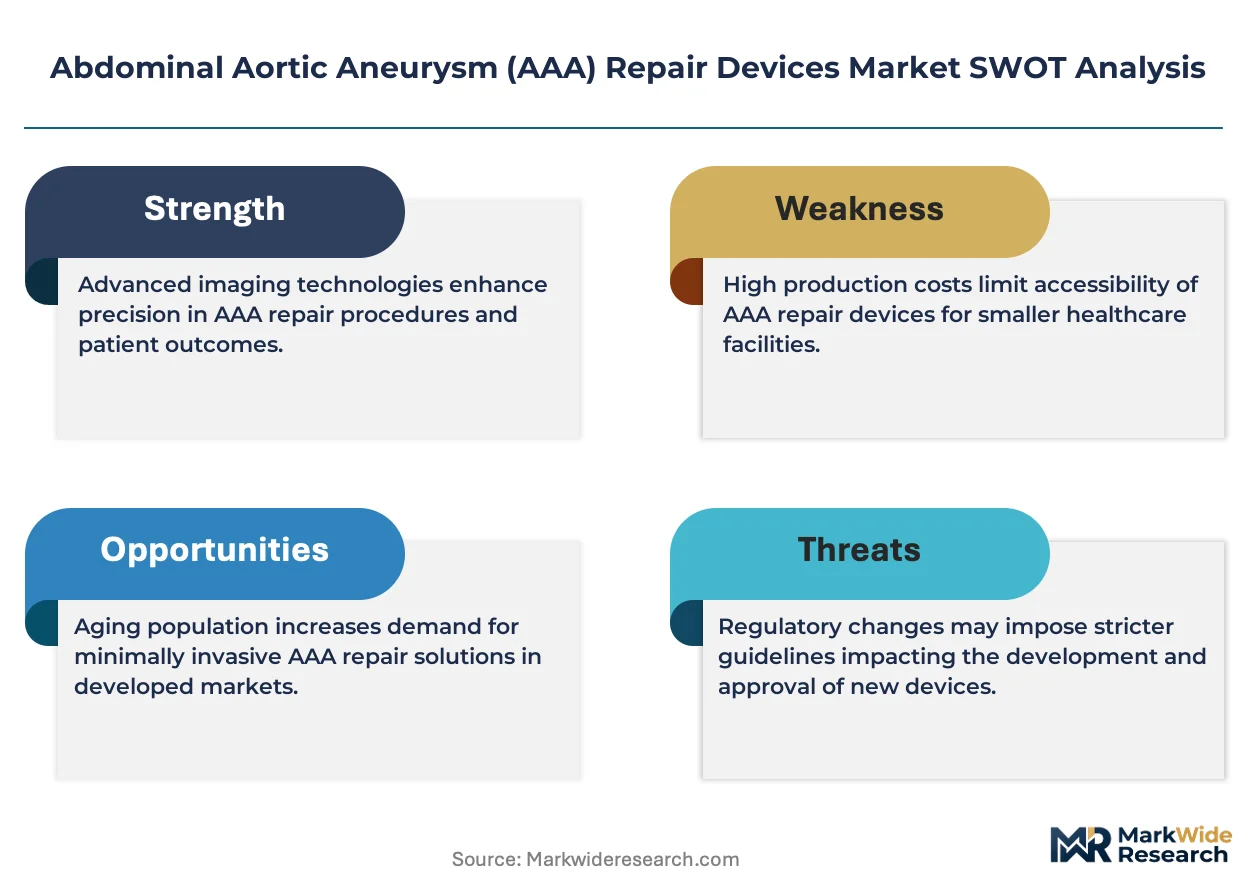
- MDR compliance requirements:EU Medical Device Regulation mandates for post-market clinical evidence are compressing margins for smaller competitors while advantaging firms with established surveillance registries.
- Nitinol superelastic frameworks:Advanced shape-memory alloys enable precise deployment at challenging juxtarenal landing zones previously excluded from endovascular treatment.
Market Restraints
- Platinum-iridium marker bands:Precious metal price volatility in radiopaque stent components creates input cost unpredictability for manufacturers.
- Long-term durability data gaps:Fifteen-year graft surveillance requirements under FDA premarket approval pathways delay new entrant commercialization timelines.
- Open surgical alternatives:Durable cost-effectiveness in younger patients with favorable anatomy limits absolute endovascular penetration rates.
Strategic Opportunities
- Drug-eluting surface modifications:Bioactive coatings targeting endothelialization and endoleak reduction represent unmet clinical need with premium pricing potential.
- Japan's super-aged society:PMDA accelerated approval pathways for life-threatening vascular conditions offer faster market access than FDA timelines.
- Integrated surveillance platforms:Remote patient monitoring and AI-assisted imaging analysis create recurring revenue streams beyond initial device implantation.
Industry Challenges
- Interventional radiologist training pipelines:Complex fenestrated procedures require specialized physician expertise that academic medical centers struggle to scale.
- Legacy hospital IT integration:Graft tracking systems must interface with fragmented electronic health record architectures across fragmented United States health networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abdominal Aortic Aneurysm (AAA) Repair Devices Market |
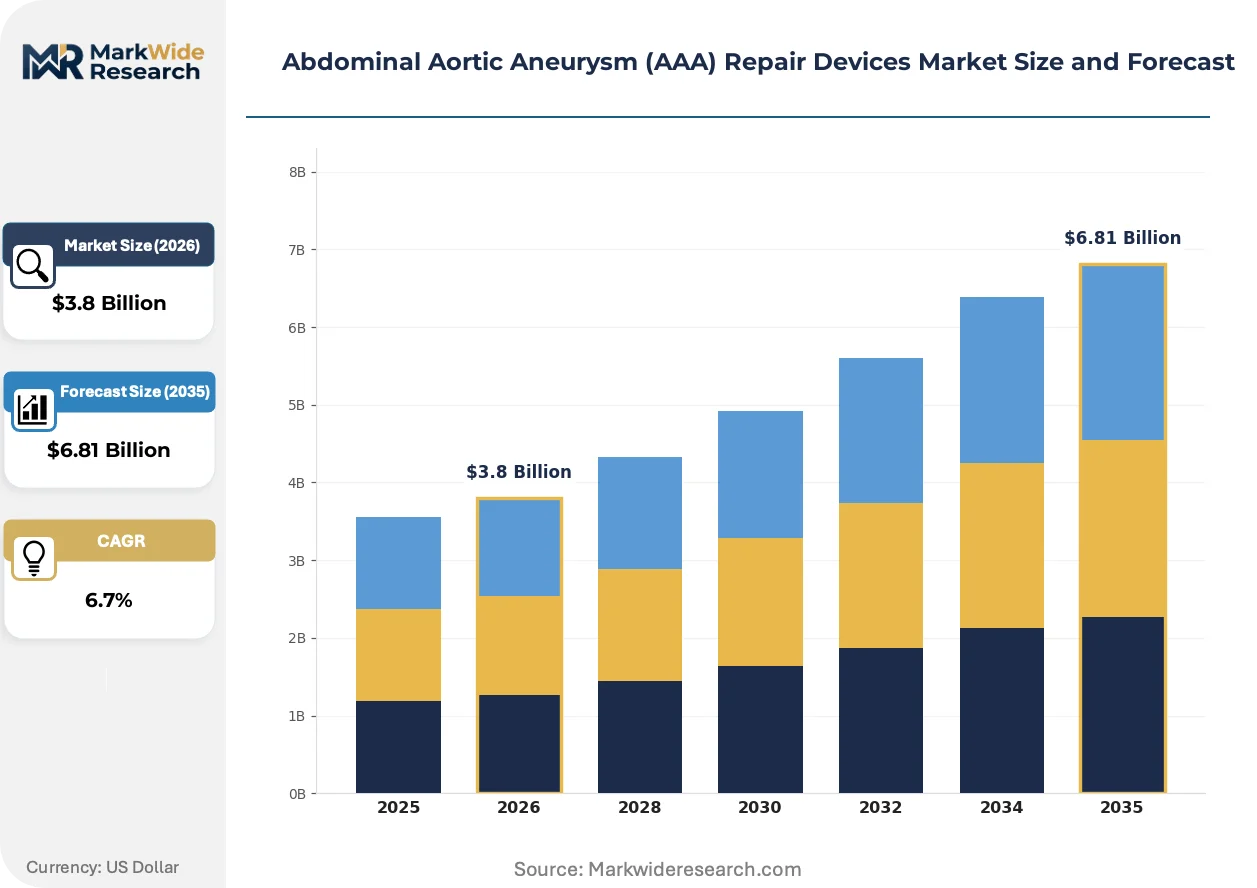
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endovascular Aneurysm Repair, Open Surgical Repair, Stent Grafts, Aortic Grafts Delivery Mode: Percutaneous, Minimally Invasive, Traditional Open, Hybrid End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Biomaterials, Imaging Systems, Surgical Instruments, Robotic Assistance |
| Companies Covered | Medtronic, Cook Medical, W. L. Gore & Associates, Inc., Endologix LLC, Terumo Corporation, Cardinal Health, MicroPort Scientific Corporation, Boston Scientific Corporation, Artivion, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abdominal Aortic Aneurysm (AAA) Repair Devices Market Emerging Trajectories
Device architectures are converging with digital health infrastructure while regulatory frameworks force evidence-generation investments that reshape competitive economics.
Polymer-ceramic nanocomposite graft materials are hybridizing traditional ePTFE fabric coverage with bioactive surface properties. Academic medical centers in the United States are piloting these constructs in high-risk anatomies. This convergence is hybridizing the boundary between passive mechanical exclusion and active biological healing.
FDA guidance on fenestrated device indications is tightening evidentiary requirements for complex anatomies. Manufacturers must now submit fifteen-year durability data rather than five-year benchmarks. United States applicants with existing post-market registries are compressing review timelines while de novo entrants face extended development cycles.
Hospital procurement committees are consolidating vendor relationships around integrated service contracts rather than transactional device purchasing. Integrated delivery networks in the United States are bundling graft surveillance, re-intervention procedures, and physician training into multi-year agreements. This consolidation is compressing supplier margins while locking in volume commitments.
Abdominal Aortic Aneurysm (AAA) Repair Devices Market Segmentation
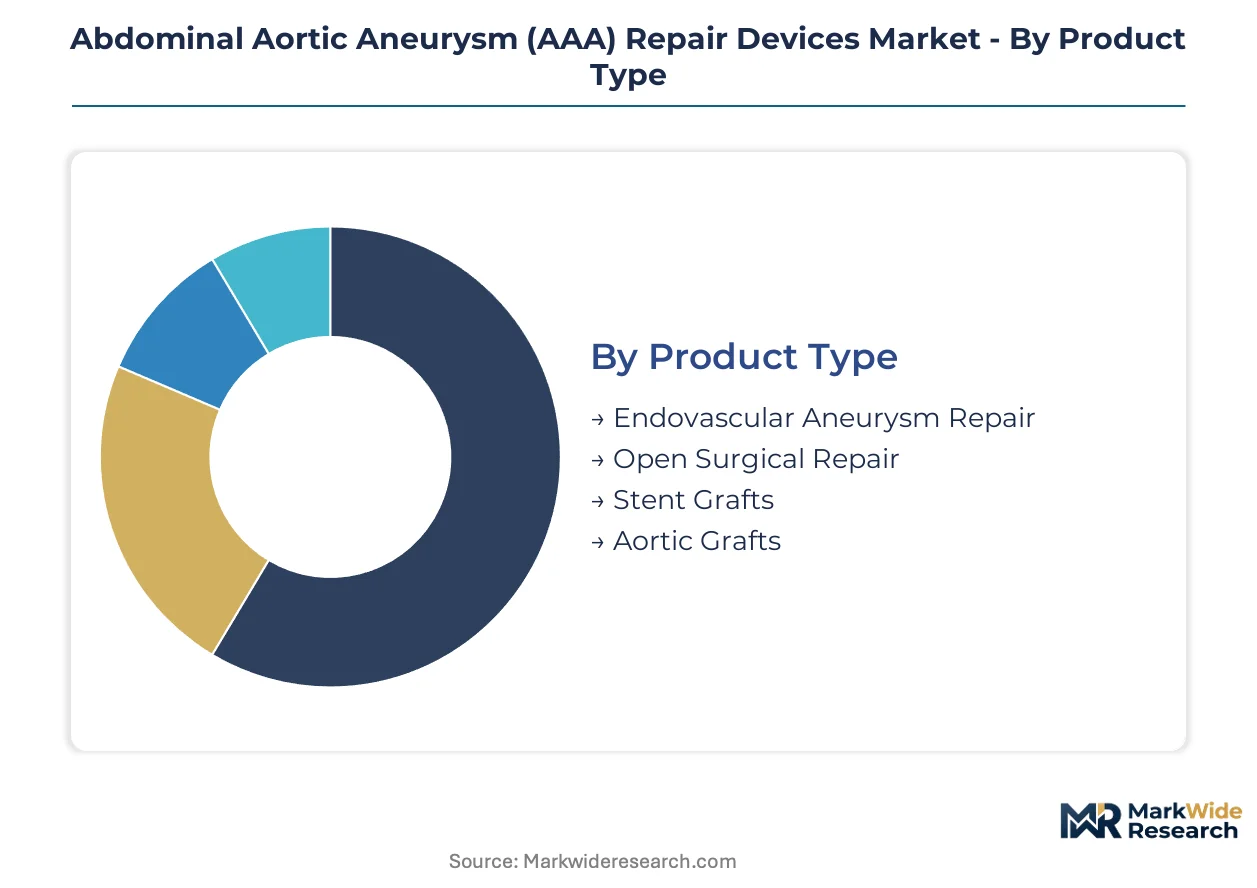
Device architecture and procedural approach fundamentally determine reimbursement pathways, physician training requirements, and hospital capital allocation in AAA repair. Segmentation reveals how endovascular platforms now command procedure economics while surgical alternatives retain niche utility in complex anatomies.
Product Type:
The use-case spectrum spans from catheter-deployed endoprostheses to hand-sewn surgical conduits, with material science and deployment mechanics defining clinical applicability.
- Endovascular Aneurysm Repair:Nitinol-framed stent grafts with polyester or ePTFE fabric coverage deploy via femoral access to exclude aneurysmal sacs from arterial pressure. United States hospital systems concentrate demand here as CMS reimbursement favors same-day discharge protocols.
- Stent Grafts:Modular bifurcated or tubular configurations accommodate infrarenal and juxtarenal landing zones with fenestrated designs expanding treatable anatomies. Academic medical centers in the United States drive adoption of custom-fit physician-modified grafts for challenging aortic morphologies.
- Open Surgical Repair:Woven polyester or Dacron tube grafts sutured directly to native aorta after aneurysm resection. Younger patients with favorable anatomy and low surgical risk profiles sustain residual demand.
- Aortic Grafts:Broad category encompassing both endovascular and open surgical conduit materials, with sizing ranges from 16mm to 36mm diameter accommodating diverse patient anatomies.
The dominant share belongs to Endovascular Aneurysm Repair, while Stent Grafts is closing the gap fastest through fenestrated and branched design iterations.
Delivery Mode:
Access strategy shapes procedural invasiveness, recovery timelines, and eligibility for same-day discharge protocols across United States integrated delivery networks.
- Percutaneous:Totally percutaneous access using pre-close suture techniques eliminates surgical cutdown. Ambulatory surgical centers in the United States favor this approach for reduced staffing and facility costs.
- Minimally Invasive:Small incision access with partial surgical exposure balances deployment precision against tissue trauma. Community hospitals lacking advanced endovascular programs default to this intermediate approach.
- Traditional Open:Full laparotomy or retroperitoneal exposure with aortic cross-clamping and graft interposition. High-volume aortic centers retain capability for rupture emergencies and hostile anatomy cases.
- Hybrid:Combined open and endovascular techniques such as debranching procedures enabling proximal seal zones. Tertiary referral centers apply these in thoracoabdominal extensions.
Percutaneous delivery claims the volume lead, though Minimally Invasive protocols are expanding most quickly through community hospital adoption.
End User:
Facility type dictates capital equipment requirements, case volume thresholds, and reimbursement capture mechanics across the care continuum.
- Hospitals:Comprehensive infrastructure for both elective and emergency AAA repair with 24/7 vascular surgery coverage. United States hospital systems anchor procedure volumes through integrated endovascular program investments.
- Ambulatory Surgical Centers:Focused facilities optimized for uncomplicated elective EVAR with streamlined discharge protocols. Medicare site-of-service differentials accelerate volume migration to this setting.
- Specialty Clinics:Vascular-focused outpatient practices handling diagnostic workup and surveillance imaging. Preoperative planning and post-implant monitoring concentrate here.
- Research Institutions:Academic medical centers conducting IDE trials and post-market surveillance registries. FDA-mandated long-term follow-up data generation depends on these sites.
Hospitals retain the dominant patient share, yet Ambulatory Surgical Centers are gaining share fastest on reimbursement arbitrage and operational efficiency.
Technology:
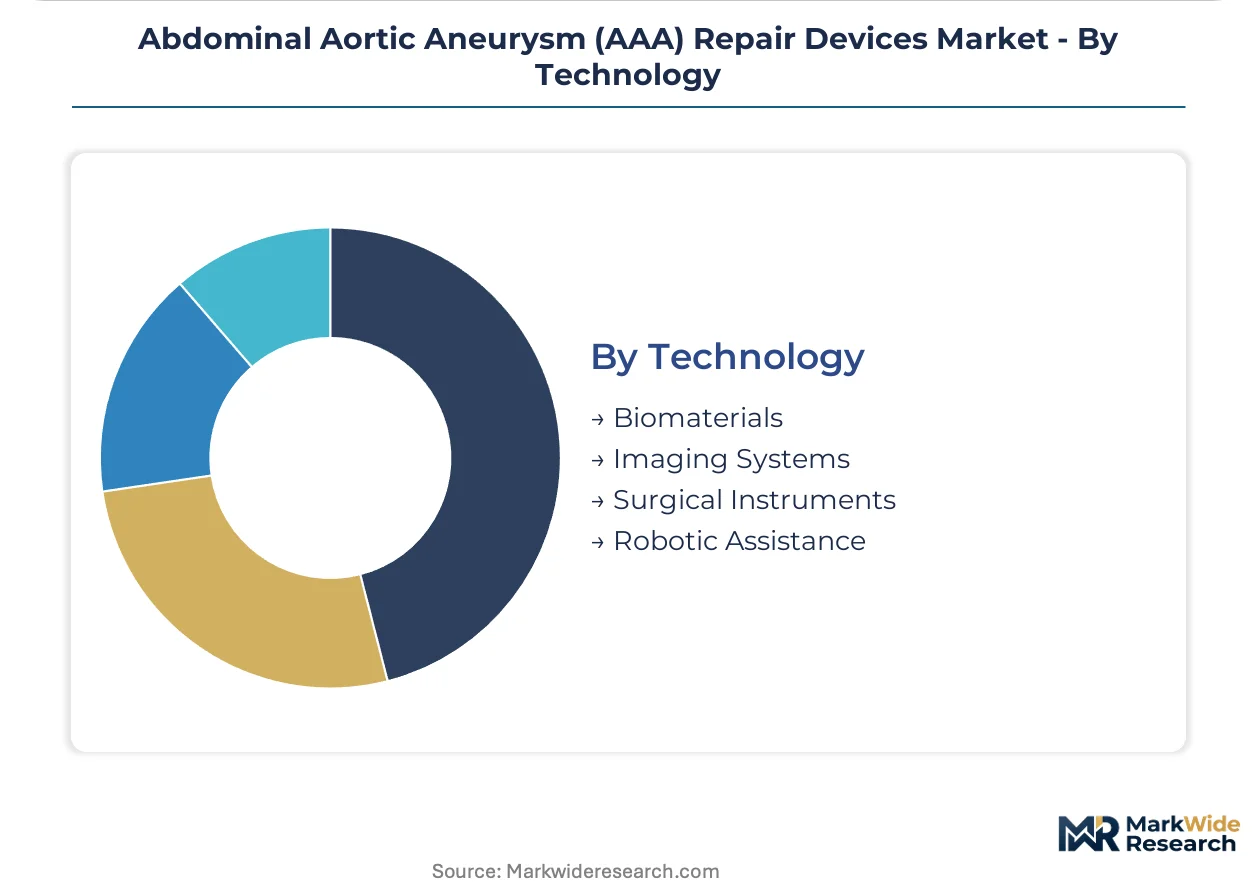
Underlying technical enablers span from graft material science to intraoperative imaging and mechanical assistance systems.
- Biomaterials:ePTFE, polyester, and nitinol formulations with drug-eluting or bioactive surface modifications. Surface engineering targeting endothelialization and endoleak reduction commands premium positioning.
- Imaging Systems:C-arm fluoroscopy, intravascular ultrasound, and fusion imaging for precise graft deployment. Three-dimensional roadmapping reduces contrast load and radiation exposure.
- Surgical Instruments:Delivery sheaths, dilators, and deployment handles calibrated to specific graft platforms. Proprietary instrument compatibility locks hospitals into vendor ecosystems.
- Robotic Assistance:Telemanipulation platforms for precise stent graft positioning in complex fenestrated cases. Early adoption concentrates in high-volume United States academic centers.
Biomaterials technology anchors commercial value, while Robotic Assistance is climbing the fastest on procedural precision demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States demonstrate the lowest price elasticity, absorbing premium device costs through integrated service contracts, while emerging markets in Asia-Pacific exhibit acute sensitivity to upfront capital expenditure for endovascular programs.
United States
Medicare's abdominal aortic aneurysm screening benefit for men aged 65-75 sustains predictable procedure pipelines across integrated delivery networks. FDA premarket approval pathways for fenestrated devices now mandate fifteen-year durability data, advantaging incumbent manufacturers with established surveillance registries. Cleveland Clinic and Mayo Clinic anchor complex case referral patterns in the Midwest, driving adoption of physician-modified graft techniques.
Germany
Europe's largest elderly population sustains elective repair volumes through statutory health insurance reimbursement frameworks. EMA Medical Device Regulation conformity assessments have forced domestic manufacturers to rebuild clinical evidence packages, compressing margins for mid-tier competitors. Heidelberg and Munich academic medical centers concentrate fenestrated procedure expertise, training interventionalists from across the European Union.
Japan
PMDA accelerated approval pathways for life-threatening vascular conditions offer faster commercial access than FDA timelines, attracting manufacturers seeking earlier revenue recognition. METI industrial policy supports domestic nitinol processing capabilities for stent framework production. Tokyo and Osaka metropolitan hospitals dominate procedure volumes, with super-aged demographic profiles expanding treatable patient populations.
China
NMPA regulatory harmonization with international standards is compressing review timelines for imported endograft systems while strengthening domestic competitor positions. Provincial centralized procurement initiatives in Jiangsu and Guangdong are driving price erosion for standard EVAR devices. Shanghai and Beijing tertiary hospitals concentrate complex fenestrated expertise, creating tiered treatment capacity.
United Kingdom
NHS England's vascular surgery reconfiguration has consolidated AAA repair services into high-volume regional centers, reducing addressable hospital accounts for device suppliers. NICE technology appraisals increasingly reference long-term cost-effectiveness against open surgical alternatives in younger patient cohorts. London and Manchester academic networks generate post-market registry data supporting EMA compliance requirements.
Abdominal Aortic Aneurysm (AAA) Repair Devices Market Vendor Landscape
Integrated endovascular conglomerates and specialized aortic engineering houses split the market into distinct capability tiers. Consolidation pressure intensifies as hospital procurement committees demand bundled surveillance contracts spanning implantation through long-term follow-up. Three archetypes dominate: diversified medical technology portfolios with vascular divisions, pure-play aortic specialists with custom fabrication capabilities, and Asian challengers leveraging nitinol supply chain proximity. Competitive maneuvering concentrates on strategic partnerships for post-market registry construction and capacity expansion into ambulatory surgical center channels.
Within the diversified technology tier, Medtronic and Boston Scientific Corporation occupy positions defined by integrated delivery network contracting scale and cross-portfolio leverage. Cook Medical exemplifies the specialized engineering archetype through its concentration on physician-modified and custom-fit graft solutions. W. L. Gore & Associates, Inc. anchors the materials science differentiation vector with proprietary expanded polytetrafluoroethylene platforms. These three represent distinct strategic postures rather than direct substitutability in hospital vendor selection processes.
| Leading Market Players |
|---|
| Medtronic |
| Cook Medical |
| W. L. Gore & Associates, Inc. |
| Endologix LLC |
| Terumo Corporation |
| Cardinal Health |
| MicroPort Scientific Corporation |
| Boston Scientific Corporation |
| Artivion, Inc. |
| Others |
Supply Flow & Price Mechanics
Platinum-iridium marker band volatility determines both pricing tier spreads and supply chain shape in AAA repair devices, compressing margins on standard EVAR platforms while amplifying premium capture for fenestrated systems with alternative radiopaque engineering.
Pricing Analysis
Aftermarket surveillance revenue streams drive lifetime value capture across integrated delivery networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by graft complexity and physician customization requirements. Price differentiation hinges on FDA premarket approval tier and long-term registry data depth. Cost compression in standard bifurcated grafts is intensifying because provincial procurement initiatives in Asia-Pacific force volume discounts. Ambulatory surgical centers exhibit acute price sensitivity while academic medical centers absorb premium fenestrated device costs through bundled service contracts.
Supply Chain Analysis
Upstream nitinol superelastic alloy feedstock concentrates in United States, Germany, and Japan specialty metallurgy facilities. Device manufacturing draws from ePTFE membrane casting, cobalt-chromium wire drawing, and precision laser-cutting operations. Single-source vulnerability permeates platinum-group metal sourcing for radiopaque markers, with South African and Russian supply concentration creating tariff exposure. Distribution runs through GPO-negotiated contracts into hospital systems and direct-to-ASC channels for high-volume standardized grafts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as graft surveillance systems, AI-assisted imaging analysis, and re-intervention procedure bundling create interoperability-dependent ecosystems that lock hospitals into vendor orbits.
For Market Incumbents: Pre-empt emerging entrant challenges in drug-eluting surface modifications by accelerating R&D partnerships with academic medical centers possessing established post-market registries. Backward integration into nitinol processing capabilities in Germany or Japan secures feedstock priority during commodity tightness. Lock hospital systems into multi-year integrated service contracts spanning implantation through surveillance to raise switching costs.
For New Entrants and Emerging Players: Mid-market community hospitals in United States secondary metros represent the most penetrable entry point, lacking complex fenestrated case volumes but seeking percutaneous EVAR platforms for straightforward anatomies. Japan's PMDA accelerated approval pathway offers faster revenue recognition than FDA timelines for breakthrough graft designs. Target GPO contracts with price-competitive standard bifurcated offerings before expanding into custom-fit physician-modified solutions.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized aortic engineering houses with established surveillance registries over diversified conglomerates facing cross-portfolio margin pressure. Long-term viability rests on fifteen-year durability data generation capabilities and EMA MDR compliance infrastructure. Watch FDA guidance evolution on fenestrated device indications as the inflection signal for addressable patient population expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts bundle surveillance, re-intervention, and training into multi-year agreements. |
| FDA Submission | Premarket approval pathways for fenestrated designs require fifteen-year durability data that advantages incumbent registry holders. |
| CE Marking Pathway | EMA MDR conformity assessments force clinical evidence package rebuilding that compresses smaller competitor margins. |
| Software Companion Development | AI-assisted graft tracking and remote patient monitoring create recurring revenue beyond initial device implantation. |
| Reimbursement Strategy | CMS national coverage determinations on fenestrated indications dictate commercial addressable populations. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with vascular surgeons, interventional radiologists, hospital purchasing committees, and GPO contracts managers; and secondary validation through FDA premarket approval filings, EMA MDR conformity databases, CMS Medicare claims data, and hospital procurement records. Bottom-up procedure volume modeling triangulated against top-down manufacturer revenue estimates across the analysis window.
Forecast inputs span product architecture complexity, delivery mode invasiveness, end-user facility type, and biomaterials technology tier. Segmentation dimensions include graft configuration, access strategy, and surveillance integration level. CAGRs derive from procedure volume trajectories, reimbursement rate evolution, and technology substitution elasticities. Nitinol price indices and platinum-group metal volatility feed into input cost assumptions.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, trade tariff schedules on nitinol alloys, or EMA MDR enforcement intensity would shift the trajectory. Cross-checking against CMS national coverage determination timelines and PMDA accelerated approval decision patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Patient-Controlled Injectors Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Shock Wave Therapy Devices Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
Mobile Cardiac Telemetry Device Market
Cardiovascular Devices
Global Abdominal Aortic Aneurysm Treatment Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Resuscitation Bags Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Continuous Cardiac Monitoring Systems Market
Cardiovascular Devices
Infusion Catheters Market
Cardiovascular Devices
Cardiovascular Devices Market