
 US Hemostats Market | 2026-2036
US Hemostats Market Size, Share, and Industry Trends Forecast 2026-2036
US Hemostats Market Insights
Hospital buying group consolidation is expanding across the US Hemostats Market as integrated delivery networks centralize surgical supply procurement. Baxter International leverages its broad absorbable hemostat portfolio to sustain multi-year contracts with major health systems. Johnson & Johnson Services anchors its position through channel control over oxidized cellulose strips used in cardiac and orthopedic procedures. BD competes on manufacturing scale, supplying private-label hemostatic agents to group purchasing organizations.
Hemostats comprise biologically active or mechanical agents that accelerate clot formation at surgical sites, typically formulated from oxidized regenerated cellulose, gelatin, collagen, or thrombin-based matrices requiring controlled porosity and tensile strength. Their primary commercial purpose is intraoperative blood loss management across open and minimally invasive procedures. Absorbable hemostats lead product type revenue due to their compatibility with laparoscopic delivery modes and reduced need for retrieval. Fibrin sealants represent the fastest-growing segment as surgeons adopt spray application systems for complex tissue planes in cardiac surgery and neurosurgery. Surgical sealants remain margin-dense where premium pricing attaches to synthetic polymer formulations with barrier properties.
FDA 510(k) premarket notification requirements govern hemostat classification and predicate device selection, while OSHA bloodborne pathogen standards drive demand for effective intraoperative bleeding control. The Centers for Medicare & Medicaid Services reimbursement rates for outpatient surgical procedures directly influence adoption of advanced hemostatic products in ambulatory settings. Stakeholders must monitor FDA guidance on regenerative medicine advanced therapy designations as cell-based hemostatic innovations approach clinical evaluation.
Market Dynamics
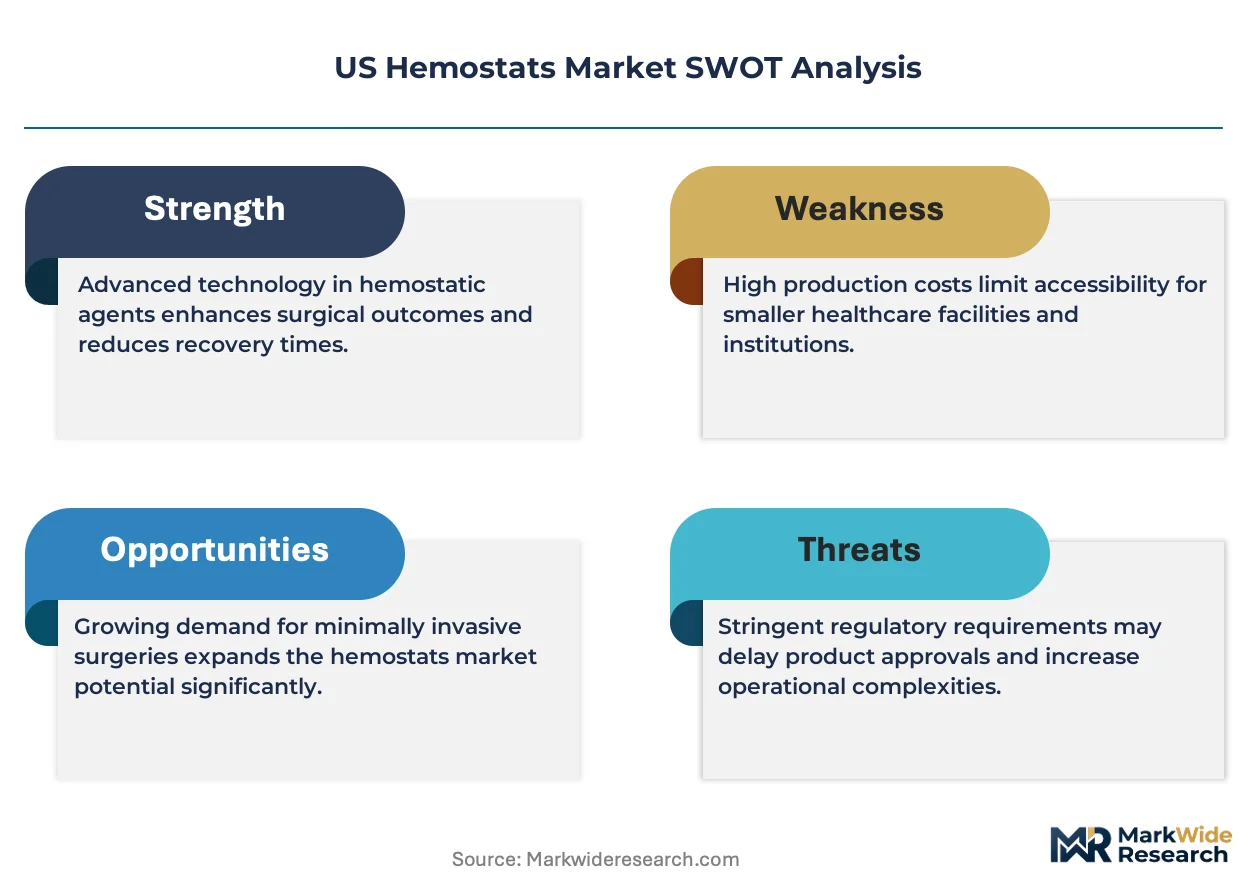
Integrated delivery network consolidation is compressing vendor access points across the US Hemostats Market, forcing manufacturers to secure multi-year enterprise contracts or exit hospital formularies entirely. This procurement centralization is reshaping competitive positioning by privileging scale over specialization.
Growth Catalysts
- Ambulatory surgical center expansion:CMS reimbursement rate adjustments for outpatient procedures are accelerating facility construction in Texas, California, and Florida, directly expanding the addressable site base for absorbable hemostat deployment.
- FDA 510(k) pathway clarity:Predicate device selection standards for oxidized regenerated cellulose products have stabilized, reducing regulatory uncertainty and compressing time-to-market for second-generation formulations.
- Laparoscopic procedure volume:Minimally invasive surgical techniques now dominate general surgery, creating pull for hemostats compatible with trocar delivery and automated applicator systems.
Market Restraints
- Raw material concentration:Pharmaceutical-grade regenerated cellulose supply concentrates among three specialty chemical producers, exposing manufacturers to input cost volatility and allocation risk during demand surges.
- Reimbursement compression:CMS bundled payment models for cardiac and orthopedic procedures are compressing allowable supply costs per episode, squeezing margin on premium hemostatic agents.
- Mechanical substitute availability:Advanced electrosurgical devices and vessel sealing systems are capturing bleeding control applications in open abdominal surgery, displacing topical hemostat volume in high-volume procedures.
Strategic Opportunities
- Fibrin sealant spray systems:Complex tissue plane management in neurosurgery and thoracic procedures represents underpenetrated application space where automated delivery technology can command premium positioning.
- Cell-based hemostatic innovation:FDA regenerative medicine advanced therapy designation pathways for platelet-derived and stem cell-based products offer expedited review timelines and orphan-drug-style exclusivity mechanisms.
- Private-label manufacturing scale:Group purchasing organization contract structures favor suppliers capable of absorbing gelatin and collagen hemostat production at contract-manufacturing scale without brand premium dependency.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization study requirements for novel matrix formulations extend development cycles by 18-24 months, compressing effective patent life.
- Formulary committee access:Hospital value analysis committees now require health-economic outcome data for hemostat adoption, demanding clinical evidence investments that mid-tier suppliers struggle to fund.
- Legacy device integration:Robotic surgical platforms from Intuitive Surgical and Medtronic require hemostat applicator compatibility certification, creating technical barriers to entry in the fastest-growing surgical channel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hemostats Market |
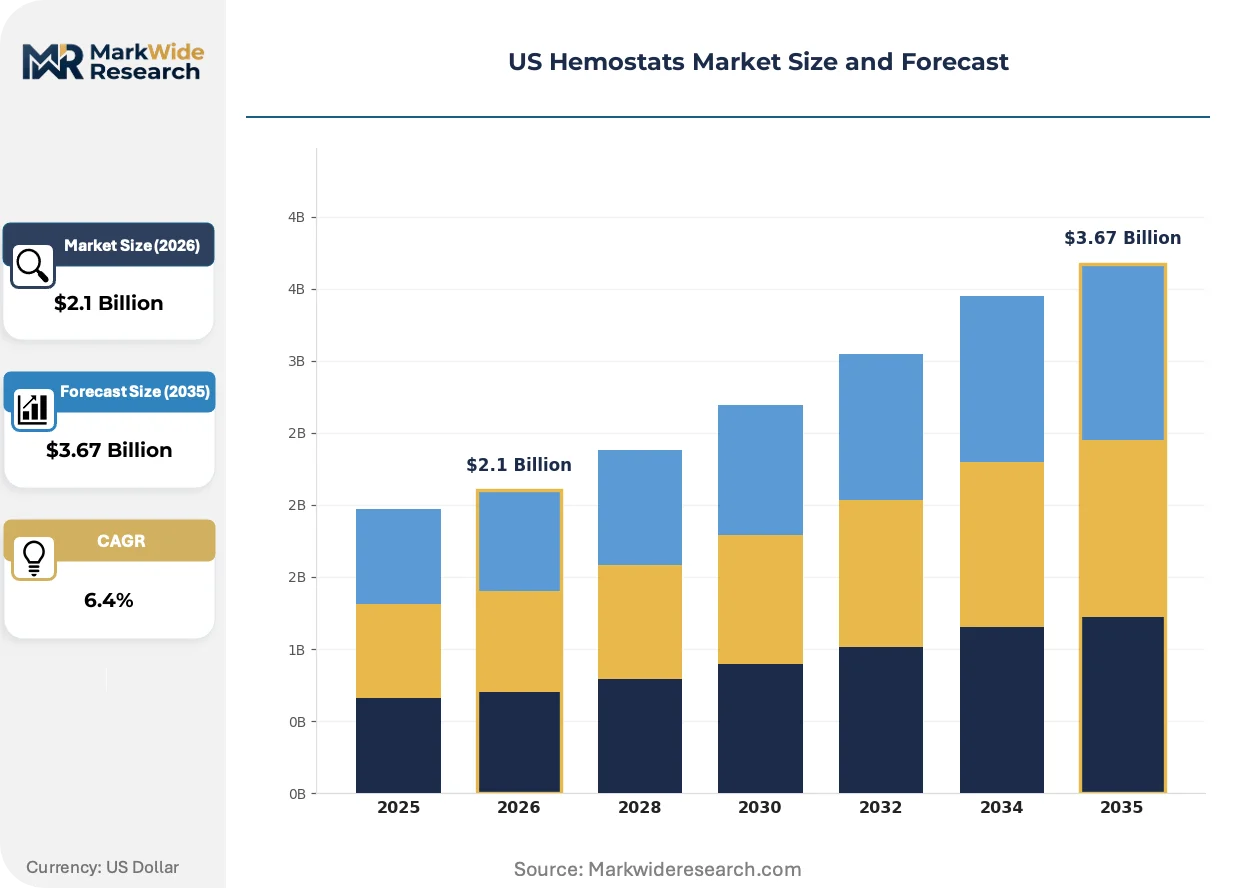
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Hemostats, Non-Absorbable Hemostats, Surgical Sealants, Fibrin Sealants End User: Hospitals, Surgical Centers, Clinics, Ambulatory Surgical Units Application: Cardiac Surgery, Orthopedic Surgery, General Surgery, Neurosurgery Delivery Mode: Topical Application, Injection, Spray, Gel |
| Companies Covered | Baxter International, Johnson & Johnson Services, Pfizer, BD, Integra LifeSciences Corporation, Stryker, Medtronic, Teleflex, B Braun, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hemostats Market Trends and Innovations
Surgical bleeding control is converging around automated delivery systems and bioactive matrix combinations that reduce operative time and transfusion dependency. These innovations are compressing the gap between mechanical and biological hemostasis while reshaping procurement criteria.
Flowable hemostatic matrices combining oxidized cellulose with thrombin are unifying mechanical compression and enzymatic clot acceleration in single-application formats. Cardiac surgery departments at Cleveland Clinic and Mayo Clinic have adopted these hybrid products for sternotomy bleeding control. The technology is unifying previously separate product categories into single-SKU solutions that simplify inventory management and reduce operative decision complexity.
OSHA bloodborne pathogen standard enforcement has intensified scrutiny of intraoperative bleeding control effectiveness, particularly in trauma and emergency surgery settings. Hospital accreditation surveys now incorporate hemostat adequacy assessments as infection control sub-elements. General surgery and orthopedic trauma units in Level I trauma centers are responding by upgrading to higher-performance absorbable agents despite per-unit cost premiums.
Health system supply chain directors are consolidating hemostat sourcing through single-source enterprise agreements that bundle absorbable, flowable, and sealant categories. This contract structure displaces the traditional multi-vendor, procedure-specific purchasing model that dominated the 2010s. The behavioral shift is most visible in Texas and Florida IDNs where ambulatory expansion is creating unified procurement footprints across inpatient and outpatient surgical sites.
US Hemostats Market Segmentation
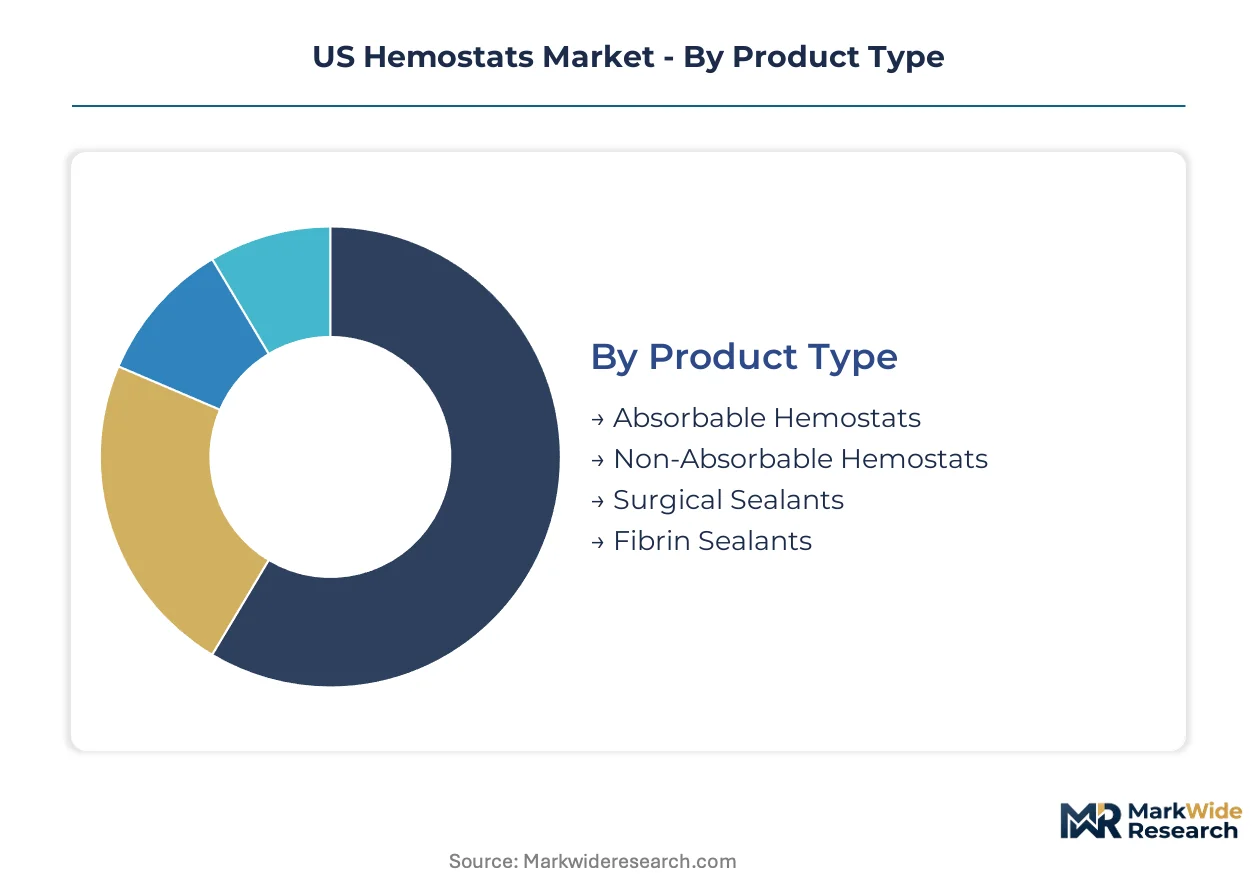
Hemostat procurement decisions fragment across clinical, operational, and economic dimensions. Surgical directors prioritize absorption profiles and delivery compatibility while supply chain managers optimize for contract consolidation and inventory velocity.
Product Type:
Material composition and biodegradation kinetics define the technology axis for hemostat selection in operative workflows.
- Absorbable Hemostats:Oxidized regenerated cellulose matrices dominate laparoscopic deployment due to controlled porosity and tensile strength specifications. Demand concentrates in Texas and Florida ambulatory surgical centers where trocar-compatible formats reduce operative complexity and retrieval requirements.
- Fibrin Sealants:Thrombin-fibrinogen combinations enable spray application across complex tissue planes in cardiac and neurosurgical procedures. Deployment is expanding fastest in Cleveland Clinic and Mayo Clinic cardiac surgery departments where automated delivery systems reduce transfusion dependency.
- Non-Absorbable Hemostats:Mechanical agents requiring post-operative retrieval serve trauma stabilization where immediate bleeding control precedes definitive repair.
- Surgical Sealants:Synthetic polymer barriers command premium positioning in dural closure and air-leak prevention following thoracic resection.
Mature deployment sits with absorbable hemostats. Newer deployment is concentrated in fibrin sealant spray systems.
End User:
Facility reimbursement structure and case volume determine procurement authority and product tier access.
- Hospitals:Integrated delivery networks centralize enterprise contracts across inpatient surgical services, leveraging multi-year agreements with Baxter and Johnson & Johnson for absorbable portfolio access. Value analysis committees in Texas health systems now require health-economic outcome data for formulary inclusion.
- Ambulatory Surgical Units:CMS reimbursement rate adjustments for outpatient procedures are accelerating facility construction in California and Florida. These sites prioritize single-SKU solutions that simplify inventory management across high-volume orthopedic and general surgery cases.
- Surgical Centers:Independent facilities compete on procedure throughput, driving preference for hemostats with rapid application and minimal training requirements.
- Clinics:Limited procedure scope restricts hemostat procurement to topical formats for minor surgical interventions and dermatologic procedures.
Procurement authority is consolidating in hospital IDNs. Volume expansion is climbing the fastest in ambulatory surgical units.
Application:
Procedure-specific bleeding patterns dictate matrix selection and performance thresholds.
- Cardiac Surgery:Sternotomy bleeding control demands flowable matrices combining oxidized cellulose with thrombin for rapid clot formation under active circulation. Hybrid products have achieved standard-of-care status at major academic medical centers.
- Orthopedic Surgery:Bone surface hemostasis in joint replacement and trauma fixation relies on gelatin-based sponges and collagen matrices. Florida and California orthopedic volume is driving absorbable hemostat consumption through both inpatient and ambulatory channels.
- General Surgery:Laparoscopic cholecystectomy and colectomy procedures favor oxidized regenerated cellulose strips compatible with automated applicator systems.
- Neurosurgery:Dural and intracranial applications require precision delivery with minimal tissue reactivity, favoring fibrin sealant spray over particulate matrices.
Established utilization patterns center on cardiac surgery. Steepest expansion trajectory is appearing in orthopedic surgery.
Delivery Mode:
Application mechanics determine compatibility with minimally invasive platforms and operative workflow efficiency.
- Spray:Fibrin sealant aerosolization enables uniform coverage across irregular tissue planes in thoracic and neurosurgical procedures. FDA 510(k) pathway clarity for spray device predicates has stabilized regulatory timelines for second-generation system entrants.
- Topical Application:Direct matrix placement remains the workhorse format for open abdominal and orthopedic procedures, with oxidized cellulose strips and gelatin sponges dominating hospital formularies.
- Injection:Flowable hemostatic matrices deliver through standard syringes for deep cavity bleeding control where direct visualization is limited.
- Gel:Viscous formulations provide sustained contact for mucosal and dental surgical applications outside core hemostat demand.
Dominant utilization remains topical application. Technology migration is accelerating toward spray delivery systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade regenerated cellulose production anchors the US hemostats supply base, with specialty chemical manufacturing clustering in the Gulf Coast and Mid-Atlantic corridors. Hospital procurement consolidation and ambulatory surgical center expansion are redistributing demand geography across state-level health system footprints.
Texas
Ambulatory surgical center construction in Dallas-Fort Worth and Houston is absorbing oxidized regenerated cellulose strips for high-volume orthopedic and general surgery cases. CMS reimbursement rate adjustments for outpatient procedures are accelerating facility licensing in the state. Integrated delivery networks in the Texas Medical Center are centralizing enterprise hemostat contracts across inpatient and outpatient surgical sites.
California
Laparoscopic procedure volume in Los Angeles and San Francisco Bay Area health systems is pulling trocar-compatible absorbable hemostat formats. OSHA bloodborne pathogen standard enforcement in trauma centers is upgrading bleeding control product tiers. Kaiser Permanente and Sutter Health procurement consolidation is compressing vendor access points for hemostatic agents.
Florida
Orthopedic surgery volume in Miami and Tampa metropolitan markets is driving gelatin-based sponge consumption through both hospital and ambulatory channels. State health facility licensing boards are streamlining ASC certification timelines. Florida Hospital and Baptist Health integrated networks are unifying hemostat sourcing across their surgical footprints.
Ohio
Cardiac surgery departments at Cleveland Clinic are adopting flowable hemostatic matrices combining oxidized cellulose with thrombin for sternotomy bleeding control. FDA 510(k) predicate device selection standards are stabilizing regulatory pathways for second-generation formulations. The Cleveland-Akron medical corridor is serving as a pilot site for hybrid hemostat product evaluation.
Illinois
General surgery residency programs in Chicago academic medical centers are training on automated hemostat applicator systems compatible with robotic surgical platforms. CMS bundled payment models for cardiac and orthopedic procedures are compressing allowable supply costs per episode. Northwestern Medicine and Advocate Aurora Health are consolidating value analysis committee oversight of hemostat formulary decisions.
US Hemostats Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cell-based hemostatic innovation and spray delivery technology licensing. The vendor base compresses around three to five integrated manufacturers with multi-year health system contracts, while mid-tier suppliers compete for private-label group purchasing organization slots. Strategic archetypes include diversified medical technology conglomerates with surgical portfolio breadth, specialty hemostat-focused manufacturers with oxidized cellulose expertise, and contract manufacturing organizations serving generic absorbable formats. Competitive moves center on enterprise contract consolidation and robotic surgical platform compatibility certification.
Within the diversified conglomerate tier, Baxter International and Johnson & Johnson Services exemplify scale-driven positioning through broad absorbable hemostat portfolio coverage and channel control over oxidized cellulose strips. BD occupies a contract manufacturing position, supplying private-label hemostatic agents to group purchasing organizations without brand premium dependency. These three anchors illustrate the market's segmentation between full-service surgical suppliers and manufacturing-scale private-label specialists.
| Leading Market Players |
|---|
| Baxter International |
| Johnson & Johnson Services |
| Pfizer |
| BD |
| Integra LifeSciences Corporation |
| Stryker |
| Medtronic |
| Teleflex |
| B Braun |
| Others |
Pricing and Supply Chain Analysis
Hospital buying group consolidation is compressing vendor access points and forcing manufacturers to absorb service bundling costs or exit formularies entirely. This procurement centralization privileges suppliers capable of offering oxidized regenerated cellulose matrices with embedded technical support and inventory management services.
Pricing Analysis
Service bundling separates premium-tier suppliers from contract-manufacturing specialists in the US Hemostats Market. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) predicate lineage, robotic platform certification status, and health-economic outcome data availability. Cost compression in the standard tier is intensifying because CMS bundled payment models squeeze allowable supply costs per cardiac and orthopedic episode. Ambulatory surgical centers exhibit the highest price sensitivity due to thin procedure margins, while academic medical centers prioritize performance metrics over per-unit cost.
Supply Chain Analysis
Specialized chemical engineering talent availability in the Gulf Coast and Mid-Atlantic corridors anchors pharmaceutical-grade regenerated cellulose production. US hemostat manufacturing draws from cellulose ether suppliers in Texas and Louisiana, collagen processors in the Midwest, and thrombin concentrate facilities in North Carolina. Single-source vulnerability concentrates in oxidized regenerated cellulose precursor supply, where three specialty chemical producers control pharmaceutical-grade output. Distribution runs through group purchasing organization warehouses with direct-to-hospital replenishment for high-volume absorbable formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Hemostats Market is becoming a vertical-integration race as manufacturers pursue captive supply of pharmaceutical-grade regenerated cellulose to defend margin against raw material volatility.
For Market Incumbents: Deploy robotic surgical platform compatibility certification as a defensive moat. Baxter International and Johnson & Johnson Services should accelerate applicator system validation with Intuitive Surgical and Medtronic to lock out mid-tier competitors. Backward integration into oxidized cellulose precursor production insulates against allocation risk from Gulf Coast chemical suppliers during demand surges.
For New Entrants and Emerging Players: Direct-to-ambulatory surgical center digital procurement portals offer bypass routes around consolidated hospital IDN contracts. Fibrin sealant spray systems for neurosurgery and thoracic procedures represent the most penetrable white space, with automated delivery technology licensing as the preferred go-to-market angle. Target Texas and Florida ASC construction pipelines where facility-level purchasing authority persists outside enterprise agreements.
For Investors and Strategic Acquirers: The window for entry favors cell-based hemostatic innovators with FDA regenerative medicine advanced therapy designation pathways. Long-term viability hinges on demonstrating clinical outcome differentiation against mechanical substitutes in cardiac surgery. Watch for FDA guidance clarity on platelet-derived product predicates as the inflection signal for valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Platform Certification | Applicator compatibility with Intuitive Surgical systems secures access to fastest-growing surgical channel. |
| Backward Integration into Precursors | In-house oxidized cellulose production mitigates allocation risk from Gulf Coast chemical suppliers. |
| Regenerative Medicine Designation | FDA advanced therapy pathways offer expedited review for platelet-derived hemostatic innovations. |
| Enterprise Contract Consolidation | Multi-year IDN agreements bundle absorbable, flowable, and sealant categories to displace multi-vendor purchasing. |
| Automated Delivery System Licensing | Fibrin sealant spray technology partnerships command premium positioning in neurosurgery and thoracic procedures. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, CMS reimbursement rate filings, and hospital procurement contract disclosures, complemented by interviews with supply chain directors at integrated delivery networks, group purchasing organization contract managers, biomedical engineers specializing in laparoscopic platforms, and regulatory affairs leads at hemostat manufacturers. Secondary validation drew from OSHA bloodborne pathogen standard enforcement records, ambulatory surgical center licensing databases, and SEC filings of diversified medical technology conglomerates. Bottom-up procedure volume estimates and top-down market sizing triangulated across data streams.
Historical adoption curves for oxidized regenerated cellulose and fibrin sealant categories were cross-referenced against panel input from cardiac and orthopedic surgeons regarding technology switching behavior. The analytical framework modeled product type, end-user facility tier, application specialty, and delivery mode segmentation across the projection horizon. CAGRs were derived from procedure volume growth trajectories, reimbursement rate adjustment schedules, and ambulatory surgical center construction pipelines. Forecast inputs included laparoscopic procedure migration rates and robotic surgical platform installation data.
The model holds under stable FDA 510(k) predicate selection standards and continued CMS outpatient reimbursement favorability; deviation in bundled payment model expansion or regenerative medicine guidance timing would shift volume trajectories. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Saphenous Vein Grafts Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Global Cardiovascular Ultrasound System Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Absorbable Heart Stent Market
Cardiovascular Devices
North America Vascular Graft Market
Cardiovascular Devices
Spain Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Drug Eluting Balloon Market
Cardiovascular Devices
Italy Cardiovascular Devices Market