
 Mobile Cardiac Telemetry Device Market | 2026-2036
Mobile Cardiac Telemetry Device Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Cardiac Telemetry Device Market Foresight
Remote monitoring subscription layers are hardening into the core revenue model for mobile cardiac telemetry vendors. iRhythm Technologies leverages its cloud-based algorithm infrastructure to sustain recurring revenue per patient. Medtronic plc anchors its position through integrated device-to-dashboard workflows that dominate hospital procurement cycles. BioTelemetry competes on national scale, controlling one of the largest independent remote cardiac monitoring networks in the United States.
A mobile cardiac telemetry device is a portable, body-worn system that captures electrocardiographic signals continuously and transmits them via cellular or Bluetooth networks to centralized monitoring centers for real-time arrhythmia analysis and clinical intervention. These systems typically operate on single-lead or multi-lead configurations with sampling rates exceeding 250 Hz to ensure diagnostic-grade signal fidelity for detecting atrial fibrillation, ventricular tachycardia, and other episodic events. Patch devices now lead volume shipments due to patient compliance advantages and adhesive form factors that eliminate electrode gel maintenance, while cellular-enabled transmitters command premium positioning because they enable uninterrupted data streams outside Wi-Fi coverage zones where Bluetooth-dependent systems face connectivity gaps.
FDA 510(k) clearances and ISO 13485 quality management certifications shape product development timelines and market access thresholds for manufacturers targeting the United States and European Union markets respectively. The EU Medical Device Regulation imposes stricter clinical evidence requirements on software-as-medical-device components, forcing vendors to expand post-market surveillance infrastructures. Stakeholders must monitor reimbursement coding battles between event monitoring and mobile telemetry categories, as payer classification decisions will determine which device formats achieve profitable utilization rates across health systems.
Market Dynamics
The mobile cardiac telemetry market pivots on algorithmic performance benchmarks tightening under FDA 510(k) pathways, forcing vendors to rebuild signal processing architectures around real-time arrhythmia detection thresholds that now exceed prior clinical validation standards.
Growth Catalysts
- CMS reimbursement alignment:Medicare coverage determinations for remote cardiac monitoring now explicitly favor continuous telemetry over event-based Holter alternatives, expanding billable indications for ambulatory patch systems in United States cardiology practices.
- Bluetooth 5.3 and ultra-wideband integration:Next-generation wireless protocols enable sub-10ms latency for critical arrhythmia alerts, allowing patch manufacturers to reduce cellular modem dependency and extend battery life below adhesive wear limits.
- Aging cardiovascular disease burden in Germany and Japan:National health systems in these countries now mandate post-discharge monitoring for atrial fibrillation patients, creating institutional procurement pipelines for 14-day continuous wear devices.
Market Restraints
- Silver and conductive polymer input volatility:Electrode manufacturing depends on precious metal coatings and specialized adhesive polymers subject to chemical supply chain disruptions concentrated in East Asian specialty chemical producers.
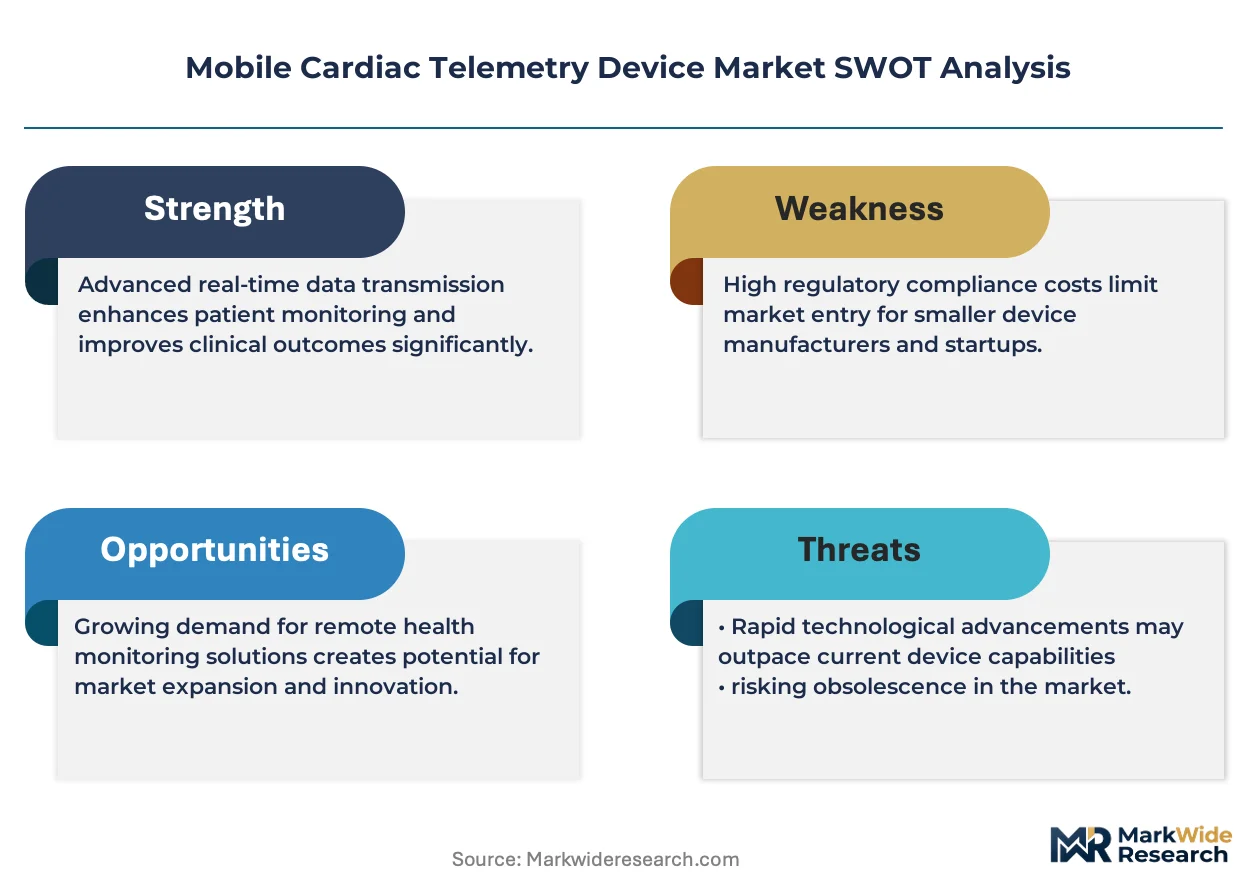
- EU MDR clinical evidence escalation:The Medical Device Regulation now classifies AI-enabled arrhythmia algorithms as Class IIa or higher, requiring prospective clinical studies that extend time-to-market by 18-24 months for software updates.
- Consumer-grade wearable substitution:Apple Watch and similar devices with irregular rhythm notification features capture low-acuity monitoring demand, compressing addressable market for prescription-grade telemetry among younger, self-pay patient segments.
Strategic Opportunities
- Post-acute care transitions in United States skilled nursing facilities:Medicare Advantage plans increasingly contract for remote monitoring during 30-day readmission windows, creating channel partnerships between telemetry vendors and SNF operator networks.
- AI-ECG and digital biomarker convergence:Integration of heart rate variability analytics with sleep staging and activity classification enables multi-parameter risk stratification platforms that command premium reimbursement.
- Direct-to-employer contracting:Self-insured corporations in technology and financial services sectors now purchase cardiac monitoring as preventive benefits, bypassing traditional hospital-centric distribution.
Industry Challenges
- ISO 13485 quality management system maintenance:Continuous software deployment pipelines for machine learning models conflict with document control requirements, forcing hybrid quality architectures that strain smaller engineering teams.
- Interoperability with Epic and Cerner EHR infrastructures:HL7 FHIR implementation varies across health system instances, requiring costly customization for each enterprise deployment rather than standardized integration.
- Biocompatibility testing for extended-wear adhesives:14-day and 30-day patch designs face dermatological adverse event monitoring requirements that extend clinical validation timelines and limit formulation flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Cardiac Telemetry Device Market |
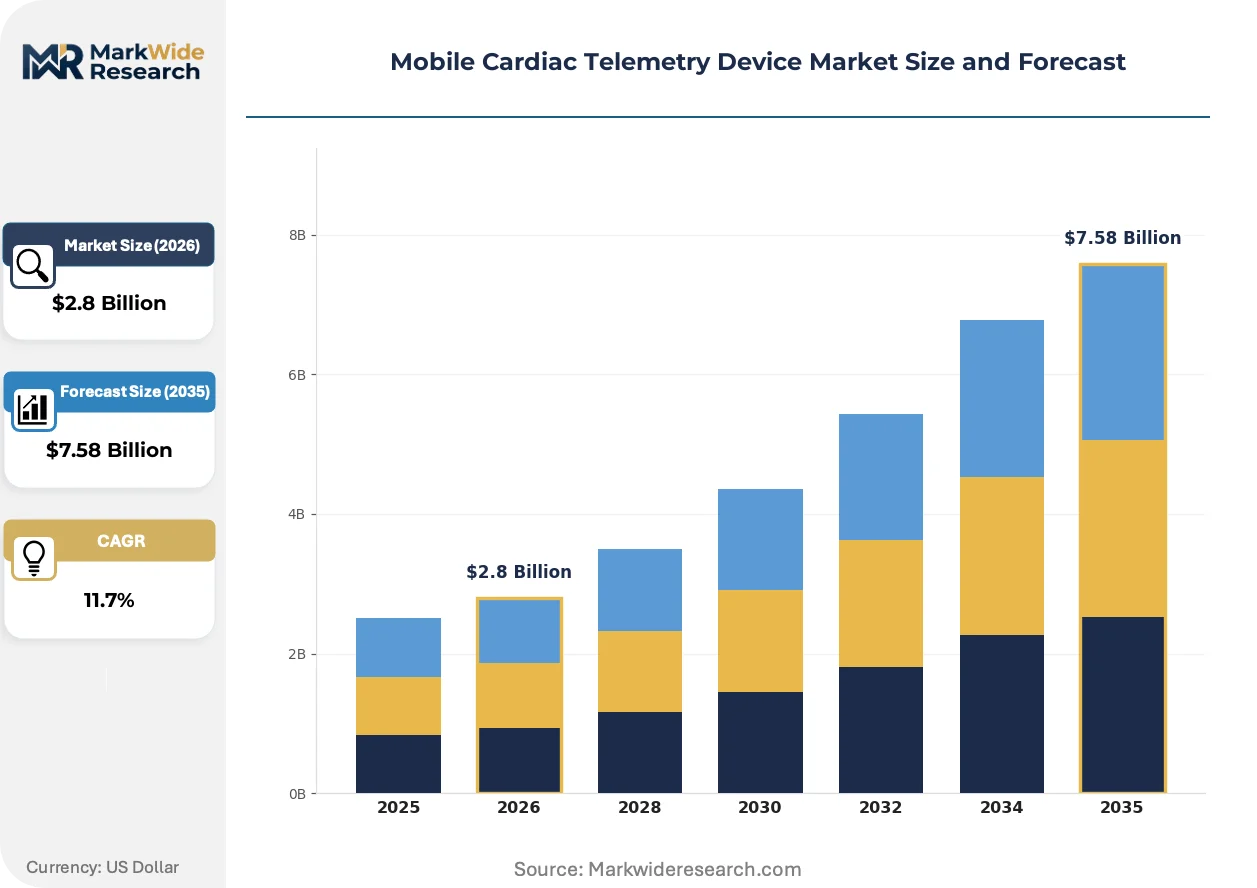
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Monitors, Hand-held Devices, Patch Devices, Transmitters Technology: Bluetooth, Cellular, Wi-Fi, NFC End User: Hospitals, Homecare Providers, Cardiology Clinics, Remote Monitoring Services Application: Arrhythmia Monitoring, Post-operative Care, Fitness Tracking, Heart Rate Variability |
| Companies Covered | Medtronic plc, iRhythm Technologies, Boston Scientific Cardiac Diagnostics, Zoll Medical Corporation, Koninklijke Philips, BioTelemetry, ScottCare Cardiovascular Solutions, Biotricity, Applied Cardiac Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Cardiac Telemetry Device Market Shifts & Advancements
Algorithmic transparency requirements and disposable electronics miniaturization are restructuring competitive advantage around signal fidelity and patient adherence engineering rather than hardware durability alone.
Dry electrode arrays with micro-needle conductive interfaces are absorbing the function of traditional gel-based Ag/AgCl electrodes in next-generation patch designs. Cardiology clinics in the United States and Germany are piloting these configurations for patients with skin sensitivity to prolonged adhesive exposure. The shift is absorbing maintenance burdens from clinical staff while compressing signal artifact rates that previously required manual technician review.
The FDA's evolving guidance on predetermined change control plans for machine learning-enabled devices is restructuring software development lifecycle investments. Manufacturers must now lock algorithmic performance boundaries at submission rather than iterating post-clearance. United States-based vendors with cloud infrastructure are responding by segmenting model architectures into locked core classifiers and configurable post-processing layers.
Hospital procurement committees now unbundle device acquisition from monitoring service contracts, reversing prior bundled pricing conventions. Health systems in Japan and select United States integrated delivery networks are negotiating direct algorithm licensing while sourcing patches from contract manufacturers. This behavior concentrates most visible in regions where cardiology department budgets face institutional cost-reduction mandates.
Mobile Cardiac Telemetry Device Market Segmentation
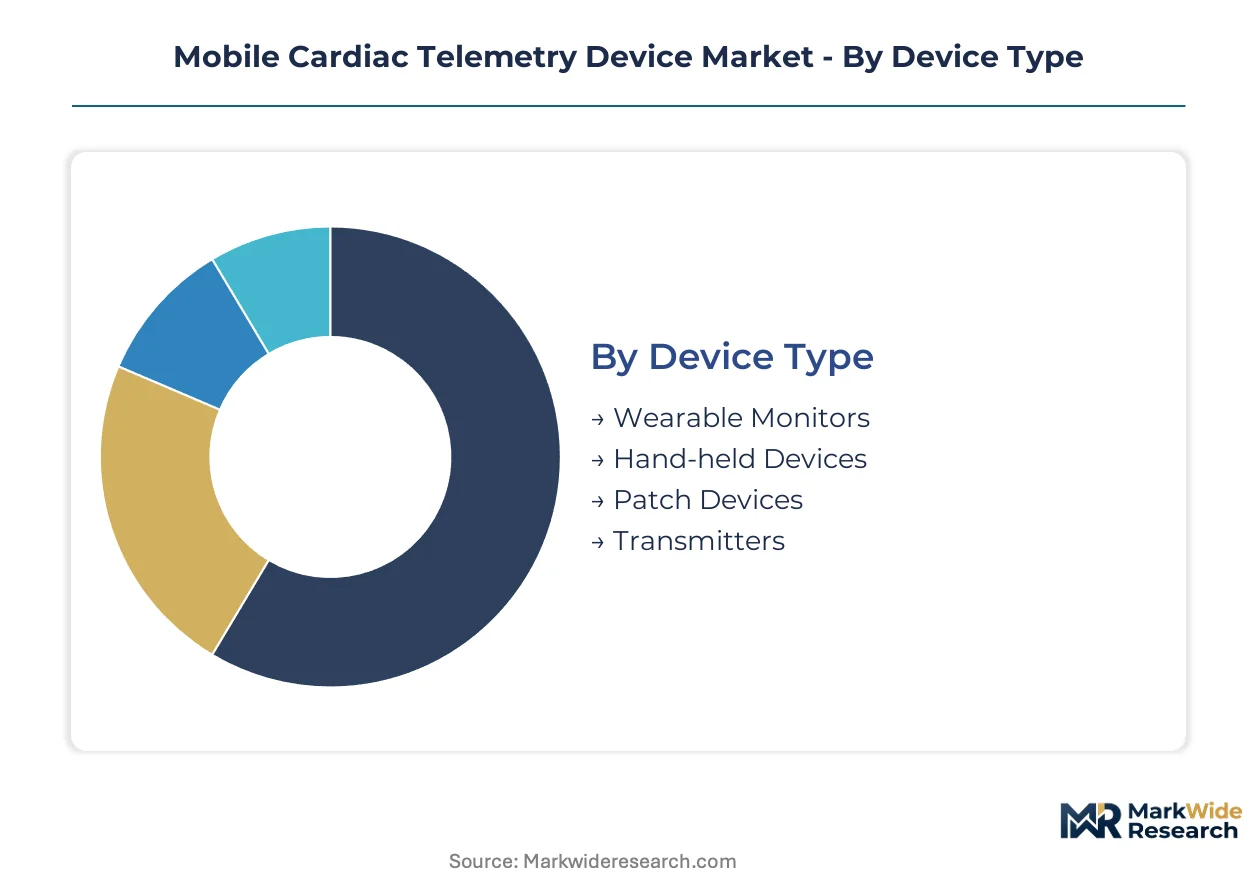
Segmentation in mobile cardiac telemetry reveals where capital deployment, regulatory burden, and reimbursement rates diverge. Device manufacturers optimize portfolios by matching hardware configurations to specific clinical workflows and connectivity infrastructures.
Device Type:
Capital requirements vary sharply across form factors, with cloud-connected backend systems demanding heavier infrastructure investment than disposable hardware.
- Patch Devices:Single-use adhesive systems with integrated electrodes and sealed electronics eliminate gel maintenance and patient education overhead. Demand concentrates in United States cardiology clinics where CMS reimbursement codes for continuous ambulatory monitoring favor patch-based billable events over traditional Holter replacements.
- Wearable Monitors:Reusable wrist-worn or chest-strap configurations with detachable sensors support multi-patient utilization across hospital fleets. Procurement in Germany and Japan targets aging populations requiring extended monitoring beyond acute episodes, with institutional buyers prioritizing device durability over disposability economics.
- Hand-held Devices:Patient-activated recorders with symptomatic event capture function.
- Transmitters:Dedicated cellular or Bluetooth relay units bridging legacy electrode sets to monitoring centers.
Most installed capacity flows through Patch Devices. Expansion is steepest in Wearable Monitors.
Technology:
Connectivity selection determines power budgets, real-time alert latency, and geographic coverage constraints for ambulatory patients.
- Cellular:Integrated LTE-M or NB-IoT modems enable uninterrupted data transmission outside Wi-Fi coverage, critical for rural United States deployments and emergency arrhythmia alerts. Hardware cost premiums and recurring carrier fees concentrate adoption in reimbursed clinical indications rather than consumer-adjacent segments.
- Bluetooth:Low-energy protocols in 5.0+ configurations support multi-day battery life in patch form factors. Japanese health systems leverage Bluetooth-dependent systems for post-discharge atrial fibrillation monitoring where smartphone tethering assumptions hold across aging but digitally equipped patient populations.
- Wi-Fi:Higher bandwidth suitable for multi-lead streaming in stationary home environments.
- NFC:Proximity-based pairing for initial device provisioning and patient onboarding workflows.
Cellular dominates revenue per unit shipped. Bluetooth is gaining share fastest in volume terms.
End User:
Customer type dictates sales cycle length, with hospital procurement committees extending evaluation timelines versus direct-to-provider contracting.
- Remote Monitoring Services:Independent diagnostic testing facilities and national monitoring centers purchase devices at scale for patient leasing programs. United States-based services compete on algorithm accuracy and 24/7 technician staffing, with device selection driven by integration speed into existing cloud infrastructure.
- Hospitals:Integrated delivery networks negotiate enterprise contracts bundling devices with EHR connectivity and staff training. German hospital procurement prioritizes ISO 13485-certified suppliers with established EU MDR technical documentation to minimize regulatory due diligence burden.
- Cardiology Clinics:Outpatient practices with direct patient relationships and prescription authority.
- Homecare Providers:Skilled nursing and post-acute services managing 30-day readmission risk windows.
Remote Monitoring Services command the highest device throughput per account. Hospital expansion is climbing the fastest as health systems build internal telemetry programs.
Application:
Clinical indication determines reimbursement tier and algorithm performance requirements, with arrhythmia detection facing stricter FDA validation than wellness-oriented monitoring.
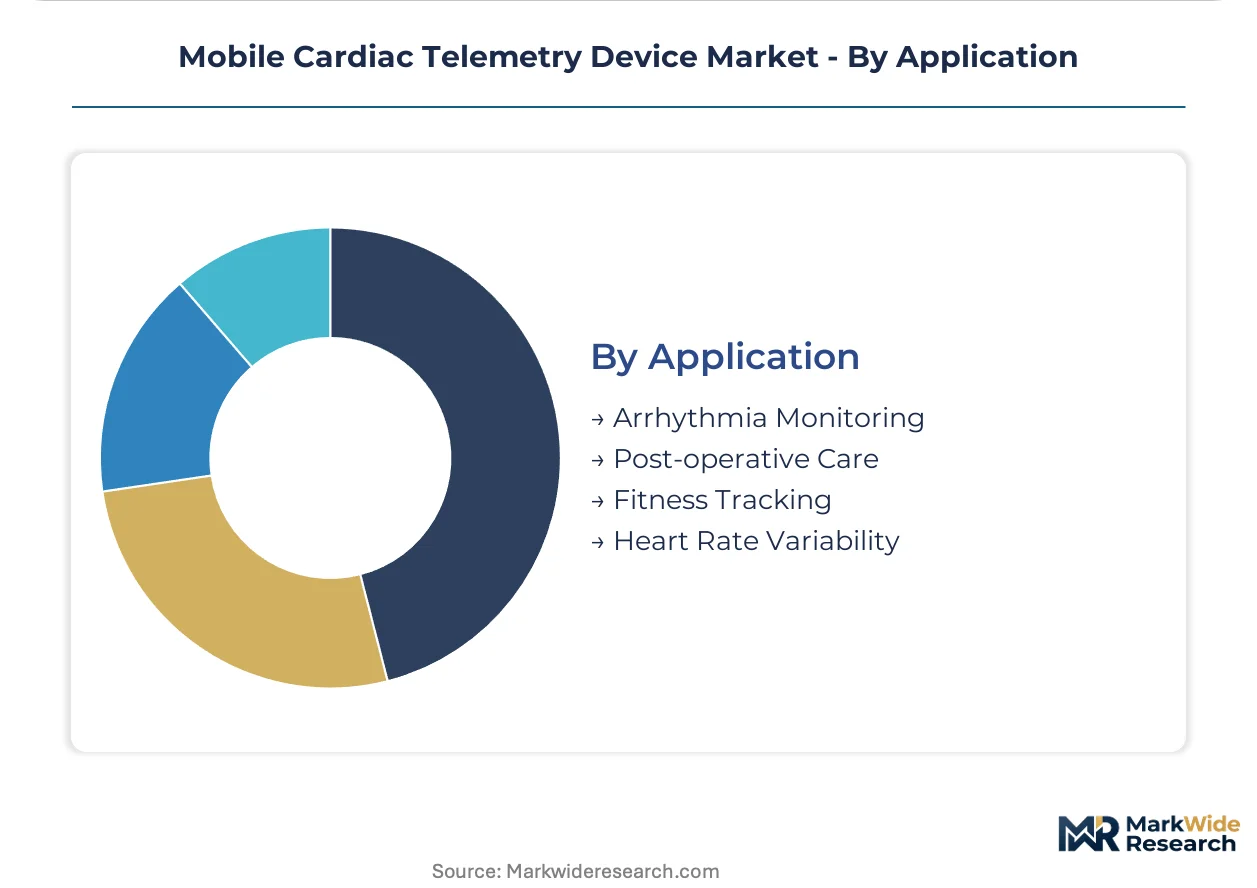
- Arrhythmia Monitoring:Diagnostic-grade atrial fibrillation and ventricular tachycardia detection requires sampling rates above 250 Hz and real-time alert latency under 30 seconds. United States demand concentrates in Medicare-eligible populations where continuous telemetry carries distinct reimbursement advantages over event-based alternatives.
- Post-operative Care:Cardiac surgery and electrophysiology procedure follow-up monitoring captures recurrence of atrial flutter or conduction abnormalities. Japanese national health insurance mandates post-discharge surveillance for specific procedure codes, institutionalizing procurement pipelines for 14-day wear devices.
- Heart Rate Variability:Autonomic function assessment for stress and recovery metrics.
- Fitness Tracking:Consumer-adjacent wellness applications with lower regulatory barriers.
Arrhythmia Monitoring absorbs the majority of prescription-grade device shipments. Post-operative Care shows the steepest expansion trajectory as surgical volume rises and readmission penalties tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Germany diverge in reimbursement velocity, with American Medicare Advantage plans accelerating remote monitoring contracts while German statutory health insurance imposes lengthier technology assessment protocols. Japan bridges both models through national health technology pricing that institutionalizes post-discharge cardiac surveillance.
United States
Medicare coverage determinations now explicitly favor continuous telemetry over event-based Holter monitoring, expanding billable indications for ambulatory patch systems across cardiology practices. FDA 510(k) pathways for real-time arrhythmia detection algorithms are tightening performance benchmarks that exceed prior clinical validation standards. Boston and the Research Triangle host concentrated algorithm development clusters where cloud-based diagnostic platforms integrate with Epic and Cerner EHR infrastructures.
Germany
Aging cardiovascular disease burden and statutory health insurance mandates for post-discharge atrial fibrillation monitoring create institutional procurement pipelines for 14-day continuous wear devices. EU Medical Device Regulation imposes stricter clinical evidence requirements on software-as-medical-device components, forcing vendors to expand post-market surveillance infrastructures. Bavaria and Baden-Württemberg concentrate medical technology manufacturing where ISO 13485-certified suppliers dominate hospital procurement cycles.
Japan
National health insurance mandates post-discharge surveillance for specific cardiac procedure codes, institutionalizing procurement pipelines for extended-wear telemetry devices. Pharmaceuticals and Medical Devices Agency oversight shapes algorithmic transparency requirements for machine learning-enabled diagnostic systems. Tokyo and Osaka metropolitan areas concentrate remote monitoring service networks where Bluetooth-dependent systems leverage high smartphone penetration among aging patient populations.
United Kingdom
National Health Service long-term plan targets for cardiovascular disease prevention are expanding remote monitoring pilots in integrated care systems. Medicines and Healthcare products Regulatory Agency alignment with EU MDR post-Brexit maintains stringent clinical evidence requirements for AI-enabled arrhythmia algorithms. London and the Greater Manchester health innovation cluster host digital health procurement programs that unbundle device acquisition from monitoring service contracts.
South Korea
National health insurance service expansion of remote patient monitoring benefits covers cardiac telemetry for post-operative care transitions. Ministry of Food and Drug Safety accelerated review pathways for software-as-medical-device products are compressing time-to-market for algorithm updates. Seoul Capital Area medical device manufacturing clusters are piloting dry electrode arrays with micro-needle conductive interfaces for patients with adhesive sensitivity.
Mobile Cardiac Telemetry Device Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated device-to-dashboard workflows dominating hospital procurement cycles while independent remote monitoring networks compete on national scale and algorithm accuracy. The vendor base concentrates around three strategic archetypes: cloud-native algorithm developers with recurring revenue subscription models, diversified medical technology conglomerates with enterprise EHR integration capabilities, and independent diagnostic testing facilities with 24/7 technician staffing infrastructure. Competitive moves center on unbundling device acquisition from monitoring service contracts and establishing direct algorithm licensing arrangements with health systems facing cost-reduction mandates.
Within the cloud-native tier, iRhythm Technologies exemplifies algorithm-centric positioning sustained through cloud-based infrastructure and recurring revenue per patient models. Medtronic plc anchors the diversified conglomerate archetype with integrated device-to-dashboard workflows that dominate hospital procurement cycles. BioTelemetry occupies a position within the independent monitoring network tier, controlling national-scale remote cardiac surveillance infrastructure across the United States.
| Leading Market Players |
|---|
| Medtronic plc |
| iRhythm Technologies |
| Boston Scientific Cardiac Diagnostics |
| Zoll Medical Corporation |
| Koninklijke Philips |
| BioTelemetry |
| ScottCare Cardiovascular Solutions |
| Biotricity |
| Applied Cardiac Systems |
| Others |
Supply & Pricing Matrix
Silver spot price volatility and conductive polymer feedstock indices cascade through electrode manufacturing costs, compressing margins on adhesive patch components while cellular modem procurement from East Asian semiconductor fabs sustains premium pricing tiers for real-time telemetry systems.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for Bluetooth-enabled patch controllers, forcing legacy cellular-dependent systems toward three-tier pricing structure across premium, standard, and economy levels. FDA 510(k) certification tier separates diagnostic-grade arrhythmia algorithms from wellness-adjacent monitoring, with ISO 13485 quality management investment acting as the primary price differentiation driver. Cost compression in the standard tier is intensifying because contract manufacturers in China are absorbing adhesive formulation R&D overhead. Hospital procurement committees exhibit the highest price sensitivity, while remote monitoring services prioritize algorithm accuracy over unit economics.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States hospital procurement committees and German statutory health insurance frameworks are fragmenting electrode supplier concentration across Japan, South Korea, and domestic United States specialty chemical producers. Silver-coated conductive polymers and medical-grade silicone adhesives feed from East Asian petrochemical complexes, with LTE-M cellular modems resting on Taiwan and South Korea semiconductor packaging capacity. Single-source vulnerability concentrates in FDA-registered adhesive formulation facilities. Distribution runs through GPO contracts and direct hospital system agreements rather than traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where Medicare reimbursement alignment and EU MDR clinical evidence escalation are filtering demand toward premium-specification continuous telemetry over event-based alternatives.
For Market Incumbents: Extend cloud-based algorithm infrastructure investments to lock recurring revenue per patient models before hospital procurement committees complete unbundling of device acquisition from monitoring service contracts. Defend against independent diagnostic testing facility expansion by securing exclusive EHR integration partnerships with Epic and Cerner deployments. Prioritize ISO 13485 quality system automation to reduce software deployment pipeline friction under FDA predetermined change control plans. For New Entrants and Emerging Players: Enter via direct-to-employer contracting channels in United States technology and financial services sectors, where self-insured corporations purchase cardiac monitoring as preventive benefits outside hospital-centric distribution. Target skilled nursing facility operator networks managing Medicare Advantage 30-day readmission windows as the most penetrable end-use segment. Lead with AI-ECG multi-parameter risk stratification platforms that command premium reimbursement through heart rate variability analytics integration. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native algorithm developers possessing locked FDA 510(k) clearances and established recurring revenue infrastructure. Long-term viability favors vendors with backward integration into adhesive formulation and electrode manufacturing rather than pure software plays exposed to hardware commoditization. Watch for CMS reimbursement coding battles between event monitoring and mobile telemetry categories as the primary inflection signal determining profitable utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Real-Time Arrhythmia Algorithms | 510(k) clearance with predetermined change control plans locks competitive positioning under tightening performance benchmarks. |
| CE Marking Pathway under EU MDR | Class IIa software-as-medical-device classification requires prospective clinical studies that extend time-to-market for algorithm updates. |
| Hospital System Partnership for EHR Integration | Epic and Cerner HL7 FHIR implementations demand costly customization that creates switching costs and recurring integration revenue. |
| Software Companion Development for Multi-Parameter Analytics | Heart rate variability with sleep staging and activity classification enables premium reimbursement through digital biomarker convergence. |
| Reimbursement Strategy for Continuous Telemetry Codes | Medicare coverage determinations explicitly favor continuous telemetry over event-based Holter alternatives in United States cardiology practices. |
Research Methodology
Coverage spans the United States, Germany, Japan, the United Kingdom, and South Korea, with primary inputs from each market combining executive interviews with cardiology clinic directors, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and remote monitoring service operations leads. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare coverage determinations, hospital procurement contract records, and cellular carrier IoT deployment disclosures. Bottom-up device shipment modeling and top-down reimbursement flow analysis were triangulated against algorithm accuracy benchmarks and adhesive formulation cost structures.
Granularity-level framing applied device type, connectivity technology, end-user archetype, and clinical application dimensions at the country level, with sampling rate specifications and real-time alert latency thresholds modeled as quality-tier differentiators. CAGRs were derived from logistic diffusion curves fitted to Medicare Advantage remote monitoring penetration rates and statutory health insurance mandate implementation timelines. Forecast inputs incorporated EU MDR transition compliance costs and Bluetooth 5.3 protocol adoption curves in patch device engineering.
Inputs from PMDA, FDA, and EU notified body regulatory filings were available through the study window; gaps in real-time hospital procurement contract pricing introduce uncertainty bands around device margin assumptions. Deviation in CMS reimbursement coding classification between event monitoring and mobile telemetry categories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Abdominal Aortic Aneurysm (AAA) Repair Devices Market
Cardiovascular Devices
North America Cardiac Assist Devices Market
Cardiovascular Devices
Global Aortic Repair Devices Market
Cardiovascular Devices
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market
Cardiovascular Devices
Neurovascular Coiling Assist Devices Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Resuscitation Bags Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market