
 Cervical Dilators Market | 2026-2036
Cervical Dilators Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Dilators Market Analysis
ISO 13485 certification for medical device quality management is redrawing competitive boundaries in cervical dilator manufacturing. CooperSurgical Inc. leverages its vertically integrated production network to sustain consistent supply to hospital systems across North America. Cook Medical anchors its position through deep specialization in hydrophilic polymer formulations for laminaria-based dilators. Medtronic competes by controlling distribution channels that reach ambulatory surgical centers with same-day procedure protocols.
Cervical dilators are tapered instruments designed to gradually widen the cervical canal, typically manufactured from silicone, polyvinyl chloride, or absorbent laminaria materials that expand upon fluid contact to achieve mechanical dilation over controlled time intervals. Their primary purpose spans obstetric induction, gynecological surgical access, and embryo transfer procedures in assisted reproduction. Mechanical dilators retain dominant share in hospital settings where immediate, physician-controlled dilation remains protocol standard, while balloon dilators capture expanding preference in fertility centers for their pressure-regulated expansion and reduced cervical trauma. Hydrophilic dilators represent the fastest-growing category as outpatient migration drives demand for single-use, hydration-activated devices that eliminate sterilization overhead.
FDA 510(k) clearance pathways and EU MDR Class IIa device requirements impose substantial clinical evidence burdens on manufacturers seeking market access in the United States and European Union. The FDA's ongoing scrutiny of synthetic laminaria alternatives has redirected R&D investment toward silicone and polyethylene formulations with documented biocompatibility profiles. Japan's PMDA maintains distinct standards for obstetric device materials that limit direct product portability from Western markets. Stakeholders must monitor evolving notified body capacity constraints under MDR implementation and calibrate regulatory submission strategies across multiple jurisdictions to secure timely approval timelines.
Market Dynamics
EU MDR Class IIa device requirements are compressing manufacturer margins while accelerating consolidation among notified body-dependent suppliers. The shift from reusable to single-use hydrophilic dilators is redrawing procurement specifications across hospital systems.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearances for silicone-based dilators with established biocompatibility profiles are shortening time-to-market for iterative product improvements.
- Fertility center expansion:Specialized reproductive clinics in Germany and Spain are standardizing balloon dilator protocols for embryo transfer procedures.
- Hydrophilic polymer chemistry:Advanced laminaria alternatives with controlled expansion rates are capturing preference in ambulatory settings seeking same-day discharge.
Market Restraints
- Notified body capacity constraints:EU MDR implementation bottlenecks are extending certification timelines by 12-18 months for Class IIa obstetric devices.
- Raw material concentration:Medical-grade silicone supply chains cluster in Northeast Asian chemical manufacturing zones, exposing producers to logistics volatility.
- Sterilization infrastructure legacy:Hospital systems with sunk capital in autoclave networks resist full conversion to single-use hydrophilic formats.
Strategic Opportunities
- Japan PMDA compliance:Distinct material standards for obstetric devices create first-mover advantage for Western manufacturers investing in localized biocompatibility testing.
- Telemedicine-integrated distribution:Direct-to-clinic replenishment models bypass traditional distributor markups for high-volume fertility networks.
- ISO 13485 certification arbitrage:Quality management gaps among regional Asian manufacturers open acquisition targets for quality-compliant Western players.
Industry Challenges
- Polymer engineering talent scarcity:Specialized formulation chemists with hydrophilic coating expertise command premium compensation in medical device hubs.
- Legacy sterilization workforce retraining:Hospital supply chain staff require reskilling as facilities transition from reusable to disposable dilator inventories.
- Cross-jurisdiction dossier harmonization:Divergent FDA and PMDA clinical evidence requirements force redundant testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Dilators Market |
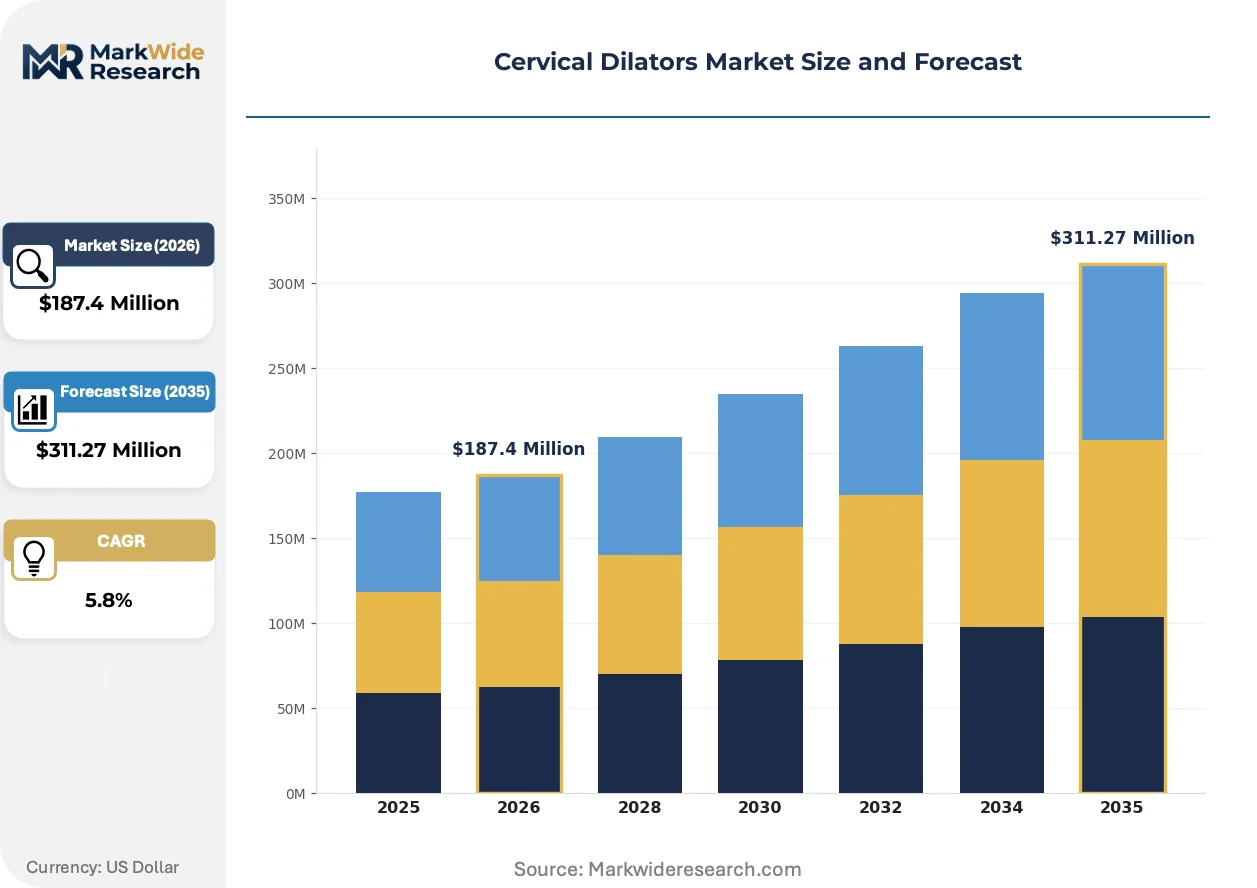
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Dilators, Mechanical Dilators, Hydrophilic Dilators, Other Types End User: Hospitals, Clinics, Ambulatory Surgical Centers, Fertility Centers Material: Silicone, PVC, Polyethylene, Other Materials Application: Gynecological Procedures, Obstetric Procedures, IVF Treatments, Diagnostic Procedures |
| Companies Covered | CooperSurgical Inc., MedGyn Products Inc., Cook Medical, Hologic Inc., Boston Scientific Corporation, Medtronic, Teleflex Incorporated, Medline Industries LP, Sklar Surgical Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Dilators Market Emerging Trajectories
Material science advances and regulatory compression are forcing simultaneous innovation in product format and quality systems. Manufacturers must now engineer for single-use performance while documenting compliance across multiple jurisdictions.
Silicone-hydrogel composite dilators are decomposing the traditional mechanical-balloon dichotomy by combining immediate physician control with pressure-limited expansion. Fertility centers in the Netherlands and Belgium are piloting these hybrid formats for IVF protocols. The technology is decomposing established procurement categories that separated emergency dilation from scheduled reproductive procedures.
EU MDR technical documentation requirements are forcing manufacturers to rebuild clinical evidence portfolios for legacy laminaria products. Small-to-mid-cap suppliers without verticalized regulatory affairs functions are outsourcing dossier preparation to specialized CROs. German notified bodies report 40% application backlogs for obstetric device recertifications.
Integrated delivery networks in the United States are consolidating gynecological supply contracts under centralized procurement officers. Independent ambulatory surgery centers lose price leverage as hospital systems negotiate volume-tiered agreements directly with manufacturers. This concentration is most visible in Texas and Florida where IDN expansion has compressed independent distributor margins by half.
Cervical Dilators Market Segmentation
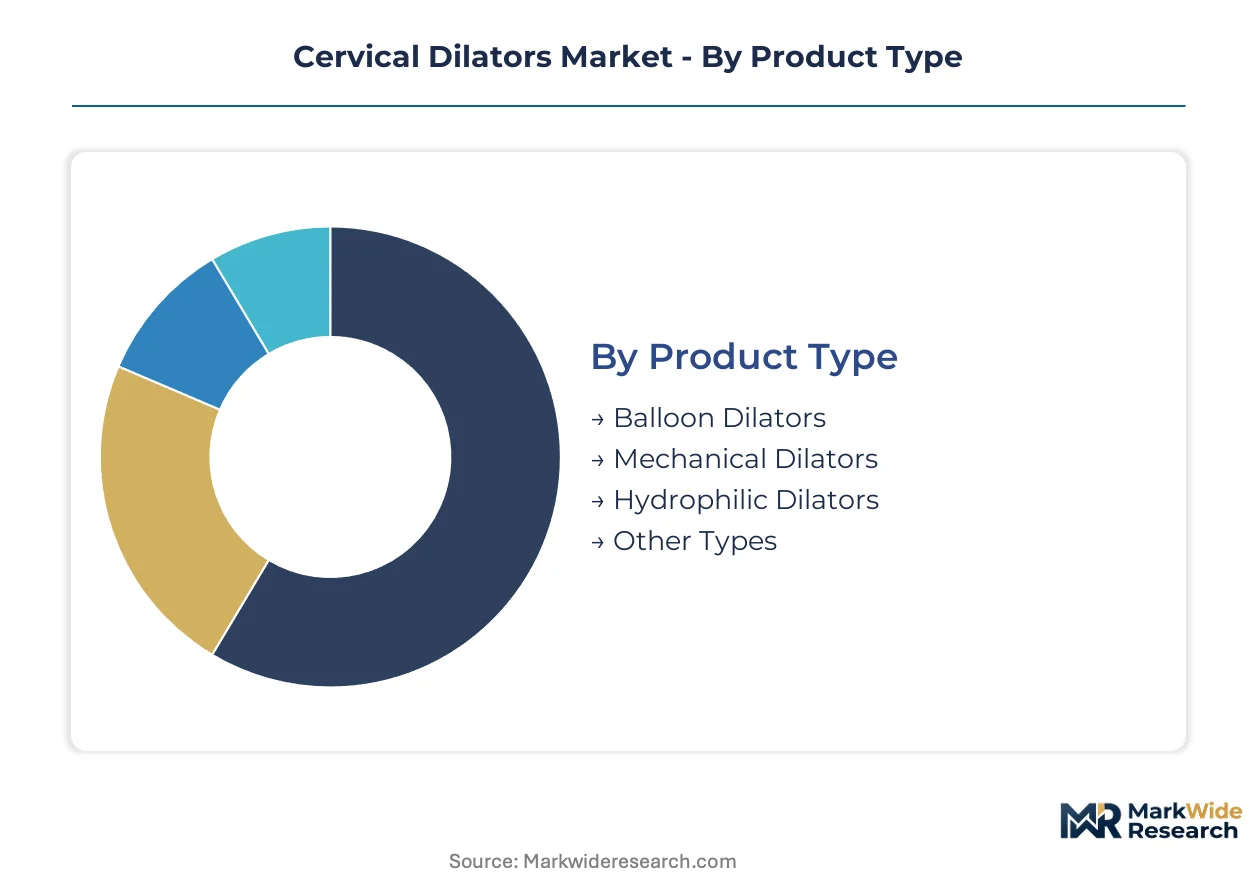
Cervical dilator segmentation reveals how regulatory pathways and clinical settings reshape procurement priorities. Manufacturers must align product formats with specific compliance requirements and end-use protocols.
Product Type:
FDA 510(k) clearance timelines vary significantly across mechanical, balloon, and hydrophilic formats, with silicone-based submissions averaging shorter review cycles than laminaria alternatives.
- Mechanical Dilators:Stainless steel or rigid polymer rods with graduated diameters enable immediate, physician-controlled dilation. Hospital systems in the United States standardize these for emergency obstetric access where speed overrides material preference. FDA maintains well-established predicate device libraries for this category, streamlining iterative approvals.
- Hydrophilic Dilators:Hydration-activated polymer shafts expand through osmotic fluid absorption, eliminating sterilization infrastructure. Ambulatory surgical centers in Germany and Spain are converting to these formats for same-day discharge protocols. EU MDR technical documentation requirements are forcing manufacturers to rebuild clinical evidence portfolios for legacy products in this segment.
- Balloon Dilators:Pressure-regulated inflation systems reduce cervical trauma in fertility applications.
- Other Types:Specialty configurations including osmotic laminaria and combination devices.
Established volume favors mechanical dilators; emerging adoption favors hydrophilic dilators.
End User:
Procurement authority concentrates differently across integrated delivery networks, independent clinics, and specialized reproductive facilities.
- Hospitals:Centralized supply chains negotiate volume-tiered agreements directly with manufacturers. Texas and Florida IDNs have compressed independent distributor margins through consolidated gynecological contracts. Autoclave infrastructure investments create inertia against full single-use conversion.
- Fertility Centers:Specialized reproductive clinics in the Netherlands and Belgium pilot hybrid silicone-hydrogel formats for IVF embryo transfer. Balloon dilator protocols are standardizing across German and Spanish fertility networks. These facilities prioritize pressure-limited expansion to minimize cervical trauma in elective procedures.
- Ambulatory Surgical Centers:Same-day discharge requirements drive preference for disposable formats with minimal processing overhead.
- Clinics:Independent gynecological practices maintain flexibility in format selection but lose price leverage.
Procurement scale favors hospitals; protocol specialization favors fertility centers.
Material:
Biocompatibility documentation requirements under EU MDR and Japan PMDA are redirecting formulation investments away from traditional laminaria toward synthetic polymers.
- Silicone:Medical-grade formulations with established ISO 10993 testing histories command premium positioning. Supply chains cluster in Northeast Asian chemical manufacturing zones, exposing producers to logistics volatility. FDA's scrutiny of synthetic laminaria alternatives has accelerated R&D investment in silicone-based alternatives with documented safety profiles.
- Polyethylene:Controlled expansion rates and predictable hydration kinetics suit outpatient migration trends. German notified bodies report application backlogs for obstetric device recertifications involving novel polyethylene formulations.
- PVC:Cost-effective for high-volume disposable applications with established sterilization compatibility.
- Other Materials:Hydrogel composites and experimental bioabsorbable formulations.
Regulatory familiarity favors silicone; performance innovation favors polyethylene.
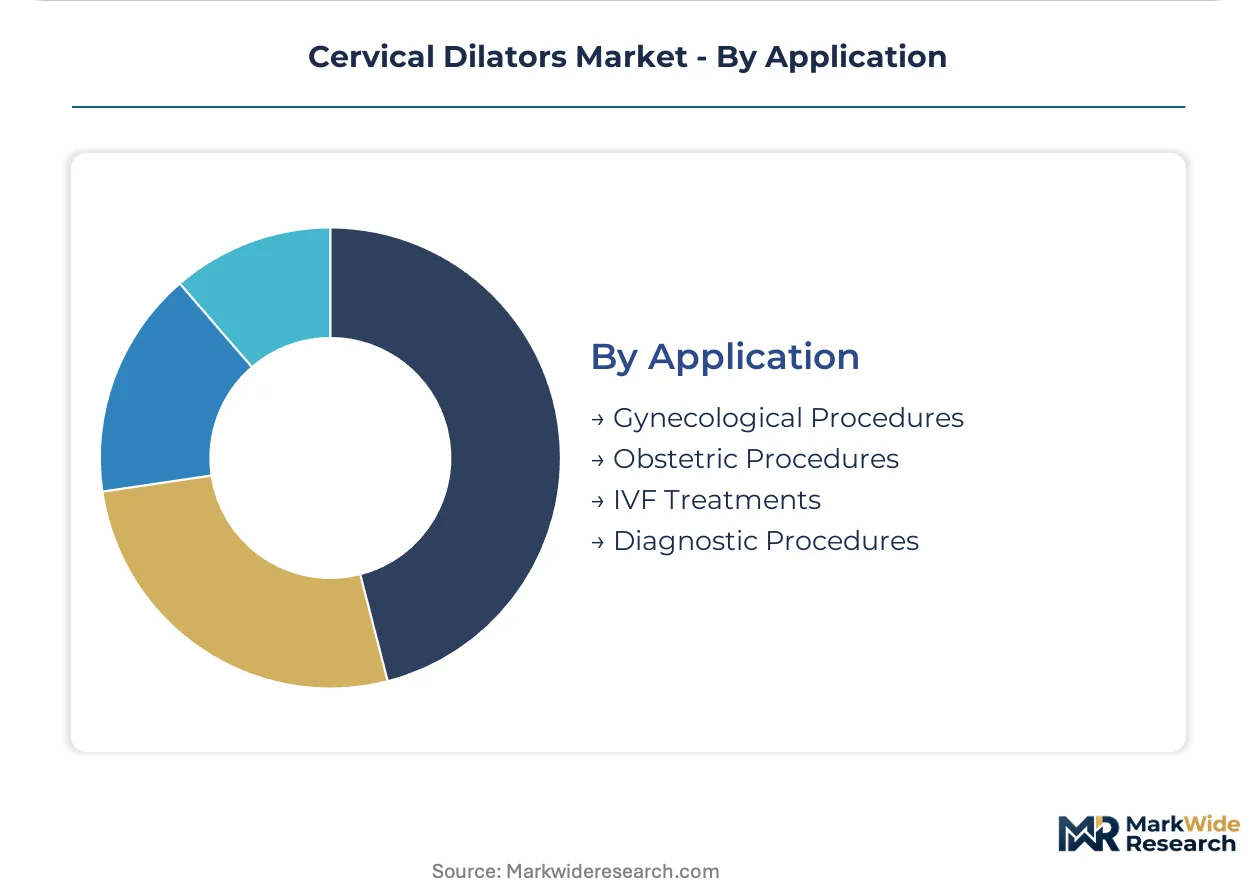
Application:
Procedure urgency and reimbursement structures determine whether mechanical immediacy or controlled expansion takes priority.
- Obstetric Procedures:Labor induction and emergency cervical preparation demand rapid, reliable dilation. Mechanical formats retain protocol standard in United States hospital systems where physician control outweighs material considerations. Sterilization infrastructure legacy creates resistance to full hydrophilic conversion.
- IVF Treatments:Elective embryo transfer procedures prioritize cervical trauma minimization. Fertility centers in Germany and Spain are standardizing balloon dilator protocols. Hydrophilic alternatives are gaining traction for their single-use convenience and elimination of cross-contamination risk.
- Gynecological Procedures:Diagnostic and operative access requirements vary by surgical complexity.
- Diagnostic Procedures:Hysteroscopy and biopsy access favor formats with minimal cervical disruption.
Urgency requirements favor obstetric applications; margin expansion favors IVF treatments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers in the United States and fertility clinic operators in Germany drive divergent demand patterns. Material compliance requirements under FDA and EU MDR reshape manufacturing footprints. Regional clusters concentrate around regulatory expertise and sterilization infrastructure legacy.
United States
Integrated delivery networks in Texas and Florida consolidate gynecological supply contracts under centralized procurement officers. FDA 510(k) clearance pathways for silicone-based dilators streamline iterative product improvements. Boston's medical device corridor hosts quality management specialists supporting ISO 13485 certification maintenance.
Germany
Specialized reproductive clinics standardize balloon dilator protocols for embryo transfer procedures. EU MDR Class IIa device requirements compress manufacturer margins while extending certification timelines. The Rhine-Ruhr industrial zone maintains sterilization equipment manufacturing clusters serving hospital autoclave networks.
Japan
Fertility centers in Tokyo and Osaka pilot pressure-regulated dilation systems for elective IVF procedures. PMDA maintains distinct material standards for obstetric devices that limit direct product portability from Western markets. The Kansai region concentrates polymer formulation expertise for hydrophilic coating development.
Spain
Ambulatory surgical centers in Madrid and Barcelona convert to hydrophilic formats for same-day discharge protocols. EU MDR technical documentation requirements force manufacturers to rebuild clinical evidence portfolios for legacy products. Catalonia hosts notified body consulting specialists navigating MDR implementation bottlenecks.
Netherlands
Fertility networks in Amsterdam and Rotterdam pilot silicone-hydrogel composite dilators combining physician control with pressure-limited expansion. REACH compliance requirements influence polymer selection for single-use disposable formats. The Eindhoven region anchors medical technology R&D clusters focused on hydration-activated devices.
Cervical Dilators Market Vendor Landscape
Player mix skews toward vertically integrated medical device conglomerates with established regulatory affairs functions. Tiered competitive structure separates quality-certified multinational suppliers from regional fabricators lacking MDR dossier capacity. Strategic archetypes include sterilization infrastructure owners, hydrophilic polymer specialists, and fertility-focused distributors. Dominant competitive moves center on ISO 13485 certification arbitrage and direct-to-clinic distribution model deployment.
Within the multinational tier, CooperSurgical Inc., Cook Medical, and Medtronic occupy positions exemplifying divergent competitive vectors. CooperSurgical represents the vertically integrated archetype with captive production networks sustaining hospital system supply consistency. Cook Medical anchors the polymer specialization vector through hydrophilic formulation expertise. Medtronic exemplifies distribution channel control reaching ambulatory surgical centers with same-day procedure protocols. These three entities collectively illustrate how regulatory compliance capacity, material science depth, and route-to-market configuration determine competitive positioning under FDA and EU MDR compression.
| Leading Market Players |
|---|
| CooperSurgical Inc. |
| MedGyn Products Inc. |
| Cook Medical |
| Hologic Inc. |
| Boston Scientific Corporation |
| Medtronic |
| Teleflex Incorporated |
| Medline Industries LP |
| Sklar Surgical Instruments |
| Others |
Supply Flow & Price Mechanics
Silicone-hydrogel composite formulations displacing traditional laminaria are redrawing procurement economics while concentrating polymer sourcing in Northeast Asian chemical manufacturing zones. Hospital systems negotiating volume-tiered agreements directly with manufacturers capture cost advantages that independent ambulatory centers cannot match.
Pricing Analysis
Cost-plus contracts indexed to medical-grade silicone spot prices dominate procurement between hospital integrated delivery networks and tier-one manufacturers. Three-tier pricing structure across premium ISO 13485-certified, standard FDA-cleared, and economy non-certified levels reflects quality differentiation and regulatory burden. Pricing pressure stems from EU MDR recertification costs compressing margins for legacy laminaria suppliers. Fertility centers demonstrate lowest price sensitivity due to procedure reimbursement rates, while independent clinics face acute cost compression.
Supply Chain Analysis
Shanghai port congestion and Taiwan Strait transit vulnerabilities expose medical-grade silicone feedstock flows to logistics disruption. Raw material sourcing centers on China, Japan, and South Korea for polymer precursors, with Germany and the United States contributing specialized hydrophilic coating chemistries. Single-source dependency for laminaria alternatives creates vulnerability as FDA scrutiny redirects formulation investment. Distribution runs through manufacturer-direct contracts with hospital procurement officers, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cervical dilator market fragmentation creates acquisition opportunities as EU MDR compliance costs separate quality-certified multinationals from regional fabricators lacking dossier capacity. Outpatient migration toward single-use hydrophilic formats generates niche openings for specialized polymer suppliers.
For Market Incumbents: Shield market position through captive silicone-hydrogel production capacity and ISO 13485 certification maintenance. Acquire regional Asian manufacturers with quality management gaps to secure manufacturing footprint. Prioritize direct-to-clinic distribution partnerships with high-volume fertility networks in Germany and Spain to lock in balloon dilator procurement. For New Entrants and Emerging Players: Differentiate on PMDA-compliant material portfolios targeting Japan's distinct obstetric device standards. Penetrate Netherlands and Belgium fertility centers piloting hybrid silicone-hydrogel formats. Deploy telemedicine-integrated replenishment models bypassing traditional distributor markups. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap polymer specialists with hydrophilic coating expertise and dormant regulatory affairs capacity. Five-to-ten year viability favors manufacturers with backward integration into medical-grade silicone supply. Monitor notified body backlog resolution as inflection signal for MDR recertification timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acquisition | Quality management gaps among regional Asian manufacturers create arbitrage targets for Western consolidators. |
| Silicone-Hydrogel R&D Investment | Hybrid formats decompose mechanical-balloon procurement categories in Netherlands fertility networks. |
| PMDA Biocompatibility Testing | Japan's distinct material standards reward first-movers investing in localized compliance infrastructure. |
| Direct-to-Clinic Distribution | Telemedicine-integrated replenishment bypasses distributor markups for high-volume fertility centers. |
| EU MDR Dossier Outsourcing | Specialized CRO partnerships address 40% application backlogs reported by German notified bodies. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, and hospital GPO contract databases. Interviews with biomedical engineers, hospital procurement committee members, fertility clinic operators, and regulatory affairs specialists informed demand-side validation. Bottom-up procedure volume estimates triangulated with top-down manufacturer shipment data across mechanical, balloon, and hydrophilic product categories.
Segmentation dimensions modeled include product format, end-user facility type, material composition, and application procedure. CAGRs derive from trend extrapolation of procedural volumes, reimbursement trajectory, and regulatory compliance cost pass-through across the projection horizon. Forecast inputs incorporate fertility center expansion rates in Germany and Spain, plus ambulatory surgical center conversion timelines to single-use formats.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR Class IIa device requirements; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as notified body capacity constraints and PMDA material standard evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Supraglottic Device Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Active Wheelchair Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Global Microscopy Device Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
Wrist Fixator Procedure Kit Market
Medical Devices
Telehealth Device Market
Medical Devices
Global Keratometers Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Posture Correction Market
Medical Devices
Asia Pacific Veterinary Equipment and Disposables Market