
 Digital Mobile Radio (DMR) Market | 2026-2036
Digital Mobile Radio (DMR) Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Mobile Radio (DMR) Market Intelligence
The integration of data applications directly onto DMR devices is narrowing the gap between professional mobile radio and commercial cellular networks. Motorola Solutions, Inc. leverages its extensive public safety portfolio to lead in this integrated space. Hytera Communications Corporation Limited competes with a focus on open-standard solutions, while JVCKENWOOD Corporation differentiates through its expertise in audio quality and device durability.
Digital Mobile Radio is a two-way radio standard defined by the European Telecommunications Standards Institute (ETSI). It operates within existing licensed frequency bands and utilizes Time Division Multiple Access (TDMA) to provide two voice or data paths on a single 12.5 kHz channel. Portable radios continue to dominate sales volume, especially for public safety and event management applications. However, repeaters and base stations represent a significant value segment, critical for building out network coverage for utilities management and transportation clients.
Spectrum allocation and equipment certification are governed by national bodies like the US Federal Communications Commission (FCC) and China's Ministry of Industry and Information Technology (MIIT). The ETSI standard itself provides the foundational technical specifications, ensuring interoperability and defining performance benchmarks that guide manufacturers. The key decision for network operators now revolves around balancing investment in pure DMR infrastructure versus hybrid systems that bridge to broadband LTE and 5G.
Market Dynamics
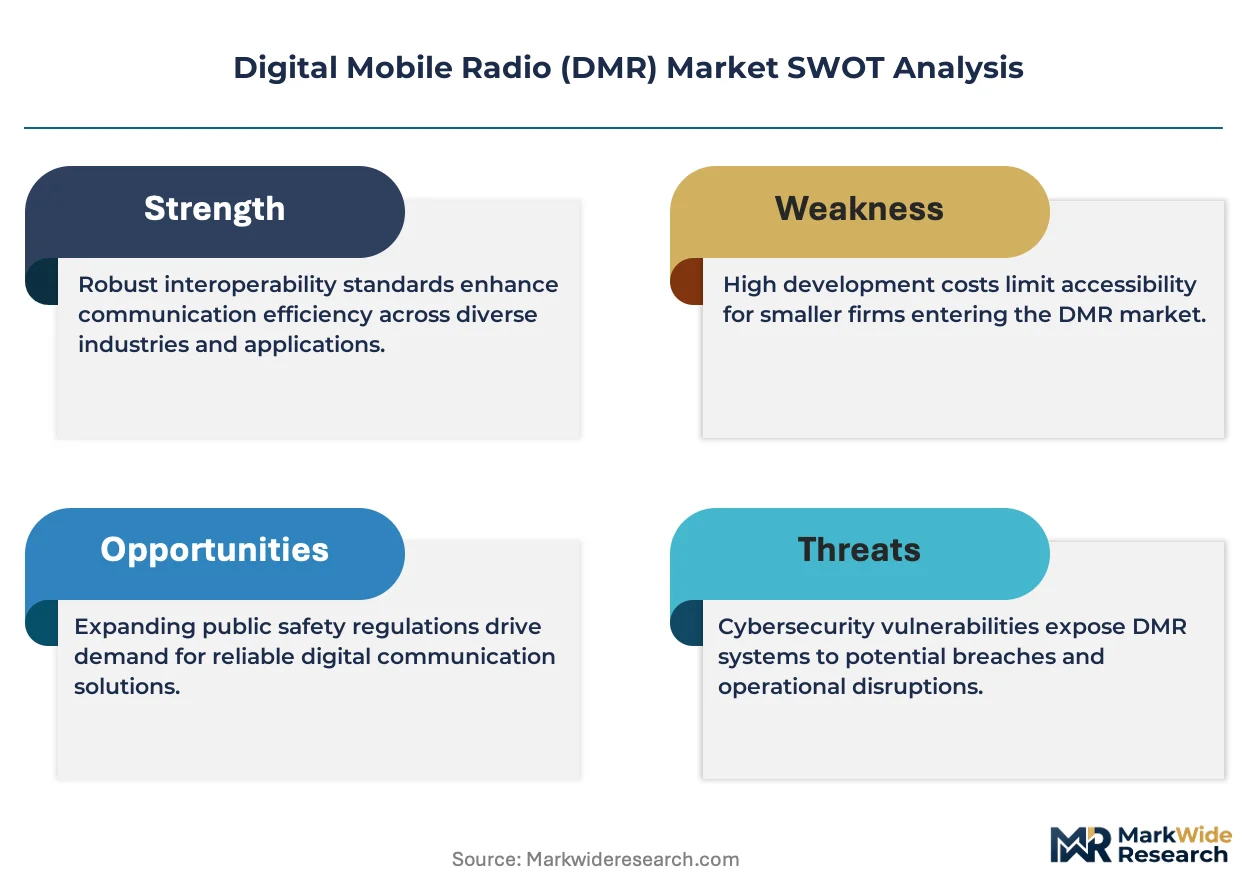
The structural transition from analog to digital two-way radio systems, accelerated by public safety modernization programs, defines the market. This shift is driven by the need for enhanced data capabilities and superior voice clarity under ETSI standards.
Growth Catalysts
- Public Safety Mandates:Government directives for interoperable first responder networks, especially in the US, compel the replacement of analog systems, creating steady demand.
- Spectrum Efficiency:DMR's TDMA technology doubles channel capacity on a single frequency, a key advantage for operators in congested urban radio environments.
- Industrial Data Integration:The need for combined voice and data for telemetry in utilities and transportation expands the market beyond its public safety origins.
Market Restraints
- High Initial Capex:The upfront investment for DMR hardware is substantially higher than for analog systems, posing a budget barrier for smaller commercial users.
- Substitution from Cellular:Push-to-Talk over Cellular (PoC) provides a low-cost alternative for non-mission-critical users, eroding the low-end commercial segment.
- Vendor Interoperability Gaps:Despite the ETSI standard, proprietary features can create interoperability issues, risking vendor lock-in for network operators.
Strategic Opportunities
- Emerging Market Infrastructure:Utility and transport projects in Southeast Asia and Latin America create greenfield opportunities for large-scale DMR network deployments.
- Hybrid DMR-LTE Convergence:Developing hybrid devices that switch between narrowband DMR for critical voice and broadband LTE for data meets a core demand for versatile communications.
- Software-Enabled Data Services:Offering data services like indoor location tracking and telemetry over DMR networks creates new software-based revenue streams for vendors.
Industry Challenges
- Legacy System Integration:Ensuring seamless interoperability and a phased migration path between new DMR networks and existing analog systems is a complex technical challenge for operators.
- Spectrum Licensing Complexity:Securing licensed spectrum is a lengthy process governed by national regulators like the FCC and MIIT, which can delay network rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Mobile Radio (DMR) Market |
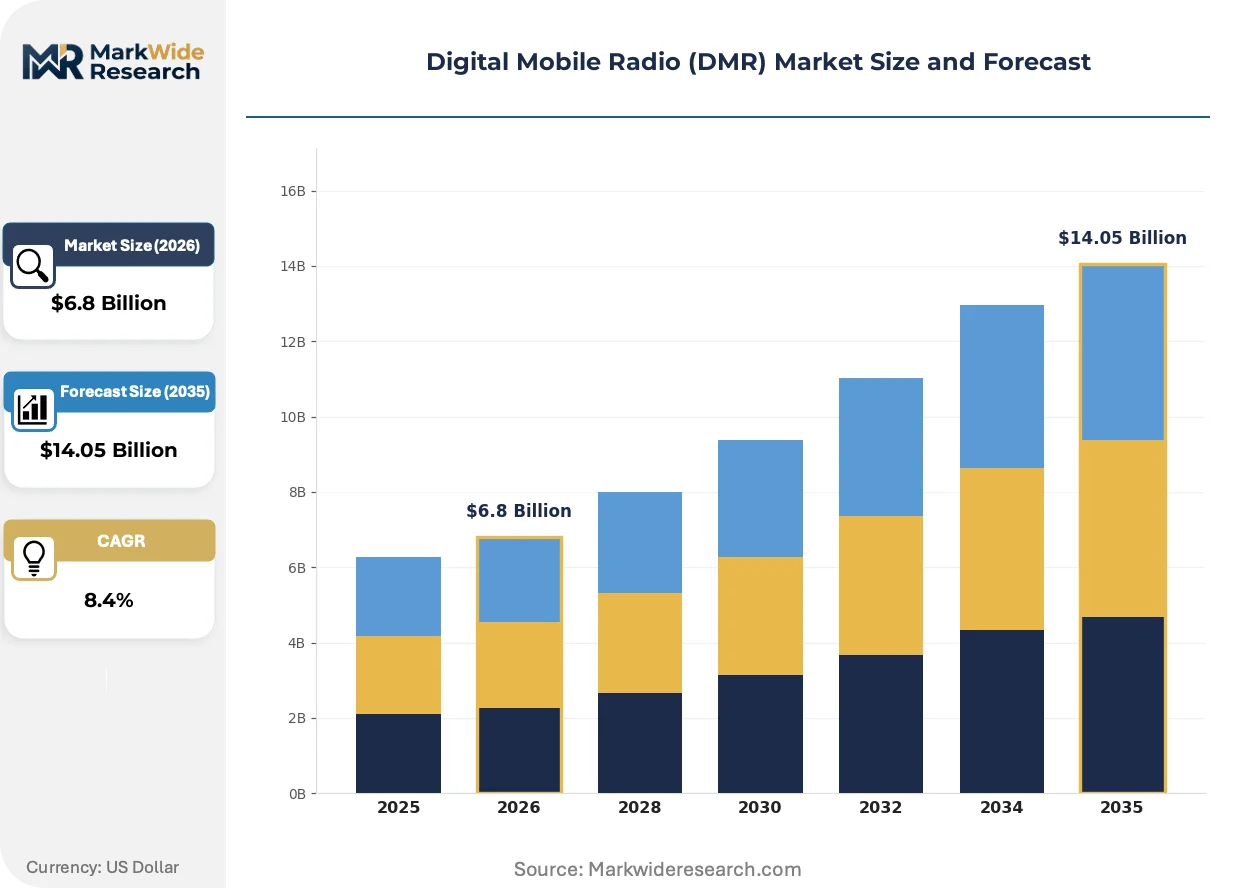
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Radios, Mobile Radios, Repeaters, Base Stations, Data Modules Technology: Frequency Division Multiple Access, Time Division Multiple Access, Analog Selective Calling, Digital Voice Coding Application: Public Safety, Transportation, Utilities Management, Oilfield Operations, Event Management End User: Emergency Services, Logistic Operators, Power Providers, Exploration Companies, Security Agencies |
| Companies Covered | JVCKENWOOD Corporation, Icom Inc., Motorola Solutions, Inc., BK Technologies, Thales, Hytera Communications Corporation Limited, Sepura Limited, Anytone, L3Harris Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Mobile Radio (DMR) Market Strategic Shifts & Innovations
DMR's evolution is defined by its deepening integration with data applications and enterprise IT systems. This movement transforms the two-way radio from a simple voice tool into a node within a broader operational data network.
On-device data applications provide functionalities like text messaging, GPS location, and telemetry directly on the radio handset. Public safety and logistics organizations are the primary adopters, seeking to improve situational awareness and operational efficiency. The market is migrating from a voice-centric model to one where the radio serves as a ruggedized data endpoint.
The European Telecommunications Standards Institute (ETSI) continues to evolve the DMR standard, focusing on enhanced security and data features. This standardization facilitates interoperability, a key requirement for multi-agency public safety networks. Consequently, equipment manufacturers are focusing on certifying devices to the latest Tier III trunking specifications to ensure compliance and market access.
A clear shift in purchasing criteria favors hybrid communication solutions over single-technology systems. Buyers, especially in transportation and utilities, now seek devices that combine reliable DMR voice with broadband data access via LTE or Wi-Fi. This demand is most visible in North America and Europe, where agencies are upgrading infrastructure.
Digital Mobile Radio (DMR) Market Segmentation
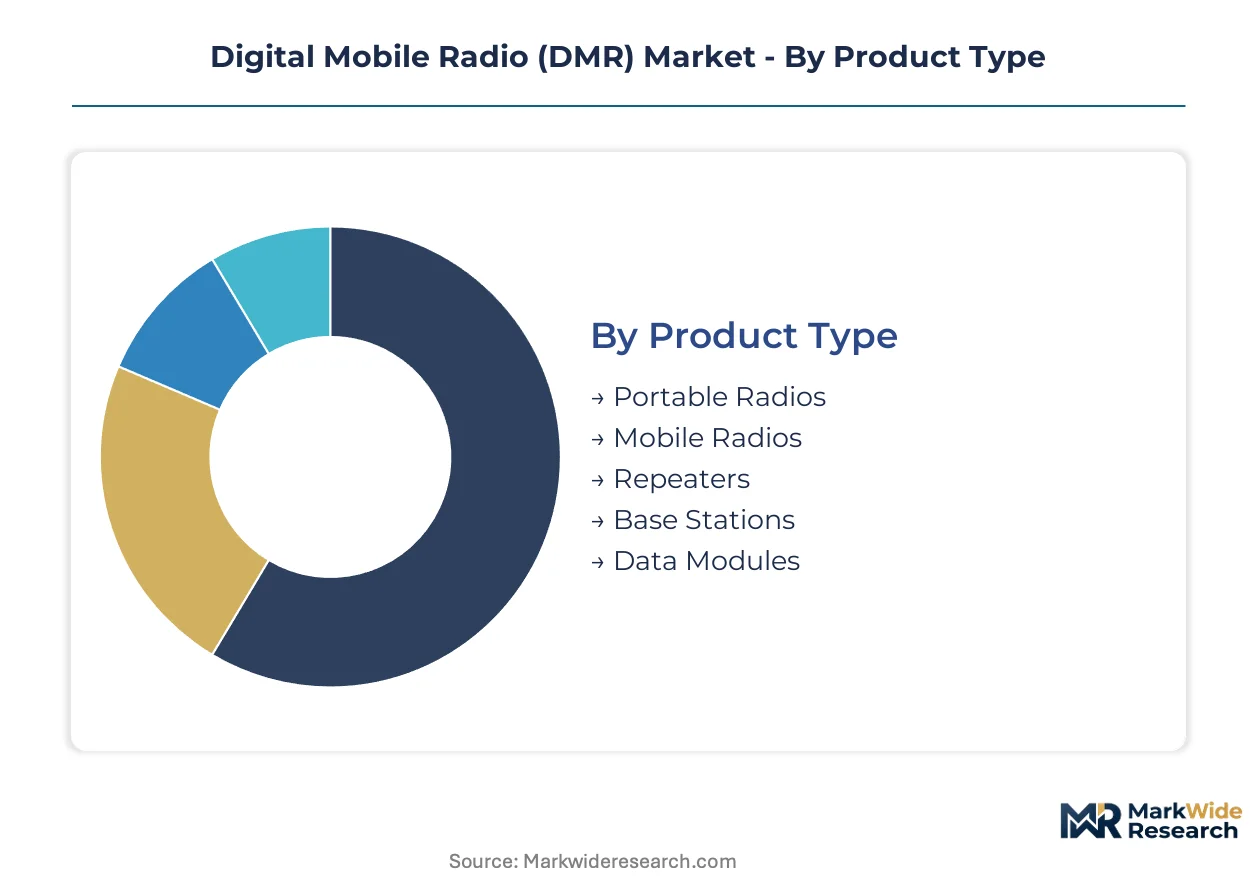
The Digital Mobile Radio market's segmentation offers a detailed view of the diverse product offerings, underlying technologies, critical applications, and specific end-user groups driving demand. Understanding these segments is crucial for identifying market concentration points and areas of technological advancement within the communications industry.
Product Type:
The Digital Mobile Radio market's product segmentation reflects a mix of well-established hardware and emerging data-centric modules, addressing a broad spectrum of user requirements.
- Portable Radios:These handheld, battery-powered devices offer mobility and on-site communication capabilities. Demand concentrates heavily within public safety and event management applications, driven by the need for immediate, reliable, and secure voice communication in dynamic environments.
- Repeaters:Designed to extend the coverage and improve the signal quality of DMR networks, repeaters are critical infrastructure components. Their deployment is significant for utilities management and transportation clients, enabling expansive network coverage for remote operations and large facilities.
- Mobile Radios:These units are typically vehicle-mounted, providing robust communication solutions for mobile workforces.
- Base Stations:Fixed infrastructure components, base stations form the backbone of DMR networks, managing channels and connecting various radio terminals.
- Data Modules:Integrated components that enable data applications like GPS tracking and telemetry directly on DMR devices, enhancing operational intelligence.
Portable Radios retains volume leadership; Data Modules holds the steepest expansion curve.
Technology:
Technological segmentation highlights the core innovations enabling DMR's efficiency and advanced features across various operational environments.
- Time Division Multiple Access:This technology provides two independent voice or data paths on a single 12.5 kHz channel, maximizing spectrum utilization. Its efficiency is highly valued in congested urban radio environments, allowing more users to communicate simultaneously.
- Digital Voice Coding:This process converts analog voice signals into digital data, enabling superior voice clarity and noise reduction, especially in challenging acoustic conditions. Public safety and industrial users prioritize this technology for clear, intelligible communication during critical operations.
- Frequency Division Multiple Access:This method divides a radio channel into multiple distinct frequency bands, allowing simultaneous but separate transmissions.
- Analog Selective Calling:An older signaling technique used in analog radio systems to alert specific radios or groups to an incoming call.
Time Division Multiple Access remains central to DMR's core efficiency; Digital Voice Coding is expanding most quickly for enhanced audio performance.
Application:
Application segmentation reveals the diverse operational contexts where DMR systems provide critical communication solutions for specific user groups.
- Public Safety:This segment encompasses critical voice and data communication for first responders, police, and fire services. Demand is strong in the United States and European emergency services, driven by government mandates for interoperable and reliable communication networks.
- Utilities Management:DMR systems support telemetry, SCADA, and voice communication for monitoring and managing critical infrastructure like power grids and water systems. Power providers globally utilize DMR for remote asset control and ensuring worker safety in distributed operations.
- Transportation:This application supports communication for railways, ports, and logistics operators, facilitating efficient fleet management and coordination.
- Oilfield Operations:DMR provides robust and reliable communication in challenging and often remote industrial environments within the energy sector.
- Event Management:Facilitates seamless coordination and security for large-scale public gatherings, concerts, and sporting events.
Public Safety applications drive significant market volume; Utilities Management demonstrates strong growth in industrial deployments.
End User:
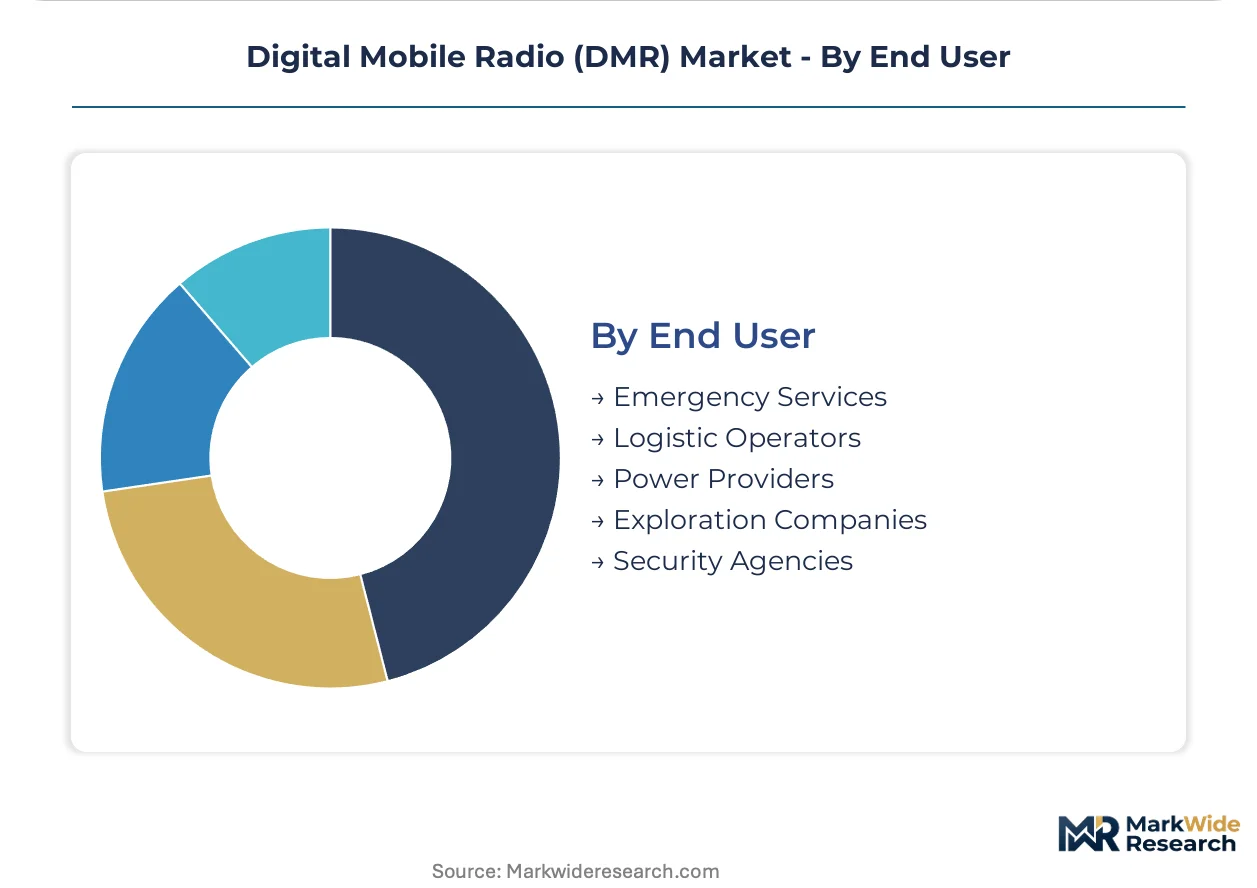
End user segmentation categorizes the primary beneficiaries of DMR technology, reflecting varied investment capacities and critical communication needs.
- Emergency Services:This group includes police, fire departments, and ambulance services, relying on DMR for mission-critical voice and data communication. Government agencies worldwide are the primary customers, prioritizing reliability and security for first responders.
- Logistic Operators:Encompassing fleet management, warehousing, and delivery services, this segment uses DMR for real-time coordination and operational efficiency. Transportation hubs and large distribution centers are key adopters, seeking streamlined communication across their operations.
- Power Providers:These entities utilize DMR for maintaining grid stability and coordinating field personnel during maintenance and outages.
- Exploration Companies:Businesses involved in mining, oil, and gas exploration deploy DMR for communication in remote and hazardous work sites.
- Security Agencies:These organizations leverage DMR for secure and private communication channels during surveillance and enforcement activities.
Emergency Services represent the largest segment by expenditure; Exploration Companies are increasingly adopting DMR for remote site connectivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public safety agencies globally represent a significant concentration of DMR market demand. These organizations require reliable and secure communication networks for critical operations. Industrial users, particularly in utilities and transportation, also drive substantial investment.
United States
Public safety mandates for interoperable first responder networks drive demand in the United States. The US Federal Communications Commission (FCC) guides spectrum allocation and equipment certification for radio systems. Major metropolitan areas like New York and Los Angeles are upgrading their emergency communication infrastructure to digital standards.
Germany
Industrial data integration and enhanced voice clarity are key demand drivers for utilities and transport in Germany. ETSI standards, developed in Europe, ensure interoperability and performance benchmarks for DMR systems. The industrial heartland in Bavaria and North Rhine-Westphalia sees significant adoption for transport and manufacturing communication.
China
Public safety modernization programs accelerate the transition from analog to digital two-way radio systems across China. China's Ministry of Industry and Information Technology (MIIT) governs spectrum allocation and equipment certification. Manufacturing hubs in the Pearl River Delta and Yangtze River Delta utilize DMR for operational coordination and efficiency.
India
Emerging market infrastructure projects in utilities and transportation create greenfield opportunities for large-scale DMR network deployments in India. The country's national telecommunications regulator oversees spectrum licensing for these critical communication systems. Major cities like Mumbai and Delhi are seeing increased investment in smart city and public safety communication upgrades.
Brazil
Utilities management and transportation clients seek expansive network coverage for remote operations across Brazil. The national telecommunications agency ensures adherence to communication standards for critical infrastructure. Industrial zones around São Paulo and Minas Gerais are adopting DMR for efficient resource management and worker safety.
Digital Mobile Radio (DMR) Market Key Industry Players
Channel-controlling players compete with product-specialist players across the Digital Mobile Radio market. The market exhibits a tiered structure, with established manufacturers offering comprehensive solutions alongside niche providers focusing on specific components or data applications. Strategic archetypes include integrated system providers, hardware specialists, and software-enabled service innovators. Portfolio diversification and strategic partnerships are dominant competitive moves among these entities, aiming to capture new revenue streams.
On the integrated system provider vector, Motorola Solutions, Inc. exemplifies a comprehensive approach, leveraging its extensive public safety portfolio and broad market presence. Hytera Communications Corporation Limited, a Chinese-based entity, occupies a position focused on open-standard solutions and a wide range of offerings, catering to diverse commercial and governmental clients. JVCKENWOOD Corporation, a Japan-based manufacturer, represents an archetype emphasizing audio quality and device durability, particularly for professional and event management applications. These companies collectively anchor significant portions of the market's value proposition through their distinct strategic focuses.
| Leading Market Players |
|---|
| JVCKENWOOD Corporation |
| Icom Inc. |
| Motorola Solutions, Inc. |
| BK Technologies |
| Thales |
| Hytera Communications Corporation Limited |
| Sepura Limited |
| Anytone |
| L3Harris Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
Component supply chain concentration in East Asia determines both pricing tier spreads and the overall supply chain shape within the Digital Mobile Radio market. This dependency influences the cost structures for various product types, from portable radios to complex base stations.
Pricing Analysis
Cost-plus contracts for DMR infrastructure often integrate material cost indexation, reflecting semiconductor and specialized component price fluctuations. Pricing models for portable radios are typically per-unit transactional, while large network deployments are project-based. Price differentiation stems from ETSI Tier III certification levels, ensuring advanced features and interoperability, and established brand premiums from companies like Motorola Solutions. Pricing pressure originates from the substitution threat posed by Push-to-Talk over Cellular (PoC) alternatives, particularly in the commercial segment. Smaller commercial users exhibit the highest price sensitivity, whereas public safety agencies prioritize reliability and security over initial capital expenditure.
Supply Chain Analysis
Contract manufacturing concentration among key electronics manufacturing service (EMS) providers in Asia, particularly China and Taiwan, underpins DMR device production. Geographic supply for critical components like specialized RF modules and semiconductors primarily originates from East Asia. Raw material dependencies include advanced chipsets, battery cells, and robust casing materials. Single-source vulnerability for specific proprietary components represents a structural supply chain risk for some manufacturers. Downstream distribution runs through direct sales channels for large public safety and utility projects, complemented by a network of authorized dealers and value-added resellers for commercial portable radio sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Digital Mobile Radio market is undergoing a high-growth disruption, driven by the regulatory inflection towards digital communication standards for public safety. This transition creates both significant opportunities and strategic imperatives for market participants.
For Market Incumbents: Build network effects moats by expanding integrated solutions that combine DMR with broadband data capabilities. This strategy counters the threat of cellular substitution by offering a hybrid communication ecosystem. Invest in R&D for advanced security features and software-defined radio functionalities, leveraging existing public safety relationships and channel control to maintain market leadership.
For New Entrants and Emerging Players: Build out specialized software services that enhance the utility of existing DMR networks, focusing on data applications like indoor location tracking and telemetry. Target underpenetrated industrial data integration segments within utilities and transportation, where the need for combined voice and data is critical. A viable go-to-market angle involves strategic partnerships with enterprise IT integrators to embed DMR data into broader operational systems.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors integrated solution providers capable of bridging narrowband DMR with broadband LTE/5G. Long-term viability for DMR is strong in mission-critical applications where cellular networks lack resilience or dedicated spectrum. Acquisition targets should be archetype companies with strong intellectual property in hybrid communication technologies or specialized data application development. A key signal to watch is the pace of ETSI standard evolution for enhanced data and security features.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Hybrid DMR-LTE Devices | This initiative meets demand for versatile communication, combining critical voice with broadband data access. |
| Expand Software-Enabled Data Services | Offering new software-based revenue streams enhances operational intelligence for end-users. |
| Invest in ETSI Tier III Certification | Ensuring compliance with advanced trunking specifications unlocks market access and interoperability. |
| Target Emerging Market Infrastructure Projects | This strategy captures greenfield opportunities for large-scale network deployments in utilities and transport. |
| Form Strategic Partnerships with IT Integrators | This move embeds DMR data into broader enterprise operational systems, expanding market reach. |
Research Approach
The analysis maps Digital Mobile Radio sub-sectors, including portable radios, repeaters, and data modules, each validated through extensive primary interviews with public safety officials, utility operations managers, and transportation logistics leads. This primary research is complemented by secondary validation from ETSI specifications, US Federal Communications Commission (FCC) filings, and national telecommunications regulatory reports. A robust bottom-up and top-down triangulation approach ensures data consistency and accuracy across all market segments.
The forecast framework held fixed macroeconomic conditions and regulatory environments, while varying technological adoption rates and shifts in end-user preferences across the modeling period. Segmentation dimensions modeled include product type, underlying technology, application, end-user group, and regional adoption patterns. Compound annual growth rates were derived from historical data trends and projected shifts in demand, with key forecast inputs including public safety budget allocations and industrial infrastructure investment cycles.
Stress conditions across spectrum availability and cellular convergence rates were modeled; outcomes outside those bands fall beyond the analytical envelope of this study. Forecasts reflect assumptions regarding technological advancements and market dynamics. Quarterly review of public safety budget allocations and cellular network expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G Monetization Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
Myanmar ICT Market
Telecommunications
Egypt ICT Market
Telecommunications
Singapore Telecom Market
Telecommunications
5G in Defense Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
Ghana Telecom Market
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
Spain ICT Market
Telecommunications
DWDM System Market
Telecommunications
Russia ICT Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Virtual CPE (Vcpe) Market