

LTE and 5G NR-Based CBRS Networks Market Size, Share, and Industry Trends Forecast 2026-2036
LTE and 5G NR-Based CBRS Networks Market Insights
Private network licensing revenue is rewriting how infrastructure vendors capture value in spectrum-constrained environments. Samsung Networks leverages its end-to-end portfolio to anchor large enterprise deployments across industrial campuses. Ericsson competes through R&D intensity in 5G NR software stacks, while Federated Wireless specializes in spectrum access system coordination for priority users.
LTE and 5G NR-Based CBRS Networks employ shared 3.5 GHz spectrum with automated environmental sensing capability and three-tier access priority to deliver localized broadband without exclusive spectrum ownership. The architecture integrates LTE baseline coverage with 5G NR capacity layers, enabling sub-10 millisecond latency for industrial automation and real-time video analytics. Private network deployments lead the deployment model segment, as mining operators and manufacturing plants seek deterministic connectivity beyond macro network reach. Neutral host configurations represent the fastest-growing structural category, driven by stadiums, airports, and hospitality venues requiring multi-tenant infrastructure. Edge computing services within the service offering segment concentrate margin pools where low-latency processing aligns with factory floor applications.
The FCC's Citizens Broadband Radio Service rules and SAS administrator certification requirements shape equipment interoperability and market access conditions in the United States. The EPA's environmental review for coastal radar protection and the NTIA's spectrum coordination mandates further constrain deployment parameters in specific geographic zones. Stakeholders must monitor pending rulemakings on expanded 3.45 GHz access and international harmonization pressures that could recalibrate equipment investment timelines.
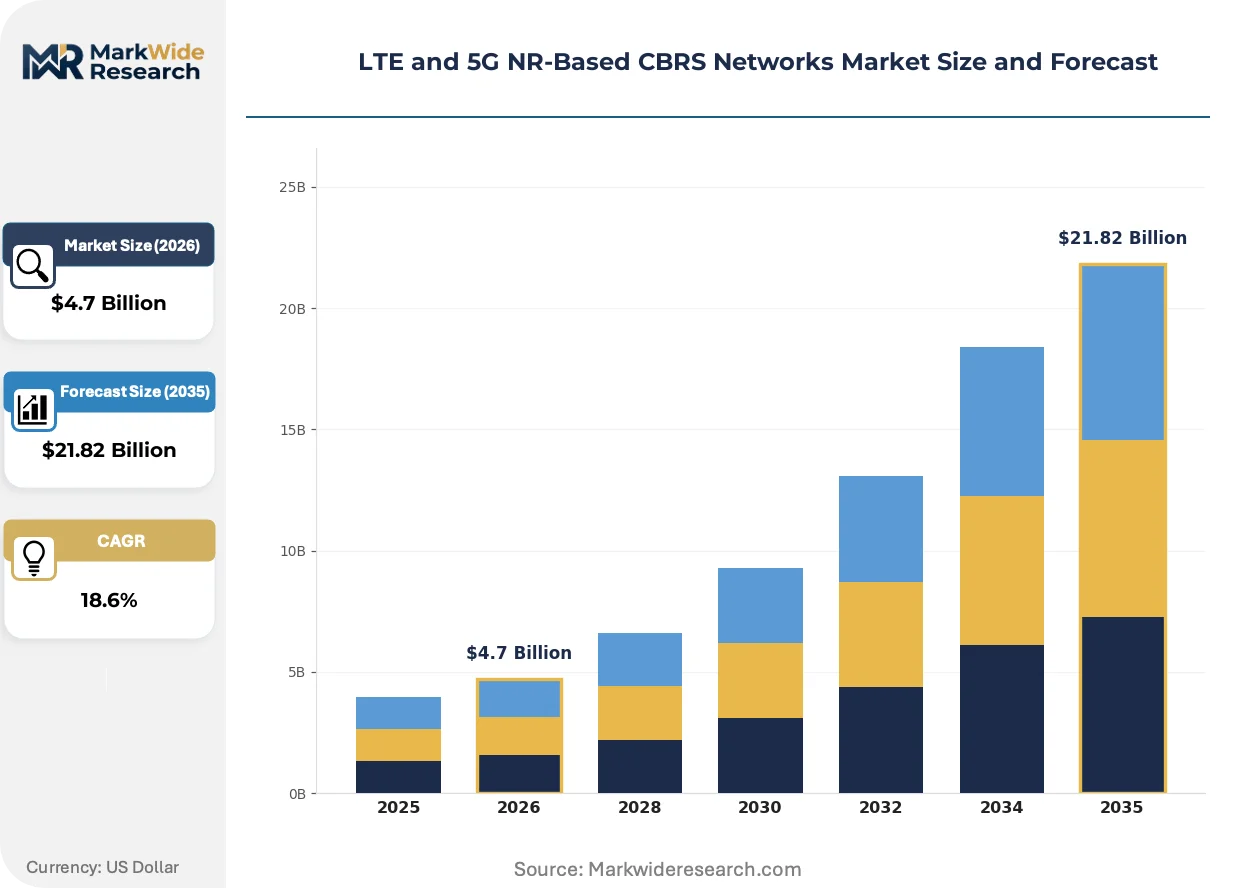
Market Dynamics
The FCC's three-tier spectrum access framework is compressing deployment timelines for private cellular networks while fragmenting infrastructure procurement across enterprise IT and operational technology buyers.
Growth Catalysts
- Industrial automation demand:Manufacturing plants in the United States are deploying private 5G networks to support sub-10 millisecond latency requirements for robotic control systems and real-time quality inspection.
- Priority Access License framework:The FCC's PAL auction structure creates predictable spectrum rights for enterprises seeking interference-protected bandwidth in the 3.5 GHz band.
- Spectrum Access System maturation:Certified SAS administrators are reducing incumbent protection complexity, enabling faster site activation and dynamic channel assignment for General Authorized Access users.
Market Restraints
- Radio unit cost concentration:Macro base station suppliers command premium pricing for 5G NR massive MIMO arrays, inflating total cost of ownership for mid-sized private deployments.
- Incumbent radar interference zones:Naval radar operations along the Atlantic and Gulf coasts impose exclusion zones that block CBRS deployment in major port cities.
- Optical transport dependency:Fronthaul fiber connectivity requirements limit network reach in rural industrial sites lacking dense fiber infrastructure.
Strategic Opportunities
- Neutral host stadium infrastructure:Multi-tenant CBRS deployments in sports venues and convention centers are capturing mobile operator offload traffic while serving private enterprise tenants.
- Edge computing convergence:Integration of 5G core user plane functions with on-premises GPU clusters is creating localized inference pipelines for computer vision applications.
- Expanded 3.45 GHz harmonization:Pending FCC rulemakings on additional mid-band spectrum could extend equipment investment lifecycles and double channel bandwidth for capacity-heavy sites.
Industry Challenges
- RF planning expertise scarcity:Enterprise IT departments lack in-house propagation modeling capabilities for complex industrial environments with metallic interference.
- Multi-vendor integration complexity:Disaggregated RAN architectures require specialized systems integrators to harmonize radio units, distributed units, and core network functions from different suppliers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LTE and 5G NR-Based CBRS Networks Market Trends and Innovations
Open RAN disaggregation is fragmenting vendor lock-in patterns while accelerating software-defined feature deployment cycles across private cellular infrastructure.
Cloud-native 5G core architectures are digitizing network function deployment. Mining operators in the Powder River Basin are adopting containerized packet cores to enable rapid site replication across dispersed extraction locations. This shift is compressing traditional hardware refresh cycles and displacing proprietary appliance-based mobile packet core solutions.
The EPA's environmental review coordination with NTIA for coastal radar protection is tightening deployment windows in specific geographic corridors. Industrial applicants in Virginia Beach and San Diego face extended pre-deployment sensing periods. Equipment vendors are responding with enhanced environmental sensing capability algorithms that accelerate incumbent detection and channel availability determination.
Buyer procurement patterns are consolidating around integrated solution contracts rather than component sourcing. Manufacturing plants are awarding single-vendor responsibility for radio access, transport, and edge compute layers to reduce interface risk. This concentration is most pronounced in automotive assembly facilities across Michigan and Tennessee, where deterministic latency requirements dominate vendor selection criteria.
LTE and 5G NR-Based CBRS Networks Market Segmentation
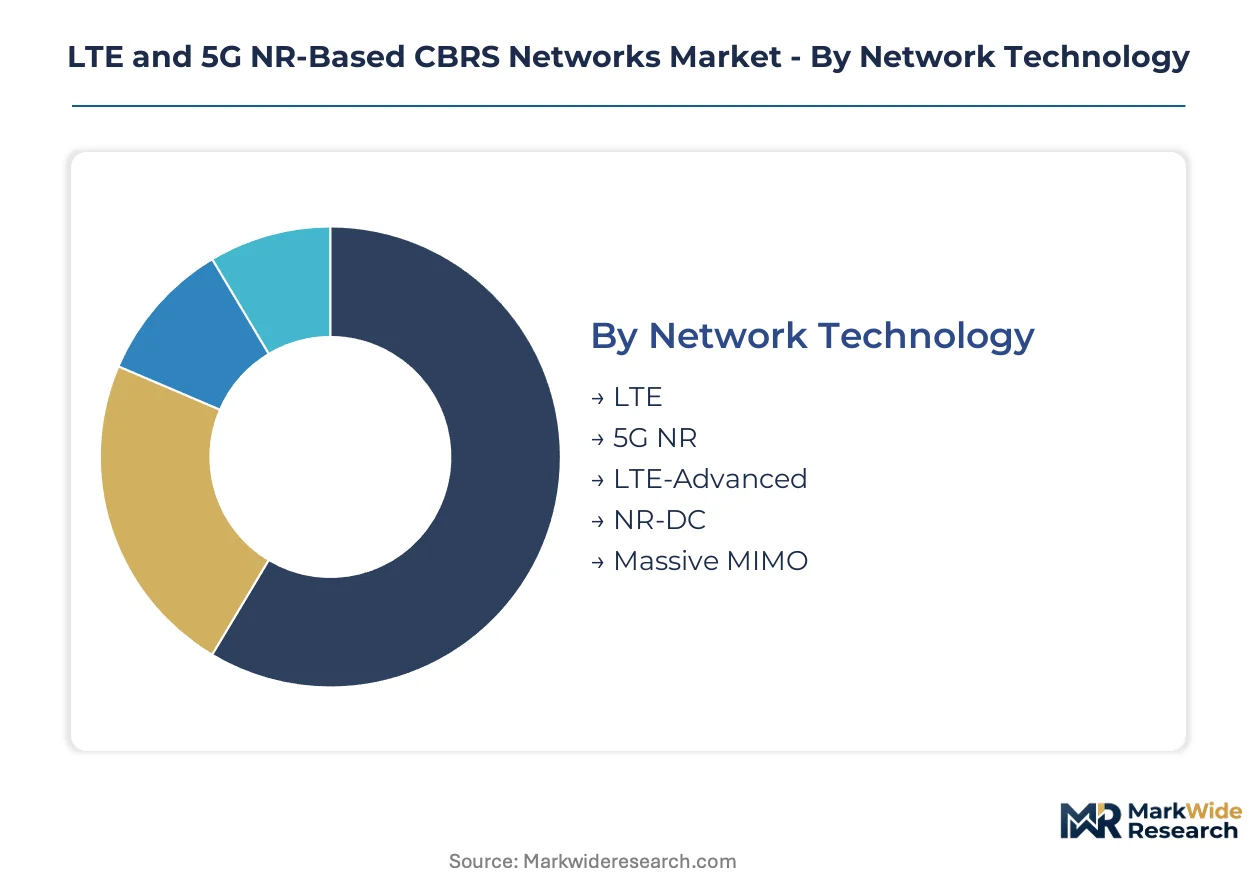
CBRS network segmentation reveals how spectrum access priorities, deployment economics, and vertical-specific latency requirements reshape procurement patterns across industrial and commercial buyers. Technology choices cascade through deployment architecture, end-user operational models, and service packaging decisions.
Network Technology:
Mature LTE baselines coexist with emerging 5G NR capacity layers across the technology spectrum.
- LTE:Proven 3.5 GHz baseline technology delivering reliable broadband coverage with established device ecosystems. Manufacturing plants in Michigan and Tennessee deploy LTE-first architectures for deterministic factory floor connectivity where equipment refresh cycles extend beyond five years.
- 5G NR:Next-generation air interface enabling sub-10 millisecond latency through optimized numerology and flexible subcarrier spacing. Mining operators in the Powder River Basin specify 5G NR for autonomous haul truck coordination where real-time kinematic positioning demands ultra-reliable low-latency communication.
- LTE-Advanced:Carrier aggregation and enhanced MIMO configurations extending LTE lifecycle investments.
- NR-DC:Dual connectivity architectures binding LTE anchor carriers with 5G NR mmWave or mid-band supplementation.
- Massive MIMO:64T64R antenna arrays concentrating beamforming gain for high-density neutral host venues.
5G NR handles the majority of throughput expansion; Massive MIMO is climbing the fastest on share as stadium and airport densities intensify.
Deployment Model:
Cost tier stratification separates capital-intensive private builds from operational-expense-driven neutral host arrangements.
- Private Network:Dedicated infrastructure owned and operated by single enterprises with Priority Access License or General Authorized Access spectrum rights. Automotive assembly facilities across the US Southeast favor private builds to isolate robotic control traffic from macro network congestion.
- Neutral Host:Multi-tenant infrastructure serving multiple mobile operators and enterprise tenants through shared radio access and transport layers. Sports venues in Texas and California capture neutral host economics by aggregating carrier offload with private enterprise demand.
- Public Network:Traditional macro cellular extension into CBRS bands through mobile operator infrastructure.
- Hybrid Network:Architectures blending private radio access with public core network functions.
- Enterprise Network:Managed service constructs where vendors retain ownership and operational responsibility.
Private Network absorbs the largest capital commitment; Neutral Host is expanding most quickly as venue operators monetize infrastructure sharing.
End User Type:
Application-specific latency and reliability requirements concentrate demand across vertically differentiated operational technology buyers.
- Manufacturing Plants:Discrete and process automation facilities requiring deterministic connectivity for robotic control, computer vision quality inspection, and programmable logic controller integration. Tennessee automotive clusters and Michigan industrial corridors anchor this segment's procurement volume.
- Mining Operators:Surface and underground extraction companies deploying private cellular for autonomous equipment, remote operations centers, and worker safety systems. Powder River Basin coal operations and Arizona copper pits drive equipment ruggedization requirements.
- Telecom Operators:Mobile network providers using CBRS for capacity augmentation and fixed wireless access.
- Educational Institutions:University campuses and K-12 districts seeking controlled connectivity for research networks and digital learning infrastructure.
- Hospitality Providers:Resort and hotel operators deploying neutral host or private infrastructure for guest services and back-of-house automation.
Manufacturing Plants command the deepest equipment integration; Mining Operators are gaining share fastest as extraction automation accelerates.
Service Offering:
Margin pool distribution follows the progression from connectivity commodity toward value-added platform services.
- Edge Computing:On-premises GPU clusters and containerized user plane functions enabling localized inference for computer vision and predictive maintenance. Factory floor deployments in Ohio and Illinois combine 5G core distribution with NVIDIA edge stacks for real-time defect detection.
- Network Slicing:Virtualized end-to-end resource isolation enabling differentiated service levels across simultaneous industrial and administrative traffic classes.
- Spectrum Leasing:Priority Access License sub-leasing and dynamic General Authorized Access coordination services.
- Quality of Service:Traffic prioritization and guaranteed bitrate engineering for mission-critical operational technology flows.
- Security Management:Zero-trust architecture implementation and encrypted fronthaul/backhaul protection.
Edge Computing captures the highest margin expansion; Network Slicing shows the steepest trajectory as manufacturing IT-OT convergence deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States buyers absorb premium pricing for deterministic latency, while European and Asian purchasers prioritize cost efficiency in spectrum-constrained deployments.
United States
Automotive assembly plants in Tennessee and Michigan drive private 5G procurement for robotic control systems. The FCC's three-tier spectrum access framework and PAL auction structure anchor regulatory certainty. Virginia Beach and San Diego industrial corridors face extended deployment windows due to naval radar exclusion zones along Atlantic and Gulf coasts.
Germany
Industrial machinery manufacturers in Bavaria and North Rhine-Westphalia pilot CBRS-equivalent localized networks for factory automation. The country's national telecom regulator enforces spectrum coordination mandates aligned with EU-wide harmonization pressures. Stuttgart automotive clusters integrate private cellular with existing industrial Ethernet backbones.
Japan
Precision electronics fabricators in Kanto and Kansai regions demand sub-10 millisecond latency for semiconductor quality inspection. METI promotes local 5G licensing frameworks that mirror CBRS shared-spectrum principles. Nagoya manufacturing corridors deploy hybrid LTE-5G architectures to preserve equipment lifecycle investments.
South Korea
Shipbuilding yards in Busan-Ulsan and steel complexes in Pohang seek deterministic connectivity beyond macro network coverage. The national spectrum authority allocates localized 5G bands for industrial automation. Seoul Capital Area technology parks test edge-compute integration with private cellular cores.
United Kingdom
Logistics hubs in Midlands and North England evaluate neutral host architectures for warehouse automation. Ofcom's shared spectrum framework enables localized licensing without exclusive frequency ownership. London financial services corridors explore private networks for low-latency trading infrastructure.
LTE and 5G NR-Based CBRS Networks Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Infrastructure vendors with end-to-end radio access and core network portfolios command premium positioning in large enterprise deployments. Equipment specialists and spectrum coordination providers occupy adjacent niches. Three archetypes dominate: integrated system houses, radio unit specialists, and software-defined orchestration platforms. Competitive moves center on single-vendor responsibility contracting and Open RAN disaggregation partnerships.
Within the integrated system tier, Samsung Networks and Ericsson exemplify end-to-end portfolio positioning. Federated Wireless occupies a distinct coordination-focused niche. Samsung Networks leverages Korean manufacturing scale. Ericsson's Swedish engineering heritage anchors its R&D intensity reputation. Federated Wireless represents the spectrum access system specialization archetype that reduces incumbent protection complexity for priority users.
| Leading Market Players |
|---|
| Samsung Networks |
| Ericsson |
| Nokia |
| CommScope |
| Airspan |
| JMA Wireless |
| Federated Wireless |
| Qualcomm |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on FCC-certified Spectrum Access System administrators compresses both pricing tier spreads and supply chain resilience across private cellular deployments. Equipment vendors absorb premium margins where SAS coordination bottlenecks intersect with Priority Access License scarcity, while General Authorized Access buyers face volatile channel availability that reshapes procurement timing and total cost of ownership calculations.
Pricing Analysis
Project-based contracting dominates large enterprise deployments, with automotive assembly facilities in Michigan and Tennessee negotiating single-vendor responsibility for integrated radio access, transport, and edge compute layers. Price differentiation rests on certification tier—FCC-certified SAS integration commands premium positioning against uncertified alternatives—and vertical integration depth, where end-to-end portfolio vendors extract margin over disaggregated component suppliers. Cost compression in mid-sized private builds is intensifying because macro base station suppliers maintain premium pricing for 5G NR massive MIMO arrays. Manufacturing plants with deterministic latency requirements show least price sensitivity; rural industrial sites lacking fiber infrastructure exhibit highest.
Supply Chain Analysis
GaN-on-SiC RF power amplifier substrates draw from United States, Japanese, and South Korean foundry capacity, with substrate quality tiers determining radio unit performance ceilings. Fronthaul optical transceivers and precision timing synchronization modules represent critical component dependencies alongside massive MIMO antenna arrays. Single-source vulnerability concentrates in FCC-certified SAS administrator pools, where Federated Wireless and Google dominate certification pathways. Distribution runs through direct enterprise sales for private networks and systems integrator channels for neutral host stadium deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FCC's pending 3.45 GHz harmonization rulemaking accelerates private cellular disruption by extending equipment investment lifecycles and doubling channel bandwidth for capacity-heavy industrial sites.
For Market Incumbents: Pre-empt Open RAN disaggregation by anchoring single-vendor responsibility contracts in automotive clusters before neutral host venues consolidate procurement around multi-tenant architectures. Acquire specialized spectrum coordination capabilities to defend against SAS administrator bottlenecks threatening core network integration margins. Prioritize R&D in environmental sensing algorithms that compress incumbent detection timelines for coastal radar protection zones. For New Entrants and Emerging Players: Mid-market commercial buildings in secondary US manufacturing corridors represent the most penetrable entry point, where IT-OT convergence lags Tennessee and Michigan benchmarks but fiber infrastructure density supports private 5G economics. Mining operations in Arizona copper pits offer white-space potential as extraction automation outpaces incumbent vendor ruggedization roadmaps. Target channel partnerships with industrial systems integrators possessing propagation modeling expertise for metallic interference environments. For Investors and Strategic Acquirers: Expanded 3.45 GHz access reshapes the acquisition landscape by rewarding equipment vendors with software-defined upgrade paths rather than hardware refresh dependencies. Long-term viability centers on vendors bridging LTE anchor investments with 5G NR capacity layer roadmaps across the analysis window. Prioritize targets with FCC SAS administrator relationships and containerized packet core deployment records. Monitor Priority Access License auction participation rates as inflection signal for enterprise commitment depth.| Strategic Initiative | Industry Significance |
|---|---|
| SAS Administrator Certification Investment | FCC certification reduces incumbent protection complexity for Priority Access License holders in coastal zones. |
| Open RAN Partnership Formation | Disaggregated architectures fragment vendor lock-in patterns while accelerating software deployment cycles. |
| Edge Compute Integration | Containerized 5G core user plane functions with NVIDIA GPU clusters enable factory floor inference pipelines. |
| Neutral Host Infrastructure Buildout | Multi-tenant stadium deployments capture mobile operator offload traffic alongside private enterprise demand. |
| Environmental Sensing Algorithm R&D | Enhanced incumbent detection accelerates channel availability determination in Virginia Beach and San Diego corridors. |
Research Methodology
The analysis maps private network deployments, neutral host configurations, and hybrid architectures, each validated through network planning engineers, industrial IT directors, and spectrum coordination specialists. Primary interviews with manufacturing plant automation leads, mining operations technology officers, and SAS administrator technical teams combined with secondary validation against FCC rulemaking dockets, NTIA spectrum coordination filings, and EPA environmental review records. Bottom-up equipment shipment aggregation and top-down spectrum license allocation analysis provided triangulation anchors.
Assumptions held fixed include the three-tier spectrum access framework structure and incumbent naval radar protection zones, while equipment cost curves and Priority Access License auction participation rates varied across the projection horizon. Segmentation dimensions modeled span network technology evolution, deployment model economics, end-user vertical latency requirements, and service offering margin progression. CAGRs derived from equipment vendor shipment disclosures and enterprise procurement pattern analysis, with inputs from Open RAN deployment timelines and cloud-native core adoption curves.
Practitioners should monitor FCC rulemaking progress on 3.45 GHz harmonization and NTIA coastal radar protection zone adjustments for early signals requiring forecast revision. Cross-checking against FCC SAS administrator certification databases and Priority Access License assignment records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.