
 Singapore Telecom Market | 2026-2036
Singapore Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Telecom Market Outlook
Engineering talent with 5G core network expertise is rotating toward network slicing and edge computing deployments, tightening the labor pool for legacy infrastructure maintenance. Singapore Telecommunications Ltd leverages its submarine cable landing stations to anchor international bandwidth flows through the city-state. StarHub Ltd competes through specialized enterprise IoT bundles for smart manufacturing clients. M1 Ltd differentiates with aggressive pricing on unlimited mobile plans targeting digital-native residential segments.
Singapore telecom encompasses the provisioning of voice, data, and broadband connectivity services over licensed spectrum and fiber-optic infrastructure operating at wavelengths from 1260 nm to 1625 nm for single-mode fiber backbones. These networks enable real-time financial transactions, remote vessel management, and government digital service delivery across a compact but high-density urban environment. Mobile services and broadband services command the largest revenue pools, with 5G and fiber optics segments capturing premium margins as enterprise customers upgrade from LTE and copper-based legacy lines. Residential prepaid plans remain a volume category, while postpaid unlimited plans for enterprises generate the highest per-account yields.
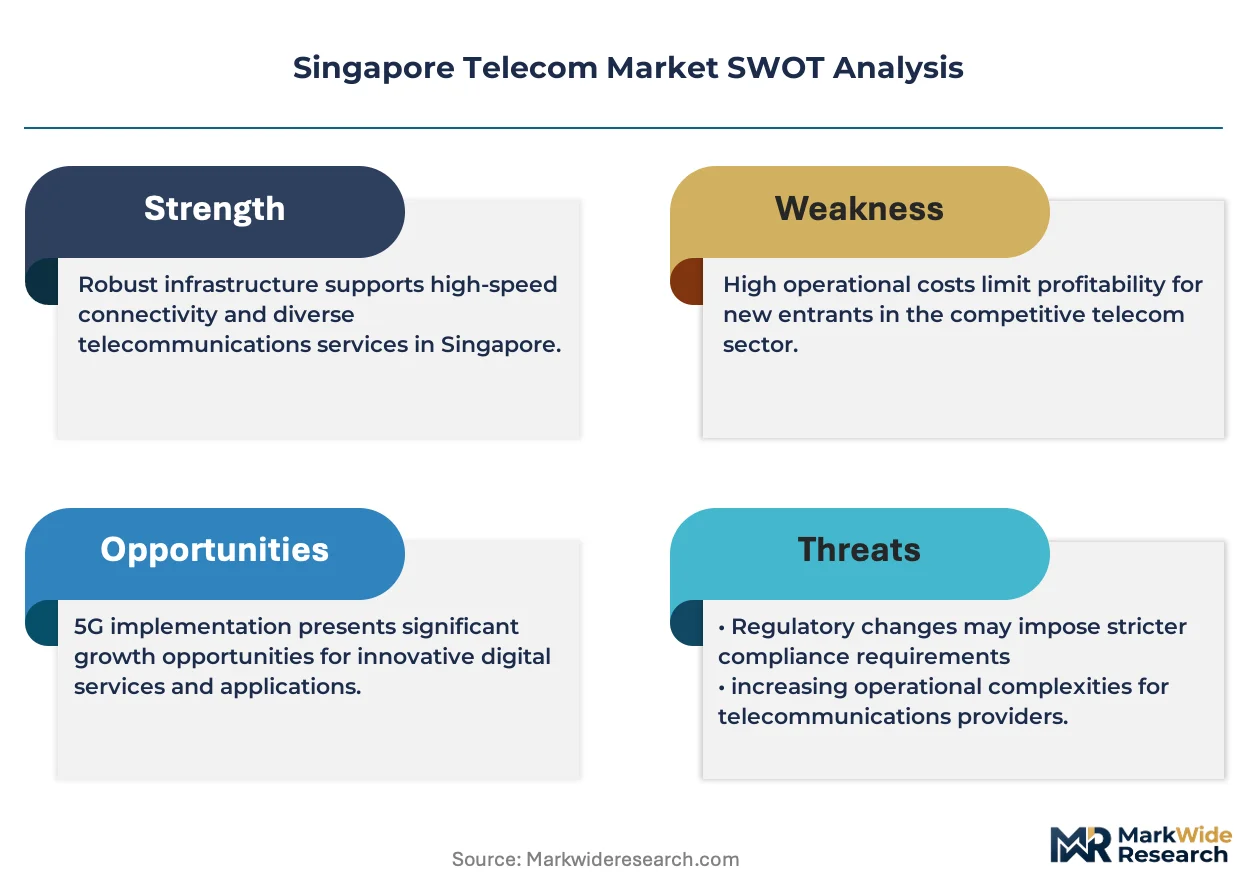
IMDA spectrum auctions and licensing frameworks dictate network rollout timelines and competitive entry barriers for new operators. The Personal Data Protection Act, enforced by the Personal Data Protection Commission, mandates strict data localization and breach notification protocols that shape cloud service architectures and cross-border data routing decisions. Cybersecurity requirements under Singapore's Cybersecurity Act impose additional compliance burdens on critical infrastructure operators. Stakeholders must weigh capex commitments against regulatory compliance costs as they evaluate spectrum renewal strategies and fiber densification investments.
Market Dynamics
Enterprise cloud migration and edge computing deployment are compressing latency requirements across Singapore's financial and maritime corridors, forcing infrastructure densification decisions that favor fiber over wireless for critical workloads.
Growth Catalysts
- IMDA spectrum frameworks:Licensing clarity accelerates 5G standalone network investments. Mobile network operators secure contiguous mid-band allocations that enable network slicing for enterprise verticals.
- Financial services latency demands:High-frequency trading platforms and real-time risk engines drive premium connectivity contracts. Submarine cable landing stations anchor international bandwidth flows through the city-state.
- Maritime logistics digitization:Remote vessel management and port automation systems expand dedicated IoT connectivity contracts. Jurong Port corridor generates concentrated demand for private 5G deployments.
Market Restraints
- Engineering talent scarcity:5G core network expertise rotates toward network slicing and edge computing deployments, tightening the labor pool for legacy infrastructure maintenance.
- Data sovereignty compliance costs:Personal Data Protection Act amendments mandate strict localization and breach notification protocols that inflate cloud service architecture expenses.
- Copper legacy depreciation drag:Residential and SME segments still anchor revenue on aging copper-based lines, compressing capital efficiency metrics.
Strategic Opportunities
- Central Business District fiber densification:Underserved commercial strata title buildings present whitespace for neutral host infrastructure models.
- Cross-border ASEAN data corridor:Singapore's submarine cable dominance positions operators as interconnection hubs for regional cloud regions.
- Cybersecurity Act compliance services:Critical infrastructure operators face mandated security audits, creating adjacent revenue streams for managed security offerings.
Industry Challenges
- Multi-vendor 5G core integration:Disaggregated radio access network architectures introduce interoperability testing burdens that delay commercial launches.
- Submarine cable repair skill pipeline:Specialized marine cable jointing expertise concentrates with aging technician cohorts, threatening maintenance response times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Telecom Market |
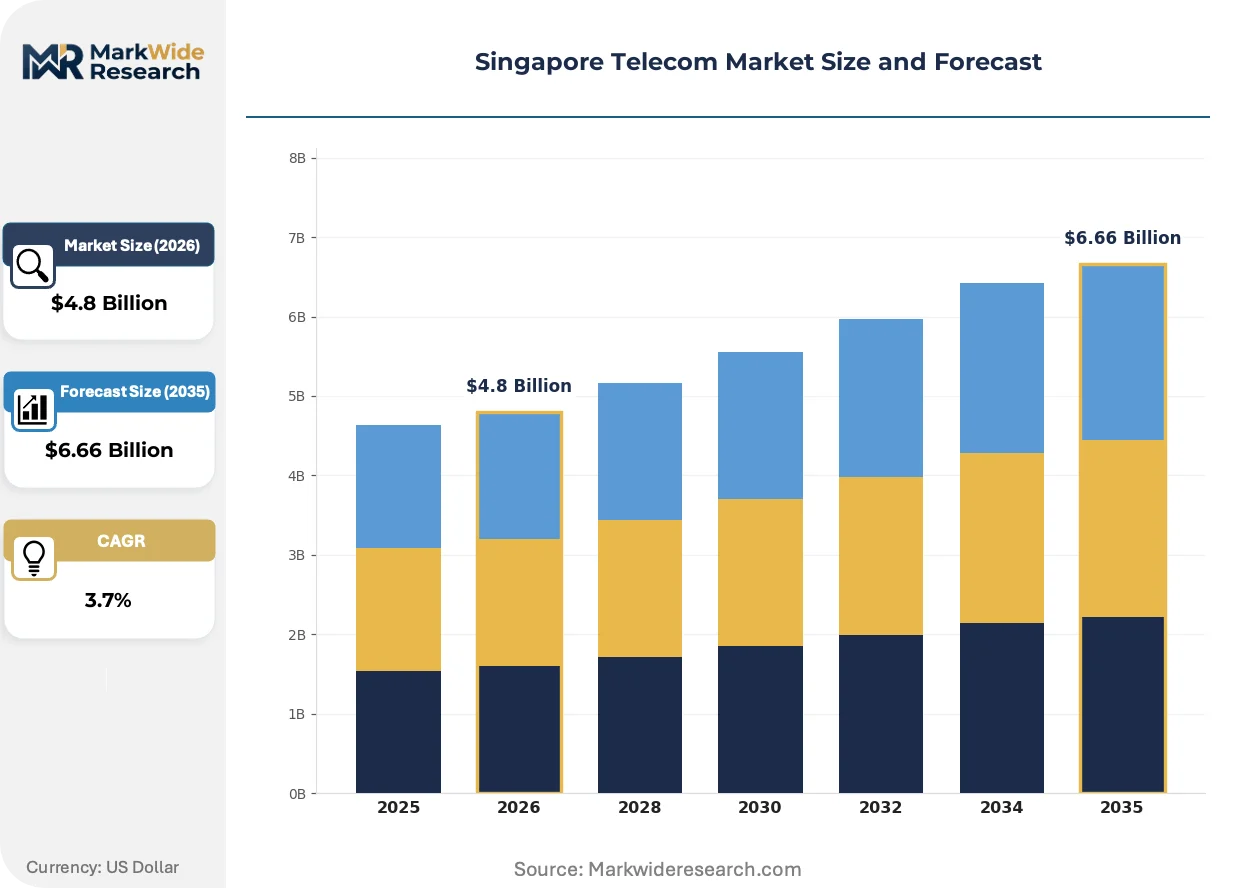
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-line Services, Internet Services, Broadband Services Technology: 5G, Fiber Optics, LTE, VoIP Customer Type: Residential, Small Business, Enterprises, Government Pricing Model: Prepaid, Postpaid, Unlimited Plans, Tiered Pricing |
| Companies Covered | M1 Ltd, MyRepublic, Singapore Telecommunications Ltd, Superhub Pte Ltd, ViewQwest Pte Ltd, StarHub Ltd, SIMBA Telecom Pte Ltd, WhistleOut Pte Ltd, NetLink NBN Trust, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Telecom Market Strategic Shifts
Network function virtualization and cloud-native architectures are dismantling traditional hardware-centric deployment models, enabling software-defined scalability that matches Singapore's compressed geography with elastic capacity provisioning.
Single-mode fiber operating at 1260 nm to 1625 nm wavelengths is supplanting hybrid fiber-copper last-mile connections for enterprise premises. Financial institutions and maritime logistics operators are adopting these pure fiber links within eighteen-month refresh cycles. This migration is compressing maintenance overhead while enabling symmetric gigabit services that legacy copper cannot sustain.
Singapore's Cybersecurity Act imposes mandatory security audits on critical infrastructure operators including telecommunications networks. The regulation forces segmentation between IT and operational technology systems, elevating compliance expenditure lines. Mobile network operators and data center providers are responding by embedding security-by-design into procurement specifications for network equipment vendors.
Enterprise buyers are consolidating connectivity contracts under single-source managed service arrangements that bundle mobile, fixed, and cloud interconnection. Systems integrators and carrier-neutral data center operators are capturing these consolidated relationships, displacing traditional telco direct sales models. This pattern concentrates most visibly in the financial services vertical, where procurement teams prioritize operational simplicity over vendor diversification.
Singapore Telecom Market Segmentation
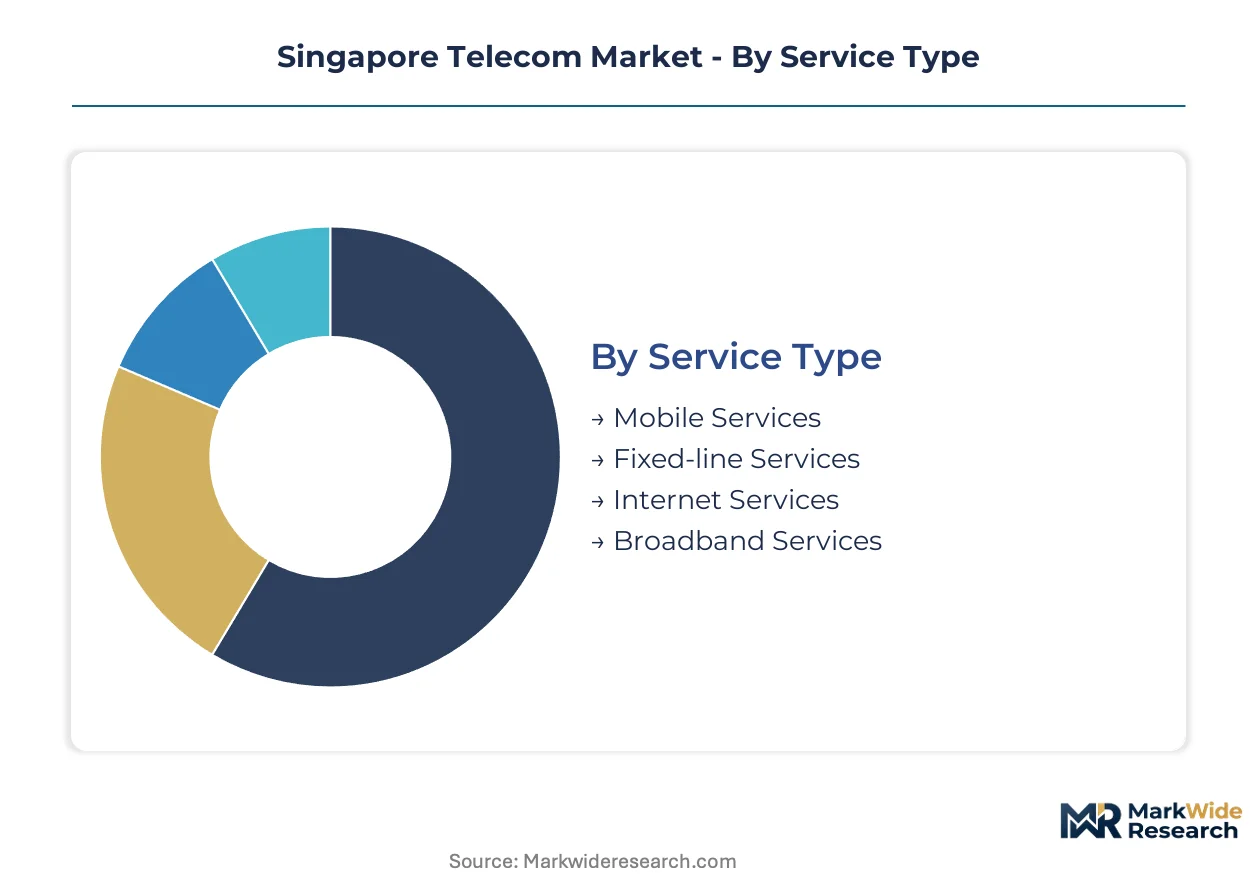
Segmentation in Singapore's telecom market exposes where infrastructure investment concentrates and where regulatory pressure reshapes service architectures. Each dimension reveals distinct margin profiles and substitution vulnerabilities that operators must navigate.
Service Type:
Substitution pressure runs strongest against legacy fixed-line voice as mobile data and over-the-top applications displace traditional circuit-switched traffic.
- Mobile Services:Wireless connectivity delivered over licensed spectrum bands supports voice, messaging, and data consumption across handheld devices. Financial services traders and maritime logistics coordinators in the Central Business District and Jurong Port corridor drive premium enterprise mobility contracts with sub-10 millisecond latency requirements.
- Broadband Services:High-capacity fixed connectivity provisioned through single-mode fiber operating at 1260 nm to 1625 nm wavelengths enables symmetric gigabit throughput. Residential estates and commercial strata buildings sustain volume demand as the Personal Data Protection Act mandates localized data processing for sensitive workloads.
- Fixed-line Services:Traditional copper-based voice and narrowband data connections serving legacy enterprise PBX systems and residential voice customers.
- Internet Services:IP transit and peering arrangements that aggregate international bandwidth flows through submarine cable landing stations.
Mobile Services anchors the volume base while Broadband Services gains share at the steepest rate.
Technology:
Cost tier differentiation separates capital-intensive next-generation deployments from depreciating legacy infrastructure carrying residual revenue.
- 5G:Fifth-generation cellular networks utilizing standalone core architectures and network slicing capabilities for enterprise verticals. IMDA spectrum allocations in mid-band ranges enable private network deployments for smart manufacturing and port automation systems.
- Fiber Optics:Single-mode fiber infrastructure replacing hybrid copper last-mile connections with pure photonic transport. Financial institutions execute eighteen-month refresh cycles to eliminate maintenance overhead and enable cloud-native application delivery.
- LTE:Fourth-generation mobile technology sustaining coverage breadth while 5G densification proceeds selectively.
- VoIP:Packet-switched voice transport over IP networks displacing traditional PSTN services.
Fiber Optics dominates capital deployment while 5G climbs the fastest in enterprise revenue contribution.
Customer Type:
Application intensity varies sharply across segments, with latency-sensitive workloads concentrating in enterprise and government verticals.
- Enterprises:Large organizations consolidating connectivity contracts under managed service arrangements bundling mobile, fixed, and cloud interconnection. Systems integrators capture these relationships in financial services procurement.
- Residential:Individual households consuming prepaid and postpaid mobile plans alongside fiber broadband subscriptions. Digital-native segments respond to aggressive unlimited data pricing from challenger operators.
- Government:Public sector entities procuring secure connectivity for digital service delivery with mandatory Cybersecurity Act compliance segmentation.
- Small Business:SME segments anchoring revenue on aging copper-based lines with compressed capital efficiency metrics.
Residential anchors the volume base while Enterprises expands most quickly in per-account yield terms.
Pricing Model:
Margin structure stratifies across commitment duration and usage predictability, with unlimited plans capturing premium yields from high-consumption segments.
- Unlimited Plans:Flat-rate pricing for unconstrained data consumption targeting digital-native residential segments and data-intensive enterprise mobility users.
- Postpaid:Contract-based billing with monthly recurring charges and overage provisions for enterprise and high-value residential accounts.
- Tiered Pricing:Usage-based rate structures with volume thresholds that align cost to consumption patterns for variable-demand customers.
- Prepaid:Pay-in-advance models with no contractual commitment serving price-sensitive residential volume and transient populations.
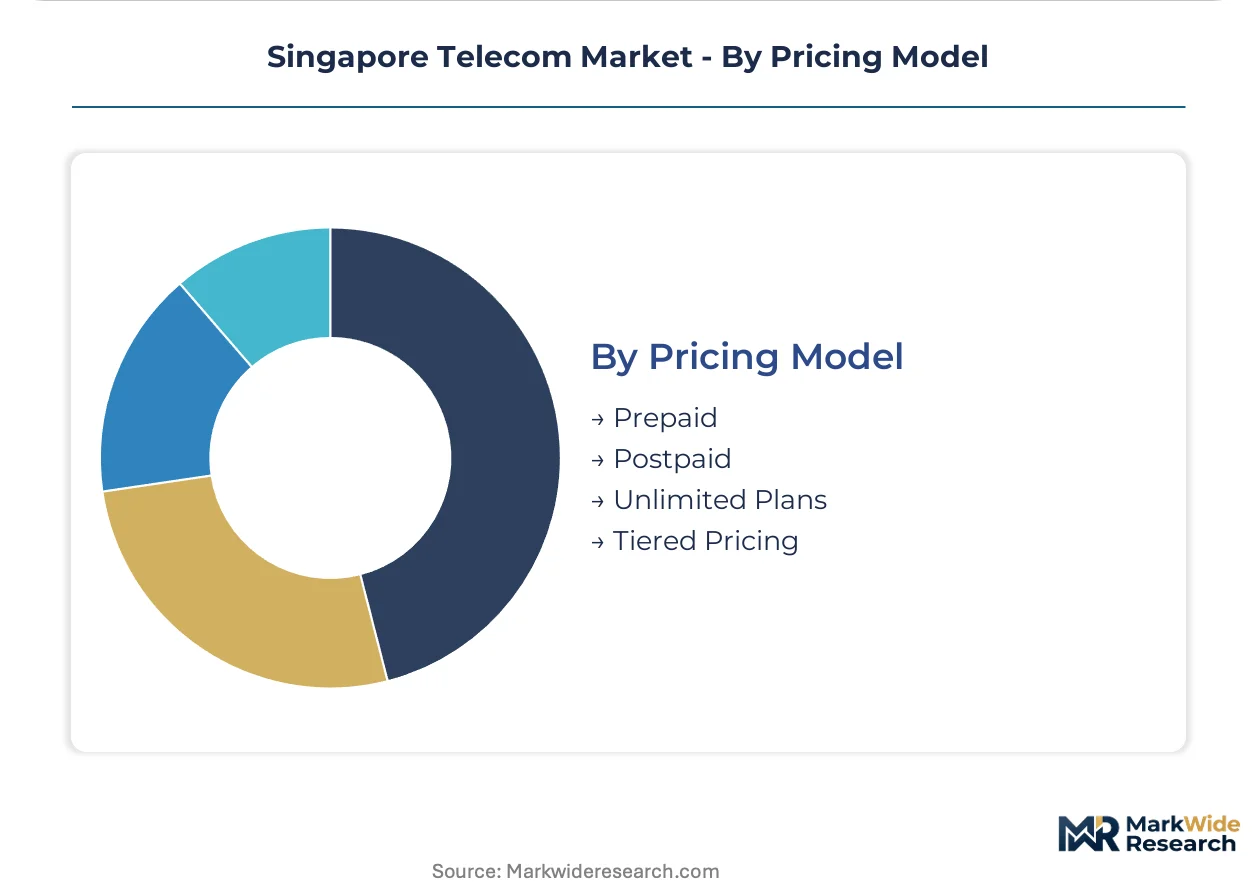
Postpaid anchors the volume base while Unlimited Plans gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IMDA spectrum frameworks anchor Singapore's telecom expansion, licensing clarity that accelerates 5G standalone investments and shapes infrastructure rollout timelines across the city-state's compact geography.
Central Business District
Financial services latency demands and high-frequency trading platforms drive premium connectivity contracts in this dense commercial core. The Personal Data Protection Act mandates strict data localization for sensitive workloads processed here. Marina Bay and Raffles Place clusters concentrate submarine cable landing stations that anchor international bandwidth flows.
Jurong Port Corridor
Maritime logistics digitization and remote vessel management systems expand dedicated IoT connectivity contracts across this southwestern industrial zone. Cybersecurity Act requirements impose mandatory security audits on critical port infrastructure operators. Tuas Port automation systems generate concentrated demand for private 5G deployments and edge computing nodes.
Tampines Regional Centre
Residential digital-native segments respond to aggressive unlimited data pricing from challenger operators in this eastern population hub. IMDA licensing frameworks govern spectrum allocations that enable network slicing for smart estate management. Tampines and Pasir Ris estates sustain volume demand for fiber broadband subscriptions alongside mobile services.
One-North and Buona Vista
Enterprise cloud migration and research institution connectivity requirements deepen reliance on low-latency fiber infrastructure in this technology corridor. Personal Data Protection Act amendments tighten breach notification protocols for biomedical and data science clusters. Fusionopolis and Biopolis precincts execute eighteen-month refresh cycles to eliminate copper maintenance overhead.
Singapore Telecom Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around full-service operators capable of bundling mobile, fixed, and enterprise solutions. Three archetypes dominate: submarine cable-anchored incumbents with international bandwidth control, price-aggressive challengers targeting residential displacement, and neutral-host infrastructure specialists serving underserved commercial buildings. Competitive moves concentrate on fiber densification partnerships and managed service bundling that displaces direct telco sales relationships.
Among Singapore-based integrated operators, Singapore Telecommunications Ltd and StarHub Ltd exemplify the incumbent tier with submarine cable landing station assets and enterprise IoT specialization. M1 Ltd occupies the challenger position with aggressive unlimited mobile pricing. NetLink NBN Trust represents the neutral-host infrastructure archetype, enabling fiber access without direct retail service competition.
| Leading Market Players |
|---|
| M1 Ltd |
| MyRepublic |
| Singapore Telecommunications Ltd |
| Superhub Pte Ltd |
| ViewQwest Pte Ltd |
| StarHub Ltd |
| SIMBA Telecom Pte Ltd |
| WhistleOut Pte Ltd |
| NetLink NBN Trust |
| Others |
Value Chain & Pricing Dynamics
Single-mode fiber displacement of copper last-mile infrastructure simultaneously redraws procurement geography toward East Asian photonics manufacturers and compresses unit economics for legacy maintenance services. This substitution dynamic concentrates vendor power with fiber-optic equipment suppliers while eroding pricing flexibility for operators still anchoring revenue on depreciating copper assets.
Pricing Analysis
Price spreads between Central Business District premium contracts and Tampines residential unlimited plans exceed threefold, reflecting latency-grade differentiation rather than bandwidth volume alone. Pricing stratifies across enterprise SLA tiers, residential consumption profiles, and wholesale bandwidth commitments, with submarine cable landing proximity commanding measurable premiums. Cost compression in residential mobile stems from SIMBA Telecom and M1 Ltd challenger pricing, while enterprise fiber yields resist downward pressure due to Cybersecurity Act compliance bundling. SME segments anchored on copper exhibit highest price sensitivity; financial services traders demonstrate lowest sensitivity, prioritizing sub-10 millisecond latency guarantees over per-megabit rates.
Supply Chain Analysis
Just-in-time procurement governs optical transceiver and fiber cable inventory, though strategic stockpiling of 5G radio units has intensified following mid-band spectrum allocation clarity from IMDA. Hardware sourcing concentrates with Chinese, South Korean, and Finnish network equipment vendors, while submarine cable manufacturing rests on Japanese and French specialist yards. Raw material dependencies span germanium for optical amplifiers, rare earth elements for laser components, and high-purity silica for fiber preforms. Single-source vulnerability concentrates in 5G baseband chipsets, where foundry capacity constraints threaten rollout timelines. Distribution runs through carrier-neutral data center operators and systems integrators that increasingly displace direct manufacturer-to-telco relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise cloud migration fragments demand across specialized latency tiers, cybersecurity compliance bundles, and vertical-specific IoT configurations, creating service-layer niches that favor focused specialists over full-service generalists.
For Market Incumbents: Fortify submarine cable landing station control through exclusive dark fiber leases to cloud regions, while embedding managed security services into enterprise connectivity contracts to offset displacement by systems integrators. Talent scarcity in 5G core network slicing represents an existential threat; vertical integration into edge computing infrastructure through neutral-host partnerships offers defensive margin protection against StarHub Ltd enterprise IoT specialization and M1 Ltd residential pricing aggression. For New Entrants and Emerging Players: Neutral-host infrastructure gaps in underserved Central Business District strata title buildings present immediate whitespace, as incumbent fiber densification prioritizes anchor tenants over fragmented commercial ownership structures. Private 5G deployments for Jurong Port automation systems offer the most penetrable enterprise vertical, given maritime logistics digitization mandates and incumbent focus on financial services latency contracts. A channel partnership model with NetLink NBN Trust wholesale access bypasses retail customer acquisition costs while enabling service differentiation through vertical-specific compliance tooling. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors infrastructure-specialist acquisitions with submarine cable adjacencies or cybersecurity compliance capabilities. Long-term viability hinges on 5G standalone network coverage completion and fiber-to-the-premises penetration saturation across the analysis window. Acquisition targets should demonstrate captive enterprise relationships in financial services or maritime logistics, with managed service revenue exceeding fifty percent of connectivity sales. The signal to watch is IMDA spectrum renewal timing for 3.5 GHz allocations, which will determine infrastructure depreciation cycles and capital intensity trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Submarine Cable Landing Expansion | Anchors international bandwidth flows through Singapore's geographic chokepoint position. |
| Private 5G Network Deployment | Captures Jurong Port automation and smart manufacturing verticals with dedicated slicing. |
| Managed Security Service Bundling | Addresses Cybersecurity Act audit mandates while displacing pure connectivity commoditization. |
| Neutral-Host Infrastructure Partnership | Penetrates underserved commercial strata buildings without retail customer acquisition overhead. |
| Edge Computing Node Colocation | Compresses latency for financial services high-frequency trading and real-time risk engines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mobile network engineering directors, enterprise procurement leads at financial institutions and maritime logistics operators, data center interconnection specialists, and IMDA regulatory affairs officers. Secondary validation drew from IMDA spectrum auction disclosures, submarine cable landing station capacity filings, Cybersecurity Act compliance audit records, and Personal Data Protection Commission enforcement actions. Bottom-up service revenue modeling triangulated against top-down infrastructure deployment tracking across fiber densification and 5G standalone rollout.
Across the analysis window, projections integrate service-type segmentation by mobile, broadband, fixed-line, and internet revenue pools; technology segmentation across 5G, fiber optics, LTE, and legacy copper; and customer-type splits between enterprise, residential, government, and SME verticals. CAGRs derive from installed base evolution, pricing trajectory assumptions, and substitution elasticity estimates between fiber and copper last-mile connections. Forecast inputs incorporate IMDA licensing timeline scenarios and enterprise cloud migration intensity patterns specific to Singapore's financial and maritime corridor concentration.
Forecasts assume regulatory continuity in IMDA spectrum frameworks and Personal Data Protection Act enforcement regimes; material policy shifts would require re-modeling substitution timelines and compliance cost structures. Specific risks include submarine cable repair skill pipeline collapse, multi-vendor 5G core interoperability delays, and data sovereignty amendment surprises that reshape cross-border routing economics. Revision becomes warranted when enterprise cloud migration velocity or cybersecurity audit enforcement intensity crosses thresholds that alter infrastructure depreciation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Telecom Expense Management Market
Telecommunications
Egypt Telecom Tower Market
Telecommunications
Oman Telecommunication Market
Telecommunications
Turkey Telecom Market
Telecommunications
5G RAN Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Satcom Terminal Market
Telecommunications
Germany Fixed Wireless Access (FWA) Market
Telecommunications
France Telecom Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Italy Telecom Market
Telecommunications
Myanmar ICT Market
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
GPON Equipment Market