
 UAE Cloud Computing Market | 2026-2036
UAE Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Cloud Computing Market Insights
Market Context
Subscription-based managed services is rebalancing what enterprises purchase, shifting capital expenditure toward operational models with embedded support. Microsoft Corporation leverages its Azure sovereign cloud architecture to anchor government and regulated sector relationships. Amazon Web Services sustains hyperscale infrastructure investments across Dubai and Abu Dhabi availability zones. Oracle Corporation specializes in database-as-a-service migrations for legacy enterprise workloads seeking regional data residency.
Technical Definition and Structural Segments
Cloud computing in the UAE denotes on-demand delivery of compute, storage, and networking resources over IP-based infrastructure with guaranteed uptime thresholds and multi-tenant virtualization. Its primary commercial purpose centers on replacing owned data center capacity with metered utility services that scale elastically with transaction volumes. Public cloud deployment captures the dominant share of new enterprise workloads given hyperscaler presence and price-performance ratios, while hybrid cloud architectures retain traction among banks and healthcare providers managing sensitive data classifications. SaaS delivery models command the largest revenue pool within service types due to productivity application renewals, whereas IaaS expansion accelerates fastest as developers provision containerized environments directly.
Regulatory Framework
The UAE's National Cybersecurity Council, Telecommunications and Digital Government Regulatory Authority, and Federal Data Protection Law establish compliance baselines for data localization, encryption standards, and breach notification protocols that cloud providers must satisfy for market access. These frameworks shape procurement decisions by mandating in-country infrastructure, certifying providers against specific assurance levels, and penalizing cross-border transfers lacking adequate safeguards. Stakeholders must monitor evolving sovereign cloud requirements and assess whether current multi-cloud configurations align with anticipated classification tier expansions.
Market Dynamics
The UAE cloud computing market is experiencing structural reconfiguration as sovereign data residency mandates from the Federal Data Protection Law force hyperscalers to deploy in-country infrastructure, compressing procurement cycles and elevating compliance to a primary vendor selection criterion.
Growth Catalysts
- National In-Country Value program:Government procurement rules now weight local data center presence and Emirati workforce participation, redirecting enterprise budgets toward domestic cloud infrastructure.
- Core banking modernization:Financial services institutions are migrating legacy mainframe workloads to containerized environments, creating sustained demand for managed database services with guaranteed latency thresholds.
- Hub71 technology cluster:Abu Dhabi's startup ecosystem concentrates venture-backed SaaS ventures requiring elastic compute, generating recurring infrastructure consumption from early-stage enterprises.
Market Restraints
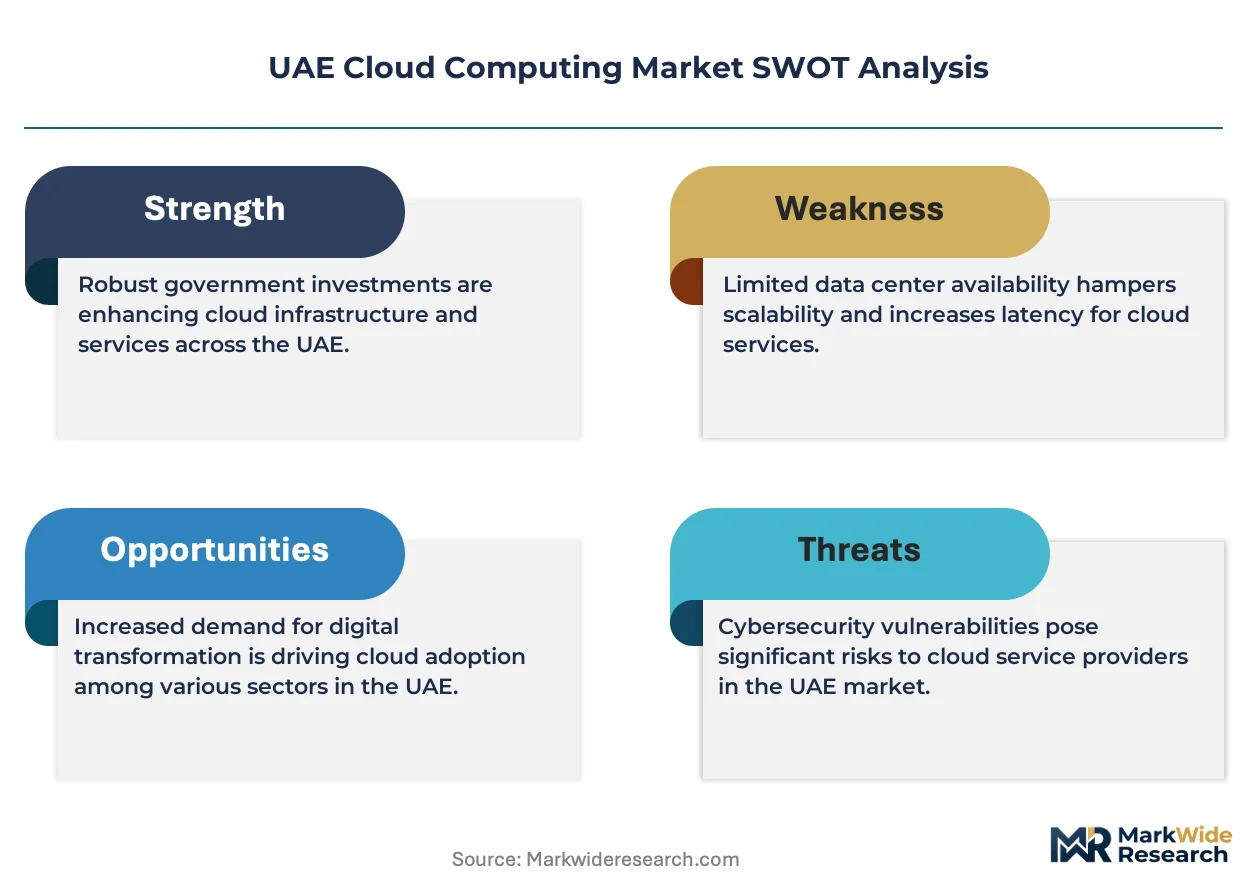
- Limited fiber backhaul in Northern Emirates:Ras Al Khaimah and Fujairah lack redundant submarine cable landing stations, constraining edge computing deployments outside Dubai and Abu Dhabi.
- Skilled cloud architecture talent scarcity:UAE nationals with multi-cloud certification credentials remain insufficient relative to enterprise demand, inflating implementation timelines and professional services costs.
- Cross-border data transfer restrictions:The Federal Data Protection Law's adequacy requirements block seamless integration with European and Asian cloud regions, fragmenting multi-cloud strategies.
Strategic Opportunities
- Sharjah's emerging media production hub:Content rendering and AI-generated video workloads present unmet demand for GPU-intensive cloud instances with low-latency connectivity to broadcast facilities.
- Healthcare data lake consolidation:Dubai Health Authority's interoperability mandates are creating procurement openings for unified analytics platforms spanning public and private hospital networks.
- Convergence of sovereign cloud with confidential computing:Hardware-based enclave technologies enable processing of classified government workloads on shared infrastructure, expanding addressable market segments.
Industry Challenges
- Legacy mainframe integration complexity:Banks migrating decades-old COBOL applications encounter data schema incompatibilities that extend cloud transition timelines beyond contracted periods.
- Certification timeline compression:The Telecommunications and Digital Government Regulatory Authority's evolving assurance frameworks require providers to re-certify annually, diverting engineering resources from product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Cloud Computing Market |
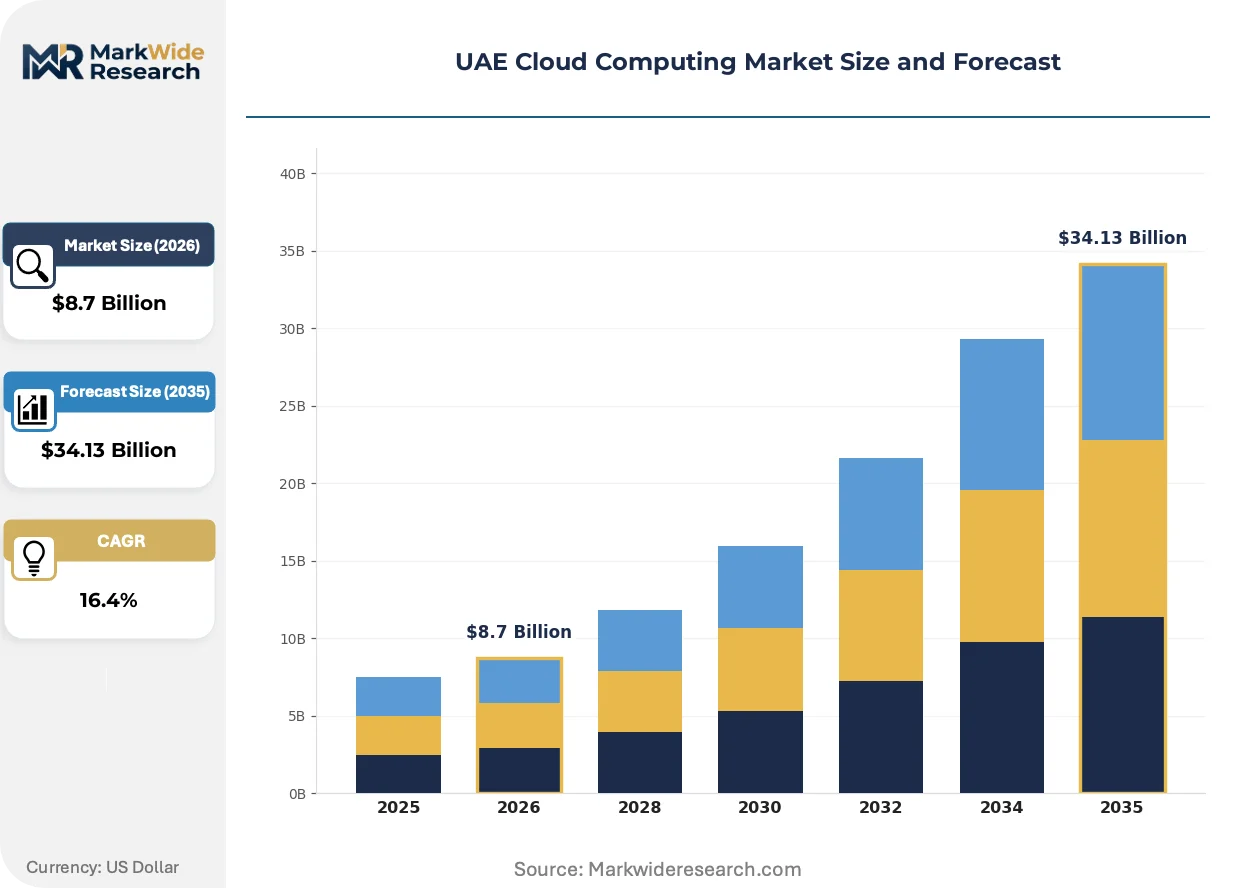
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, DaaS End User: Healthcare, BFSI, Telecommunications, Retail Technology: AI, IoT, Big Data, Blockchain |
| Companies Covered | Amazon Web Services, Microsoft Corporation, Google LLC, Oracle Corporation, Alibaba Cloud, IBM Corporation, Salesforce, SAP, Rackspace Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Cloud Computing Market Trends and Innovations
Container orchestration and edge-native architectures are displacing monolithic virtual machine deployments across UAE enterprise data centers, with financial services and logistics operators leading adoption curves.
Confidential computing with hardware-based trusted execution environments is rewriting how government agencies evaluate cloud risk. Dubai's smart city operators now provision sensitive biometric processing on multi-tenant infrastructure. This capability compresses the traditional air-gapped versus cloud-native dichotomy that previously segmented procurement.
The Federal Data Protection Law's data classification tiers are forcing providers to segment infrastructure by assurance level. Banks and healthcare operators must now map workloads to certified environments with distinct encryption and access controls. This regulatory architecture is fragmenting the previously unified public cloud market into sovereign, regulated, and standard service strata.
Enterprise buyers are consolidating vendor relationships around integrated platform stacks rather than best-of-breed point solutions. CIOs at UAE logistics conglomerates now demand unified billing, identity management, and support channels across compute, storage, and productivity applications. This preference shift disadvantages specialized providers lacking adjacent service portfolios, concentrating procurement authority with full-stack hyperscalers.
UAE Cloud Computing Market Segmentation
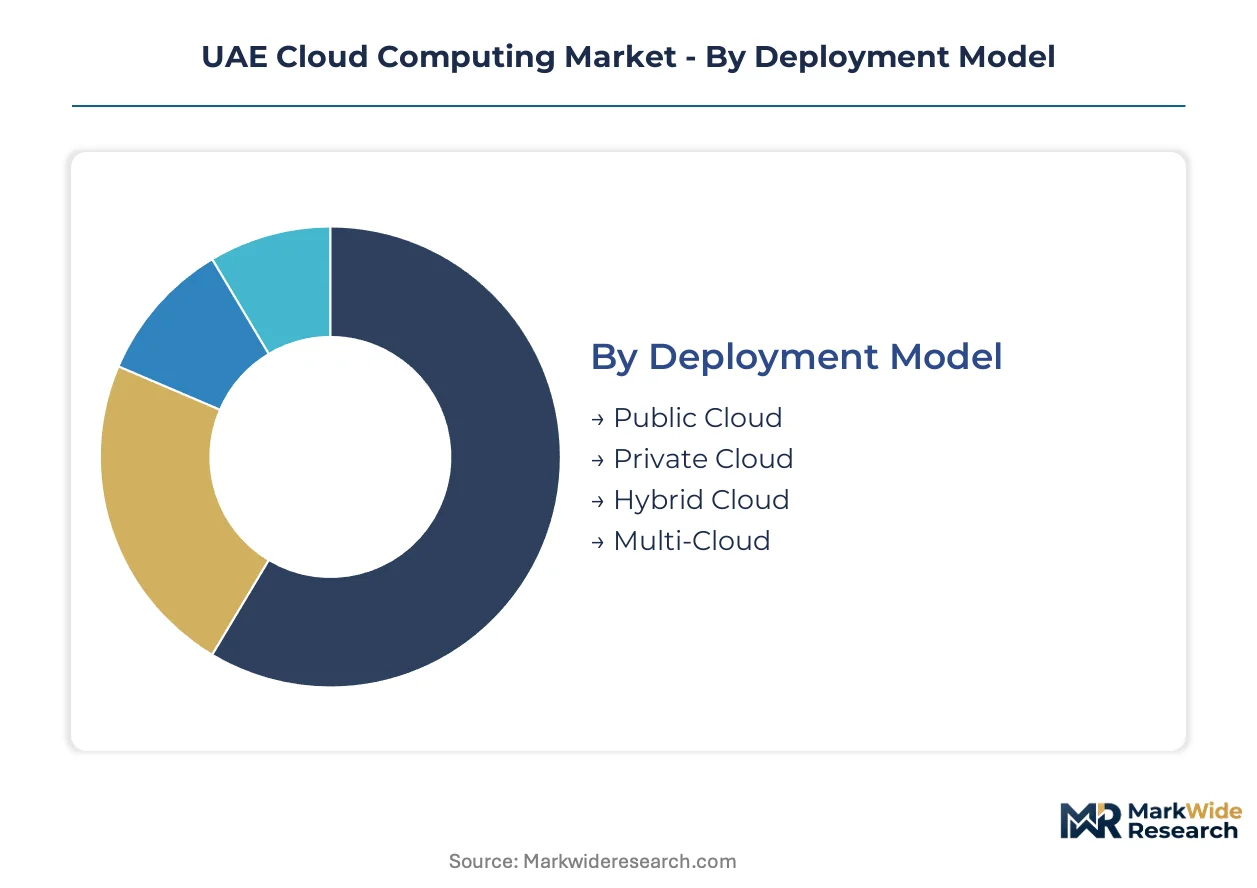
Cloud procurement in the UAE fragments across deployment architectures, service layers, and sector-specific compliance requirements. Buyers weight data residency mandates against elasticity needs, creating distinct purchasing coalitions within each segment. Understanding these fault lines clarifies where vendor consolidation will accelerate versus where specialized providers retain pricing power.
Deployment Model:
Cost tier determines initial buyer screening, with hyperscale public cloud anchoring entry-level commitments while sovereign requirements elevate private and hybrid alternatives.
- Public Cloud:Multi-tenant infrastructure delivered over shared data center assets with metered consumption billing. Dubai's Internet City and Abu Dhabi's Hub71 concentrate startup and SME demand where elastic scaling outweighs data classification concerns. The Federal Data Protection Law's standard-tier workloads flow here, capturing volume from retail and non-regulated services.
- Hybrid Cloud:Orchestrated workloads spanning on-premises assets and hyperscale regions with unified management planes. UAE banks and healthcare operators deploy this architecture to partition sensitive customer records from burst compute, satisfying the National Cybersecurity Council's segmentation mandates without surrendering elasticity entirely.
- Private Cloud:Dedicated single-tenant infrastructure with customized security boundaries and guaranteed resource isolation. Government ministries and defense contractors procure these environments for classified processing under sovereign cloud certification.
- Multi-Cloud:Distributed workloads across two or more hyperscale providers with abstraction layer management. Large enterprises adopt this pattern to mitigate vendor lock-in and satisfy procurement diversification requirements under the National In-Country Value program.
Volume sits with Public Cloud; growth tilts toward Hybrid Cloud.
Service Type:
Application maturity separates buyers, with established enterprises renewing SaaS productivity suites while developers drive IaaS and PaaS expansion.
- SaaS:Pre-configured application software delivered via browser or mobile interfaces with vendor-managed infrastructure. UAE logistics conglomerates and professional services firms standardize on unified collaboration platforms, consolidating vendor relationships under single billing and identity management frameworks.
- IaaS:Raw compute, storage, and networking resources provisioned through APIs and console interfaces. Container orchestration adoption across Dubai's fintech startups accelerates consumption of virtualized instances with direct developer control over environment configuration.
- PaaS:Managed runtime environments abstracting infrastructure management from application deployment. Abu Dhabi's Hub71 ventures leverage these services to compress time-to-market for mobile and web applications without building DevOps capabilities in-house.
- DaaS:Cloud-hosted virtual desktop infrastructure streaming full Windows or Linux environments to endpoint devices. Healthcare networks in Dubai deploy this model to secure clinician access across distributed hospital campuses while centralizing patient data within certified data centers.
Revenue concentrates in SaaS renewals; IaaS climbs the fastest as containerization spreads.
End User:
Regulatory intensity segments buyers, with financial and healthcare operators facing the strictest data classification requirements.
- BFSI:Banks, insurance carriers, and investment firms migrating core banking systems and risk analytics to cloud infrastructure. The Central Bank of the UAE's operational resilience guidelines mandate guaranteed latency thresholds and disaster recovery capabilities that shape vendor selection.
- Healthcare:Hospital networks, diagnostic chains, and telemedicine platforms consolidating electronic medical records and imaging archives. Dubai Health Authority's interoperability mandates create procurement openings for unified analytics platforms spanning public and private provider networks.
- Telecommunications:Mobile and fixed-line operators virtualizing network functions and customer management systems. Etisalat and du leverage cloud infrastructure to deploy 5G core networks and edge computing nodes across the Emirates.
- Retail:E-commerce platforms and brick-and-mortar chains scaling transactional infrastructure during seasonal demand spikes. Dubai's luxury retail sector deploys AI-powered personalization engines requiring elastic GPU resources.
BFSI anchors committed spend; healthcare procurement is expanding most quickly under interoperability mandates.
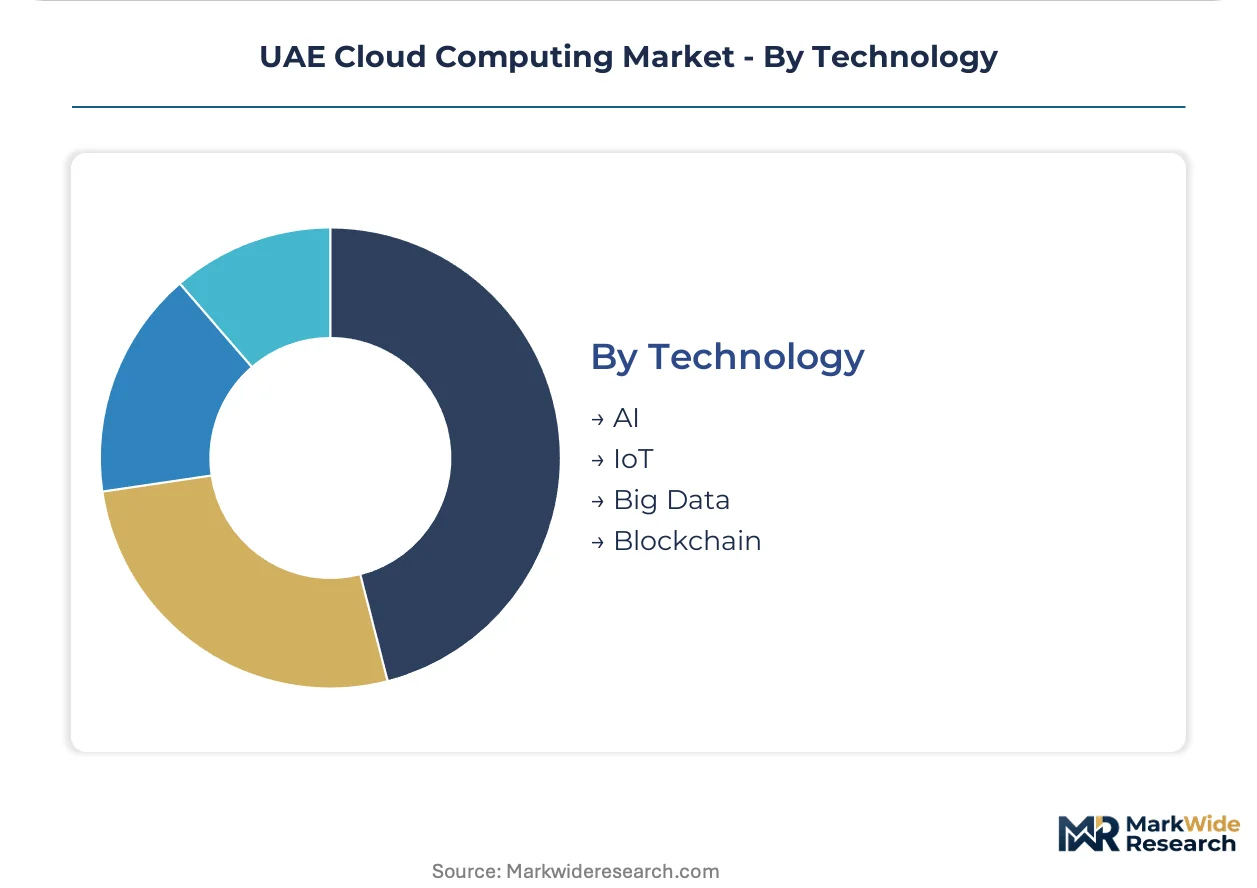
Technology:
Infrastructure performance requirements differentiate workloads, with AI and big data demanding specialized silicon while IoT and blockchain optimize for distributed edge deployment.
- AI:Machine learning training and inference workloads requiring GPU and TPU acceleration with high-bandwidth memory subsystems. Sharjah's emerging media production hub generates unmet demand for rendering and generative video processing with low-latency connectivity to broadcast facilities.
- Big Data:Distributed analytics platforms processing petabyte-scale datasets across clustered compute nodes. UAE government smart city initiatives consolidate telemetry from transportation, energy, and environmental sensors into unified data lakes.
- IoT:Edge-connected device fleets generating telemetry streams for real-time monitoring and predictive maintenance. Logistics operators across Jebel Ali Free Zone deploy these architectures for container tracking and warehouse automation.
- Blockchain:Distributed ledger infrastructure requiring Byzantine fault tolerance and cryptographic verification. Dubai's trade finance and real estate registries pilot these systems for transparent transaction settlement.
Big Data captures current infrastructure commitment; AI gains share fastest under generative workload expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure production concentrates in Dubai and Abu Dhabi data center clusters, while consumption demand spreads across all seven Emirates with pronounced gaps in Northern Emirates connectivity.
Dubai
Dubai Internet City hosts the densest concentration of hyperscale availability zones, with financial services and retail enterprises driving elastic compute procurement. The Dubai Data Law mandates free zone data localization for certain classifications. Dubai South's logistics corridor deploys edge nodes for real-time container tracking across Jebel Ali operations.
Abu Dhabi
Abu Dhabi's sovereign wealth-backed technology investments anchor government cloud migration at scale, with Hub71 startup ecosystem generating sustained SaaS infrastructure demand. The National Cybersecurity Council certifies providers against tiered assurance levels here. Masdar City's smart grid pilots consume substantial IoT analytics capacity from local data centers.
Sharjah
Sharjah's emerging media production sector generates unmet GPU-intensive workload demand for content rendering and AI-generated video processing. The Sharjah Media City free zone incentives attract post-production houses requiring low-latency broadcast connectivity. University City research clusters increasingly provision cloud-based simulation environments for engineering applications.
Northern Emirates
Ras Al Khaimah and Fujairah face infrastructure constraints from limited submarine cable diversity, compressing enterprise cloud adoption timelines. The Telecommunications and Digital Government Regulatory Authority's universal service obligations are extending fiber backhaul into these emirates. Fujairah's port modernization plans include edge computing investments for maritime logistics optimization.
Al Ain
Al Ain's healthcare and education sectors represent latent cloud demand as Dubai and Abu Dhabi providers extend service coverage inland. The Abu Dhabi Health Services Company is consolidating patient records infrastructure that will require regional data residency compliance. United Arab Emirates University research computing increasingly leverages hybrid cloud for high-performance workloads.
UAE Cloud Computing Market Competitive Landscape
Top-tier vendors anchor hyperscale infrastructure deployment, while regional specialists and telecom-affiliated providers occupy mid-market segments serving compliance-sensitive buyers. The market structure tilts toward consolidation as sovereign certification requirements elevate capital barriers for new entrants. Three archetypes dominate: global hyperscalers with sovereign cloud architectures, regional data center operators with in-country value credentials, and telecom-integrated providers leveraging last-mile connectivity. Competitive moves center on certification acquisition against evolving National Cybersecurity Council frameworks and strategic partnerships with systems integrators possessing Emirati workforce depth.
Within the hyperscaler tier, Amazon Web Services, Microsoft Corporation, and Oracle Corporation exemplify contrasting market positioning strategies. Amazon Web Services occupies a scale-driven position across Dubai and Abu Dhabi availability zones. Microsoft Corporation represents the sovereign cloud architecture specialist with Azure government relationships. Oracle Corporation anchors database-as-a-service migration demand among legacy enterprise workloads seeking regional data residency guarantees.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Corporation |
| Google LLC |
| Oracle Corporation |
| Alibaba Cloud |
| IBM Corporation |
| Salesforce |
| SAP |
| Rackspace Technology |
| Others |
Pricing and Supply Chain Analysis
Multi-cloud certified Emirati architects concentrated in Dubai Internet City and Abu Dhabi's Hub71 command wage premiums that widen pricing spreads between sovereign-certified and standard-tier cloud offerings. The Federal Data Protection Law's data localization mandates compress procurement cycles for compliant infrastructure, amplifying labor-cost pass-through into premium service tiers.
Pricing Analysis
Margin tightening in sovereign cloud tiers reflects the National Cybersecurity Council's annual re-certification burden and Emirati workforce quotas under the National In-Country Value program. Pricing stratifies across premium sovereign-certified, standard regulated, and economy public tiers, with certification grade and guaranteed latency thresholds as primary differentiation drivers. Cost-down pressure on standard-tier public cloud accelerates because hyperscale providers compete for startup volume at Hub71. Retail and logistics conglomerates exhibit highest price sensitivity, while government ministries and defense contractors show lowest sensitivity given classification requirements.
Supply Chain Analysis
Regional distribution centers in Dubai Internet City and Abu Dhabi anchor hub-and-spoke patterns extending compute capacity across the seven Emirates. Hardware supply concentrates in Taiwan, South Korea, and the United States for advanced server silicon and networking equipment. Raw material dependencies span gallium nitride substrates, high-bandwidth memory modules, and specialized cooling fluids. Single-source vulnerability from submarine cable landing stations constrains Northern Emirates connectivity. Distribution runs through hyperscale availability zones with edge node extensions into free zone logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics in UAE cloud infrastructure prop pricing power, with certified sovereign capacity bottlenecked by Emirati workforce scarcity and annual National Cybersecurity Council re-certification cycles.
For Market Incumbents: Deploy sovereign cloud certification as a defensive moat against emerging regional data center operators. Microsoft Corporation and Amazon Web Services should accelerate Emirati workforce pipeline investments through Hub71 partnerships to preempt National In-Country Value procurement penalties. Capture channel control by embedding systems integrators with deep Emirati technical benches into government RFP workflows.
For New Entrants and Emerging Players: Capture Sharjah's unmet GPU-intensive media production demand where hyperscale presence remains thin. Target healthcare data lake consolidation in Dubai and Al Ain under Dubai Health Authority interoperability mandates. Pursue a specialist positioning in confidential computing hardware enclaves for classified government workloads, leveraging partnerships with UAE sovereign wealth technology funds.
For Investors and Strategic Acquirers: Re-rating potential sits with regional data center operators possessing in-country value credentials and existing National Cybersecurity Council certifications given regulatory elevation of compliance to primary vendor selection criterion. Long-term viability favors providers with integrated sovereign cloud architectures spanning Dubai and Abu Dhabi availability zones. Watch the Federal Data Protection Law's classification tier expansion as the signal for infrastructure segmentation into premium regulated strata.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | National Cybersecurity Council tiered assurance unlocks government and defense procurement pipelines. |
| Emirati Workforce Pipeline | National In-Country Value program compliance redirects enterprise budgets toward certified domestic operators. |
| Confidential Computing Deployment | Hardware-based enclave technologies expand addressable market into classified processing on shared infrastructure. |
| Edge Node Extension | Dubai South logistics corridor and Northern Emirates fiber backhaul capture distributed compute demand. |
| Healthcare Data Lake Partnership | Dubai Health Authority interoperability mandates create recurring infrastructure consumption from hospital network consolidation. |
Research Methodology
Document review covered hyperscaler capex disclosures, Telecommunications and Digital Government Regulatory Authority certification registers, and Federal Data Protection Law implementation guidance, complemented by interviews with cloud platform engineers, government procurement officers at UAE ministries, IT directors at Dubai-based financial institutions, and systems integration specialists with National In-Country Value credentials. Secondary sources included SEC filings from listed hyperscalers, UAE customs data on server hardware imports, and Dubai Health Authority interoperability framework documents. Bottom-up demand modeling from enterprise workload migrations was triangulated against top-down infrastructure capacity assessments across Dubai and Abu Dhabi data center clusters.
Market size outputs reflect segmentation across deployment models, service types, and end-user verticals with regulatory intensity weighting, across the analysis window. CAGRs were derived from elasticity-adjusted adoption curves for containerized workloads and sovereign cloud migration timelines. Modeled inputs included financial services core banking modernization pipelines, Hub71 venture-backed SaaS infrastructure consumption, and healthcare interoperability mandate procurement schedules.
The model holds under stable Federal Data Protection Law classification tiers and continued National Cybersecurity Council certification continuity; deviation in adequacy determination for European cross-border transfers or submarine cable disruption would shift multi-cloud strategy fragmentation and infrastructure demand geography. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
North America Cloud Microservices Platform Market
Cloud Computing
Application Hosting Market
Cloud Computing
UK Cloud Computing Market
Cloud Computing
Telecom Cloud Market
Cloud Computing
Multi-Cloud Optimization Tools Market
Cloud Computing
Cloud Backup Market
Cloud Computing
Consumer Cloud Subscription Market
Cloud Computing
Europe Mobile Cloud Market
Cloud Computing
Cloud Microservice and Application Market
Cloud Computing
Cloud Managed Networking Market
Cloud Computing
China Cloud Computing Market
Cloud Computing
Indonesia Cloud Market
Cloud Computing
Retail Cloud Market
Cloud Computing
Saudi Arabia Cloud Services Market
Cloud Computing
Europe Cloud Computing Market
Cloud Computing
Hybrid Cloud Market