
 Denmark Telecom Market | 2026-2036
Denmark Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Telecom Market Insights
Denmark is tilting its infrastructure investment toward nationwide fiber and 5G densification. Nuuday leverages its converged service portfolio across fixed and mobile domains. TDC NET anchors the wholesale fiber layer through open-access network architecture. Telia Denmark competes on enterprise-grade connectivity and IoT integration.
Telecom encompasses the transmission of voice, data, and video across wired and wireless infrastructures operating at frequencies from sub-1 GHz to millimeter-wave bands and optical wavelengths of 1260–1625 nm, serving commercial, governmental, and consumer communication needs. Fiber optic deployment dominates capital allocation among technology segments as operators replace legacy copper. Mobile data generates the fastest service-type expansion, driven by unlimited plan uptake and video consumption. Enterprise customer contracts yield the deepest margin pools due to SLA premiums and managed service attach rates.
The Danish Energy Agency coordinates spectrum auctions while the Danish Business Authority enforces net neutrality and consumer protection frameworks, collectively shaping operator licensing costs and service obligations. BIS compliance requirements for network equipment security certification filter vendor eligibility. Stakeholders must weigh open RAN interoperability against single-vendor integration efficiency as procurement standards tighten.
Market Dynamics
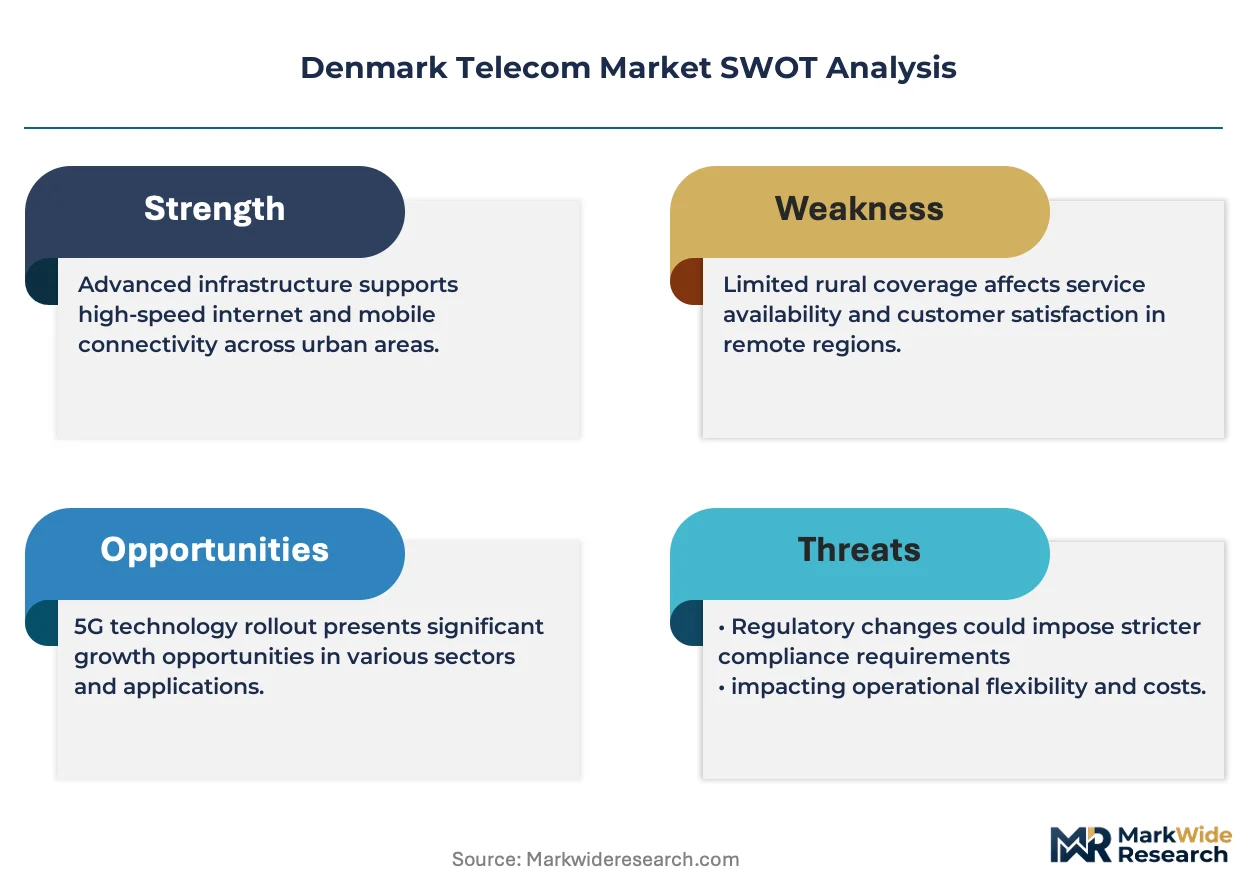
Denmark's telecom infrastructure is undergoing forced obsolescence as the Danish Energy Agency accelerates spectrum reallocation and the national broadband strategy mandates copper decommissioning timelines. Operators face simultaneous capital demands for fiber trenching, 5G densification, and legacy network retirement.
Growth Catalysts
- Enterprise Cloud Migration:Danish manufacturing and logistics firms are consolidating IT infrastructure onto cloud-managed WAN services, driving demand for symmetric fiber connectivity and SLA-guaranteed mobile backup.
- Open-Access Fiber Mandate:TDC NET's wholesale fiber architecture enables retail service competition without parallel infrastructure build, reducing market entry barriers for challenger operators.
- Millimeter-Wave Spectrum Release:Auctions in the 26 GHz and 28 GHz bands unlock fixed wireless access deployment in rural Jutland regions where fiber economics remain prohibitive.
Market Restraints
- Copper Retirement Costs:Mandatory PSTN switch-off by 2027 imposes stranded asset write-downs and customer migration expenses on operators maintaining legacy voice infrastructure.
- Equipment Vendor Concentration:BIS network security certification requirements limit eligible 5G RAN suppliers to a narrow pool of pre-approved vendors, constraining price competition.
- Fiber Trenching Constraints:Dense urban underground utility congestion in Copenhagen and Aarhus extends deployment timelines and elevates civil engineering costs per premises passed.
Strategic Opportunities
- Island Fiber Extension:Bornholm and smaller Baltic Sea islands remain underserved by high-capacity connectivity, presenting first-mover advantages for submarine cable or fixed wireless deployments.
- Private 5G Networks:Industrial zones in Odense and Aalborg seek campus-wide cellular coverage for automated logistics, creating enterprise vertical revenue streams beyond consumer mobile.
- Green Power Purchase Agreements:Data center operators in Esbjerg's renewable energy cluster demand 24/7 carbon-free electricity matching, differentiating telecom infrastructure hosting services.
Industry Challenges
- Field Engineering Talent Scarcity:Specialized fiber splicing and 5G antenna alignment skills face supply constraints as infrastructure build-out accelerates across multiple simultaneous projects.
- Multi-Vendor RAN Integration:Open RAN interoperability mandates from the Danish Business Authority complicate network operations centers managing disaggregated hardware and software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Telecom Market |
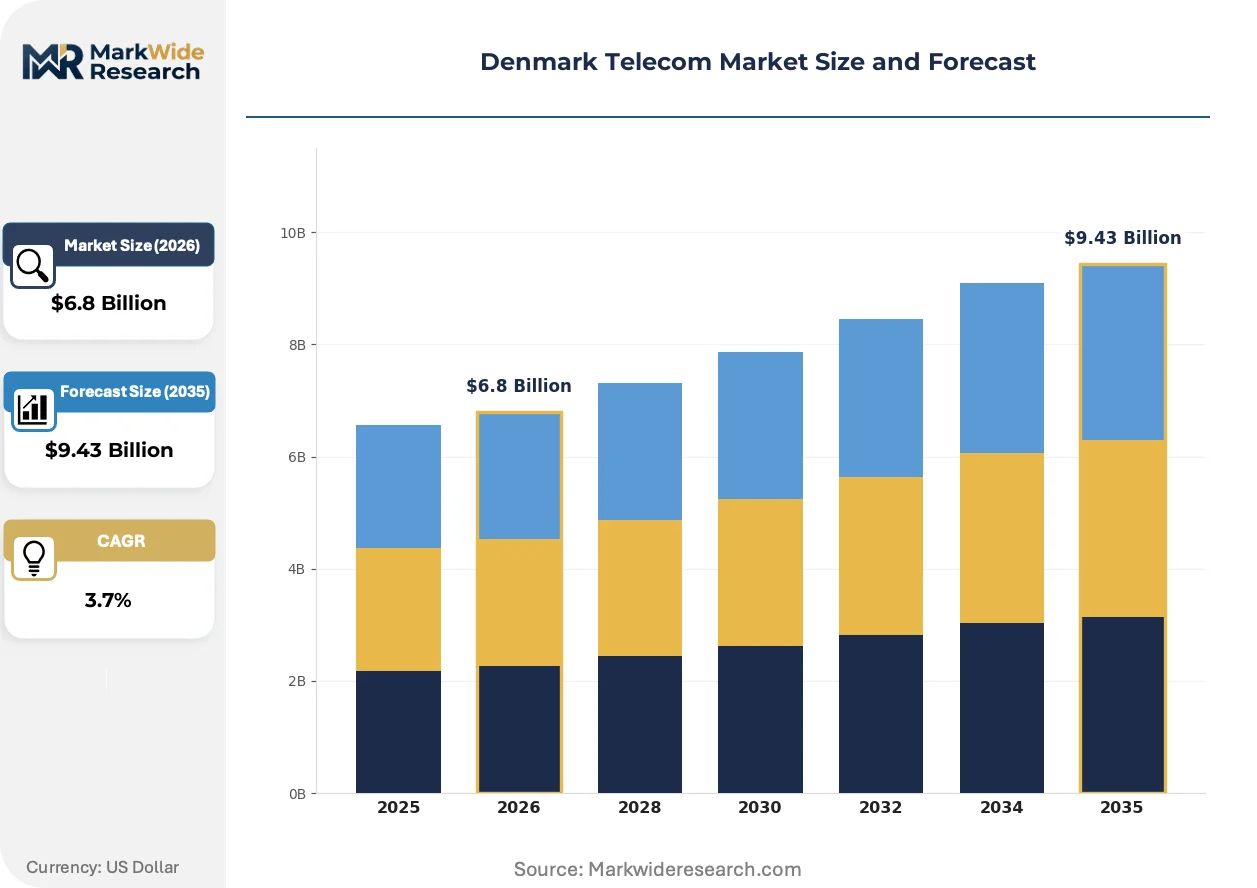
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 5G, 4G LTE, Fiber Optic, DSL Service Type: Mobile Voice, Mobile Data, Fixed Line, Internet Customer Type: Residential, SMB, Enterprises, Government Deployment Model: On-Premises, Cloud, Hybrid, Managed |
| Companies Covered | Nuuday, 3 Denmark, Kemp & Lauritzen AS, Hi3G Denmark, Telia Denmark, Telenor Denmark, TDC NET, RTX A/S, Norlys, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Telecom Market Trends and Innovations
XGS-PON fiber technology is replacing GPON across Danish operator access networks, doubling per-fiber capacity without new cable deployment. This transition compresses equipment refresh cycles while enabling 10 Gbps residential service tiers.
Passive optical networking is rendering obsolete traditional active Ethernet distribution in greenfield residential developments. TDC NET and regional utilities are deploying XGS-PON exclusively for new fiber-to-the-home builds, eliminating street-side powered cabinets. The shift reduces operational power consumption and fault points across Denmark's suburban expansion zones.
The Danish Business Authority's implementation of EU-wide cybersecurity certification schemes for 5G infrastructure is tightening vendor eligibility criteria. Operators must now document supply chain provenance and software bill of materials for core network elements. Equipment procurement teams are restructuring evaluation workflows to incorporate BIS security attestation requirements ahead of contract award.
Enterprise buyers are consolidating telecommunications spend under managed service contracts with outcome-based performance metrics. Danish logistics and pharmaceutical firms now specify application response time guarantees rather than bandwidth tiers, forcing operators to reengineer network monitoring and SLA reporting systems. This behavioral shift is most pronounced among Copenhagen-headquartered multinational corporations with distributed Nordic operations.
Denmark Telecom Market Segmentation
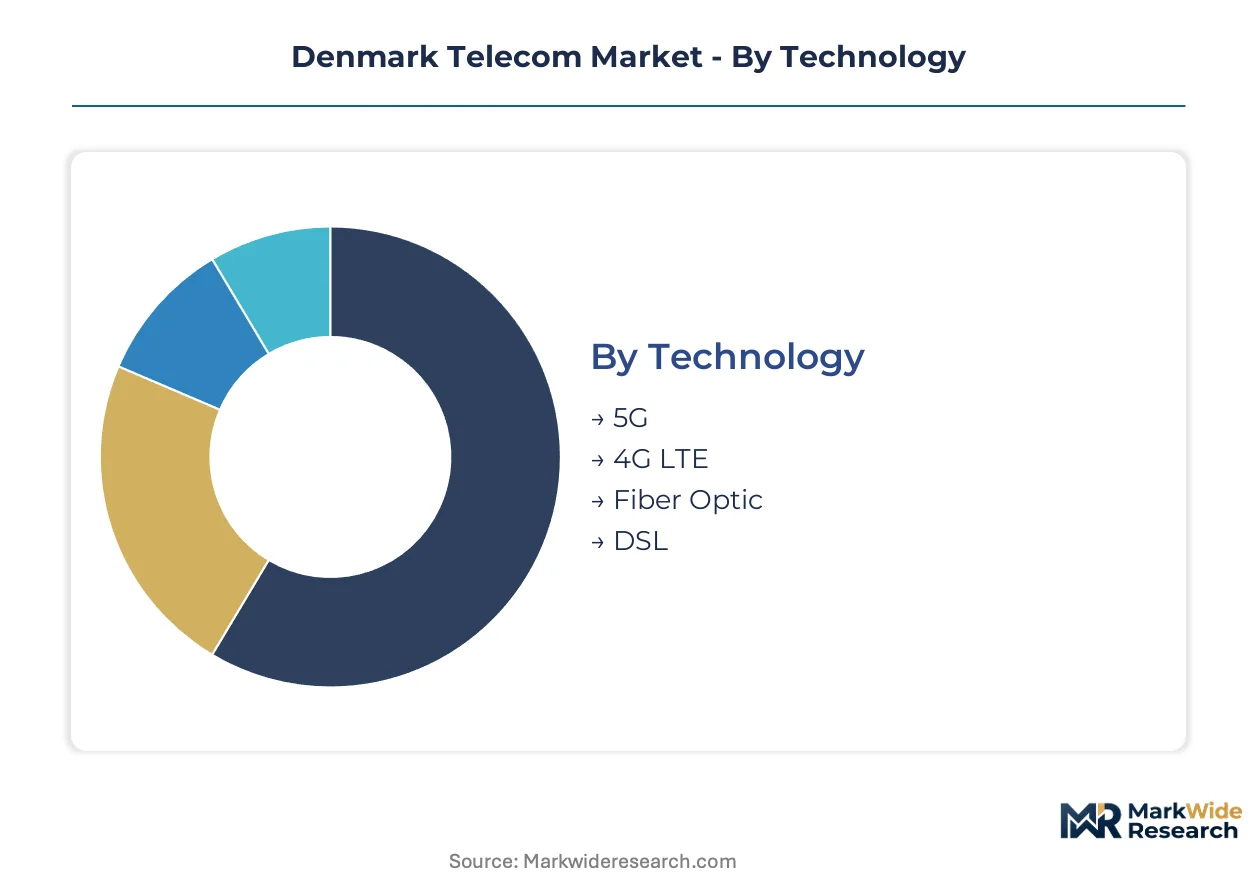
Denmark's telecom market exhibits distinct demand patterns across technology generations, service bundles, and customer tiers. Segmentation reveals where capital allocation concentrates and which infrastructure layers command premium pricing.
Technology:
Cost tier stratification separates legacy maintenance spend from next-generation deployment budgets.
- 5G:Millimeter-wave and sub-6 GHz deployments serve Copenhagen's dense urban corridors and industrial zones. Enterprise private networks in Odense and Aalborg drive site-specific densification beyond macro coverage.
- 4G LTE:Carrier aggregation and dynamic spectrum sharing extend utility as 5G fallback. Rural Jutland regions rely on LTE for voice continuity during fiber backhaul gaps.
- Fiber Optic:XGS-PON upgrades double per-fiber capacity across TDC NET's wholesale layer.
- DSL:Copper retirement timelines strand remaining DSL assets in Bornholm peripheries.
Fiber Optic holds installed capacity. 5G is rotating up the share rankings.
Service Type:
Application focus distinguishes consumption-heavy data services from stable voice and connectivity utilities.
- Mobile Data:Unlimited plan structures and video streaming dominate traffic profiles. Copenhagen's 5G corridor concentrates the heaviest per-user consumption loads.
- Internet:Symmetric fiber tiers replace copper-based broadband in suburban expansion zones. XGS-PON enables 10 Gbps residential offerings without cable replacement.
- Mobile Voice:PSTN switch-off mandates accelerate VoLTE migration.
- Fixed Line:Legacy POTS contracts diminish as operators enforce copper retirement.
Internet holds installed capacity. Mobile Data is rotating up the share rankings.
Customer Type:
Volume concentration varies sharply between mass-market residential and high-margin enterprise contracts.
- Enterprises:Cloud-managed WAN services with SLA guarantees command premium attach rates. Danish manufacturing and logistics firms specify application response metrics over raw bandwidth.
- Residential:Price-sensitive households drive unlimited mobile and gigabit fiber adoption. Copenhagen and Aarhus urban cores show highest penetration of converged service bundles.
- SMB:Hybrid connectivity packages combine fiber primary with 4G backup.
- Government:Public sector procurement emphasizes cybersecurity certification and open RAN interoperability.
Residential holds installed capacity. Enterprises is rotating up the share rankings.
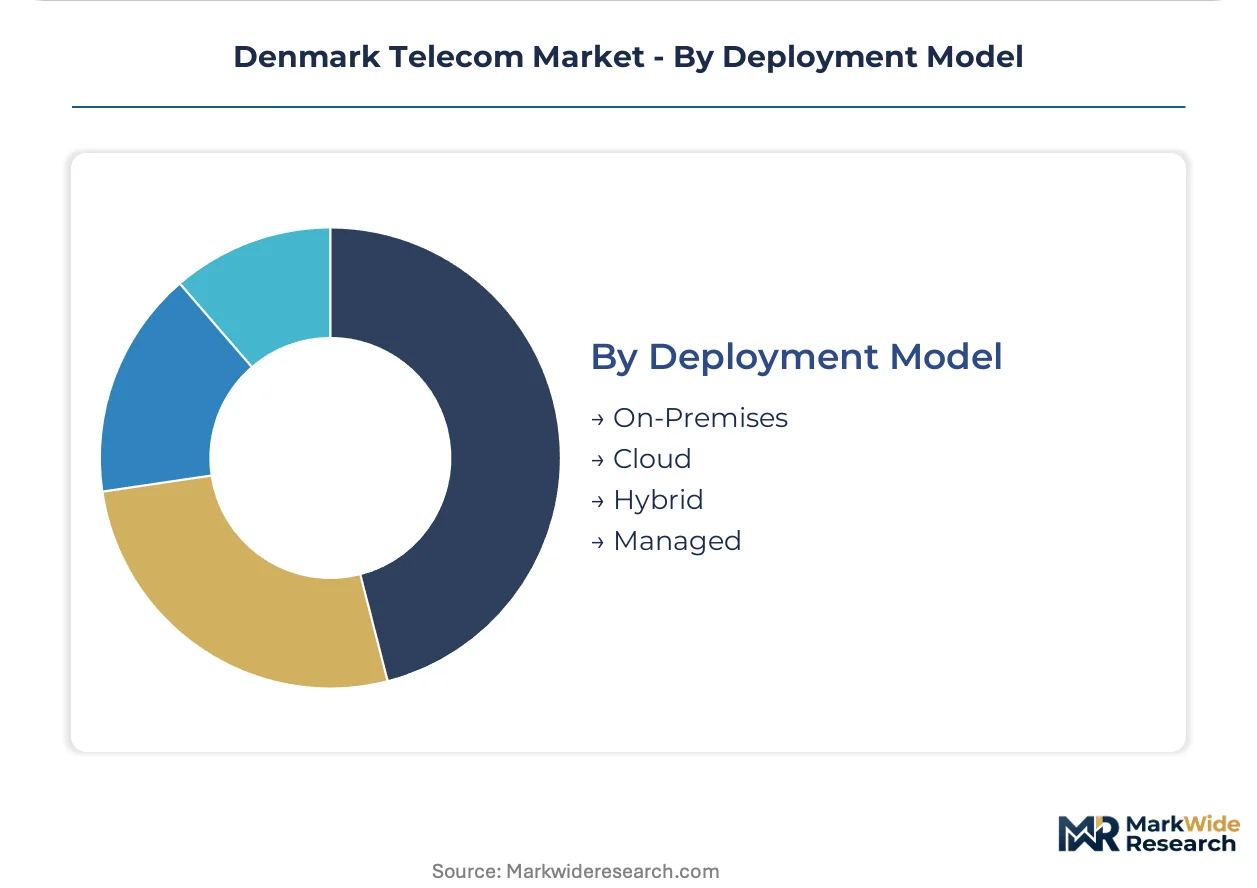
Deployment Model:
Maturity curves separate established on-premises infrastructure from cloud-native service delivery.
- Managed:Outcome-based contracts with performance SLAs consolidate enterprise telecom spend. Nuuday and Telia Denmark compete on application response guarantees rather than circuit speeds.
- Cloud:Cloud-managed WAN and SASE architectures displace premise-based security stacks. Danish pharmaceutical multinationals with Nordic distribution networks lead adoption.
- Hybrid:Split traffic routing balances latency-sensitive workloads against cost-optimized cloud paths.
- On-Premises:Legacy PBX and dedicated line contracts persist in regulated industries.
On-Premises holds installed capacity. Managed is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Danish Energy Agency anchors infrastructure governance across Denmark's five administrative regions, coordinating spectrum allocation and broadband deployment mandates through national policy frameworks that shape operator investment priorities.
Hovedstaden
Copenhagen's 5G corridor concentrates millimeter-wave densification and enterprise private network trials. The Danish Business Authority enforces cybersecurity certification for critical infrastructure operators headquartered in the capital region. Frederiksberg hosts TDC NET's network operations center managing wholesale fiber provisioning.
Midtjylland
Aarhus drives fiber-to-the-home expansion through municipal utility partnerships with regional energy cooperatives. The national broadband strategy mandates 100 Mbps universal coverage deadlines that accelerate trenching schedules in Central Jutland. Randers and Silkeborg anchor logistics firm demand for cloud-managed WAN services.
Syddanmark
Odense's industrial robotics cluster generates private 5G network specifications for automated manufacturing campuses. The Danish Energy Agency's 26 GHz spectrum release enables fixed wireless access in rural Funen peripheries where fiber economics falter. Esbjerg's renewable energy corridor attracts data center operators seeking carbon-free power purchase agreements.
Nordjylland
Aalborg's port and logistics infrastructure demands high-availability connectivity for supply chain digitization. Bornholm and smaller Baltic islands remain underserved, presenting submarine cable deployment opportunities. The Danish Business Authority's open RAN interoperability guidelines influence procurement decisions among municipal network operators.
Sjælland
Suburban Copenhagen spillover drives residential fiber adoption in Roskilde and Køge corridor developments. Regional utilities deploy XGS-PON exclusively for greenfield residential builds, eliminating street-side powered cabinets. Næstved hosts pharmaceutical distribution centers specifying application response time SLAs over raw bandwidth metrics.
Denmark Telecom Market Competitive Landscape
Capability concentration sits with infrastructure-owning incumbents; scale advantage sits with converged service retailers. Denmark's telecom structure tiers around wholesale fiber access, mobile network infrastructure, and retail service distribution. Three archetypes dominate: national infrastructure utilities with open-access fiber layers, integrated converged operators spanning fixed and mobile domains, and challenger mobile virtual network operators competing on price-positioned unlimited data plans. Competitive moves center on fiber co-investment partnerships for civil engineering cost sharing and managed service contract consolidation targeting enterprise verticals.
Within the integrated operator tier, Nuuday and Telia Denmark occupy positions as converged service providers leveraging infrastructure access for bundled residential and enterprise offerings. TDC NET anchors the wholesale infrastructure layer as the open-access fiber utility enabling retail competition without parallel network builds. These three entities exemplify the market's structural division between infrastructure ownership and service retailing.
| Leading Market Players |
|---|
| Nuuday |
| 3 Denmark |
| Kemp & Lauritzen AS |
| Hi3G Denmark |
| Telia Denmark |
| Telenor Denmark |
| TDC NET |
| RTX A/S |
| Norlys |
| Others |
Pricing and Supply Chain Analysis
BIS network security certification requirements for 5G infrastructure create a regulatory chokepoint that compresses vendor eligibility pools and simultaneously widens pricing spreads between certified and uncertified equipment tiers while forcing operators toward single-source dependencies that reshape procurement risk profiles.
Pricing Analysis
Copenhagen commands premium fiber connectivity pricing relative to rural Jutland regions where fixed wireless access substitutes constrain rate premiums. Three-tier pricing structure across premium, standard, and economy levels segments enterprise SLA-guaranteed services from residential gigabit tiers and basic mobile data plans. Price differentiation hinges on symmetric bandwidth guarantees and managed service attach rates. Cost compression in residential fiber is intensifying because open-access wholesale architecture enables retail competition without infrastructure duplication. SMB buyers exhibit highest price sensitivity, while enterprise manufacturing and logistics firms prioritize application response guarantees over per-megabit rates.
Supply Chain Analysis
Optical fiber feedstock and 5G RAN equipment manufacturing concentrates in China, South Korea, and Finland, with specialized XGS-PON chipset fabrication anchored in Taiwan and USA facilities. Danish operators draw from submarine cable landing stations in Esbjerg and Copenhagen for international bandwidth, while domestic civil engineering contractors supply trenching and splicing labor. Single-source vulnerability sits with millimeter-wave antenna suppliers approved under BIS certification schemes. Distribution runs through TDC NET's wholesale fiber layer to retail service providers, with direct vendor relationships for enterprise-grade equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as cloud-managed WAN services and private 5G networks threaten to disintermediate traditional connectivity revenues through verticalized enterprise solutions.
For Market Incumbents: Insulate core fiber infrastructure returns by accelerating XGS-PON deployment timelines and securing exclusive civil engineering partnerships in Copenhagen and Aarhus corridors. Deepen managed service penetration among Danish pharmaceutical and logistics firms to embed switching costs before challenger operators replicate SLA-guaranteed offerings. Vertical integration into field engineering capabilities addresses talent scarcity risks that delay rollout schedules.
For New Entrants and Emerging Players: Bornholm and smaller Baltic Sea islands represent the most penetrable entry point for first-mover fixed wireless or submarine cable deployments where fiber economics falter and incumbent coverage gaps persist. Private 5G network specifications from Odense's industrial robotics cluster offer enterprise vertical revenue streams beyond saturated consumer mobile markets. Go-to-market positioning should emphasize carbon-free power purchase alignment with Esbjerg's renewable energy corridor data center operators.
For Investors and Strategic Acquirers: The market sits at an infrastructure replacement phase that favors wholesale fiber utilities with open-access architecture and established civil engineering relationships over retail service providers facing margin compression. Long-term viability across the next decade hinges on spectrum position and fiber footprint depth rather than brand equity. Acquisition targets should demonstrate BIS certification compliance and XGS-PON deployment progress. The signal to watch is millimeter-wave spectrum auction participation rates as an indicator of competitive intensity for fixed wireless access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| XGS-PON Network Upgrade | Doubles per-fiber capacity without cable replacement, enabling 10 Gbps residential tiers. |
| Private 5G Network Deployment | Captures enterprise vertical revenue from Odense manufacturing and Aalborg logistics clusters. |
| Open RAN Interoperability Investment | Satisfies Danish Business Authority mandates while diversifying vendor pools beyond certified suppliers. |
| Renewable Energy Power Agreement | Differentiates data center hosting services in Esbjerg's carbon-free electricity cluster. |
| Island Connectivity Infrastructure | Secures first-mover advantage in Bornholm and Baltic Sea peripheries underserved by fiber. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, spectrum auction records, and infrastructure deployment databases. Primary interviews engaged network operations executives at wholesale fiber utilities, enterprise procurement leads at Danish manufacturing and logistics firms, civil engineering contractors specializing in urban trenching, and regulatory affairs specialists at the Danish Energy Agency. Secondary validation drew from Danish Business Authority cybersecurity certification disclosures, national broadband strategy implementation reports, and operator capex guidance filings. Bottom-up fiber deployment tracking and top-down service revenue estimates were triangulated to anchor market sizing.
Forecast inputs include technology generation transitions, service bundle migration patterns, customer tier spending shifts, and deployment model evolution across the projection horizon. Segmentation dimensions modeled encompass technology generation, service type, customer tier, and deployment architecture. CAGRs were derived from infrastructure investment run-rates and service adoption curves rather than extrapolated historical trends. Industry-specific forecast inputs incorporate spectrum reallocation timelines and copper retirement mandates from the national broadband strategy.
Practitioners should monitor BIS certification requirement expansions and millimeter-wave auction participation for early signals of vendor pool constraints and competitive intensity shifts. Forecasts reflect assumptions regarding civil engineering labor availability and municipal permitting timelines that could accelerate or delay fiber coverage targets. Cross-checking against Danish Energy Agency broadband coverage reporting is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
Qatar Telecom Market
Telecommunications
Denmark ICT Market
Telecommunications
Mexico Telecom Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
MVNO Market
Telecommunications
Indonesia ICT Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Cambodia ICT Market
Telecommunications
Dialer Market
Telecommunications
Argentina ICT Market
Telecommunications
Russia Telecom Market
Telecommunications
South Korea Telecom Market
Telecommunications
Private Branch Exchange Market