
 Czech Republic Telecom Market | 2026-2036
Czech Republic Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Czech Republic Telecom Market Insights
The EU Green Deal is repositioning telecom infrastructure procurement standards across Central Europe, compelling operators to reduce network energy intensity and disclose carbon footprints. O2 Czech Republic leverages its nationwide fiber backbone to sustain competitive positioning in enterprise connectivity. T-Mobile Czech Republic anchors market share through dense 5G site deployment in urban corridors. CETIN competes as the dominant wholesale infrastructure provider, controlling access pricing for retail operators.
Czech Republic Telecom encompasses the design, deployment, and commercial operation of wired and wireless communication systems delivering voice, data, and multimedia services across residential, enterprise, and public sector endpoints. The sector relies on fiber-optic transmission achieving sub-millisecond latency for financial trading platforms and cloud access. Mobile services dominate revenue generation, though fiber optic infrastructure captures the fastest expansion as enterprises abandon copper-based DSL. Business users concentrate margin pools through contracted service-level agreements and dedicated bandwidth provisioning, while residential users drive volume across bundled voice-data-video packages.
The Czech Telecommunication Office enforces net neutrality and spectrum allocation rules that shape operator investment timelines and service pricing. BIS certification requirements for network equipment create compliance barriers for non-EU vendors seeking market entry. The EU AI Act and GDPR impose data governance obligations on telecom-hosted cloud and IoT services, redirecting vendor development resources. Stakeholders must monitor spectrum auction schedules and wholesale access tariff revisions to anticipate competitive repositioning.
Market Dynamics
The Czech Republic telecom sector is absorbing structural pressure from the EU Green Deal's energy efficiency mandates, which are rewriting procurement criteria for network infrastructure and forcing operators to accelerate fiber densification while retiring legacy copper assets.
Growth Catalysts
- EU Green Deal compliance:The framework mandates carbon footprint disclosure and energy intensity reductions, compelling operators to modernize infrastructure and creating replacement demand for efficient transmission equipment.
- Manufacturing SME cloud adoption:Industrial enterprises in the Central Bohemian Region are migrating operations to cloud platforms, driving contracted fiber connectivity and dedicated bandwidth provisioning.
- Open RAN architecture:Disaggregated radio access networks are lowering vendor lock-in and enabling multi-vendor deployments that accelerate 5G site rollout timelines.
Market Restraints
- Copper retirement costs:Legacy DSL infrastructure decommissioning requires substantial labor and materials expenditure, compressing operator margins during transition periods.
- Wholesale access dependency:CETIN's dominance in fiber backhaul pricing creates structural margin pressure for retail operators unable to bypass incumbent infrastructure.
- Spectrum scarcity:Limited mid-band allocation constrains 5G capacity expansion in dense urban corridors where mobile data consumption concentrates.
Strategic Opportunities
- Industrial IoT convergence:Manufacturing automation in Plzeň and Ostrava is creating demand for private 5G networks and edge computing nodes co-located with production facilities.
- GDPR-compliant cloud hosting:Data sovereignty requirements under EU regulation are redirecting enterprise workloads to domestic data centers, expanding colocation and interconnect revenue pools.
- Smart city infrastructure:Municipal governments in Brno and Liberec are procuring integrated fiber-IoT platforms for traffic management and public safety applications.
Industry Challenges
- Fiber splicing technician shortage:Specialized field engineering capacity constraints are extending deployment timelines for last-mile connections in secondary cities.
- Legacy billing system integration:Operator migration to cloud-native OSS/BSS platforms encounters friction with entrenched customer data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Czech Republic Telecom Market |
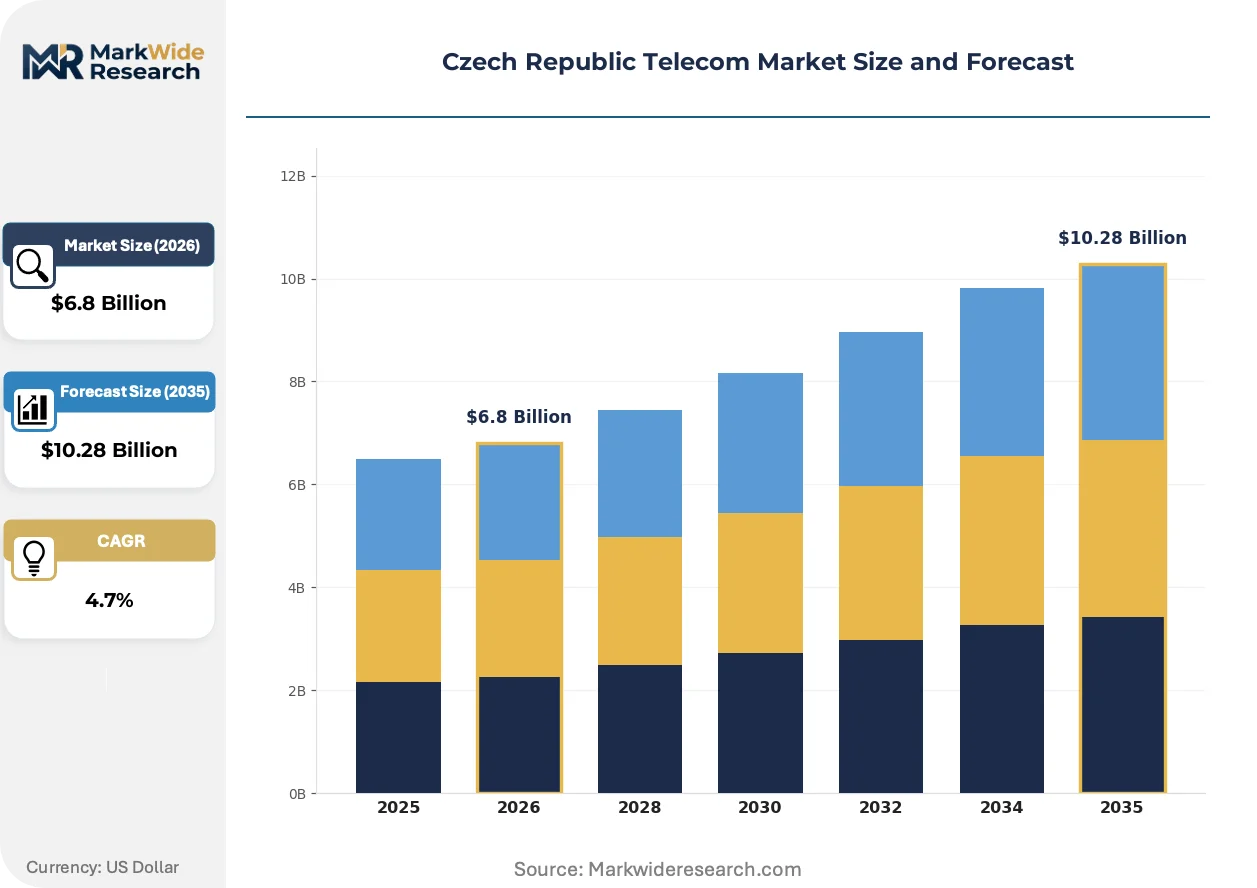
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed Line Services, Data Services, VoIP Services Customer Type: Residential Users, Business Users, Government Bodies, Educational Institutions Technology: 4G LTE, 5G, Fiber Optic, DSL Application: Voice Communication, Internet Access, Video Streaming, Cloud Services |
| Companies Covered | O2 Czech Republic, T-Mobile Czech Republic, Vodafone Czech Republic, CETIN, GTS Czech, Nordic Telecom, PODA a.s., Nej.cz, Starnet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Czech Republic Telecom Market Trends and Innovations
Technology convergence and regulatory pressure are restructuring how Czech operators architect networks and commercialize connectivity. Three developments are compressing traditional deployment models and opening alternative service paradigms.
XGS-PON fiber technology is absorbing enterprise demand previously served by dedicated leased lines. Financial services firms in Prague are adopting symmetric 10 Gbps passive optical networks for trading floor connectivity. The technology is absorbing premium enterprise revenue streams as operators bundle guaranteed latency tiers over shared infrastructure.
CSRD sustainability disclosure rules are mandating granular energy reporting from network operators. The Czech Telecommunication Office is aligning certification requirements with EU standardization, forcing equipment vendors to document lifecycle emissions. Wholesale infrastructure providers face the steepest compliance burden as their asset bases attract heightened scrutiny under the directive.
Enterprise buyers are consolidating vendor relationships around integrated connectivity-cloud-security stacks. Manufacturing customers in the automotive supply chain are abandoning point-solution procurement for single-contract managed services. This concentration is most visible in the Central Bohemian Region, where tier-one suppliers are negotiating multi-site framework agreements with integrated service level guarantees.
Czech Republic Telecom Market Segmentation
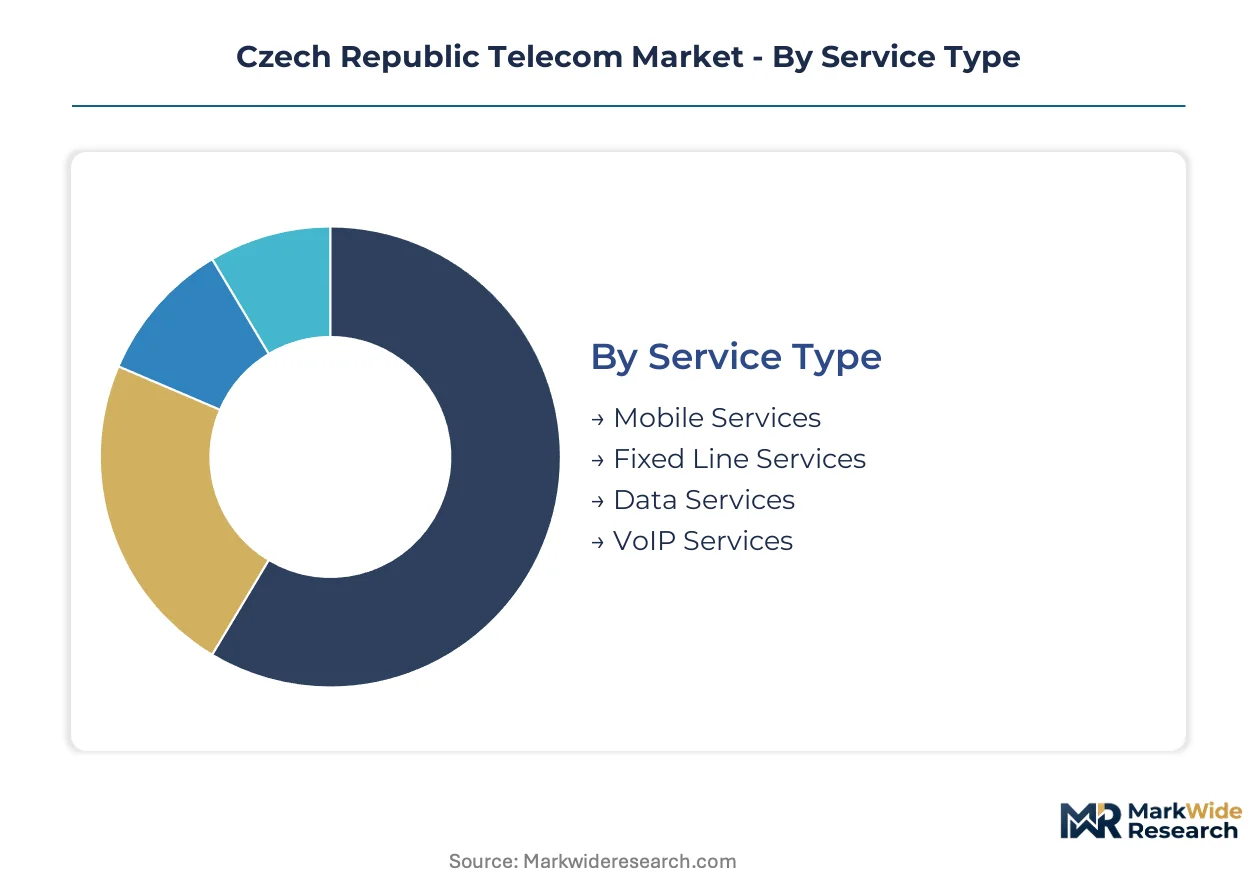
Segmentation reveals how Czech operators allocate capital across divergent margin pools. Service mix determines infrastructure investment priority, while customer type shapes contract structure and churn risk.
Service Type:
Supply concentration in fiber backhaul tilts competitive advantage toward integrated operators with owned infrastructure.
- Mobile Services:Wireless voice and data subscriptions generate recurring revenue through spectrum-dependent radio access networks. Prague and Brno concentrate data consumption, with EU Green Deal energy mandates forcing base station modernization.
- Fixed Line Services:Traditional copper-based telephony and leased circuits face accelerated retirement as CETIN's wholesale pricing structure renders retail economics unsustainable for voice-only products.
- Data Services:Dedicated internet access and MPLS connectivity for enterprises command premium pricing through service-level agreements.
- VoIP Services:Session-initiated protocol voice replaces legacy PSTN, bundling into converged packages for residential and SOHO segments.
Today's leader: Mobile Services. Tomorrow's challenger: Data Services.
Customer Type:
Contract value and technical sophistication separate procurement patterns across buyer categories.
- Residential Users:Mass-market consumers purchase bundled voice-data-video packages through standardized pricing tiers. Churn sensitivity concentrates in Prague's competitive urban corridors.
- Business Users:Enterprises in the Central Bohemian Region negotiate multi-site framework agreements with guaranteed latency and dedicated bandwidth provisioning.
- Government Bodies:Public sector procurement follows EU public procurement directives with mandatory sustainability disclosure under CSRD rules.
- Educational Institutions:Universities and research facilities demand high-capacity research networks with international peering for academic collaboration.
Business Users capture the steepest expansion trajectory as manufacturing cloud adoption accelerates.
Technology:
Legacy asset retirement costs dominate operator capex allocation decisions.
- 4G LTE:Mature radio access technology carries majority of mobile traffic while operators densify 5G overlay. Spectrum refarming pressures remaining mid-band allocations.
- 5G:New radio standards enable network slicing and ultra-reliable low-latency communication for industrial automation in Plzeň and Ostrava manufacturing zones.
- Fiber Optic:XGS-PON and point-to-point fiber absorb enterprise demand previously served by copper leased lines.
- DSL:Asymmetric digital subscriber line infrastructure faces mandated decommissioning under EU digital decarbonization timelines.
Fiber Optic commands current investment priority. 5G offers the most significant capability upgrade path.
Application:
Bandwidth intensity and latency sensitivity determine transport architecture requirements.
- Voice Communication:Circuit-switched and packetized voice services migrate to all-IP infrastructure with quality-of-service prioritization.
- Internet Access:Broadband connectivity spans asymmetric residential products to symmetric enterprise dedicated access.
- Video Streaming:Over-the-top video consumption drives peak traffic engineering and caching node placement.
- Cloud Services:Enterprise SaaS and IaaS access requires sub-millisecond latency for financial trading platforms and real-time manufacturing control systems.
Internet Access anchors volume. Cloud Services delivers the highest value per bit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fiber splicing technicians and network engineers concentrate in Prague and Brno, anchoring deployment capacity for infrastructure expansion across the Czech Republic's primary economic corridors.
Prague
Financial services firms and technology headquarters drive premium connectivity demand through low-latency fiber requirements. The Czech Telecommunication Office enforces net neutrality and spectrum rules that shape operator investment timelines. Enterprise data centers in Prague 4 and Prague 8 host GDPR-compliant cloud workloads for multinational corporations.
Central Bohemian Region
Manufacturing SMEs accelerate cloud adoption for production automation and supply chain digitization. EU Green Deal energy efficiency mandates compel infrastructure modernization across industrial zones. Automotive suppliers in Mladá Boleslav and Kladno negotiate multi-site framework agreements with guaranteed bandwidth provisioning.
Brno
Research institutions and smart city initiatives generate demand for high-capacity academic networks and integrated fiber-IoT platforms. CSRD sustainability disclosure rules mandate granular energy reporting from municipal network operators. The Brno Technology Park anchors private 5G network trials for industrial automation applications.
Plzeň
Heavy manufacturing and engineering clusters create demand for private 5G networks and edge computing nodes co-located with production facilities. BIS certification requirements for network equipment filter vendor participation in critical infrastructure procurement. Škoda Auto's supply chain ecosystem drives contracted fiber connectivity for real-time manufacturing control systems.
Ostrava
Steel industry modernization and logistics hubs generate industrial IoT convergence opportunities for automation and predictive maintenance. Spectrum scarcity in mid-band allocations constrains 5G capacity expansion despite concentrated mobile data consumption. The Ostrava-Karviná industrial zone hosts edge computing deployments for manufacturing process optimization.
Czech Republic Telecom Market Competitive Landscape
Capital-heavy infrastructure owners compete with asset-light retail service providers for margin capture in the Czech Republic telecom sector. O2 Czech Republic, T-Mobile Czech Republic, and CETIN anchor a consolidated structure where wholesale access pricing shapes retail economics. Three archetypes dominate: integrated operators with owned fiber backhaul, mobile-first retailers dependent on wholesale infrastructure, and specialized wholesale infrastructure providers controlling access pricing. Competitive repositioning concentrates on fiber densification timelines and 5G site rollout density in urban corridors.
Within the integrated operator tier, O2 Czech Republic and T-Mobile Czech Republic exemplify players leveraging nationwide infrastructure for enterprise connectivity positioning. CETIN occupies the dominant wholesale infrastructure provider position, controlling access pricing that structures retail operator margins. Among specialized retailers, Vodafone Czech Republic represents the mobile-first archetype navigating wholesale dependency through dense 5G deployment strategies.
| Leading Market Players |
|---|
| O2 Czech Republic |
| T-Mobile Czech Republic |
| Vodafone Czech Republic |
| CETIN |
| GTS Czech |
| Nordic Telecom |
| PODA a.s. |
| Nej.cz |
| Starnet |
| Others |
Pricing and Supply Chain Analysis
XGS-PON fiber deployment across Czech industrial zones is compressing per-bit delivery costs while concentrating procurement leverage among operators with captive fiber backhaul. This technology transition simultaneously reduces marginal transmission expense and reinforces CETIN's structural position as the dominant wholesale infrastructure gatekeeper.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels structures Czech telecom revenue capture. Price differentiation hinges on guaranteed latency tiers and BIS certification status of network equipment. Pricing pressure stems from wholesale access dependency as retail operators absorb CETIN's fiber backhaul tariffs. Residential subscribers exhibit highest price sensitivity, while financial services firms in Prague tolerate premium tiers for sub-millisecond connectivity.
Supply Chain Analysis
Optical transceiver supply rests on Chinese and Taiwanese component manufacturers, with European fiber cable production anchored in Germany and the Netherlands. Network equipment draws from Finnish, Swedish, and South Korean vendors, while specialized splicing hardware sources from Japanese precision toolmakers. Single-source vulnerability concentrates in 400G coherent optics modules. Distribution runs through CETIN's wholesale infrastructure layer before retail operator handoff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Czech Republic telecom market compounds steadily as EU Green Deal compliance mandates perpetuate infrastructure replacement cycles. Manufacturing SME cloud adoption sustains enterprise connectivity demand across the Central Bohemian Region.
For Market Incumbents: Deepen fiber densification in secondary cities to preempt emerging retail competitors. CETIN's wholesale pricing power threatens margin compression; operators should prioritize backward integration into last-mile fiber assets. Accelerate XGS-PON rollout to capture manufacturing enterprise demand migrating from copper leased lines. For New Entrants and Emerging Players: Municipal smart city procurement teams represent the most penetrable channel partner type for specialized IoT connectivity vendors. Secondary cities including Liberec and Ostrava exhibit underserved demand for integrated fiber-IoT platforms. Position around GDPR-compliant edge computing nodes co-located with manufacturing facilities. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light retail operators facing wholesale access dependency. The five-to-ten year viability window favors infrastructure owners with captive fiber backhaul. Watch spectrum auction schedules and wholesale tariff revision timing as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Densification Program | XGS-PON deployment captures manufacturing enterprise demand previously served by copper infrastructure. |
| Private 5G Network Deployment | Industrial automation in Plzeň and Ostrava creates captive connectivity revenue with guaranteed SLAs. |
| GDPR-Compliant Cloud Hosting | Data sovereignty requirements redirect enterprise workloads to domestic Prague data center facilities. |
| Energy Efficiency Certification | CSRD disclosure rules force equipment vendors to document lifecycle emissions for network infrastructure. |
| Smart City Infrastructure Partnership | Municipal procurement in Brno and Liberec integrates fiber transport with IoT traffic management platforms. |
Research Methodology
Coverage spans the Czech Republic's primary economic corridors, with primary inputs from each region combined with secondary validation. Network planning executives at integrated operators, wholesale infrastructure managers, manufacturing IT directors in the Central Bohemian Region, and Czech Telecommunication Office regulatory staff contributed primary perspectives. Secondary sources include CTU spectrum allocation records, EU Green Deal implementation guidelines, CETIN wholesale tariff disclosures, and operator sustainability reports under CSRD rules. Bottom-up service revenue modeling triangulates against top-down infrastructure investment tracking.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions encompass service type, customer category, technology generation, and application bandwidth intensity. CAGRs derive from subscriber growth trajectories, ARPU evolution by tier, and infrastructure deployment schedules. Forecast inputs incorporate spectrum auction timing, EU digital decarbonization mandates, and manufacturing automation adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to wholesale access tariff revisions and spectrum allocation decisions. Assumptions reflect current regulatory trajectories and infrastructure investment commitments. A small set of named triggers warrants ongoing watch: CETIN pricing policy shifts, mid-band spectrum release schedules, and EU energy efficiency standard tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Egypt ICT Market
Telecommunications
Egypt Telecom Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Tetra Terminals Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
5G Transport Networks Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
Global Telecommunication Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
Telecom Expense Management Market
Telecommunications
China ICT Market
Telecommunications
South Korea Telecom Market
Telecommunications
Global 5G Services Market
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Global Cognitive Radio Market