
 CDMA Mobile Phone Market | 2026-2036
CDMA Mobile Phone Market Size, Share, and Industry Trends Forecast 2026-2036
CDMA Mobile Phone Market Analysis
FCC Part 27 spectrum certification is reorganizing vendor eligibility for CDMA equipment supply to North American carriers. Qualcomm sustains its baseband chipset dominance through captive integration with EV-DO Rev. B modems. ZTE Corporation anchors production scale for CDMA2000 infrastructure across Asia-Pacific legacy networks. Samsung Electronics competes in ruggedized feature phone segments where military-grade durability requirements persist.
CDMA mobile phones employ code-division multiple access spread-spectrum technology, transmitting voice and data across 1.25 MHz channels using unique pseudorandom codes with chip rates of 1.2288 Mcps for IS-95 and CDMA2000 1x standards. These devices primarily serve legacy voice networks, narrowband machine-to-machine communications, and specialized government systems where backward compatibility outweighs LTE migration costs. Feature phones retain structural importance in the product type dimension as emerging market carriers monetize ultra-low ARPU subscriber bases with sub-$15 hardware. The technology dimension shows CDMA2000 1xEV-DO commanding residual margin pools in maritime and remote telemetry applications where satellite backhaul costs prohibit LTE deployment.
FCC equipment authorization procedures, China's MIIT radio transmission equipment type approval, and India's WPC frequency allocation rules collectively constrain which hardware variants achieve commercial distribution. FCC 3G sunset mandates directly compress carrier capex timelines for CDMA network maintenance. Stakeholders must weigh spectrum refarming economics against stranded asset risk in subscriber bases where device replacement cycles exceed seven years.
Market Dynamics
Carrier decisions on spectrum refarming versus stranded asset preservation dominate competitive positioning as CDMA networks approach end-of-life thresholds in multiple jurisdictions. Equipment vendors face compressed replacement cycles while serving subscriber bases with extended device refresh intervals.
Growth Catalysts
- Rural infrastructure mandates:India's TRAI universal service obligations compel carriers to maintain voice coverage in remote districts where CDMA base stations deliver cost-effective narrowband connectivity.
- Industrial IoT protocols:CDMA2000 1xEV-DO modems power maritime telemetry and remote pipeline monitoring where satellite backhaul economics favor legacy cellular over LTE deployment.
- Government system refresh cycles:Defense and public safety agencies in China specify CDMA2000 for secure voice handsets, creating captive demand insulated from consumer technology migration.
Market Restraints
- Input cost volatility:Qualcomm baseband chipset allocation prioritizes 5G and LTE volumes, constraining CDMA component availability and elevating unit costs for low-volume orders.
- Regulatory friction:FCC Part 27 certification reorganization disqualifies smaller vendors from North American carrier supply chains, concentrating equipment sourcing among legacy-qualified manufacturers.
- Substitution threat:NB-IoT and LTE-M modules displace CDMA2000 in machine-to-machine applications where carriers have completed 4G network overlays.
Strategic Opportunities
- Underpenetrated government verticals:India's defense procurement channels specify ruggedized CDMA handsets for border patrol units operating beyond LTE coverage footprints.
- Technology convergence:Dual-mode CDMA-LTE chipsets enable carriers to sunset 2G while preserving CDMA voice roaming agreements with rural partners.
- Regulatory tailwind:China's MIIT radio equipment type approval streamlines domestic CDMA2000 infrastructure deployment for industrial private networks.
Industry Challenges
- RF engineering talent scarcity:Spread-spectrum optimization expertise concentrates among retiring engineers, complicating network maintenance for carriers with aging CDMA installations.
- Certification timeline compression:FCC 3G sunset deadlines compress equipment authorization windows, forcing vendors to parallel-track regulatory submissions across multiple carrier specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CDMA Mobile Phone Market |
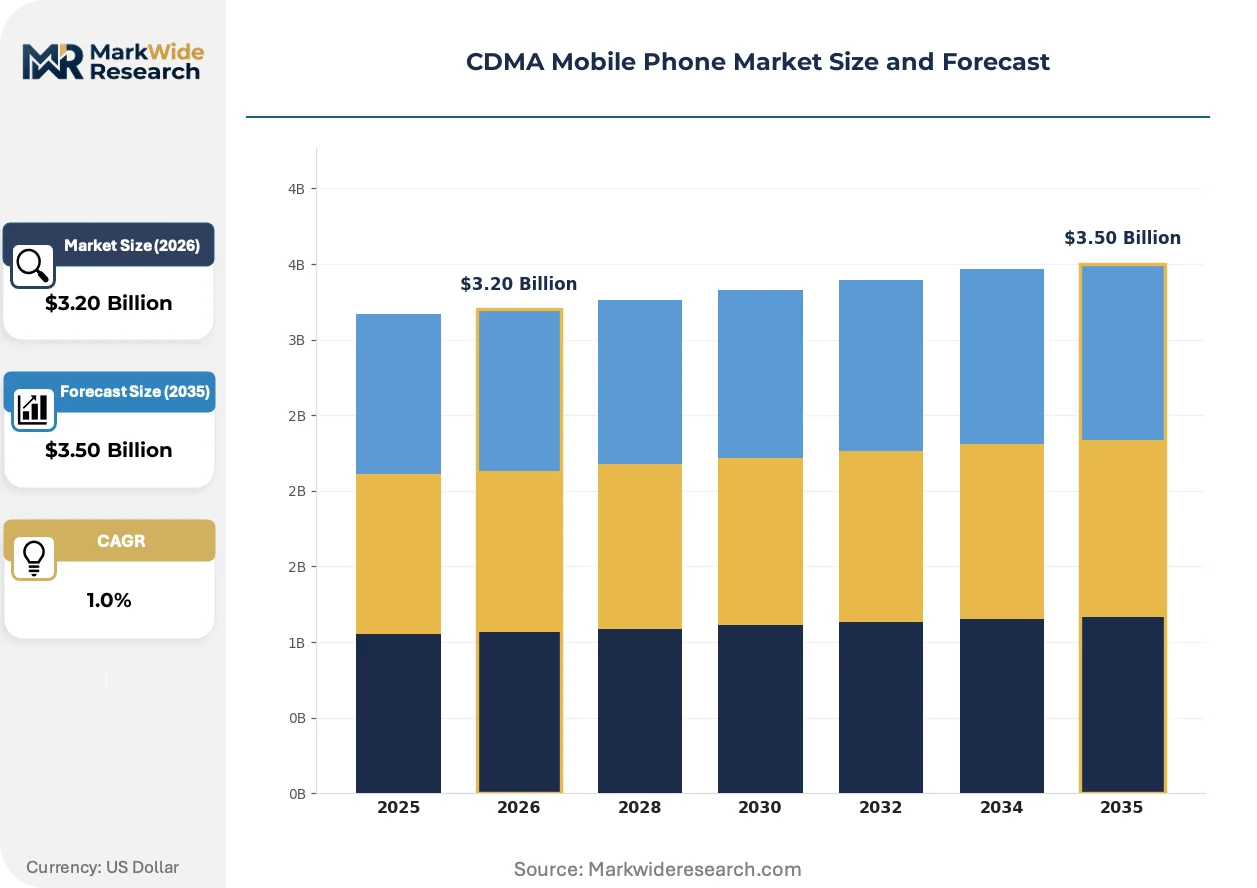
| Market Size in 2026 | $3.20 Billion |
| Market Size in 2035 | $3.50 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Feature Phones, Tablets, Modems End User: Consumers, Enterprises, Government, Educational Institutions Technology: 3G, 4G LTE, CDMA2000, EV-DO Distribution Channel: Online Retail, Offline Retail, Direct Sales, Resellers |
| Companies Covered | ZTE Corporation, Motorola, Qualcomm, Kyocera, TCL, Samsung Electronics, Huawei, Nokia, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CDMA Mobile Phone Market Emerging Trajectories
Technology transition pressures and regulatory phase-out timelines are compressing the viable operational window for CDMA networks. Vendors and carriers alike must navigate equipment sourcing constraints while serving residual demand pockets.
Multi-mode baseband architectures that combine CDMA2000 1x and EV-DO Rev. B with LTE fallback are supplanting single-protocol designs in ruggedized handset development. Defense contractors and industrial equipment manufacturers specify these chipsets to ensure connectivity across heterogeneous network coverage. The structural consequence is extended production runs for CDMA-capable silicon that would otherwise face immediate obsolescence.
China's MIIT radio transmission equipment type approval framework now expedites CDMA2000 infrastructure certifications for domestic industrial deployments. Manufacturers serving smart grid and remote telemetry verticals benefit from streamlined homologation timelines. Private network operators in western provinces exploit this regulatory efficiency to deploy CDMA-based narrowband systems ahead of full LTE coverage.
Carrier procurement patterns now emphasize multi-year spare parts commitments over volume handset purchases. Network maintenance teams in India's rural circles negotiate captive supplier agreements to secure base station component availability through 2030. This behavioral shift reflects stranded asset risk management rather than technology expansion, with procurement contracts structured around obsolescence mitigation rather than growth enablement.
CDMA Mobile Phone Market Segmentation
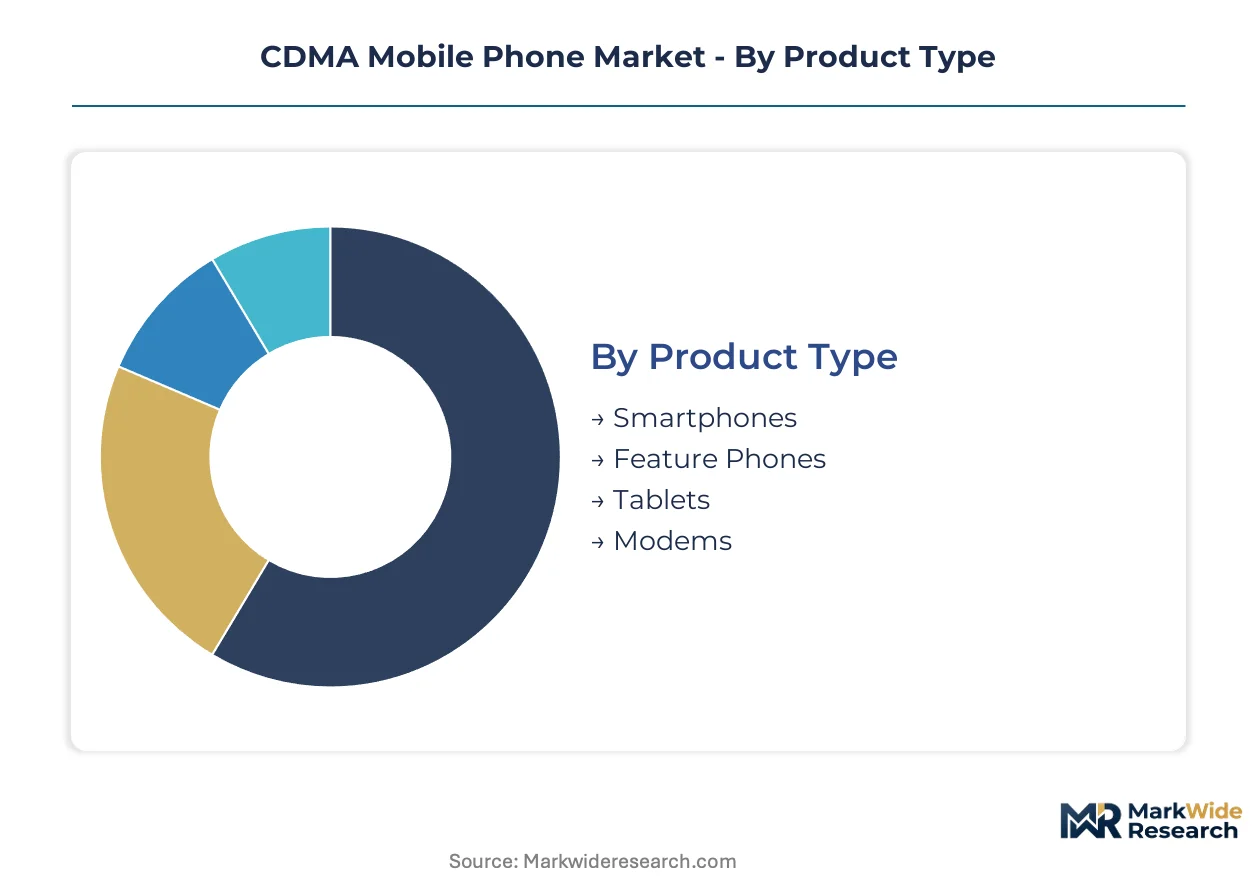
CDMA mobile phone segmentation reveals how legacy technology fragments across diverging use cases. Product architecture, end-user requirements, and channel economics each create distinct margin architectures that vendors must navigate as networks sunset.
Product Type:
Margin pools concentrate in specialized hardware where backward compatibility commands pricing premiums over commoditized alternatives.
- Feature Phones:These devices employ single-mode CDMA2000 1x basebands with minimal application processing, optimized for voice reliability and extended battery life. Demand clusters in India's rural telecommunications circles where TRAI universal service obligations sustain sub-$15 hardware procurement. Carriers monetize ultra-low ARPU subscriber bases through subsidized distribution.
- Modems:Industrial-grade EV-DO Rev. B modules integrate ruggedized enclosures and extended temperature specifications for telemetry applications. Maritime and remote pipeline monitoring systems in China's western provinces favor these units where satellite backhaul costs prohibit LTE deployment.
- Smartphones:Dual-mode CDMA-LTE architectures dominate this segment, enabling carriers to preserve voice roaming agreements while migrating data traffic.
- Tablets:Enterprise field-service deployments represent the primary demand channel, with government agencies specifying secure CDMA connectivity for classified environments.
The dominant share belongs to Feature Phones, while Modems are closing the gap fastest.
End User:
Procurement authority and device refresh cycles diverge sharply across customer categories, creating tiered pricing structures.
- Government:Defense and public safety agencies in China specify CDMA2000 for secure voice handsets with hardware encryption modules. MIIT radio equipment type approval streamlines domestic procurement channels, insulating this segment from consumer technology migration.
- Enterprises:Industrial IoT deployments in maritime logistics and energy infrastructure sustain narrowband machine-to-machine orders. FCC Part 27 certification requirements constrain vendor eligibility, concentrating supply among legacy-qualified manufacturers.
- Consumers:Rural subscriber bases in India drive residual demand through carrier-subsidized feature phone programs.
- Educational Institutions:Limited deployments focus on secure campus communications in remote locations beyond LTE coverage.
Government procurement maintains the highest margin tier, with Enterprise demand expanding most quickly through industrial IoT integration.
Technology:
Protocol architecture determines component sourcing constraints and equipment authorization complexity across regulatory jurisdictions.
- CDMA2000:The 1x standard employs 1.2288 Mcps chip rates across 1.25 MHz channels, optimized for voice circuit switching. India's rural infrastructure mandates sustain base station deployments where narrowband connectivity satisfies universal service obligations.
- EV-DO:Evolution-Data Optimized Rev. B delivers peak downlink rates through multi-carrier aggregation, serving telemetry applications where bandwidth requirements exceed 1x capacity. Maritime operators in Chinese coastal provinces specify these modems for vessel tracking systems.
- 3G:Legacy IS-95A/B networks persist in minimal maintenance mode with no new infrastructure deployment.
- 4G LTE:Dual-mode implementations enable carriers to sunset 2G while preserving CDMA voice roaming with rural partners.
CDMA2000 retains the largest installed base, though EV-DO is gaining share fastest in industrial telemetry verticals.
Distribution Channel:
Channel selection reflects customer scale, technical support requirements, and regulatory documentation needs.
- Direct Sales:Carrier procurement teams negotiate multi-year spare parts commitments with equipment vendors. Network maintenance agreements in India's rural circles secure base station component availability through extended timelines.
- Offline Retail:Branded carrier stores and authorized dealers distribute consumer feature phones with subsidy lock-in. Physical presence remains essential for subscriber identity verification and SIM provisioning.
- Online Retail:Enterprise buyers procure ruggedized handsets and modems through B2B platforms with technical specification filtering.
- Resellers:Systems integrators bundle CDMA hardware with private network deployment services for industrial clients.
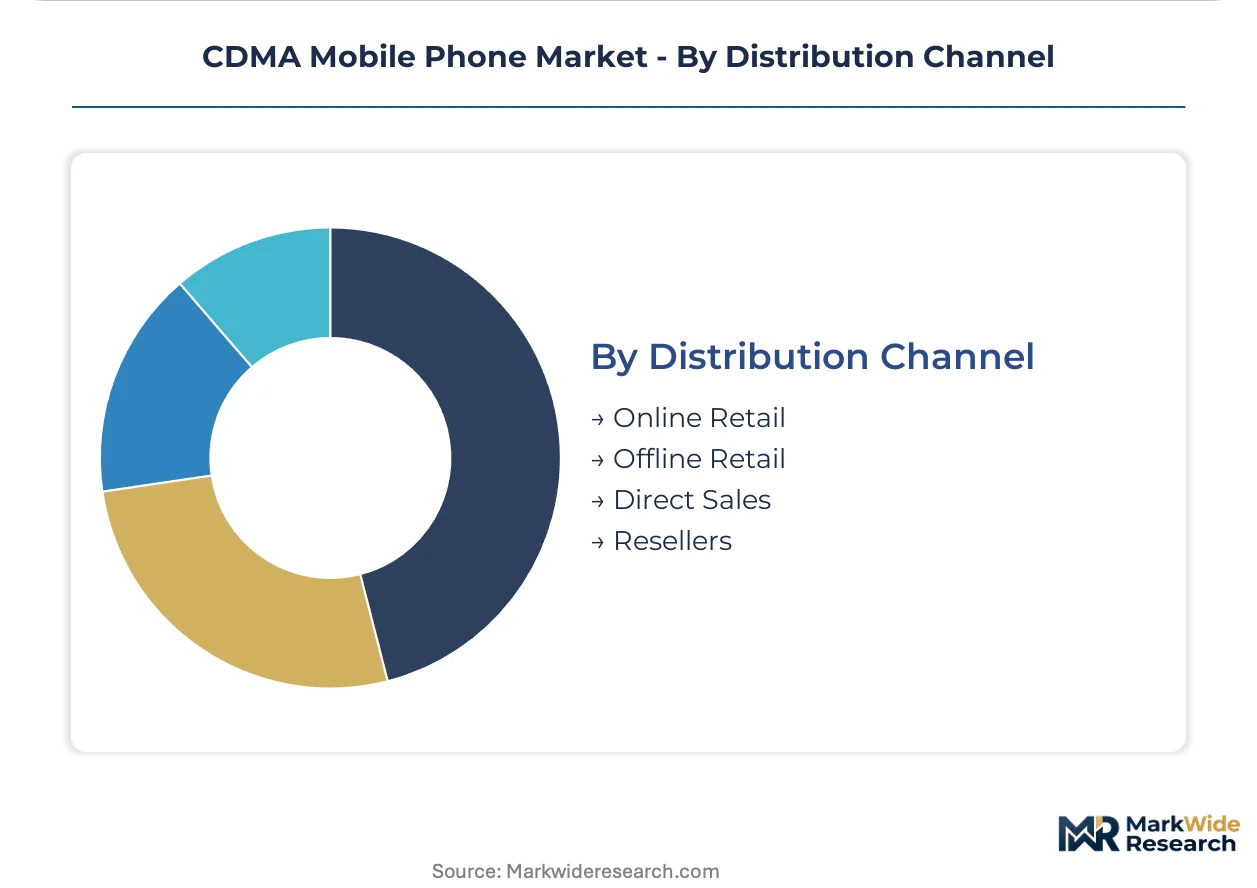
Direct Sales captures the highest value per transaction, while Resellers are climbing the fastest through systems integration bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government mandates to preserve rural voice connectivity and defense procurement specifications sustain residual CDMA infrastructure across multiple jurisdictions. FCC sunset timelines in the United States compress carrier migration decisions, while India's universal service obligations compel continued narrowband network maintenance.
United States
Carrier spectrum refarming economics dominate equipment procurement as FCC Part 27 certification reorganization narrows vendor eligibility. The FCC's 3G sunset timeline accelerates infrastructure decommissioning in urban markets while preserving rural CDMA voice roaming. Defense contractors in Virginia and Maryland specify secure CDMA handsets for classified communications environments.
China
Industrial private networks and government secure voice systems anchor domestic demand for CDMA2000 infrastructure. MIIT radio transmission equipment type approval streamlines certification timelines for western province deployments. ZTE and Huawei production facilities in Shenzhen and Chengdu serve domestic CDMA2000 base station and handset orders.
India
TRAI universal service obligations compel carriers to maintain voice coverage in remote districts where CDMA base stations deliver cost-effective connectivity. WPC frequency allocation rules govern equipment import and commercial distribution authorization. Rural telecommunications circles in Rajasthan and Madhya Pradesh sustain sub-$15 feature phone procurement programs.
Japan
Maritime telemetry and remote industrial monitoring sustain EV-DO module demand where satellite backhaul costs exceed cellular economics. METI industrial standards coordination influences equipment specification for private network deployments. Coastal prefectures including Aichi and Hiroshima host maritime logistics operators specifying CDMA2000 vessel tracking systems.
South Korea
Defense and public safety agencies specify ruggedized CDMA handsets for secure communications in mountain and coastal zones beyond LTE coverage. The national spectrum regulator governs equipment authorization for military-grade devices. Industrial clusters in Gyeonggi-do and Busan-Ulsan manufacture dual-mode CDMA-LTE chipsets for government procurement channels.
CDMA Mobile Phone Market Vendor Landscape
Listed leaders compete with private specialists across baseband silicon and infrastructure equipment segments. Qualcomm sustains captive integration dominance through EV-DO Rev. B modem production, while ZTE Corporation and Huawei anchor scale manufacturing for Asia-Pacific legacy networks. The competitive structure rewards backward integration into chipset design and multi-year spare parts commitments for carrier maintenance contracts. Strategic moves concentrate on dual-mode CDMA-LTE chipset development and defense sector certification capture.
Among Asia-Pacific-based equipment vendors, ZTE Corporation and Huawei exemplify the integrated infrastructure archetype serving domestic CDMA2000 deployments. Samsung Electronics occupies a position within the diversified electronics tier, competing in ruggedized feature phone segments where military-grade durability requirements persist. These three companies represent distinct strategic postures: pure-play infrastructure specialization, captive domestic market service, and cross-segment electronics manufacturing leverage.
| Leading Market Players |
|---|
| ZTE Corporation |
| Motorola |
| Qualcomm |
| Kyocera |
| TCL |
| Samsung Electronics |
| Huawei |
| Nokia |
| LG Electronics |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for Qualcomm baseband chipsets concentrate pricing power with legacy-qualified vendors serving North American carriers under FCC Part 27 certification. This inventory compression amplifies cost pass-through to India's rural procurement programs and China's industrial private network deployments.
Pricing Analysis
Certification level (FCC Part 27-grade versus standard MIIT-type-approved) creates the primary spread between premium and standard hardware tiers. Contract-based long-term offtake dominates carrier procurement, with price differentiation resting on volume scale and after-sales spare parts bundling. Cost compression in economy feature phones intensifies because Qualcomm allocates silicon capacity toward 5G volumes. Government buyers in China exhibit lowest price sensitivity due to secure voice mandates, while India's rural carriers face acute budget constraints.
Supply Chain Analysis
Port congestion at Shenzhen and Shanghai elevates inbound logistics costs for CDMA2000 base station components destined for western China deployments. Manufacturing concentrates in China, South Korea, and Taiwan, with Qualcomm baseband silicon and ZTE infrastructure equipment anchoring tier-one supply. Raw material dependencies include gallium arsenide substrates, ceramic filters, and lithium-ion cells. Single-source vulnerability around EV-DO Rev. B modem chipsets persists. Distribution runs through direct carrier procurement teams with multi-year maintenance commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carrier consolidation across India's rural telecommunications circles and China's industrial private network sectors has shifted buyer power toward volume aggregators. This concentration demands strategic recalibration from all market participants.
For Market Incumbents: Compound defensive moats through captive backward integration into baseband chipset inventory and multi-year spare parts lock-in with India's TRAI-mandated rural carriers. Prioritize dual-mode CDMA-LTE certification investment to offset NB-IoT substitution threats in maritime telemetry verticals. For New Entrants and Emerging Players: Differentiate on streamlined MIIT type approval navigation for western China's smart grid deployments. Target India's defense procurement channels for ruggedized secure voice handsets. Pursue systems integrator partnerships to bypass direct carrier qualification barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates with stranded CDMA infrastructure divisions. Frame five-to-ten-year viability around government secure communications mandates rather than consumer technology migration. Monitor FCC 3G sunset enforcement consistency as the critical inflection signal for stranded asset risk realization.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Chipset Development | Qualcomm and Samsung Electronics preserve voice roaming revenues while enabling LTE data migration. |
| Defense Sector Certification Capture | MIIT streamlined approval unlocks China's secure handset procurement for qualified vendors. |
| Spare Parts Captive Supply | ZTE secures multi-year maintenance contracts with India's rural circles through component availability guarantees. |
| Industrial Private Network Deployment | Huawei leverages domestic type approval efficiency for western province CDMA2000 infrastructure. |
| Regulatory Compliance Investment | FCC Part 27 requalification preserves North American carrier supply chain eligibility for legacy manufacturers. |
Methodological Framework
A standing panel of carrier network planning officers, defense procurement specialists, industrial IoT systems integrators, and RF engineering consultants provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FCC equipment authorization databases, MIIT radio transmission type approval registries, and TRAI universal service obligation filings. Bottom-up carrier capex tracking and top-down semiconductor shipment analysis enabled triangulation across data sources.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product architecture (feature phone, modem, smartphone, tablet), end-user category (government, enterprise, consumer), technology protocol (CDMA2000, EV-DO, dual-mode), and distribution channel structure. CAGRs derived from installed base depreciation curves and residual replacement demand patterns incorporated Qualcomm chipset allocation constraints and regulatory sunset timelines as key forecast inputs.
Material uncertainties — carrier spectrum refarming decisions, defense budget reallocation, and baseband silicon supply interruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding network maintenance commitment durations and equipment authorization pathway stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
GSM Mobile Phone Market
Telecommunications
LTE and 5G NR-Based CBRS Networks Market
Telecommunications
Telecommunication Service Market
Telecommunications
Egypt Telecom Market
Telecommunications
Video Door Phones Market
Telecommunications
DECT System Market
Telecommunications
Peru Telecom Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
Finland Telecom Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Mftpaas Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Global IP Phone Market
Telecommunications
MVNO Market