
 IP PBX Market | 2026-2036
IP PBX Market Size, Share, and Industry Trends Forecast 2026-2036
IP PBX Market Outlook
Software-defined telephony is fragmenting traditional hardware-centric architectures into modular, API-driven communication stacks. Cisco Systems anchors enterprise-grade deployments through deep channel partnerships and certified interoperability programs. Yealink competes aggressively on endpoint economics, leveraging vertically integrated manufacturing to undercut Western rivals in price-sensitive tenders. 3CX specializes in channel-only distribution, sustaining margin discipline by refusing direct sales and forcing reseller investment in technical certification.
An IP PBX is a private branch exchange system that routes voice, video, and messaging traffic over Internet Protocol networks using session initiation protocol signaling, packet-switched architecture, and codec-based compression for bandwidth efficiency. It replaces circuit-switched TDM infrastructure with software running on standard servers or virtualized instances, enabling centralized management of extensions, auto-attendants, and unified messaging across distributed locations. Cloud deployment models now capture the fastest expansion as recurring revenue structures displace perpetual license models and reduce capital barriers for mid-market buyers. SME end users represent the deepest latent pool, though large enterprises still dominate absolute spending through hybrid configurations that preserve on-premises control for compliance-sensitive departments while offloading burst capacity to hosted instances.
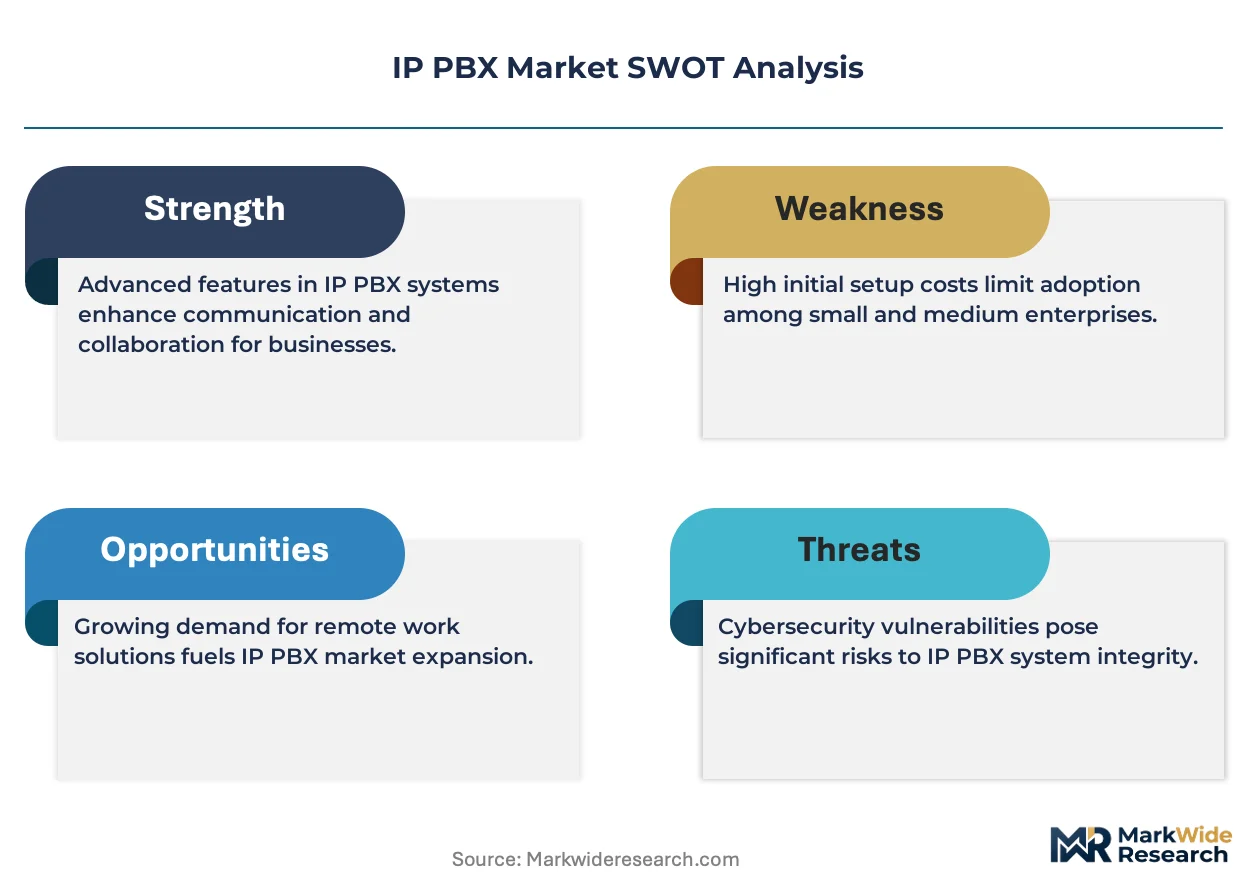
The FCC enforces STIR/SHAKEN authentication standards that compel carriers and PBX operators to implement cryptographic caller verification, reshaping product roadmaps toward native compliance rather than bolt-on modules. GDPR and the EU AI Act impose data residency and algorithmic transparency obligations on European deployments, particularly for cloud-hosted systems processing biometric voiceprints or automated transcription. India's TRAI mandates interconnection and quality-of-service benchmarks that favor licensed operators with established network infrastructure. Stakeholders must weigh sovereign data requirements against multi-tenant cloud economics when architecting cross-border communication platforms.
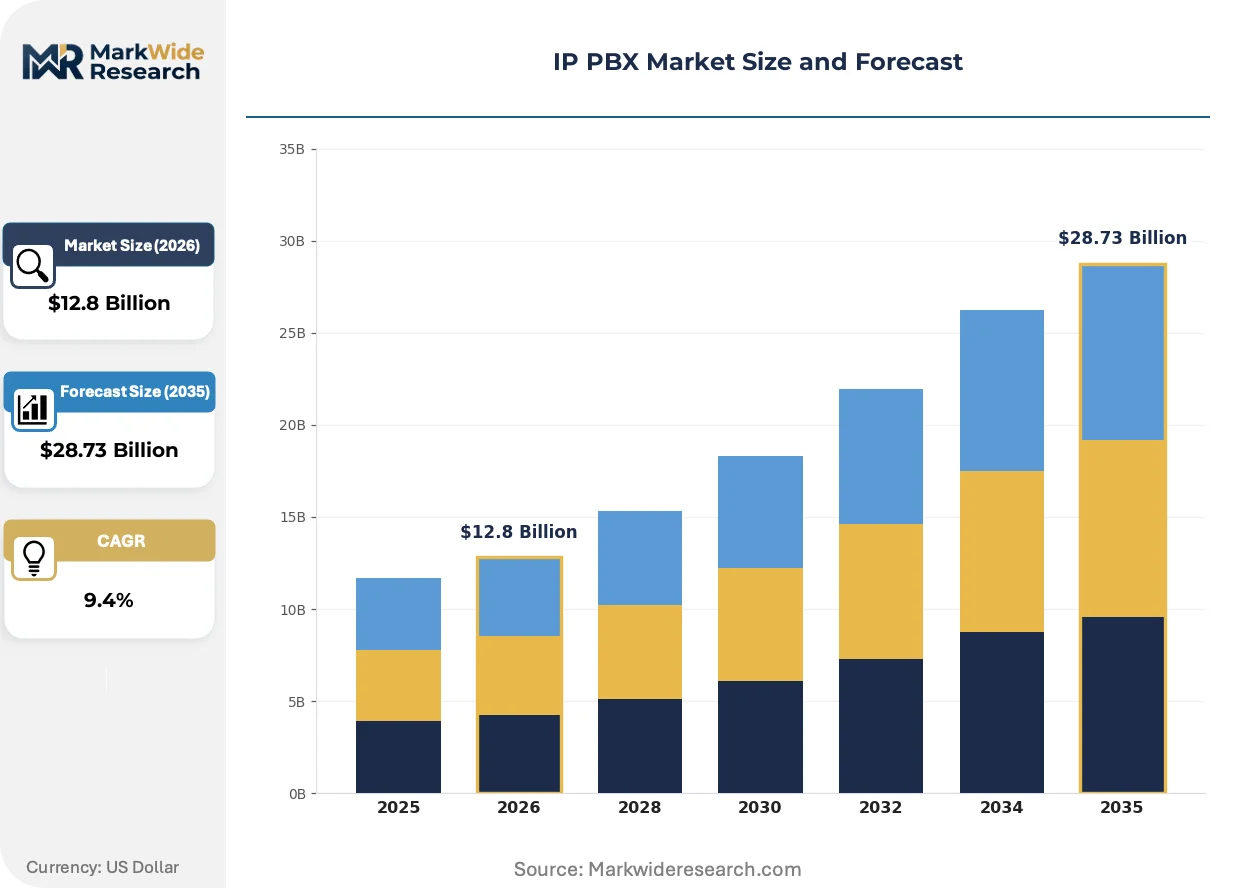
Market Dynamics
The migration from hardware-centric PBX appliances toward software-defined, cloud-native architectures is compressing capital requirements and redistributing value toward subscription-based service orchestration layers.
Growth Catalysts
- STIR/SHAKEN Mandate:The FCC's caller authentication framework compels North American carriers and enterprises to upgrade legacy SIP infrastructure, accelerating replacement cycles for non-compliant TDM systems.
- Healthcare Digitization:Hospital networks are unifying patient communications through VoIP-enabled nurse call systems and telehealth integration, expanding addressable endpoints per facility.
- India's SME Wave:TRAI's net-neutrality enforcement and PLI scheme incentives for domestic equipment manufacturing are displacing PSTN subscriptions among price-sensitive small businesses.
Market Restraints
- Silicon Supply Concentration:Specialized VoIP processor fabrication concentrates among Taiwan-based foundries, exposing equipment lead times to geopolitical disruption risks.
- GDPR Data Residency:The EU AI Act's biometric voiceprint processing restrictions impose multi-tenant cloud architecture penalties, favoring higher-cost sovereign hosting deployments.
- Legacy PSTN Interconnection:Incumbent carriers in regulated markets maintain termination fee structures that erode IP telephony margin advantages for high-volume call centers.
Strategic Opportunities
- Edge AI Convergence:On-device natural language processing is virtualizing transcription and sentiment analysis workloads, reducing latency for real-time customer service applications.
- Indonesia's Underpenetrated Mid-Market:Archipelago geography and limited fixed-line legacy infrastructure create first-mover advantages for cloud-PBX providers targeting distributed retail chains.
- API-First Distribution:Communication-platform-as-a-service channels are displacing traditional VAR relationships, enabling direct developer adoption and consumption-based billing models.
Industry Challenges
- SIP Security Expertise Scarcity:Session border controller configuration and real-time transport protocol encryption require specialized network engineering skills that outpace workforce development pipelines.
- Multi-Vendor Interoperability Certification:Proprietary codec implementations and non-standard signaling extensions fragment testing matrices, delaying enterprise deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IP PBX Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud, Hybrid, Virtual End User: SMEs, Large Enterprises, Government, Educational Institutions Feature Set: Call Routing, Voicemail, Conferencing, IVR Connectivity Type: Analog, Digital, SIP, IP |
| Companies Covered | RingCentral, Yealink, Cisco Systems, Vonage, 3CX, Avaya, Alcatel-Lucent Enterprise, NEC Corporation, Mitel Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IP PBX Market Strategic Shifts
Software abstraction is collapsing the distinction between premises-based control and cloud-delivered capacity, forcing vendors to rearchitect around containerized microservices rather than monolithic appliances.
Session border controller functionality is virtualizing into Kubernetes-orchestrated network functions, enabling telecom operators to deploy elastic security and routing layers across distributed points of presence. Mid-market enterprises are adopting these cloud-native SBCs to eliminate dedicated hardware refresh cycles. This shift is virtualizing the traditional demarcation between carrier networks and customer premises equipment, compressing vendor margins on physical appliances.
The EU AI Act's algorithmic transparency requirements are reshaping European deployment roadmaps for systems processing automated call transcription and voice biometric authentication. Vendors must now document training data provenance and enable human-in-the-loop override mechanisms. Cloud-hosted PBX providers serving German financial services and French healthcare verticals are responding by partitioning EU customer data into sovereign infrastructure zones.
Subscription consumption models are displacing perpetual licensing across North American and European mid-market procurement patterns. Buyers now prioritize operational expenditure predictability over capital depreciation schedules, particularly in distributed retail and professional services verticals. This behavioral pivot is most pronounced among US healthcare clinic networks and UK legal partnerships, where finance departments favor monthly per-seat billing aligned with headcount volatility.
IP PBX Market Segmentation
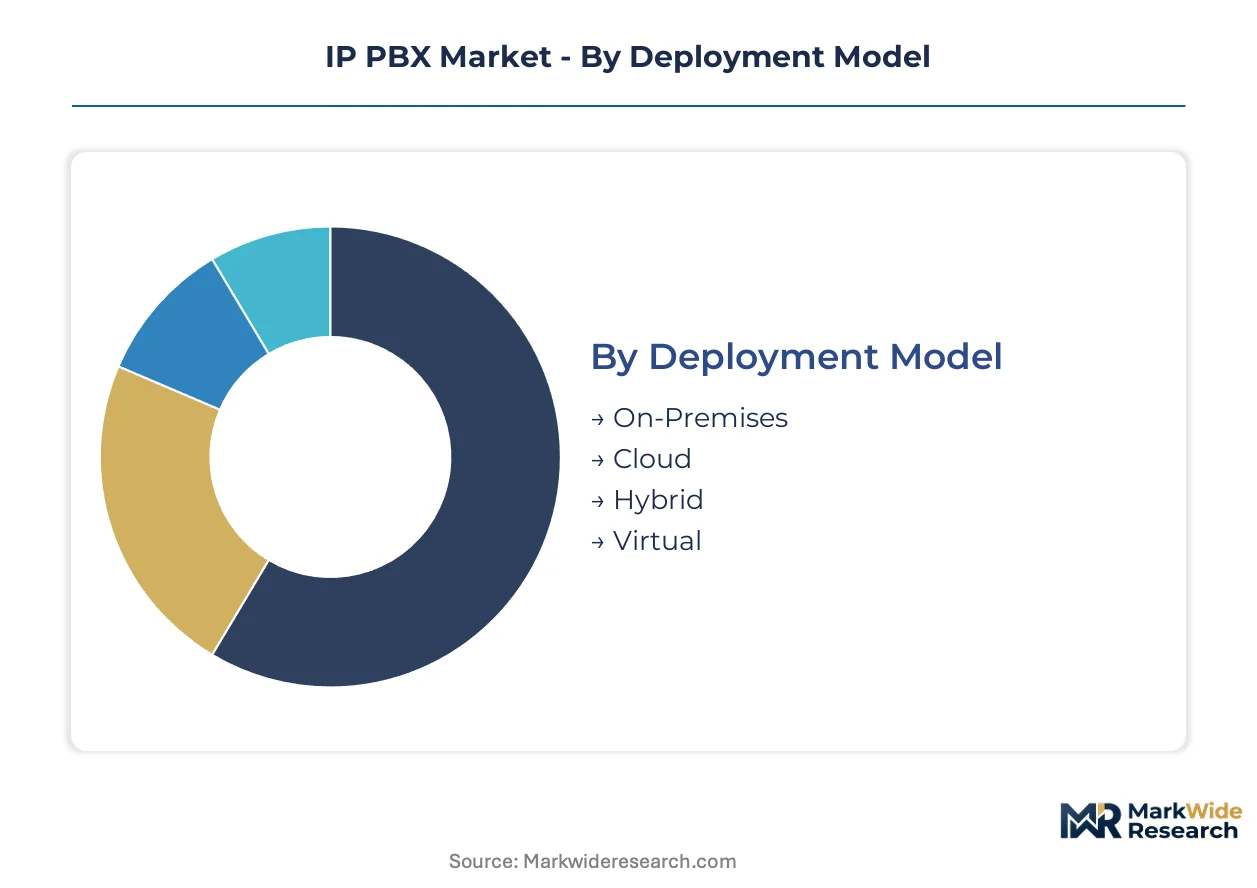
IP PBX segmentation reveals divergent growth mechanics across deployment architectures and buyer profiles. Cloud-native configurations are compressing capital barriers while on-premises systems retain compliance-critical installations. Feature specialization and connectivity standards further stratify procurement patterns across regulated and price-sensitive verticals.
Deployment Model:
Mature on-premises installations coexist with emerging cloud-native architectures, creating a bifurcated replacement cycle across enterprise estates.
- On-Premises:Hardware appliances installed within customer data centers deliver complete administrative control over session initiation protocol routing and codec selection. Financial services firms in Frankfurt and healthcare networks across Bavaria favor this model to satisfy Bundesdatenschutzgesicht data residency requirements without third-party cloud exposure.
- Cloud:Multi-tenant hosted platforms eliminate server maintenance burdens through browser-based administration portals. Distributed retail chains across Indonesia's archipelago leverage this model to provision store endpoints without fixed-line infrastructure investment.
- Hybrid:Split architectures maintain on-premises call control while bursting overflow capacity to hosted instances during peak demand intervals. Contact center operators in Mumbai deploy this configuration to balance TRAI-mandated quality-of-service compliance with elastic staffing costs.
- Virtual:Software-only distributions deploy on hypervisor infrastructure using existing server hardware. Cost-conscious educational institutions across India's state university systems favor this approach to maximize prior capital investment in campus IT infrastructure.
On-Premises handles the majority of throughput; Cloud is the fastest mover on share.
End User:
Volume concentration tilts toward institutional buyers with compliance obligations, though absolute seat expansion concentrates among underpenetrated mid-market segments.
- SMEs:Businesses with under 500 employees drive seat growth through subscription consumption models that convert unpredictable capital expenditure into predictable operational budgeting. India's PLI scheme incentives for domestic equipment manufacturing accelerate displacement of legacy PSTN subscriptions among price-sensitive proprietorships in Gujarat and Tamil Nadu.
- Large Enterprises:Multi-site organizations with dedicated IT staff demand API-driven orchestration layers integrating voice with CRM and workforce management platforms. German automotive suppliers leverage these integrations to unify communications across global engineering centers while maintaining local data sovereignty.
- Government:Public sector procurement emphasizes certified interoperability and domestic content requirements. Municipal administrations across France prioritize ANSSI-certified configurations for sensitive administrative communications.
- Educational Institutions:Universities and K-12 districts require scalable extension management across dispersed campuses. State-funded technical colleges in Karnataka expand VoIP deployments to support hybrid learning infrastructure mandated by national digital education initiatives.
Large Enterprises dominate absolute spending; SMEs are expanding most quickly across emerging economies.
Feature Set:
Core functionality commoditization is pushing differentiation toward integrated collaboration stacks and AI-augmented interaction management.
- Call Routing:Session initiation protocol-based intelligent distribution directs inbound traffic across extensions, hunt groups, and time-based rules. Manufacturing facilities across Mexico's industrial corridors deploy geographic routing to connect customers with Spanish-speaking agents in Monterrey versus English-speaking support in Tijuana.
- Voicemail:Unified messaging platforms transcribe voice messages for email and mobile delivery. Professional services partnerships in London's financial district prioritize these capabilities to accelerate client response cycles without real-time availability constraints.
- Conferencing:Multi-party audio and video bridging supports distributed team collaboration. Brazilian agribusiness conglomerates leverage these features to coordinate operations across remote plantation sites with limited terrestrial connectivity.
- IVR:Interactive voice response automates caller qualification through touch-tone or natural language inputs. Healthcare clinic networks across Texas deploy these systems to triage patient inquiries and reduce nursing staff administrative burden.
Call Routing remains the foundational purchase criterion; IVR is climbing the fastest as labor cost pressures intensify.
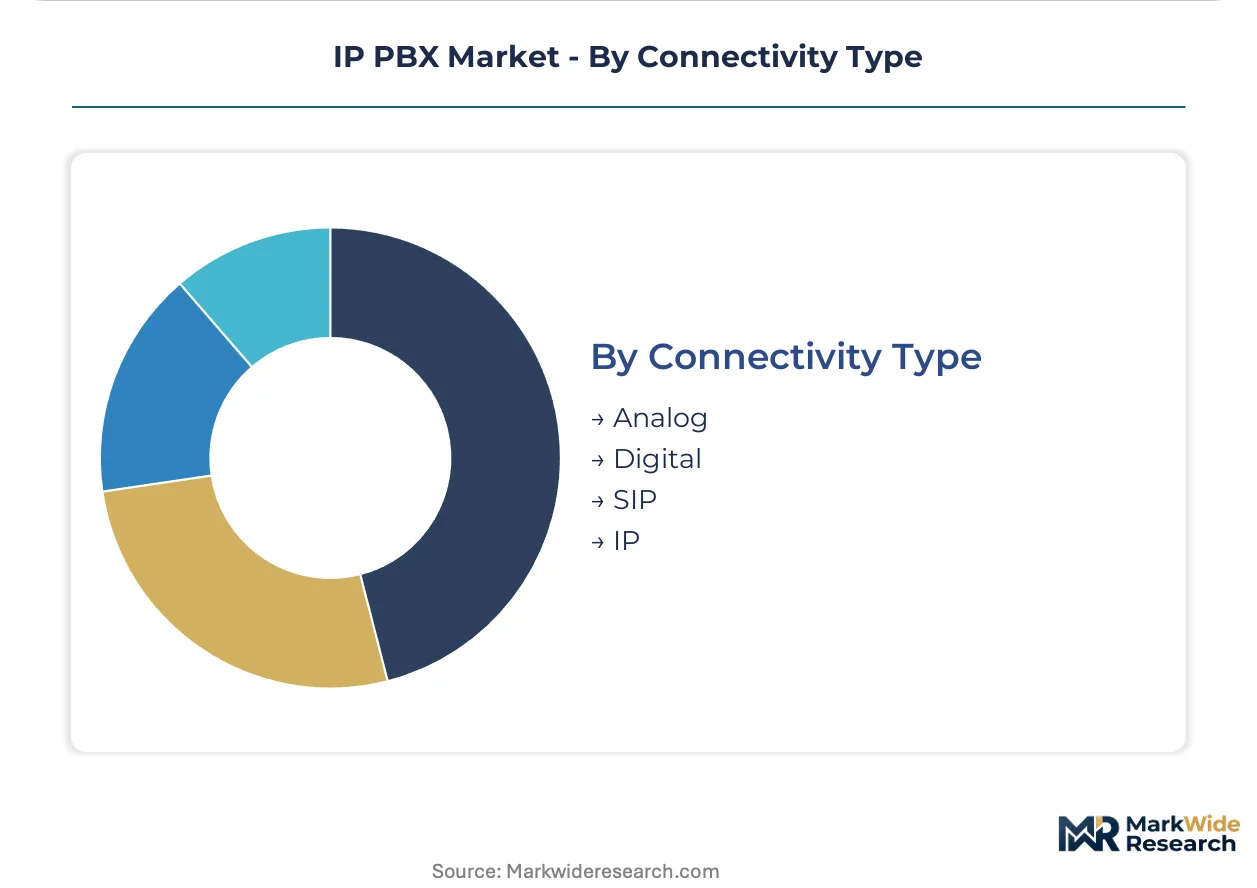
Connectivity Type:
Protocol migration from circuit-switched to packet-based transport is accelerating SIP standardization while analog persistence reflects legacy equipment replacement inertia.
- Analog:Traditional RJ-11 interfaces support existing fax machines and emergency phones during transition periods. Older hospitality properties across Portugal's Algarve coast retain these connections for in-room phones pending full property renovation cycles.
- Digital:ISDN and T1 interfaces bridge legacy PBX investments with modern IP infrastructure. Government administrative buildings in Warsaw maintain these connections for secure inter-agency communications pending full SIP migration.
- SIP:Session initiation protocol trunks deliver voice over IP with standardized signaling and codec negotiation. The FCC's STIR/SHAKEN mandate compels North American carriers and enterprises to upgrade to compliant SIP infrastructure, accelerating replacement of non-authenticated TDM systems.
- IP:Native Internet Protocol connectivity enables direct endpoint registration without translation gateways. Greenfield smart office developments across Singapore's One-North district deploy pure-IP configurations to minimize hardware footprint and energy consumption.
SIP handles the majority of new trunk provisioning; IP is gaining share fastest among new construction and full replacement scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese semiconductor foundries export specialized VoIP processors to equipment manufacturers across North America, Europe, and Asia-Pacific, creating supply chain dependencies that shape regional deployment timelines and procurement strategies.
United States
Healthcare clinic networks and financial services firms drive enterprise VoIP upgrades to meet FCC STIR/SHAKEN authentication mandates. The FCC enforces cryptographic caller verification standards that accelerate SIP trunk replacements for legacy TDM infrastructure. Dallas-Fort Worth hosts concentrated contact center operations where hybrid cloud-premise architectures balance compliance with elastic capacity.
Germany
Automotive suppliers and industrial manufacturers demand API-driven orchestration layers integrating voice with ERP systems. The EU AI Act imposes algorithmic transparency obligations on automated transcription and biometric voiceprint processing. Bavarian engineering centers deploy sovereign-hosted configurations to satisfy BSI data residency requirements without multi-tenant cloud exposure.
India
SME digitization and PLI scheme incentives for domestic equipment manufacturing displace legacy PSTN subscriptions among price-sensitive businesses. TRAI mandates interconnection and quality-of-service benchmarks that favor licensed operators with established network infrastructure. Gujarat and Tamil Nadu manufacturing clusters accelerate VoIP adoption through state-led digital infrastructure initiatives.
Indonesia
Archipelago geography and limited fixed-line legacy infrastructure create first-mover opportunities for cloud-PBX providers targeting distributed retail chains. The country's national telecommunications regulator enforces quality-of-service standards for VoIP interconnection. Jakarta and Surabaya retail headquarters provision store endpoints without terrestrial infrastructure investment.
Singapore
Greenfield smart office developments and financial services digitization drive pure-IP configuration demand. The Infocomm Media Development Authority promotes standards-based interoperability for enterprise communication platforms. One-North district developments minimize hardware footprint through native Internet Protocol connectivity and centralized cloud management.
IP PBX Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that fragments between enterprise-grade systems integrators and endpoint economics specialists. Consolidation pressure concentrates among North American and European incumbents with established carrier relationships, while Asian manufacturers exploit vertically integrated production cost advantages. Three archetypes dominate: full-stack platform vendors, endpoint hardware specialists, and channel-only software distributors. M&A activity targets API-first communication platforms, while strategic partnerships focus on cloud-native session border controller virtualization.
Within the channel-only tier, 3CX exemplifies margin discipline through reseller certification requirements. Cisco Systems anchors enterprise-grade deployments through deep interoperability programs. Yealink occupies a position among endpoint specialists leveraging manufacturing integration to undercut Western rivals in price-sensitive tenders.
| Leading Market Players |
|---|
| RingCentral |
| Yealink |
| Cisco Systems |
| Vonage |
| 3CX |
| Avaya |
| Alcatel-Lucent Enterprise |
| NEC Corporation |
| Mitel Networks |
| Others |
Value Chain & Pricing Dynamics
Hsinchu Science Park's foundry capacity for specialized VoIP processors determines equipment lead times and pricing power across downstream markets, with Taiwanese fabrication bottlenecks translating directly into premium pricing for enterprise-grade session border controllers and high-density gateway appliances.
Pricing Analysis
Current-generation cloud-native software licenses command three-to-five times the per-seat annual rates of prior-generation perpetual licenses, while next-generation AI-augmented interaction platforms with embedded transcription and sentiment analysis introduce additional premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates certified carrier-grade deployments from mid-market hosted solutions and entry-level open-source distributions. Pricing pressure stems from vertically integrated Asian manufacturers compressing endpoint hardware margins through captive semiconductor production. SMEs in India and Indonesia exhibit highest price sensitivity, while German automotive suppliers and US healthcare networks prioritize interoperability certification over unit cost.
Supply Chain Analysis
Foxconn, Pegatron, and Wistron hold concentrated contract manufacturing capacity for IP PBX appliances and VoIP endpoints, with their production footprints spanning Taiwan, mainland China, and Vietnam. Specialized DSP chips and gigabit Ethernet PHYs draw from TSMC's Taiwanese foundries and MediaTek's fabless design ecosystem. Single-source vulnerability concentrates in advanced node semiconductor fabrication, where geopolitical disruption risks extend equipment delivery timelines. Distribution runs through certified value-added resellers and systems integrators, with direct-to-enterprise sales limited to cloud-native subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as API-first communication stacks displace hardware-centric procurement patterns, with interoperability certification emerging as the decisive ecosystem control point.
For Market Incumbents: Build switching-cost moats through deep CRM and workforce management platform integrations that embed voice orchestration into core business workflows. Cisco Systems and Avaya should accelerate API certification programs to preempt cloud-native entrants from capturing mid-market developer mindshare. Channel control investments in reseller technical certification create defensive barriers against 3CX's channel-only distribution model. Vertical integration into session border controller software reduces dependency on third-party security vendors. For New Entrants and Emerging Players: Build out sovereign-hosted deployment capabilities targeting German financial services and French healthcare verticals constrained by EU AI Act data residency requirements. Indonesia's archipelago retail chains and India's state university systems represent the most penetrable geographies, with limited legacy infrastructure reducing replacement-cycle friction. Developer-first go-to-market strategies through communication-platform-as-a-service APIs enable consumption-based billing adoption without traditional VAR relationship investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-first software platforms with recurring revenue structures over hardware-dependent legacy vendors facing perpetual license decline. Long-term viability hinges on cloud-native architecture migration completion and AI-augmented feature integration. Acquisition targets should demonstrate established carrier interoperability certification and vertical-specific deployment traction. The signal to watch is STIR/SHAKEN compliance adoption velocity, which separates upgrade-ready installed bases from stranded legacy assets requiring full replacement.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | Embedded voice orchestration into Salesforce and ServiceNow ecosystems locks in enterprise workflows. |
| Sovereign Cloud Infrastructure Deployment | EU data residency compliance captures German automotive and French healthcare procurement cycles. |
| Edge AI Convergence Investment | On-device NLP virtualization reduces latency for real-time customer service transcription workloads. |
| Channel Certification Program Expansion | Technical reseller investment deepens moats against direct-sales cloud competitors. |
| STIR/SHAKEN Native Compliance | FCC-mandated cryptographic authentication accelerates SIP trunk replacement cycles. |
Study Parameters
The analysis maps on-premises, cloud, hybrid, and virtual deployment architectures, each validated through primary interviews with PBX systems integrators, carrier SIP trunk product managers, enterprise IT procurement officers, and channel partner technical directors. Secondary validation draws from FCC STIR/SHAKEN implementation filings, TRAI interconnection quality-of-service reports, EU AI Act algorithmic transparency guidance, and hyperscaler communication platform revenue disclosures. Bottom-up seat deployment estimates triangulate against top-down carrier trunk provisioning data.
Assumptions held fixed include regulatory enforcement timelines for caller authentication mandates and data residency requirements, while technology adoption curves and competitive pricing dynamics were varied across sensitivity scenarios. Segmentation dimensions modeled encompass deployment model, end-user organization size, feature specialization, and connectivity protocol migration status. CAGRs derive from installed base replacement cycle analysis and greenfield penetration elasticity across emerging economy SME segments. Forecast inputs incorporate VoIP processor foundry capacity constraints and PLI scheme incentive phase structures.
Sensitivities concentrate around Taiwanese semiconductor supply disruption, EU AI Act biometric processing restriction enforcement, and India TRAI quality-of-service benchmark revisions. Forecasts reflect documented assumptions regarding carrier interconnection fee structures and cloud migration cost parity thresholds. Quarterly review of foundry utilization rates, carrier STIR/SHAKEN compliance certification timelines, and API-first platform developer adoption metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Roaming Tariff Market
Telecommunications
Global Relay Market
Telecommunications
Italy Telecom Market
Telecommunications
Cloud Telephony Service Market
Telecommunications
5G System Integration Market
Telecommunications
Colombia Telecom Market
Telecommunications
Oman Telecommunication Market
Telecommunications
Poland Telecom Market
Telecommunications
Thailand Telecom Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
GPON Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
Private Branch Exchange Market
Telecommunications
Global SMB Telecom Voice and Data Services Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
Iran Telecom Market