
 Indoor Cycling Software Market | 2026-2036
Indoor Cycling Software Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Cycling Software Market Intelligence
North American cloud infrastructure expansion is rewriting how indoor cycling platforms deliver low-latency streaming to mass audiences. Zwift leverages its proprietary 3D engine to anchor premium subscriber retention across English-speaking markets. TrainerRoad specializes in structured workout protocols that dominate serious amateur cyclist segments. MyWhoosh competes on price positioning while extending its reach into Middle Eastern and Asian markets through localized event calendars.
Indoor cycling software comprises digital platforms that render virtual environments, process real-time biometric telemetry, and synchronize resistance control with smart trainers via ANT+ and Bluetooth protocols. These systems serve the primary commercial purpose of converting stationary exercise into immersive, measurable training experiences that replicate outdoor cycling dynamics. Cloud-based deployment captures the largest addressable base by eliminating local hardware dependencies, while gamification layers represent the fastest-growing solution type as achievement systems and virtual currency mechanics deepen session frequency. Performance tracking integration with wearable compatibility and power meter ecosystems commands the highest margin pools due to subscription stickiness among data-driven athletes.
The Federal Trade Commission scrutinizes subscription cancellation practices and auto-renewal disclosures for fitness apps operating in the United States. The European Union's GDPR and forthcoming AI Act constrain how European platforms deploy personalized coaching algorithms and biometric inference. Stakeholders must monitor evolving interoperability standards as smart trainer manufacturers and software platforms negotiate control over user data flows and device certification protocols.
Market Dynamics
The convergence of cloud-native streaming infrastructure and biometric sensor ecosystems is compressing latency thresholds and redefining subscriber retention mechanics across indoor cycling platforms.
Growth Catalysts
- EU AI Act compliance frameworks:European platforms deploying algorithmic coaching engines must demonstrate transparency in automated decision-making, creating competitive moats for compliant operators.
- Smart trainer penetration in German boutique studios:Hardware-software bundling arrangements accelerate platform adoption among premium fitness operators seeking differentiated member experiences.
- Bluetooth Low Energy 5.3 protocol adoption:Enhanced power efficiency and broadcast capacity enable simultaneous multi-rider telemetry streaming without local network congestion.
Market Restraints
- Cloud compute cost volatility:Real-time 3D rendering workloads on AWS and Azure infrastructure expose platform margins to unpredictable egress pricing fluctuations.
- Smart trainer supply concentration:Taiwan-based manufacturing clusters for electromagnetic resistance units create single-source vulnerability for software platforms dependent on hardware interoperability.
- Biometric inference limitations:Non-invasive lactate threshold estimation remains technically unreliable, constraining algorithmic coaching accuracy for elite athlete segments.
Strategic Opportunities
- Underpenetrated Middle Eastern markets:Saudi Arabia and UAE fitness infrastructure investments create first-mover advantages for platforms localizing event calendars and payment systems.
- Medical fitness reimbursement pathways:Germany's DiGA framework and similar digital health approval streams in France enable physician-prescribed cycling interventions.
- Convergence of virtual reality headsets and haptic feedback vests:Immersive hardware integration opens subscription tiers beyond screen-based experiences.
Industry Challenges
- ANT+ and Bluetooth certification timelines:Device interoperability testing with proprietary trainer firmware delays feature rollouts and strains engineering resources.
- Power data standardization disputes:Competing protocols for normalized power calculation create user confusion and fragment training load metrics across platforms.
- Legacy studio management system integration:Boutique operators require costly middleware development to synchronize indoor cycling software with existing member billing and scheduling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Cycling Software Market |
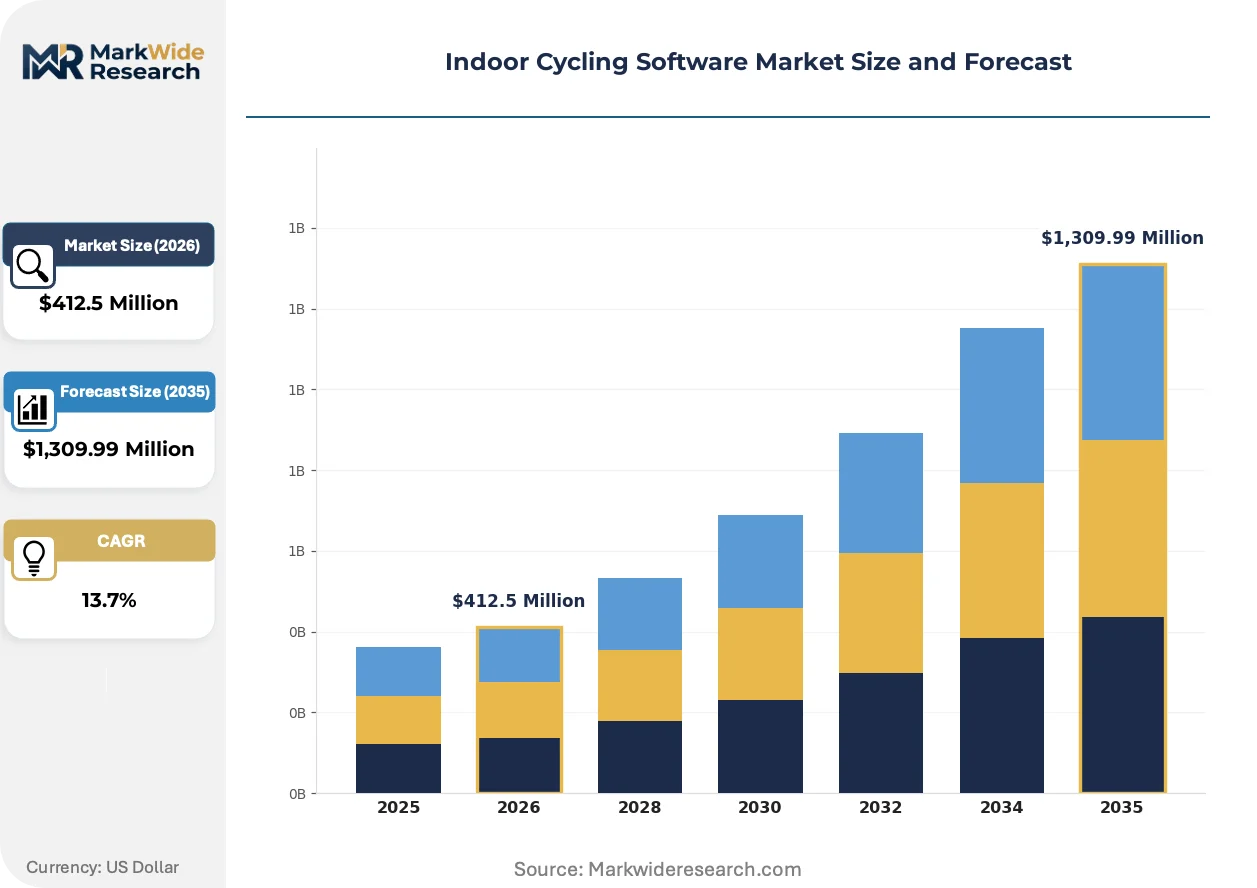
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,309.99 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Type: Performance Tracking, Virtual Classes, Training Plans, Gamification, Social Integration End User: Fitness Centers, Home Enthusiasts, Corporate Wellness, Rehabilitation Centers Integration Level: Wearable Compatibility, Smart Trainer Sync, Third-Party Apps, Heart Rate Monitors, Power Meters |
| Companies Covered | Wahoo SYSTM, TrainingPeaks Virtual, Zwift, FulGaz, icTrainer, TrainerRoad, MyWhoosh, bkool, Rouvy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Cycling Software Market Strategic Shifts & Innovations
Platform operators are racing to compress the fidelity gap between physical exertion and digital immersion, deploying sensor fusion and edge computing to eliminate perceptible latency in virtual environments.
Photogrammetry-based world reconstruction is virtualizing outdoor course replication with centimeter-grade accuracy. Competitive cyclist segments in the United States and United Kingdom are migrating toward these ultra-realistic environments at accelerating rates. This capability is virtualizing the traditional distinction between indoor training and outdoor route preparation, collapsing preparation cycles and intensifying platform switching costs.
The EU Digital Services Act disclosure requirements are mandating algorithmic transparency for personalized workout recommendations. Platforms must now explain how biometric data influences difficulty adjustments and route selections. Subscription services targeting European Union member states are restructuring data governance architectures and hiring dedicated algorithmic accountability officers to maintain operational continuity.
Hardware-software unbundling is fragmenting purchasing decisions across home enthusiast segments. Consumers increasingly acquire smart trainers and platform subscriptions through separate channels, compressing traditional bundling economics. This pattern is most pronounced in United States direct-to-consumer markets where price comparison tools and seasonal discounting have eroded exclusive hardware-software pairing arrangements.
Indoor Cycling Software Market Segmentation
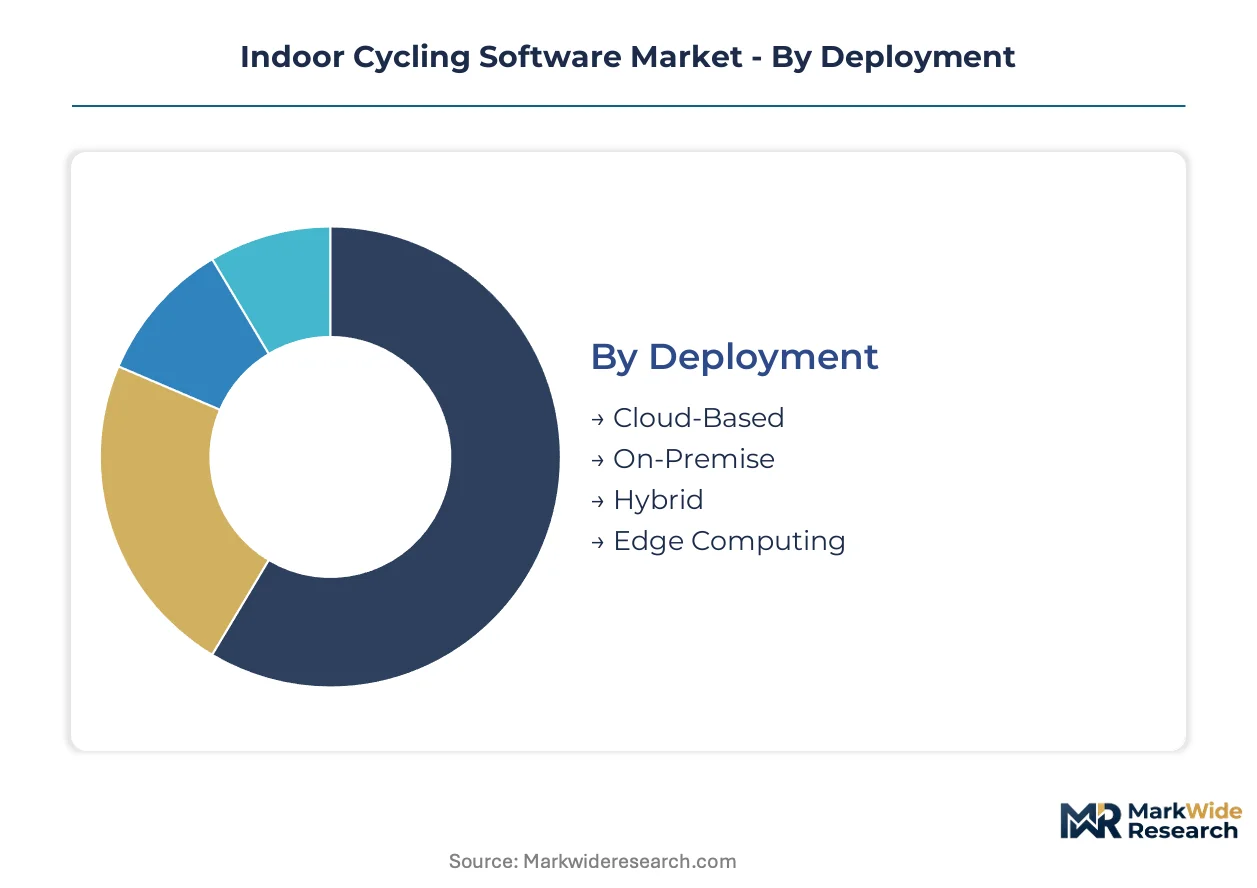
Indoor cycling software segmentation reveals how deployment architecture, solution functionality, and integration depth determine pricing power and subscriber retention. Platform operators calibrate feature bundles across these dimensions to capture distinct user willingness-to-pay profiles.
Deployment:
Cost tier structure separates local infrastructure investment from recurring subscription models, with capital intensity and latency performance defining competitive positioning.
- Cloud-Based:Server-rendered 3D environments stream to consumer devices without local GPU requirements. Demand concentrates among United States home enthusiasts where broadband penetration supports 4K streaming workloads and eliminates hardware refresh cycles.
- On-Premise:Locally installed software processes telemetry and renders graphics on dedicated hardware within facility premises. German boutique studios favor this model to guarantee session continuity during internet outages and maintain direct control over member data.
- Hybrid:Edge-cached assets reduce bandwidth consumption while core logic runs remotely. This architecture serves corporate wellness installations with intermittent connectivity.
- Edge Computing:Distributed processing nodes minimize round-trip latency for competitive racing applications. Saudi fitness infrastructure investments are piloting this deployment for premium indoor cycling venues.
Cloud-Based commands the established base. The steepest expansion runs through Edge Computing.
Solution Type:
Application focus determines whether platforms monetize through data-driven athlete subscriptions or mass-market entertainment engagement.
- Performance Tracking:Power curve analysis, training stress scoring, and periodization planning tools dominate serious amateur cyclist segments in the United Kingdom and United States. This functionality commands premium pricing through integration with ANT+ and Bluetooth power meter ecosystems.
- Gamification:Achievement badges, virtual currency economies, and unlockable equipment layers deepen session frequency among casual users. United Arab Emirates fitness operators are deploying these mechanics to differentiate member experiences in saturated urban markets.
- Virtual Classes:Instructor-led video sessions synchronize resistance profiles across subscriber bases. Corporate wellness programs in France leverage this format for standardized group exercise delivery.
- Training Plans:Structured workout protocols adapt to fitness assessments and schedule constraints. Rehabilitation centers in Germany prescribe these interventions under the DiGA digital health framework.
- Social Integration:Friend leaderboards, club formations, and event scheduling tools reduce churn through network effects. Asian markets show particular responsiveness to community-driven platform selection.
Performance Tracking anchors revenue concentration among data-driven athletes. Social Integration is gaining share fastest among platforms targeting mass-market expansion.
End User:
Customer type segmentation maps pricing tolerance against acquisition cost and lifetime value profiles across institutional and individual purchasers.
- Home Enthusiasts:Individual subscribers purchasing direct-to-consumer access represent the volume foundation. United States penetration rates for connected fitness hardware create the deepest addressable pool for platform conversion.
- Fitness Centers:Multi-seat licensing agreements with boutique studios and commercial gyms generate predictable recurring revenue. Hardware-software bundling accelerates adoption among German operators seeking differentiated member experiences.
- Corporate Wellness:Employer-sponsored programs subsidize employee access as health benefit investments. French and German enterprises are expanding these arrangements under occupational health mandates.
- Rehabilitation Centers:Clinical settings prescribe controlled cycling interventions for cardiac and orthopedic recovery. Germany's DiGA approval pathway enables physician reimbursement for qualifying software prescriptions.
Home Enthusiasts command the established base. The steepest expansion runs through Rehabilitation Centers.
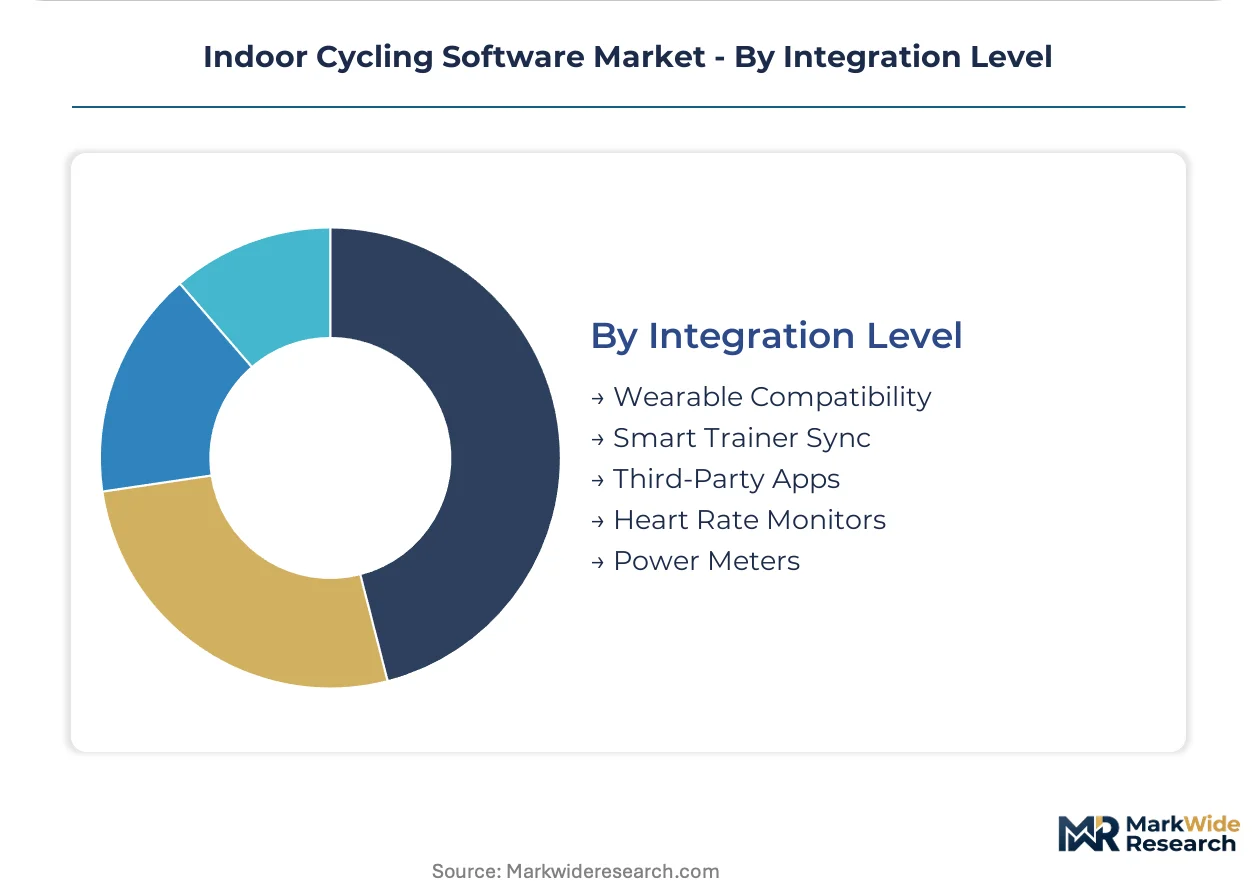
Integration Level:
Supply concentration in sensor and device ecosystems determines platform interoperability investment and certification burden.
- Smart Trainer Sync:Direct resistance control via ANT+ FE-C and Bluetooth FTMS protocols enables immersive gradient simulation. Taiwan-based manufacturing clusters for electromagnetic resistance units create certification dependency for software platforms.
- Power Meters:Crank and pedal-based wattage measurement integration supports training load quantification. Serious amateur segments in the United States and United Kingdom treat power data compatibility as a platform selection prerequisite.
- Wearable Compatibility:Optical heart rate straps and wrist-based monitors extend biometric capture beyond bike-mounted sensors. This integration broadens appeal among casual users unwilling to invest in dedicated cycling hardware.
- Heart Rate Monitors:Chest strap and earbud-based pulse detection provide accessible intensity guidance. Corporate wellness programs favor this entry-level integration for cost-controlled deployments.
- Third-Party Apps:API connections to nutrition trackers, recovery platforms, and route planning tools consolidate training data. Data portability expectations are rising among European users under GDPR-informed consent frameworks.
Smart Trainer Sync anchors technical differentiation. Power Meters is gaining share fastest among performance-oriented platform tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FTC monitors subscription cancellation practices for fitness apps operating across the United States. Germany's DiGA framework enables physician-prescribed cycling interventions. Boutique studios in Berlin and Munich are expanding immersive training platform subscriptions.
United States
Connected fitness hardware penetration among home enthusiasts creates the deepest addressable pool for platform conversion. The FTC scrutinizes auto-renewal disclosures and cancellation friction for subscription services. Silicon Valley cloud infrastructure investments compress latency thresholds for real-time 3D streaming workloads.
Germany
Boutique fitness studios in Berlin and Munich are bundling smart trainers with immersive software subscriptions to differentiate member experiences. The DiGA digital health framework enables physician reimbursement for qualifying cycling interventions prescribed through rehabilitation centers. Hardware-software integration clusters concentrate in Bavaria and North Rhine-Westphalia.
United Kingdom
Serious amateur cyclist segments demand power meter ecosystem integration as a platform selection prerequisite. GDPR compliance constrains biometric data processing for personalized coaching algorithms. London and Manchester host competitive cycling communities migrating toward photogrammetry-based virtual course replication.
Saudi Arabia
Fitness infrastructure investments create first-mover advantages for platforms localizing event calendars and payment systems. Edge computing pilots at premium indoor cycling venues minimize round-trip latency for competitive racing applications. Riyadh and Jeddah anchor national expansion of connected wellness facilities.
United Arab Emirates
Fitness operators in Dubai and Abu Dhabi deploy gamification mechanics to differentiate member experiences in saturated urban markets. The national health regulator oversees digital wellness platform claims. Corporate wellness programs subsidize employee access as health benefit investments.
Indoor Cycling Software Market Key Industry Players
Capability concentration sits with immersive rendering specialists; scale advantage sits with subscription-aggregating platforms. The vendor base separates into three functional tiers: proprietary 3D engine operators, structured workout protocol specialists, and price-positioned market extenders. Dominant competitive moves include hardware-software bundling arrangements with smart trainer manufacturers and geographic localization of event calendars for Middle Eastern and Asian market entry.
Within the immersive rendering tier, Zwift occupies a position exemplifying proprietary engine investment. TrainerRoad represents the structured protocol archetype for serious amateur segments. MyWhoosh sits within the price-competitive expansion vector targeting underpenetrated markets through localized offerings.
| Leading Market Players |
|---|
| Wahoo SYSTM |
| TrainingPeaks Virtual |
| Zwift |
| FulGaz |
| icTrainer |
| TrainerRoad |
| MyWhoosh |
| bkool |
| Rouvy |
| Others |
Cost & Logistics Intelligence
Taiwan-based electromagnetic resistance unit manufacturing concentrates upstream capability, anchoring margin capture in smart trainer certification tiers while software platforms compete downstream on subscription bundling and telemetry integration depth.
Pricing Analysis
United States home enthusiasts pay premium rates for power meter ecosystem compatibility, while Middle Eastern markets absorb entry-level tiers through localized payment systems. Three-tier pricing structure across premium, standard, and economy levels separates Zwift's proprietary engine subscribers from TrainerRoad's structured protocol users and MyWhoosh's price-positioned base. Cost compression in cloud compute tiers is intensifying because AWS and Azure egress pricing volatility exposes platform margins. Corporate wellness programs in France exhibit highest price sensitivity due to occupational health mandate budget constraints, whereas German rehabilitation centers under DiGA show lowest sensitivity given physician reimbursement pathways.
Supply Chain Analysis
Foxconn and Pegatron hold contract manufacturing capacity for consumer cycling hardware, with Quanta Computer anchoring server infrastructure for cloud-rendered platforms. Taiwan, China, and Vietnam concentrate electromagnetic actuator and sensor component production. Raw material dependencies span neodymium magnets for resistance units, silicon wafers for Bluetooth Low Energy chipsets, and aluminum extrusions for trainer frames. Single-source vulnerability runs through Taiwan-based firmware certification labs that gate ANT+ and Bluetooth interoperability. Distribution runs through direct-to-consumer channels in United States markets and boutique studio bundling arrangements in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in indoor cycling software hinge on smart trainer interoperability standards, with Bluetooth FTMS protocol adoption reshaping how hardware-software margin pools are contested and captured.
For Market Incumbents: Insulate proprietary telemetry ecosystems by deepening certification partnerships with Taiwan-based electromagnetic resistance manufacturers. Accelerate edge computing deployments in Saudi fitness infrastructure to preempt latency-based switching. ANT+ and Bluetooth protocol fragmentation poses the central threat to hardware-software bundling economics.
For New Entrants and Emerging Players: Saudi Arabia and UAE fitness infrastructure investments offer white-space entry through localized event calendars and Arabic-language interface development. Rehabilitation centers in Germany present the most penetrable segment under DiGA reimbursement pathways. A physician-prescribed cycling intervention go-to-market angle bypasses direct consumer acquisition costs.
For Investors and Strategic Acquirers: Capital is best deployed toward algorithmic coaching engine specialists with EU AI Act compliance infrastructure already operational. Long-term viability across the analysis window favors platforms with demonstrated biometric inference capabilities and transparent automated decision-making architectures. Watch for FTC enforcement actions on subscription cancellation practices as an inflection signal for United States market access risk.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Investment | Algorithmic transparency mandates from Brussels create competitive moats for early-compliant coaching engines. |
| Edge Computing Pilot Expansion | Saudi fitness infrastructure investments reward latency-minimizing platforms with premium venue partnerships. |
| DiGA Reimbursement Pathway Development | German physician-prescribed cycling interventions unlock institutional subscriber bases with predictable recurring revenue. |
| Bluetooth Low Energy 5.3 Migration | Enhanced broadcast capacity enables multi-rider telemetry without local network congestion in boutique studios. |
| Photogrammetry Course Library Expansion | Centimeter-grade virtual course replication deepens switching costs for competitive cyclist segments in the United Kingdom. |
Research Approach
The analysis maps cloud-based deployment architectures, on-premise facility installations, edge computing pilots, and hybrid corporate wellness configurations, each validated through platform engineering leads, boutique studio operators, smart trainer procurement managers, and rehabilitation center clinicians. Primary interviews combined with secondary validation from SEC filings of connected fitness hardware manufacturers, App Annie mobile engagement data, hyperscaler capex disclosures from AWS and Azure, and EU Digital Services Act implementation guidance. Bottom-up subscriber conversion modeling triangulated against top-down addressable market sizing across deployment and solution type segments.
Assumptions held fixed include broadband penetration rates supporting 4K streaming workloads and smart trainer hardware replacement cycles, while cloud compute pricing trajectories and regulatory enforcement timelines were varied across sensitivity scenarios. Segmentation dimensions modeled span deployment architecture, solution functionality, end user type, and integration depth, with regional adoption patterns capturing United States home enthusiast penetration, German DiGA reimbursement velocity, and Middle Eastern fitness infrastructure investment cadence. CAGRs were derived from subscriber growth rate extrapolation tempered by churn assumptions and average revenue per user trajectories, with biometric sensor ecosystem expansion and algorithmic coaching accuracy improvement serving as key forecast inputs.
Practitioners should monitor FTC subscription cancellation enforcement actions, EU AI Act implementation timelines, and Taiwan-based manufacturing cluster disruptions for early signals of forecast revision. Forecasts reflect assumptions regarding cloud infrastructure cost stability and hardware-software bundling economics. Quarterly review of smart trainer certification backlog durations and platform subscriber acquisition cost trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Car-Hailing Software Market
Software & Services
Global ERP Software Market
Software & Services
Dental Practice Management Software Market
Software & Services
Global Software Asset Management Market
Software & Services
Global Gym Software Market
Software & Services
Admission Management Software Market
Software & Services
App Uninstall Software Market
Software & Services
Smartphone OS Market
Software & Services
Driver Updater Software Market
Software & Services
Tenant Billing System Market
Software & Services
Nonconformance Management Software Market
Software & Services
Photobooth Software Market
Software & Services
Software Consulting Market
Software & Services
Construction Software As A Service Market
Software & Services
Video Editing Software Market
Software & Services
Global Intranet Software Market