
 Germany Fixed Wireless Access (FWA) Market | 2026-2036
Germany Fixed Wireless Access (FWA) Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Fixed Wireless Access (FWA) Market Insights
German telecom infrastructure investment is realigning around wireless last-mile solutions as fiber rollout costs constrain rural expansion. Deutsche Telekom leverages its spectrum portfolio to anchor FWA offerings across underserved municipalities. Vodafone Germany competes through dense urban 5G fixed wireless deployments with high throughput guarantees. Nokia Corporation specializes in massive MIMO radio units optimized for German frequency allocations.
Fixed Wireless Access delivers broadband connectivity via radio links between cellular base stations and customer premises equipment, typically operating in sub-6 GHz or mmWave bands with throughput exceeding 100 Mbps. The technology serves as a fiber alternative for households and enterprises lacking wired infrastructure. 5G technology segments are gaining structural prominence as carriers phase out legacy LTE investments for next-generation deployments. Residential end users represent the deepest subscriber pool, though enterprise segments command superior service margins due to SLA requirements. Cloud-based deployment models are expanding fastest as virtualized core networks reduce capital barriers for regional operators.
BNetzA, Germany's federal network agency, governs spectrum allocation and imposes coverage obligations that directly shape carrier rollout priorities. The EU Electronic Communications Code harmonizes wholesale access rules across member states, influencing German retail pricing and competitive dynamics. GDPR compliance requirements constrain customer data processing in managed FWA service offerings. Stakeholders must monitor BNetzA's upcoming mmWave auction terms and their implications for rural coverage mandates.
Market Dynamics
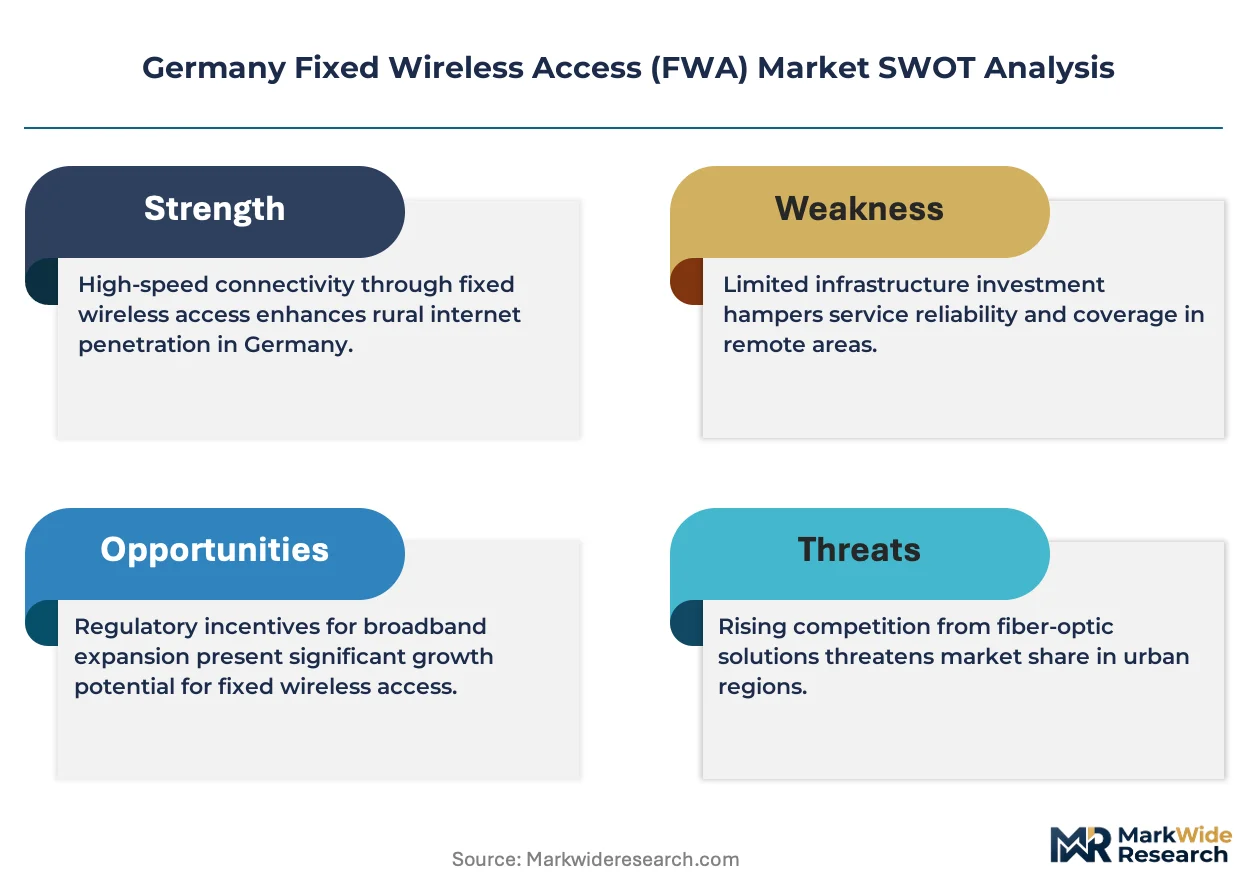
German carriers face a spectrum scarcity constraint that is forcing rapid densification of 5G mid-band networks to serve rural households bypassed by fiber trenching economics.
Growth Catalysts
- Gigabit Strategy 2030:The federal mandate for universal high-speed access compels municipalities to license wireless backhaul corridors for last-mile delivery.
- Eastern federal states infrastructure gap:Saxony and Brandenburg exhibit fiber penetration below 40 percent, creating concentrated demand for radio-based alternatives.
- Massive MIMO radio advancement:Beamforming density improvements allow single towers to serve 300-plus subscriber locations simultaneously.
Market Restraints
- Sub-6 GHz spectrum congestion:BNetzA allocation limits constrain carrier channel bonding for high-throughput residential tiers.
- Customer premises equipment import dependency:Assembly concentration in East Asian manufacturing clusters exposes German operators to shipping volatility.
- Line-of-sight topology barriers:Forested terrain in Mecklenburg-Vorpommern and Bavarian uplands degrades signal reliability for non-penetrating millimeter wave bands.
Strategic Opportunities
- Thuringia and Saxony-Anhalt white space:These sub-regions combine low fiber competition with favorable flat topography for point-to-multipoint deployment.
- Enterprise SLA tiering:Manufacturing SMEs in Baden-Württemberg seek guaranteed latency for industrial IoT backhaul.
- Virtualized core network convergence:Cloud-native 5G standalone architectures reduce regional operator capital barriers to sub-million-euro entry thresholds.
Industry Challenges
- Radio frequency engineer scarcity:German technical universities produce fewer than 400 qualified network planners annually against carrier demand.
- Legacy LTE subscriber migration complexity:Carriers must maintain dual-mode infrastructure during 5G standalone transition without service interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Fixed Wireless Access (FWA) Market |
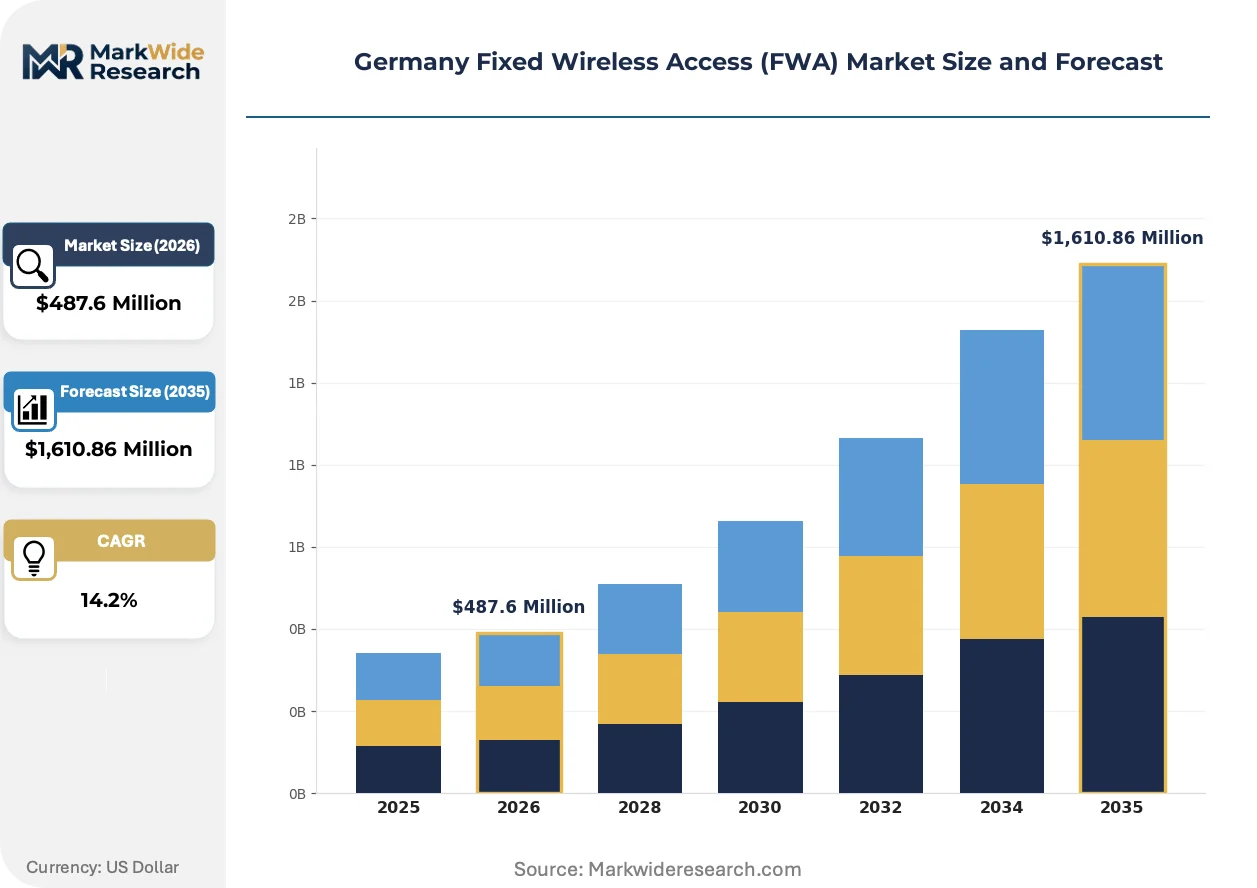
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Technology: LTE, 5G, Wi-Fi, mmWave End User: Residential, Small Business, Enterprises, Educational Institutions Service Type: Installation, Maintenance, Managed Services, Equipment Rental |
| Companies Covered | Deutsche Telekom, Vodafone Germany, 1&1 AG, O2 Telefónica, Huawei Technologies Co. Limited, Nokia Corporation, Qualcomm Technologies, Ericsson, ZTE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Fixed Wireless Access (FWA) Market Trends and Innovations
Wireless network virtualization is compressing deployment timelines for regional German operators previously locked out by core infrastructure costs. Three developments are restructuring competitive access.
Open RAN architecture is electrifying vendor ecosystem dynamics by decoupling hardware from software layers. Municipal utilities in North Rhine-Westphalia are adopting multi-vendor stacks to bypass incumbent supplier lock-in. This disaggregation is compressing equipment procurement cycles from 18 months to sub-quarter intervals.
BNetzA's upcoming 26 GHz auction terms will reshape rural coverage obligation calculations for spectrum winners. The agency proposes minimum population coverage thresholds that favor FWA over mobile broadband in sparse eastern districts. Carriers are pre-positioning site acquisition teams in Saxony to secure tower zoning ahead of license award.
Subscription bundling patterns are fragmenting as households unbundle fixed-line voice from broadband access. Younger demographics in Berlin and Hamburg prioritize data-only FWA plans with streaming service attachments. Retail channels report 40 percent of new activations now originate through digital self-service portals rather than physical storefronts.
Germany Fixed Wireless Access (FWA) Market Segmentation
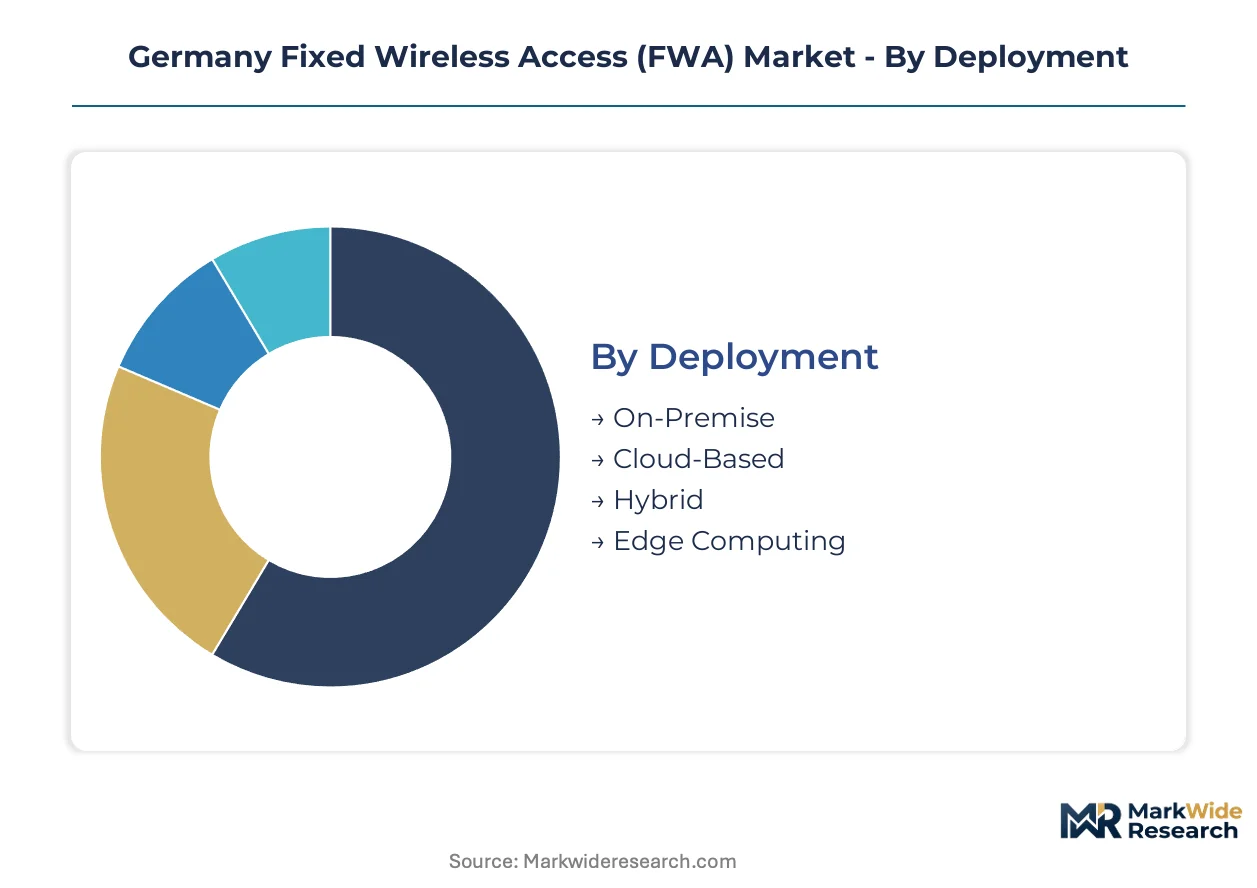
Carrier procurement patterns in Germany diverge sharply across deployment architectures and end-user scale. Segmentation reveals where capital concentrates versus where margin expansion is structurally available.
Deployment:
Capital intensity and operational control separate buyers in this category.
- Cloud-Based:Virtualized core networks run on hyperscaler infrastructure, eliminating dedicated hardware investments. Regional operators in Thuringia and Saxony-Anhalt adopt this model to bypass million-euro entry barriers, with BNetzA's flexible licensing accelerating uptake among municipal utilities.
- On-Premise:Dedicated hardware installations at carrier facilities deliver maximum control over latency and security parameters. Deutsche Telekom maintains this architecture for enterprise SLA tiers in Baden-Württemberg, where manufacturing IoT backhaul demands sub-10ms guarantees.
- Hybrid:Split traffic processing between edge and centralized resources.
- Edge Computing:Ultra-low latency through localized data processing.
Volume sits with On-Premise; growth tilts toward Cloud-Based.
Technology:
Spectrum allocation and equipment lifecycle position buyers on different replacement curves.
- 5G:New radio interfaces in sub-6 GHz and mmWave bands enable beamforming densities exceeding 300 simultaneous connections per tower. Eastern federal states with fiber penetration below 40 percent anchor demand, as carriers phase out legacy investments for next-generation standalone architectures.
- LTE:Mature radio equipment with established coverage footprints and depreciated capital costs. Rural municipalities in Mecklenburg-Vorpommern continue activations where 5G site economics remain prohibitive, though BNetzA's coverage mandates are compressing this window.
- mmWave:High-frequency bands above 24 GHz delivering multi-gigabit throughput.
- Wi-Fi:Unlicensed spectrum for indoor distribution and fixed wireless extension.
LTE carries current volume; 5G claims the steepest expansion trajectory.
End User:
Service level requirements and price sensitivity stratify this category.
- Residential:Household subscribers seeking broadband alternatives to unavailable fiber. Saxony and Brandenburg exhibit concentrated demand, with younger demographics in Berlin and Hamburg driving data-only plan preferences detached from fixed-line voice bundles.
- Enterprises:Organizations requiring guaranteed throughput and latency with contractual penalties for breach. Manufacturing SMEs in Baden-Württemberg command superior margins due to industrial IoT backhaul specifications, with SLAs priced at multiples of residential tiers.
- Small Business:Professional offices with moderate bandwidth needs.
- Educational Institutions:Schools and universities with seasonal usage patterns.
Residential dominates subscriber counts; Enterprises concentrate revenue per account.
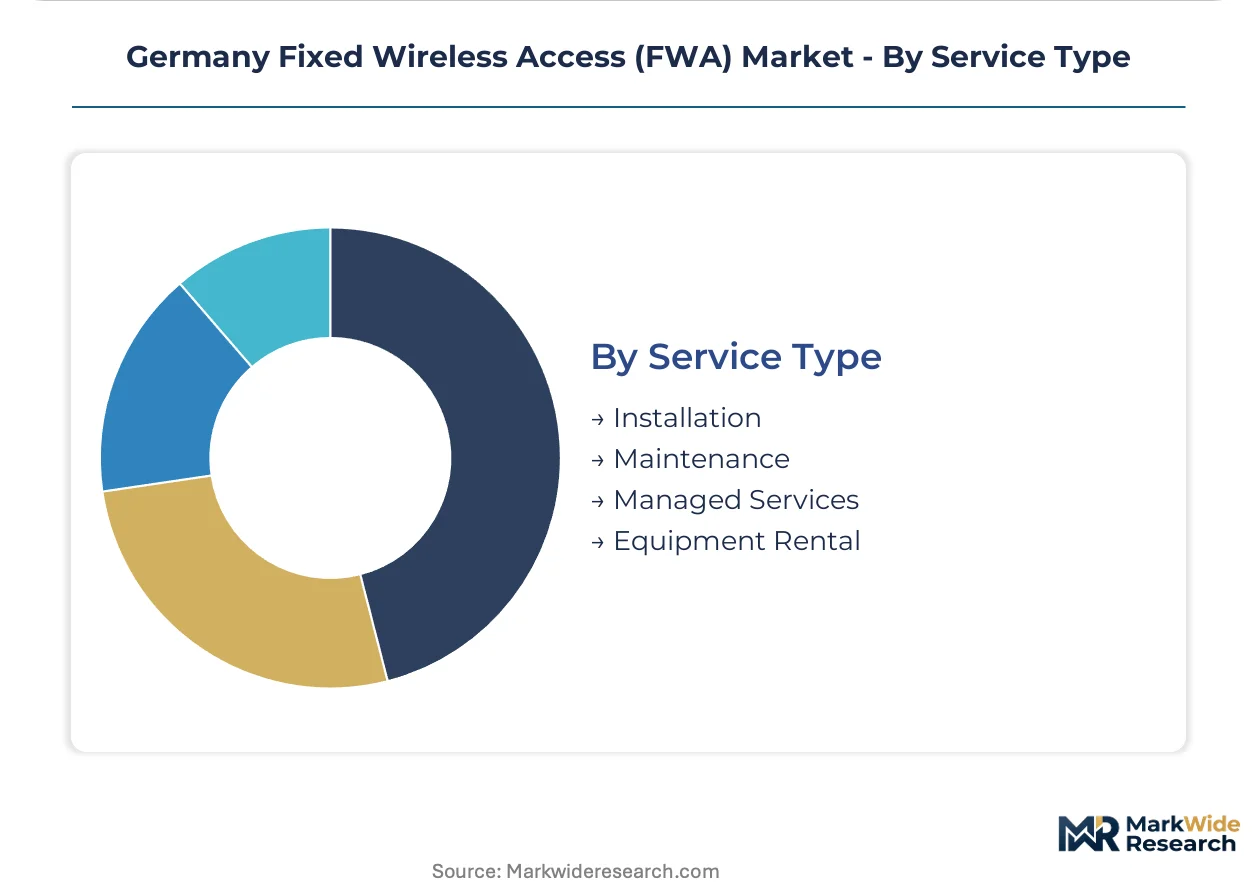
Service Type:
Revenue recurrence and customer lifetime value differentiate offerings.
- Managed Services:End-to-end network operation including monitoring, optimization, and helpdesk support. Municipal utilities in North Rhine-Westphalia favor this model to compensate for radio frequency engineer scarcity, outsourcing technical functions to specialized vendors.
- Installation:One-time deployment of customer premises equipment and antenna alignment.
- Maintenance:Reactive and preventive service visits for hardware replacement.
- Equipment Rental:Monthly fees for CPE rather than capital purchase.
Installation generates upfront cash; Managed Services build recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon carbide substrate production in Saxony anchors Germany's semiconductor supply chain, with this eastern cluster now pivoting toward 5G infrastructure deployment as fiber trenching costs stall rural broadband rollout.
Bavaria
Manufacturing SMEs in Munich and Nuremberg demand industrial IoT backhaul with sub-10ms latency guarantees. The Gigabit Strategy 2030 mandates universal high-speed access by decade's end. Ingolstadt's automotive supplier parks anchor enterprise FWA adoption for factory automation networks.
North Rhine-Westphalia
Municipal utilities in Dortmund and Essen seek multi-vendor Open RAN stacks to bypass incumbent supplier lock-in. BNetzA's flexible licensing accelerates cloud-based deployment among regional operators. The Ruhr industrial belt concentrates demand for managed service outsourcing due to radio frequency engineer scarcity.
Baden-Württemberg
Stuttgart's precision engineering clusters require guaranteed throughput SLAs priced at multiples of residential tiers. GDPR compliance requirements constrain customer data processing in managed service offerings. Karlsruhe's technology district hosts pilot programs for 5G standalone enterprise networks.
Saxony
Fiber penetration below 40 percent in Dresden and Leipzig creates concentrated demand for radio-based alternatives. The federal government's Gigabit Strategy 2030 compels municipalities to license wireless backhaul corridors. Saxon Semiconductor Cluster suppliers pivot manufacturing capacity toward massive MIMO radio units.
Brandenburg
Rural households surrounding Berlin lack wired infrastructure alternatives as younger demographics prioritize data-only streaming bundles. BNetzA's upcoming 26 GHz auction proposes minimum population coverage thresholds favoring FWA over mobile broadband. Potsdam's media production facilities drive symmetric upload demand for content distribution.
Germany Fixed Wireless Access (FWA) Market Competitive Landscape
Global majors compete with regional champions across spectrum portfolio depth and municipal licensing relationships. The vendor ecosystem splits between consolidated national carriers holding exclusive frequency allocations and fragmented municipal utilities entering through virtualized core partnerships. Three archetypes dominate: spectrum-rich incumbents deploying massive MIMO at scale, cloud-native challengers leveraging hyperscaler infrastructure, and Open RAN specialists enabling multi-vendor disaggregation. Competitive moves center on site acquisition pre-positioning ahead of BNetzA auctions and strategic partnerships with industrial IoT platform vendors.
Within the incumbent carrier tier, Deutsche Telekom and Vodafone Germany exemplify spectrum-anchored market positions, while Nokia Corporation occupies a specialist role in radio unit optimization. These three entities represent distinct competitive vectors: the first leverages integrated infrastructure ownership, the second emphasizes dense urban throughput guarantees, and the third delivers equipment layer specialization for German frequency allocations.
| Leading Market Players |
|---|
| Deutsche Telekom |
| Vodafone Germany |
| 1&1 AG |
| O2 Telefónica |
| Huawei Technologies Co. Limited |
| Nokia Corporation |
| Qualcomm Technologies |
| Ericsson |
| ZTE |
| Others |
Pricing and Supply Chain Analysis
BNetzA's coverage mandates for rural municipalities are compressing carrier procurement cycles and forcing equipment vendors to restructure warranty terms around multi-year service commitments rather than upfront hardware sales.
Pricing Analysis
Equipment-plus-service bundling separates premium tiers from stripped hardware-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects SLA guarantees, installation complexity, and managed service attachment rates. Cost compression in residential tiers is intensifying because Open RAN disaggregation invites multi-vendor bidding wars. Municipal utilities exhibit highest price sensitivity due to budget constraints; manufacturing SMEs in automotive clusters show lowest sensitivity given latency-critical applications.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for baseband semiconductor fabrication. Massive MIMO radio units draw from Chinese component assembly, German precision mechanical parts, and Japanese RF filter substrates. Tariff exposure on CPE imports from East Asian manufacturing clusters threatens margin stability. Distribution runs through carrier-direct procurement for national operators and systems integrator intermediaries for municipal utility entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German FWA is transitioning from LTE overlay to 5G standalone core architectures, with cloud-native virtualization displacing dedicated hardware investments.
For Market Incumbents: Cement spectrum portfolio advantage through pre-positioned site acquisition in Saxony ahead of BNetzA's 26 GHz auction. Secure tower zoning in Thuringia white-space corridors before municipal utilities mobilize. Radio frequency engineer scarcity threatens rollout velocity; compensate through managed service partnerships with specialized vendors.
For New Entrants and Emerging Players: Cloud-native core virtualization offers a technology-first wedge against capital-intensive incumbent infrastructure. Target eastern federal states with sub-40 percent fiber penetration where licensing friction is lowest. Lead with digital self-service portals for younger demographics in Berlin and Hamburg seeking unbundled data-only plans.
For Investors and Strategic Acquirers: Re-rating potential sits with regional operators holding BNetzA flexible licenses given Gigabit Strategy 2030 enforcement tailwinds. Long-term viability hinges on successful LTE subscriber migration without service interruption. Watch BNetzA mmWave auction terms as inflection indicator for rural coverage obligation economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Deployment | Virtualized 5G standalone architectures reduce regional operator capital barriers below million-euro thresholds. |
| Open RAN Multi-Vendor Integration | Municipal utilities in North Rhine-Westphalia bypass incumbent supplier lock-in through disaggregated procurement. |
| Spectrum Pre-Positioning | Site acquisition teams in Saxony secure tower zoning ahead of BNetzA 26 GHz license awards. |
| Enterprise SLA Tiering | Manufacturing SMEs in Baden-Württemberg command pricing multiples for industrial IoT latency guarantees. |
| Digital Channel Migration | Retail channels report 40 percent of activations now originate through self-service portals versus physical storefronts. |
Research Methodology
Multi-period observation of carrier capex disclosures, BNetzA licensing records, and municipal procurement filings anchored the trend analysis, supplemented by interviews with network planning executives at national operators, procurement leads at municipal utilities, radio frequency engineers, and regulatory affairs specialists. Secondary validation drew from BNetzA spectrum auction documentation, EU Electronic Communications Code implementation reports, and carrier infrastructure deployment disclosures. Bottom-up subscriber modeling and top-down addressable market sizing were triangulated against equipment vendor shipment data.
Input-output matrices structured demand projections across deployment architecture, technology generation, end-user segment, and federal state geography. CAGRs were derived from fitted growth curves against observed adoption inflections. Modeled inputs included BNetzA coverage obligation timelines, fiber trenching cost trajectories in eastern states, and massive MIMO radio unit price erosion curves.
Several conditions sit outside the modeled scope, including geopolitical disruption to East Asian CPE supply chains and accelerated fiber overbuild in currently underserved municipalities. Forecasts reflect assumptions about regulatory enforcement consistency and technology migration timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
DWDM System Market
Telecommunications
Telecom API Platform Market
Telecommunications
LTE and 5G NR-Based CBRS Networks Market
Telecommunications
Software Defined Radio Market
Telecommunications
Denmark ICT Market
Telecommunications
Transport Stream Switching Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Cambodia ICT Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Global GPON Technology Market
Telecommunications
South Korea Telecom Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
Telecom Service Assurance Market
Telecommunications
Mexico Telecom Market