
 Free Space Optics (FSO) Communication Market | 2026-2036
Free Space Optics (FSO) Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Free Space Optics (FSO) Communication Market Analysis
Laser beam tracking and adaptive optics is reconfiguring how FSO terminals maintain connectivity through atmospheric turbulence. fSONA Networks leverages hardened maritime and defense-grade terminals to sustain long-haul coastal links. LightPointe Communications anchors its position in enterprise bridge applications, competing on hybrid radio-laser failover architectures. Mynaric AG dominates optical inter-satellite link manufacturing, extending its reach across European and North American space programs.
Free Space Optics communication transmits data through modulated light beams in unguided atmospheric or vacuum channels, typically operating at wavelengths between 780 nm and 1550 nm with gigabit-per-second throughput and minimal electromagnetic interference. Its primary commercial purpose is to deliver high-bandwidth, license-free connectivity where fiber installation proves impractical or where radio frequency congestion limits traditional wireless. Laser technology leads the technology dimension due to its superior power efficiency and beam collimation for long-distance links, while LED-based systems occupy a growing niche in short-range indoor and campus deployments. The military application segment concentrates the highest-margin procurement pools, whereas telecommunications infrastructure represents the largest volume opportunity as carriers seek backhaul alternatives in dense urban corridors.
The FCC governs unlicensed optical transmission power limits in the United States, while the ETSI framework in Europe harmonizes cross-border equipment certification for terrestrial and aerial FSO links. The ITU-R coordinates spectrum-sharing protocols between satellite-based optical terminals and terrestrial networks, shaping how manufacturers design dual-use hardware for space and ground applications. Stakeholders must monitor how national security export controls on laser components reshape supplier eligibility for defense contracts across NATO procurement frameworks.
Market Dynamics
Laser beam tracking and adaptive optics are compressing link establishment times while expanding operational weather windows for FSO terminals. Military procurement specifications now mandate sub-arcsecond tracking precision, forcing component suppliers to redesign gimbal assemblies and wavefront sensors around hardened aerospace standards.
Growth Catalysts
- FCC spectrum allocation rulings:The United States regulator is accelerating FSO deployment as a licensed-frequency alternative for dense urban corridors. Carriers now route emergency backhaul through optical links when microwave bands congest.
- Optical inter-satellite terminals:Government constellation programs across NATO member states are expanding procurement of secure laser-based links for battlefield communications. Terminal manufacturers are scaling cleanroom capacity to meet multi-year procurement schedules.
- Telecommunications infrastructure backhaul:Dense urban corridors present fiber installation impracticalities that FSO resolves with gigabit-per-second throughput. License-free operation eliminates spectrum coordination delays that plague microwave deployments.
Market Restraints
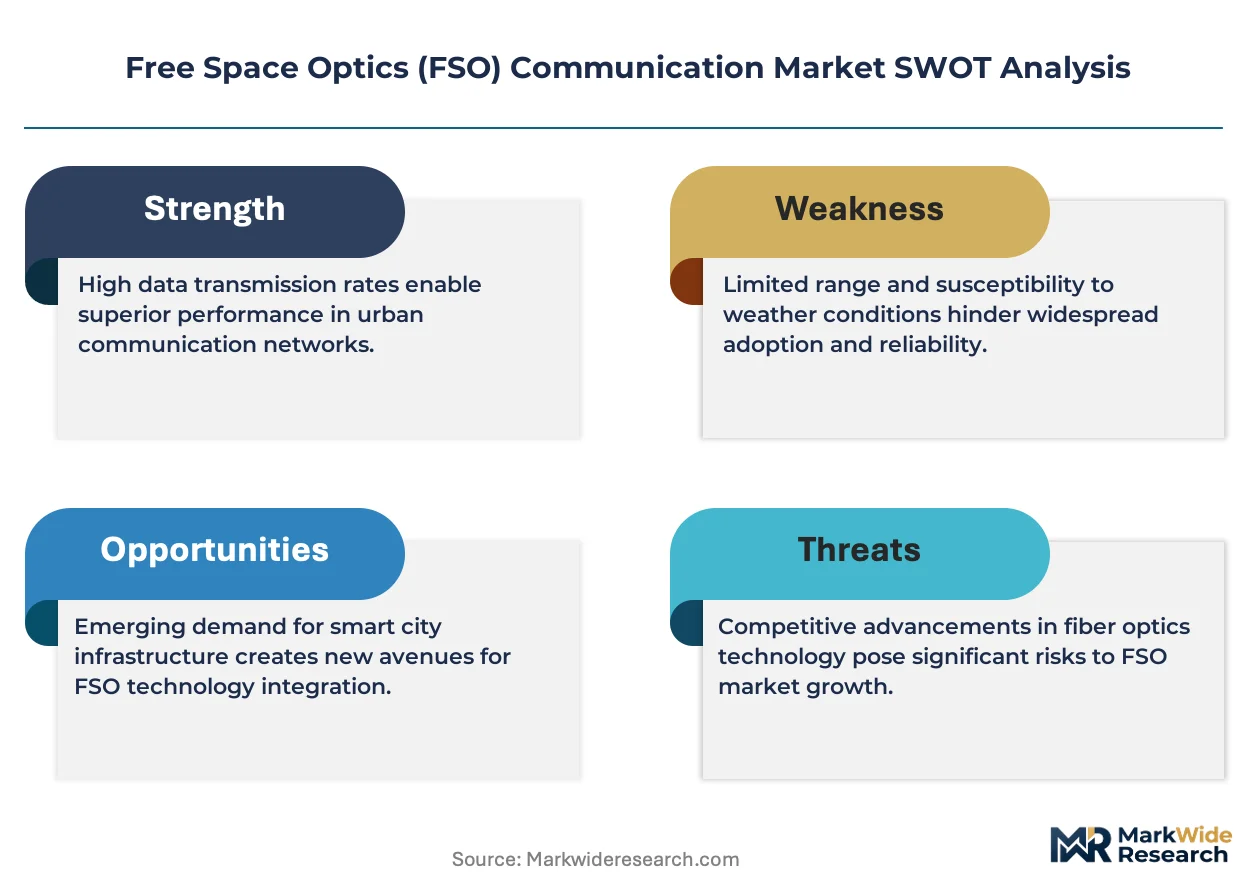
- Atmospheric turbulence degradation:Scintillation and beam wander impose fundamental physical limits on link availability in coastal and desert climates. Adaptive optics add cost and complexity that price out campus and small enterprise segments.
- Precision optics supply concentration:German and Japanese suppliers dominate deformable mirror and fast-steering mirror production. Geopolitical export controls on dual-use laser components threaten delivery schedules for defense contractors.
- Radio frequency fallback systems:Hybrid architectures that combine millimeter-wave backup with primary optical links capture risk-averse buyers. Pure-play FSO vendors face displacement where all-weather availability dominates specification sheets.
Strategic Opportunities
- Maritime coastal links:Hardened terminals for offshore platforms and port-to-ship communications represent underpenetrated demand. Salt spray and vibration specifications exceed current commercial product durability ratings.
- ITU-R spectrum-sharing protocols:The global framework coordinates satellite-based optical terminals with terrestrial networks. Dual-use hardware designs that serve space and ground applications qualify manufacturers for expanded procurement pools.
- LED-based indoor campus systems:Short-range visible light communication converges with FSO engineering expertise. Universities and corporate campuses seek interference-free connectivity in electromagnetically sensitive facilities.
Industry Challenges
- Adaptive optics engineering talent scarcity:Wavefront sensor calibration and real-time control algorithm development require specialized photonics expertise. Defense contractors compete with astronomical observatories and medical device manufacturers for limited personnel pools.
- ITAR and EAR compliance complexity:Laser component classifications trigger multi-jurisdiction export licensing requirements. Procurement delays from classification reviews extend contract award-to-delivery timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Free Space Optics (FSO) Communication Market |
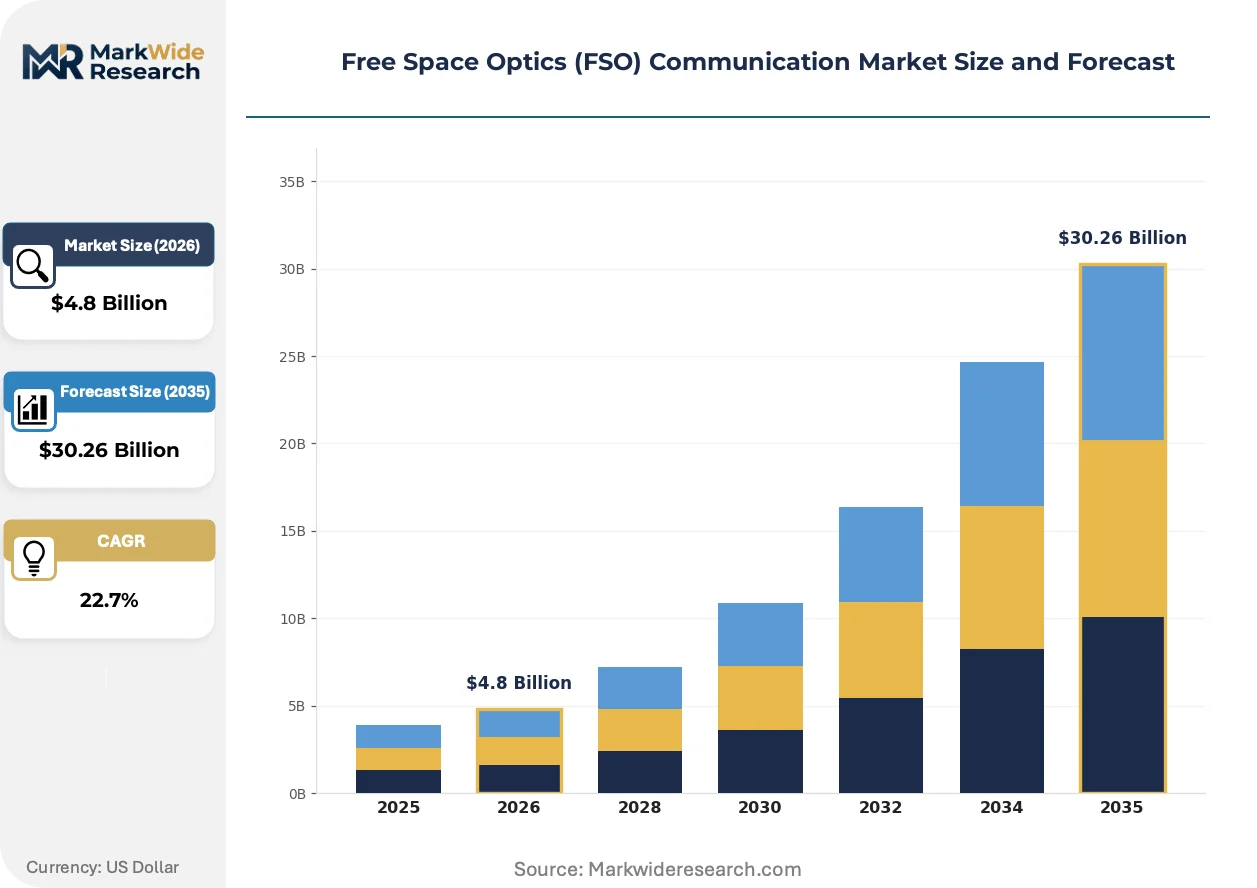
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Data Center, Telecommunications, Military, Security Technology: Laser, LED, Optical Switch, Wavefront Coding End User: Commercial, Government, Research Institutions, Healthcare Deployment: Urban Areas, Suburban Areas, Remote Locations, Temporary Installations |
| Companies Covered | fSONA Networks, LightPointe Communications, Mynaric AG, AOptix Technologies, Wireless Excellence Limited, Cailabs, Mostcom JSC, AIRLINX Communications, EC System, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Free Space Optics (FSO) Communication Market Emerging Trajectories
Beam tracking precision and atmospheric compensation algorithms are compressing the performance gap between laboratory demonstrations and fielded military systems. Component miniaturization is enabling terminal form factors that integrate onto tactical vehicles and small satellites.
Coherent detection with digital signal processing is collapsing the power budget requirements for long-haul maritime links. Naval procurement agencies in NATO member states are specifying terminals that maintain connectivity through sea-state-induced platform motion. The structural consequence is collapsing the minimum viable platform size for autonomous optical communications, opening submarine-to-satellite and unmanned surface vessel applications previously reserved for radio frequency.
ETSI harmonization of cross-border equipment certification for terrestrial and aerial FSO links is standardizing type-approval testing across European Union member states. Manufacturers now design single product variants that satisfy German, French, and Italian national requirements without redesign. The commercial segment benefits most, as enterprise bridge applications demand rapid deployment without jurisdiction-specific regulatory delays.
Defense procurement consolidation around performance-based specifications is displacing component-centric buying patterns. Prime contractors now contract for availability and data rate guarantees rather than discrete terminal purchases. The United States military application segment exhibits this shift most visibly, with multi-year service contracts replacing transactional hardware acquisitions.
Free Space Optics (FSO) Communication Market Segmentation
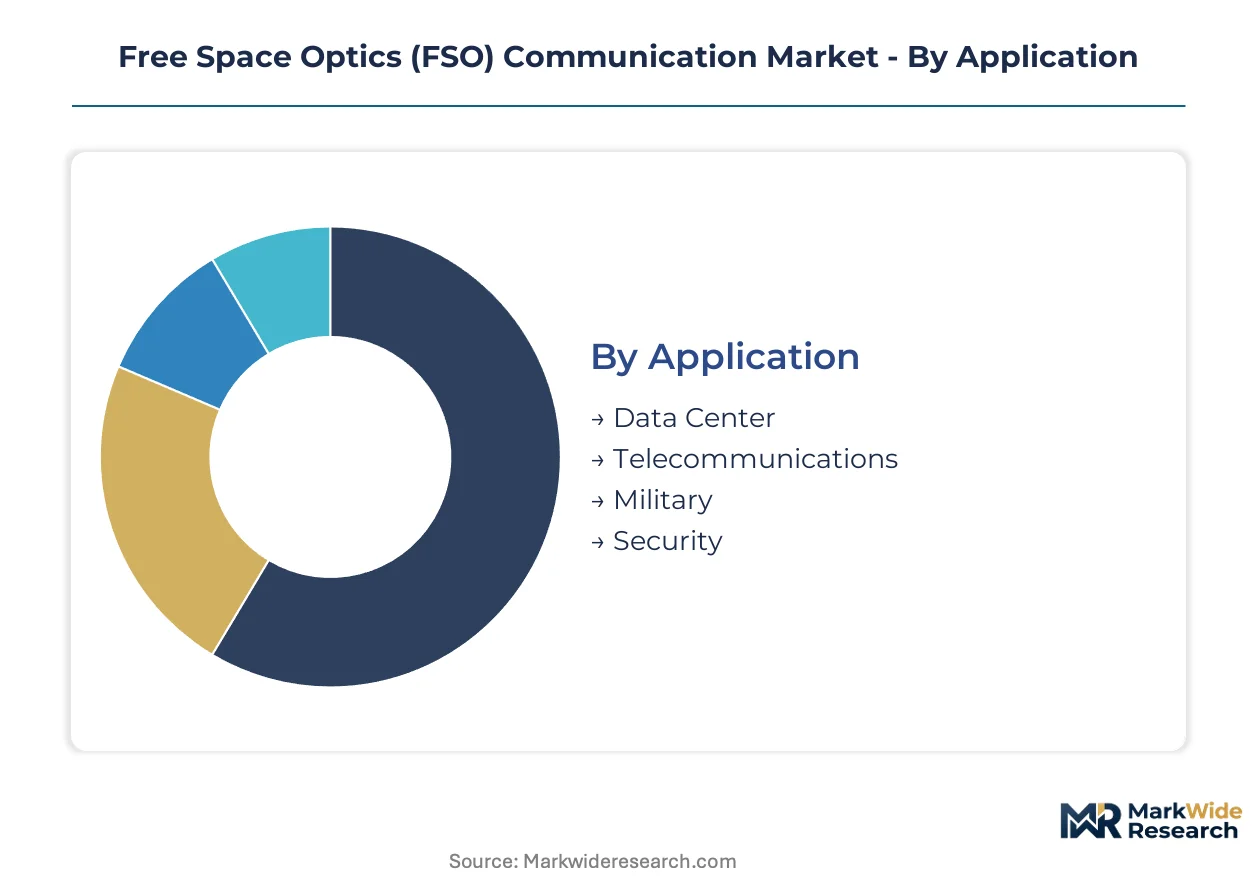
FSO procurement patterns diverge sharply across application environments, with military specifications demanding hardened hardware while commercial buyers prioritize rapid deployment economics. Technology selection, end-user category, and deployment topology each impose distinct engineering constraints that shape supplier product roadmaps and pricing architectures.
Application:
Cost tier differentiation across FSO applications separates mission-critical defense procurement from volume-driven commercial infrastructure spending.
- Data Center:High-density optical interconnects serve hyperscale facilities requiring terabit-scale throughput between adjacent buildings. Demand clusters in Frankfurt, Amsterdam, and Singapore where land constraints prevent fiber trenching between campus structures. Operators specify sub-10 microsecond latency budgets that exclude radio-frequency alternatives.
- Telecommunications:License-free backhaul links resolve spectrum congestion in dense urban corridors where microwave coordination delays stall 5G rollout timelines. Carriers in Germany and the United States route emergency capacity through optical bridges when licensed bands saturate during peak events.
- Military:NATO battlefield communications programs mandate sub-arcsecond tracking precision for tactical vehicle and satellite integration.
- Security:Surveillance networks deploy covert optical links immune to RF detection and jamming protocols.
Telecommunications holds installed capacity. Military is rotating up the share rankings.
Technology:
Application requirements dictate technology selection, with power efficiency and beam collimation driving long-range procurement decisions.
- Laser:Diode and fiber laser sources deliver superior power efficiency and narrow beam divergence for inter-satellite and maritime links. Wavelength selection at 1550 nm versus 780 nm trades eye safety certification against atmospheric transmission windows, with defense contractors standardizing on the longer wavelength for personnel protection compliance.
- LED:Visible light and infrared LED systems occupy short-range indoor applications where eye safety and electromagnetic immunity outweigh bandwidth requirements. Corporate campuses and healthcare facilities in Japan specify LED-based visible light communication for electromagnetically sensitive zones.
- Optical Switch:Beam steering without mechanical gimbals reduces maintenance intervals and vibration susceptibility for satellite terminals.
- Wavefront Coding:Computational imaging techniques extend depth of field in turbulent atmospheric conditions without adaptive optics hardware.
Laser dominates current procurement volumes. LED is climbing the fastest among emerging technology categories.
End User:
Customer type determines specification stringency, with government procurement mandating aerospace-grade qualification protocols absent from commercial buying.
- Commercial:Enterprise bridge applications prioritize rapid deployment and hybrid radio-laser failover architectures. Financial services firms in London and New York specify optical links for trading floor disaster recovery where RF congestion threatens backup connectivity.
- Government:Military and civilian agencies specify availability guarantees and multi-year service contracts rather than discrete hardware purchases. United States Space Force procurement consolidates around performance-based specifications displacing component-centric acquisition patterns.
- Research Institutions:Astronomical observatories and particle physics facilities source wavefront sensors and deformable mirrors for atmospheric compensation experiments.
- Healthcare:Hospital networks deploy optical links to isolate medical imaging networks from electromagnetic interference in MRI suites.
Government holds qualification-driven procurement volume. Commercial is gaining share fastest as enterprise bridge applications standardize.
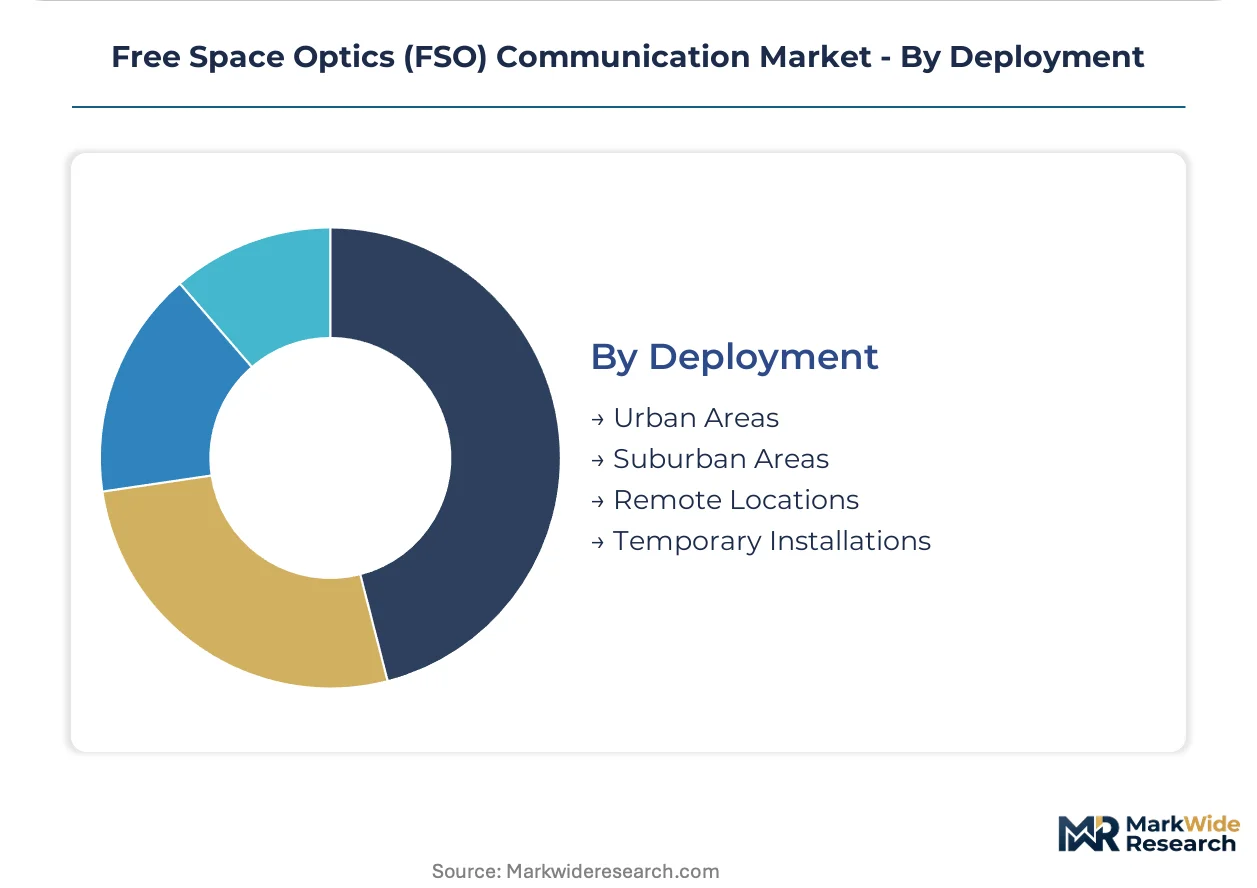
Deployment:
Geography and installation duration shape hardware durability requirements and regulatory compliance scope.
- Urban Areas:Dense building environments create multipath interference and line-of-sight obstruction challenges resolved through rooftop relay architectures. Municipal permitting in German cities favors optical links over fiber trenching through historic districts.
- Suburban Areas:Moderate density corridors present favorable link budgets with reduced atmospheric turbulence compared to coastal or desert extremes. Telecommunications carriers deploy here for 5G backhaul where fiber buildout economics fail.
- Remote Locations:Offshore platforms and mining operations specify hardened terminals exceeding commercial product durability ratings for salt spray and vibration exposure.
- Temporary Installations:Event coverage and disaster response demand rapid-deploy tripods with automated alignment eliminating skilled technician requirements.
Urban Areas concentrate current infrastructure investment. Remote Locations show steepest expansion trajectory as maritime and energy applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports optical inter-satellite terminals to NATO procurement programs across the United States, France, and the United Kingdom, anchoring transatlantic defense supply chains for secure laser-based battlefield communications.
United States
The FCC accelerates FSO deployment through spectrum allocation rulings that position optical links as licensed-frequency alternatives in dense urban corridors. Carriers route emergency backhaul through laser bridges when microwave bands congest during peak demand events. Military procurement in California and Texas concentrates on sub-arcsecond tracking precision for tactical vehicle integration.
Germany
Cleanroom capacity expansion in Bavaria supports multi-year optical terminal production schedules for government constellation programs. ETSI harmonization streamlines cross-border equipment certification across EU member states. Mynaric AG anchors manufacturing clusters near Munich, supplying NATO allies with hardened aerospace-grade terminals.
United Kingdom
Financial services firms in London specify optical links for trading floor disaster recovery where RF congestion threatens backup connectivity. The national regulator coordinates with ETSI frameworks for terrestrial and aerial link certification. Research institutions in Cambridge source wavefront sensors for atmospheric compensation development.
Japan
METI standards guide visible light communication deployment in electromagnetically sensitive healthcare and corporate facilities. LED-based indoor campus systems occupy growing niches in Tokyo and Osaka medical imaging networks. Precision optics suppliers in Nagoya dominate deformable mirror production for adaptive optics integration.
United Arab Emirates
Maritime coastal link specifications for offshore platforms and port-to-ship communications drive hardened terminal demand in Dubai and Abu Dhabi. Salt spray and vibration requirements exceed current commercial durability ratings. Smart city initiatives deploy license-free optical backhaul across dense urban corridors.
Free Space Optics (FSO) Communication Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: defense-prime integrators with multi-year service contracts, commercial bridge specialists competing on hybrid failover architectures, and component-scale suppliers of precision optics. The dominant competitive moves are capacity expansion in cleanroom manufacturing and strategic partnerships for dual-use space-ground hardware qualification.
Within the defense-tier segment, Mynaric AG exemplifies European optical terminal manufacturing, while fSONA Networks represents hardened maritime and defense-grade specialization. LightPointe Communications occupies a position among enterprise bridge providers competing on rapid deployment economics. These three anchors illustrate how geographic origin and customer-type focus stratify competitive positioning across NATO procurement pools and commercial infrastructure markets.
| Leading Market Players |
|---|
| fSONA Networks |
| LightPointe Communications |
| Mynaric AG |
| AOptix Technologies |
| Wireless Excellence Limited |
| Cailabs |
| Mostcom JSC |
| AIRLINX Communications |
| EC System |
| Others |
Supply Flow & Price Mechanics
Bavaria's cleanroom capacity expansion around Munich is compressing lead times for aerospace-grade optical terminals, granting German manufacturers pricing leverage over NATO defense contractors facing multi-year procurement deadlines. This geographic concentration of precision manufacturing feeds directly into tiered contract structures that separate performance-guaranteed service agreements from transactional hardware sales.
Pricing Analysis
Next-generation coherent detection terminals command substantial premiums over legacy direct-detection systems, while prior-generation LED-based campus links face accelerating price erosion from commoditized visible-light components. Three-tier pricing structure across premium, standard, and economy levels separates military-qualified aerospace-grade hardware from commercial bridge equipment and entry-level enterprise failover systems. Pricing pressure stems from hybrid radio-laser architectures capturing risk-averse buyers who previously accepted optical-only premiums. Enterprise bridge applications exhibit highest price sensitivity due to rapid deployment economics, while defense procurement shows lowest sensitivity given availability guarantees and ITAR compliance requirements.
Supply Chain Analysis
Tariff exposure between Japan and the United States threatens deformable mirror delivery schedules for adaptive optics integration in NATO terminal programs. Precision optics manufacturing concentrates in Germany, Japan, and the United States, with cleanroom assembly drawing from specialized photonics foundries in Bavaria and Nagoya. Supply chains rest on indium phosphide laser diodes, fast-steering mirror assemblies, and wavefront sensor arrays vulnerable to single-source concentration in Japanese component houses. Distribution runs through defense prime contractors holding multi-year service contracts, bypassing traditional channel structures for commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSO communication is approaching a platform-economics inflection where ITU-R spectrum-sharing protocols and dual-use hardware qualification standards are collapsing the boundary between space and ground terminal ecosystems, rewarding manufacturers who engineer interoperability from initial design.
For Market Incumbents: Pre-empt displacement from hybrid millimeter-wave failover systems by deepening captive supply of adaptive optics components and securing ETSI pre-certification for terrestrial-aerial dual-use variants. Backward integration into wavefront sensor calibration capabilities defends margin position against emerging photonics specialists entering from astronomical instrumentation markets. For New Entrants and Emerging Players: Establish a beachhead in maritime coastal links for offshore energy platforms, where salt spray and vibration specifications exceed current commercial durability ratings and defense incumbents lack dedicated product lines. LED-based indoor campus systems for electromagnetically sensitive healthcare facilities offer the most penetrable wedge, with go-to-market through medical device distributors already calling on hospital imaging departments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component-scale suppliers of precision optics with transferable expertise across defense, astronomical, and medical device end markets. Long-term viability hinges on qualification moats rather than volume scale, with acquisition target archetypes being cleanroom manufacturing specialists holding dual-use ITAR certifications. The signal to watch is Space Force procurement consolidation around availability-based contracting, which will compress hardware margins while expanding service revenue pools.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Hardware Qualification | ITU-R protocol alignment qualifies manufacturers for expanded NATO and commercial satellite procurement pools simultaneously. |
| Adaptive Optics Talent Acquisition | Wavefront sensor expertise from astronomical observatories accelerates military sub-arcsecond tracking specification compliance. |
| Maritime Terminal Hardening | Salt spray and vibration ratings exceeding commercial standards unlock offshore platform and port-to-ship demand. |
| ETSI Pre-Certification Investment | Single product variants satisfying German, French, and Italian requirements eliminate jurisdiction-specific regulatory delays. |
| Performance-Based Contracting Transition | Availability guarantees displace transactional hardware sales in United States military procurement patterns. |
Methodological Framework
A standing panel of defense procurement officers, optical terminal engineering directors, telecommunications carrier backhaul planners, and precision optics manufacturing executives provided ongoing calibration throughout the study period. Primary interview findings combined with secondary validation from FCC spectrum allocation rulings, ETSI equipment certification databases, NATO procurement disclosure filings, and ITU-R satellite coordination protocols. Bottom-up terminal shipment analysis and top-down defense budget allocation triangulation anchored volume and value estimates.
Scenario-bracketing around atmospheric turbulence degradation severity and export control enforcement intensity bounded forecast uncertainty across the projection horizon. Segmentation modeling incorporated application environment, technology generation, end-user qualification tier, and deployment topology dimensions. CAGRs derived from terminal unit economics scaled against procurement pipeline visibility from disclosed multi-year government constellation programs, with coherent detection adoption curves and LED-based indoor system penetration as industry-specific forecast inputs.
Stress conditions across ITAR licensing delays, deformable mirror supply concentration, and hybrid RF-optical competitive substitution were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding ETSI harmonization timelines and Space Force contracting modality shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
Austria Telecom Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
Kenya Telecom Market
Telecommunications
Argentina ICT Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Vietnam Telecom Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Global LTE Market
Telecommunications
MVNO Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
Italy Telecom Market
Telecommunications
Belgium Telecom Market
Telecommunications
Global International Calling Apps Market