
 Global Dense Wave Digital Multiplexing (DWDM) System Market | 2026-2036
Global Dense Wave Digital Multiplexing (DWDM) System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dense Wave Digital Multiplexing (DWDM) System Market Analysis
China is fragmenting DWDM procurement across state-backed carriers and hyperscale data center operators. Huawei Technologies leverages its captive silicon photonics foundry to dominate domestic 400G coherent deployments. Ciena Corporation anchors transatlantic submarine cable upgrades with its WaveLogic platform. Nokia competes through Open Optical Networking partnerships with European telecom incumbents.
Dense Wave Digital Multiplexing (DWDM) systems transmit multiple optical carrier signals through a single fiber by using different wavelengths of laser light, typically spanning the C-band and L-band with channel spacing of 100 GHz or tighter. These systems maximize fiber capacity for backbone networks, metro rings, and data center interconnects requiring terabit-scale throughput. Transponders and coherent technology segments lead current revenue as 800G rollouts accelerate, while optical amplifiers retain stable margin pools from submarine and long-haul refresh cycles. Add-drop multiplexers and short-reach variants face pricing pressure from pluggable coherent optics displacing traditional chassis-based architectures.
FCC spectrum coordination rules in the United States, EU F-Gas Regulation targeting fluorinated greenhouse gases in optical amplifiers, and China's GB standards for fiber optic equipment collectively shape product certification requirements and market access timelines. ETSI interoperability frameworks in Europe further constrain vendor lock-in strategies by mandating open line system interfaces. Stakeholders must monitor Open RAN convergence with optical transport layers and assess captive versus merchant silicon strategies before committing to next-generation platform roadmaps.
Market Dynamics
Coherent DSP architectures are collapsing the boundary between transponders and pluggable optics, forcing incumbents to choose between chassis-based platform defense and merchant silicon commoditization.
Growth Catalysts
- Data center interconnect build-outs:Hyperscale operators in the United States and China are deploying 800G-capable line systems to support AI training cluster east-west traffic.
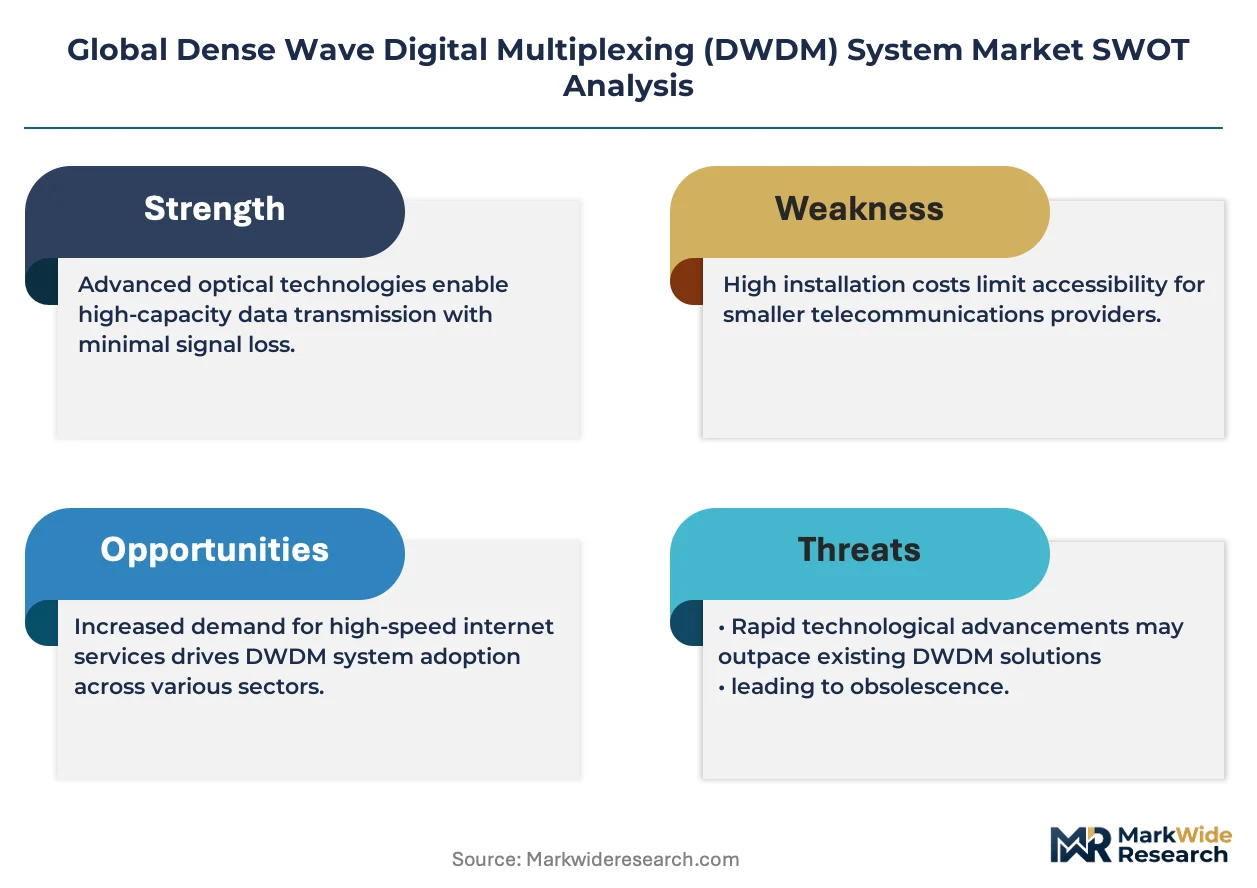
- EU F-Gas Regulation:The European Union's phasedown of fluorinated greenhouse gases in erbium-doped fiber amplifiers is accelerating transitions to pump-laser efficiency improvements and alternative cooling architectures.
- Submarine cable refresh cycles:Transatlantic and transpacific cable consortiums are replacing 10-year-old wet plant infrastructure with C+L-band capable repeaters.
Market Restraints
- Indium phosphide supply concentration:High-performance coherent modulators depend on III-V semiconductor foundries concentrated in Taiwan and Japan, creating single-source vulnerability for 400G+ components.
- Legacy SONET/SDH interoperability:Incumbent carriers in Germany and Japan maintain circuit-switched overlay requirements that delay all-packet optical convergence.
- Copper cable substitution in short-reach:Active optical cables and direct attach copper are capturing data center rack-to-rack connections under 100 meters.
Strategic Opportunities
- Open line system penetration in India:The country's national optical fiber network expansion creates entry points for disaggregated transponder vendors against integrated system incumbents.
- Silicon photonics convergence with co-packaged optics:Switch ASIC vendors and optical engine suppliers are collaborating on 51.2T switch platforms with embedded coherent interfaces.
- Japan's Green Transformation bonds:METI-directed financing is subsidizing energy-efficient optical transport upgrades in regional carrier networks.
Industry Challenges
- Coherent DSP firmware talent scarcity:Algorithm development for probabilistic constellation shaping and neural network-based equalization requires specialized optical-communications PhD pipelines concentrated at fewer than twelve universities globally.
- Multi-vendor interoperability certification:Open ROADM and TIP OOPT compliance testing extends product qualification timelines by six to nine months for systems targeting tier-one carrier procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dense Wave Digital Multiplexing (DWDM) System Market |
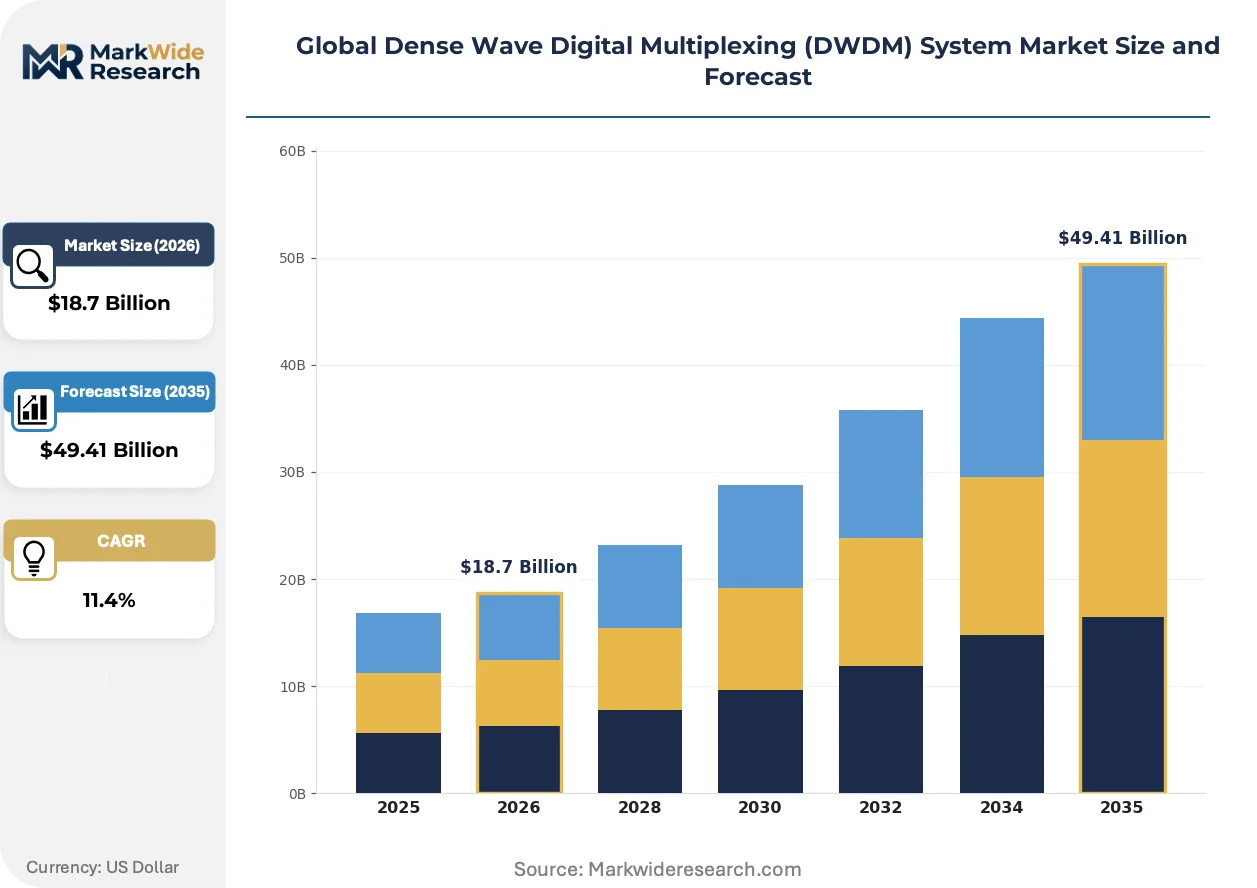
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transponders, Add-Drop Multiplexers, Optical Switches, Optical Amplifiers End User: Telecommunication Providers, Data Centers, Enterprises, Research Institutions Technology: Wave Division Multiplexing, Coherent Technology, Short-Reach, Long-Reach Component: Optical Fiber, Multiplexer, Demultiplexer, Monitoring Equipment |
| Companies Covered | Huawei Technologies, Ciena Corporation, Cisco Systems, Nokia, Infinera Corporation, ZTE Corporation, Fujitsu Limited, ADVA Optical Networking, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dense Wave Digital Multiplexing (DWDM) System Market Emerging Trajectories
Pluggable coherent optics are decoupling optical transport from proprietary chassis architectures, redistributing value capture toward DSP and silicon photonics suppliers.
Disaggregated transponder architectures are virtualizing network functions that previously required dedicated hardware shelves. Cloud operators in the United States are deploying 400ZR and OpenZR+ pluggables directly into switch faceplates, bypassing traditional optical line terminal chassis. This shift is virtualizing the optical transport layer into standard data center infrastructure management frameworks.
The EU F-Gas Regulation is mandating fluorinated gas containment and recovery protocols for optical amplifier manufacturing. Equipment vendors serving European carrier markets are redesigning erbium-doped fiber amplifier modules with reduced refrigerant dependency and sealed pump laser enclosures. Submarine cable system suppliers face the steepest compliance burden, as wet plant repeaters cannot be serviced post-deployment.
Hyperscale procurement patterns are compressing vendor qualification cycles from multi-year frameworks to annual technology refresh agreements. Chinese cloud operators are awarding 800G coherent transponder contracts through consolidated bidding platforms that prioritize cost-per-gigabit over historical supplier relationships. This behavioral shift is most visible in procurement for data center interconnects linking Beijing, Shanghai, and Shenzhen metro clusters.
Global Dense Wave Digital Multiplexing (DWDM) System Market Segmentation
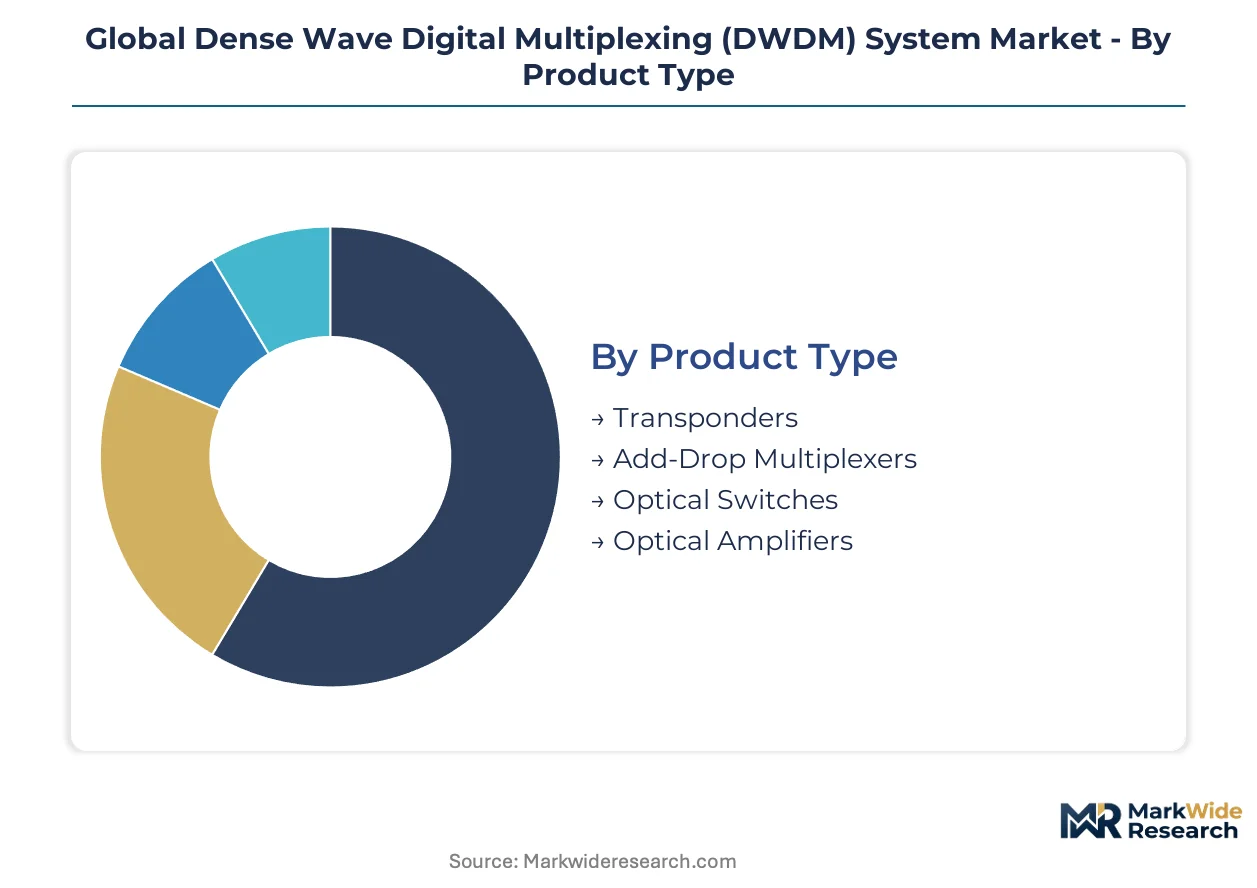
DWDM system segmentation reveals how optical transport value pools split between hardware tiers, customer procurement patterns, and technology maturity curves. Each dimension carries distinct margin structures and vendor competitive dynamics.
Product Type:
The use-case spectrum spans submarine cable repeaters, metro aggregation nodes, and data center interconnect faceplates with divergent reliability specifications.
- Transponders:These coherent DSP-powered modules convert client-side electrical signals into optical wavelengths with programmable modulation formats. Hyperscale data centers in the United States and China are absorbing 400ZR and 800G variants for AI cluster east-west traffic. Supply constraints around indium phosphide modulators limit shipment scaling for 400G+ coherent engines.
- Optical Amplifiers:Erbium-doped fiber amplifiers regenerate signals across C-band and L-band without optical-to-electrical conversion. Submarine cable consortiums spanning transatlantic and transpacific routes drive demand for sealed wet-plant repeaters. The EU F-Gas Regulation is forcing redesigns to eliminate fluorinated greenhouse gases from cooling systems.
- Add-Drop Multiplexers:ROADM nodes enable wavelength-selective routing at intermediate network points.
- Optical Switches:All-optical cross-connects bypass electronic switching for latency-sensitive paths.
Established volume favors Optical Amplifiers; emerging adoption favors Transponders.
End User:
Procurement scale varies dramatically between state-backed infrastructure programs and private cloud build-outs.
- Telecommunication Providers:Incumbent carriers in Germany and Japan maintain circuit-switched overlays that delay packet-optical convergence. Deutsche Telekom and NTT East prioritize chassis-based platforms with decade-long depreciation schedules.
- Data Centers:Hyperscale operators in Beijing, Shanghai, and Shenzhen metro clusters consolidate 800G coherent procurement through annual bidding platforms. Cloud infrastructure spending concentrates interconnection bandwidth in China and the United States.
- Enterprises:Private dark fiber leases and managed wavelength services dominate financial services and healthcare verticals.
- Research Institutions:National laboratories deploy specialized C+L-band systems for scientific data transfer.
Carrier procurement sustains Optical Amplifier margins; data center expansion drives Transponder volume acceleration.
Technology:
Signal reach requirements determine whether coherent DSP investment justifies cost-per-bit economics.
- Coherent Technology:Probabilistic constellation shaping and neural network-based equalization enable 800G transmission over 1,000+ kilometer spans. Algorithm development pipelines at fewer than twelve global universities constrain firmware talent availability.
- Long-Reach:Submarine and terrestrial ultra-long-haul links require advanced forward error correction and Raman amplification.
- Wave Division Multiplexing:Conventional intensity-modulated direct detection persists in cost-sensitive metro access.
- Short-Reach:Data center interconnects under 10 kilometers face displacement by pluggable coherent optics and active optical cables.
Coherent Technology commands premium positioning; Short-Reach faces compression from copper substitution below 100 meters.
Component:
Supply chain concentration varies from commodity fiber drawing to specialized multiplexing silicon.
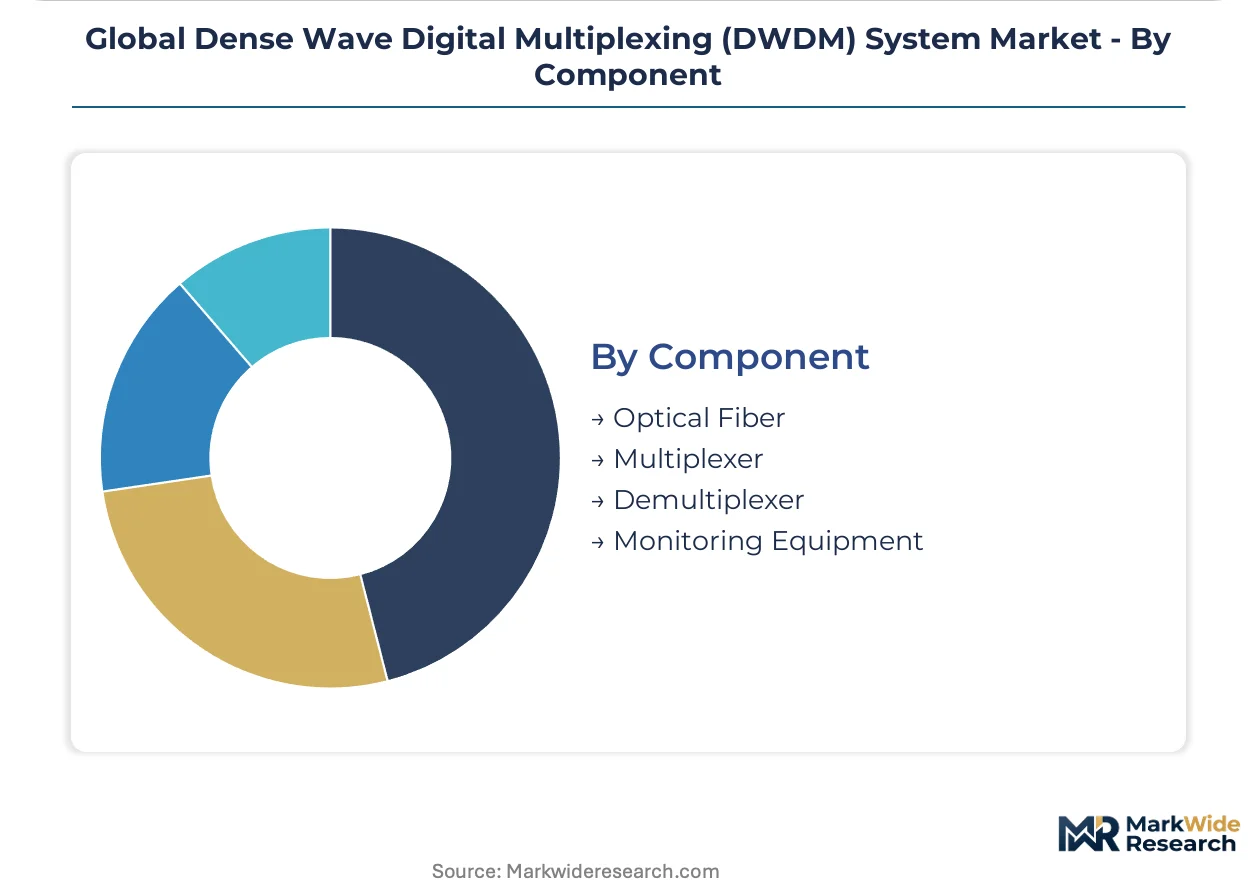
- Optical Fiber:Single-mode fiber with ultra-low attenuation coefficients anchors submarine and long-haul deployments. Corning and YOFC control preform and drawing capacity for large-core effective area fibers.
- Multiplexer:Arrayed waveguide gratings and thin-film filters combine multiple wavelengths onto single fibers.
- Demultiplexer:Complementary separation functions recover individual channels at receive terminals.
- Monitoring Equipment:Optical time-domain reflectometers and spectrum analyzers assure link integrity.
Optical Fiber represents the fastest-growing trajectory; Monitoring Equipment maintains stable replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards for fiber optic equipment anchor China's procurement frameworks, while FCC spectrum coordination rules and EU F-Gas Regulation create divergent compliance pathways across major demand centers. National cloud infrastructure build-outs and submarine cable refresh cycles concentrate investment in specific metropolitan clusters.
China
Hyperscale data center operators in Beijing, Shanghai, and Shenzhen metro clusters drive 800G coherent transponder procurement through consolidated bidding platforms. MIIT's GB standards mandate domestic certification timelines that favor captive silicon photonics capabilities. Huawei Technologies leverages its foundry position to dominate 400G deployments across state-backed carrier networks.
United States
FCC spectrum coordination rules shape optical transport certification requirements for terrestrial and submarine cable systems. Hyperscale operators deploy 800G-capable line systems to support AI training cluster east-west traffic in Northern Virginia and Dallas-Fort Worth data center corridors. Ciena Corporation anchors transatlantic submarine cable upgrades with coherent platform deliveries.
Germany
Deutsche Telekom maintains chassis-based platform preferences with decade-long depreciation schedules that delay packet-optical convergence. ETSI interoperability frameworks constrain vendor lock-in through open line system interface mandates. Munich and Frankfurt anchor carrier procurement for metro aggregation nodes serving central European backbone routes.
Japan
METI-directed Green Transformation bonds subsidize energy-efficient optical transport upgrades in regional carrier networks. NTT East prioritizes circuit-switched overlay requirements that complicate all-packet migration. Tokyo and Osaka metropolitan areas concentrate submarine cable landing station investments for transpacific route expansions.
India
The national optical fiber network expansion creates entry points for disaggregated transponder vendors against integrated system incumbents. TRAI frameworks influence spectrum allocation for terrestrial backbone routes connecting Delhi-Mumbai-Chennai corridors. Bangalore and Hyderabad data center clusters drive emerging demand for metro-scale DWDM interconnects.
Global Dense Wave Digital Multiplexing (DWDM) System Market Vendor Landscape
Integrated system vendors and disaggregated component suppliers split the market along chassis-based versus pluggable coherent architecture lines. The vendor base concentrates around coherent DSP capabilities and captive silicon photonics foundry access. Three archetypes dominate: vertically integrated platform vendors, merchant silicon specialists, and submarine cable system integrators. Competitive moves center on Open Optical Networking partnerships and OpenZR+ pluggable qualification programs.
Within the integrated platform tier, Huawei Technologies and Ciena Corporation exemplify divergent geographic anchoring strategies. Nokia occupies a position bridging European telecom incumbent relationships with Open Optical Networking standardization efforts. ZTE Corporation represents state-backed vertical integration into domestic Chinese procurement frameworks. These three vendors illustrate how captive foundry access, submarine cable consortium relationships, and regional regulatory compliance each anchor distinct competitive positions.
| Leading Market Players |
|---|
| Huawei Technologies |
| Ciena Corporation |
| Cisco Systems |
| Nokia |
| Infinera Corporation |
| ZTE Corporation |
| Fujitsu Limited |
| ADVA Optical Networking |
| NEC Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Taiwan-based indium phosphide foundries is compressing coherent modulator pricing while simultaneously forcing suppliers toward multi-source qualification programs and volume discount structures for hyperscale buyers.
Pricing Analysis
Geographic price spreads between Chinese consolidated bidding platforms and European carrier procurement frameworks exceed two-to-one for equivalent 800G coherent transponder specifications. Contract-based long-term offtake agreements dominate submarine cable consortium purchases, while spot-market dynamics govern data center interconnect procurement. Price differentiation separates chassis-integrated platforms with decade-long service commitments from pluggable optics with three-year replacement cycles. Hyperscale cloud operators exhibit extreme price sensitivity, whereas Deutsche Telekom and NTT East prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan Semiconductor Manufacturing Company and Japan-based III-V foundries for coherent DSP and modulator production. Raw material dependencies center on erbium-doped fiber preforms from Corning and YOFC, pump laser diodes from Lumentum and II-VI, and specialized hermetic packaging from South Korean suppliers. Single-source vulnerability in indium phosphide wafer processing creates exposure to geopolitical disruption. Distribution runs through direct OEM relationships for integrated systems and merchant silicon channels for pluggable optics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hyperscale procurement consolidation in China and the United States, fragmenting historical carrier-centric vendor relationships.
For Market Incumbents: Pre-empt pluggable coherent commoditization by accelerating captive silicon photonics foundry investments and securing OpenZR+ interoperability certification ahead of annual hyperscale bidding cycles. Defend chassis-based platform revenue through submarine cable consortium relationships where sealed wet-plant repeaters resist disaggregation. Prioritize EU F-Gas Regulation compliance as a qualification barrier against merchant silicon entrants. For New Entrants and Emerging Players: Establish a beachhead in India's national optical fiber network expansion where disaggregated transponder architectures face lower incumbent switching costs. Target metro-scale data center interconnects in Bangalore and Hyderabad with Open Optical Networking-compliant solutions. Pursue qualification through TIP OOPT frameworks to compress carrier procurement timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among submarine cable system integrators with decade-long maintenance contracts and wet-plant upgrade cycles. Long-term viability favors vendors with backward integration into coherent DSP design and silicon photonics manufacturing. Monitor indium phosphide supply diversification announcements as an inflection indicator for merchant silicon competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| OpenZR+ Pluggable Qualification | Enables hyperscale cloud operators to bypass traditional optical line terminal chassis procurement. |
| Silicon Photonics Foundry Investment | Secures captive supply of coherent engines for 800G data center interconnect deployments. |
| Submarine Cable Consortium Partnership | Locks in decade-long wet-plant repeater refresh cycles resistant to pluggable disruption. |
| EU F-Gas Regulation Compliance Certification | Creates qualification barrier for optical amplifier vendors serving European carrier markets. |
| Coherent DSP Firmware Talent Acquisition | Addresses algorithm development scarcity for probabilistic constellation shaping capabilities. |
Methodological Framework
Operator-level perspectives from optical transport network architects, hyperscale data center procurement directors, submarine cable consortium technical managers, and carrier infrastructure planning officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, MIIT GB standard documentation, ETSI interoperability framework specifications, and hyperscaler capital expenditure disclosures. Bottom-up shipment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Scenario-bracketing framed demand projections under alternative coherent DSP penetration rates and pluggable optics substitution assumptions. Segmentation dimensions spanned product type, end user archetype, signal reach technology, and component supply tier. CAGRs were derived from fitted growth curves calibrated to historical deployment cycles and forward infrastructure budget announcements. Indium phosphide supply constraints and EU F-Gas Regulation compliance timelines served as industry-specific forecast inputs.
Sensitivities concentrate around indium phosphide foundry capacity expansion, Open RAN convergence with optical transport layers, and Chinese cloud infrastructure budget revisions. Forecasts reflect documented assumptions regarding coherent technology adoption curves and regulatory implementation schedules. Quarterly review of hyperscale bidding platform awards and submarine cable consortium contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
LTE and LTE Advance Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
Dialer Market
Telecommunications
5G System Integration Market
Telecommunications
Indonesia Volte Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
Kenya Telecom Market
Telecommunications
Cambodia ICT Market
Telecommunications
Global Cognitive Radio Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Spain ICT Market
Telecommunications
Global 5G Base Station Market
Telecommunications
US 5G Radio Access Network Professional Services Market
Telecommunications
Philippines Telecom Market