
 5G Spectrum Market | 2026-2036
5G Spectrum Market Size, Share, and Industry Trends Forecast 2026-2036
5G Spectrum Market Insights
3GPP Release 17 certification is collapsing the qualification timeline for infrastructure vendors seeking operator trials. Huawei Technologies Co., Ltd. leverages its integrated baseband-to-antenna portfolio to dominate mid-band rollouts across multiple continents. Nokia Corporation differentiates through its AirScale portfolio with massive MIMO configurations that sustain R&D intensity above industry norms. Samsung Electronics Co., Ltd. anchors its position in mmWave through vertical integration into semiconductor fabrication for beamforming chipsets.
5G spectrum encompasses licensed and unlicensed radio frequency allocations from sub-1 GHz through 47 GHz, engineered to deliver peak data rates exceeding 10 Gbps via orthogonal frequency-division multiplexing and time-division duplexing protocols. These frequencies enable ultra-reliable low-latency communication for industrial automation, vehicular networks, and dense urban connectivity. Mid-band spectrum between 1-6 GHz captures the largest share of capital deployment due to its balance of coverage and capacity, while mmWave frequencies above 24 GHz represent the fastest-growing allocation as enterprises adopt private networks for manufacturing and logistics. Shared spectrum models are maturing in regulatory frameworks but remain marginal in revenue contribution compared to licensed public network auctions.
The FCC in the United States, Ofcom in the United Kingdom, and the Radio Regulatory Bureau of the ITU shape market access through auction design, interference coordination rules, and international harmonization of frequency bands. REACH and RoHS compliance in Europe constrains base station material composition, while the EU AI Act introduces algorithmic transparency requirements for automated spectrum management systems. Stakeholders must monitor national security review frameworks that increasingly restrict vendor eligibility based on supply chain provenance rather than technical performance alone.
Market Dynamics
Mid-band spectrum auctions are compressing deployment timelines as regulators accelerate C-band reallocation to satisfy mobile broadband capacity constraints in dense urban corridors.
Growth Catalysts
- Automotive V2X Mandates:South Korea's Ministry of Science and ICT requires 5G-V2X compatibility in new vehicle platforms, forcing chipset procurement across domestic manufacturing lines.
- REACH Compliance Deadlines:ECHA restrictions on hazardous substances in base station electronics are accelerating material substitution programs among European infrastructure vendors.
- Smart Factory Private Networks:Manufacturing clusters in Japan's Aichi Prefecture are deploying localized 5G to replace wired industrial ethernet for automated guided vehicle coordination.
Market Restraints
- mmWave Propagation Physics:Line-of-sight requirements above 24 GHz necessitate tenfold denser small-cell grids versus sub-6 GHz, multiplying site acquisition costs in obstructed urban environments.
- Semiconductor Foundry Concentration:Beamforming chipset fabrication concentrates in Taiwan and South Korea, exposing infrastructure vendors to single-source geopolitical interruption.
- FCC Equipment Authorization Delays:Certification backlogs for new radio configurations extend product launch windows by six to nine months for non-priority applicants.
Strategic Opportunities
- Rural Fixed Wireless Access:Germany's underserved eastern municipalities present white-space demand for 3.5 GHz residential broadband where fiber trenching proves uneconomical.
- AI-Driven Spectrum Management:Convergence of machine learning with dynamic frequency allocation enables real-time interference mitigation in stadium and convention center deployments.
- Japan's Local 5G Licensing:METI's streamlined framework for enterprise-owned spectrum below 4.9 GHz removes operator intermediaries for industrial campus networks.
Industry Challenges
- RF Engineer Scarcity:Massive MIMO array calibration and beam pattern optimization require specialized expertise that telecommunications programs produce insufficiently.
- Legacy 4G Core Integration:Non-standalone 5G deployments demand backward compatibility maintenance that fragments vendor software roadmaps and testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Spectrum Market |
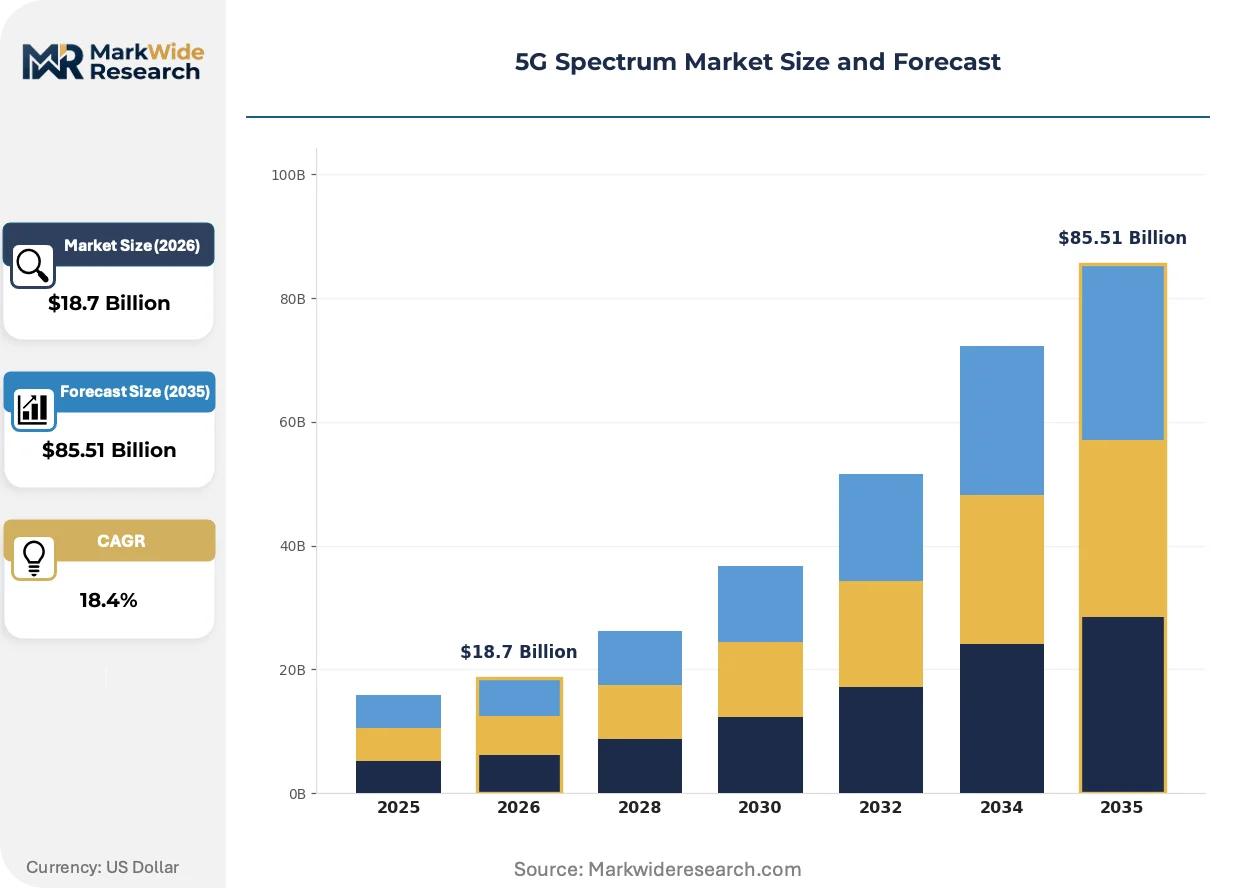
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Frequency Band: Low Band, Mid Band, High Band, mmWave End User: Telecommunications, Automotive, Smart Cities, Industrial IoT Deployment Model: Private Networks, Shared Spectrum, Public Networks, Hybrid Deployment Technology Type: Massive MIMO, Beamforming, Network Slicing, Small Cells |
| Companies Covered | Huawei Technologies Co., Ltd., Telefonaktiebolaget LM Ericsson, Nokia Corporation, Samsung Electronics Co., Ltd., Qualcomm Incorporated, ZTE Corporation, Cisco Systems, Inc., Intel Corporation, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Spectrum Market Trends and Innovations
Beamforming architectures and open radio access network specifications are fragmenting vendor lock-in patterns while compressing hardware refresh cycles across operator procurement.
Integrated antenna-radio units are miniaturizing through gallium nitride power amplifier adoption, collapsing base station footprint requirements. Japanese operators are deploying these compact configurations in Tokyo's dense Shibuya corridor to circumvent rooftop space constraints. The technology is miniaturizing site preparation from multi-week structural assessments to same-day pole mounting, accelerating urban rollout velocity.
The EU AI Act imposes algorithmic transparency requirements on automated spectrum allocation systems that base station vendors must embed in network management software. European operators deploying self-optimizing networks in Frankfurt and Paris must now document decision logic for regulatory audit. Infrastructure suppliers are reengineering their machine learning pipelines to satisfy explainability mandates before commercial deployment.
Enterprise buyers are consolidating vendor relationships around end-to-end private network contracts that bundle spectrum access, core infrastructure, and managed services. Manufacturing conglomerates in China's Guangdong province are bypassing traditional operator intermediaries to negotiate direct equipment procurement with infrastructure OEMs. This pattern concentrates purchasing power among large industrial accounts while marginalizing smaller regional system integrators.
5G Spectrum Market Segmentation
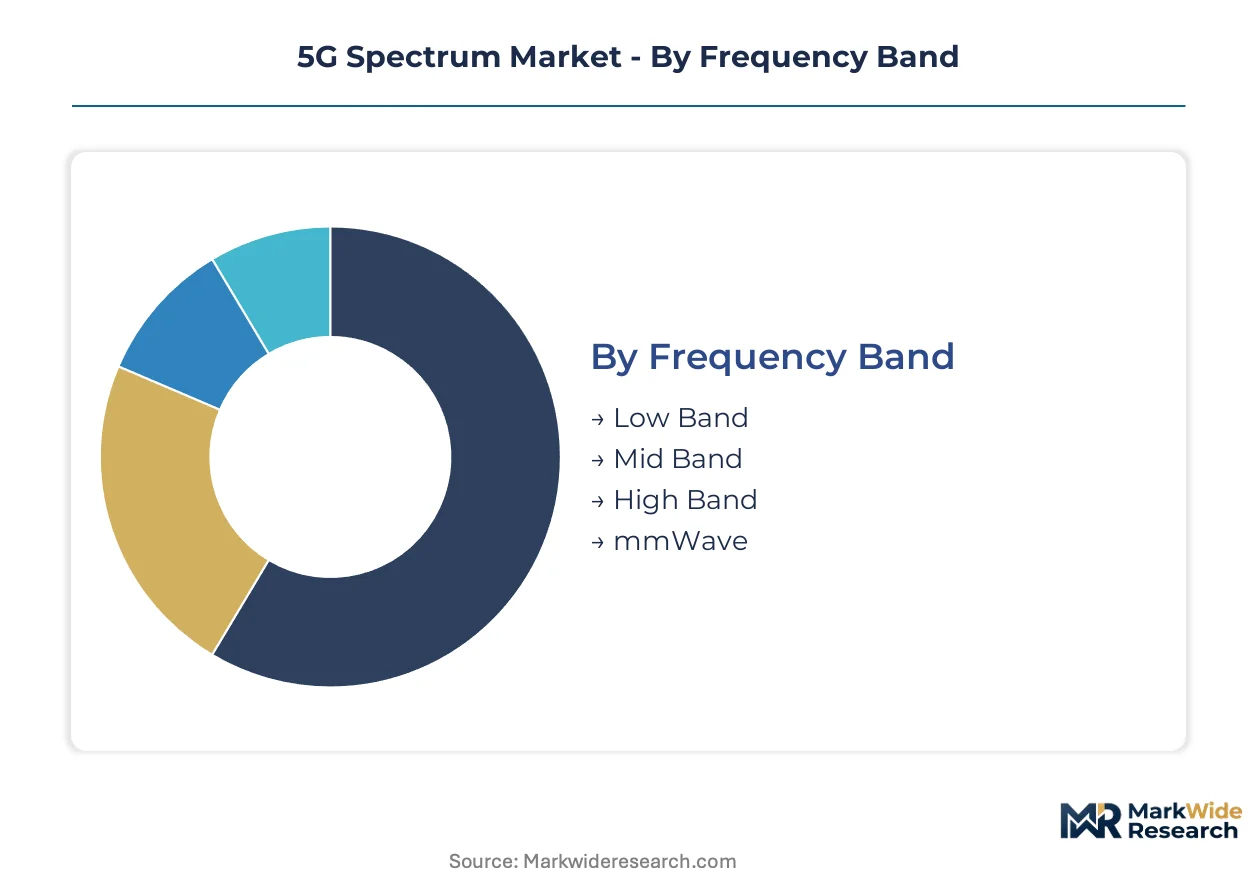
5G spectrum segmentation reveals how frequency allocations, deployment architectures, and technology choices channel capital toward distinct use cases. Each dimension shapes procurement patterns among telecommunications operators, automotive OEMs, and industrial enterprises.
Frequency Band:
Low-band frequencies flow through nationwide coverage contracts, while mid-band and mmWave allocations concentrate in urban corridor auctions and enterprise private network deals.
- Low Band:Sub-1 GHz propagation penetrates buildings and rural terrain without dense infrastructure. German operators deploy these frequencies across eastern municipalities where fiber backhaul remains uneconomical.
- Mid Band:The 1-6 GHz range balances coverage radius with capacity density. China's dense urban corridors absorb the majority of capital deployment here, driven by mobile broadband saturation in tier-one cities.
- High Band:Upper mid-band allocations between 6-24 GHz support stadium and convention center overlays. Japanese regulators have prioritized harmonization in this range for event-venue applications.
- mmWave:Frequencies above 24 GHz deliver peak throughput for manufacturing automation. South Korea's Ministry of Science and ICT has designated specific mmWave blocks for smart factory private networks in Gyeonggi Province.
Mid Band dominates installed base. mmWave is where expansion concentrates.
End User:
Procurement patterns diverge sharply: telecommunications operators buy through competitive auction frameworks, while automotive and industrial buyers negotiate direct equipment contracts.
- Telecommunications:Licensed spectrum acquisitions and base station rollouts constitute the foundational revenue stream. FCC auction structures in the United States compress deployment timelines through accelerated clearing requirements.
- Automotive:V2X mandates in South Korea and Japan force chipset procurement across domestic vehicle platforms. 5G-V2X compatibility is now required in new vehicle certifications issued by Korea's Ministry of Science and ICT.
- Smart Cities:Municipal governments deploy integrated sensor networks for traffic management and public safety. Barcelona and Singapore have established procurement frameworks bundling spectrum access with managed infrastructure services.
- Industrial IoT:Manufacturing conglomerates in Japan's Aichi Prefecture and China's Guangdong province bypass operator intermediaries for localized 5G replacing wired industrial ethernet.
Telecommunications anchors current revenue. Industrial IoT is climbing the fastest.
Deployment Model:
Cost tier differentiation separates capital-intensive public network builds from leaner private and shared alternatives.
- Private Networks:Enterprise-owned infrastructure eliminates operator intermediaries. METI's streamlined Local 5G licensing in Japan removes regulatory friction for industrial campus deployments below 4.9 GHz.
- Shared Spectrum:Dynamic frequency allocation enables secondary access to underutilized bands. Ofcom's framework in the United Kingdom permits localized access without exclusive licensing.
- Public Networks:Traditional operator-led deployment remains the default for consumer mobile broadband. Competitive auctions in Germany, the United States, and South Korea allocate exclusive use rights.
- Hybrid Deployment:Combined public-private architectures serve campuses with dual connectivity requirements. German automotive suppliers in Baden-Württemberg utilize hybrid models for R&D facility connectivity.
Public Networks retain volume leadership. Private Networks show the steepest expansion trajectory.
Technology Type:
Supply concentration in semiconductor fabrication shapes which technologies achieve deployment scale.
- Massive MIMO:64T64R and 32T32R antenna configurations multiply spectral efficiency in mid-band rollouts. Nokia's AirScale portfolio sustains R&D intensity above industry norms in this category.
- Beamforming:Phased-array architectures compensate for mmWave propagation limitations. Fabrication concentrates in Taiwan and South Korea, exposing vendors to single-source geopolitical interruption.
- Network Slicing:Virtualized core partitioning enables differentiated service tiers over common infrastructure. European operators in Frankfurt deploy slicing for industrial latency guarantees.
- Small Cells:Compact base stations densify coverage in obstructed urban environments. Tokyo's Shibuya corridor has adopted miniaturized gallium nitride configurations to circumvent rooftop space constraints.
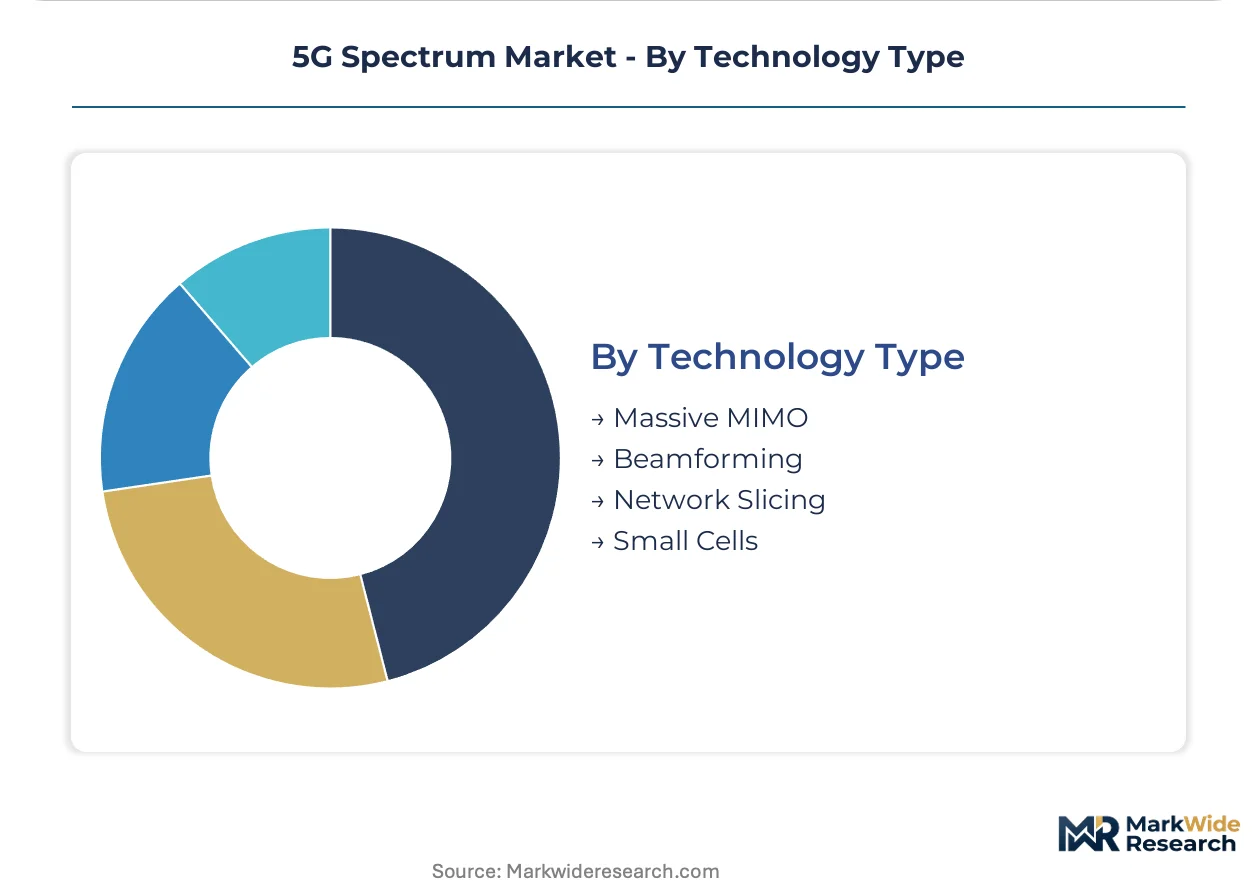
Massive MIMO leads capital deployment. Beamforming is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunications operators dominate procurement across four major economies, with automotive and industrial buyers emerging as secondary demand clusters in East Asia and Western Europe.
United States
FCC auction frameworks compress deployment timelines through accelerated clearing requirements. The regulator's C-band reallocation has concentrated capital deployment in urban corridors. Dense small-cell infrastructure offsets propagation limitations across Manhattan and downtown Chicago.
China
MIIT spectrum allocations prioritize mid-band rollouts for mobile broadband saturation in tier-one cities. The ministry's harmonization directives align equipment certification with 3GPP Release 17 timelines. Yangtze River Delta manufacturing clusters absorb private network equipment for automated guided vehicle coordination.
Germany
BNetzA competitive auctions reallocate 3.5 GHz frequencies for enhanced mobile broadband. REACH compliance deadlines accelerate material substitution programs among domestic infrastructure vendors. Eastern municipalities deploy sub-1 GHz fixed wireless access where fiber trenching proves uneconomical.
South Korea
MSIT mandates 5G-V2X compatibility in new vehicle platforms, forcing chipset procurement across domestic manufacturing lines. The ministry has designated specific mmWave blocks for smart factory private networks. Gyeonggi Province manufacturing conglomerates negotiate direct equipment contracts bypassing operator intermediaries.
Japan
METI streamlined Local 5G licensing removes regulatory friction for enterprise-owned spectrum below 4.9 GHz. Aichi Prefecture manufacturing clusters deploy localized 5G replacing wired industrial ethernet. Tokyo's Shibuya corridor adopts miniaturized gallium nitride configurations to circumvent rooftop space constraints.
5G Spectrum Market Competitive Landscape
Player mix skews toward integrated infrastructure vendors with captive semiconductor capabilities. Market structure concentrates around three dominant equipment suppliers controlling mid-band and mmWave base station supply. Strategic archetypes include integrated baseband-to-antenna portfolio vendors, AirScale-focused massive MIMO specialists, and beamforming chipset fabricators with foundry relationships. Competitive moves center on R&D intensity maintenance above industry norms and vertical integration into semiconductor fabrication for beamforming components.
Among Asia-Pacific-based integrated vendors, Huawei Technologies Co., Ltd. and ZTE Corporation exemplify the baseband-to-antenna archetype through their end-to-end infrastructure positioning. Samsung Electronics Co., Ltd. occupies a distinct position as a semiconductor-integrated equipment supplier with foundry-backed beamforming capabilities. Nokia Corporation and Telefonaktiebolaget LM Ericsson represent European-tier specialists competing through massive MIMO configuration depth and open radio access network specifications.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Samsung Electronics Co., Ltd. |
| Qualcomm Incorporated |
| ZTE Corporation |
| Cisco Systems, Inc. |
| Intel Corporation |
| NEC Corporation |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride power amplifier substitution for legacy silicon LDMOS components is redrawing supplier geography toward Japanese and South Korean foundries while compressing base station hardware price points by a third across mid-band configurations. This material transition simultaneously concentrates procurement leverage among operators with volume scale and fragments pricing power among component vendors locked into long-term supply agreements.
Pricing Analysis
Cost-plus contracts with gallium nitride wafer price indexation dominate procurement between infrastructure OEMs and telecommunications operators. Three-tier pricing structure across premium certified, standard compliant, and economy-tier configurations differentiates bids based on 3GPP Release 17 certification status and massive MIMO channel count. Pricing pressure stems from operator consolidation in China's tier-one cities, where three carriers concentrate procurement volume. Municipal governments and industrial enterprises exhibit highest price sensitivity due to budget-constrained procurement frameworks, while national operators with auction-backed spectrum positions absorb premium-tier pricing.
Supply Chain Analysis
Strategic stockpiling of beamforming chipsets prevails over just-in-time inventory as infrastructure vendors buffer against Taiwan and South Korea foundry concentration. Raw material dependencies center on high-purity gallium substrates, silicon carbide wafers, and advanced packaging substrates. Single-source vulnerability in Taiwan semiconductor fabrication exposes vendors to geopolitical interruption. Distribution runs through direct OEM-to-operator contracts for public networks, with system integrators mediating private network deployments in manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among telecommunications operators and industrial conglomerates, with China's three national carriers and Japan's manufacturing keiretsu consolidating procurement volume to extract pricing concessions from infrastructure vendors.
For Market Incumbents: Secure captive supply of gallium nitride power amplifiers through backward integration into Japanese or South Korean foundry partnerships to offset single-source risk. Defend position by accelerating 3GPP Release 18 R&D investment ahead of competitor roadmaps, as delayed certification collapses trial eligibility with tier-one operators. Channel control through exclusive managed service bundling protects margin structures against pure equipment vendors. For New Entrants and Emerging Players: AI-driven spectrum management software layers represent an under-served service gap where incumbent infrastructure vendors lack machine learning pipeline expertise. Target Germany's eastern municipalities for rural fixed wireless access deployments where fiber economics fail and established vendors under-penetrate. Go-to-market through direct municipal procurement frameworks bypasses operator intermediaries and accelerates revenue recognition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional system integrators in Europe's smart city deployment sector. Long-term viability favors targets with established regulatory relationships in multiple national jurisdictions, as FCC and BNetzA authorization timelines create defensive moats. Watch for inflection when METI expands Japan's Local 5G licensing framework beyond 4.9 GHz, signaling enterprise spectrum liberalization momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GaN Foundry Capacity | Captive supply of power amplifiers insulates Nokia and Samsung from Taiwan concentration risk. |
| 3GPP Release 18 Pre-Standard Development | Early protocol influence secures trial eligibility with China Mobile and Verizon procurement teams. |
| AI-Driven Spectrum Management Platform Launch | Machine learning pipelines satisfy EU AI Act explainability mandates for Frankfurt operator deployments. |
| Local 5G Licensing Partnership in Japan | METI framework access enables direct Aichi Prefecture manufacturing contracts without operator intermediaries. |
| mmWave Small Cell Joint Venture | Tokyo Shibuya corridor deployment proves miniaturized gallium nitride configurations for dense urban replication. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of 3GPP release documentation, national regulatory auction records, and infrastructure vendor SEC disclosures. Primary interviews engaged network planning executives at tier-one operators, semiconductor procurement directors at equipment OEMs, and spectrum policy leads at BNetzA and FCC. Secondary validation drew from ITU-R harmonization reports, MIIT equipment certification databases, and ECHA REACH compliance filings. Bottom-up deployment forecasts triangulate against top-down spectrum allocation value estimates.
Segmentation dimensions modeled span frequency band, deployment architecture, end-user category, and technology type across the analysis window. Analytical framework projects capital deployment trajectories using operator auction commitments, equipment shipment disclosures, and private network licensing velocity. CAGRs derive from regression analysis of spectrum price per MHz-pop against deployment density metrics, incorporating foundry capacity expansion schedules and regulatory clearing timelines as industry-specific inputs.
Forecasts assume regulatory continuity in FCC auction frameworks, EU REACH compliance deadlines, and METI Local 5G licensing structures; material policy shifts would require re-modeling. Specific risks include semiconductor export restriction expansion, accelerated 4G core decommissioning mandates, and AI Act enforcement variance across member states. Revision becomes warranted when BNetzA or FCC auction participation thresholds cross 20% decline relative to prior allocation rounds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
Asia-Pacific Distributed Antenna System Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
5G Technology ROI Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Mesh Wifi System Market
Wireless Technologies
Multefire Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Industrial 5G Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Global Wi-Fi 6 Market
Wireless Technologies
Wireless Paging Systems Market