
 Europe Mobile Virtual Network Operator (MVNO) Market | 2026-2036
Europe Mobile Virtual Network Operator (MVNO) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mobile Virtual Network Operator (MVNO) Market Insights
The gap between premium full-service MVNOs and discount data-only operators is broadening across Europe. Virgin Media O2 leverages its quad-play heritage to bundle mobile with broadband and entertainment, sustaining higher average revenue per user than standalone competitors. Lycamobile Europe Limited anchors its position in ethnic and diaspora calling segments, dominating international voice corridors with specialized prepaid offerings. Giffgaff Limited differentiates through community-driven customer service and transparent monthly subscriptions, competing without physical retail overhead.
A Mobile Virtual Network Operator leases wholesale network capacity from host mobile network operators rather than owning radio spectrum or physical infrastructure, routing subscriber traffic through core network agreements while managing its own billing, customer relationship systems, and service packaging. Full MVNOs maintain the deepest technical integration with separate mobile switching centers and home location registers, whereas discount and data-only variants rely on lighter wholesale arrangements focused on price arbitrage. Discount MVNOs currently occupy the largest subscriber base across European markets, though data-only MVNOs are expanding fastest as enterprises replace fixed-line connectivity with managed 4G and 5G WAN solutions. Monthly subscription models capture the steadiest revenue pools, while pay-as-you-go plans face structural decline outside tourist and temporary-resident segments.
The European Electronic Communications Code and national implementations by regulators such as BNetzA in Germany and Ofcom in the United Kingdom enforce wholesale access pricing and net neutrality obligations that determine MVNO viability on host networks. GDPR compliance requirements shape customer data handling costs and consent architectures across all subscriber-facing platforms. Stakeholders must monitor pending spectrum reallocation decisions and wholesale rate reviews in France, Italy, and Spain, as these will recalibrate margin structures for new entrants and incumbents alike.
Market Dynamics
The EU's Electronic Communications Code is rewiring wholesale access economics across European mobile markets, compressing host network pricing and enabling new MVNO entrants to arbitrage infrastructure costs without spectrum ownership.
Growth Catalysts
- Wholesale access reform:The Electronic Communications Code mandates cost-oriented pricing for network access, lowering barriers for new MVNOs negotiating host agreements in Germany, France, and Spain.
- Enterprise mobility substitution:Small enterprises are replacing fixed-line WAN with managed 4G and 5G connectivity, creating fresh demand for data-only MVNOs serving business segments.
- 5G standalone deployment:Host operators' 5G core investments enable MVNOs to offer network-sliced enterprise services previously reserved for full MNOs.
Market Restraints
- Host network concentration:Three to four infrastructure owners control national wholesale markets in most EU member states, limiting MVNO bargaining power on roaming and priority data terms.
- GDPR compliance architecture:Customer consent management and data portability requirements impose fixed technology costs that disproportionately burden smaller MVNOs with sub-500,000 subscribers.
- Fixed wireless substitution:Cable operators' DOCSIS 4.0 and fiber-to-the-premises expansions threaten MVNO mobile broadband positioning in residential and SOHO segments.
Strategic Opportunities
- Eastern European expansion:Poland, Romania, and Bulgaria maintain lower MVNO penetration than Western benchmarks, offering first-mover positioning for ethnic-focused and data-only operators.
- eSIM-native provisioning:Remote SIM provisioning eliminates physical distribution costs and enables instant subscriber onboarding through digital channels, compressing customer acquisition economics.
- CSRD-aligned B2B offerings:Corporate sustainability reporting requirements create demand for carbon-footprint-transparent connectivity services that MVNOs can source from renewable-powered host networks.
Industry Challenges
- Subscriber identity management:Maintaining separate HLR/HSS infrastructure for full MVNOs demands specialized telecom engineering talent scarce outside established host operator ecosystems.
- Intergenerational system integration:MVNOs must bridge legacy 2G/3G signaling with 5G core architectures while managing disparate billing mediation across host network generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mobile Virtual Network Operator (MVNO) Market |
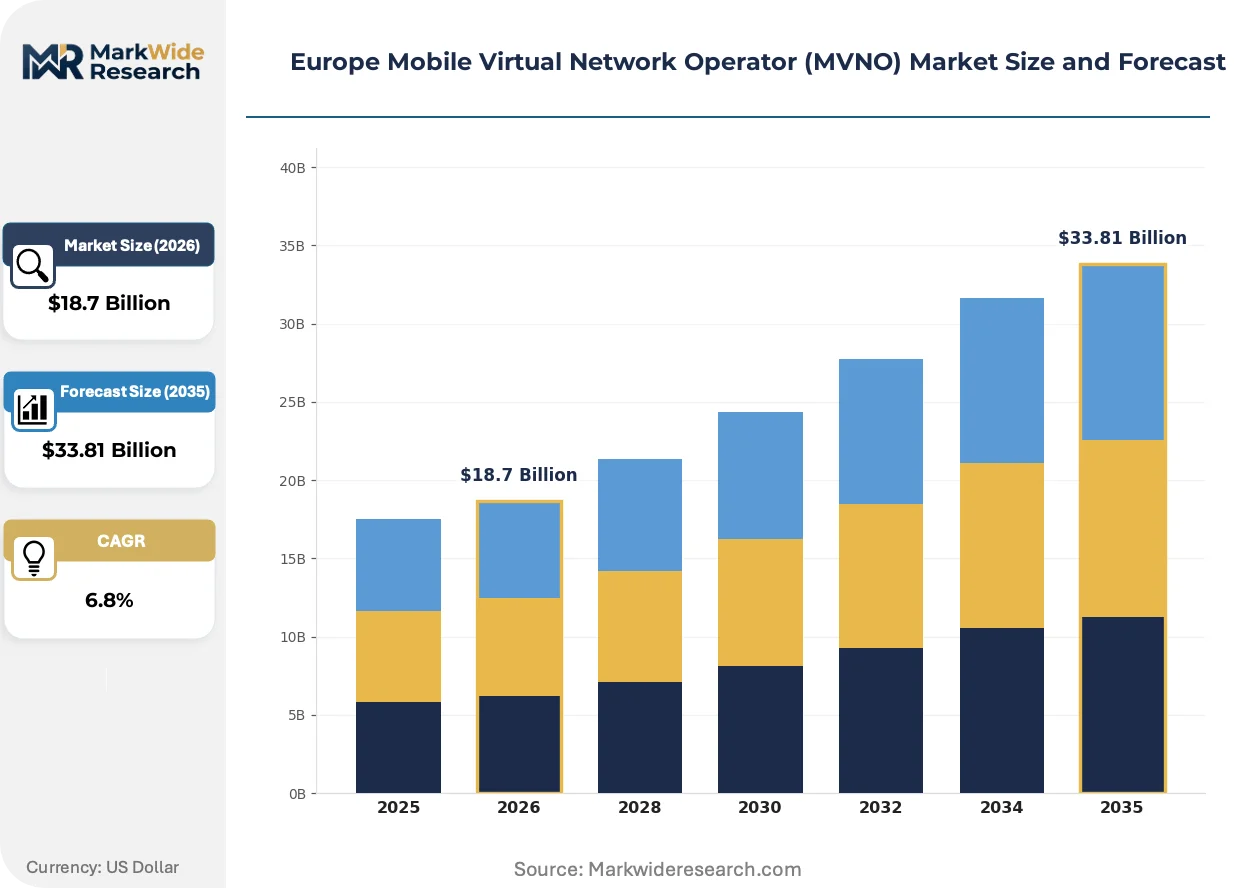
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Discount MVNO, Data-only MVNO, Full MVNO, Brand MVNO End User: Individual Consumers, Small Enterprises, Large Corporations, Government Agencies Pricing Model: Pay-as-you-go, Monthly Subscription, Bundled Plans, Family Plans Distribution Channel: Online Sales, Retail Stores, Partner Resellers, Third-party Providers |
| Companies Covered | Giffgaff Limited, Freenet AG, Lycamobile Europe Limited, Virgin Media O2, Congstar GmbH, Lebara Mobile Limited, iD Mobile Limited, Truphone Ltd., Tesco Mobile Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mobile Virtual Network Operator (MVNO) Market Trends and Innovations
European MVNOs are pivoting from price-led competition toward embedded connectivity and vertical specialization, with technology and regulation jointly compressing the viable operating model set.
Standalone 5G core networks are rewriting how MVNOs architect service differentiation. Network slicing allows operators to reserve guaranteed bandwidth slices for enterprise IoT and critical communications clients. Automotive fleet managers and industrial automation deployers are adopting these assured-connectivity tiers fastest. This capability is rewriting the boundary between light MVNOs and full infrastructure competitors.
GDPR enforcement by national data protection authorities including CNIL in France and the UK's Information Commissioner's Office is tightening consent architecture requirements. Real-time data portability mandates now force MVNOs to engineer seamless subscriber migration pathways. Prepaid and ethnic-segment operators face the steepest compliance recalibration as they historically minimized data governance investment.
Corporate buyers are unbundling connectivity from device procurement, forcing MVNOs to compete for standalone service contracts without handset subsidy lock-in. German and Dutch mid-market enterprises are leading this separation, sourcing devices through IT resellers while negotiating connectivity directly. This pattern concentrates purchasing power with procurement functions and compresses MVNO margins on traditional bundled offerings.
Europe Mobile Virtual Network Operator (MVNO) Market Segmentation
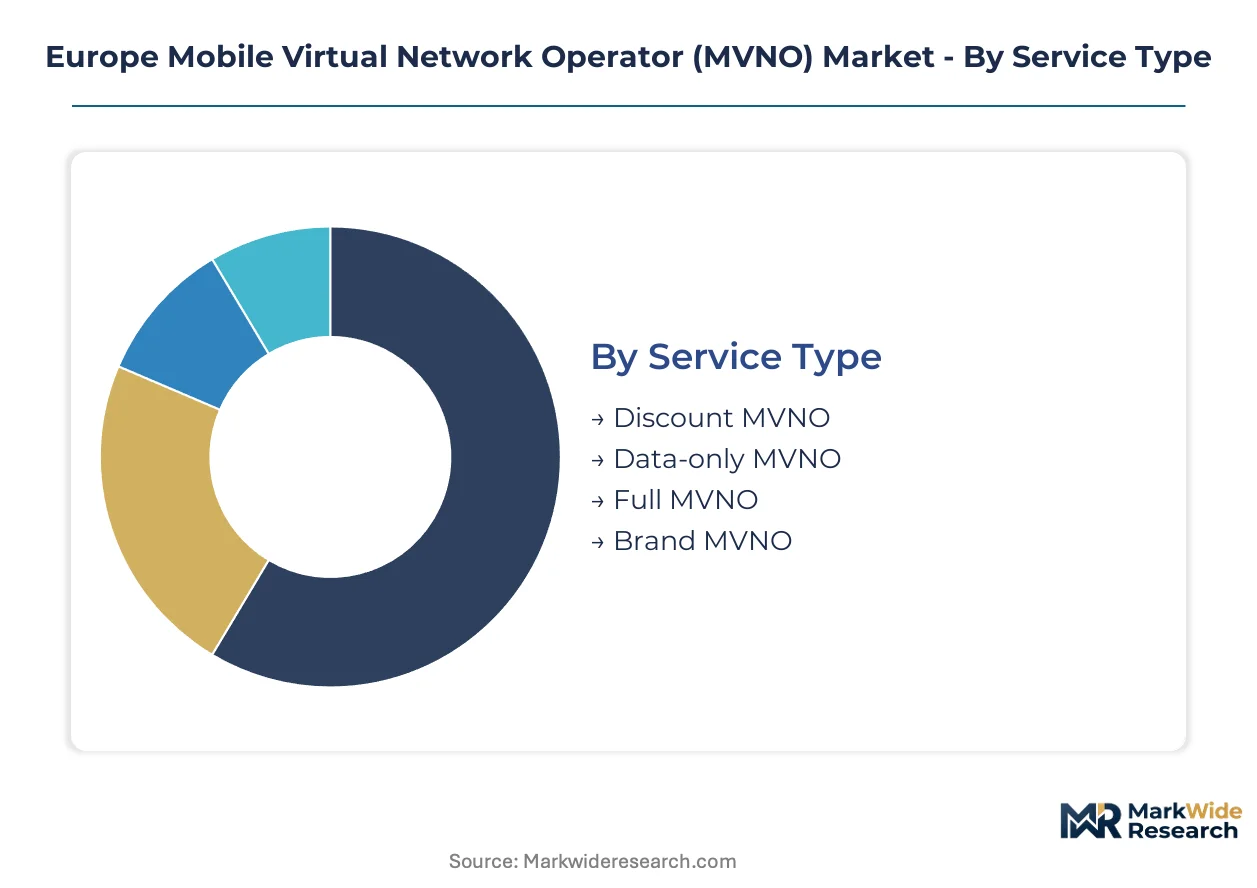
MVNO business models diverge sharply in capital requirements, from infrastructure-heavy full operators to asset-light digital resellers. Segment selection determines wholesale negotiation leverage, customer acquisition economics, and regulatory compliance burdens across European markets.
Service Type:
Capital intensity varies dramatically across service architectures, with core network ownership demanding orders-of-magnitude greater investment than wholesale resale arrangements.
- Full MVNO:Operators maintain dedicated mobile switching centers, home location registers, and core network infrastructure. German industrial corridors and enterprise zones concentrate demand here, driven by network slicing requirements for automotive and manufacturing IoT deployments. Host network integration costs and specialized engineering talent scarcity constrain new entrants.
- Discount MVNO:Light wholesale arrangements prioritize price arbitrage over technical differentiation. Subscriber bases concentrate in Southern European price-sensitive markets and Eastern European expansion zones. Thin margins demand volume scale and ruthless cost discipline in customer acquisition.
- Data-only MVNO:Purpose-built for enterprise WAN substitution and IoT connectivity. French and Dutch logistics hubs drive fastest uptake as fleet managers replace fixed-line infrastructure.
- Brand MVNO:Retail and media brands lease network capacity without operational infrastructure. UK supermarket chains and Nordic retail cooperatives anchor this segment through loyalty program integration.
Most installed capacity flows through Discount MVNOs. Expansion is steepest in Data-only MVNOs.
End User:
Customer type determines service packaging complexity, with enterprise accounts requiring bespoke SLAs and consumer segments favoring standardized digital provisioning.
- Individual Consumers:The mass-market foundation spanning prepaid ethnic segments, digital-native monthly subscribers, and tourist temporary users. German urban centers and UK metropolitan areas concentrate highest-value individual accounts.
- Small Enterprises:Replacing fixed-line WAN with managed 4G and 5G connectivity. Benelux logistics firms and Italian manufacturing SMEs drive fastest adoption of data-only business tariffs.
- Large Corporations:Demand network-sliced assured connectivity for critical communications. Automotive OEMs in Stuttgart and Munich anchor this segment through private 5G integration requirements.
- Government Agencies:Public sector procurement emphasizes security certification and data sovereignty. Nordic digital government programs and French public administration contracts set compliance benchmarks.
Individual Consumers anchor current revenue pools. Small Enterprises are climbing the fastest as fixed-mobile substitution accelerates.
Pricing Model:
Revenue predictability and customer lifetime value vary structurally across payment structures, shaping MVNO cash flow profiles and capital planning horizons.
- Monthly Subscription:Recurring revenue foundation with lowest churn and highest lifetime value. Northern European markets with mature direct debit infrastructure concentrate this model's penetration.
- Pay-as-you-go:Prepaid flexibility serving temporary residents, tourists, and credit-excluded populations. UK ethnic corridor shops and Southern European tourist zones sustain this declining structure.
- Bundled Plans:Quad-play integration with broadband and entertainment services. Virgin Media O2's UK heritage and German cable operator MVNOs dominate through infrastructure convergence.
- Family Plans:Multi-line discounts capturing household connectivity decisions. French and Spanish operators leverage this structure to reduce per-account acquisition costs.
Monthly Subscription captures the steadiest cash flows. Bundled Plans are gaining share fastest where host network operators own fixed infrastructure.
Distribution Channel:
Channel economics determine customer acquisition costs and geographic reach, with digital-native operators compressing physical overhead to fund price competition.
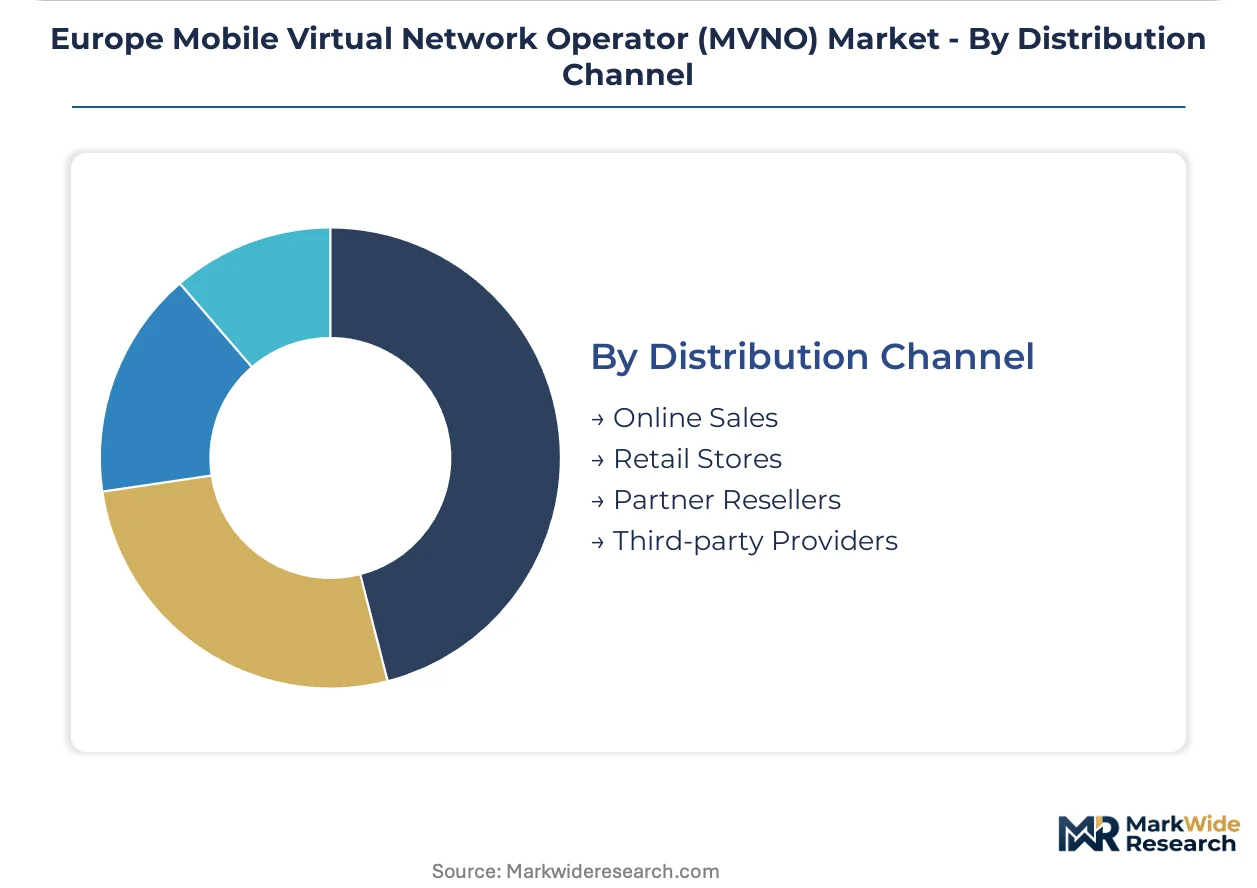
- Online Sales:Direct digital provisioning through eSIM and app-based onboarding. Giffgaff's UK community model and Scandinavian digital-first operators demonstrate lowest per-subscriber acquisition costs.
- Retail Stores:Physical presence for SIM distribution and customer service. Lycamobile's ethnic corridor shop networks in London, Paris, and Brussels anchor this channel's persistence.
- Partner Resellers:Electronics retailers and supermarket chains extending brand reach. German electronics chains and French hypermarket networks integrate MVNO offerings into broader telecom portfolios.
- Third-party Providers:Independent agents and comparison platforms aggregating subscriber decisions. Price comparison sites in the UK and Netherlands concentrate this channel's influence.
Online Sales now processes the majority of new activations. Partner Resellers are expanding most quickly as retail brands launch captive MVNO offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom engineering talent clusters in German industrial corridors anchor MVNO infrastructure development across the continent. Regulatory divergence between member states fragments wholesale access economics despite EU-level harmonization efforts. Urban density gradients determine viable business model selection from full network operators to digital-only resellers.
Germany
Automotive IoT demand from Stuttgart and Munich OEMs drives full MVNO network slicing requirements. BNetzA enforces cost-oriented wholesale pricing under the Electronic Communications Code implementation. The Rhine-Ruhr metropolitan corridor concentrates discount MVNO subscriber bases through price-sensitive industrial workforce segments.
United Kingdom
Ethnic corridor shops in London and Birmingham sustain prepaid calling card distribution for diaspora communities. Ofcom's net neutrality and wholesale access rulings shape host network negotiation frameworks. Manchester and Leeds digital enterprise zones accelerate data-only MVNO adoption for SME WAN substitution.
France
Logistics hubs around Lyon and Lille generate enterprise demand for managed 4G and 5G connectivity services. CNIL's GDPR enforcement tightens consent architecture requirements for customer data portability. The Paris metropolitan area anchors brand MVNO partnerships with retail cooperatives and supermarket chains.
Netherlands
Rotterdam and Amsterdam port complexes drive fleet management connectivity procurement from data-only specialists. The national telecom regulator ACM aligns wholesale access frameworks with EU Electronic Communications Code mandates. Eindhoven's high-tech manufacturing ecosystem experiments with private 5G integration through full MVNO intermediaries.
Spain
Tourist corridor zones in Barcelona and Madrid sustain pay-as-you-go subscriber pools despite structural decline elsewhere. The national regulatory authority CNMC monitors wholesale rate reviews affecting new entrant margin structures. Valencia's logistics automation sector pilots network-sliced assured connectivity for warehouse robotics.
Europe Mobile Virtual Network Operator (MVNO) Market Competitive Landscape
Capital-heavy full MVNOs compete with asset-light discount and data-only resellers across fragmented national wholesale markets. Three to four host network operators control infrastructure access in most member states, compressing bargaining power for downstream service providers. Strategic archetypes separate into quad-play bundlers, ethnic segment specialists, community-driven digital natives, and enterprise connectivity purveyors. Competitive moves concentrate on eSIM-native provisioning adoption and Eastern European geographic expansion.
Within the community-driven tier, Giffgaff Limited exemplifies asset-light customer acquisition through digital channels without physical retail overhead. Among German-speaking market specialists, Freenet AG and Congstar GmbH occupy positions bridging discount consumer segments with enterprise connectivity services. Lycamobile Europe Limited anchors the ethnic and diaspora calling archetype through specialized prepaid offerings concentrated in urban corridor shops.
| Leading Market Players |
|---|
| Giffgaff Limited |
| Freenet AG |
| Lycamobile Europe Limited |
| Virgin Media O2 |
| Congstar GmbH |
| Lebara Mobile Limited |
| iD Mobile Limited |
| Truphone Ltd. |
| Tesco Mobile Limited |
| Others |
Pricing and Supply Chain Analysis
German automotive OEMs and industrial fleet managers concentrate purchasing power for assured-connectivity tiers, anchoring premium subscription pricing while discount arbitrage operators serve price-sensitive consumer segments across Southern and Eastern Europe.
Pricing Analysis
The bundled-versus-unbundled service split separates enterprise procurement from consumer markets. Monthly subscription models dominate Northern European markets with mature direct debit infrastructure, while pay-as-you-go plans face structural decline outside tourist corridors. Price differentiation hinges on network slicing certification levels and host operator priority data guarantees. Pricing pressure stems from cable operators' DOCSIS 4.0 expansions threatening mobile broadband positioning. Small enterprises show highest price sensitivity as they negotiate standalone connectivity without handset subsidies.
Supply Chain Analysis
EU Electronic Communications Code mandates on domestic wholesale access reform are reshaping sourcing economics for host network agreements. Network infrastructure concentrates in Germany, France, and the United Kingdom as primary host operator territories. Core network components draw from specialized telecom engineering talent pools in Stuttgart, Munich, and Eindhoven. Single-source vulnerability runs through concentrated host network ownership—three to four infrastructure operators control national wholesale markets in most member states. Distribution feeds from digital eSIM-native channels compressing physical SIM logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in enterprise connectivity tiers where network slicing commands premium pricing, while eSIM-native provisioning eliminates physical distribution overhead.
For Market Incumbents: Hedge against fixed wireless substitution by deepening enterprise IoT service integration and securing exclusive host network slicing agreements. Invest in CSRD-aligned carbon transparency offerings as German and Dutch corporate procurement teams unbundle connectivity from device sourcing. Prioritize certification for automotive OEM private 5G integration requirements. For New Entrants and Emerging Players: eSIM-native digital provisioning offers the clearest technology-first wedge against established physical retail networks. Target Poland, Romania, and Bulgaria where MVNO penetration trails Western benchmarks. Pursue ethnic corridor shop partnerships for diaspora prepaid segments or data-only logistics hub contracts around Rotterdam and Lyon. For Investors and Strategic Acquirers: Host mobile network operators are the most active acquirer in this space, seeking vertical integration into downstream service packaging. Full MVNOs with dedicated HLR/HSS infrastructure and established host agreements represent the most defensible acquisition profile. Watch for wholesale rate review decisions in France, Italy, and Spain as inflection signals for new entrant margin viability.| Strategic Initiative | Industry Significance |
|---|---|
| eSIM-Native Provisioning Deployment | Eliminates physical SIM logistics costs and enables instant subscriber onboarding through Giffgaff-style digital channels. |
| Network Slicing Certification Investment | Unlocks premium enterprise tiers for Stuttgart automotive OEMs requiring assured bandwidth for industrial IoT. |
| Eastern European Geographic Expansion | Captures first-mover positioning in Poland and Romania where MVNO penetration remains below Western benchmarks. |
| CSRD-Aligned Carbon Transparency Program | Addresses Dutch and German corporate sustainability reporting requirements for renewable-powered connectivity sourcing. |
| Ethnic Corridor Shop Network Partnership | Secures distribution for diaspora prepaid offerings through Lycamobile-style urban retail presence in London and Brussels. |
Research Methodology
Bottom-up enterprise mobility modeling reconciled against top-down host network wholesale tracking forms the analytical core. Primary interviews with MVNO strategy executives, host network wholesale managers, regulatory affairs leads at BNetzA and Ofcom, and enterprise procurement officers at German automotive OEMs combined with secondary validation from EU Electronic Communications Code implementation documents, national regulatory authority wholesale rate filings, and host operator infrastructure disclosure reports. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of subscriber migration patterns from fixed-line to mobile WAN connectivity informed growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include service type architecture, end-user category, pricing model structure, and distribution channel intensity alongside regional regulatory cluster differentiation. CAGRs derive from host operator 5G standalone deployment timelines and enterprise IoT adoption curves.
The model holds under stable wholesale access pricing and continued EU Electronic Communications Code enforcement; deviation in spectrum reallocation decisions or host network consolidation would shift margin structures. Forecasts reflect documented assumptions on enterprise substitution rates and eSIM adoption velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Satellite Broadband Communication in Public Safety Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
IP Telephony Market
Telecommunications
TV White Space Spectrum Market
Telecommunications
Smart SIM Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
IoT MVNO (Services) Market
Telecommunications
Cloud PBX Market
Telecommunications
Argentina ICT Market
Telecommunications
Global LTE Market
Telecommunications
Utility Communications Market
Telecommunications
Africa Roaming Tariff Market
Telecommunications
Kenya Telecom Market
Telecommunications
Global IP Phone Market
Telecommunications
Cambodia Telecom Tower Market