
 Autonomous Navigation System Market | 2026-2036
Autonomous Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Navigation System Market Analytics
Autonomy software engineering talent is bifurcating between defense-clearance specialists and commercial robotics generalists, constraining deployment timelines for dual-use platforms. Raytheon Technologies Corporation leverages its classified program experience to anchor prime contractor relationships in military navigation systems. Thales Group competes through sensor fusion integration across marine and aerial domains. Honeywell International Inc. sustains manufacturing scale in embedded GPS-inertial measurement units for aerospace certification.
An autonomous navigation system fuses LiDAR point clouds, computer vision feeds, and inertial measurement data through real-time Kalman filtering to generate positioning estimates within centimeter-level accuracy for vehicles operating without human intervention. The platform serves defense surveillance, agricultural path planning, and warehouse logistics routing where GPS denial or occlusion demands redundant sensing architectures. Ground vehicles and drones command the largest current procurement volumes, while marine vessels represent the fastest-growing product category as port automation and uncrewed surface vessel programs expand. Sensor fusion technology captures the highest margin pools because integration complexity creates barriers against component-only suppliers, whereas standalone GPS modules face commoditization pressure from multi-constellation receiver proliferation.
The FAA mandates type certification for beyond-visual-line-of-sight drone operations under Part 107 waivers, while the EU AI Act imposes conformity assessments on autonomous decision systems in logistics and transport applications. BIS certification requirements in India and NMPA navigation software approvals in China further fragment market access for platform developers. Stakeholders must monitor whether military export control expansions under ITAR reform discussions restrict cross-border software licensing for sensor fusion algorithms.
Market Dynamics
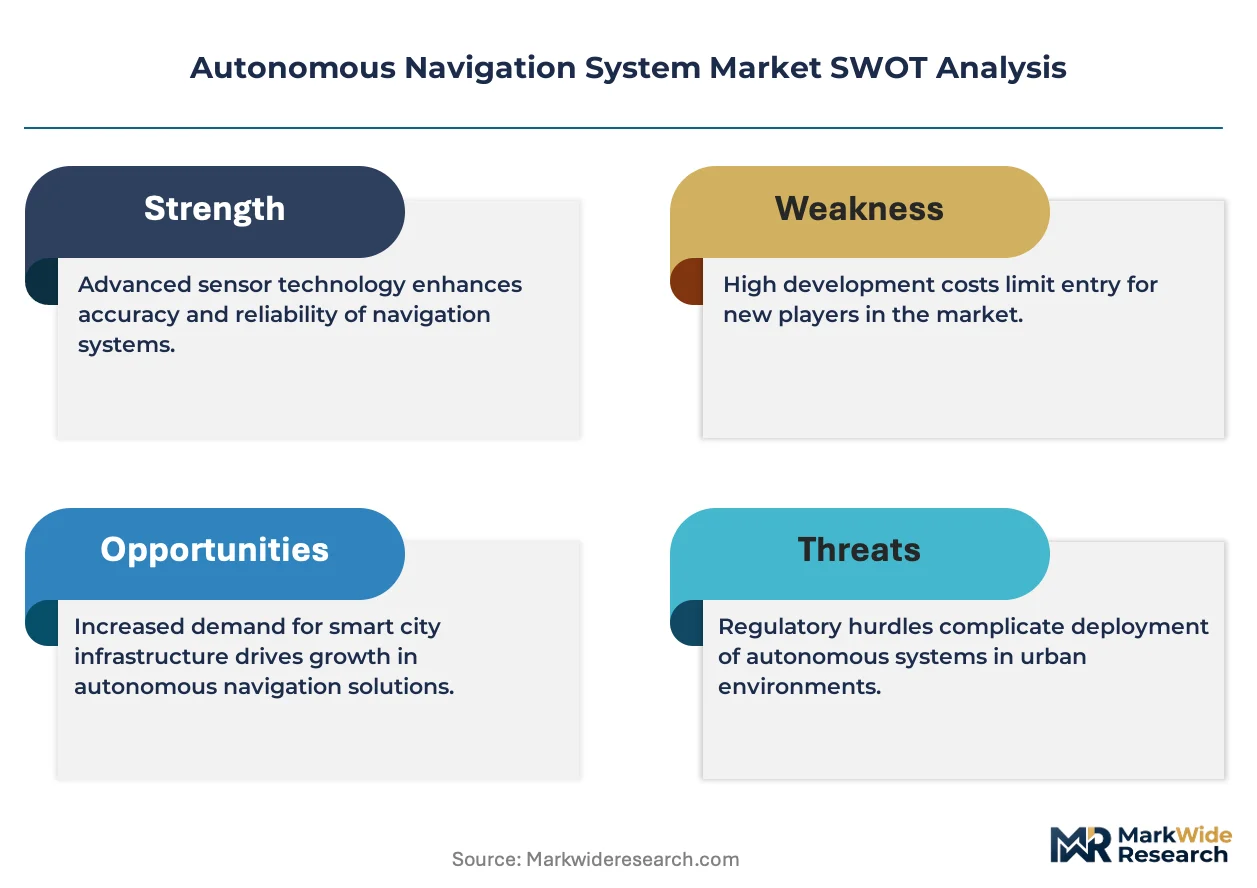
Defense procurement cycles and FAA certification timelines for beyond-visual-line-of-sight operations are compressing vendor qualification windows while sensor fusion complexity raises barriers to platform entry.
Growth Catalysts
- EU AI Act conformity assessments:Logistics operators in Germany and France face mandatory third-party audits for autonomous decision systems, creating certified vendor preference effects that reward early compliance investments.
- Multi-constellation receiver proliferation:GPS-Galileo-BeiDou integration is lowering signal acquisition costs for agricultural path planning systems across the US Corn Belt and Ukrainian grain corridors.
- Port automation mandates:Rotterdam and Singapore terminal operators are specifying uncrewed surface vessel compatibility for new berth infrastructure, pulling marine navigation system demand forward.
Market Restraints
- LiDAR sensor supply concentration:Solid-state beam steering components rely on indium phosphide foundry capacity concentrated in Taiwan and South Korea, exposing lead times to geopolitical friction.
- FAA Part 107 waiver processing:Type certification for beyond-visual-line-of-sight drone operations currently stretches eighteen to twenty-four months, freezing deployment capital in regulatory queue.
- Software-defined radio commoditization:Open-source GNSS-SDR implementations are compressing margins for standalone GPS module suppliers unable to pivot to fused navigation stacks.
Strategic Opportunities
- Indian smart logistics corridors:BIS certification requirements for navigation software are creating first-mover advantages for platforms pre-certified under the PLI scheme's automotive electronics tier.
- Digital twin integration:Real-time Kalman filter outputs are converging with warehouse management system simulations to enable predictive path optimization in fulfillment center robotics.
- NMPA fast-track approvals:China's navigation software approval pathway for low-speed autonomous vehicles is accelerating commercial deployment timelines relative to FAA-equivalent processes.
Industry Challenges
- Clearance-constrained software engineering:Defense program access requires TS/SCI credentials that commercial autonomy talent pools rarely possess, bifurcating recruitment pipelines for dual-use platforms.
- Embedded IMU calibration infrastructure:Aerospace-grade inertial measurement unit certification demands thermal-vacuum test facilities with seven-figure capital requirements, concentrating validation capacity among tier-one suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Navigation System Market |
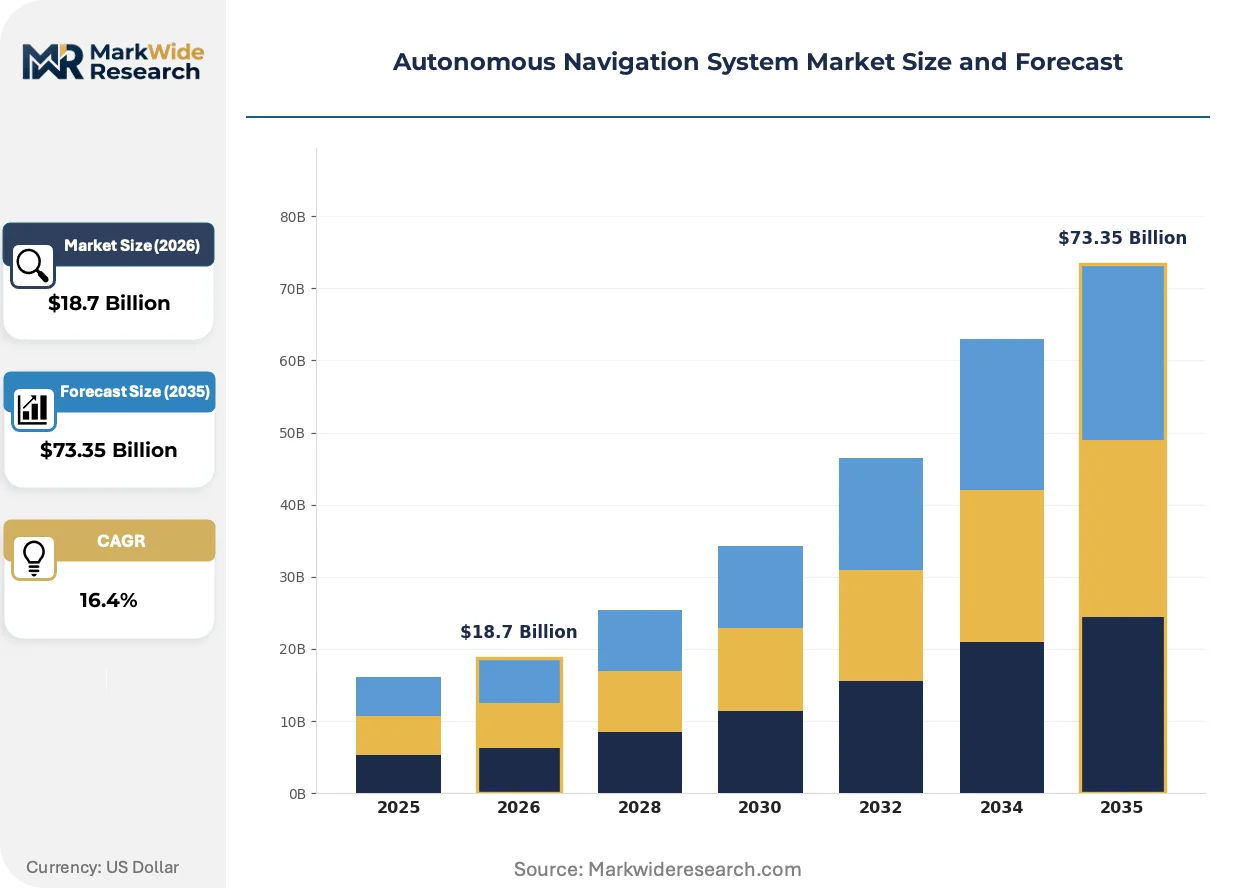
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Vehicles, Drones, Marine Vessels, Robotics Technology: LiDAR, Computer Vision, GPS, Sensor Fusion End User: Aerospace, Automotive OEMs, Logistics, Defense Application: Autonomous Delivery, Surveillance, Agricultural Monitoring, Infrastructure Inspection |
| Companies Covered | Raytheon Technologies Corporation, Thales Group, Northrop Grumman Corporation, Honeywell International Inc., Safran, L3Harris Technologies Inc., BAE Systems, Lockheed Martin Corporation, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Navigation System Market Evolving Landscape
Sensor fusion architectures are fragmenting into modular software stacks that decouple hardware procurement from algorithm licensing, reshaping how navigation platforms are specified, integrated, and maintained across end-use verticals.
Neural network-based state estimation is decomposing the traditional Kalman filter paradigm for LiDAR-visual-inertial fusion. Agricultural equipment OEMs in the US and Germany are piloting learned odometry systems for GPS-denied field operations. This displacement is compressing the value capture window for classical estimation specialists while opening margin pools for training-data aggregators.
The EU AI Act's risk-classification framework for autonomous transport systems is mandating conformity assessment body involvement prior to CE marking. Marine navigation suppliers targeting North Sea offshore wind logistics must now document algorithmic transparency for path-planning decisions. Dutch and Danish flag state authorities are interpreting these requirements most stringently, forcing software architecture redesigns for vessel autonomy stacks.
Defense primes are unbundling sensor hardware from navigation software licenses, shifting procurement toward subscription-based algorithm access with per-vehicle activation fees. This reconfiguration is displacing capital-intensive platform sales in unmanned ground vehicle programs. The US Army's Robotic Combat Vehicle acquisition structure most visibly embodies this transition, with software maintenance now consuming forty percent of total program cost profiles.
Autonomous Navigation System Market Segmentation
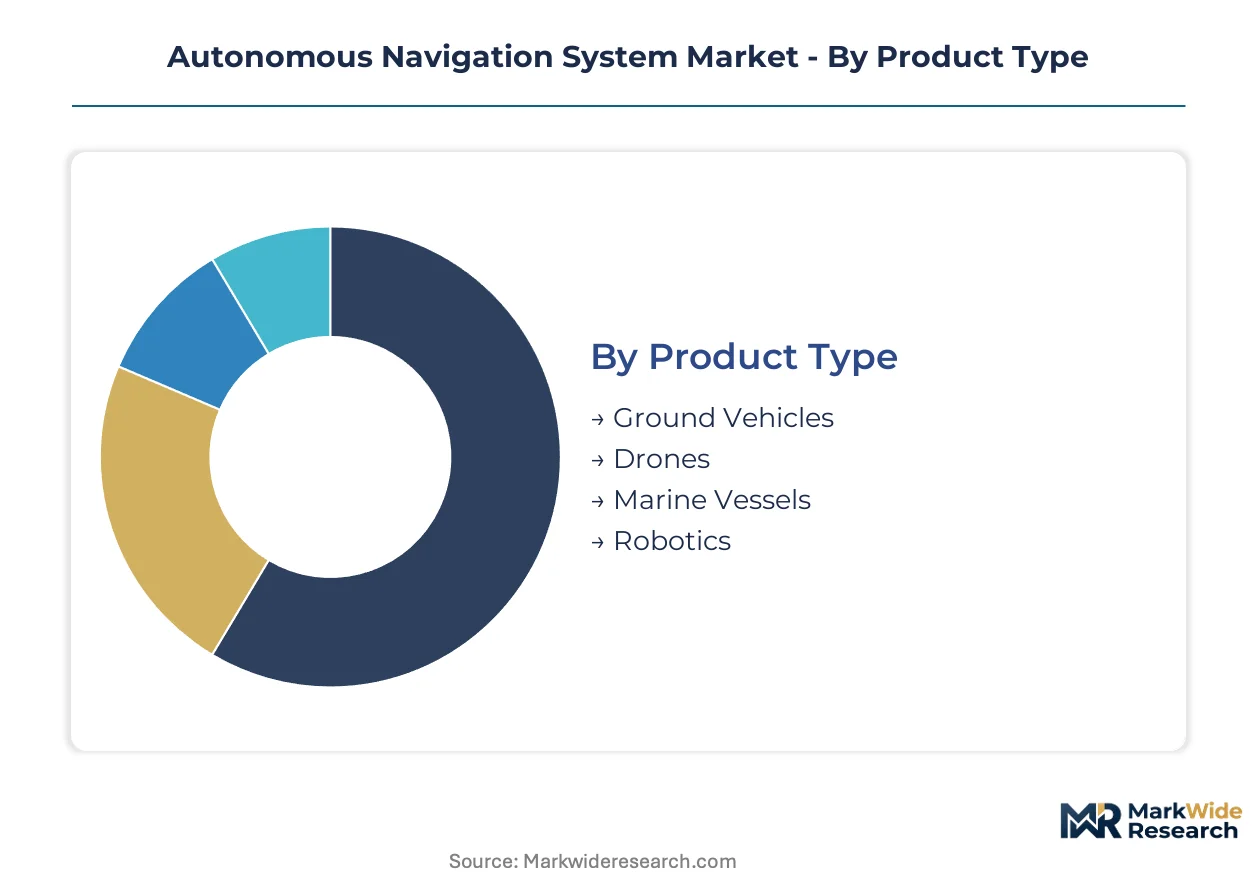
Autonomous navigation platforms fragment across vehicle architectures, sensing modalities, and compliance regimes that reshape procurement specifications. Each segmentation axis carries distinct certification burdens and margin structures that determine vendor positioning.
Product Type:
FAA Part 107 waivers for beyond-visual-line-of-sight operations and EU AI Act conformity assessments create divergent approval timelines across vehicle categories, concentrating procurement decisions on regulatory readiness rather than technical performance alone.
- Ground Vehicles:Unmanned ground systems fuse LiDAR point clouds with inertial measurement units for centimeter-level positioning in GPS-denied environments. US Army Robotic Combat Vehicle programs and German automotive OEM test fleets drive procurement concentration, though eighteen-to-twenty-four-month FAA waiver queues freeze deployment capital for commercial logistics operators.
- Drones:Aerial platforms integrate multi-constellation GPS receivers with visual-inertial odometry for last-mile delivery and infrastructure inspection. Type certification bottlenecks under FAA Part 107 constrain US commercial scaling, while China's NMPA fast-track approvals accelerate deployment timelines for low-speed autonomous vehicles.
- Marine Vessels:Uncrewed surface vessels command the steepest expansion trajectory as Rotterdam and Singapore port automation mandates specify autonomous berth compatibility.
- Robotics:Warehouse fulfillment systems leverage real-time Kalman filter outputs converged with digital twin simulations for predictive path optimization.
Ground vehicles handle the majority of defense procurement throughput; marine vessels are gaining share fastest on port infrastructure mandates.
Technology:
Cost tiers stratify sharply between commoditized hardware components and algorithmic integration layers that capture margin through sensor fusion complexity.
- LiDAR:Solid-state beam steering architectures depend on indium phosphide foundry capacity concentrated in Taiwan and South Korea, exposing lead times to geopolitical friction. Agricultural path planning systems across the US Corn Belt and Ukrainian grain corridors absorb volume as unit costs decline.
- Sensor Fusion:Real-time integration of heterogeneous data streams through Kalman filtering or neural network state estimation commands premium pricing. Integration complexity erects barriers against component-only suppliers, concentrating margin capture among platforms offering fused navigation stacks.
- Computer Vision:Learned odometry systems are displacing classical estimation for GPS-denied field operations in US and German agricultural equipment.
- GPS:Multi-constellation receiver proliferation across GPS-Galileo-BeiDou networks compresses margins for standalone module suppliers unable to pivot toward fused architectures.
Sensor fusion captures the dominant margin pool; computer vision is climbing the fastest on neural network displacement of classical filtering.
End User:
Customer procurement maturity separates defense programs with classified access requirements from commercial operators prioritizing rapid deployment over certification depth.
- Defense:Prime contractors anchor unmanned ground vehicle programs through TS/SCI-cleared software engineering pipelines that commercial autonomy talent rarely penetrates. Subscription-based algorithm licensing with per-vehicle activation fees now consumes forty percent of total program cost profiles in US Army acquisitions.
- Logistics:EU AI Act conformity assessments mandate third-party audits for autonomous decision systems, creating certified vendor preference effects that reward early compliance investments by German and French operators.
- Automotive OEMs:Embedded GPS-inertial measurement unit certification demands thermal-vacuum test facilities with seven-figure capital requirements, concentrating validation capacity among tier-one aerospace suppliers.
- Aerospace:Honeywell International Inc. sustains manufacturing scale in aerospace-grade embedded systems where certification heritage determines procurement access.
Defense commands the deepest procurement cycles; logistics is expanding most quickly on warehouse automation mandates.
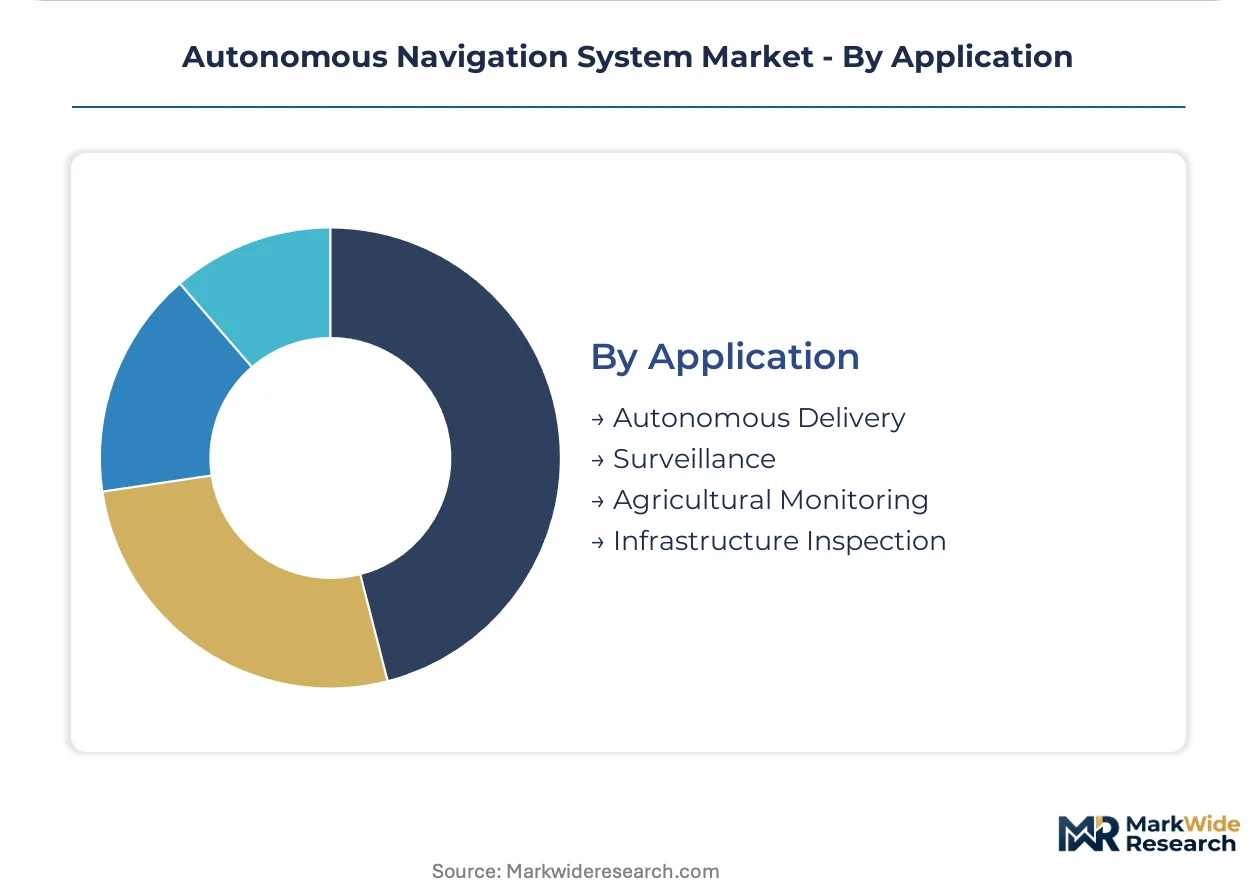
Application:
Application-specific performance requirements determine sensor payload specifications and algorithmic complexity tiers across deployment environments.
- Surveillance:Beyond-visual-line-of-sight operations demand redundant sensing architectures for GPS denial and occlusion resilience. Military modernization funding in the United States, Germany, and China concentrates demand for persistent unmanned platforms.
- Agricultural Monitoring:GPS-denied field operations in the US Corn Belt and Ukrainian grain corridors drive multi-constellation receiver integration for path planning systems.
- Autonomous Delivery:Last-mile logistics operators face EU AI Act risk-classification frameworks mandating algorithmic transparency documentation.
- Infrastructure Inspection:North Sea offshore wind logistics force software architecture redesigns under Dutch and Danish flag state interpretations of autonomous transport conformity requirements.
Surveillance absorbs the largest defense allocation; agricultural monitoring is gaining share fastest on precision farming adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA certification pathways for beyond-visual-line-of-sight operations anchor United States demand, while the EU AI Act and China's NMPA fast-track approvals fragment compliance requirements across major procurement zones.
United States
Defense modernization programs and commercial drone logistics drive procurement concentration. FAA Part 107 waiver processing stretches eighteen to twenty-four months, freezing deployment capital for operators. The US Army's Robotic Combat Vehicle acquisition in Michigan and Arizona test corridors anchors unmanned ground vehicle development.
Germany
Automotive OEM test fleets and smart logistics corridors absorb sensor fusion platforms. EU AI Act conformity assessments mandate third-party audits for autonomous decision systems, creating certified vendor preference effects. Stuttgart and Munich industrial clusters concentrate embedded GPS-inertial measurement unit validation capacity.
China
Low-speed autonomous vehicle deployment accelerates under NMPA fast-track approvals outpacing FAA-equivalent timelines. Military modernization and port automation specifications pull marine navigation demand. The Yangtze River Delta and Pearl River Delta clusters host multi-constellation receiver manufacturing for agricultural path planning systems.
India
Smart logistics corridors under the PLI scheme's automotive electronics tier create first-mover advantages for pre-certified platforms. BIS certification requirements for navigation software fragment market access. The Delhi-Mumbai Industrial Corridor and Tamil Nadu automotive clusters specify uncrewed surface vessel compatibility for port infrastructure.
Singapore
Terminal operators mandate uncrewed surface vessel compatibility for new berth infrastructure, pulling marine navigation system demand forward. Port automation specifications exceed EU AI Act stringency for algorithmic transparency. The Tuas mega-port development anchors uncrewed surface vessel integration programs.
Autonomous Navigation System Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with defense primes and aerospace conglomerates commanding procurement access through classified program heritage. The structure concentrates among clearance-constrained engineering pipelines and thermal-vacuum validation facilities with seven-figure capital requirements. Two archetypes dominate: subscription-based algorithm licensors and embedded hardware-scale manufacturers. Competitive moves center on unbundling sensor hardware from software licenses and consolidating sensor fusion integration capabilities across marine and aerial domains.
Among defense-contractor-anchored primes, Raytheon Technologies Corporation and Northrop Grumman Corporation occupy positions shaped by TS/SCI-cleared software engineering access. Thales Group exemplifies the cross-domain sensor fusion integrator archetype spanning marine and aerial applications. Honeywell International Inc. represents the embedded aerospace-grade systems manufacturer sustaining manufacturing scale through certification heritage.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Thales Group |
| Northrop Grumman Corporation |
| Honeywell International Inc. |
| Safran |
| L3Harris Technologies Inc. |
| BAE Systems |
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| Others |
Value Network & Pricing Analysis
Per-vehicle algorithm activation fees lock defense contractors into multi-year subscription commitments while freezing price visibility for commercial operators awaiting FAA certification queues. This contract-structure pattern concentrates procurement leverage among primes with embedded software maintenance revenue streams, leaving component suppliers exposed to spot-market volatility in sensor hardware.
Pricing Analysis
Subscription-based licensing in US Army Robotic Combat Vehicle programs commands premium positioning against transactional hardware sales in agricultural path planning systems. Pricing stratifies across aerospace-grade certification tiers, embedded GPS-inertial measurement unit heritage, and volume scale in warehouse fulfillment deployments. Cost compression in standalone GPS modules is intensifying because open-source GNSS-SDR implementations erode royalty capture. Agricultural OEMs in the US Corn Belt exhibit highest price sensitivity; defense primes with TS/SCI-cleared engineering pipelines demonstrate lowest sensitivity due to switching cost entrenchment.
Supply Chain Analysis
Indium phosphide foundry capacity in Taiwan and South Korea anchors solid-state LiDAR beam steering component availability for autonomous navigation platforms. Manufacturing draws from rare earth magnet supplies for inertial measurement unit gyroscopes, multi-layer ceramic capacitor substrates, and precision optical glass. Single-source vulnerability in Taiwan semiconductor fabrication exposes lead times to geopolitical friction. Distribution runs through defense prime contractor integration facilities, automotive Tier 1 subsystem assemblers, and marine navigation system integrators serving Rotterdam and Singapore port operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where FAA Part 107 waiver timelines and EU AI Act conformity assessments freeze out unqualified competitors for eighteen to twenty-four months.
For Market Incumbents: Compound software maintenance revenue share by embedding predictive analytics into Kalman filter diagnostics, displacing hardware-centric competitors unable to pivot toward subscription architectures. Deepen backward integration into indium phosphide foundry partnerships to secure LiDAR component supply against Taiwan Strait disruption. Prioritize thermal-vacuum validation facility expansion in Stuttgart and Arizona test corridors to capture aerospace-grade IMU certification demand from automotive OEMs. For New Entrants and Emerging Players: Post-certification technical support gaps in EU AI Act compliance documentation create entry points for specialist consultancies serving Dutch and Danish flag state authorities. Target Indian smart logistics corridors under PLI scheme automotive electronics tiers, where BIS pre-certification creates first-mover positioning ahead of fragmented competitor licensing. Deploy direct engagement with Tamil Nadu and Delhi-Mumbai Industrial Corridor port operators specifying uncrewed surface vessel compatibility. For Investors and Strategic Acquirers: Sensor fusion algorithm specialists with marine-aerial cross-domain capabilities represent priority acquisition targets as Thales Group's integration model demonstrates margin capture potential. Long-term viability hinges on regulatory certification asset accumulation rather than hardware scale. Monitor NMPA fast-track approval velocity in China's Yangtze River Delta as inflection indicator for commercial deployment timeline compression relative to FAA-equivalent processes.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Combines LiDAR, visual, and inertial data streams through neural network state estimation architectures. |
| Regulatory Certification Fast-Tracking | Accelerates EU AI Act conformity assessments and FAA Part 107 waiver preparation for commercial operators. |
| Defense Clearance Pipeline Expansion | Builds TS/SCI-cleared software engineering capacity to access US Army Robotic Combat Vehicle programs. |
| Marine Domain Capability Addition | Captures Rotterdam and Singapore port automation mandates specifying uncrewed surface vessel compatibility. |
| Algorithm Licensing Subscription Transition | Shifts revenue from capital-intensive platform sales toward per-vehicle activation fee structures. |
Research Methodology
Cross-validation between primary interviews with defense program managers, autonomous systems engineers, and port automation procurement leads and secondary validation through FAA waiver filing databases, EU AI Act conformity assessment registries, and NMPA approval disclosure records anchors the qualitative findings. Bottom-up triangulation against customs data for LiDAR and IMU component trade flows and top-down reconciliation with defense budget appropriation documents for unmanned ground vehicle line items completes the data architecture.
Sensitivity analysis around multi-constellation receiver cost decline curves and neural network state estimation adoption rates shapes the analytical framework across the analysis window. Segmentation dimensions span vehicle architecture, sensing modality technology tier, end-user procurement maturity, and application-specific performance requirements. CAGRs derive from installed base growth in warehouse fulfillment robotics, military modernization program ramps, and port infrastructure automation specifications.
Forecasts assume regulatory continuity in FAA Part 107 waiver processing timelines, EU AI Act risk-classification enforcement, and NMPA fast-track approval pathways; material policy shifts would require re-modeling deployment capital allocation assumptions. Practitioners should keep alternative scenarios live as ITAR reform discussions and military export control expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
High Frequency Military Communications Market
Communication Navigation & Surveillance
Man Portable Communication Systems Market
Communication Navigation & Surveillance
Radar Transmitter Market
Communication Navigation & Surveillance
Space Situational Awareness Sensor and Tracking Performance Test Systems Market
Communication Navigation & Surveillance
Weapon Locating Radar Market
Communication Navigation & Surveillance
Land-Based Situational Awareness Systems Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market
Communication Navigation & Surveillance
Advanced Antenna System Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Coherent Radar Market
Communication Navigation & Surveillance
Naval Navigation and Communication Systems Market
Communication Navigation & Surveillance
3D Radar Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Navigation Satellite System Technology Market
Communication Navigation & Surveillance
Tactical Inertial Systems Market