
 Missile Guidance Radar Market | 2026-2036
Missile Guidance Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Missile Guidance Radar Market Analytics
Defense procurement concentration is decoupling from traditional prime-contractor relationships as allied governments diversify supplier bases. Raytheon Technologies sustains technology leadership through captive GaN foundry investments. Lockheed Martin anchors major platform integration programs across multiple NATO air and missile defense architectures. BAE Systems navigates transatlantic regulatory complexity while competing for national sovereign radar contracts.
Missile guidance radar denotes active and semi-active sensor systems that track, illuminate, and provide terminal homing updates to maneuvering munitions, typically operating in X-band or Ku-band frequencies with pulse-Doppler or continuous-wave waveforms to discriminate targets from clutter. These systems serve the primary purpose of enabling precision engagement against aircraft, ballistic missiles, and maritime threats in contested electromagnetic environments. Phased array technology dominates platform-level installations due to electronic beam agility and multi-target handling capacity, while synthetic aperture radar variants represent the fastest-growing segment for standoff targeting in poor-weather conditions. Monopulse radar retains mature positions in legacy stockpile upgrades where cost constraints limit full architecture replacements.
The U.S. Department of Defense, NATO Standardization Office, and the EU's European Defence Agency collectively shape certification requirements, interoperability mandates, and cross-border technology transfer rules that determine market access for foreign suppliers. Emerging export control frameworks under the Wassenaar Arrangement increasingly restrict GaN amplifier and digital receiver technology flows to non-allied nations. Stakeholders must monitor sovereign industrial-base policies that incentivize domestic radar manufacturing over foreign platform integration.
Market Dynamics
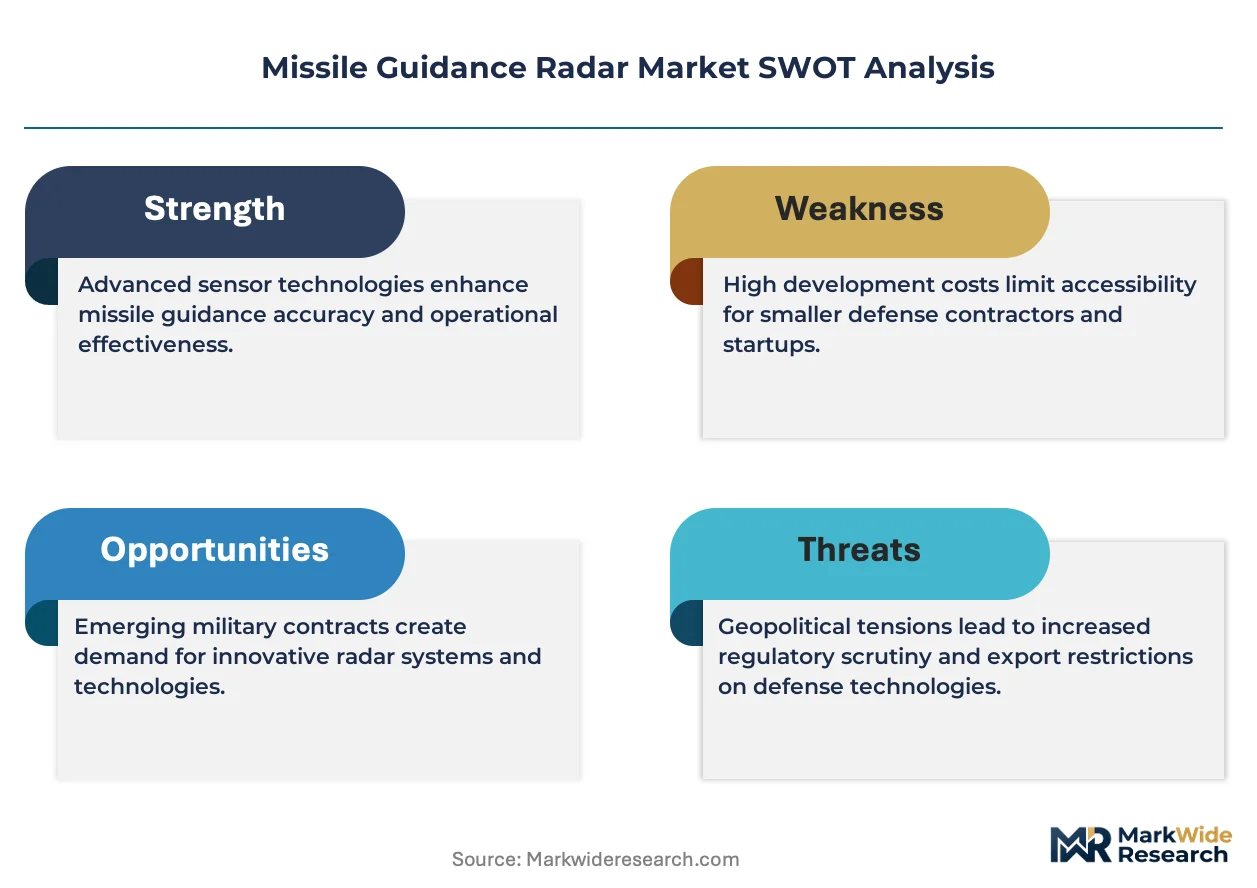
GaN semiconductor maturation is compressing transmitter thermal budgets while expanding electronic attack resistance, forcing incumbents to rebuild foundry strategies around sovereign wafer supply.
Growth Catalysts
- Hypersonic interceptor programs:Pentagon modernization budgets prioritize seeker upgrades for Mach 5+ engagement kinematics, pulling demand for wideband digital receivers.
- REACH substance restrictions:EU chemical regulations are accelerating lead-free solder and compliant substrate adoption in European radar manufacturing chains.
- Maritime patrol expansion:NATO anti-ship missile defense procurement is driving active radar adoption on frigate and destroyer platforms.
Market Restraints
- GaN wafer supply concentration:Six-inch GaN-on-SiC substrate fabrication clusters in Japan and the United States create single-source vulnerability for amplifier foundries.
- ITAR classification friction:U.S. State Department export controls on digital receiver technology block technology transfer to non-allied integration partners.
- Thermal management complexity:Power density scaling in compact seeker packages exceeds passive cooling limits, forcing active liquid or spray architectures.
Strategic Opportunities
- Standoff SAR targeting:Synthetic aperture radar variants for poor-weather precision engagement represent underdeveloped white space in cruise missile seeker portfolios.
- Australian AUKUS integration:The country's nuclear-powered submarine program creates demand for sovereign radar manufacturing capacity outside traditional U.S. supply chains.
- Dual-use satellite servicing:Space-based radar calibration and on-orbit seeker testing services open new revenue channels for ground-segment operators.
Industry Challenges
- Phased array calibration expertise:Element-level phase and amplitude matching for active electronically scanned arrays requires scarce microwave engineering talent pools.
- Legacy monopulse integration:Stockpile upgrade programs demand backward-compatible waveform generation without full architecture replacement, constraining performance envelopes.
- Cross-domain electromagnetic certification:Joint air-maritime-ground interoperability testing extends qualification timelines by 18-24 months for multi-platform seekers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Missile Guidance Radar Market |
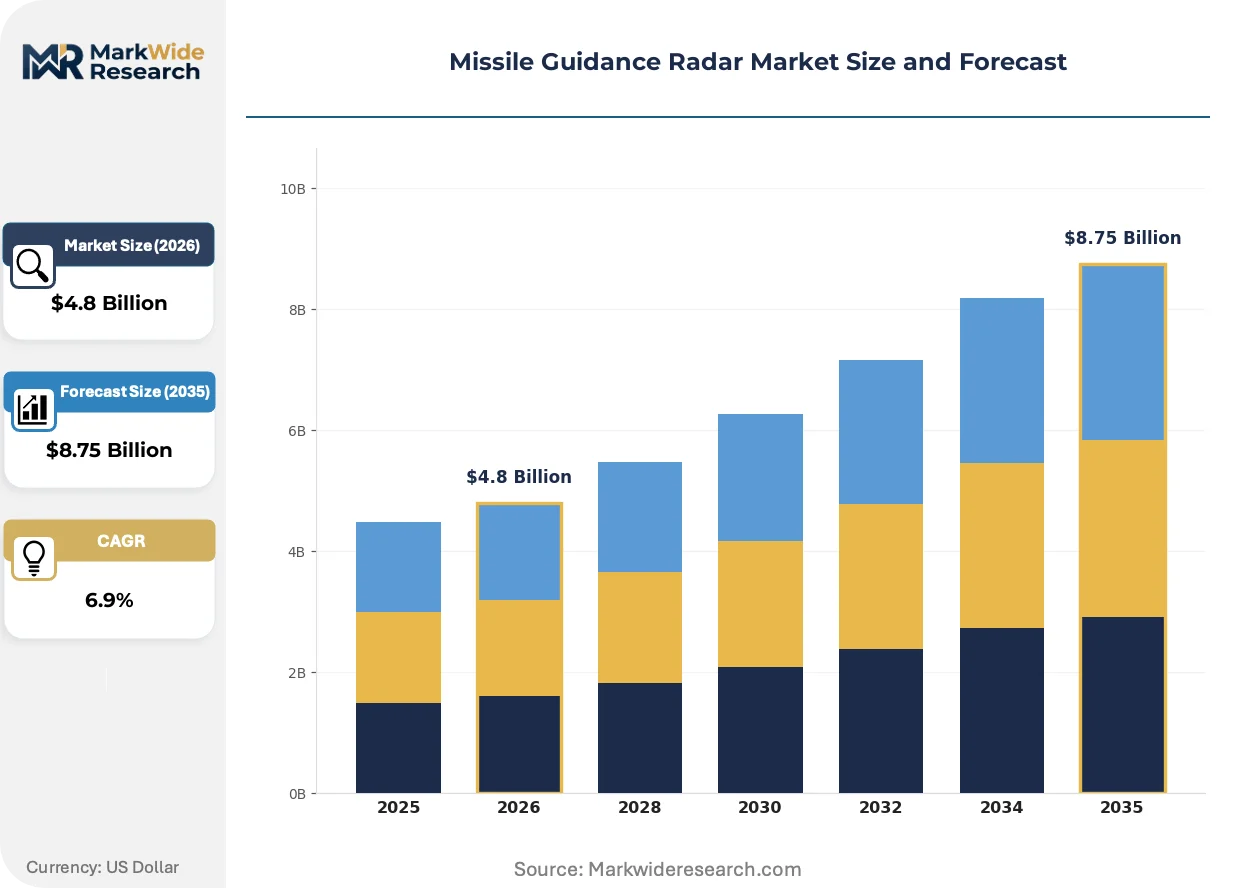
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.75 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Active Radar, Passive Radar, Semi-Active Radar, Inertial Guidance Application: Defense, Aerospace, Tactical Operations, Seaborne Platforms Technology: Phased Array, Doppler Radar, Monopulse Radar, Synthetic Aperture Radar End User: Military, Government, Defense Contractors, Research Institutions |
| Companies Covered | Raytheon Technologies Corp., Lockheed Martin Corp., BAE Systems Plc, Thales Group, Northrop Grumman Corp., Leonardo Spa, General Dynamics Corp., The Boeing Co., Israel Aerospace Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Missile Guidance Radar Market Evolving Landscape
Digital beamforming architectures are collapsing traditional hardware boundaries, merging functions previously split across analog subsystems into unified software-defined signal chains.
Software-defined radio front-ends with direct digital synthesis are unifying waveform generation, beam steering, and target tracking in single-chip implementations. Naval and airborne platform integrators in the United States and United Kingdom are prioritizing these architectures for multi-function radar resource allocation. This unification is compressing subcontractor tiers and concentrating value capture in semiconductor and firmware layers.
Wassenaar Arrangement export control frameworks are tightening GaN high-electron-mobility transistor and wideband digital converter listings, restricting technology flows to non-participant nations. European and Japanese component suppliers are reclassifying product roadmaps to maintain compliant export eligibility. Dual-use satellite and commercial radar manufacturers face heightened licensing scrutiny for formerly uncontrolled frequency bands.
Platform prime contractors are unbundling long-term sustainment from initial system procurement, selling availability-based service agreements separate from hardware acquisition. Royal Navy and U.S. Navy fleet modernization programs are piloting these models for radar mid-life upgrades. This restructuring is most advanced in Anglo-American defense procurement, where congressional and parliamentary oversight has accepted operational expenditure reclassification.
Missile Guidance Radar Market Segmentation
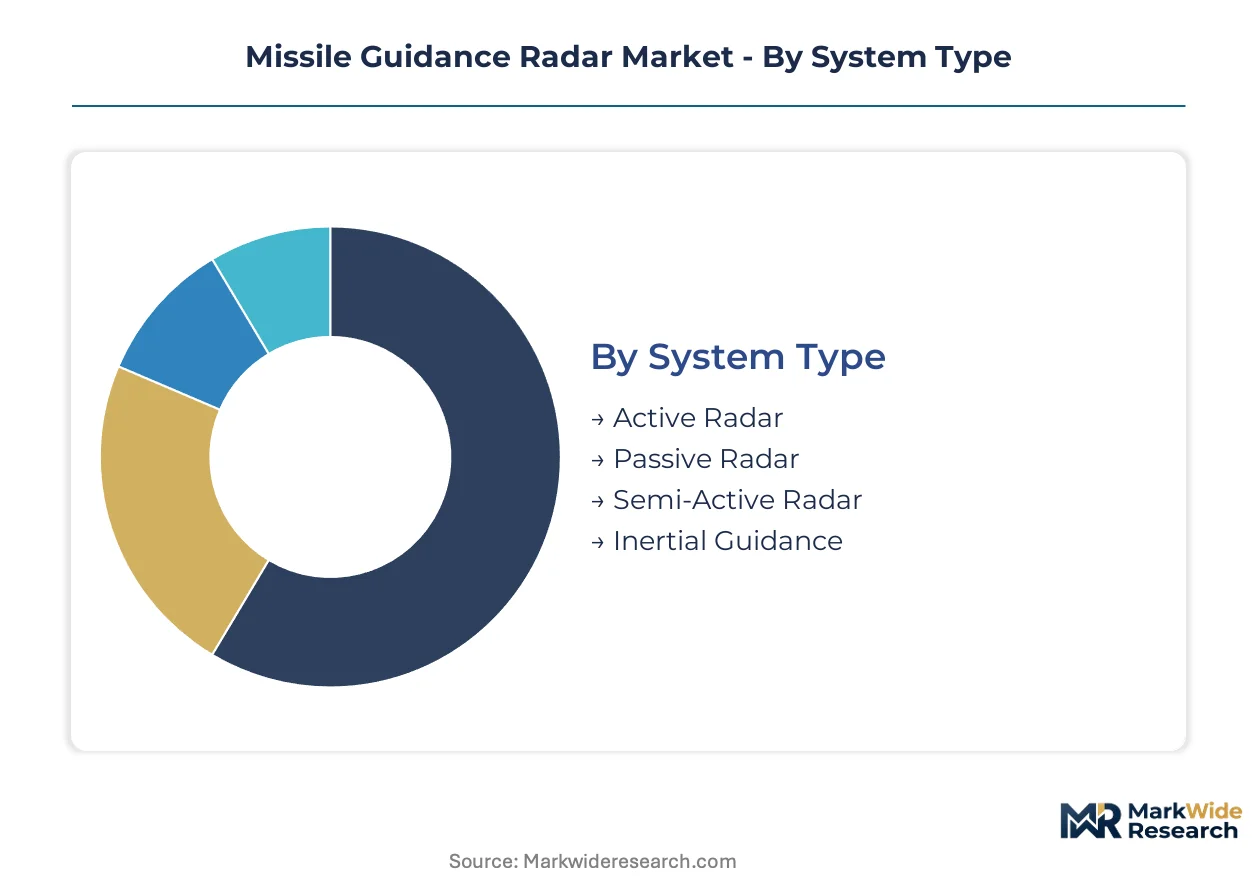
Segmentation in missile guidance radar reveals how technology maturation, procurement concentration, and platform-specific requirements reshape supplier priorities across distinct operational domains. Understanding these divisions exposes where defense budgets concentrate and where next-generation architectures displace legacy systems.
System Type:
Supply concentration for seeker architectures tilts toward active systems as sovereign manufacturing investments reduce dependence on off-board illuminators.
- Active Radar:Self-contained transmit-receive modules enable fire-and-forget engagement without external illumination. Pentagon hypersonic interceptor programs and NATO maritime defense procurement drive concentrated demand in the United States and United Kingdom for compact active seekers with GaN-based front-ends.
- Semi-Active Radar:Dependent on external target illumination from launch platforms or cooperative assets, these systems retain cost advantages for stockpile modernization where full architecture replacement exceeds budget envelopes. Legacy air defense networks in continental Europe sustain procurement through phased upgrades rather than platform replacement.
- Passive Radar:Exploits third-party electromagnetic emissions for covert targeting, reducing detectable signature during approach. Demand clusters in special-mission aircraft and submarine-launched cruise missile applications where emission control dominates operational requirements.
- Inertial Guidance:Self-contained navigation using accelerometers and gyroscopes provides jam-resistant mid-course correction without external references. Integration with GPS-denied contingency modes preserves utility in contested electronic warfare environments.
Today's leader: Active Radar. Tomorrow's challenger: Passive Radar.
Application:
Cost tier stratification separates sovereign platform integration from subsystem procurement, with prime contractors capturing value at the system level and component suppliers competing at the module tier.
- Defense:Integrated air and missile defense architectures consume the largest procurement volumes, spanning ground-based midcourse defense batteries and theater-range interceptors. U.S. Missile Defense Agency budgets prioritize wideband digital receivers for multi-domain tracking.
- Aerospace:Air-to-air and air-to-ground seekers for crewed and uncrewed platforms demand miniaturized phased arrays with active cooling. Fighter modernization programs in Japan and Australia drive regional manufacturing partnerships outside traditional U.S. supply chains.
- Tactical Operations:Short-range precision munitions for close combat require low-cost seekers with limited electronic counter-countermeasures. Procurement runs through rapid acquisition channels with compressed qualification timelines.
- Seaborne Platforms:Naval surface-to-air and anti-ship missile defense systems integrate multi-function radars with rotating or fixed-face arrays. Royal Navy Type 26 frigate and U.S. Navy DDG(X) programs anchor demand for scalable aperture designs.
Defense commands current procurement volume. Aerospace shows steepest expansion trajectory as uncrewed platform proliferation accelerates seeker demand.
Technology:
Volume concentration in phased array manufacturing has compressed analog supply chains while elevating semiconductor and firmware tiers to dominant value-capture positions.
- Phased Array:Active electronically scanned arrays dominate platform-level installations through electronic beam agility and simultaneous multi-target engagement. Element-level calibration requirements constrain supplier pools to established microwave engineering houses.
- Monopulse Radar:Mature angle-measurement architectures persist in legacy stockpile upgrades where cost constraints limit full architecture replacement. Backward-compatible waveform generation preserves interoperability with existing fire control systems.
- Synthetic Aperture Radar:Standoff all-weather imaging enables precision targeting through cloud cover and precipitation. Cruise missile seeker portfolios show underdeveloped penetration for SAR variants relative to electro-optical alternatives.
- Doppler Radar:Pulse-Doppler processing discriminates moving targets from stationary clutter through velocity filtering. Integration with continuous-wave illuminators supports semi-active homing in medium-range air defense systems.
Phased Array holds installed base dominance. Synthetic Aperture Radar offers the largest white-space opportunity for poor-weather precision engagement.
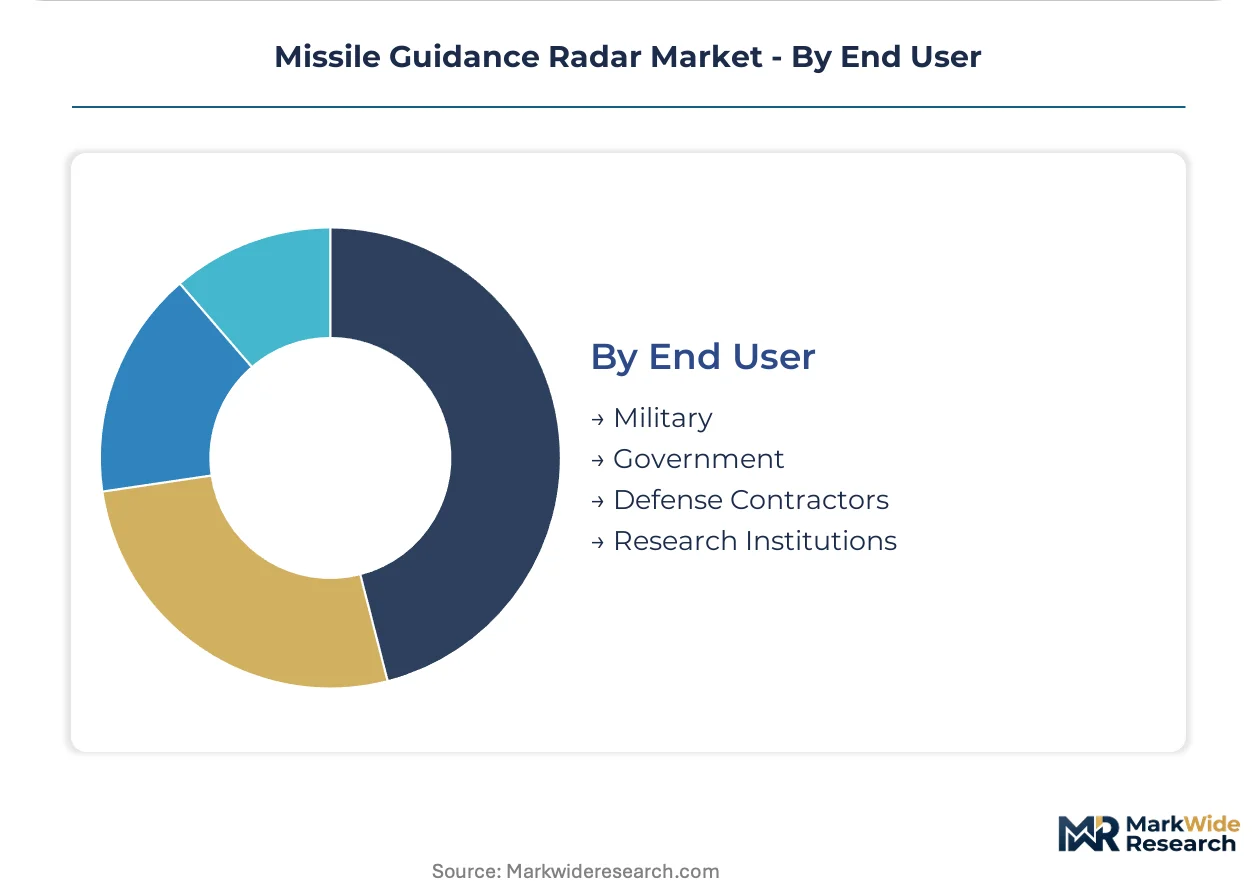
End User:
Customer type determines contracting mechanisms, with military end-users driving specification requirements and defense contractors managing subsystem integration risk.
- Military:Operational commands define performance specifications and interoperability mandates through NATO Standardization Office and U.S. Joint Requirements Oversight Council processes. Procurement concentrates in major defense acquisition programs with congressional or parliamentary authorization.
- Government:National laboratories and test ranges conduct seeker characterization, electromagnetic environmental effects testing, and countermeasure evaluation. Budget flows through research and development appropriations separate from platform procurement.
- Defense Contractors:Prime integrators and tier-one suppliers purchase subsystems for incorporation into weapon system deliveries. Long-term sustainment contracts increasingly unbundle from initial hardware acquisition under availability-based service models.
- Research Institutions:University-affiliated research centers and federally funded laboratories advance algorithm development, waveform design, and electromagnetic compatibility testing. Funding mixes defense appropriations with competitive grant mechanisms.
Military end-users anchor procurement volume. Defense Contractors control subsystem specification and supplier selection authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized microwave engineering talent pools concentrate in defense corridor cities across multiple continents, creating geographic anchors for seeker development and phased array calibration expertise.
United States
Pentagon modernization budgets prioritize hypersonic interceptor seeker systems and wideband digital receivers for Mach 5+ engagement kinematics. The Department of Defense and U.S. State Department ITAR classification frameworks restrict technology transfer to non-allied integration partners. Greater Boston and the Washington-Baltimore corridor host concentrated defense research institutions and prime contractor engineering centers driving active radar development.
United Kingdom
Royal Navy Type 26 frigate programs and fleet modernization initiatives anchor demand for scalable multi-function radar apertures. Ministry of Defence procurement pilots availability-based service agreements that unbundle long-term sustainment from initial hardware acquisition. The Bristol-Southwest England cluster sustains BAE Systems operations and submarine-launched cruise missile passive radar development.
Germany
Legacy air defense network modernization sustains semi-active radar procurement through phased upgrades rather than full platform replacement. EU REACH substance restrictions accelerate lead-free solder and compliant substrate adoption in European manufacturing chains. Bavaria and Baden-Württemberg host precision electronics suppliers serving NATO interoperability mandates.
Japan
Fighter modernization programs drive regional manufacturing partnerships for miniaturized phased arrays with active cooling outside traditional U.S. supply chains. METI industrial policy and national security legislation shape sovereign radar manufacturing incentives. The Nagoya-Chubu region concentrates aerospace subsystem suppliers and GaN-on-SiC substrate fabrication expertise.
Australia
The AUKUS nuclear-powered submarine program creates demand for sovereign radar manufacturing capacity independent of traditional supply chains. Defence procurement reforms emphasize domestic industrial base expansion for critical sensor technologies. South Australia anchors submarine construction and associated combat system integration activities.
Missile Guidance Radar Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supplier hierarchies. The market structure concentrates value capture at the semiconductor and firmware layers as digital beamforming collapses traditional hardware boundaries. Three archetypes dominate: platform prime integrators managing system-level risk, GaN foundry operators controlling sovereign wafer supply, and microwave engineering houses retaining phased array calibration expertise. Competitive moves center on captive foundry investments and availability-based service contract restructuring.
Within the platform prime tier, Raytheon Technologies Corp. and Lockheed Martin Corp. occupy positions shaped by Pentagon budget concentration and NATO architecture integration mandates. Northrop Grumman Corp. exemplifies the diversified defense conglomerate archetype spanning multiple sensor domains. These entities represent how technology leadership consolidates around GaN semiconductor investments and multi-domain electromagnetic certification capabilities.
| Leading Market Players |
|---|
| Raytheon Technologies Corp. |
| Lockheed Martin Corp. |
| BAE Systems Plc |
| Thales Group |
| Northrop Grumman Corp. |
| Leonardo Spa |
| General Dynamics Corp. |
| The Boeing Co. |
| Israel Aerospace Industries |
| Others |
Value Network & Pricing Analysis
Sovereign-backed defense contractors and Pentagon-captive foundry operators anchor supply-side ownership structures, compressing margin negotiation space for component specialists while concentrating pricing power at the semiconductor tier. This ownership pattern tightens cost pass-through mechanisms to platform integrators and sustains premium capture for GaN wafer supply.
Pricing Analysis
Bundled hardware-procurement contracts are unbundling from availability-based service agreements across Royal Navy and U.S. Navy fleet modernization programs. Three-tier pricing structure across development-grade, production-qualified, and sustainment-tier seeker systems reflects certification maturity and thermal management complexity. Cost compression in legacy monopulse upgrade tiers intensifies because stockpile modernization budgets constrain full architecture replacement. Defense contractors exhibit highest price sensitivity for subsystem procurement, while military end-users prioritize performance specifications over unit economics.
Supply Chain Analysis
GaN-on-SiC substrate fabrication rests on six-inch wafer clusters in Japan and the United States, creating single-source vulnerability for amplifier foundries serving hypersonic interceptor programs. Raw material dependencies span high-purity silicon carbide substrates, rare-earth magnetic materials for circulators, and specialty ceramics for thermal management substrates. Tariff exposure runs through Wassenaar Arrangement export control frameworks restricting digital receiver technology flows. Distribution runs through prime contractor integration hierarchies with captive tier-one supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The missile guidance radar market functions as a stable compounder, with Pentagon modernization budgets and NATO maritime defense procurement providing sustained demand visibility across multi-year acquisition cycles.
For Market Incumbents: Cement technology leadership through captive GaN foundry investments and phased array calibration expertise retention. Incumbents should defend against emerging pure-play microwave engineering houses by securing sovereign wafer supply agreements and deepening firmware-layer value capture. Multi-domain electromagnetic certification capabilities represent the critical lever for platform integration lock-in. For New Entrants and Emerging Players: Tier-two defense contractors in Australia and Japan offer channel partnership pathways for SAR seeker development and passive radar specialization. New entrants should prioritize standoff all-weather targeting applications as the most penetrable white space, with AUKUS submarine combat system integration as the specific go-to-market anchor. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap microwave engineering houses with phased array calibration capabilities and restricted government security clearances. Long-term viability framing centers on ten-year defense procurement visibility with hypersonic interceptor and uncrewed platform proliferation as demand anchors. Acquisition targets should exhibit GaN semiconductor integration expertise and NATO interoperability certification history. The signal to watch is Australian sovereign radar manufacturing capacity buildout as regional supply chain decoupling indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Captive GaN Foundry Investment | Raytheon's vertical wafer supply secures transmitter efficiency leadership against Lockheed Martin platform integration. |
| SAR Seeker Portfolio Expansion | Cruise missile manufacturers gain poor-weather precision engagement capability against electro-optical alternatives. |
| Availability-Based Service Restructuring | Royal Navy pilots unbundled sustainment contracts separate from DDG(X) hardware acquisition. |
| AUKUS Sovereign Manufacturing Buildout | Australian submarine programs demand radar capacity outside traditional U.S. supply chains. |
| Digital Beamforming Architecture Migration | Software-defined signal chains collapse analog subcontractor tiers into unified firmware layers. |
Research Methodology
Coverage spans the United States, United Kingdom, Germany, Japan, and Australia, with primary inputs from each defense corridor cluster. The research combines interviews with Pentagon program executives, Royal Navy procurement officers, GaN foundry engineering directors, and NATO Standardization Office certification leads with secondary validation from U.S. Missile Defense Agency budget justifications, EU REACH regulatory filings, Japanese METI industrial policy documents, and Wassenaar Arrangement control list amendments. Bottom-up seeker unit demand modeling triangulates against top-down defense appropriation analysis.
Rate-of-change decomposition separates volume growth from unit price evolution across the projection horizon. The analytical framework models system type, application, technology, and end user segmentation alongside sovereign manufacturing policy intensity as a cross-cutting dimension. CAGRs derive from defense procurement pipeline visibility and technology substitution curves for GaN versus legacy gallium arsenide transmitters. Hypersonic interceptor program acceleration and uncrewed platform seeker proliferation serve as primary volume drivers.
Revisions become necessary when Pentagon budget rescissions, Wassenaar Arrangement control list expansions, or GaN wafer supply disruptions materialize. Forecasts reflect documented assumptions regarding NATO interoperability mandate continuity and sovereign industrial base policy stability. A small set of triggers—Australian AUKUS construction delays, Japanese fighter program scope changes, and EU REACH substance restriction enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Navigation & Surveillance
Global Tactical Headset Market
Communication Navigation & Surveillance
Asia-Pacific Autonomous Navigation Market
Communication Navigation & Surveillance
Airborne SATCOM Market
Communication Navigation & Surveillance
Tactical Communications Market
Communication Navigation & Surveillance
Surface Radars Market
Communication Navigation & Surveillance
Latin America Inertial Systems Market
Communication Navigation & Surveillance
Space Situational Awareness (SSA) Systems Market
Communication Navigation & Surveillance
Global Navigation Satellite System (GNSS) Market
Communication Navigation & Surveillance
Global X-Band Radar Market
Communication Navigation & Surveillance
Inertial Systems Market
Communication Navigation & Surveillance
Naval Navigation and Communication Systems Market
Communication Navigation & Surveillance
Global Antenna Market
Communication Navigation & Surveillance
Anti-Jamming Market
Communication Navigation & Surveillance
Drone Transponders Market
Communication Navigation & Surveillance
EMEA Mission Critical Wireless Communications Market
Communication Navigation & Surveillance
Asia-Pacific Inertial Systems Market