
 Aerospace Floor Panels Market | 2026-2036
Aerospace Floor Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Floor Panels Market Analysis
A shift from single-source to multi-source composite supply is realigning procurement strategies across tier-one aerostructures. Collins Aerospace leverages its integrated interiors portfolio to sustain long-term OEM relationships. Hexcel Corporation anchors North American prepreg supply for honeycomb floor assemblies. Euro-Composites differentiates through European-based manufacturing and specialized thermoset processing capabilities.
Aerospace floor panels are structural sandwich assemblies, typically combining aluminum or aramid honeycomb cores with carbon fiber or glass-reinforced face sheets, engineered to meet strict strength-to-weight ratios and fire-resistance criteria for aircraft interiors. These panels distribute passenger and cargo loads across the airframe substructure while containing flame spread and toxic smoke release during thermal events. Honeycomb panels dominate current OEM installations due to their established qualification heritage and repair familiarity, while composite panels represent the fastest-expanding category as thermoplastic resins gain certification traction for weight reduction. Commercial aviation commands the largest end-user share, though military aviation applications are deepening as defense programs prioritize signature management and ballistic protection in floor structures.
FAA Part 25 flammability standards, EASA CS-25 certification requirements, and ISO 2685 fire containment protocols collectively dictate material selection, testing protocols, and market access for floor panel suppliers. These frameworks elevate barriers for unqualified entrants while rewarding incumbents with sustained type-certification relationships and design authority. Stakeholders must monitor evolving sustainable aviation mandates that may introduce recycled-content thresholds and lifecycle carbon accounting into future procurement specifications.
Market Dynamics
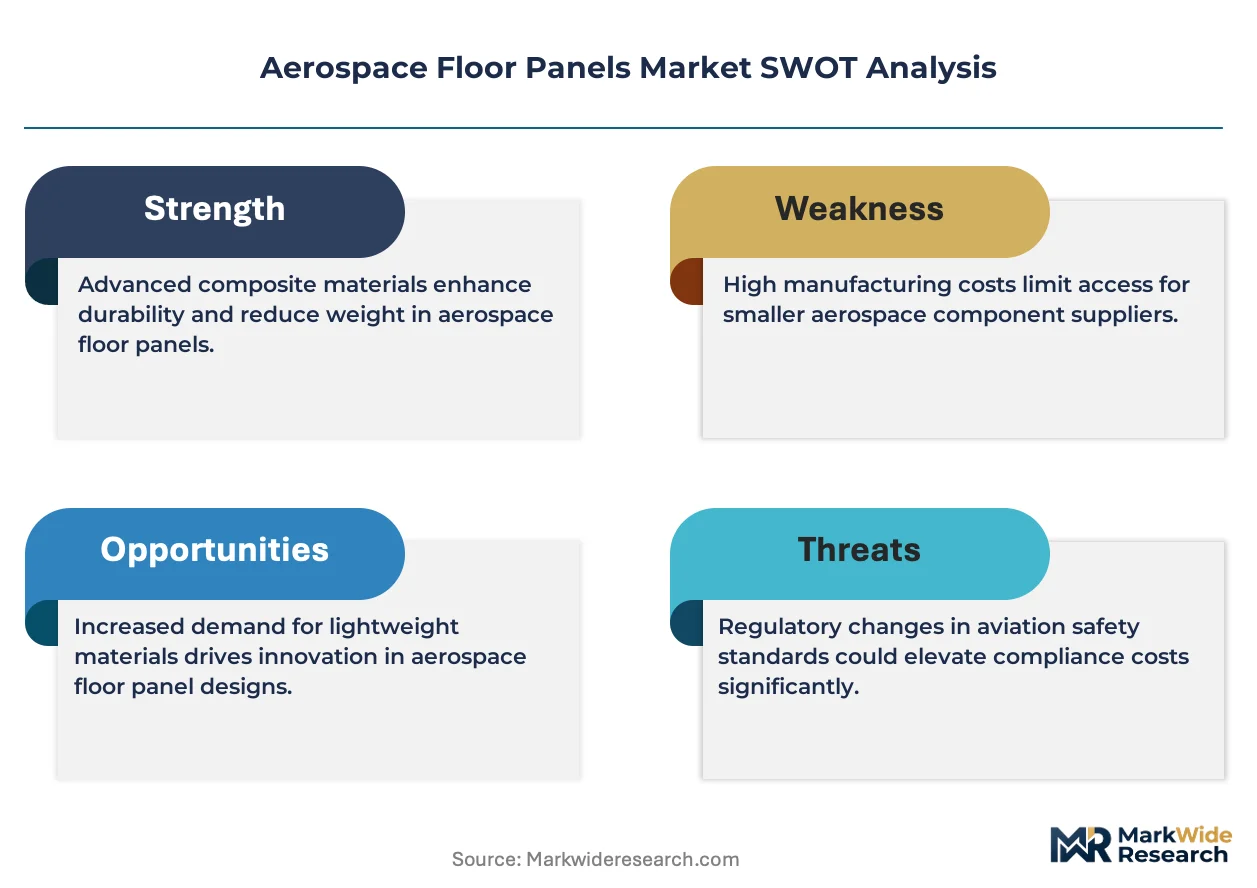
FAA and EASA fire-smoke-toxicity mandates are forcing material transitions across commercial aviation fleets, compressing qualification timelines for thermoplastic composites while elevating barriers for legacy phenolic constructions.
Growth Catalysts
- Narrow-body fleet renewal:Boeing and Airbus production rate increases at Renton and Toulouse are pulling composite floor panel volumes upward.
- EASA CS-25 certification pathways:Streamlined approval processes for thermoplastic honeycomb assemblies are accelerating OEM adoption timelines.
- Aramid fiber processing:Advances in automated core machining are reducing labor content and improving thickness consistency for sandwich panel production.
Market Restraints
- Prepreg resin cost volatility:Epoxy and BMI resin pricing fluctuations tied to petrochemical feedstocks compress margin predictability for tier-two fabricators.
- Single-source aramid dependency:Concentrated para-aramid fiber supply from DuPont and Teijin creates vulnerability for honeycomb core manufacturers.
- Phenolic legacy lock-in:Extensive repair station tooling and technician training for legacy floor panels slow composite substitution rates.
Strategic Opportunities
- Urban air mobility platforms:eVTOL manufacturers in Germany and China are specifying lightweight thermoplastic floor assemblies without legacy qualification baggage.
- FAA Sustainable Aviation Fuel compatibility:Floor panel weight reduction directly supports fuel efficiency mandates under the agency's climate roadmap.
- Repair station network expansion:Independent MRO facilities in Poland and Mexico represent underpenetrated channels for aftermarket composite panel retrofits.
Industry Challenges
- Adhesive bonding technician scarcity:Qualified personnel for autoclave and out-of-autoclave composite assembly remain concentrated at incumbent OEMs.
- Dual certification burden:Simultaneous FAA Part 25 and EASA CS-25 qualification campaigns strain engineering resources for mid-tier suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Floor Panels Market |
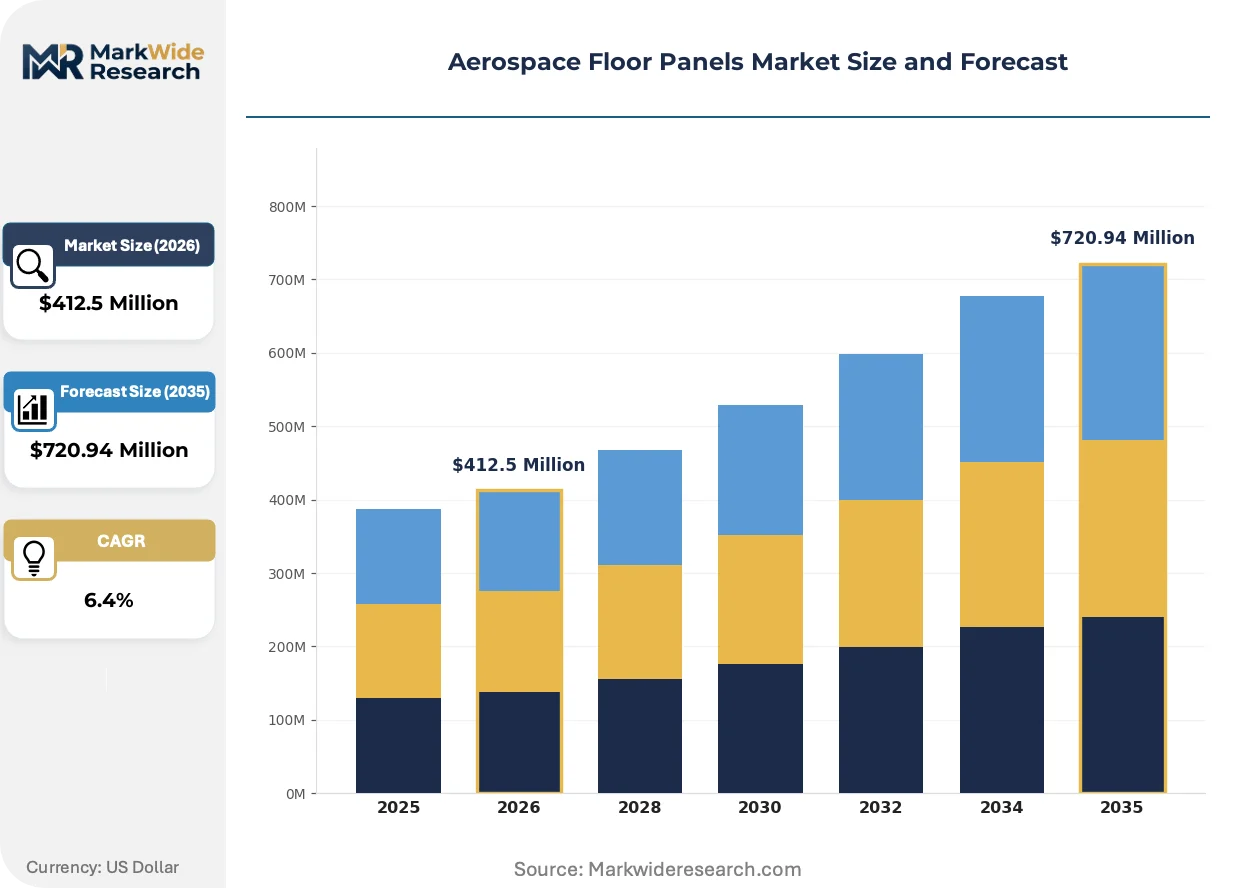
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Panels, Aluminum Panels, Honeycomb Panels, Phenolic Panels Application: Cabin Interiors, Cargo Areas, Cockpit, Lavatories End User: Commercial Aviation, Military Aviation, Rotorcraft, Spacecraft Installation Type: OEM, Retrofit, Aftermarket, Modification |
| Companies Covered | The NORDAM Group LLC, Euro-Composites, Collins Aerospace, Comtek Advanced Structures Ltd., Safran Cabin, Hexcel Corporation, Triumph Group Inc., AVIC Cabin Systems Limited, The Gill Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Floor Panels Market Emerging Trajectories
Thermoplastic resin systems are compressing manufacturing cycle times while regulatory agencies harden fire-performance thresholds, reshaping competitive advantage toward integrated material-process capabilities.
Thermoplastic polyetherketoneketone (PEKK) and polyphenylene sulfide (PPS) face sheets are replacing thermoset epoxies in next-generation floor assemblies. Narrow-body OEMs at Airbus and Boeing are qualifying these materials for high-traffic zones. PEKK is absorbing repair and maintenance volume from legacy phenolic panels by enabling fusion bonding and eliminating adhesive cure cycles.
EASA has tightened CS-25 Appendix F flammability testing protocols for heat-release and smoke-density metrics. European-based suppliers must now demonstrate compliance through full-scale cabin mock-up burn tests rather than bench-scale surrogates. Wide-body retrofit programs are absorbing the longest certification timelines as regulators scrutinize panel-to-panel joint configurations.
Airline procurement teams are consolidating vendor relationships around suppliers offering bundled floor-panel and sidewall-liner qualifications. Tier-one integrators are capturing specification authority previously held by raw material vendors. This concentration is most visible at US legacy carriers running unified interiors programs across narrow-body and wide-body subfleets.
Aerospace Floor Panels Market Segmentation
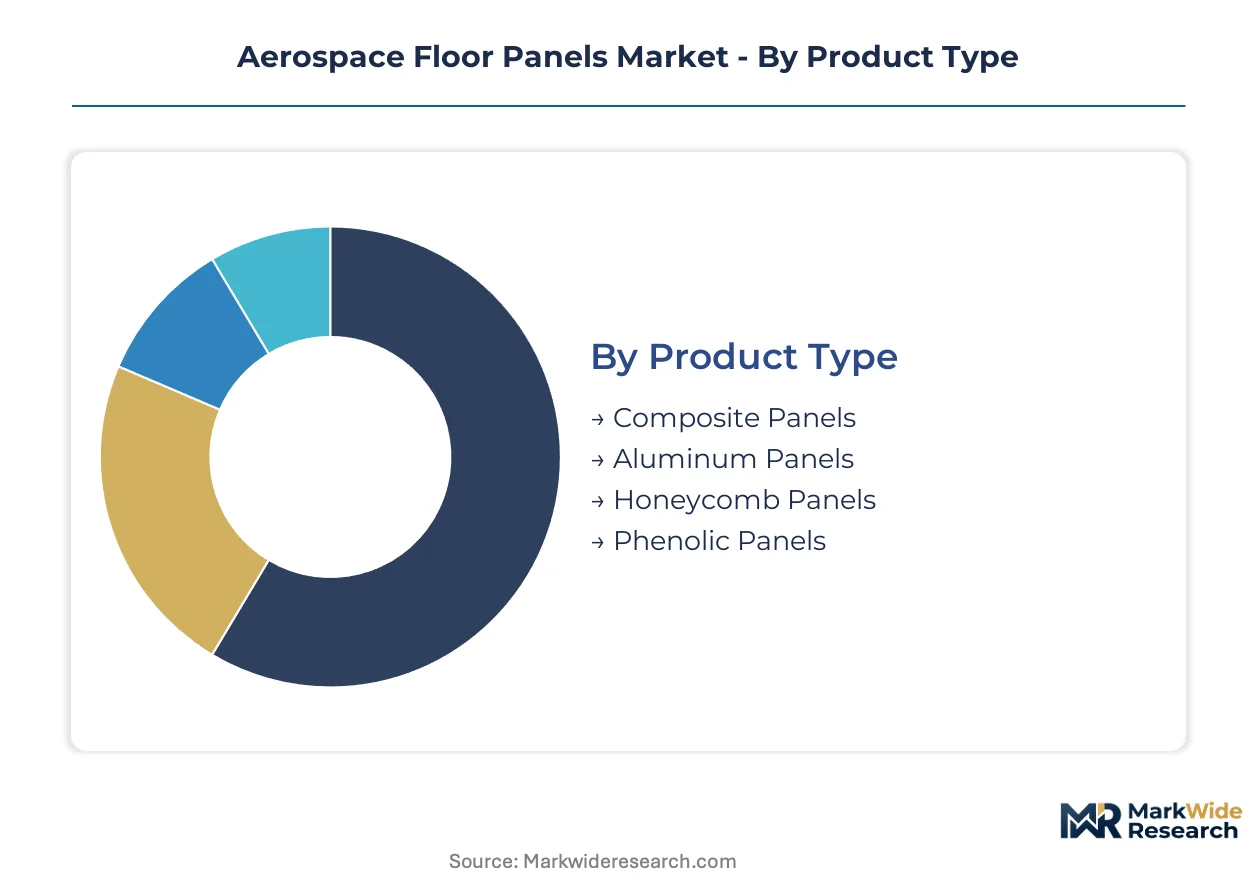
Aerospace floor panel segmentation reflects the tension between legacy qualification heritage and next-generation material transitions. Each axis—product chemistry, cabin zone, operator type, and installation channel—carries distinct certification burdens and margin profiles that reshape supplier positioning.
Product Type:
Material selection hinges on the trade-off between fire-performance certification depth and manufacturing cycle compression.
- Honeycomb Panels:Aluminum or aramid honeycomb cores bonded to carbon fiber or glass-reinforced face sheets deliver the strength-to-weight ratios FAA Part 25 mandates for passenger load distribution. Narrow-body OEM production at Renton and Toulouse pulls the majority of current volume. Mature deployment sits with Honeycomb Panels.
- Composite Panels: Thermoplastic PEKK and PPS face sheets enable fusion bonding and eliminate autoclave cure cycles, compressing lead times for high-traffic cabin zones. eVTOL manufacturers in Germany and China specify these assemblies without legacy phenolic tooling constraints. Newer deployment is concentrated in Composite Panels.
- Aluminum Panels: Solid aluminum constructions persist in freighter conversions and legacy wide-body retrofits where impact resistance outweighs weight penalties.
- Phenolic Panels: Thermoset phenolic resins retain installed base dominance in lavatory and galley subfloors due to extensive repair station technician training and tooling amortization.
Procurement is shifting toward thermoplastic qualifications as EASA CS-25 Appendix F testing protocols harden.
Application:
Cabin zone segmentation maps directly to traffic intensity, fire exposure risk, and passenger visibility—each variable altering material specification authority.
- Cabin Interiors:Passenger deck flooring absorbs the highest certification scrutiny for heat-release and smoke-density metrics under FAA Part 25.853. Airbus A320neo and Boeing 737 MAX production lines in Toulouse and Renton specify thermoplastic honeycomb assemblies for main deck zones. Mature deployment sits with Cabin Interiors.
- Cargo Areas: Lower deck cargo floors prioritize puncture resistance and concentrated load distribution over aesthetic finish, favoring aluminum-core constructions for freighter operators. Newer deployment is concentrated in Cargo Areas.
- Cockpit: Flight deck flooring integrates electromagnetic shielding layers and anti-fatigue surfacing for crew stations, with specialized qualification pathways distinct from passenger cabin protocols.
- Lavatories: Wet-area subfloors demand enhanced moisture barrier integration and drain pan compatibility, locking in phenolic panel specifications due to repair familiarity.
Specification authority for Cabin Interiors is consolidating at tier-one integrators bundling floor and sidewall qualifications.
End User:
Operator category determines the balance between production volume scale and technical performance specialization.
- Commercial Aviation:Narrow-body and wide-body fleet operators at US legacy carriers and Chinese state airlines drive composite panel volume through unified interiors programs. Mature deployment sits with Commercial Aviation.
- Military Aviation: Defense programs prioritize signature management, ballistic protection, and rapid field repairability in floor structures, with distinct MIL-STD qualification pathways. Newer deployment is concentrated in Military Aviation.
- Rotorcraft: Helicopter cabin floors emphasize vibration damping and crashworthiness under dynamic loading conditions, with lighter qualification burdens than fixed-wing transport category aircraft.
- Spacecraft: Crew and cargo module flooring for orbital platforms demands ultra-low outgassing materials and micrometeorite shielding integration, representing a nascent specification channel.
Commercial Aviation commands specification volume while Military Aviation deepens technical requirements for survivability.
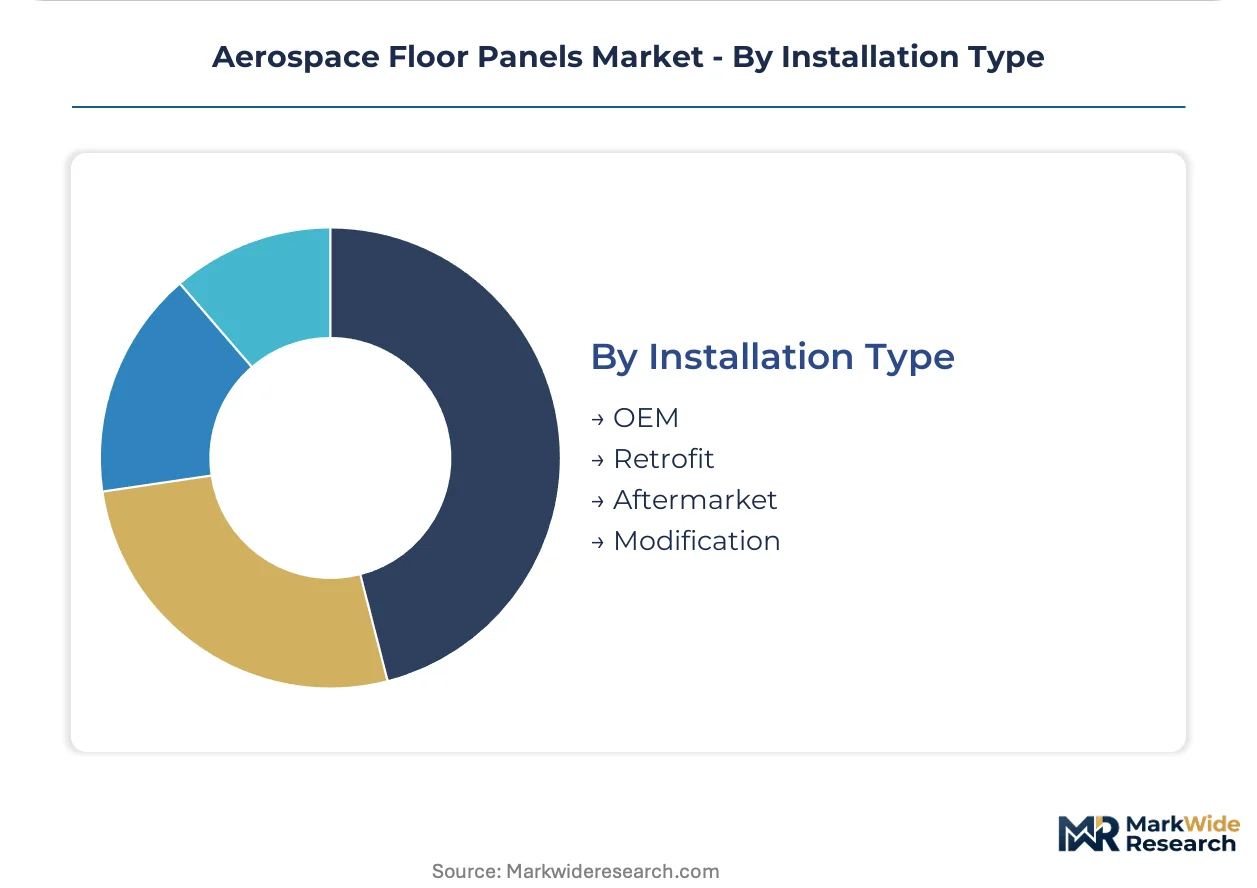
Installation Type:
Channel segmentation separates production-line pull from aftermarket retrofit economics and regulatory modification mandates.
- OEM:Original equipment installation at Airbus, Boeing, and COMAC final assembly lines locks in multi-year qualification relationships and design authority for tier-one suppliers. Mature deployment sits with OEM.
- Retrofit: Wide-body cabin reconfiguration programs at Delta, United, and Lufthansa drive composite panel substitution for legacy phenolic flooring during heavy maintenance checks. Newer deployment is concentrated in Retrofit.
- Aftermarket: Independent MRO facilities in Poland and Mexico represent underpenetrated channels for spare panel distribution and damage replacement outside OEM service networks.
- Modification: STC-driven conversions—freighter bed installations, VIP cabin reconfigurations, and medical evacuation layouts—require case-by-case engineering approval and fragmented supplier relationships.
OEM channels concentrate design authority while Retrofit and Aftermarket expansion depends on repair technician training network buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Para-aramid fiber production clusters in the United States, Germany, and China anchor aerospace floor panel supply chains. Final assembly line concentration in these three countries pulls composite honeycomb demand. Regulatory divergence between FAA and EASA certification pathways fragments procurement strategies across Atlantic supply networks.
United States
Boeing's 737 MAX and 777X production at Renton and Everett drives narrow-body and wide-body floor panel volume. FAA Part 25.853 flammability standards mandate heat-release testing for all new cabin interior materials. The Pacific Northwest aerospace corridor from Seattle to Portland concentrates tier-one integrators and honeycomb core fabricators serving OEM installation channels.
Germany
Airbus A320neo and A350 final assembly at Hamburg and Toulouse (with German supply integration) pulls thermoplastic composite demand. EASA CS-25 Appendix F protocols now require full-scale cabin mock-up burn tests rather than bench-scale surrogates. The Hamburg aerospace cluster hosts specialized thermoset processing capabilities for next-generation floor assemblies.
China
COMAC C919 production ramp-up at Shanghai Pudong and ARJ21 regional jet manufacturing in Nanchang expands domestic floor panel specification. CAAC harmonization with FAA certification standards accelerates local supplier qualification timelines. The Yangtze River Delta aerospace manufacturing zone concentrates composite panel fabricators serving indigenous and foreign OEM programs.
France
Airbus headquarters and A350 final assembly at Toulouse-Blagnac anchors European wide-body floor panel demand. EASA design organization approval requirements elevate barriers for non-EU suppliers seeking direct OEM relationships. The Occitanie region's aerospace supply chain integrates Spanish and Italian composite component flows for cross-border floor assembly production.
United Kingdom
Rolls-Royce engine nacelle programs and BAE Systems military platforms sustain specialized floor panel demand for defense applications. UK Civil Aviation Authority post-Brexit certification autonomy creates parallel qualification pathways distinct from EASA mutual recognition. The South West England aerospace cluster around Bristol and Yeovil maintains legacy phenolic panel repair capabilities for military retrofit channels.
Aerospace Floor Panels Market Vendor Landscape
Strategic partnerships dominate the current landscape as tier-one integrators consolidate specification authority. The vendor base organizes around three tiers: global aerostructures conglomerates with integrated interiors portfolios, specialized honeycomb core manufacturers with material science depth, and regional fabricators serving aftermarket retrofit channels. Two archetypes define competitive positioning: qualification-heavy incumbents leveraging decades-long OEM relationships, and technology-forward specialists compressing thermoplastic certification timelines. M&A activity and geographic expansion represent the dominant competitive moves as suppliers seek EASA and FAA dual certification capabilities.
Among North American-based suppliers, Collins Aerospace and Hexcel Corporation exemplify contrasting strategic positions. Collins Aerospace occupies the integrated systems tier through its combined interiors and structures capabilities. Hexcel Corporation anchors the material science tier as a prepreg and honeycomb core specialist. Euro-Composites represents the European regional specialist archetype, differentiated by proximity to Airbus final assembly lines and EASA-centric qualification heritage. These three entities illustrate how geographic positioning and certification focus determine specification access across Atlantic supply networks.
| Leading Market Players |
|---|
| The NORDAM Group LLC |
| Euro-Composites |
| Collins Aerospace |
| Comtek Advanced Structures Ltd. |
| Safran Cabin |
| Hexcel Corporation |
| Triumph Group Inc. |
| AVIC Cabin Systems Limited |
| The Gill Corporation |
| Others |
Supply Flow & Price Mechanics
Prepreg resin cost volatility traces a direct path from petrochemical feedstock fluctuations through tier-two fabricator margin compression to tier-one OEM pricing negotiations. Aramid fiber pricing from DuPont and Teijin concentrates upstream cost leverage, translating into differentiated procurement tiers for honeycomb core manufacturers.
Pricing Analysis
Warranty-bundled qualification support commands premium positioning for tier-one integrators, while unbundled material-only supply competes on resin cost pass-through. Pricing stratifies across FAA-EASA dual-certified, single-certified, and uncertified material tiers. Cost compression in standard-grade phenolic replacements is intensifying as airlines consolidate vendor relationships. Regional MRO facilities in Poland and Mexico exhibit highest price sensitivity due to limited volume scale and fragmented procurement authority.
Supply Chain Analysis
Direct-to-OEM channels handle Airbus, Boeing, and COMAC final assembly line demand, while aftermarket distribution feeds independent MRO networks. Supply concentrates in the United States, Germany, and China where para-aramid fiber production and final assembly lines co-locate. Raw material dependencies span epoxy and BMI resins, aluminum and aramid honeycomb cores, and carbon fiber prepreg. Single-source vulnerability from concentrated para-aramid supply creates structural exposure for honeycomb manufacturers. Distribution runs through tier-one integrators holding design authority and long-term qualification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around qualification-heavy incumbents as EASA CS-25 Appendix F testing protocol hardening forces weaker players out through unsustainable certification investment burdens.
For Market Incumbents: Lock in multi-year OEM relationships at Airbus and Boeing through bundled floor-panel and sidewall-liner qualifications. Secure backward integration into aramid honeycomb core production to neutralize DuPont and Teijin supply concentration risk. Reinforce design authority by accelerating thermoplastic PEKK and PPS certification timelines ahead of regulatory mandates. For New Entrants and Emerging Players: Begin with urban air mobility eVTOL manufacturers in Germany and China specifying lightweight thermoplastic assemblies without legacy phenolic tooling constraints. Target aftermarket retrofit channels at independent MRO facilities in Poland and Mexico where OEM service network penetration remains limited. Pursue fusion-bonding technician training partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor European-based thermoset specialists with EASA design organization approval and proximity to Airbus final assembly. Long-term viability hinges on dual FAA-EASA certification capabilities and thermoplastic resin system integration. Monitor EASA full-scale cabin mock-up burn test approval timelines as the critical inflection signal for material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Qualification Investment | PEKK and PPS certification at Airbus and Boeing compresses manufacturing cycle times against legacy epoxy systems. |
| Aramid Core Backward Integration | In-house honeycomb production neutralizes DuPont and Teijin supply concentration for tier-one integrators. |
| EASA Design Organization Approval | European regulatory credentialing unlocks direct OEM relationships and specification authority at Airbus. |
| Aftermarket MRO Network Expansion | Repair technician training buildout in Poland and Mexico captures retrofit volume outside OEM service channels. |
| Urban Air Mobility Partnership | eVTOL platform specifications in Germany and China bypass legacy phenolic qualification barriers for new entrants. |
Methodological Framework
Independent corroboration across tier-one aerostructures procurement directors, EASA certification engineers, and composite materials R&D leads underwrites the qualitative findings. Primary fieldwork incorporated structured interviews with OEM interior specification teams, honeycomb core manufacturing plant managers, and aftermarket MRO facility operators. Secondary validation drew from FAA Part 25.853 regulatory filings, EASA CS-25 certification databases, and SEC 10-K disclosures from publicly traded composite suppliers. Bottom-up segment sizing triangulated against top-down fleet renewal projections across narrow-body and wide-body production lines.
Comparable historical periods anchored volume and value projections across the analysis window, with CAGR derivation reflecting segment-specific qualification timelines and material substitution elasticities. Modeled dimensions encompassed product chemistry, cabin zone application, operator category, and installation channel, with thermoplastic certification velocity and fire-performance testing protocol evolution serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; OEM installation channels carry tighter precision than fragmented aftermarket retrofit due to visible production rate disclosures. Forecasts reflect assumptions regarding EASA-FAA regulatory harmonization pace and sustainable aviation mandate introduction timing. Periodic stress-testing of base assumptions is recommended against actual thermoplastic qualification completion rates and airline interiors program consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aircraft Galley Market
Aircraft Cabin Interior
Latin America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Aircraft Galley Inserts Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market