
 Aircraft Cargo Winches Market | 2026-2036
Aircraft Cargo Winches Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cargo Winches Market Analysis
Electrification of ground support equipment is rewriting design priorities for aircraft cargo winch manufacturers. Collins Aerospace leverages its integrated systems portfolio to anchor positions in fixed-installation military platforms. Breeze-Eastern LLC specializes in helicopter cargo hook and winch assemblies, sustaining decades of rotorcraft expertise. Ancra International LLC competes across commercial airline retrofit programs with broad product lines.
Aircraft cargo winches are motorized or manually operated mechanical devices designed to load, unload, and reposition cargo within aircraft holds, typically rated for loads from hundreds to several thousand pounds and constructed from high-strength steel alloys with corrosion-resistant finishes. Electric winches lead product type demand due to quieter operation and reduced ground support equipment emissions compliance, while hydraulic variants retain share in heavy-lift military applications where power density requirements exceed electric motor capabilities. Automated control mechanisms represent the fastest-growing segment as logistics companies and MRO providers invest in reduced-manning cargo handling operations, though manual control systems still dominate installed base economics in emerging aviation markets.
FAA airworthiness standards under Part 25 and Part 27 shape design validation requirements for transport category and rotorcraft cargo winch installations, while EASA CS-25 certification demands parallel compliance for European-registered operators. Military procurement through NAVAIR and Air Force Life Cycle Management Center imposes additional environmental and electromagnetic interference testing that filters supplier eligibility. Stakeholders must monitor evolving EPA ground support equipment emissions thresholds and defense budget authorization trajectories for strategic airlift modernization programs.
Market Dynamics
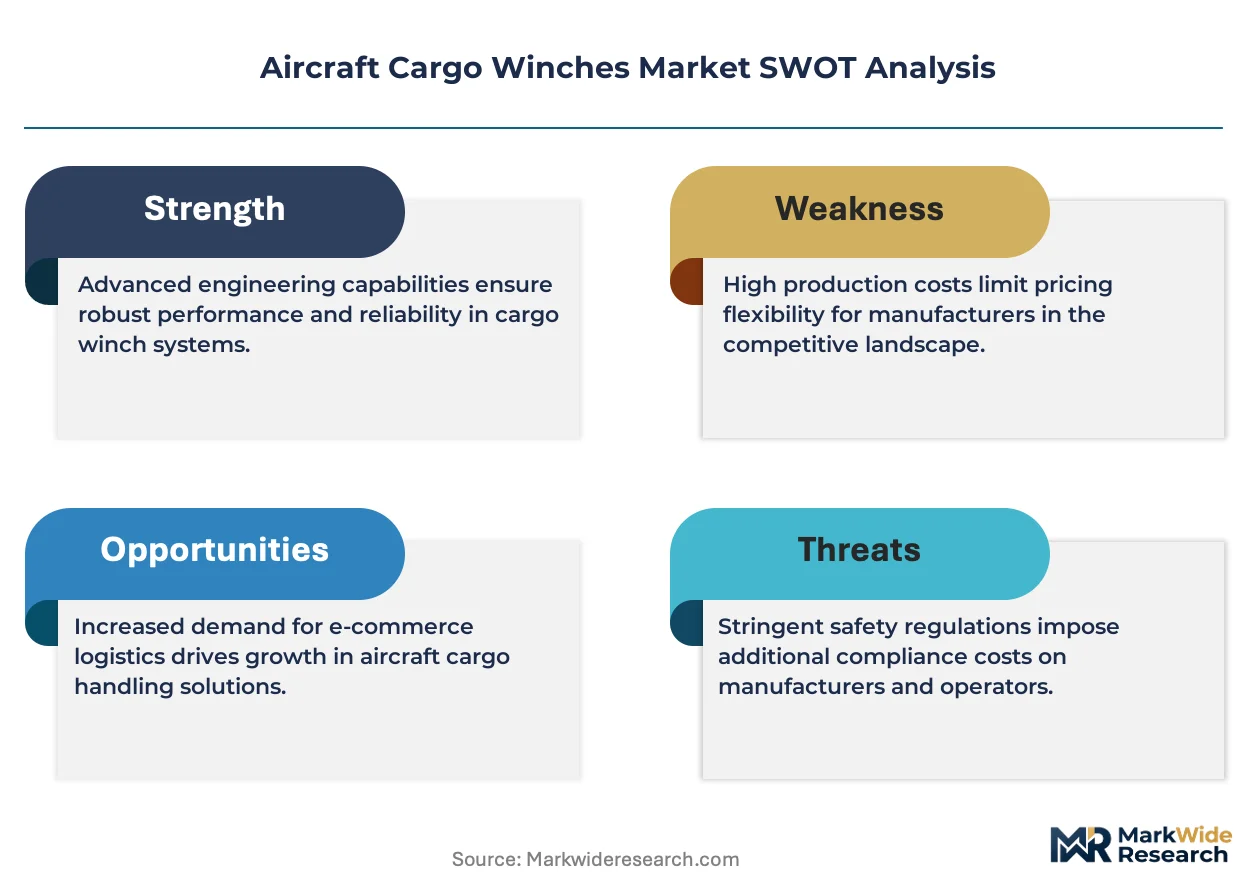
Electrification mandates for ground support equipment are compressing development cycles for aircraft cargo winch manufacturers, forcing simultaneous compliance with EPA emissions thresholds and military electromagnetic interference standards.
Growth Catalysts
- FAA Part 25 Certification:Transport category aircraft retrofits require updated cargo restraint systems, sustaining replacement demand across aging commercial fleets.
- Defense Airlift Modernization:NAVAIR procurement programs for integrated cargo handling systems anchor multi-year supplier contracts.
- Electric Motor Technology:Brushless DC architectures enable quieter operation and reduced maintenance intervals in commercial aviation ground operations.
Market Restraints
- High-Strength Steel Alloy Volatility:Aerospace-grade material costs fluctuate with nickel and chromium supply disruptions.
- Supplier Concentration:Critical hydraulic component sourcing clusters in German precision manufacturing regions.
- Power Density Limitations:Electric winch torque output falls short of heavy-lift military requirements above ten thousand pounds.
Strategic Opportunities
- India Defense Aviation:Indigenous transport aircraft programs create openings for localized cargo winch assembly partnerships.
- Automated Load Balancing:Sensor-integrated winch systems enable single-operator cargo handling in reduced-manning logistics environments.
- EU Green Deal Incentives:EASA emissions reduction frameworks subsidize electric ground support equipment retrofits at European hub airports.
Industry Challenges
- Electromechanical Systems Engineering:Shortage of specialists combining aerospace mechanical design with motor control firmware development.
- Dual Certification Timelines:Simultaneous FAA and EASA validation processes extend product launch schedules by eighteen to twenty-four months.
- Legacy Platform Integration:Retrofit compatibility with fifty-year-old military airframe architectures constrains design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cargo Winches Market |
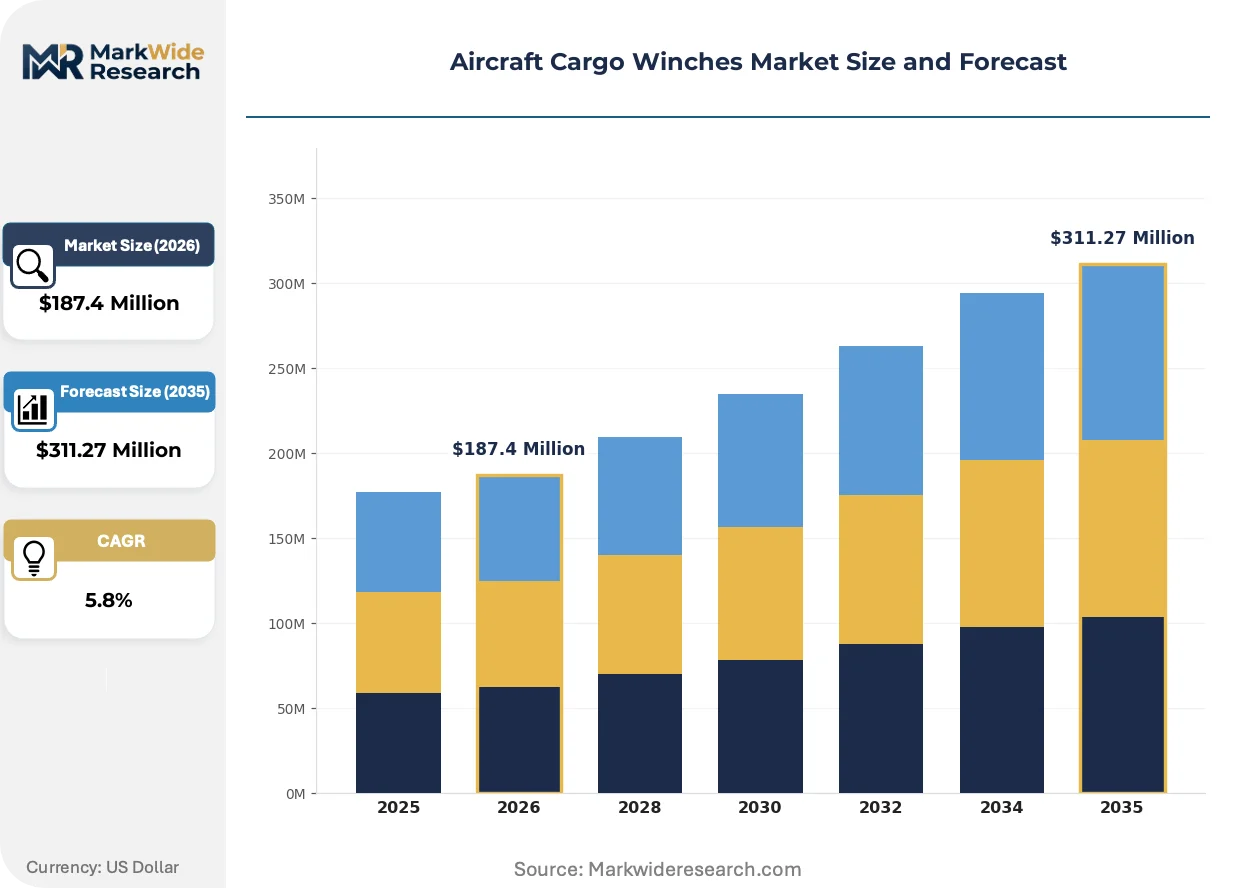
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Winches, Hydraulic Winches, Pneumatic Winches, Manual Winches End User: Airlines, Logistics Companies, Military, Maintenance, Repair, and Overhaul (MRO) Providers Installation Type: Fixed Installation, Portable Installation, Integrated Systems, Standalone Units Control Mechanism: Remote Controlled, Manual Control, Automated Systems, Hybrid Control |
| Companies Covered | Cargo Systems Inc., Ancra International LLC, AERO Specialties, Inc., Tronair, Inc., TLD Group, Breeze-Eastern LLC, Clyde Machines Inc., JBT Corporation, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cargo Winches Market Emerging Trajectories
Control architectures and material specifications are diverging between commercial and military procurement streams, creating parallel development tracks within supplier engineering departments.
Permanent magnet synchronous motor technology is migrating from industrial automation into aircraft cargo winch applications. Commercial MRO providers in the United States adopt these systems for reduced noise footprint at noise-sensitive airports. The shift is compressing demand for traditional brushed DC architectures in ground support equipment segments.
EPA ground support equipment emissions thresholds are tightening certification requirements for diesel-hydraulic auxiliary power units. Equipment lessors face stranded asset risk in California and New York markets where state-level rules exceed federal baselines. Electric winch suppliers capture retrofit contracts previously held by hydraulic system integrators.
Airline procurement departments consolidate vendor relationships under fleet-wide service agreements. Long-term performance-based contracts displace transactional spare parts purchasing for cargo handling equipment. This concentration is most visible among United States legacy carriers operating hub-and-spoke networks with standardized ground equipment fleets.
Aircraft Cargo Winches Market Segmentation
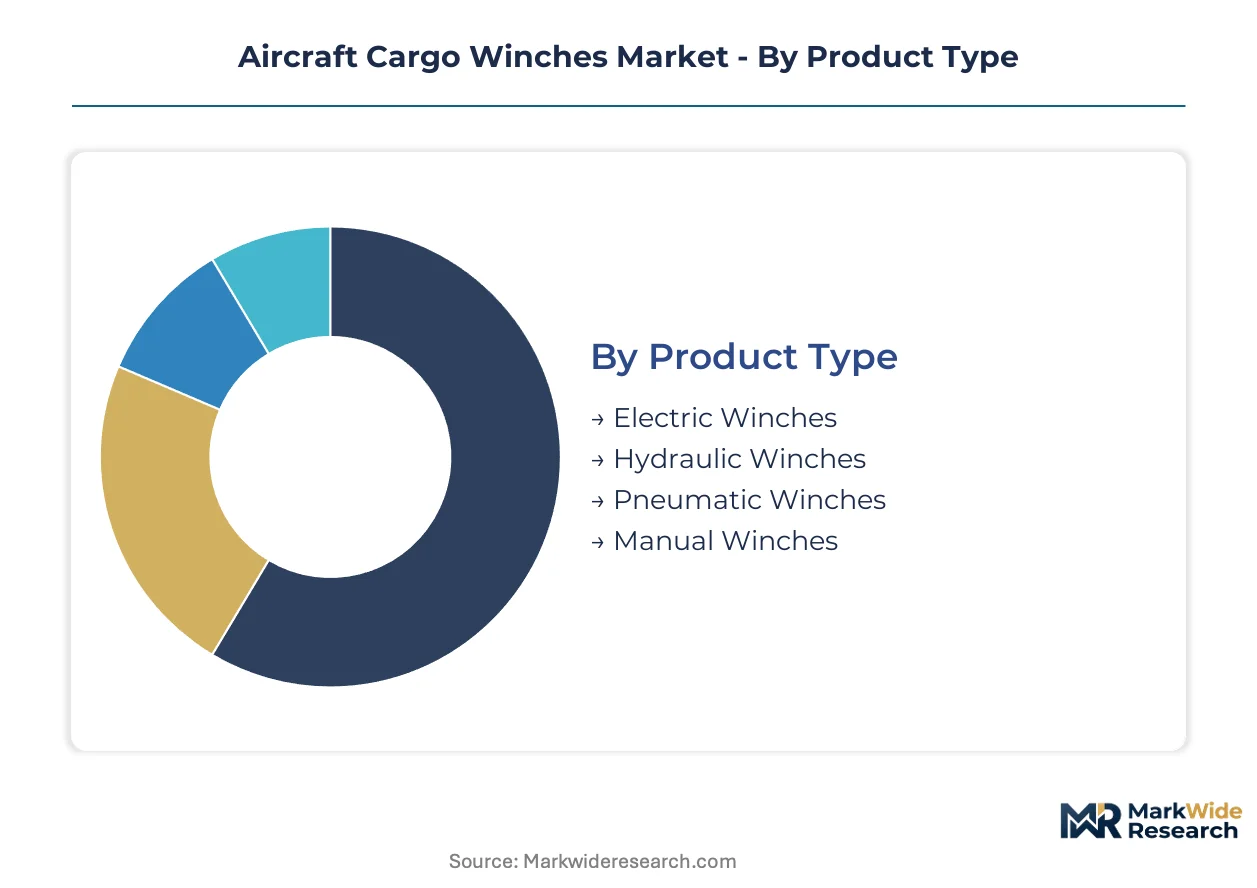
Cargo winch configurations diverge sharply between commercial ground operations and military airlift platforms, with electrification mandates and certification requirements driving procurement fragmentation across customer types. Understanding these segment boundaries clarifies where engineering investments concentrate and where retrofit opportunities emerge.
Product Type:
Cost tier differentiation separates premium electric architectures from legacy hydraulic systems, with capital intensity and operating economics dictating platform selection across defense and commercial fleets.
- Electric Winches:Brushless DC motor architectures deliver quieter operation and reduced maintenance intervals, aligning with EPA emissions thresholds at United States hub airports. Airlines operating noise-sensitive routes in California and New York prioritize these systems for ground support fleet renewals.
- Hydraulic Winches:High power-density fluid power systems sustain torque output above ten thousand pounds for heavy-lift military applications. NAVAIR procurement programs for C-130 and C-17 integrated cargo handling anchor multi-year supplier commitments despite higher baseline costs.
- Pneumatic Winches:Compressed-air drive systems serve niche applications in explosive-atmosphere cargo environments where spark suppression is mandatory.
- Manual Winches:Hand-crank mechanical devices retain installed base presence in emerging aviation markets with limited ground power infrastructure and constrained capital budgets.
Electric architectures command the established base. The steepest expansion runs through automated control integration.
End User:
Application context shapes specification priorities, with military electromagnetic interference standards and commercial turnaround-time metrics pulling designs in divergent directions.
- Airlines:Hub-and-spoke carriers consolidate vendor relationships under fleet-wide service agreements, standardizing ground equipment configurations across domestic station networks. United States legacy carriers drive demand for reduced-manning cargo handling to compress turnaround windows.
- Military:Air Force Life Cycle Management Center and NAVAIR impose environmental testing and electromagnetic compatibility validation that filters supplier eligibility. Strategic airlift modernization programs sustain procurement volume for integrated cargo handling systems.
- Logistics Companies:Third-party ground handlers at European hub airports leverage EU Green Deal incentives to accelerate electric ground support equipment adoption.
- Maintenance, Repair, and Overhaul (MRO) Providers:Independent repair stations across the United States sustain replacement demand for aging commercial fleet cargo restraint systems under FAA Part 25 retrofit mandates.
Military procurement anchors high-revenue contracts. The steepest expansion trajectory belongs to MRO retrofit programs.
Installation Type:
Supply concentration in precision manufacturing clusters shapes availability and lead times for integrated versus standalone configurations.
- Fixed Installation:Permanently mounted winch systems dominate military transport aircraft with dedicated cargo missions. Collins Aerospace leverages integrated systems portfolios to anchor positions in C-130 and C-17 platforms.
- Integrated Systems:Cargo handling suites combining winches, restraint rails, and load sensors command premium positioning in new-build military contracts.
- Portable Installation:Removable units serve mixed-use aircraft requiring rapid reconfiguration between passenger and cargo operations.
- Standalone Units:Self-contained ground support equipment addresses commercial apron operations with fleet flexibility requirements.
Fixed installations command the established base. The steepest expansion runs through integrated systems.
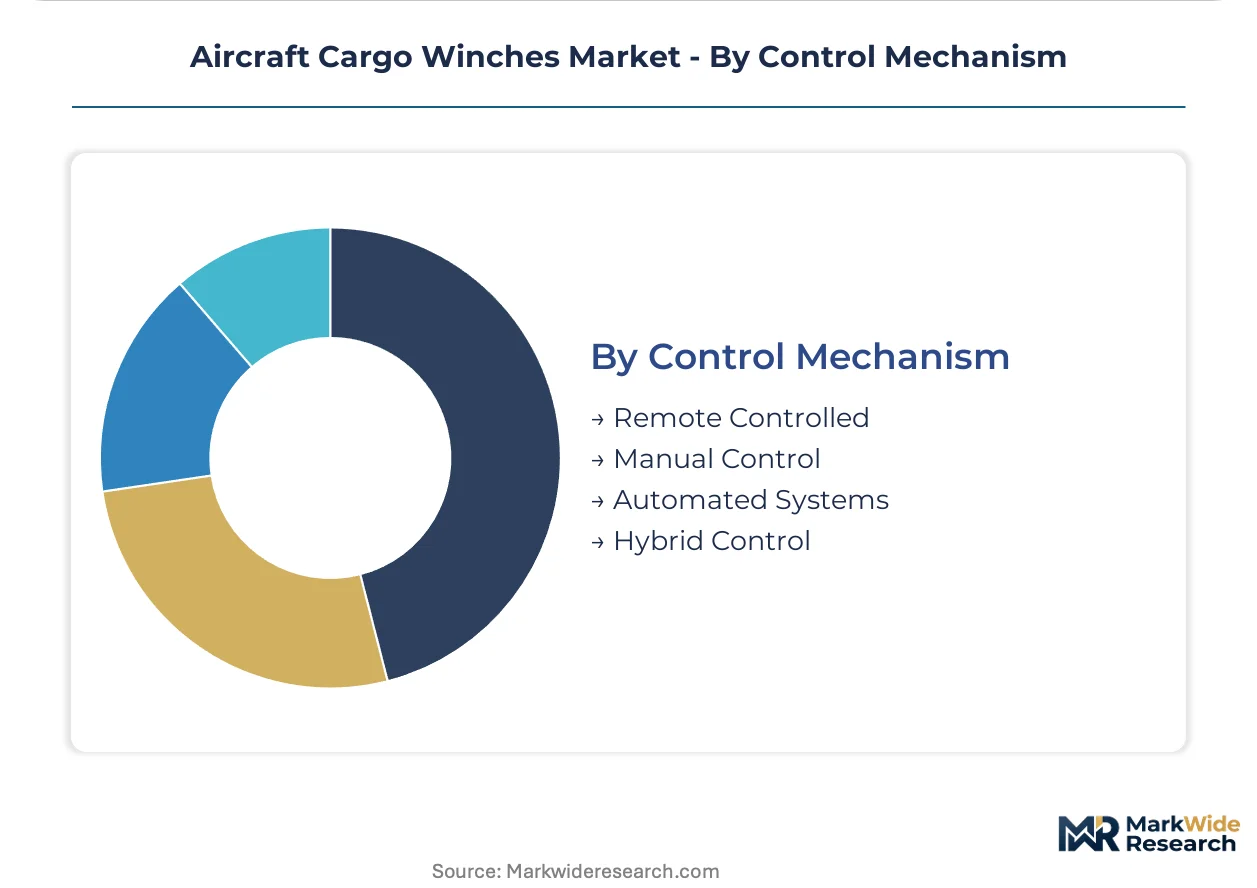
Control Mechanism:
Customer type and labor cost structure determine automation investment thresholds, with sensor integration enabling single-operator cargo handling.
- Automated Systems:Sensor-integrated winch architectures with load balancing algorithms reduce crew requirements in reduced-manning logistics environments. Logistics companies investing in warehouse automation extend similar efficiency targets to airside operations.
- Remote Controlled:Radio-frequency and tethered control systems improve operator positioning flexibility during irregular load handling.
- Manual Control:Direct mechanical operation persists in price-sensitive segments and legacy platform retrofits where electrical system upgrades are cost-prohibitive.
- Hybrid Control:Configurable architectures allowing automated sequencing with manual override capability bridge transition requirements for mixed fleet operators.
Manual control commands the established base. The steepest expansion runs through automated systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and commercial aviation maintenance clusters concentrate demand across distinct national markets, with regulatory frameworks and fleet modernization cycles shaping geographic purchasing patterns.
United States
NAVAIR and Air Force Life Cycle Management Center sustain multi-year procurement for C-130 and C-17 integrated cargo handling systems. FAA Part 25 certification mandates drive retrofit demand across aging commercial fleets. Seattle-Tacoma and Dallas-Fort Worth anchor defense and commercial aviation manufacturing clusters where MRO providers standardize ground equipment configurations.
Germany
Precise hydraulic component manufacturing sustains supplier positioning in heavy-lift military applications. EASA CS-25 certification requirements filter eligibility for European-registered operator retrofits. Hamburg and Munich house specialized engineering firms serving Airbus military transport programs and third-party ground handler fleets.
France
Strategic airlift modernization programs sustain integrated systems procurement for tactical transport aircraft. EU Green Deal subsidies accelerate electric ground support equipment adoption at Paris-Charles de Gaulle and Lyon-Saint Exupéry hubs. Toulouse aerospace cluster firms supply sensor-integrated winch architectures for reduced-manning cargo operations.
United Kingdom
Royal Air Force procurement through Defence Equipment and Support anchors demand for fixed-installation military platforms. EASA parallel compliance requirements extend product validation timelines for dual-certification strategies. Bristol and Broughton manufacturing centers concentrate rotorcraft cargo hook and winch assembly expertise.
India
Indigenous transport aircraft development programs create openings for localized cargo winch assembly partnerships. Directorate General of Civil Aviation airworthiness directives tighten material testing standards for commercial retrofit imports. Bangalore and Hyderabad defense aviation clusters attract joint ventures targeting domestic procurement preferences.
Aircraft Cargo Winches Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement streams, with military integrated systems contracts consolidating around aerospace conglomerates while commercial ground support equipment sustains mid-scale fabrication specialists. The vendor base separates into three strategic archetypes: defense-anchored systems integrators, commercial MRO-focused retrofit suppliers, and helicopter-specialized hook and winch assemblers. Competitive moves concentrate on strategic partnerships for certification acceleration and portfolio diversification into adjacent ground support equipment categories.
Among defense-anchored systems integrators, Collins Aerospace exemplifies the integrated portfolio approach, while Breeze-Eastern LLC occupies a position within helicopter-specialized assemblies. Ancra International LLC represents the commercial retrofit supplier archetype serving airline fleet standardization programs.
| Leading Market Players |
|---|
| Cargo Systems Inc. |
| Ancra International LLC |
| AERO Specialties, Inc. |
| Tronair, Inc. |
| TLD Group |
| Breeze-Eastern LLC |
| Clyde Machines Inc. |
| JBT Corporation |
| Collins Aerospace |
| Others |
Supply Flow & Price Mechanics
German precision hydraulic component manufacturing clusters anchor upstream supply for heavy-lift military winch systems, concentrating margin capture in specialized fluid power engineering while downstream commercial electric winch assemblers face commoditization pressure from brushless DC motor standardization.
Pricing Analysis
Cost-plus contracts with nickel and chromium price indexation dominate military procurement through NAVAIR and Air Force Life Cycle Management Center. Three-tier pricing structure across integrated systems, standalone units, and portable configurations separates premium electromagnetic interference-tested military platforms from standard commercial ground support equipment. Cost compression in electric motor tiers is intensifying because EPA emissions thresholds accelerate fleet replacement cycles. Logistics companies and third-party ground handlers exhibit highest price sensitivity, while defense integrators prioritize performance guarantees over unit economics.
Supply Chain Analysis
High-strength steel alloy feedstock draws from German precision forging operations, Chinese nickel processing facilities, and United States specialty steel mills. Aerospace-grade chromium plating, permanent magnet synchronous motors, and corrosion-resistant hydraulic seals constitute critical component dependencies. Single-source vulnerability concentrates in German precision hydraulic valve manufacturing. Distribution runs through OEM-direct military contracting and commercial aviation ground equipment lessors with fleet standardization mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting toward integrated cargo handling ecosystems, as sensor-integrated winch architectures demand interoperability with airline fleet management systems and military mission planning software.
For Market Incumbents: Entrench positions through captive supply of brushless DC motor controllers and accelerated FAA-EASA dual certification pipelines. Electromagnetic interference testing bottlenecks threaten supplier eligibility for NAVAIR programs. Vertical integration into permanent magnet sourcing secures margin pools as rare earth price volatility intensifies. For New Entrants and Emerging Players: Build out automated load balancing capabilities targeting MRO retrofit programs for aging commercial fleets under FAA Part 25 mandates. India indigenous transport aircraft programs offer the most penetrable geographic entry point. Partner with domestic defense aviation clusters in Bangalore and Hyderabad to satisfy Directorate General of Civil Aviation localization preferences. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-integrated winch architectures as firmware development costs displace mechanical engineering spend. Five-to-ten year viability favors suppliers with dual-use commercial-military certification portfolios. Acquisition target archetype: mid-scale electric ground support equipment fabricators with EPA compliance-ready product lines. Monitor defense budget authorization trajectories for strategic airlift modernization programs as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Acceleration | Simultaneous FAA Part 25 and EASA CS-25 validation compresses product launch schedules for integrated cargo handling systems. |
| Permanent Magnet Supply Integration | Backward integration into rare earth sourcing hedges brushless DC motor cost volatility for commercial electric winch production. |
| Sensor-Integrated Platform Development | Load balancing algorithms enable single-operator cargo handling at United States legacy carrier hub-and-spoke networks. |
| Localized Assembly Partnership | Joint ventures in India defense aviation clusters satisfy domestic procurement preferences for indigenous transport aircraft programs. |
| Fleet-Wide Service Agreement | Performance-based contracts displace transactional spare parts purchasing among United States hub-and-spoke carriers. |
Methodological Framework
A spread of perspectives from NAVAIR procurement officers, commercial airline ground equipment managers, MRO technical directors, and hydraulic component engineering leads converged on the working assumptions. Primary fieldwork combined structured interviews with FAA certification specialists and EASA compliance auditors. Secondary validation drew from NAVAIR contract announcements, FAA airworthiness directive filings, EASA CS-25 certification databases, and defense budget authorization documents. Bottom-up unit economics for electric and hydraulic winch configurations were triangulated against top-down fleet replacement projections.
Demand-supply balance modeling across the projection horizon segmented procurement by product type, end user, installation configuration, and control mechanism. Military electromagnetic interference standards and commercial EPA emissions thresholds provided industry-specific forecast inputs. CAGRs were derived from segment-level replacement cycle analysis and new-build program visibility.
Stress conditions across nickel-chromium alloy price volatility, defense authorization delays, and dual certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet modernization pacing and regulatory threshold evolution. Cross-checking against NAVAIR procurement pipeline disclosures and airline capital expenditure guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Fadec Market
Aircraft
Australia Aviation Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Air Deflector Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
Light Electric Aircraft Market
Aircraft
Light and Very Light Jets Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Asia-Pacific Attack Helicopter Market
Aircraft
Utility Aircraft Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
Tilt Rotor Aircraft Market