
 3D Printing Robots Market | 2026-2036
3D Printing Robots Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Robots Market Outlook
Aftermarket service revenue is reshaping margin capture across the 3D printing robots sector. Kuka AG leverages its established automotive robotics footprint to anchor large-format deposition services in European aerospace clusters. ABB Group sustains competitive positioning through integrated force-control software that enables real-time path correction during multi-axis printing. FANUC Corporation dominates high-volume FDM cell deployments with its proprietary servo architecture optimized for continuous extrusion duty cycles.
3D printing robots combine articulated or Cartesian kinematic platforms with deposition heads that extrude thermoplastic or photopolymer feedstock at temperatures ranging from 180°C to 300°C, producing near-net-shape components without dedicated tooling. Industrial robots command the largest installed base due to payload capacity exceeding 200 kg for metal-composite hybrid structures, while collaborative robots represent the fastest-expanding category as force-limited designs enable unguarded human-robot interaction in prototyping environments. SLA technology retains premium positioning in dental and medical applications where layer resolution below 50 microns determines functional outcomes.
CE marking under the EU Machinery Directive and FDA 21 CFR Part 820 quality system requirements shape product certification pathways for cross-border equipment sales. China's SAMR enforces GB standards for robotic safety that manufacturers must satisfy for domestic market access. Stakeholders must monitor divergence between regional conformity assessment frameworks as modular platform architectures complicate single-design global deployment strategies.
Market Dynamics
CE marking under the EU Machinery Directive and FDA 21 CFR Part 820 quality system requirements are forcing equipment manufacturers to rearchitect control systems for dual-jurisdiction compliance, compressing product development cycles and raising certification costs.
Growth Catalysts
- EU Machinery Directive CE marking:Aerospace clusters in Germany and France require robotic additive manufacturing cells for large-format structural components, accelerating capital deployment in certified systems.
- MIIT-backed smart manufacturing initiatives:China's industrial automation corridors drive localized procurement of deposition platforms with force-limited collaborative designs.
- Photopolymer feedstock advances:SLA technology with sub-50-micron layer resolution enables functional outcomes in dental and medical applications, expanding addressable procedure volumes.
Market Restraints
- High-purity metal powder costs:Titanium and nickel superalloy feedstock price volatility constrains metal-composite hybrid structure economics for aerospace tier-two suppliers.
- Regional certification divergence:China's SAMR GB standards for robotic safety create friction against EU Machinery Directive architectures, complicating single-design global deployment.
- Conventional CNC machining substitution:Five-axis milling retains cost advantages for production runs exceeding 10,000 units, limiting robot deposition to low-to-mid volume brackets.
Strategic Opportunities
- Underpenetrated Brazilian aerospace supply chain:ANVISA regulatory alignment with FDA pathways creates near-term equipment qualification routes for deposition cell exporters.
- Real-time path correction software:Integration of force-control algorithms with multi-axis printing platforms enables unguarded human-robot interaction in prototyping environments.
- Japan's METI carbon-neutral manufacturing roadmap:Government incentives for localized production of large-format structural components accelerate adoption of thermoplastic deposition systems.
Industry Challenges
- Multi-axis programming talent scarcity:Shortage of technicians proficient in simultaneous six-axis path generation and thermal management slows cell commissioning timelines.
- Legacy MES integration complexity:Proprietary robot controller architectures resist seamless data exchange with existing shop-floor execution systems, requiring custom middleware development.
- Medical device PMA timeline compression:FDA 510(k) clearance pathways for patient-specific implants demand extensive mechanical testing documentation, extending time-to-revenue for deposition platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Robots Market |
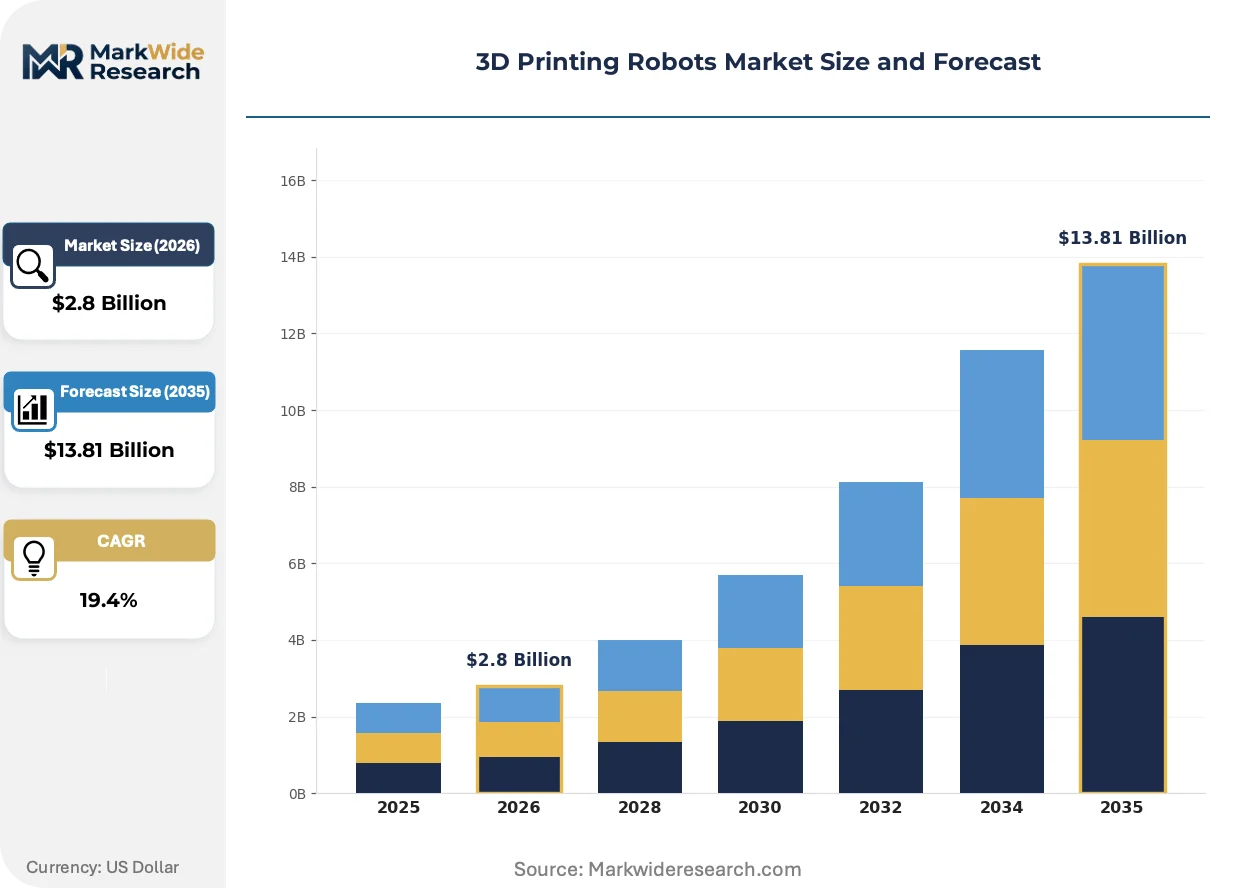
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13.81 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Robots, Collaborative Robots, Scara Robots, Delta Robots Material Type: PLA, ABS, Nylon, TPU Technology: FDM, SLS, SLA, DLP Application: Manufacturing, Prototyping, Education, Healthcare |
| Companies Covered | Kuka AG, ABB Group, Yaskawa Electric Corporation, FANUC Corporation, Universal Robots A/S, Massive Dimension, CEAD B.V., Caracol, Comau S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Robots Market Strategic Shifts
Deposition platform architectures are fragmenting along application-specific performance requirements, with force-limited collaborative designs gaining share in prototyping while heavy-payload articulated systems anchor aerospace production.
Thermoplastic composite deposition with continuous carbon fiber reinforcement is hybridizing traditional FDM extrusion with automated fiber placement techniques. Automotive tier-one suppliers in Germany and the United States are piloting these systems for structural battery enclosures and seat frames. The convergence is compressing the tooling-to-part cycle from weeks to hours for low-volume production runs.
REACH substance restrictions on certain photoinitiator chemistries are forcing reformulation of dental-grade resins used in SLA printing platforms. European dental laboratories face supply chain requalification costs exceeding six figures per resin platform. Manufacturers are accelerating bio-based alternative development to preempt regulatory displacement.
Aftermarket service unbundling is displacing bundled maintenance contracts in high-volume FDM cell deployments. Fleet operators in China's Yangtze River Delta now procure deposition head refurbishment, motion controller calibration, and software updates through separate vendor relationships. This fragmentation is compressing service margins for original equipment suppliers while creating openings for specialized third-party technicians.
3D Printing Robots Market Segmentation
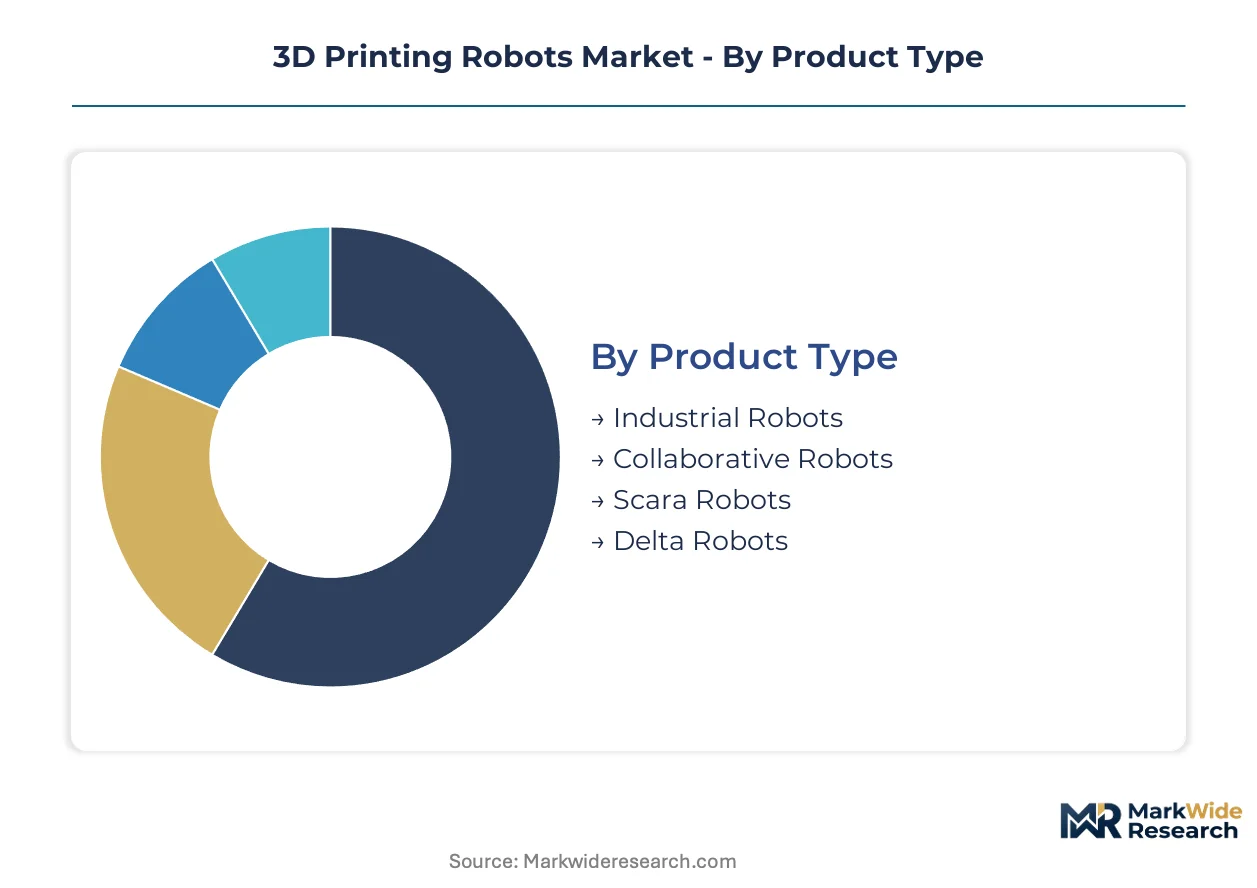
Deposition platform architectures fragment along payload capacity, material compatibility, and regulatory certification requirements. Each segment carries distinct aftermarket service intensity, spare parts velocity, and technician training demands that reshape vendor margin structures.
Product Type:
Aftermarket service contracts vary dramatically by kinematic configuration, with heavy-payload systems requiring intensive preventive maintenance and collaborative designs generating higher per-unit software support revenue.
- Industrial Robots:Articulated six-axis platforms with payload capacity exceeding 200 kg dominate aerospace structural component production. German and US manufacturers deploy these cells for titanium and nickel superalloy deposition, though high-purity metal powder costs constrain tier-two supplier adoption.
- Collaborative Robots:Force-limited designs enable unguarded human-robot interaction through integrated torque sensors and speed monitoring. China's MIIT-backed smart manufacturing corridors drive localized procurement for prototyping environments where rapid reprogramming outweighs throughput maximization.
- Scara Robots:Selective compliance articulated arms optimize planar deposition tasks with 4-axis precision for electronic component encapsulation.
- Delta Robots:Parallel kinematic structures deliver high-speed pick-and-place integration for photopolymer vat polymerization systems in dental laboratories.
Industrial robots hold the largest share; momentum sits with collaborative robots.
Material Type:
Feedstock chemistry determines nozzle wear rates, thermal management complexity, and end-use certification pathways across medical and aerospace applications.
- PLA:Polylactic acid biopolymer extrudes at 180-220°C with minimal warping for educational and prototyping deployments. China's Yangtze River Delta fleet operators favor PLA for high-volume FDM cell refurbishment cycles due to lower deposition head degradation.
- ABS:Acrylonitrile butadiene styrene requires heated build chambers to prevent delamination in automotive interior component production. REACH substance restrictions on certain photoinitiator chemistries indirectly pressure ABS formulation stability in European supply chains.
- Nylon:Polyamide variants absorb atmospheric moisture, demanding sealed filament storage and specialized drying protocols for functional mechanical parts.
- TPU:Thermoplastic polyurethane enables flexible lattice structures for medical cushioning applications with shore hardness ranging from 85A to 95A.
PLA dominates installed base volume; nylon exhibits the steepest expansion trajectory in aerospace-grade composite formulations.
Technology:
Layer resolution specifications and build envelope constraints create distinct competitive moats between extrusion-based and photopolymerization platforms.
- FDM:Fused deposition modeling extrudes thermoplastic filament through heated nozzles in 50-400 micron layer heights. FANUC's proprietary servo architecture dominates high-volume cell deployments with continuous extrusion duty cycles optimized for automotive tier-one supplier pilot programs.
- SLS:Selective laser sintering fuses polyamide powder beds with CO2 lasers, enabling unsupported geometries and nested part packing for production runs below 10,000 units.
- SLA:Stereolithography cures photopolymer resin with UV lasers achieving sub-50-micron layer resolution for dental and medical device applications where FDA 510(k) clearance pathways demand extensive mechanical testing documentation.
- DLP:Digital light processing projects entire layer images simultaneously, compressing print duration for jewelry and hearing aid shell production.
FDM commands the broadest installed base; SLA captures premium positioning in regulated medical environments.
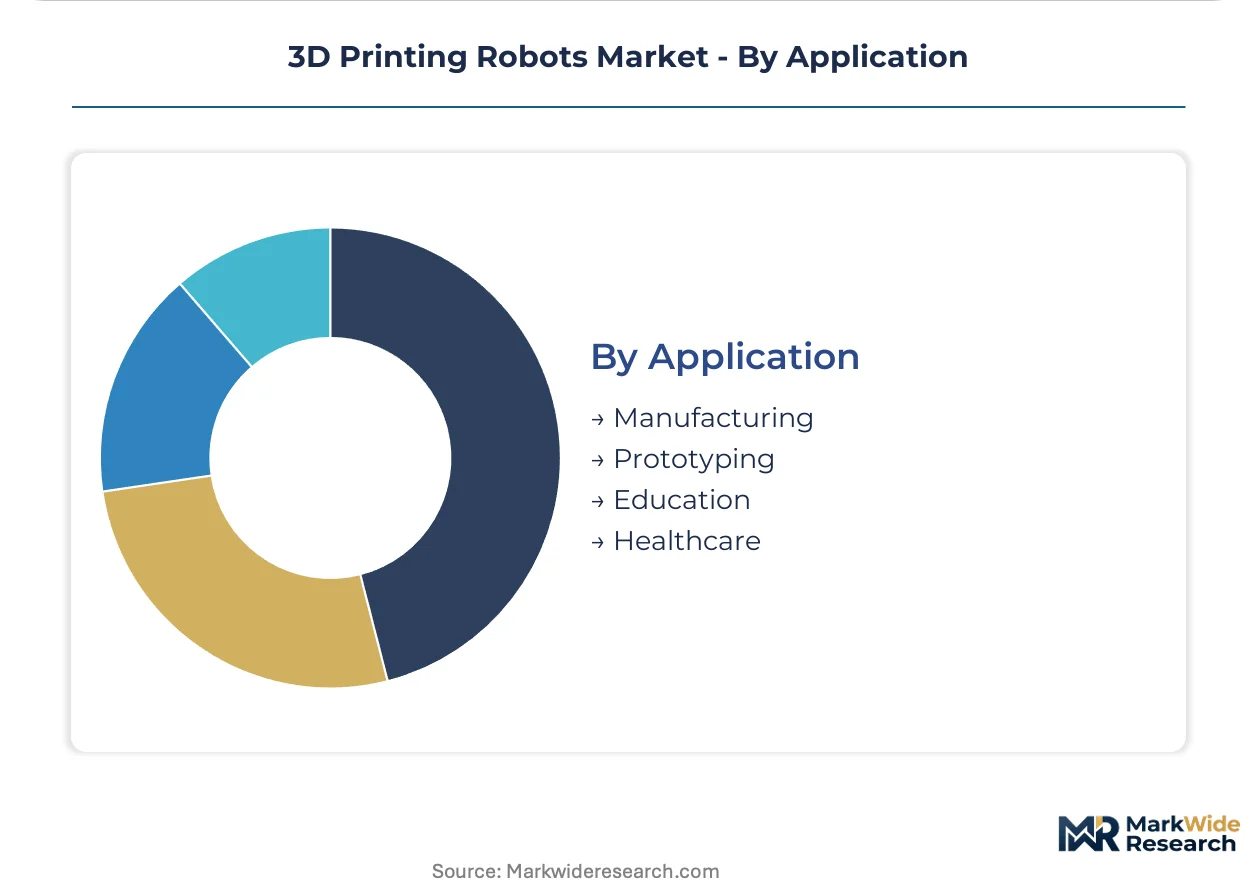
Application:
End-use environment dictates safety architecture, throughput requirements, and software integration depth with legacy manufacturing execution systems.
- Manufacturing:Production-grade deposition cells integrate with factory MES through OPC-UA protocols for traceability in aerospace structural component supply chains. ABB's force-control software enables real-time path correction during multi-axis printing for automotive battery enclosures.
- Prototyping:Rapid iteration environments prioritize build speed over dimensional repeatability, with unguarded collaborative robot deployments accelerating design validation cycles.
- Education:University and technical training programs emphasize open-source controller architectures to develop multi-axis programming proficiency.
- Healthcare:Patient-specific implant production requires ISO 13485 quality system compliance and SAMR GB standard adherence for Chinese market access.
Manufacturing generates the highest equipment revenue; healthcare applications are climbing the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's industrial automation corridors show the highest price elasticity, squeezing equipment margins, while aerospace manufacturers in Germany and the United States absorb premium pricing for certified deposition cells without volume reduction.
United States
FAA certification pathways for flight-critical structural components drive capital deployment in robotic additive manufacturing. FDA 21 CFR Part 820 quality system requirements shape equipment qualification for patient-specific implant production. Greater Boston and Pacific Northwest clusters concentrate dental laboratories deploying SLA platforms with sub-50-micron resolution.
Germany
Automotive tier-one suppliers pilot thermoplastic composite deposition for battery enclosures and seat frames. CE marking under the EU Machinery Directive mandates force-limited collaborative designs for unguarded human-robot interaction. Bavaria and Baden-Württemberg anchor aerospace production cells for titanium and nickel superalloy structures.
China
MIIT-backed smart manufacturing initiatives accelerate localized procurement of deposition platforms. SAMR enforces GB standards for robotic safety that complicate single-design global deployment. Yangtze River Delta fleet operators unbundle aftermarket services, procuring deposition head refurbishment through separate vendor relationships.
Japan
METI's carbon-neutral manufacturing roadmap incentivizes thermoplastic deposition systems for localized large-format component production. JIS standards for robotic safety align with EU Machinery Directive architectures, easing cross-border equipment sales. Kanto and Kansai regions concentrate prototyping environments prioritizing rapid reprogramming over throughput maximization.
Brazil
ANVISA regulatory alignment with FDA pathways creates near-term equipment qualification routes for deposition cell exporters. Aerospace supply chain underpenetration offers first-mover positioning for certified systems. São Paulo and Rio de Janeiro clusters concentrate medical device prototyping labs seeking patient-specific implant production capabilities.
3D Printing Robots Market Competitive Environment
Industrial robotics incumbents and specialized deposition platform builders split the market along payload capacity and certification depth. Consolidation concentrates around automotive and aerospace verticals where CE marking and FDA pathways create regulatory moats. Three archetypes dominate: diversified automation conglomerates with established automotive footprints, pure-play deposition specialists with application-specific kinematic designs, and collaborative robot vendors force-optimized for prototyping environments. Competitive moves center on strategic partnerships for MES integration middleware and geographic expansion into underpenetrated aerospace supply chains.
Within the diversified automation tier, Kuka AG and ABB Group occupy positions anchored by established automotive robotics footprints, while FANUC Corporation exemplifies scale-driven servo architecture optimization for continuous extrusion duty cycles. CEAD B.V. and Caracol represent the pure-play deposition specialist archetype with application-specific large-format platform designs. Universal Robots A/S sits within the collaborative robot tier, force-optimized for unguarded human-robot interaction in rapid iteration environments.
| Leading Market Players |
|---|
| Kuka AG |
| ABB Group |
| Yaskawa Electric Corporation |
| FANUC Corporation |
| Universal Robots A/S |
| Massive Dimension |
| CEAD B.V. |
| Caracol |
| Comau S.p.A. |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta fleet operators unbundle aftermarket services, forcing original equipment suppliers to defend hardware margins while third-party technicians capture refurbishment revenue. This fragmentation concentrates pricing power with buyers who arbitrage deposition head calibration and motion controller updates across separate vendor relationships.
Pricing Analysis
Deposition head refurbishment contracts now drive lifetime value more than initial equipment sales, with three-tier pricing structure across premium certified, standard OEM, and economy third-party service levels. Price differentiation hinges on CE marking compliance depth and MIIT-backed smart manufacturing certification tier. Cost compression in economy refurbishment tiers is intensifying because Yangtze River Delta operators source calibration services from independent technicians. Aerospace manufacturers in Germany and the United States show the lowest price sensitivity, absorbing premium certified-system pricing without volume reduction.
Supply Chain Analysis
Foxconn and Jabil hold concentrated contract-manufacturing capacity for servo motor assemblies and deposition head subsystems. Supply chains draw from Germany for precision motion controllers, Japan for high-torque servo architectures, and China for aluminum structural frames. Single-source vulnerability sits with titanium powder feedstock from limited aerospace-grade suppliers. Distribution runs through direct OEM sales for industrial robots and regional distributor networks for collaborative prototyping systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service unbundling accelerates faster than hardware shipments, making software-update subscriptions and deposition head refurbishment the dominant recurring-revenue layer. Equipment vendors must restructure pricing models around attach rates rather than upfront capital recovery.
For Market Incumbents: Build regulatory-certification moats by deepening FDA 510(k) pathway expertise and CE marking dual-jurisdiction compliance architectures. Kuka AG and ABB Group should anchor backward integration into force-control software development to preempt middleware competitors. Defend against pure-play deposition specialists by locking aerospace tier-one suppliers into multi-year service contracts with guaranteed spare parts availability.
For New Entrants and Emerging Players: Build out application-specific kinematic designs for underpenetrated Brazilian aerospace supply chains where ANVISA regulatory alignment lowers qualification barriers. Target medical device prototyping labs in São Paulo and Rio de Janeiro seeking patient-specific implant production capabilities. Lead with force-limited collaborative platforms priced below FANUC's proprietary servo architecture to capture rapid-reprogramming prototyping demand.
For Investors and Strategic Acquirers: Long-term, this sits as a service-attach play because deposition head refurbishment velocity outpaces installed base expansion. Acquisition targets should display vertical integration into thermoplastic composite formulation or real-time path correction algorithm development. Watch for inflection when MIIT-backed smart manufacturing procurement shifts from pilot subsidies to mandatory compliance requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Force-Control Software Integration | ABB's real-time path correction enables unguarded human-robot interaction in prototyping environments. |
| Dual-Jurisdiction Compliance Investment | CE marking and FDA 21 CFR Part 820 rearchitecting creates regulatory moats against low-cost entrants. |
| Aftermarket Service Unbundling | Yangtze River Delta operators now procure deposition head refurbishment through separate vendor relationships. |
| Thermoplastic Composite Deposition | Automotive tier-one suppliers in Germany pilot continuous carbon fiber reinforcement for battery enclosures. |
| Collaborative Robot Force Optimization | Universal Robots' torque-sensor designs enable unguarded operation where rapid reprogramming outweighs throughput. |
Study Parameters
Desk research of SEC 10-K filings, EU Machinery Directive technical documentation, and SAMR GB standard publications preceded structured interviews with plant engineers at aerospace tier-one suppliers, aftermarket service heads at FDM fleet operators, and biomedical engineers at dental laboratories. Primary fieldwork with deposition platform procurement teams in Germany's Bavaria cluster and China's Yangtze River Delta validated secondary trade data and customs records. Bottom-up unit economics and top-down macroeconomic triangulation anchored market size estimation.
Assumptions held fixed include current EU Machinery Directive enforcement intensity and MIIT smart manufacturing subsidy continuity, while titanium powder price volatility and REACH photoinitiator restriction timelines were stress-tested. Segmentation modeling spanned kinematic configuration, material compatibility tier, and regulatory certification depth across the projection horizon. CAGRs derived from installed base replacement cycles and aftermarket service attach rate trajectories, with inputs from FANUC's servo architecture duty cycle specifications and ABB's force-control software adoption curves.
Stress conditions across titanium superalloy feedstock costs, FDA 510(k) clearance timeline compression, and SAMR GB standard divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including multi-axis programming talent scarcity and legacy MES integration complexity. Quarterly review of MIIT procurement subsidy renewals and ANVISA regulatory alignment progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Saudi Arabia and Egypt Healthcare 3D Printing Market
3D Printing Technology
3D Printing Pellet Extruder Market
3D Printing Technology
Asia-Pacific Healthcare 3D Printing (Additive Manufacturing) Market
3D Printing Technology
Europe 3D Printing Market
3D Printing Technology
3D Printing Service Bureaus Market
3D Printing Technology
3D Printing Vacuum Furnaces Market
3D Printing Technology
3D Printing Market
3D Printing Technology
3D Printing in Aerospace and Defense Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Food 3D Printing Market
3D Printing Technology
3D Manufacturing Software Market
3D Printing Technology
United Kingdom 3D Printing Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Military 3D Printing Market
3D Printing Technology
Polymer 3D Printing Systems Market
3D Printing Technology
3D Printing in Aviation Market