
 Collaborative Robots Market | 2026-2036
Collaborative Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Collaborative Robots Market Intelligence
Modular payload-and-controller bundling is consolidating buyer choice around integrated workcells rather than standalone robot arms. Universal Robots leverages its open software architecture to sustain ecosystem partnerships across third-party peripherals. ABB anchors high-repetition electronics assembly with force-sensing payloads that reduce reprogramming downtime. FANUC Corporation dominates automotive sub-assembly with compact six-axis units designed for dense factory floors.
Collaborative robots are power- and force-limited robotic systems equipped with torque sensors, speed monitoring, and hand-guiding capability, designed to operate safely alongside human workers without fixed guarding. Articulated cobots lead unit shipments due to dexterity in confined workspaces, while SCARA configurations capture margin pools in high-speed electronics assembly where repeatability tolerances sit below 0.02 millimeters. Vision-guided technology segments expand fastest as machine-learning-based part recognition reduces fixture costs and changeover times for packaging automation and pharmaceutical handling applications.
ISO 10218 and TS 15066 establish collision-force thresholds and safety-rated monitored stop functions that determine product eligibility in European and North American factory deployments. OSHA in the United States and Germany's KBA-aligned workplace safety inspectors enforce risk-assessment documentation that lengthens sales cycles but creates compliance moats for certified suppliers. Stakeholders must monitor evolving AI-actuator integration standards and regional certification divergence as cobots assume tasks beyond pre-programmed motion paths.
Market Dynamics
Machine-learning vision systems are decentralizing quality control authority from centralized IT departments to factory-floor operators, compressing reprogramming cycles from hours to minutes and reshaping how automotive and electronics manufacturers justify cobot capital expenditure.
Growth Catalysts
- ISO 10218-1 compliance mandates:European workplace safety inspectors enforce documented risk assessments that favor certified cobot suppliers with established safety-rated monitored stop functions.
- Electronics contract manufacturers:High-mix, low-volume production lines in Germany and China deploy force-sensing cobots to eliminate hard tooling changeover costs.
- Torque sensor miniaturization:Advances in compact force-torque sensing enable sub-10kg payloads with hand-guiding capability, opening pharmaceutical packaging applications.
Market Restraints
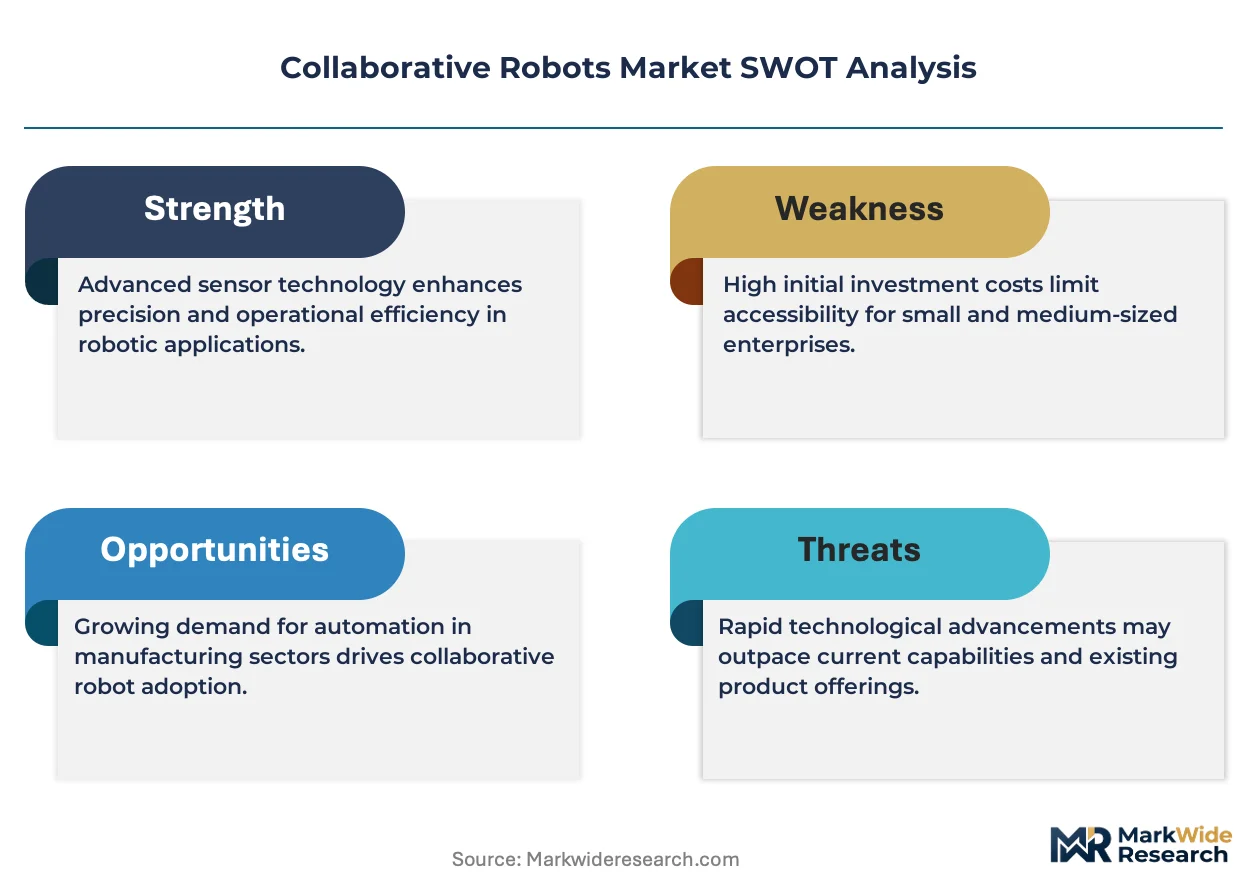
- Harmonic drive supply concentration:Japanese and German precision gearbox manufacturers control critical cobot joint actuation, creating input cost volatility and lead time exposure.
- TS 15066 implementation friction:Collision-force threshold documentation requirements lengthen sales cycles by 4-8 weeks in North American factory deployments.
- Traditional industrial robot substitution:FANUC and ABB offer discounted six-axis units with light curtains that compete on price in high-volume automotive sub-assembly.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for electronics and automotive component makers create first-mover advantage for cobot vendors establishing local service networks.
- AI-actuator convergence:Integration of edge-computing vision processors with brushless DC motors enables autonomous path correction without cloud connectivity.
- Pharmaceutical cleanroom handling:Sterile packaging and vial manipulation applications remain underpenetrated due to legacy SCARA dominance and regulatory validation requirements.
Industry Challenges
- Cobot programming skill scarcity:Factory maintenance technicians lack training in collaborative robot scripting languages and safety-parameter configuration, forcing vendors to embed application engineers at customer sites.
- Legacy PLC integration complexity:Proprietary fieldbus protocols from Siemens, Rockwell, and Mitsubishi require middleware development that extends deployment timelines and erodes margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collaborative Robots Market |
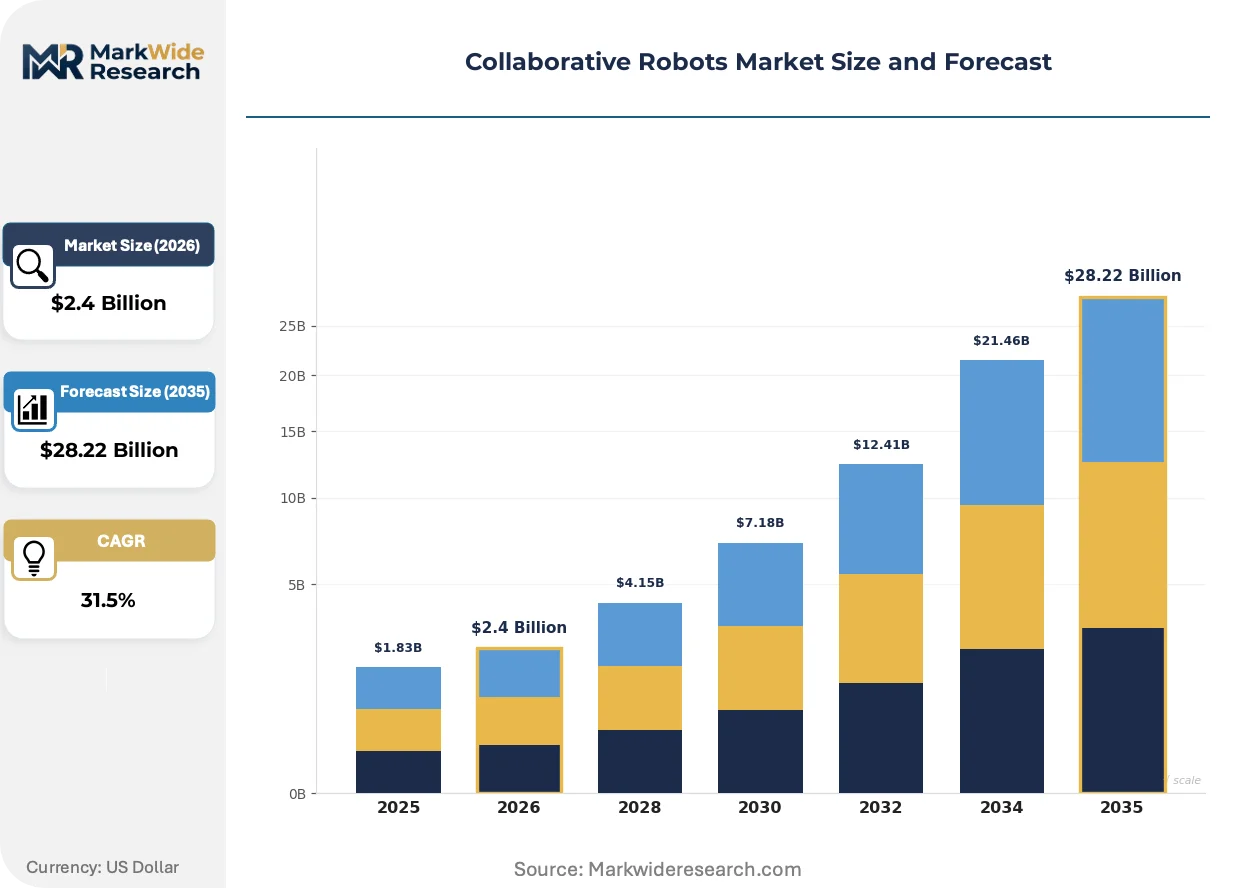
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $28.22 Billion |
| CAGR (2026 – 2036) | 31.5% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Articulated, SCARA, Delta, Cylindrical, Cartesian Technology: Force Sensing, Vision Guided, Machine Learning, Adaptive Control, Sensor Fusion Application: Electronics Assembly, Packaging Automation, Food Processing, Pharmaceutical Handling, Precision Machining End User Industry: Electronics Manufacturers, Consumer Goods Producers, Pharmaceutical Firms, Aerospace Fabricators, Metalworking Plants |
| Companies Covered | Universal Robots, ABB, FANUC Corporation, KUKA AG, Techman Robot, AUBO Robotics, Yaskawa Electric Corporation, Doosan Robotics, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collaborative Robots Market Strategic Shifts & Innovations
Edge-deployed machine learning is compressing the boundary between perception and actuation, enabling cobots to handle unstructured environments without pre-programmed motion paths. Three developments are accelerating this shift.
Embedded vision processors with on-board neural network inference are decentralizing part-recognition tasks from factory servers to robot controllers. Automotive suppliers in Stuttgart and electronics manufacturers in Shenzhen deploy these systems for bin-picking applications with no prior CAD models. The technology is decentralizing fixture engineering from specialized integrators to line operators.
The EU AI Act's risk classification framework for autonomous industrial systems imposes conformity assessment requirements on cobots with self-learning motion planning. German manufacturers must document algorithmic decision boundaries and human oversight protocols. High-mix electronics assembly lines face the steepest compliance burden as they rely most heavily on adaptive path generation.
Small-batch manufacturers now favor rental and performance-based service contracts over capital purchase. German automotive suppliers and US medical device contract manufacturers lease cobot hours with guaranteed uptime rather than owning depreciating assets. The shift is most visible in Michigan and Bavaria where factory utilization rates fluctuate with OEM order volatility.
Collaborative Robots Market Segmentation
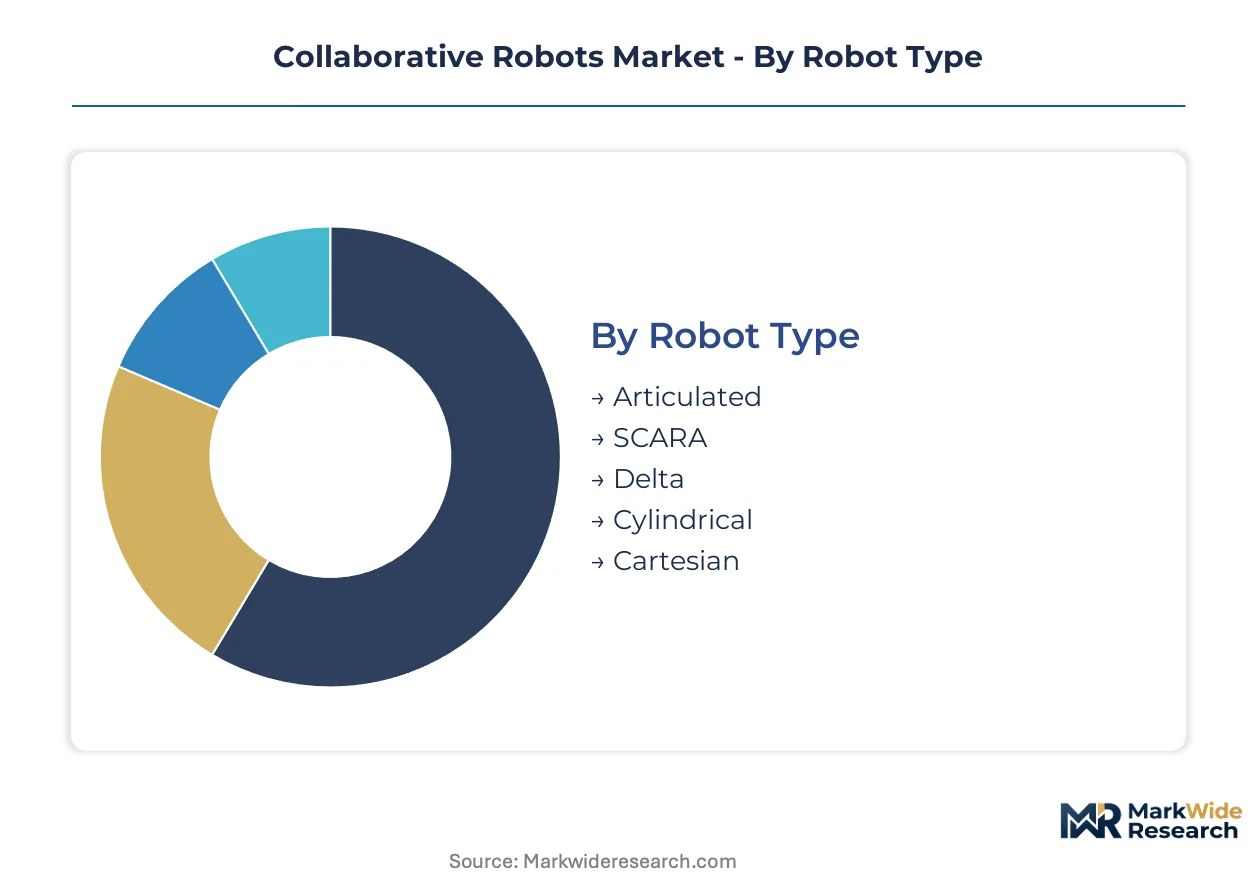
Segmentation in collaborative robots reveals how payload specifications, sensing architectures, and end-use constraints fragment procurement decisions across factory automation buyers. Each dimension carries distinct certification requirements and integration complexity that shape vendor selection and deployment timelines.
Robot Type:
Buyers differentiate primarily by workspace geometry constraints and repeatability tolerances rather than purchase price.
- Articulated:Six-axis jointed arms with torque-limited servos enable hand-guiding in confined automotive sub-assembly cells. Electronics contract manufacturers in Germany favor these for high-mix production where reprogramming frequency exceeds 50 cycles per month.
- SCARA:Selective compliance assembly robot arms deliver sub-0.02 millimeter repeatability for semiconductor packaging and surface-mount technology lines. Chinese electronics clusters deploy these where speed priorities override collaborative safety requirements in partially fenced configurations.
- Delta:Parallel-link structures achieve high-speed pick-and-place in food packaging and pharmaceutical blister packing with payloads under 3 kilograms.
- Cylindrical:Rotary joint and prismatic slide configurations suit machine tending applications with radial workspace requirements.
- Cartesian:Gantry-mounted linear actuators dominate large-format 3D printing and CNC loading where precision outweighs flexibility needs.
Articulated configurations lead volumes today; SCARA variants are gaining share fastest in precision assembly corridors.
Technology:
Technology selection tracks the maturity of factory IT infrastructure and operator technical depth.
- Force Sensing:Integrated torque sensors at each joint enable power-limiting compliance with ISO 10218 collision-force thresholds. Automotive suppliers in Michigan require these for mixed human-robot assembly stations where safety-rated monitored stops are mandatory.
- Vision Guided:Embedded camera systems with edge-deployed neural networks eliminate hard tooling for bin-picking and quality inspection. Shenzhen electronics manufacturers deploy these to compress changeover times from hours to minutes in high-mix contract manufacturing.
- Machine Learning:Self-optimizing path planning algorithms adapt to unstructured part presentation without pre-programmed motion libraries.
- Adaptive Control:Real-time impedance adjustment enables consistent contact forces during polishing, deburring, and surface finishing operations.
- Sensor Fusion:Combined vision, force, and proximity sensing architectures support pharmaceutical cleanroom applications with multi-modal environmental awareness.
Force sensing dominates current installations; vision-guided systems are climbing the fastest as machine-learning inference migrates to robot controllers.
Application:
Application segmentation reflects regulatory validation burdens and contamination control requirements.
- Electronics Assembly:Surface-mount device placement, screwdriving, and cable routing tasks demand sub-millimeter accuracy in electrostatic-controlled environments. German automotive electronics suppliers deploy collaborative systems for just-in-sequence dashboard module assembly.
- Packaging Automation:Case packing, palletizing, and sortation applications prioritize speed over precision in consumer goods distribution centers.
- Food Processing:IP69K-rated cobots handle primary packaging and tray loading where washdown protocols and allergen segregation apply.
- Pharmaceutical Handling:Sterile vial manipulation and secondary packaging require ISO 14644 cleanroom compatibility and batch traceability documentation.
- Precision Machining:Machine tending and metrology integration in metalworking plants emphasize vibration damping and thermal stability.
Electronics assembly commands the largest installed base; pharmaceutical handling shows the steepest expansion trajectory as regulatory validation templates mature.
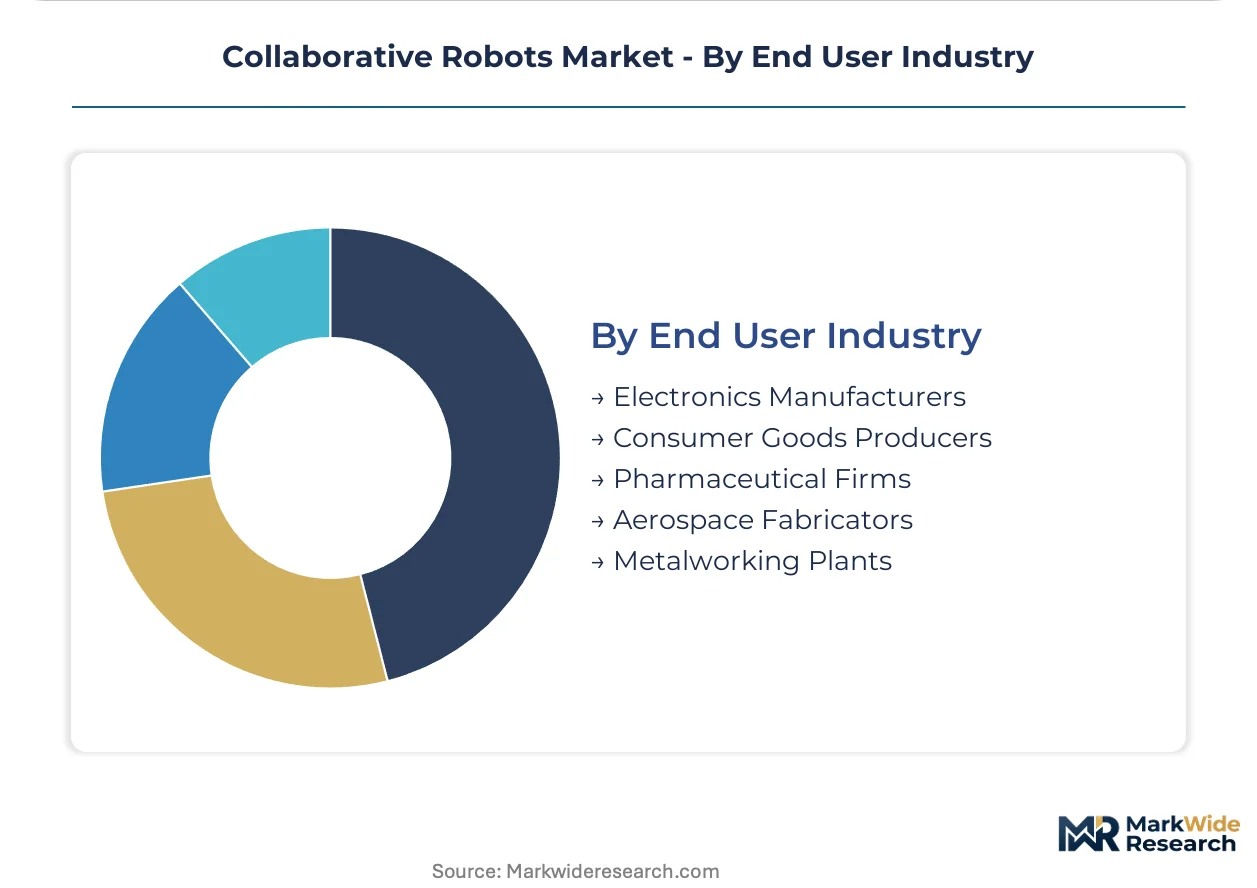
End User Industry:
End user segmentation concentrates on production volume predictability and capital expenditure approval thresholds.
- Electronics Manufacturers:Contract assemblers and original design manufacturers face extreme order volatility that favors rental and performance-based service contracts over asset ownership.
- Consumer Goods Producers:Personal care and household product packagers deploy cobots for seasonal demand surges with rapid redeployment across SKUs.
- Pharmaceutical Firms:Batch pharmaceutical and medical device manufacturers require extensive IQ/OQ/PQ validation protocols that extend deployment timelines.
- Aerospace Fabricators:Low-volume, high-variety composite drilling and fastening applications in tier-one supplier networks.
- Metalworking Plants:CNC machine tending and grinding operations where workforce availability constrains night-shift utilization.
Electronics manufacturers anchor current demand; pharmaceutical firms are expanding most quickly as cleanroom-compatible platforms achieve regulatory acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark pioneered collaborative robotics in the mid-2000s, establishing the technical foundations that now diffuse through German automotive electronics and Chinese contract manufacturing corridors.
Germany
Automotive electronics suppliers in Stuttgart deploy force-sensing cobots for just-in-sequence dashboard assembly where reprogramming cycles exceed fifty times monthly. Germany's KBA-aligned workplace safety inspectors enforce ISO 10218-1 risk-assessment documentation that extends sales cycles but protects certified vendors. Bavarian medical device contract manufacturers lease cobot hours with guaranteed uptime clauses rather than owning depreciating assets.
China
Shenzhen electronics clusters integrate vision-guided cobots to compress changeover times from hours to minutes in high-mix contract manufacturing environments. The Ministry of Industry and Information Technology prioritizes intelligent manufacturing equipment through dual carbon-aligned industrial upgrading programs. Yangtze River Delta automotive suppliers deploy compact six-axis units for dense sub-assembly floors where floor space commands premium valuations.
United States
Michigan automotive tier-one suppliers deploy force-limited articulated arms for mixed human-robot stations where OSHA mandates safety-rated monitored stops. The Inflation Reduction Act's domestic content provisions incentivize reshoring of electronics assembly that favors flexible automation over fixed tooling. Medical device contract manufacturers in Minnesota favor rental models with performance guarantees over capital expenditure approvals.
Japan
Osaka-based precision manufacturers source compact SCARA configurations for semiconductor packaging where repeatability tolerances sit below 0.02 millimeters. METI's Society 5.0 roadmap accelerates human-machine collaboration standards development for aging workforce adaptation. Nagoya automotive suppliers deploy delta robots for high-speed pick-and-place in food packaging adjacent to their core industrial clusters.
India
Tamil Nadu electronics manufacturing services providers pilot collaborative systems for smartphone assembly under Production-Linked Incentive scheme subsidies. The Central Electricity Authority's industrial power reliability standards shape factory automation investment timing in grid-constrained corridors. Karnataka automotive component makers establish first-mover service networks with European cobot vendors seeking PLI-qualified partnerships.
Collaborative Robots Market Key Industry Players
Premium-margin players sit above commodity-margin players across software architecture openness and ecosystem partnership depth. The vendor base stratifies into three tiers: full-stack platform providers with proprietary controller integration, joint-venture specialists leveraging parent-company distribution networks, and regional assemblers competing on localized service response. Dominant competitive moves include capacity expansion in Southeast Asian electronics corridors and strategic partnerships between vision software vendors and hardware-agnostic controller platforms.
Among Denmark-based platform originators, Universal Robots exemplifies the open-architecture archetype that sustains third-party peripheral ecosystems. Japanese industrial automation conglomerates FANUC Corporation and Yaskawa Electric Corporation occupy positions within the precision-motion tier, anchoring high-repetition electronics and automotive sub-assembly segments through established distributor relationships. Chinese specialists AUBO Robotics and Techman Robot represent the rapid-response service model that penetrates high-mix contract manufacturing through localized application engineering.
| Leading Market Players |
|---|
| Universal Robots |
| ABB |
| FANUC Corporation |
| KUKA AG |
| Techman Robot |
| AUBO Robotics |
| Yaskawa Electric Corporation |
| Doosan Robotics |
| DENSO Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up automation specialists in Europe and North America now control distribution networks that bundle hardware with multi-year service contracts, compressing price transparency while extending payment terms that strain smaller Asian assemblers. This ownership consolidation concentrates pricing power among vendors with certified ISO 10218 compliance, forcing uncertified competitors toward economy-tier positioning or regional niche specialization.
Pricing Analysis
Subscription-based leasing with performance-guarantee clauses dominates German automotive electronics and US medical device contract manufacturing, separating premium tier vendors with embedded application engineers from standard tier suppliers relying on third-party integrators. Price differentiation rests on ISO 10218-1 certification tier and after-sales response time guarantees. Cost compression in the standard tier intensifies as Chinese specialists bundle vision software at marginal cost. Electronics contract manufacturers in Shenzhen exhibit highest price sensitivity; pharmaceutical cleanroom operators in Bavaria and Minnesota show lowest.
Supply Chain Analysis
Harmonic drive precision gearing rests on Japanese and German specialty manufacturers, while brushless DC motor controllers draw heavily from Chinese and Taiwanese electronics clusters. Torque sensor MEMS fabrication centers on US and German semiconductor foundries. Single-source vulnerability in precision gearbox supply creates lead time exposure when automotive demand surges. Distribution runs through authorized system integrators in Stuttgart, Shenzhen, and Detroit who bundle installation with regulatory documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 10218 and TS 15066 compliance mandates function as regulatory compounders, lengthening sales cycles for uncertified suppliers while embedding certified vendors into automotive and pharmaceutical procurement workflows. This dynamic favors early certification investment as a demand-creation mechanism.
For Market Incumbents: To counter price erosion from Chinese vision-guided specialists, Universal Robots and ABB should embed proprietary force-sensing firmware updates as recurring revenue streams rather than one-time hardware sales. Backward integration into torque sensor calibration facilities in Germany and Michigan reduces dependency on Japanese component suppliers while accelerating TS 15066 documentation turnaround. For New Entrants and Emerging Players: Direct-to-factory digital sales channels bypass incumbent integrator networks that capture margin in mid-market electronics assembly. Pharmaceutical cleanroom handling in India and Southeast Asia offers the most penetrable white-space, as legacy SCARA dominance leaves collaborative systems underdeployed despite PLI scheme subsidies. Target smartphone assembly lines in Tamil Nadu with rental-first positioning and guaranteed uptime clauses. For Investors and Strategic Acquirers: Valuations sit cheapest among European mid-caps with ISO 10218 certification but limited Asia-Pacific service infrastructure. Long-term viability in this market hinges on software architecture openness that sustains third-party peripheral ecosystems. Watch for EU AI Act conformity assessment requirements as the inflection signal that separates compliant platform vendors from hardware-commoditized assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Certification-First Market Entry | ISO 10218-1 documentation capabilities unlock German automotive electronics procurement workflows. |
| Edge Computing Vision Integration | On-board neural network inference reduces fixture engineering costs for Shenzhen contract manufacturers. |
| Regional Service Network Expansion | Local application engineering in Karnataka and Tamil Nadu captures PLI scheme-qualified partnerships. |
| Rental and Performance Contract Pivot | Guaranteed uptime clauses align with Bavarian medical device manufacturer asset-light preferences. |
| AI-Act Compliance Documentation | Algorithmic decision boundary records satisfy German KBA-aligned inspector requirements for adaptive path generation. |
Research Approach
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, regulatory filing analysis, and customs trade data — were reconciled to construct segment-level demand estimates. Factory automation directors, cobot application engineers, safety compliance officers, and electronics contract manufacturing executives provided operational validation. Secondary sources included ISO certification databases, MIIT intelligent manufacturing disclosures, SEC equipment supplier filings, and German KBA workplace safety inspection records. Bottom-up unit shipment estimates triangulated against top-down capital expenditure projections from automotive and electronics manufacturing clusters.
Data-stream reconciliation across robot type, payload specification, sensing architecture, and end-use application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from fitted growth curves applied to certified versus uncertified vendor penetration rates. Forecast inputs incorporated TS 15066 implementation friction timelines, PLI scheme subsidy qualification thresholds, and edge-computing vision processor cost decline trajectories.
The model assumes a particular technology adoption path; alternative pathways for autonomous path correction without cloud connectivity would alter the outlook if AI-actuator integration standards diverge regionally. Forecasts reflect assumptions about harmonized safety certification acceptance and stable precision gearbox supply. A small set of named triggers — EU AI Act enforcement intensity, Japanese harmonic drive capacity expansion, and India's PLI scheme renewal terms — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Laboratory Robotics Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
Africa Agricultural Robots and Mechatronics Market
Robotics and Automation
Europe Agricultural Robot Market
Robotics and Automation
South America Agricultural Robots and Mechatronics Market
Robotics and Automation
Robot Pedestal Market
Robotics and Automation
Mobile Robot Charging Station Market
Robotics and Automation
North America Automated Liquid Handling Market
Robotics and Automation
Metal Fabrication Robots Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Mobile Robotics Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
Medical Rehabilitation Robotics Market
Robotics and Automation
Robotic Welding Market
Robotics and Automation
Global Entertainment Robots Market
Robotics and Automation
Europe Logistics Robotics Market