
 3D Printing Vacuum Furnaces Market | 2026-2036
3D Printing Vacuum Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Vacuum Furnaces Market Insights
Titanium aluminide is repositioning legacy nickel superalloys in aerospace turbine applications, forcing furnace suppliers to engineer higher thermal uniformity and tighter atmosphere control. SECO/WARWICK leverages its European installed base to anchor aftermarket service contracts across German and Polish aerospace tiers. Ipsen competes through vertical integration into control system software, while Sentro Tech specializes in compact batch configurations for research institutions and startup metal printing labs.
3D printing vacuum furnaces are hermetically sealed thermal processing systems operating below atmospheric pressure, typically achieving temperatures from 1,000°C to 2,400°C with vacuum levels reaching 10⁻⁵ mbar for degassing, stress relief, and microstructural densification of additively manufactured metal parts. Horizontal vacuum furnaces dominate current installations due to their compatibility with large-format build plates from powder bed fusion systems, though continuous vacuum furnace architectures are attracting investment from high-volume automotive OEMs seeking inline integration with automated post-processing lines. Electron beam heating commands premium positioning in semiconductor producer and aerospace manufacturer segments where rapid thermal cycling and minimal contamination prove essential.
The EPA enforces Maximum Achievable Control Technology standards on thermal processing emissions, while the EU F-Gas Regulation restricts fluorinated greenhouse gases used in certain quenching media, compelling furnace redesigns. ISO 9001 and Nadcap accreditation function as de facto market access gates for suppliers serving aerospace and defense primes. Stakeholders must monitor how evolving sustainability disclosure rules reshape procurement criteria for capital equipment across European and North American manufacturing bases.
Market Dynamics
Titanium aluminide adoption in aerospace turbine blades is forcing furnace suppliers to engineer tighter thermal uniformity and atmosphere control, while EPA and EU F-Gas Regulation emissions mandates accelerate induction and resistive heating transitions.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in quenching media compel furnace redesigns toward induction and resistive heating systems that eliminate process gas venting.
- Aerospace turbine blade post-processing:Additively manufactured titanium aluminide components require vacuum furnace densification to achieve microstructural properties matching legacy nickel superalloys.
- German industrial clustering:Munich and Stuttgart combine automotive OEM density with research institution linkages, concentrating demand for compact batch and continuous vacuum furnace architectures.
Market Restraints
- Graphite heating element supply concentration:High-purity graphite sourcing clusters in limited geographies, exposing furnace manufacturers to input cost volatility and supply disruption risk.
- Technical limitation in thermal uniformity:Large-format build plates from powder bed fusion systems create temperature gradient challenges that horizontal vacuum furnace architectures struggle to resolve at scale.
- Nadcap accreditation friction:Aerospace and defense primes require supplier certification that extends qualification timelines and elevates compliance costs for furnace makers.
Strategic Opportunities
- Continuous vacuum furnace architectures:High-volume automotive OEMs seek inline integration with automated post-processing lines, creating white space beyond batch processing dominance.
- Research institution channel expansion:Startup metal printing labs and university additive manufacturing centers represent underpenetrated demand for compact, configurable batch systems.
- Induction heating technology convergence:Combining induction power supplies with vacuum chamber design eliminates gas venting while enabling rapid thermal cycling for semiconductor producer segments.
Industry Challenges
- Vacuum system engineering talent scarcity:Specialized expertise in hermetic sealing design and high-temperature thermocouple calibration remains concentrated among legacy furnace engineering teams.
- ISO 9001 and Nadcap certification timelines:Documentation and audit requirements for aerospace supplier qualification compress already extended equipment delivery schedules.
- Integration complexity with powder bed fusion lines:Automated material handling between printing and post-processing systems demands custom engineering that fragments project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Vacuum Furnaces Market |
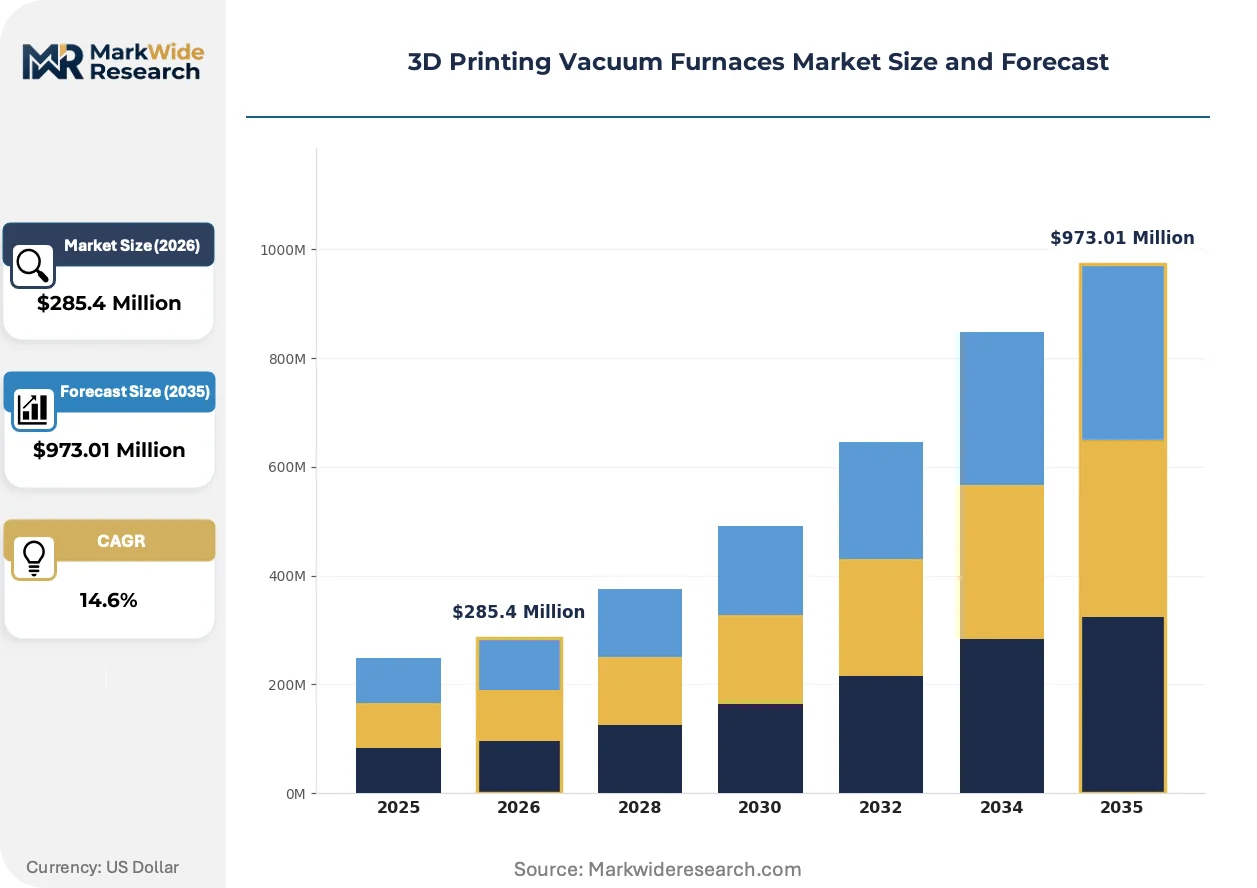
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $973.01 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Vacuum Furnace, Vertical Vacuum Furnace, Box Vacuum Furnace, Batch Vacuum Furnace, Continuous Vacuum Furnace Technology: Resistive Heating, Induction Heating, Electron Beam Heating, Infrared Heating, Plasma Heating Application: Metal Sintering, Composite Curing, Heat Treatment, Brazing, Annealing End User: Aerospace Manufacturers, Semiconductor Producers, Tool Manufacturing Firms, Research Institutions, Automotive OEMs |
| Companies Covered | NITREX, Meige Vacuum, Sentro Tech, Sotor Heat Treatment, Normanbell, Ipsen, JJJvac, TAV, SECO/WARWICK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Vacuum Furnaces Market Trends and Innovations
Electron beam heating architectures are reshaping competitive positioning in contamination-sensitive segments, while regulatory emissions mandates and buyer consolidation across aerospace tiers reconfigure procurement patterns.
Resistive heating element technology is integrating advanced ceramic composite materials to achieve temperature stability above 2,000°C. Aerospace manufacturers adopt these systems for stress relief of structural brackets at accelerated qualification pace. This integration compresses the performance gap between mid-range and premium furnace configurations.
REACH and EU F-Gas Regulation restrictions on fluorinated greenhouse gases are compelling furnace redesigns toward closed-loop quenching media. Industrial consequence includes elevated R&D allocation toward alternative cooling architectures. Semiconductor producer segments in Germany and the Netherlands respond fastest, demanding rapid thermal cycling capabilities without gas venting.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundles into discrete performance contracts and spare parts procurement. Original equipment manufacturers face margin pressure as aerospace tiers source consumables through third-party distributors. This pattern concentrates in Poland and the Czech Republic where independent service providers have established vacuum pump and seal inventories.
3D Printing Vacuum Furnaces Market Segmentation
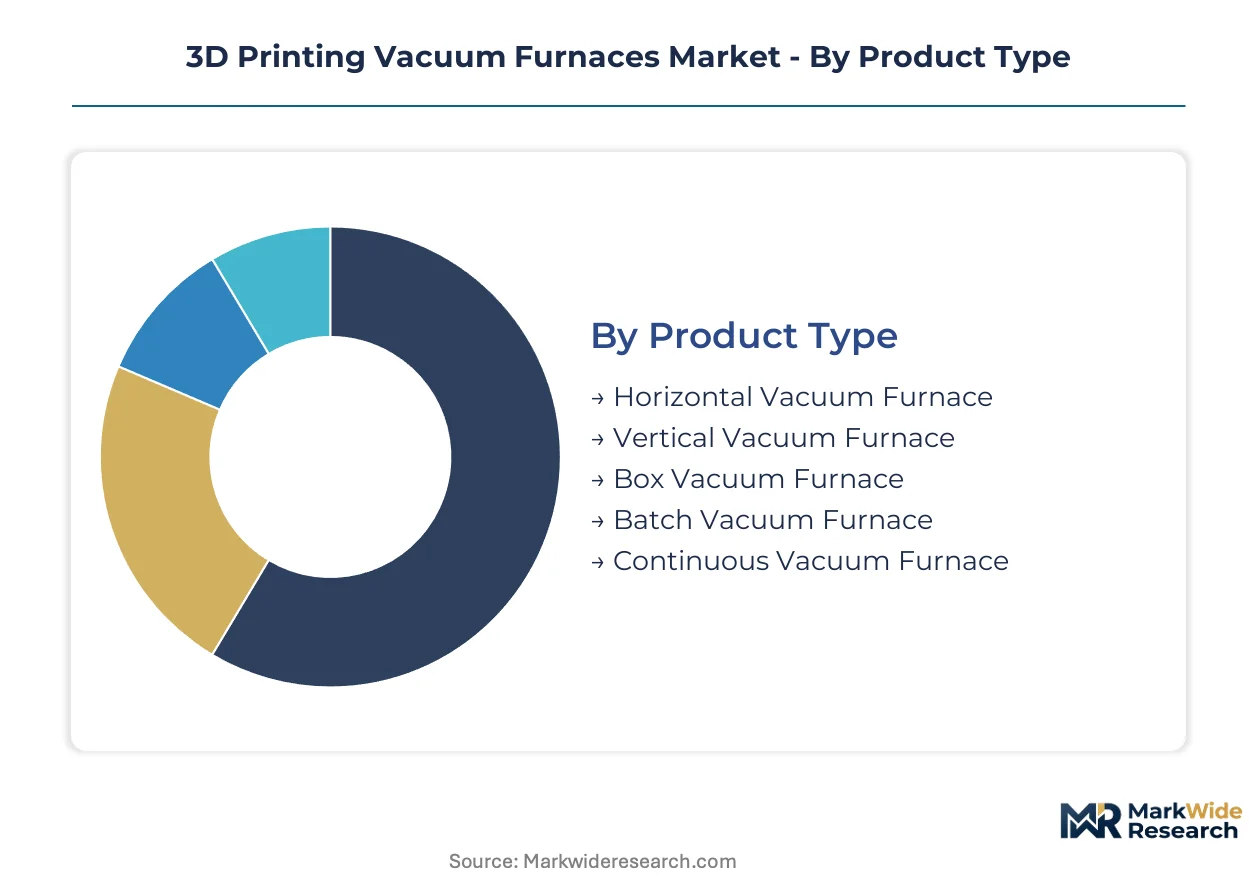
Buyers in this market select furnace configurations based on thermal uniformity requirements, part geometry constraints, and integration complexity with existing additive manufacturing lines. Segmentation reveals how equipment specifications diverge across aerospace qualification demands versus research institution flexibility needs.
Product Type:
Horizontal architectures dominate procurement decisions for large-format compatibility, though continuous systems are gaining traction in high-volume environments.
- Horizontal Vacuum Furnace:Chamber orientation accommodates build plates from powder bed fusion systems up to 600mm in width. Aerospace manufacturers in Germany specify these for titanium aluminide turbine blade densification where thermal gradient control across extended horizontal zones remains critical.
- Continuous Vacuum Furnace:Inline material handling enables automated transfer from printing to post-processing stations without atmosphere breach. Automotive OEMs in Stuttgart industrial clusters pilot these architectures for structural bracket stress relief at production scale.
- Vertical Vacuum Furnace:Stacked loading configuration optimizes floor space utilization in facility-constrained environments.
- Box Vacuum Furnace:Cubic chamber geometry suits irregular part geometries and research prototyping workflows.
- Batch Vacuum Furnace:Intermittent loading cycle matches low-volume, high-mix production typical of startup metal printing labs.
Volume sits with horizontal configurations; growth tilts toward continuous architectures.
Technology:
Heating method selection determines atmosphere purity, thermal ramp rates, and regulatory compliance posture across emission-sensitive jurisdictions.
- Resistive Heating:Graphite or refractory metal elements achieve temperature stability above 2,000°C with capital cost advantages over electron beam alternatives. Tool manufacturing firms in Poland adopt these for heat treatment of additively manufactured cutting inserts where contamination tolerance exceeds aerospace thresholds.
- Electron Beam Heating:Directed energy deposition enables rapid thermal cycling with minimal residual gas interaction. Semiconductor producers in the Netherlands specify these for brazing of copper-tungsten heat spreaders where atmospheric purity requirements exceed 10⁻⁶ mbar.
- Induction Heating:Electromagnetic coupling eliminates heating element degradation and enables closed-loop thermal management without gas venting.
- Infrared Heating:Radiant energy transfer suits polymer composite curing and lower-temperature annealing applications.
- Plasma Heating:Ionized gas environments enable surface activation concurrent with thermal processing for specialized coating adhesion.
Resistive systems capture the largest installed base; induction configurations are climbing the fastest as EU F-Gas Regulation compliance hardens.
Application:
Process type dictates chamber atmosphere requirements, cooling rate specifications, and qualification documentation intensity.
- Metal Sintering:Densification of powder-based green bodies or additively manufactured preforms requires controlled heating profiles to 1,400°C with binder evacuation protocols. Research institutions in Munich leverage these capabilities for titanium alloy process development bridging academic and industrial adoption.
- Heat Treatment:Stress relief and microstructural modification of as-printed metal parts demands precise temperature uniformity within ±5°C. Aerospace manufacturers specify these processes for structural bracket qualification under Nadcap accreditation requirements.
- Composite Curing:Polymer matrix consolidation under vacuum pressure eliminates void formation in fiber-reinforced components.
- Brazing:Filler metal melting and capillary flow under protective atmosphere joins dissimilar materials in semiconductor thermal management assemblies.
- Annealing:Recrystallization and residual stress reduction at sub-sintering temperatures improves ductility in tool steel components.
Metal sintering commands the heaviest equipment investment; heat treatment applications are expanding most quickly as printed part qualification accelerates.
End User:
Customer type determines specification stringency, service contract structure, and procurement cycle duration from initial inquiry to installation.
- Aerospace Manufacturers:Nadcap accreditation and AS9100 compliance requirements extend equipment qualification timelines. Turbine blade producers specify horizontal vacuum furnaces with 10⁻⁵ mbar capability and documented thermal uniformity mapping for titanium aluminide densification.
- Research Institutions:Configurability and rapid retooling outweigh absolute performance specifications. University additive manufacturing centers in Stuttgart prioritize compact batch systems with interchangeable hot zones for alloy development across titanium, nickel, and refractory metal families.
- Semiconductor Producers:Contamination control and rapid thermal cycling dominate procurement criteria for heat spreader and packaging applications.
- Tool Manufacturing Firms:Cost efficiency and throughput optimization drive selection for cutting insert and die component processing.
- Automotive OEMs:Inline integration and automation compatibility guide continuous vacuum furnace adoption for structural component production.
Aerospace buyers deploy the highest unit values; research institutions represent the steepest expansion trajectory as metal printing education proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for 3D printing vacuum furnaces clusters in industrialized economies with dense aerospace and automotive manufacturing footprints. Germany, the United States, Japan, China, and the Netherlands concentrate procurement volumes through 2035.
Germany
Bavarian aerospace tiers and Stuttgart automotive clusters drive horizontal vacuum furnace procurement for titanium aluminide densification. The EU F-Gas Regulation restricts fluorinated quenching media, compelling induction heating retrofits across Munich-area installations. Research institutions in Karlsruhe and Aachen anchor alloy development programs bridging academic and industrial adoption.
United States
EPA Maximum Achievable Control Technology standards push furnace operators toward closed-loop thermal systems. Aerospace primes in California and Texas specify electron beam configurations for rapid cycling of turbine blade post-processing. The Department of Defense additive manufacturing maturation initiative accelerates Nadcap qualification timelines for structural bracket applications.
Japan
METI industrial decarbonization roadmaps favor resistive heating architectures with reduced energy intensity. Tool manufacturers in Nagoya industrial corridors adopt compact batch systems for cutting insert densification. Semiconductor producers in Kyushu demand vacuum levels below 10⁻⁶ mbar for copper-tungsten heat spreader brazing.
China
MIIT equipment upgrade subsidies support vacuum furnace procurement for aerospace supply chain localization. Powder bed fusion system deployments in Xi'an and Chengdu create downstream post-processing demand. GB standards for thermal processing equipment tighten documentation requirements for export-qualified suppliers.
Netherlands
ECHA REACH compliance frameworks restrict process chemistry in quenching operations. ASML supplier ecosystems in Eindhoven drive electron beam furnace adoption for contamination-sensitive thermal management assemblies. Rotterdam port logistics enable graphite heating element import channels serving Benelux tool manufacturing tiers.
3D Printing Vacuum Furnaces Market Competitive Landscape
Strategic partnerships dominate the current landscape as furnace suppliers seek control system integration and aftermarket service scale. The vendor base fragments across European engineering heritage firms, Asian cost-optimized fabricators, and North American technology specialists. Three archetypes occupy distinct positions: full-line thermal processing conglomerates with aerospace accreditation depth; compact system specialists targeting research institutions and startup labs; and induction technology purveyors capitalizing on emissions compliance transitions. Geographic expansion and technology licensing represent the primary competitive vectors as players chase EU F-Gas Regulation-driven replacement cycles.
Among European heritage suppliers, SECO/WARWICK and Ipsen occupy positions anchored by installed base density and control system integration capabilities. Sentro Tech exemplifies the compact batch specialist archetype serving university additive manufacturing centers. These three names represent the competitive spectrum from full-line thermal processing to configurable research-scale systems.
| Leading Market Players |
|---|
| NITREX |
| Meige Vacuum |
| Sentro Tech |
| Sotor Heat Treatment |
| Normanbell |
| Ipsen |
| JJJvac |
| TAV |
| SECO/WARWICK |
| Others |
Pricing and Supply Chain Analysis
High-purity graphite heating elements flow from concentrated sourcing nodes through three-tier pricing structures that separate aerospace-grade thermal uniformity systems from research-scale batch configurations and economy tool-manufacturing units. EU F-Gas Regulation compliance costs and Nadcap accreditation requirements compress margins at the mid-tier while premium electron beam configurations retain pricing power through semiconductor producer demand.
Pricing Analysis
Volume concentrates in resistive heating horizontal furnaces serving automotive OEMs and tool manufacturers, while margins concentrate in electron beam and induction systems for aerospace and semiconductor segments. Three-tier pricing structure across premium, standard, and economy levels separates Nadcap-accredited aerospace configurations from research-scale batch units and Polish tool-manufacturing imports. Pricing pressure stems from aftermarket service unbundling in Poland and the Czech Republic, where independent distributors fragment traditional equipment-plus-maintenance bundles. Research institutions and startup metal printing labs exhibit highest price sensitivity, while semiconductor producers in the Netherlands demonstrate lowest sensitivity due to contamination control requirements.
Supply Chain Analysis
Vacuum system engineering talent scarcity in Germany, Japan, and the United States constrains chamber fabrication capacity and extends delivery timelines for hermetic sealing design and high-temperature thermocouple calibration. High-purity graphite heating elements, refractory metal components, and advanced ceramic composites anchor raw material dependencies, with sourcing concentrated among legacy suppliers in limited geographies. Single-source vulnerability in graphite supply exposes furnace manufacturers to input cost volatility and disruption risk. Distribution runs through direct OEM sales for aerospace primes, third-party distributors for research institutions, and integrated service providers in Central European industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
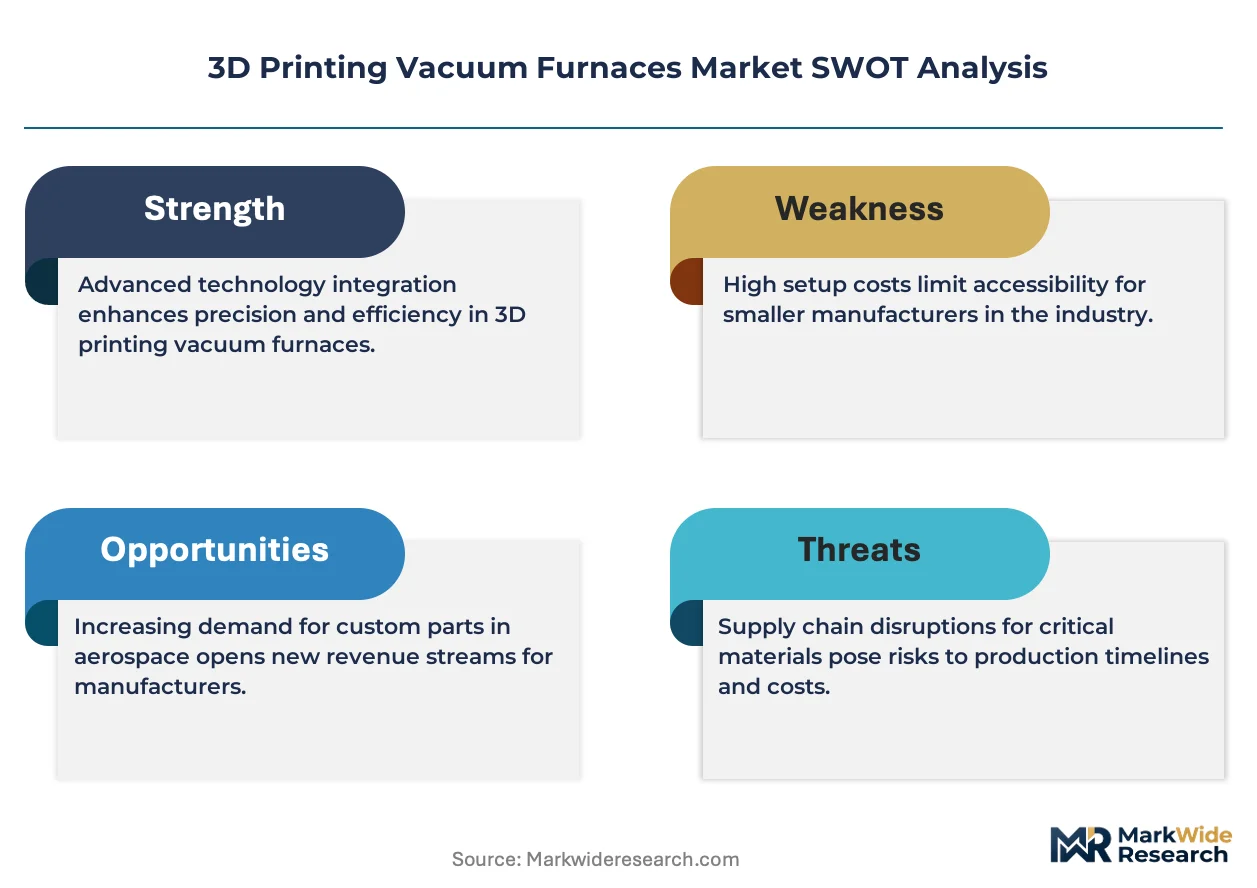
This market consolidates around EU F-Gas Regulation-driven technology transitions, with weaker players lacking induction heating engineering capabilities facing accelerated exit pressure.
For Market Incumbents: To counter aftermarket service unbundling by independent distributors in Poland and the Czech Republic, SECO/WARWICK and Ipsen should deepen backward integration into control system software and captive spare parts production. Anchor position through long-term performance contracts with German aerospace tiers and induction heating retrofit programs for EU F-Gas compliance. For New Entrants and Emerging Players: Startup metal printing labs and university additive manufacturing centers represent the most penetrable buyer archetype, with compact batch vacuum furnace demand outpacing specialist supply. Target Stuttgart and Karlsruhe research clusters with configurable hot-zone systems and rapid retooling capabilities. Go-to-market through direct academic channel partnerships rather than industrial distributor networks. For Investors and Strategic Acquirers: Induction heating technology licensing announcements from European heritage suppliers are the leading indicator that emissions-driven replacement cycles are accelerating. Position for five-to-ten year viability through acquisition of induction power supply specialists with vacuum chamber integration capabilities. Watch for EPA Maximum Achievable Control Technology enforcement actions as the signal for North American compliance-driven demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Heating Technology Licensing | Enables EU F-Gas Regulation compliance without process gas venting for German aerospace tiers. |
| Backward Integration into Control Systems | Ipsen's software captive supply differentiates aftermarket service retention against third-party distributors. |
| Research Institution Channel Expansion | Sentro Tech's compact batch focus captures Stuttgart and Karlsruhe alloy development program demand. |
| Continuous Vacuum Furnace Pilot Programs | Stuttgart automotive OEM inline integration trials validate automated post-processing line economics. |
| Nadcap Accreditation Investment | AS9100 compliance documentation compresses qualification timelines for aerospace prime procurement. |
Research Methodology
Trade publications, customs filings, and SEC equipment manufacturer disclosures formed the secondary backbone, supplemented by primary interviews with vacuum furnace engineering directors, aerospace tier procurement managers, research institution facility heads, and aftermarket service distributors. Bottom-up and top-down triangulation validated installed base estimates and replacement cycle assumptions across German, American, and Japanese manufacturing clusters.
Bottom-up modeling aggregated segment-level demand from product type, heating technology, and end-user dimensions, while top-down cross-checks anchored aggregate market scale against industrial additive manufacturing capital expenditure patterns across the projection horizon. CAGRs derived from equipment replacement cycles, regulatory compliance deadlines, and technology transition curves. Forecast inputs incorporated EPA enforcement timelines, EU F-Gas Regulation phase-out schedules, and titanium aluminide qualification pace at aerospace primes.
Revisions become necessary when EPA Maximum Achievable Control Technology enforcement intensity, EU F-Gas Regulation amendment scope, or graphite supply disruption severity materially deviates from baseline assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Technology
Global Industrial 3D Printing Market
3D Printing Technology
Hybrid Additive Manufacturing Machine Market
3D Printing Technology
Global 3D Printing in Medical Applications Market
3D Printing Technology
3D Printing Robots Market
3D Printing Technology
3D Printing Materials and Equipment Market
3D Printing Technology
3D Concrete Printers Market
3D Printing Technology
Additive Manufacturing Platform Market
3D Printing Technology
Digital Light Processing (DLP) Printer Market
3D Printing Technology
3D Printing Technology in Pharmaceutical Market
3D Printing Technology
Global 3D Metal Printing Machines Market
3D Printing Technology
3D Printing in Automotive Additive Market
3D Printing Technology
Latin America Industrial 3D Printing Market
3D Printing Technology
North America Industrial 3D Printing Market
3D Printing Technology
Global Additive Manufacturing with Metal Powders Market
3D Printing Technology
Conventional and Rapid Prototyping Market
3D Printing Technology
North America Additive Manufacturing with Metal Powders Market