
 3D Optical Microscope Market | 2026-2036
3D Optical Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
3D Optical Microscope Market Analysis
Capital-intensity divergence between photonics specialists and diversified conglomerates is collapsing as confocal and super-resolution platforms require comparable cleanroom-grade manufacturing infrastructure. Bruker Corp. leverages its atomic force microscopy installed base to cross-sell 3D optical systems into materials science departments. Keyence Corp. anchors its position through direct sales engineers who embed configuration software at customer sites. Nikon Corp. competes by sustaining vertical integration into proprietary objective lens grinding.
A 3D optical microscope captures topographic and volumetric data from specimens using structured light, confocal laser scanning, or interferometric techniques, achieving axial resolutions below 100 nanometers for semiconductor wafer inspection and cellular morphology studies. Confocal microscopes dominate revenue due to mature software ecosystems and established service networks, while super-resolution variants capture the fastest expansion as cryo-electron microscopy workflows demand correlated optical registration. Semiconductor inspection applications concentrate margin pools because fabs require sub-nanometer repeatability certifications and 24-hour uptime guarantees.
FDA device classification rules for diagnostic microscopy systems shape product development roadmaps for medical end users, while EPA hazardous substance restrictions affect optical coating chemistries and supplier qualification protocols in the United States. ISO 10993 biocompatibility standards and IEC 61010-1 safety requirements govern instrument placement in clinical and industrial laboratories respectively. Stakeholders must monitor how export control expansions on dual-use metrology equipment reshape customer eligibility in advanced manufacturing economies.
Market Dynamics
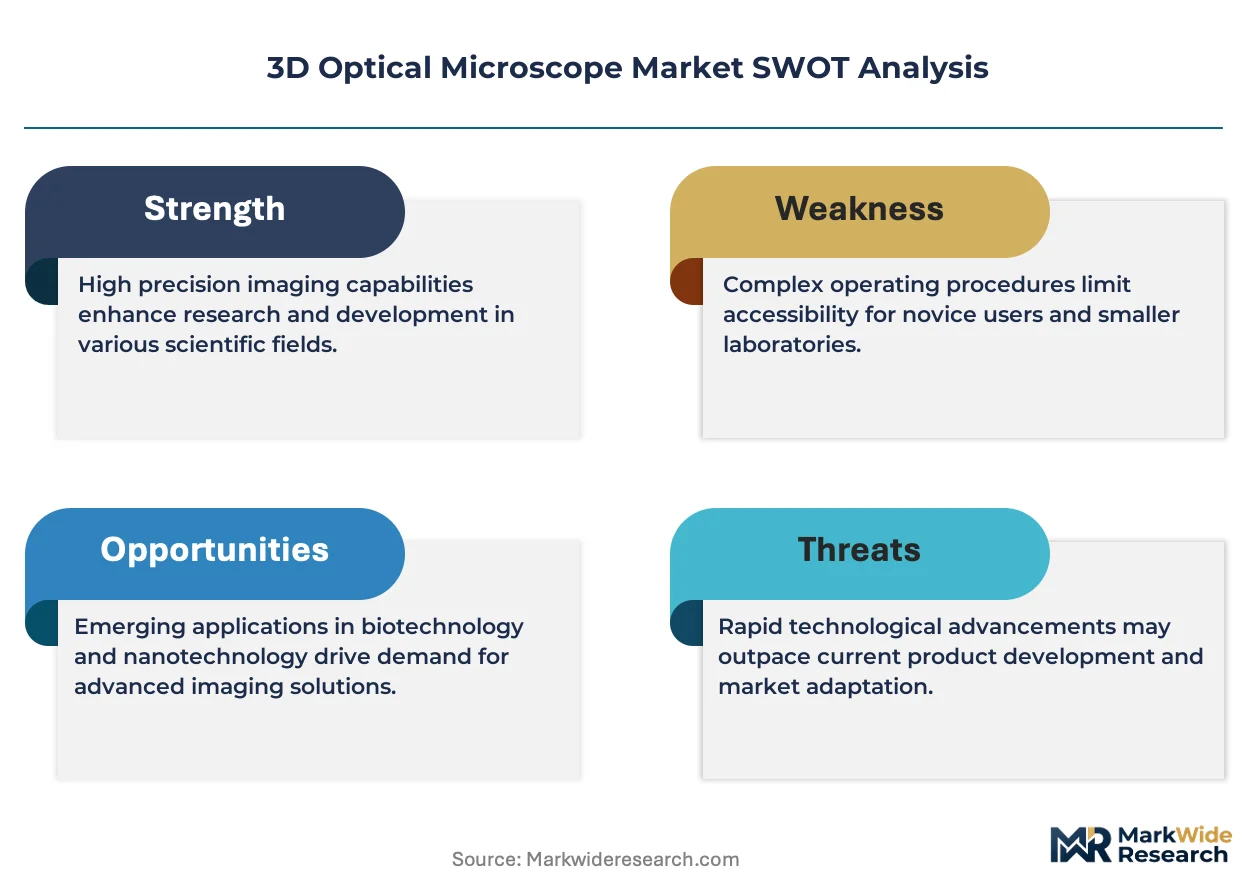
Node shrinkage below 7nm in semiconductor fabrication is forcing metrology vendors to recalibrate resolution specifications and service architectures around fab uptime guarantees rather than discrete hardware sales.
Growth Catalysts
- Sub-7nm node migration:Taiwan, South Korea, and United States foundries are expanding capital expenditure on inspection equipment to maintain yield rates at advanced process nodes.
- REACH compliance deadlines:European Union material disclosure requirements for imported instruments are accelerating replacement cycles for older systems with non-compliant optical coatings.
- Cryo-EM correlation workflows:Structural biology laboratories are integrating super-resolution optical registration to bridge light and electron microscopy data sets.
Market Restraints
- Specialized objective lens supply:Japanese and German optical glass suppliers concentrate premium objective manufacturing, creating single-source vulnerability for sub-100nm axial resolution systems.
- Cleanroom infrastructure requirements:Confocal and interferometric platform assembly now demands ISO Class 5-7 environments, elevating fixed cost thresholds for new entrants.
- Atomic force microscopy substitution:AFM vendors are bundling 3D topography capabilities at price points that compress entry-level optical system margins.
Strategic Opportunities
- India biopharma expansion:CDSCO regulatory harmonization with ICH standards is accelerating contract research organization investment in GMP-compliant imaging infrastructure.
- GB standards alignment:China's electronic equipment safety mandates are creating compliance-driven replacement demand for imported laboratory instruments.
- Structured light-photogrammetry convergence:Industrial quality control departments are adopting hybrid optical systems that merge microscopic and macroscopic 3D capture in single workflows.
Industry Challenges
- Interferometry specialist scarcity:The pool of engineers capable of calibrating sub-nanometer repeatability systems is insufficient to match installation growth in East Asian foundry clusters.
- FDA 510(k) pathway complexity:Diagnostic microscopy system classifications require clinical validation timelines that extend product launch cycles by 18-24 months for medical end users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Optical Microscope Market |
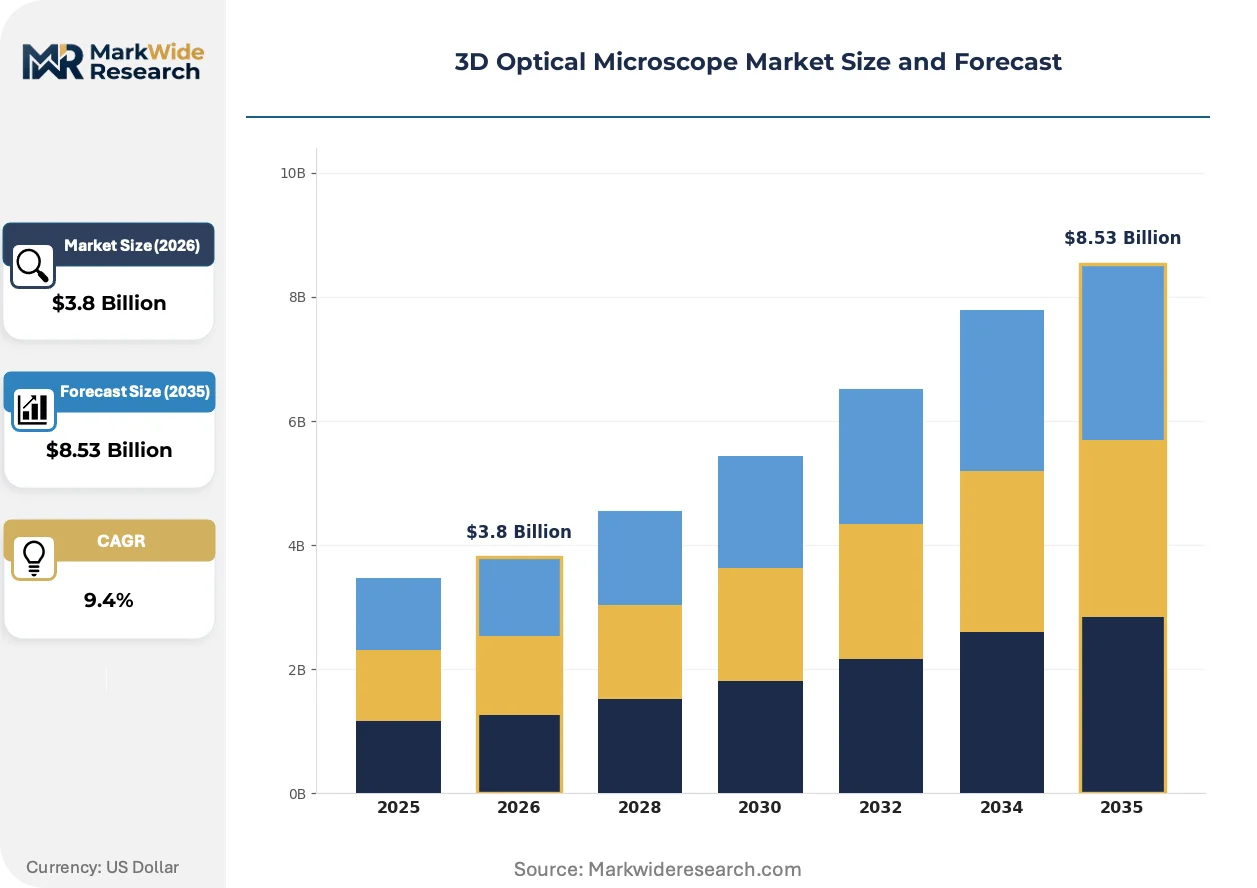
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
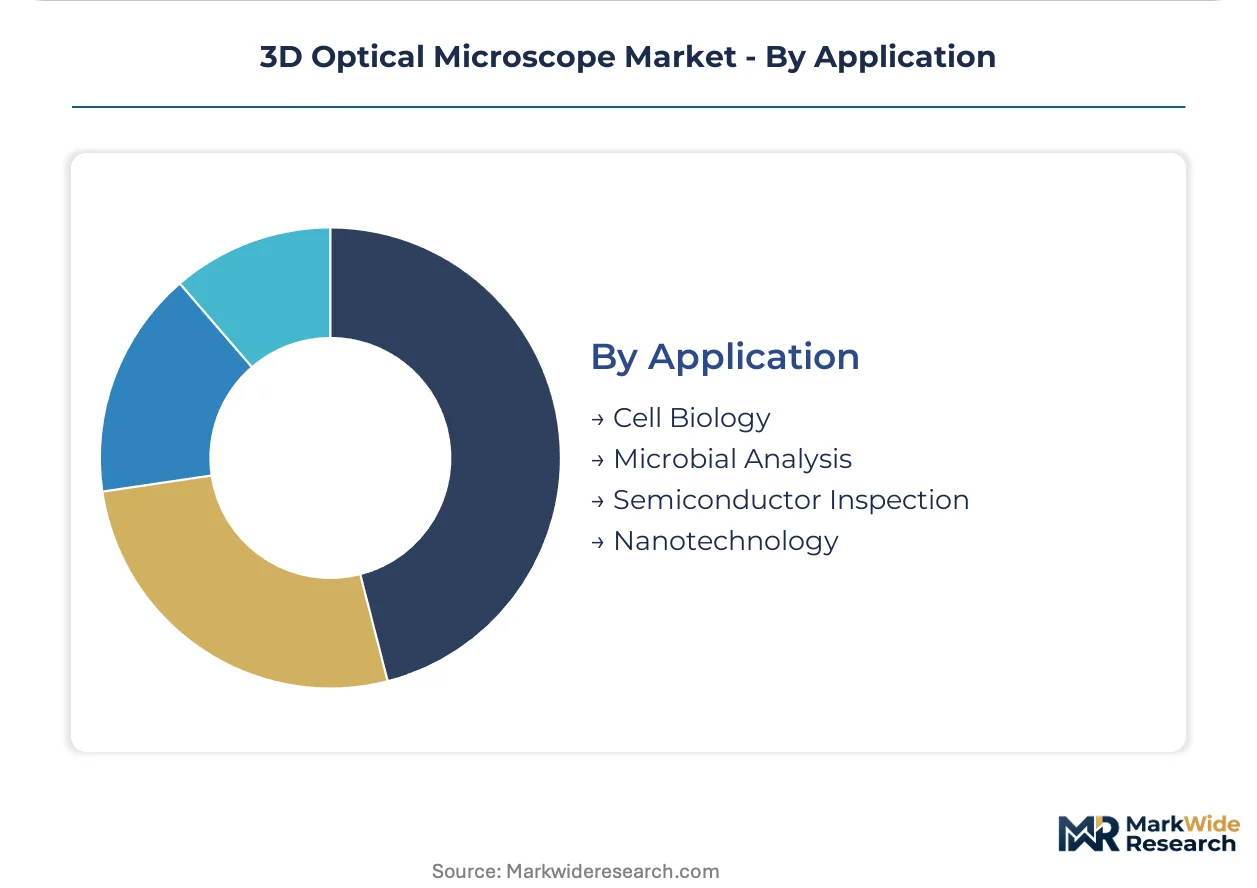
| Segmentation | Product Type: Confocal Microscopes, Light Sheet Microscopes, Multi-Photon Microscopes, Super-Resolution Microscopes End User: Academic Institutions, Medical Diagnostics, Industrial Research, Material Sciences Technology: Imaging Analysis, Fluorescence Microscopy, 3D Reconstruction, Image Processing Application: Cell Biology, Microbial Analysis, Semiconductor Inspection, Nanotechnology |
| Companies Covered | Bruker Corp., Carl Zeiss AG, Keyence Corp., Hirox Co. Ltd., Leica Microsystems, Olympus Corp., Hitachi High-Technologies Corp., Nikon Corp., Danaher Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Optical Microscope Market Emerging Trajectories
Instrumentation architecture is pivoting from standalone hardware to integrated data pipelines where optical capture, AI-assisted segmentation, and enterprise LIMS connectivity ship as unified platforms rather than modular add-ons.
Super-resolution localization microscopy is fragmenting the traditional confocal installed base as neuroscience and materials science departments prioritize single-molecule precision over multi-purpose flexibility. Research institutes in Germany and the Netherlands are deploying these systems at twice the rate of general-purpose alternatives. The technology is fragmenting vendor R&D budgets toward proprietary fluorophore development and specialized detector arrays rather than incremental objective lens improvements.
EPA hazardous substance restrictions on optical coating chemistries are forcing reformulation of anti-reflective and beam-splitter compounds used in ultraviolet-visible systems. Coating suppliers in the United States must now qualify alternative chemistries through extended durability testing. Semiconductor inspection applications face the steepest compliance costs due to stringent uptime requirements that preclude experimental coating batches.
Service unbundling is accelerating as foundry customers negotiate separate contracts for hardware, software maintenance, and metrology data analytics. Original equipment manufacturers in Taiwan and South Korea are responding with subscription-based calibration certification programs that decouple instrument ownership from performance guarantees. This shift is most pronounced in 24-hour production environments where downtime penalties exceed capital depreciation schedules.
3D Optical Microscope Market Segmentation
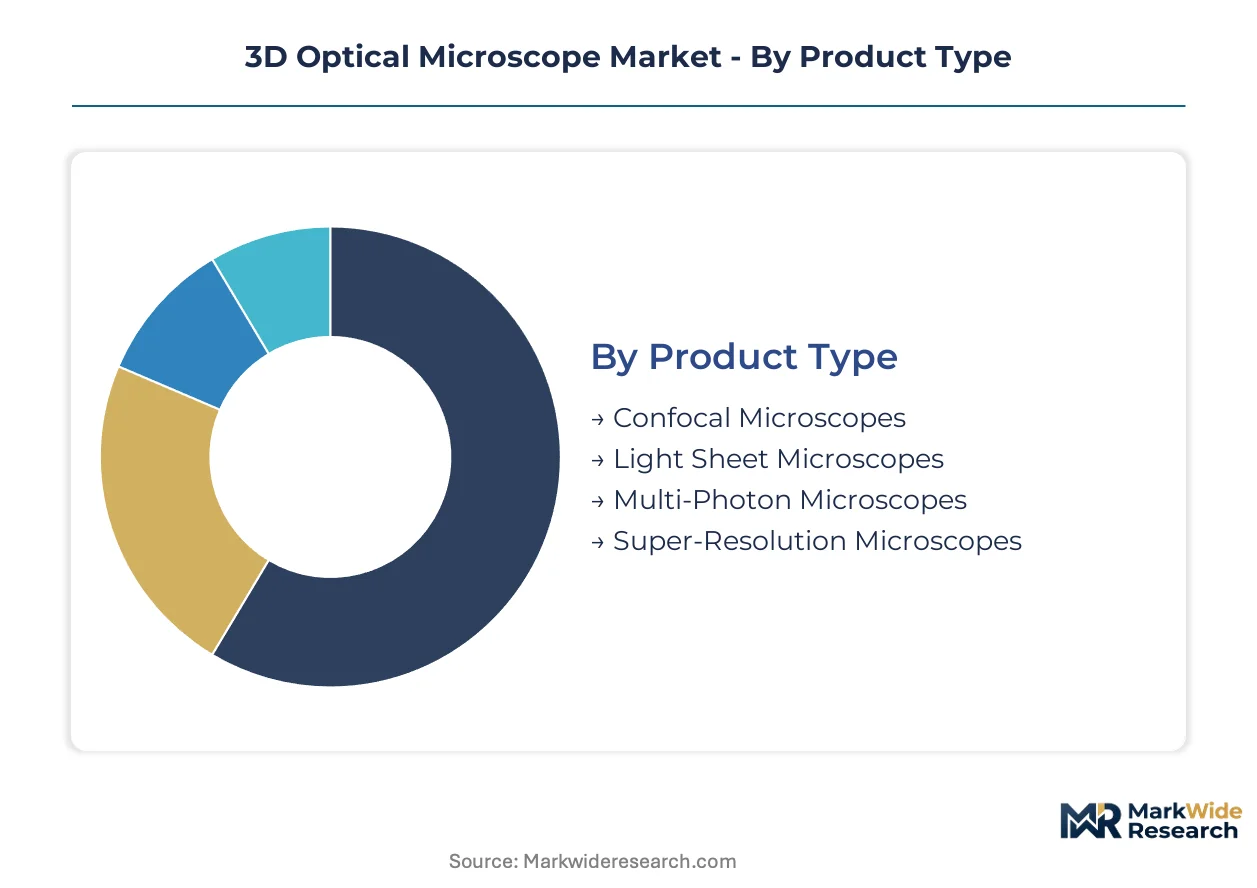
Segmentation in 3D optical microscopy reveals how technical specifications, compliance requirements, and end-use workflows fragment procurement patterns across scientific and industrial buyers. Channel strategies diverge sharply between capital-intensive semiconductor fabs and grant-funded academic laboratories.
Product Type:
Confocal platforms move through direct sales engineers who embed at customer sites for configuration, while super-resolution systems route through specialized distributors with applications expertise in structural biology.
- Confocal Microscopes:Laser scanning systems with pinhole-based optical sectioning achieve axial resolutions near 100 nanometers for live-cell imaging and wafer metrology. Taiwan and South Korea foundries sustain premium procurement through 24-hour uptime service contracts that bundle hardware with predictive maintenance analytics.
- Super-Resolution Microscopes:Localization techniques including STED and STORM break the diffraction limit to resolve structures below 50 nanometers. Research institutes in Germany and the Netherlands deploy these at twice the rate of general-purpose alternatives as cryo-EM correlation workflows demand precise optical registration.
- Light Sheet Microscopes:Selective plane illumination enables rapid volumetric imaging of large specimens with reduced phototoxicity. Developmental biology departments prioritize these for long-term live imaging of model organisms.
- Multi-Photon Microscopes:Nonlinear excitation using femtosecond pulsed lasers penetrates deep into scattering tissue. Neuroscience facilities with two-photon intravital imaging requirements drive specialized configurations.
By volume, confocal systems lead due to mature service networks and software ecosystems. By growth pace, super-resolution variants are climbing the fastest as single-molecule precision displaces multi-purpose flexibility in materials science and neuroscience departments.
End User:
Procurement authority and budget cycles create four distinct customer archetypes with incompatible sales motion requirements and support expectations.
- Academic Institutions:Grant-funded laboratories prioritize modular upgrade paths and open-source software compatibility. Funding agency peer review processes favor instruments with demonstrated publication track records in high-impact journals.
- Semiconductor Inspection:Fabs require sub-nanometer repeatability certifications and fab-wide metrology data integration. Equipment purchase decisions centralize with yield engineering teams rather than individual researchers.
- Medical Diagnostics:Clinical laboratories face FDA 510(k) pathway complexity that extends product launch cycles. CAP proficiency testing requirements shape instrument validation protocols.
- Material Sciences:Industrial R&D departments balance resolution specifications against throughput metrics for quality control workflows. Corrosion and failure analysis applications demand ruggedized environmental enclosures.
Semiconductor inspection commands the highest average selling prices. Academic institutions represent the largest installed base expansion opportunity through national research infrastructure programs.
Technology:
Software and algorithmic capabilities increasingly determine competitive positioning as hardware commoditizes across objective lens and detector suppliers.
- 3D Reconstruction:Deconvolution and structured illumination algorithms transform 2D optical sections into volumetric models. Computational demands drive GPU-accelerated workstation bundling with high-end systems.
- Image Processing:Real-time denoising and segmentation pipelines reduce raw data storage requirements. AI-assisted feature recognition is displacing manual analysis in high-throughput screening applications.
- Imaging Analysis:Quantitative morphometry and intensity profiling tools enable standardized measurement protocols. GMP-compliant laboratories require 21 CFR Part 11 validated software modules.
- Fluorescence Microscopy:Spectral unmixing and lifetime imaging capabilities expand multiplexing capacity. Proprietary fluorophore development fragments vendor R&D budgets away from hardware improvements.
Image processing capabilities show the steepest investment trajectory as foundry customers negotiate separate contracts for metrology data analytics.
Application:
Workflow integration requirements and regulatory exposure create distinct performance specifications and service architectures.
- Semiconductor Inspection:Wafer metrology at sub-7nm nodes demands interferometric repeatability below 0.1 nanometers. Node shrinkage is forcing vendors to recalibrate resolution specifications around fab uptime guarantees.
- Cell Biology:Live imaging protocols require environmental control modules for temperature, humidity, and gas exchange. Long-term time-lapse studies prioritize photostability over absolute resolution.
- Nanotechnology:Graphene and 2D material characterization combines optical registration with correlative electron microscopy. Cleanroom compatibility constrains instrument form factors.
- Microbial Analysis:High-throughput colony screening and antibiotic susceptibility testing drive automation integration. Clinical microbiology laboratories require LIMS connectivity for epidemiological surveillance.
Semiconductor inspection concentrates margin pools through premium service contracts. Cell biology applications sustain the broadest vendor participation due to diverse experimental requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in East Asian manufacturing clusters while European procurement cycles stretch under REACH compliance burdens. Taiwan and South Korea fabs command premium service terms through 24-hour uptime guarantees. German and Dutch research institutes absorb longer validation timelines for super-resolution platforms.
Taiwan
TSMC and United Microelectronics drive metrology capital expenditure as 3nm production ramps in Hsinchu Science Park. The National Development Council's semiconductor initiative channels subsidies toward inspection infrastructure. Tainan and Taichung foundry clusters now specify sub-nanometer repeatability certifications as standard procurement terms.
South Korea
Samsung Foundry and SK Hynix expand 3D optical microscope deployment for GAA transistor inspection at Pyeongtaek and Yongin complexes. MFDS medical device regulations shape diagnostic system import protocols for Seoul-based clinical laboratories. Busan equipment distributors report 40% longer installation cycles due to cleanroom infrastructure verification requirements.
United States
Intel's Arizona and Ohio fab investments sustain demand for interferometric platforms with fab-wide data integration. FDA 510(k) pathways extend product launch timelines for diagnostic microscopy vendors serving Boston and San Francisco biotech corridors. EPA hazardous substance restrictions on optical coatings force reformulation of ultraviolet-visible system components.
Germany
Max Planck Institutes and Helmholtz Centers deploy super-resolution systems for cryo-EM correlation workflows at twice the rate of general-purpose alternatives. ECHA REACH compliance deadlines accelerate replacement cycles for non-compliant imported instruments. Munich and Heidelberg microscopy clusters concentrate service engineer training programs for sub-nanometer calibration specialization.
China
Yangtze Memory Technologies and SMIC expand domestic metrology procurement as node development targets 7nm production. MIIT GB standards for electronic equipment safety tighten material disclosure requirements for imported laboratory instruments. Shanghai and Beijing research parks prioritize structured light-photogrammetry convergence for industrial quality control applications.
3D Optical Microscope Market Vendor Landscape
Concentration sits with diversified metrology conglomerates and specialized optics houses that control captive supply of objective lens grinding. The vendor base splits between photonics specialists requiring cleanroom-grade manufacturing infrastructure and diversified instrument platforms bundling multiple modalities. Strategic archetypes include atomic force microscopy cross-sellers, direct-embedded sales engineers, and vertically integrated lens manufacturers. Competitive moves center on service unbundling into subscription calibration programs and AI-assisted segmentation software bundling.
Among diversified metrology platforms, Bruker Corp., Keyence Corp., and Nikon Corp. occupy distinct positioning vectors. Bruker exemplifies the cross-selling archetype leveraging installed atomic force microscopy bases for 3D optical system penetration. Keyence anchors the direct-embedded sales model through configuration software deployment at customer sites. Nikon represents vertical integration into proprietary objective lens production. Carl Zeiss AG and Leica Microsystems sit within the premium optics heritage tier, while Danaher Corp. occupies the life sciences conglomerate position. Olympus Corp. and Hitachi High-Technologies Corp. exemplify diversified electronics-to-instrument pivots, with Hirox Co. Ltd. representing specialized digital microscopy focus.
| Leading Market Players |
|---|
| Bruker Corp. |
| Carl Zeiss AG |
| Keyence Corp. |
| Hirox Co. Ltd. |
| Leica Microsystems |
| Olympus Corp. |
| Hitachi High-Technologies Corp. |
| Nikon Corp. |
| Danaher Corp. |
| Others |
Supply Flow & Price Mechanics
Cleanroom-grade manufacturing infrastructure requirements in East Asian foundry clusters create scale thresholds that compress price floors for sub-100nm axial resolution systems while elevating entry barriers for non-integrated competitors. Taiwan and South Korean fabs leverage 24-hour uptime guarantees to negotiate subscription-based calibration certifications that decouple hardware ownership from performance guarantees, reshaping how vendors capture lifetime value.
Pricing Analysis
The customization-premium spread separates configured-to-order confocal platforms from standard laboratory systems by factors reflecting cleanroom assembly costs and interferometric calibration specialization. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling intensity. Pricing pressure stems from atomic force microscopy vendors bundling 3D topography capabilities at compressed margins. Academic institutions exhibit highest price sensitivity through grant-funded procurement cycles, while semiconductor fabs absorb premium tiers for uptime guarantees.
Supply Chain Analysis
Specialized objective lens grinding capacity concentrated in Japan and Germany creates single-source vulnerability for sub-nanometer repeatability systems. Optical glass supply draws from Schott AG and Ohara Corporation formulations, while detector arrays source from Sony and Hamamatsu Photonics fabrication lines. Tariff exposure on dual-use metrology equipment under export control expansions threatens component flow into Chinese foundry customers. Distribution runs through direct-embedded sales engineers at premium tiers and specialized distributors for super-resolution platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Atomic force microscopy substitution represents the primary displacement threat that 3D optical incumbents must navigate through service architecture differentiation and software ecosystem lock-in.
For Market Incumbents: Compound defensive positioning by embedding AI-assisted segmentation software as unified platform bundles rather than modular add-ons, and by securing captive supply of proprietary objective lens grinding through backward integration into Japanese or German optical houses. AFM cross-sellers threaten materials science departments where Bruker leverages installed bases; certification investment in FDA 510(k) pathways protects medical diagnostics share. For New Entrants and Emerging Players: Service-layer gaps in interferometry specialist calibration capacity across East Asian foundry clusters present white-space entry points. Target India's biopharma expansion where CDSCO harmonization accelerates GMP-compliant imaging infrastructure investment, and pursue structured light-photogrammetry convergence for industrial quality control departments seeking hybrid microscopic-macroscopic capture. Go-to-market through applications-specialized distributors with structural biology expertise bypasses direct sales engineer cost structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated optics houses with captive lens supply and established fab service networks over diversified conglomerates managing multiple modality portfolios. Long-term viability hinges on AI-assisted analysis software ownership and subscription calibration revenue streams. Watch for export control expansions on dual-use metrology equipment as the signal indicating customer eligibility restrictions in advanced manufacturing economies.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Calibration Certification | Decouples instrument ownership from uptime guarantees for Taiwan and South Korean fabs. |
| AI-Assisted Segmentation Software | Bundles optical capture with enterprise LIMS connectivity as unified data pipelines. |
| Proprietary Fluorophore Development | Fragments R&D budgets toward specialized detector arrays for super-resolution localization. |
| REACH Compliance Reformulation | Forces optical coating chemistry alternatives through extended durability testing protocols. |
| Cryo-EM Correlation Integration | Bridges light and electron microscopy data sets for structural biology laboratories. |
Methodological Framework
A standing panel of yield engineering directors, metrology procurement managers, biomedical imaging specialists, and optical coating suppliers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEMI equipment market data, ECHA REACH substance restriction databases, FDA 510(k) submission records, and foundry capital expenditure disclosures. Bottom-up instrument shipment modeling triangulated against top-down semiconductor inspection equipment spending analysis.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include product type, end user archetype, technology capability, and application workflow. CAGRs were derived from installation base expansion rates and replacement cycle compression factors. Forecast inputs incorporated node shrinkage timelines below 7nm and cryo-EM correlation workflow adoption curves.
Forecasts assume regulatory continuity in FDA device classification and ECHA REACH compliance regimes; material policy shifts would require re-modeling. Specific risk factors include export control expansions on dual-use metrology equipment and EPA hazardous substance restrictions on optical coating chemistries. Practitioners should keep alternative scenarios live as semiconductor fabrication node roadmaps and structural biology instrumentation budgets evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Photonic Crystals Market
Optics
Global Fiber Optic Sensors Market
Optics
North America Optical Imaging Market
Optics
Fiber Optic Amplifier Market
Optics
Optical Telescope Market
Optics
Digital Holographic Microscopy Market
Optics
Optical Fiber Raw Material Market
Optics
Smart Photochromic Lenses Market
Optics
Beam Combining Optics Market
Optics
Anomaloscope Market
Optics
Interchangeable Lens Market
Optics
Global Fiber Optic Components Market
Optics
AR and VR Lens Market
Optics
Optical Receivers Market
Optics
Fiber Optics Market
Optics
Tunable Laser Market