
 North America Optical Imaging Market | 2026-2036
North America Optical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Optical Imaging Market Outlook
CE marking reciprocity under the FDA-MDSAP mutual recognition framework is rotating vendor eligibility across the North America Optical Imaging Market. Carl Zeiss Meditec AG leverages its captive optics foundry to control supply of high-NA objectives for ophthalmology suites. Abbott Laboratories anchors its position through dedicated R&D spend on catheter-integrated photoacoustic platforms. Heidelberg Engineering GmbH specializes in confocal scanning laser technology for glaucoma progression monitoring.
Optical imaging denotes non-invasive techniques that capture photon-based contrast from biological tissues, typically employing wavelengths between 400 nm and 1700 nm to resolve morphological, functional, or molecular information. These systems rely on coherent light sources, scanning galvanometers, and avalanche photodiode detectors to construct tomographic or planar images for clinical diagnosis and preclinical research. Frequency-domain OCT dominates hospital procurement budgets due to superior axial resolution and established reimbursement codes, while photoacoustic imaging represents the fastest-expanding technology segment as hybrid systems penetrate oncology intraoperative workflows. Among applications, ophthalmology occupies the deepest installed base, though neurology applications for blood-brain barrier imaging are capturing expanding research funding pools.
FDA 510(k) premarket notification requirements and Health Canada Medical Device License standards govern commercial entry, with both agencies intensifying scrutiny of software-as-medical-device algorithms embedded in AI-enhanced optical platforms. The MDR-to-FDA harmonization gap creates compliance friction for European manufacturers seeking parallel North American clearance. Stakeholders must track evolving CMS coverage determinations for optical biopsy techniques to anticipate reimbursement-driven demand inflections.
Market Dynamics
Fluorescence-guided surgical systems are compressing hospital capital cycles across the United States, with procurement committees prioritizing intraoperative precision over incremental hardware upgrades. This technology pull is restructuring vendor qualification criteria and shortening incumbent equipment replacement timelines.
Growth Catalysts
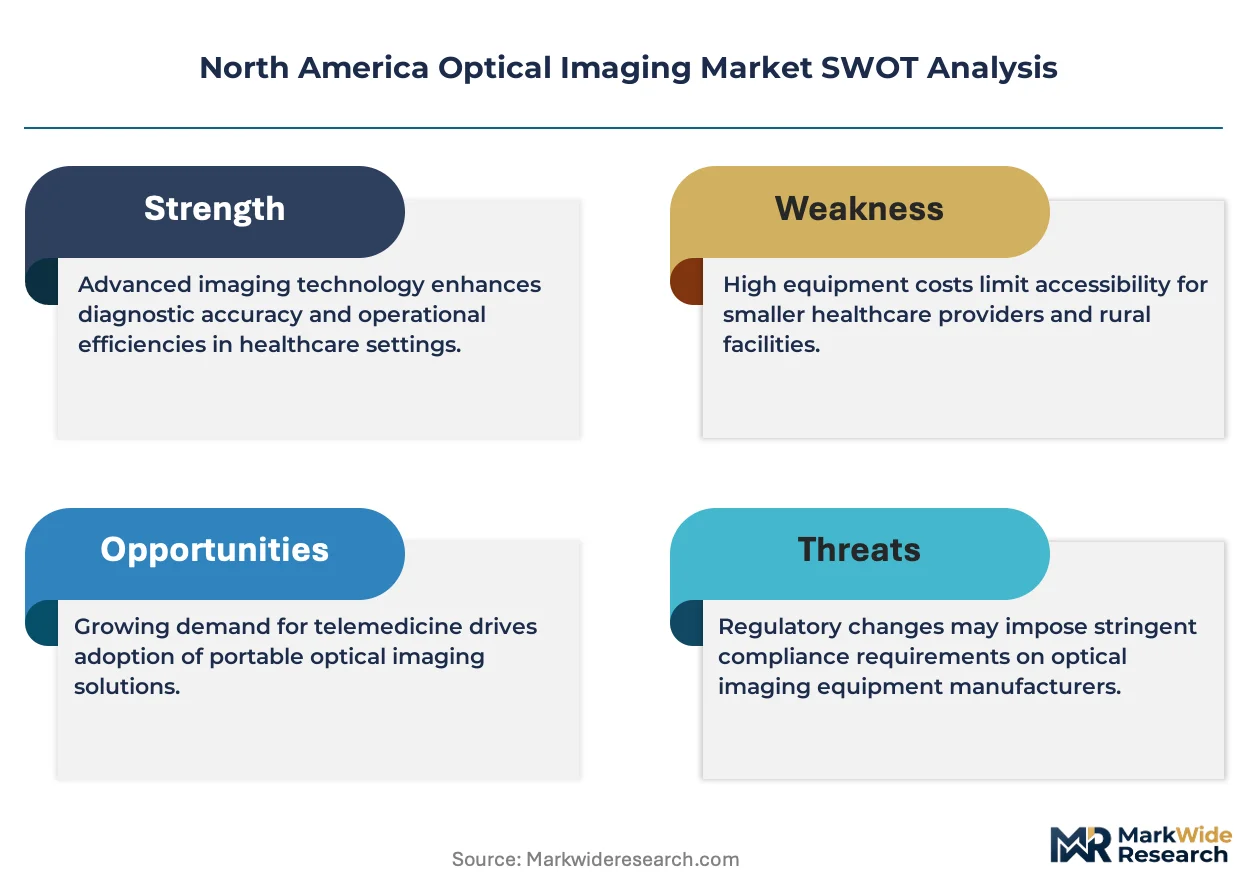
- MDSAP mutual recognition:CE marking reciprocity under the FDA-MDSAP framework accelerates vendor eligibility rotation for European manufacturers entering the United States and Canada.
- Photoacoustic platform R&D:Catheter-integrated photoacoustic systems attract dedicated research funding from oncology surgical suites seeking hybrid intraoperative guidance.
- California biomedical corridor:Research institutes clustering near Stanford and UCSF campuses concentrate demand pull for confocal scanning laser ophthalmology systems.
Market Restraints
- High-NA objective supply concentration:Captive optics foundry control by dominant vendors limits second-source availability for precision ophthalmology hardware.
- MDR-to-FDA harmonization friction:European manufacturers face compliance gaps when pursuing parallel North American clearance, extending time-to-market.
- Software-as-medical-device scrutiny:FDA and Health Canada intensify validation requirements for AI-enhanced optical platforms, elevating documentation burden.
Strategic Opportunities
- Neurology blood-brain barrier imaging:Research funding pools for functional neuroimaging applications remain underpenetrated relative to ophthalmology's installed base.
- CMS coverage determination tracking:Optical biopsy technique reimbursement decisions create demand inflection points for vendors monitoring Medicare administrative channels.
- Frequency-domain OCT standardization:Established reimbursement codes for axial resolution systems enable predictable hospital budget allocation versus emerging photoacoustic categories.
Industry Challenges
- AI algorithm validation timelines:Software-as-medical-device submissions require extensive clinical evidence packages, stretching regulatory affairs capacity.
- Legacy system integration complexity:Hybrid photoacoustic platforms must interface with existing surgical navigation infrastructure, complicating deployment.
- Specialized photonics talent scarcity:Avalanche photodiode detector design and coherent light source engineering skills concentrate in limited geographic pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Optical Imaging Market |
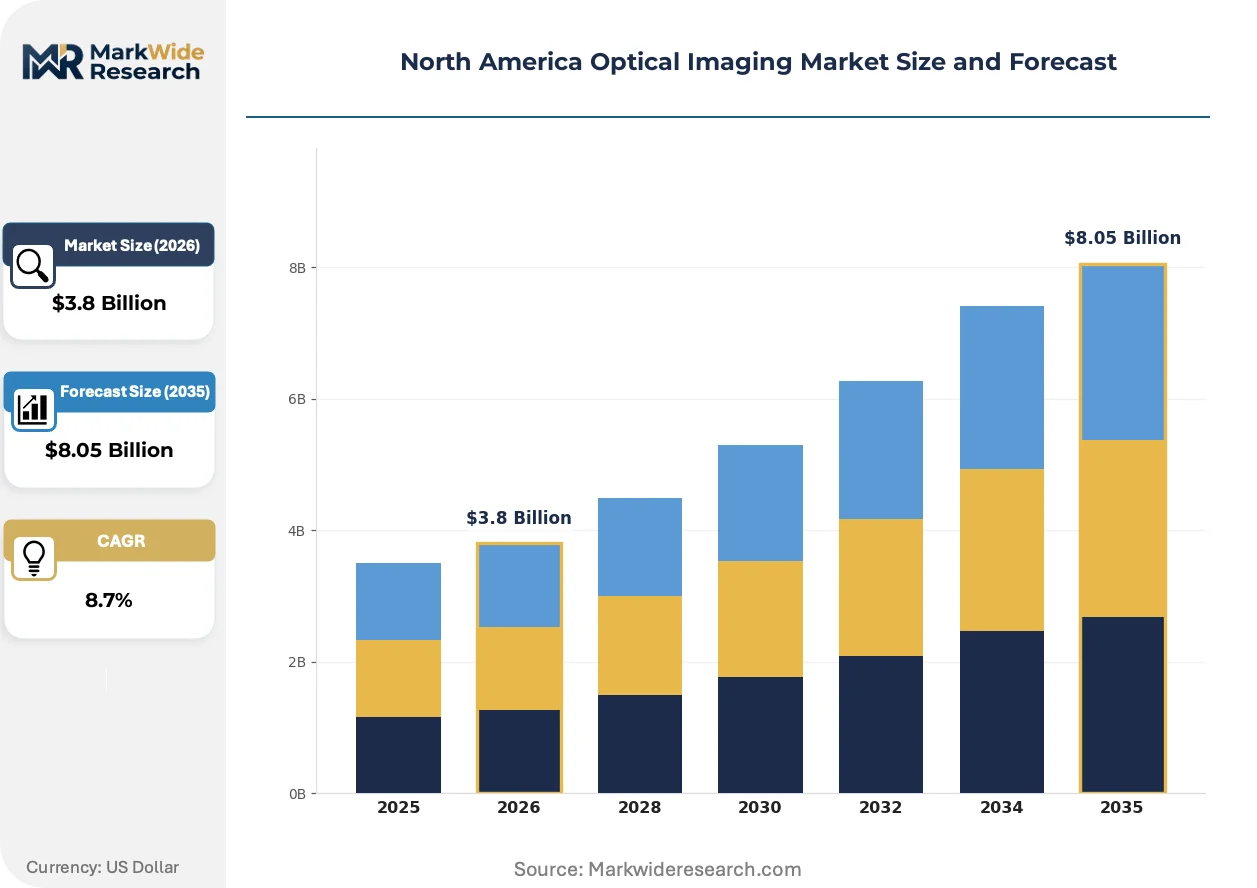
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OCT, Fundus Cameras, Fluorescence Imaging, Multi-Photon Microscopy End User: Hospitals, Diagnostic Labs, Research Institutes, Clinics Technology: Time-domain, Frequency-domain, Hybrid, Photoacoustic Application: Neurology, Oncology, Cardiology, Ophthalmology |
| Companies Covered | Carl Zeiss Meditec AG, Topcon Corporation, Canon Inc., GE Healthcare, Heidelberg Engineering GmbH, Abbott Laboratories, Nidek Co., Ltd., Bruker Corporation, PerkinElmer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Optical Imaging Market Strategic Shifts
Photon-based contrast capture systems are fragmenting across wavelength-specific applications, with vendors pursuing divergent hardware architectures for clinical versus research end-uses. This specialization pressure is reshaping R&D allocation and partnership strategies.
Frequency-domain optical coherence tomography is bifurcating into hospital-grade systems with established reimbursement pathways and research-grade platforms with customizable scan protocols. Academic medical centers in Boston and Houston are adopting the latter for glaucoma progression studies. This split is compressing vendor R&D budgets between regulatory-heavy clinical submissions and flexible research configurations.
FDA 510(k) clearance pathways are compressing premarket notification timelines for optical imaging hardware while expanding documentation requirements for embedded AI algorithms. Device manufacturers are responding by segregating software validation teams from hardware engineering functions. The ophthalmology segment bears the heaviest compliance burden due to established predicate device density.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, forcing vendors to compete on discrete maintenance pricing. This disintermediation is most visible in California's integrated delivery networks, where Stanford Health Care and UCSF Health negotiate service terms separately from system acquisitions. Independent service organizations are capturing maintenance revenue previously retained by original equipment manufacturers.
North America Optical Imaging Market Segmentation
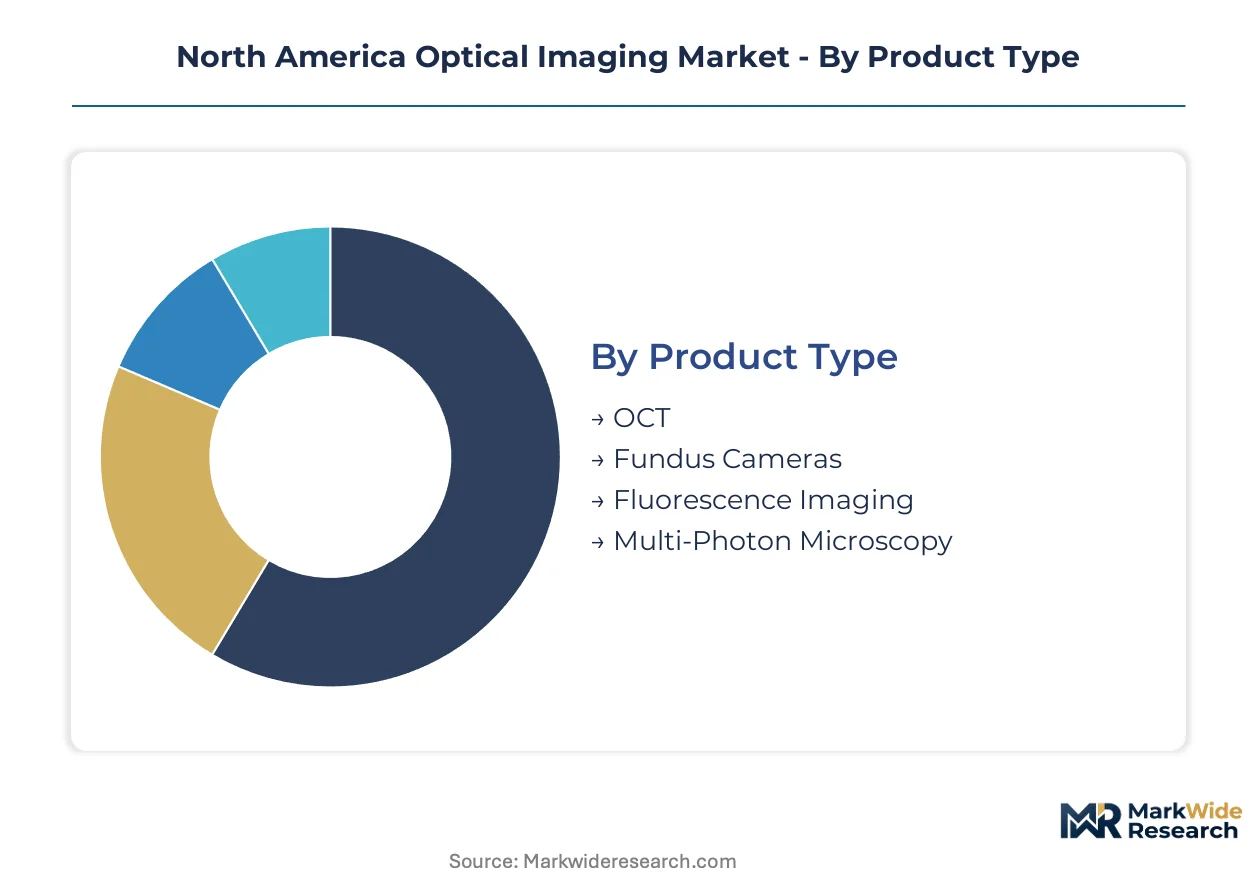
Optical imaging vendors configure product portfolios around distinct procurement channels, with hospital capital committees, research grant flows, and clinic reimbursement pathways each favoring different technical specifications. Segment-level channel strategies determine pricing architecture and service bundling across the North American market.
Product Type:
Hospital procurement channels favor systems with established reimbursement codes, while research institutes source through grant-funded capital equipment programs with customizable specifications.
- OCT:Frequency-domain optical coherence tomography systems deliver sub-micron axial resolution using low-coherence interferometry with spectrometer-based detection. Hospital ophthalmology departments in California and Massachusetts concentrate procurement around systems with validated glaucoma progression algorithms. Established CMS coverage codes compress sales cycles versus emerging modalities.
- Fluorescence Imaging:Intraoperative fluorescence-guided surgical platforms employ indocyanine green or fluorescein contrast agents with near-infrared excitation sources. United States oncology surgical suites are expanding capital allocation for tumor margin delineation systems, compressing incumbent equipment replacement timelines.
- Fundus Cameras:Non-mydriatic retinal imaging devices with automated field capture protocols serve high-throughput diabetic retinopathy screening programs.
- Multi-Photon Microscopy:Femtosecond-pulsed laser excitation systems enable deep-tissue imaging with reduced phototoxicity for neuroscience research applications.
OCT dominates installed base. Fluorescence imaging is where expansion concentrates.
End User:
Customer-type concentration shapes service contract structures, with integrated delivery networks demanding unbundled maintenance pricing that independent service organizations exploit.
- Hospitals:Academic medical centers and community hospital systems deploy capital equipment through value-analysis committees with 5-7 year depreciation schedules. Stanford Health Care and UCSF Health negotiate service terms separately from system acquisitions, disintermediating original equipment manufacturers from recurring revenue streams.
- Research Institutes:Grant-funded institutions near Stanford and UCSF campuses prioritize customizable scan protocols over regulatory-heavy clinical configurations. Boston and Houston academic medical centers adopt research-grade platforms for glaucoma progression studies with flexible software architectures.
- Diagnostic Labs:High-volume retinal screening operations require automated image capture with minimal operator training.
- Clinics:Private ophthalmology practices concentrate demand for compact, reimbursable diagnostic systems with rapid patient throughput.
Hospitals anchor revenue concentration. Research institutes represent the steepest expansion trajectory for vendor R&D partnerships.
Technology:
Technology maturity tiers determine regulatory pathway selection, with predicate-rich categories clearing through abbreviated 510(k) channels while novel architectures face De Novo or PMA scrutiny.
- Frequency-domain:Spectral-domain detection with Fourier-transform reconstruction delivers superior signal-to-noise ratios versus time-domain predecessors. Established predicate device density in ophthalmology concentrates FDA submission resources, though embedded AI algorithms trigger expanded software-as-medical-device documentation requirements.
- Photoacoustic:Hybrid acoustic-optical detection platforms combine pulsed laser excitation with ultrasonic transducer arrays for deep-tissue functional imaging. Catheter-integrated configurations attract dedicated oncology R&D funding as intraoperative guidance tools, though integration with existing surgical navigation infrastructure complicates deployment.
- Time-domain:Mechanical scanning mirror architectures with single-point detection persist in legacy installed bases requiring maintenance support.
- Hybrid:Multi-modal systems combining OCT with angiography or autofluorescence capabilities command premium positioning in academic medical centers.
Frequency-domain systems anchor hospital procurement budgets. Photoacoustic platforms are gaining share fastest through oncology surgical suite penetration.
Application:
Application-specific reimbursement determinations from CMS create demand inflection points that vendors monitor through Medicare administrative channels.
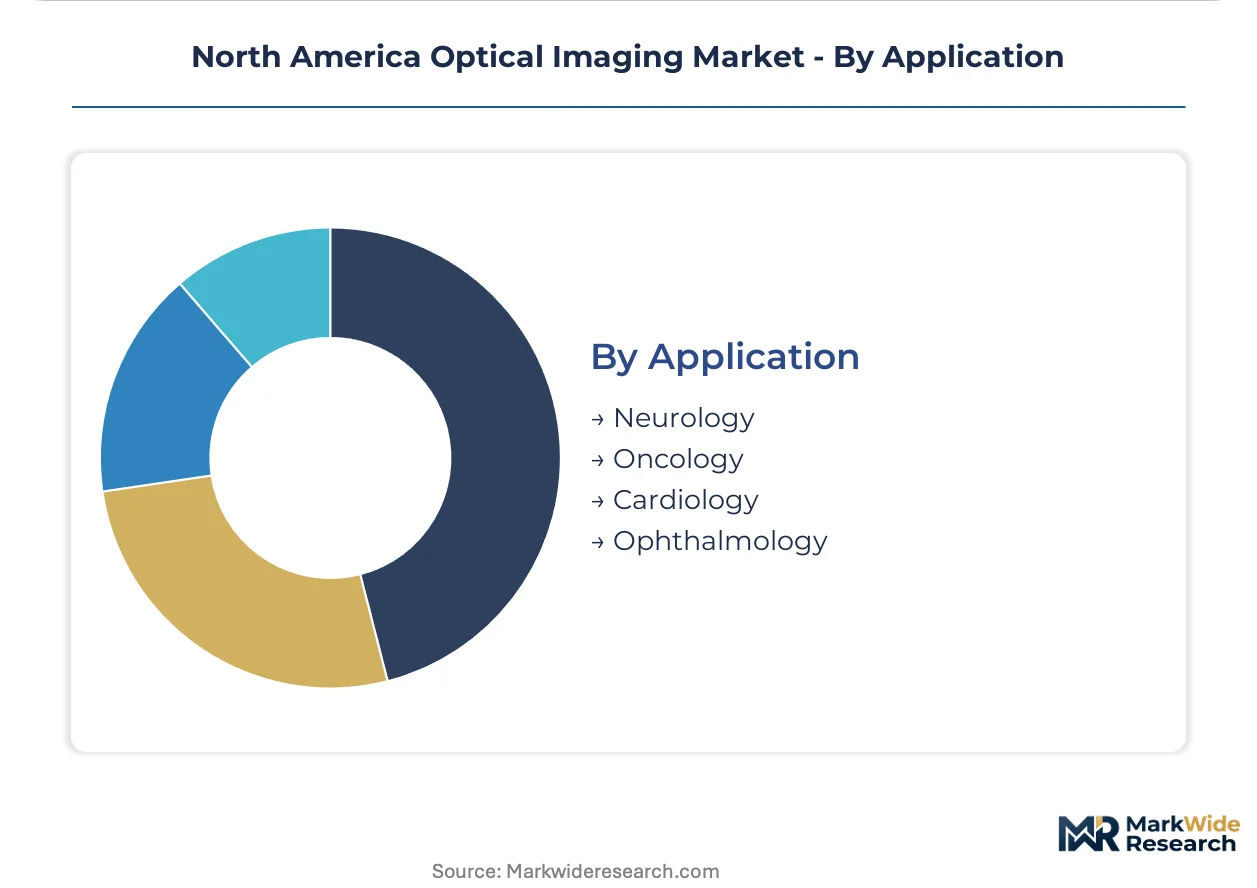
- Ophthalmology:Retinal and anterior segment imaging constitutes the deepest installed base with mature reimbursement infrastructure. Glaucoma progression monitoring and diabetic retinopathy screening drive replacement demand, with confocal scanning laser technology capturing specialized niches.
- Neurology:Blood-brain barrier imaging applications remain underpenetrated relative to ophthalmology's scale, though functional neuroimaging research funding pools are expanding. Photoacoustic and multi-photon modalities enable vascular dynamics studies with cellular resolution.
- Oncology:Intraoperative tumor margin assessment and sentinel lymph node mapping concentrate fluorescence imaging demand.
- Cardiology:Intravascular OCT and photoacoustic platforms serve plaque characterization applications with specialized catheter engineering requirements.
Ophthalmology dominates installed base. Neurology is where expansion concentrates for research-funded platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and Health Canada Medical Device License standards compress time-to-market for optical imaging vendors across North America, while procurement committees at academic medical centers concentrate demand in specific metropolitan corridors.
United States
Stanford Health Care and UCSF Health negotiate unbundled service terms separately from system acquisitions, disintermediating original equipment manufacturers from recurring revenue streams. FDA intensifies software-as-medical-device scrutiny for AI-enhanced platforms, elevating documentation burdens for embedded algorithms. California's biomedical corridor clusters research institutes near Stanford and UCSF campuses, concentrating demand pull for confocal scanning laser ophthalmology systems.
Canada
Health Canada Medical Device License standards govern commercial entry for fluorescence-guided surgical systems entering oncology surgical suites. MDSAP mutual recognition framework accelerates vendor eligibility rotation for European manufacturers seeking parallel North American clearance. Toronto and Vancouver academic medical centers adopt research-grade platforms with customizable scan protocols for glaucoma progression studies.
Mexico
Private ophthalmology practices in Mexico City and Monterrey concentrate demand for compact, reimbursable diagnostic systems with rapid patient throughput. Federal Commission for Protection against Sanitary Risk (COFEPRIS) registration requirements create compliance friction for imported optical biopsy devices. Northern border states absorb cross-border referral flows from US-based diagnostic networks seeking cost-competitive retinal screening.
North America Optical Imaging Market Competitive Environment
Listed leaders compete with private specialists across regulatory submission capacity and service contract pricing. The vendor base concentrates around three tiers: diversified healthcare conglomerates with captive optics foundries, mid-scale device specialists with regional regulatory expertise, and research-grade platform developers serving grant-funded academic centers. Strategic archetypes include integrated optics manufacturers controlling high-NA objective supply, hybrid modality developers bridging photoacoustic and OCT architectures, and independent service organizations capturing unbundled maintenance revenue. Dominant competitive moves encompass M&A activity targeting software validation capabilities and strategic partnerships with integrated delivery networks.
Among Germany-based optics manufacturers, Carl Zeiss Meditec AG and Heidelberg Engineering GmbH exemplify the integrated foundry archetype with captive supply chains for precision ophthalmology hardware. Abbott Laboratories, a US-domiciled healthcare conglomerate, anchors the diversified platform developer tier through dedicated research funding on catheter-integrated modalities. These three entities occupy positions spanning the premium equipment and hybrid intraoperative guidance segments.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Topcon Corporation |
| Canon Inc. |
| GE Healthcare |
| Heidelberg Engineering GmbH |
| Abbott Laboratories |
| Nidek Co., Ltd. |
| Bruker Corporation |
| PerkinElmer Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term service unbundling contracts now dominate hospital procurement in California and Massachusetts, locking in equipment access while stripping original equipment manufacturers of recurring maintenance revenue. This structural shift compresses capital equipment margins while elevating price transparency across the North America Optical Imaging Market.
Pricing Analysis
Certification level (FDA 510(k)-grade versus research-grade) creates the primary spread between hospital-deployable systems and grant-funded academic configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by embedded AI algorithm density and after-sales service bundling. Price erosion runs through the mid-tier segment as independent service organizations capture maintenance revenue previously retained by original equipment manufacturers. Research institutes demonstrate lowest price sensitivity due to grant-funded capital equipment programs, while community hospital systems face acute budget constraints under 5-7 year depreciation schedules.
Supply Chain Analysis
Port congestion along the Los Angeles-Long Beach corridor elevates inbound logistics costs for German-manufactured precision optics entering the United States. Geographic supply concentration centers on Germany for high-NA objective lenses, Japan for avalanche photodiode detectors, and the United States for coherent light source assemblies. Raw material dependencies include rare-earth-doped optical fibers, precision-ground aspheric lenses, and indium gallium arsenide photodetector substrates. Single-source vulnerability persists for captive optics foundry output controlled by dominant vendors. Distribution runs through integrated delivery networks in California and academic medical center procurement channels in Boston and Houston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive outcomes as interoperability between optical imaging hardware and surgical navigation systems becomes the primary procurement criterion. FDA's software-as-medical-device framework accelerates this shift by privileging vendors with validated AI algorithm pipelines.
For Market Incumbents: Fortify control over high-NA objective supply chains through captive optics foundry investments or exclusive supplier agreements. Defend installed base positions in ophthalmology suites by embedding glaucoma progression algorithms that trigger expanded documentation requirements for substitute technologies. Prioritize software validation team segregation from hardware engineering to compress FDA 510(k) timelines for AI-enhanced platforms. For New Entrants and Emerging Players: Anchor in neurology blood-brain barrier imaging applications where research funding pools remain underpenetrated relative to ophthalmology's mature installed base. Target catheter-integrated photoacoustic configurations for oncology surgical suites seeking hybrid intraoperative guidance. Pursue strategic partnerships with Stanford and UCSF campuses to secure grant-funded validation data before hospital commercialization. For Investors and Strategic Acquirers: Capital is best deployed toward software validation capabilities and AI algorithm development teams rather than pure hardware manufacturing assets. Acquisition target archetypes include independent service organizations capturing unbundled maintenance revenue in California's integrated delivery networks and research-grade platform developers with customizable scan protocols. Signal to monitor: CMS coverage determinations for optical biopsy techniques as reimbursement-driven demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Validation Investment | FDA intensifies documentation requirements for AI-enhanced optical platforms, elevating compliance barriers. |
| Hospital System Partnership | Stanford Health Care and UCSF Health negotiate unbundled service terms, disintermediating original equipment manufacturers. |
| CE Marking Pathway | MDSAP mutual recognition framework accelerates vendor eligibility rotation for European manufacturers entering North America. |
| Reimbursement Strategy | CMS coverage determinations for optical biopsy techniques create demand inflection points for Medicare-dependent segments. |
| Geographic Manufacturing Footprint | California biomedical corridor concentrates demand pull for confocal scanning laser ophthalmology systems near research institutes. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists; and secondary validation through FDA 510(k) filings, Health Canada Medical Device License records, hospital procurement databases, and CMS coverage determination documents. Bottom-up triangulation across equipment shipment data and top-down validation against grant funding flows anchored market sizing.
Across the analysis window, the forecast framework modeled demand trajectories by product type (OCT, fluorescence imaging, fundus cameras, multi-photon microscopy), end user (hospitals, research institutes, diagnostic labs, clinics), technology maturity tier, and application-specific reimbursement pathway. CAGRs were derived from equipment replacement cycle compression rates and research funding allocation shifts, with frequency-domain OCT procurement budgets and photoacoustic platform R&D spend serving as primary demand inputs.
Material uncertainties — regulatory scrutiny escalation for AI algorithms, MDR-to-FDA harmonization friction, and CMS reimbursement reversals — sit outside the modeled envelope. Forecasts reflect assumptions about continued hospital capital allocation toward intraoperative precision systems and sustained grant funding for functional neuroimaging applications. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Stroboscope Market
Optics
India Laser Market
Optics
Smart Photochromic Lenses Market
Optics
Global Nanophotonics Market
Optics
Global Fiber Optic Sensors Market
Optics
Optical Measuring Systems Market
Optics
Electro Optics Market
Optics
Advanced Optics Market
Optics
Global Semiconductor Lasers Market
Optics
Fiber Optical Receivers Market
Optics
Optical Lens for Mobile Phone Market
Optics
Optical Fiber Market
Optics
MEMS Mirrors Market
Optics
Optical Wavelength Service Market
Optics
Beam Expanders Market
Optics
Anomaloscope Market